
 Asia-Pacific Accounting Software Market | 2026-2036
Asia-Pacific Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Accounting Software Market Analytics
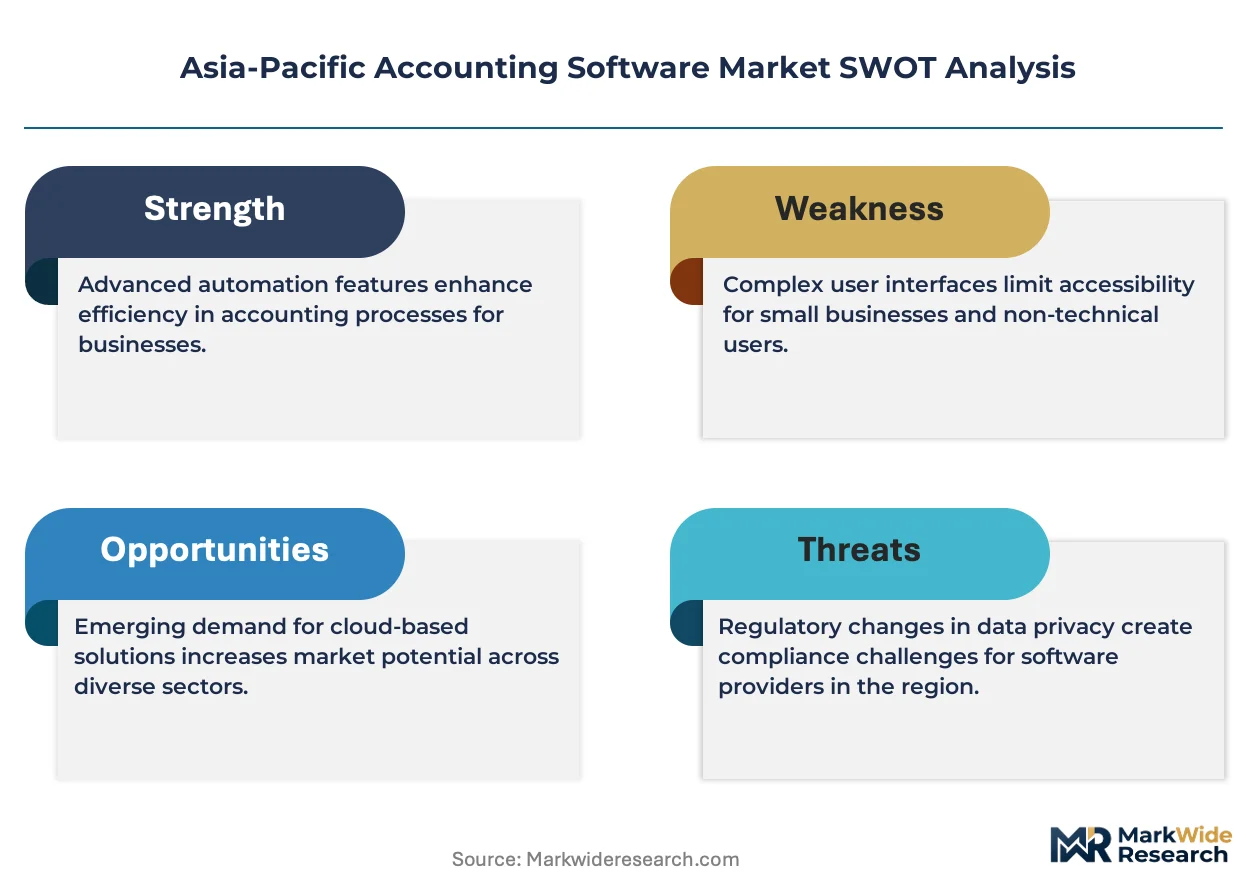
The divergence between premium and commodity tiers is hardening across the Asia-Pacific accounting software landscape. SAP SE leverages deep ERP integration to anchor enterprise contracts in manufacturing and healthcare verticals. Zoho Corporation competes aggressively on price while sustaining rapid feature releases for mid-market buyers across India and Southeast Asia.
Asia-Pacific accounting software encompasses systems for financial record-keeping, reporting automation, tax compliance, and audit trail management, typically deployed through cloud infrastructure with API connectivity to banking and tax authority portals. Cloud-based deployment leads volume expansion as regulatory bodies mandate real-time data submission, while on-premise solutions retain share among large enterprises with complex data sovereignty requirements. The freelancer segment shows fastest uptake of mobile-first, low-cost platforms across Indonesia and Vietnam.
India's GST Network, Australia's Australian Taxation Office digital reporting standards, and Singapore's IRAS e-invoicing framework collectively reshape product roadmaps and certification requirements. Compliance deadlines force buyers to replace legacy spreadsheets with auditable software, tightening vendor qualification criteria. Stakeholders must monitor which regulators next mandate API-first reporting, as this determines platform viability and customer retention across the region.
Market Dynamics
India's GST Network real-time invoice reporting mandate is forcing legacy spreadsheet users onto auditable cloud platforms, compressing replacement cycles and tightening vendor certification requirements across Southeast Asia.
Growth Catalysts
- India's GST e-invoicing mandate:The Central Board of Indirect Taxes and Customs requires real-time invoice validation through the Invoice Registration Portal, eliminating manual reconciliation for mid-market enterprises.
- Mobile-first freelancers:Indonesia's 70 million gig workers demand smartphone-native bookkeeping with automatic bank feed synchronization and simplified tax filing interfaces.
- Australia's Single Touch Payroll Phase 2:The Australian Taxation Office expanded reporting requirements to include granular employee data, driving payroll-integrated accounting upgrades.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud dominate regional data center capacity, creating single-point-of-failure exposure for SaaS accounting providers.
- Data sovereignty fragmentation:Vietnam's Cybersecurity Law and China's data localization rules prevent unified cross-border platform architectures, forcing redundant development.
- Legacy system entrenchment:Japanese SMEs retain on-premise Fujitsu and NEC installations due to lifetime employment cultures resistant to workflow disruption.
Strategic Opportunities
- Vietnam's underpenetrated mid-market:Ho Chi Minh City and Hanoi manufacturing clusters show sub-15 percent cloud accounting penetration among 50-200 employee firms.
- Embedded finance convergence:Accounting platforms integrating with neobank APIs for automated reconciliation and working capital lending unlock new revenue streams.
- Singapore's InvoiceNow network:The nationwide Peppol-based e-invoicing infrastructure creates certified integration demand for software vendors serving cross-border traders.
Industry Challenges
- API standardization gaps:India's GST Network, Australia's ATO, and Singapore's IRAS each deploy incompatible authentication protocols, multiplying integration engineering overhead.
- Localization talent scarcity:Vietnamese and Indonesian regulatory expertise for payroll and tax engine configuration commands 40 percent salary premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Accounting Software Market |
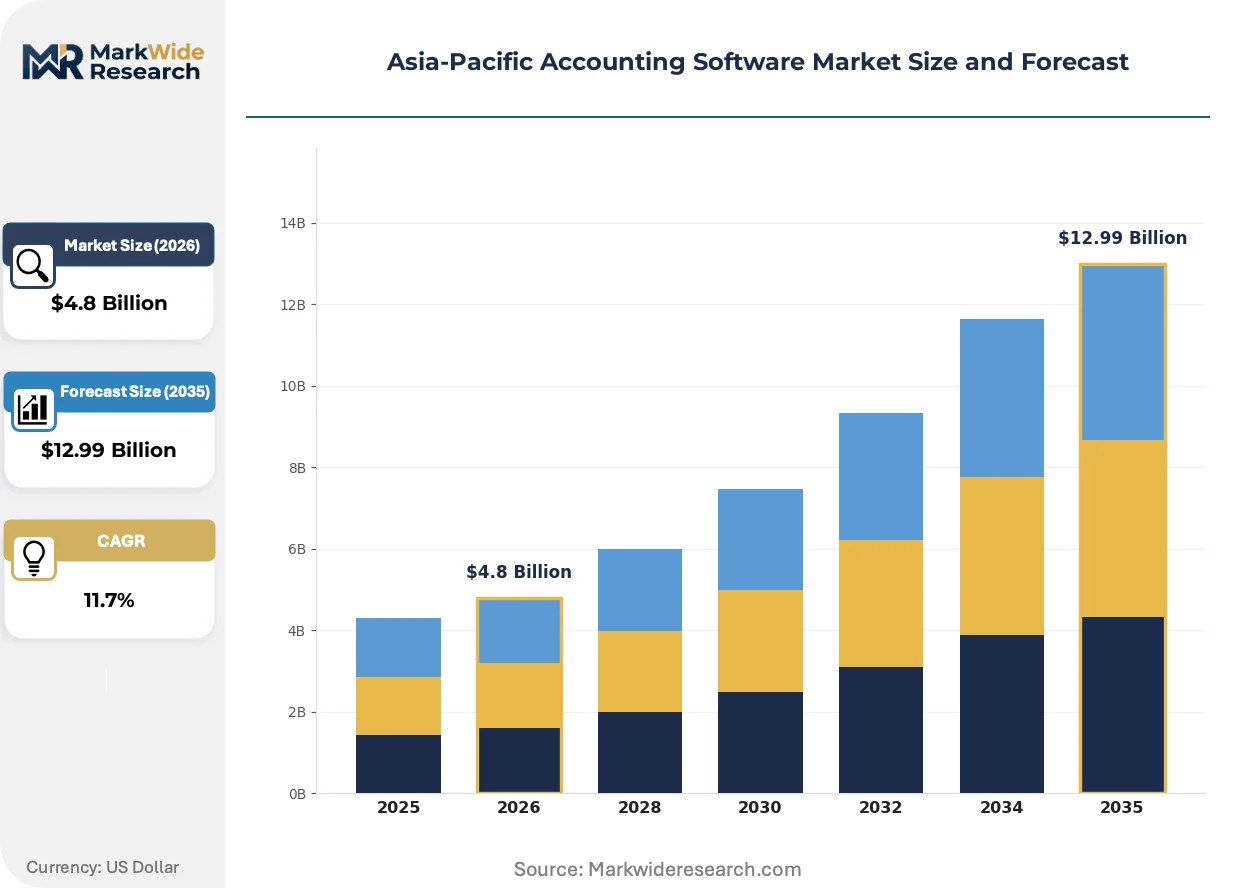
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Open-Source End User: Small Enterprises, Medium Enterprises, Large Enterprises, Freelancers Deployment Model: Single-Tenant, Multi-Tenant, Dedicated Server, Shared Hosting Industry Vertical: Retail, Manufacturing, Healthcare, Education |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, Zoho Corporation, Intuit Inc., Sage Group plc, Xero Limited, Infor Inc., Epicor Software Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Accounting Software Market Evolving Landscape
Artificial intelligence is compressing the gap between data entry and strategic advisory, while regulatory automation requirements reshape product architecture priorities across the region.
Embedded machine learning for anomaly detection is electrifying audit preparation workflows. Mid-market finance teams in Australia and Singapore deploy automated transaction categorization and fraud flagging, shrinking month-end close cycles from ten days to under seventy-two hours. This capability is compressing pricing power for traditional bookkeeping services and pushing accounting firms toward advisory revenue models.
Singapore's IRAS has mandated InvoiceNow compliance for all B2B transactions above specified thresholds by 2026, with penalties for non-compliant e-invoice formats. Software vendors must achieve Peppol Access Point certification to serve enterprise buyers, filtering out uncertified competitors. Malaysian and Thai tax authorities are monitoring Singapore's implementation timeline for their own framework development.
Subscription fatigue among Indonesian and Philippine micro-enterprises is driving unbundling of core ledger functions from full-suite offerings. Freemium tiers with pay-per-use tax filing and basic reporting now capture initial adoption, with feature expansion triggered by revenue thresholds. This consumption-pattern shift favors modular architectures over monolithic ERP replacements in price-sensitive segments.
Asia-Pacific Accounting Software Market Segmentation
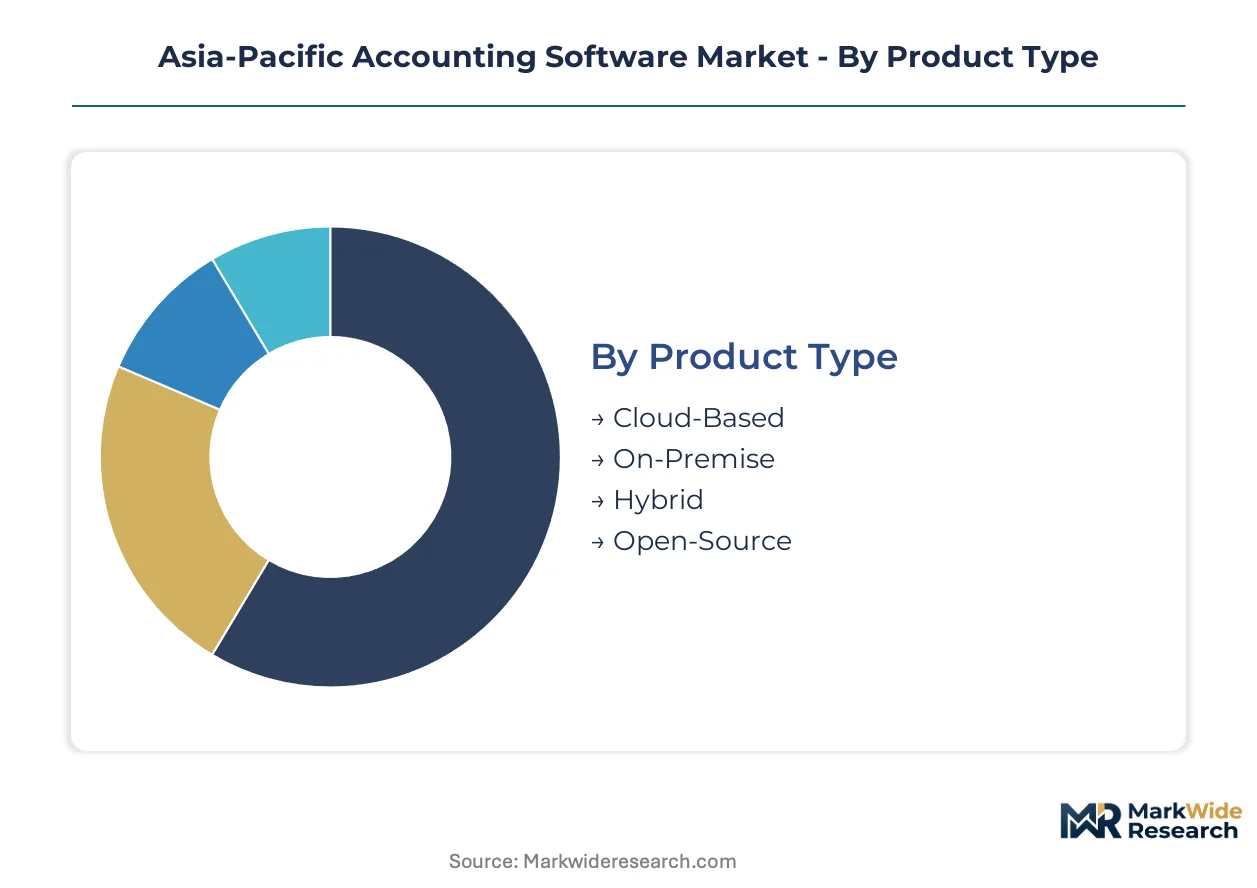
Regulatory mandates across India, Australia, and Singapore are fragmenting demand patterns by enterprise size and compliance complexity. Vendors must architect modular platforms that scale from freelancer mobile apps to multi-entity ERP integrations without redundant codebases.
Product Type:
The customization-vs-standardization spectrum runs from rigid on-premise installations to API-first cloud architectures that accommodate jurisdiction-specific tax engines.
- Cloud-Based:Browser-native platforms with automatic regulatory updates and real-time bank feeds dominate mid-market procurement in India and Southeast Asia. Australia's ATO digital reporting standards and Singapore's IRAS e-invoicing framework force API-first architectures that legacy systems cannot replicate.
- On-Premise:Perpetual-license software installed within client data centers retains footholds among Japanese manufacturers and Australian healthcare providers with strict data sovereignty requirements. These deployments require dedicated IT staff and carry higher total cost of ownership.
- Hybrid:Core ledger functions run locally while tax reporting modules sync to cloud authorities, serving Vietnamese manufacturers navigating data localization laws.
- Open-Source:Community-developed platforms with customizable codebases attract Indonesian developer ecosystems and Philippine accounting firms building proprietary workflows.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as data sovereignty rules proliferate.
End User:
Cost tier stratification separates white-glove implementation services for multinationals from self-serve onboarding flows targeting price-sensitive micro-businesses.
- Small Enterprises:Firms with under 50 employees prioritize mobile-first interfaces and automated GST compliance over advanced analytics. Indian small businesses drove fastest uptake following real-time invoice mandate enforcement.
- Medium Enterprises:Organizations with 50-500 employees demand multi-entity consolidation and audit trail automation. Singaporean trading companies and Australian professional services firms represent concentrated demand for Peppol-certified e-invoicing integration.
- Large Enterprises:Complex ERP integrations with manufacturing execution systems and treasury management platforms characterize procurement. Japanese automotive suppliers and Australian mining operators maintain on-premise footprints.
- Freelancers:Solo operators and gig workers across Indonesia and Vietnam require smartphone-native expense capture and simplified tax filing. Subscription fatigue drives preference for freemium models with usage-triggered upgrades.
Medium Enterprises absorb the majority of new vendor implementations. Freelancers are expanding most quickly as platform unbundling reduces entry costs.
Deployment Model:
Volume concentration favors multi-tenant architectures that amortize infrastructure across thousands of tenants, while dedicated resources serve compliance-sensitive outliers.
- Single-Tenant:Isolated instance per client with dedicated database and compute resources. Australian healthcare providers and Singaporean financial services firms mandate this architecture for patient and transaction data segregation.
- Multi-Tenant:Shared infrastructure with tenant isolation at application layer delivers lowest per-seat economics. Indian SaaS providers and Southeast Asian platforms standardize on this model for sub-$20 monthly price points.
- Dedicated Server:Physically segregated hardware within cloud provider facilities addresses Vietnamese Cybersecurity Law requirements without full on-premise burden.
- Shared Hosting:Entry-level partitioning on common servers serves Philippine micro-enterprises with minimal compliance obligations and tight budget constraints.
Multi-Tenant deployments carry the largest installed base. Dedicated Server configurations are climbing the fastest as data localization mandates expand.
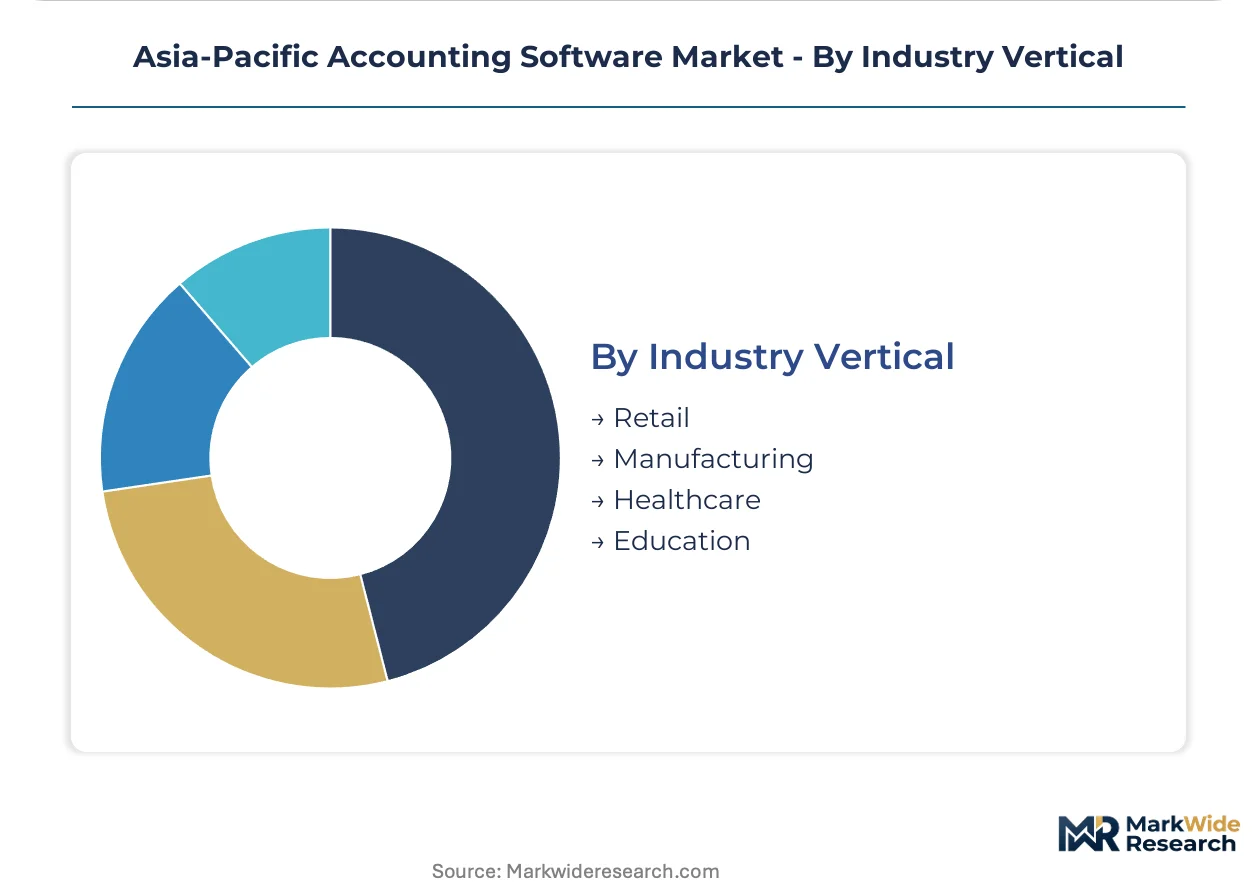
Industry Vertical:
Application-specific requirements separate retail's high-transaction-volume needs from manufacturing's inventory-costing complexity and healthcare's audit intensity.
- Retail:High-frequency transaction processing with POS integration and multi-channel inventory synchronization. Indian e-commerce sellers and Australian franchise networks drive demand for real-time GST calculation and automated reconciliation.
- Manufacturing:Work-in-progress tracking, bill-of-materials costing, and multi-currency procurement characterize requirements. Vietnamese electronics assemblers and Indonesian food processors seek shop-floor-to-ledger integration.
- Healthcare:Patient billing, insurance claim tracking, and stringent audit documentation dominate. Australian private clinics and Singaporean medical groups prioritize HIPAA-equivalent data handling with tax authority connectivity.
- Education:Tuition management, grant accounting, and donor reporting shape procurement. Indian private universities and Australian vocational training institutes represent emerging demand for fund-accounting capabilities.
Retail channels the greatest deployment volume. Healthcare is gaining share fastest as compliance automation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep pools of software engineering talent in Bengaluru, Singapore, and Sydney anchor the Asia-Pacific accounting software market's innovation capacity. These clusters feed rapid product iteration cycles and regulatory compliance engineering across the region.
India
GST Network real-time invoice mandates and mid-market digital transformation drive procurement volumes. The Central Board of Indirect Taxes and Customs enforces Invoice Registration Portal validation, eliminating manual reconciliation workflows. Bengaluru and Hyderabad SaaS clusters concentrate vendor engineering centers serving domestic and Southeast Asian markets.
Australia
Single Touch Payroll Phase 2 expansion and healthcare data sovereignty requirements sustain premium-tier demand. The Australian Taxation Office mandates granular employee data reporting, forcing payroll-integrated accounting upgrades. Sydney and Melbourne financial services corridors concentrate enterprise procurement for multi-entity consolidation platforms.
Singapore
InvoiceNow Peppol network certification and cross-border trade documentation reshape vendor qualification criteria. The Inland Revenue Authority of Singapore mandates e-invoicing compliance for B2B transactions above statutory thresholds by 2026. The city-state's trade finance hub concentrates demand from regional headquarters managing ASEAN compliance portfolios.
Vietnam
Manufacturing cluster digitization and data localization law compliance create hybrid deployment opportunities. The Cybersecurity Law mandates domestic data storage, forcing architectural adaptations from foreign SaaS providers. Ho Chi Minh City and Hanoi electronics assemblers show sub-fifteen percent cloud accounting penetration among mid-sized firms.
Indonesia
Seventy million gig workers and mobile-first micro-enterprise formation expand freelancer segment addressable market. The country's tax authority develops real-time reporting infrastructure modeled on Indian and Singaporean precedents. Jakarta and Surabaya digital economy corridors concentrate neobank partnerships for automated reconciliation and working capital lending integration.
Asia-Pacific Accounting Software Market Competitive Landscape
Top-tier vendors anchor enterprise ERP integration contracts, while mid-market specialists compete on regulatory certification speed and price-accessible cloud delivery. The market structure stratifies across three functional tiers: full-suite ERP incumbents with manufacturing and healthcare vertical depth, agile SaaS natives optimizing for GST and Peppol compliance automation, and mobile-first platforms capturing freelancer segments through unbundled freemium models. Strategic moves concentrate on API-first tax authority certification racing and embedded finance partnership formation.
Within the ERP-anchored tier, SAP SE and Oracle Corporation exemplify deep system-of-record positioning for complex multi-entity deployments. Zoho Corporation occupies a distinct mid-market vector, competing aggressively on price while sustaining rapid feature releases for compliance-heavy buyers across India and Southeast Asia. These three anchors represent divergent bets on customer acquisition economics: enterprise retention through switching-cost moats versus volume scaling through accessible price points and rapid regulatory adaptation.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Zoho Corporation |
| Intuit Inc. |
| Sage Group plc |
| Xero Limited |
| Infor Inc. |
| Epicor Software Corporation |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs from AWS, Microsoft Azure, and Google Cloud data centers cascade through SaaS provider economics into subscription tiers targeting Indian SMEs, Australian healthcare networks, and Singaporean trading houses. Engineering talent premiums in Bengaluru and Sydney compress margins at the mid-market tier while enterprise buyers absorb higher per-seat rates for single-tenant isolation and dedicated compliance engineering.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise ERP contracts with implementation services from modular SaaS tiers with pay-per-use tax filing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: InvoiceNow Peppol Access Point validation and GST Network API integration command premium positioning. Price differentiation hinges on regulatory automation grade and vertical customization scope. Cost compression in the freelancer tier intensifies because Indonesian neobank partnerships subsidize acquisition through lending revenue share. Micro-enterprises in the Philippines exhibit highest price sensitivity; Australian healthcare providers show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle complex multi-entity deployments requiring dedicated implementation teams, while self-serve web onboarding serves price-sensitive micro-businesses. Engineering supply concentrates in India, Australia, and Singapore where Bengaluru SaaS clusters, Sydney fintech corridors, and Singaporean compliance engineering pools feed product development. Raw material dependencies include cloud compute capacity, API gateway infrastructure, and regulatory certification labor. Single-source vulnerability runs through hyperscaler concentration: AWS, Azure, and Google Cloud dominate regional data center capacity without viable alternatives. Distribution runs through channel partners for Japanese manufacturing verticals and direct digital sales for Southeast Asian mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific accounting software operates as a geographic-arbitrage play where Indian engineering cost structures enable competitive pricing against Australian and Singaporean compliance premiums. Vendors capturing GST Network certification speed in India can leverage that architecture for Southeast Asian market entry.
For Market Incumbents: Lock in enterprise switching costs through deep ERP integration with manufacturing execution systems and treasury management platforms. Defend against Zoho Corporation's price aggression by accelerating InvoiceNow and GST Network certification timelines. Vertical integration into regulatory compliance engineering—captive teams in Hyderabad and Bengaluru—reduces dependency on 40-percent-salary-premium localization talent. For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated mid-market where sub-15-percent cloud accounting penetration among 50-200 employee manufacturing firms creates whitespace. Target Ho Chi Minh City and Hanoi electronics assemblers with hybrid deployment architectures satisfying Cybersecurity Law data localization requirements. Partner with regional neobanks for embedded finance integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where API standardization gaps multiply engineering overhead across India's GST Network, Australia's ATO, and Singapore's IRAS protocols. Long-term viability favors platforms with modular architectures scaling from freelancer mobile apps to multi-entity ERP without redundant codebases. Acquisition target archetype: mid-market SaaS vendors with live Peppol or GST Network certification and established channel partnerships in at least two regional markets. Watch for Malaysian and Thai tax authority e-invoicing mandate announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Peppol Access Point Certification | InvoiceNow compliance unlocks Singaporean enterprise procurement and cross-border trade documentation workflows. |
| Neobank API Integration | Embedded finance partnerships with Jakarta and Surabaya digital banks enable automated reconciliation and working capital lending revenue. |
| Hybrid Deployment Architecture | Vietnam Cybersecurity Law compliance captures manufacturing demand without full on-premise infrastructure burden. |
| Regulatory Engineering Captive | In-house Bengaluru compliance teams reduce dependency on 40-percent-premium Vietnamese and Indonesian localization talent. |
| Freemium Tier Unbundling | Usage-triggered upgrades capture Indonesian and Philippine micro-enterprise subscription fatigue with lower acquisition cost. |
Research Methodology
Coverage spans India, Australia, Singapore, Vietnam, and Indonesia, with primary inputs from each market. Primary interviews with SaaS product managers, regulatory compliance engineers, IT procurement officers at mid-market enterprises, and channel partners in accounting software distribution were triangulated against secondary validation. Secondary sources include GST Network technical documentation, Australian Taxation Office digital reporting standards, Singapore IRAS e-invoicing frameworks, and SEC filings from listed software vendors. Bottom-up sizing from individual country deployments and top-down cross-checks against regional cloud infrastructure expenditure established volume estimates.
Granularity-level framing modeled deployment model, organization size, vertical industry, and integration complexity dimensions at the country level. CAGRs were derived from regulatory mandate enforcement timelines, cloud infrastructure expansion curves, and historical replacement cycle compression patterns. Industry-specific forecast inputs included GST e-invoicing adoption curves across Indian states and InvoiceNow compliance thresholds across Singaporean enterprise segments. The analytical framework spans the projection horizon without year-specific breakpoint assumptions.
The model holds under sustained regulatory mandate enforcement and stable cloud infrastructure pricing; deviation in data sovereignty law proliferation or hyperscaler capacity constraints would shift deployment model mix and vendor economics. Forecasts reflect documented assumptions about compliance timeline adherence and mid-market digital transformation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Dental Practice Management Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global Order Management Software Market
Software & Services
Grant Management Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Queue Manager Market
Software & Services
Global User Interface Service Market
Software & Services
Discount Management Software Market
Software & Services
Construction Project Management Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Productivity Management Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market