
 Canada Geospatial Imagery Analytics Market | 2026-2036
Canada Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Geospatial Imagery Analytics Market Insights
Cloud-native image processing pipelines are narrowing the latency gap between satellite capture and actionable intelligence for Canadian operators. Maxar Technologies leverages its high-resolution constellation to sustain defense and intelligence contracts with federal agencies. Esri Canada anchors provincial GIS infrastructure deployments across Ontario and Quebec. Hexagon AB competes through specialized metrology-grade photogrammetry tools for precision agriculture clients.
Geospatial imagery analytics encompasses the extraction of quantitative and qualitative information from aerial and satellite imagery through radiometric correction, orthorectification, and spectral classification algorithms. The discipline serves environmental monitoring, infrastructure planning, and resource management by transforming raw sensor data into georeferenced intelligence layers. Remote sensing technology dominates Canadian government procurement for boreal forest and Arctic sovereignty applications. Machine learning integration represents the fastest-expanding capability segment, though GIS software retains the largest installed base across municipal planning departments. Cloud-based delivery is displacing on-premise deployments among mid-sized agricultural service providers seeking elastic compute for seasonal peak loads.
Health Canada and the Canadian Space Agency jointly shape operational standards for civilian earth observation data quality and distribution protocols. Natural Resources Canada mandates specific spectral resolutions for federal land cover classification products, directly influencing vendor technical roadmaps. The Canadian Radio-television and Telecommunications Commission governs spectrum allocation for beyond-visual-line-of-sight drone operations that feed imagery analytics workflows. Stakeholders must weigh sovereign data residency requirements against the latency advantages of cross-border cloud infrastructure as federal security classifications tighten for critical mineral site monitoring.
Market Dynamics
Federal cloud-first procurement mandates are compressing deployment timelines for geospatial analytics vendors serving Canadian resource ministries and municipal planning departments. This structural shift toward sovereign-hosted infrastructure is reshaping vendor qualification requirements and data residency compliance frameworks.
Growth Catalysts
- Wildfire monitoring mandates:Natural resource agencies across Alberta and British Columbia have institutionalized satellite-based fire perimeter tracking into seasonal operations.
- PMRA drone certification expansion:Health Canada's accelerated operator licensing for environmental surveillance drones is enlarging the certified pilot pool for aerial imagery collection.
- Carbon inventory verification protocols:Federal land cover classification standards now require spectral analytics for compliance reporting by forest tenure holders.
Market Restraints
- Compute cost volatility:Seasonal peak processing demands for prairie agriculture analytics expose service providers to elastic cloud pricing surges during harvest windows.
- Sovereign data residency requirements:Federal security classifications for critical mineral site monitoring restrict cross-border infrastructure utilization.
- Spectral resolution limitations:Current civilian satellite constellations lack the temporal revisit frequency required for real-time crop stress detection at cooperative scale.
Strategic Opportunities
- Arctic sovereignty applications:Northern transportation corridor monitoring remains underpenetrated by commercial analytics providers despite federal infrastructure investments.
- Machine learning-GIS convergence:Automated feature extraction from historical orthoimagery archives is opening subscription revenue streams for municipal asset inventory services.
- Precision cooperative channel development:Direct-to-farm data delivery partnerships bypass traditional agronomic advisory intermediaries in Saskatchewan and Manitoba.
Industry Challenges
- Photogrammetry specialist scarcity:The talent pipeline for metrology-grade analytics certification lags behind provincial GIS infrastructure deployment schedules.
- Legacy system integration friction:Municipal planning departments maintain decades of shapefile archives that resist seamless migration to cloud-native pipeline architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Geospatial Imagery Analytics Market |
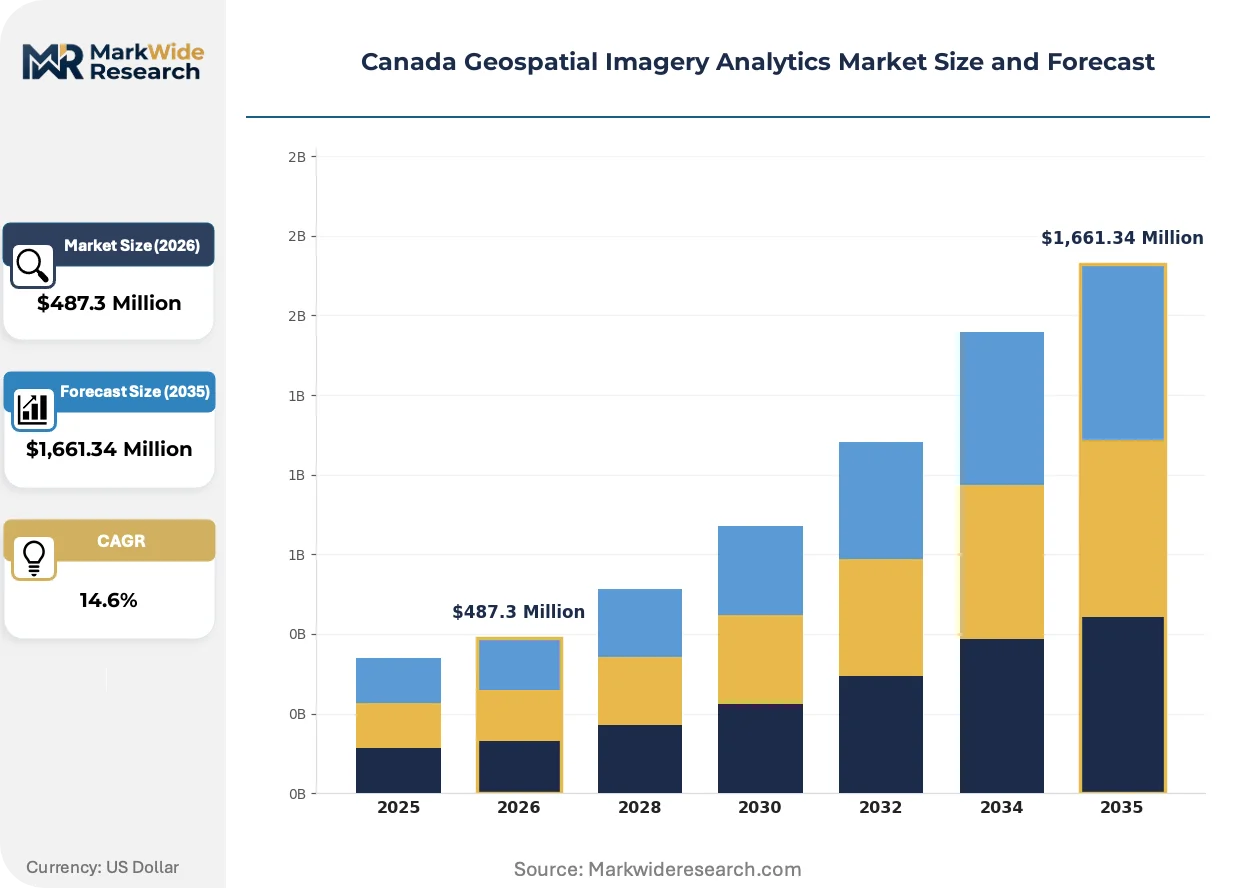
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Use Case: Surveying, Mapping, Environmental Monitoring, Urban Planning Technology: Remote Sensing, Machine Learning, GIS Software, Image Processing Delivery Mode: Cloud-Based, On-Premise, Hybrid, Mobile End User: Government, Real Estate, Transportation, Agriculture |
| Companies Covered | Harris Corporation, Maxar Technologies, ESRI Inc., BAE Systems, Satellite Imaging Corporation, Trimble Inc., Esri Canada, Hexagon AB, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Geospatial Imagery Analytics Market Trends and Innovations
Canadian geospatial markets are experiencing rapid capability convergence as artificial intelligence pipelines absorb traditional remote sensing workflows. This transformation is compressing analyst training requirements while expanding automated output quality.
Synthetic aperture radar is hybridizing with optical multispectral constellations to deliver all-weather biomass monitoring for boreal forest carbon accounting. Provincial natural resource ministries in Quebec and Ontario are adopting these fused datasets for annual timber supply reviews. The technology is hybridizing vendor service offerings, forcing pure-play optical providers toward partnership or capability acquisition.
Health Canada's joint guidance with the Canadian Space Agency on civilian earth observation data quality is mandating standardized radiometric correction protocols for federal procurement eligibility. This regulatory alignment is disqualifying non-compliant vendors from defense and intelligence contract streams. Arctic sovereignty applications face the steepest compliance adjustment timelines due to classified site monitoring requirements.
Cooperative buying consortia among prairie grain growers are consolidating analytics procurement into multi-year platform subscriptions. Traditional per-acre image processing fees are collapsing as volume commitments shift negotiating leverage toward agricultural service integrators. Saskatchewan-based precision farming groups demonstrate the most advanced collective bargaining structures in this transition.
Canada Geospatial Imagery Analytics Market Segmentation
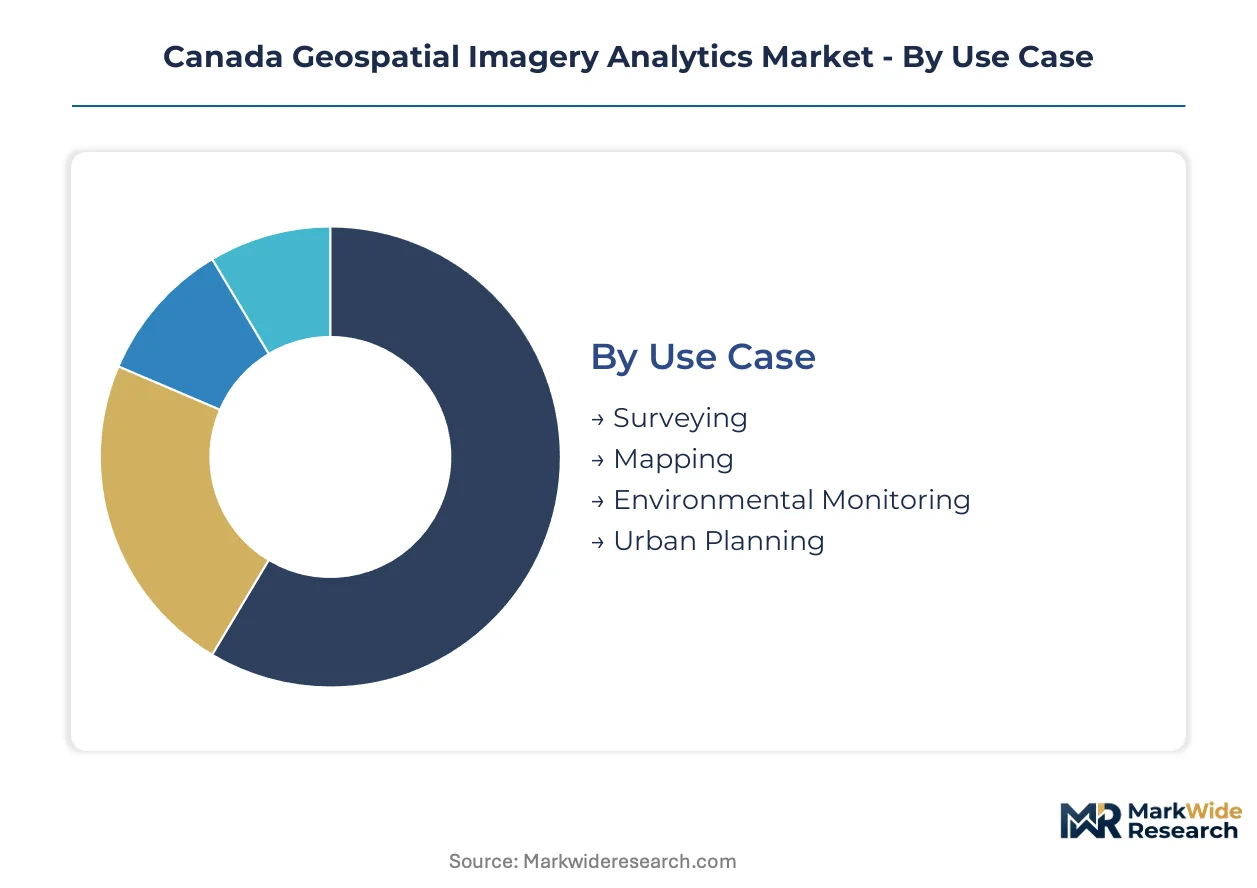
Segmentation reveals how procurement cycles, compliance burdens, and technical requirements fragment demand across Canadian federal agencies, provincial ministries, and private operators. Understanding these divides clarifies where vendor specialization yields margin protection versus where platform consolidation captures volume.
Use Case:
Surveying contracts turn over on annual timber supply review cycles, while urban planning analytics stretch across decade-long municipal master plan horizons.
- Environmental Monitoring:Satellite-based wildfire perimeter tracking and boreal forest carbon inventory verification absorb the majority of federal earth observation procurement. Alberta and British Columbia natural resource agencies have institutionalized seasonal procurement rhythms for fire behavior modeling.
- Urban Planning:Municipal asset inventory automation from historical orthoimagery archives is generating subscription revenue for cloud-native pipeline vendors. Ontario and Quebec GIS infrastructure deployments favor vendors with legacy shapefile migration capabilities.
- Surveying:Metrology-grade photogrammetry for precision agriculture cooperatives in Saskatchewan and Manitoba demands certified analyst talent that outstrips supply.
- Mapping:Arctic sovereignty corridor documentation remains underpenetrated by commercial providers despite federal infrastructure commitments.
Environmental monitoring dominates installed base. Urban planning is where expansion concentrates.
Technology:
Cost tiers separate capital-intensive sensor platforms from software-only deployments that scale through subscription economics.
- GIS Software:Provincial infrastructure deployments across Ontario and Quebec anchor the largest installed base of georeferenced intelligence layers. Municipal planning departments maintain decades of archival data that resists seamless cloud migration.
- Machine Learning:Automated feature extraction pipelines are compressing analyst training requirements while expanding output quality for agricultural service integrators. Prairie precision farming cooperatives demonstrate the most advanced adoption curves.
- Remote Sensing:Synthetic aperture radar-optical hybridization delivers all-weather biomass monitoring for federal land cover classification compliance.
- Image Processing:Cloud-native radiometric correction and orthorectification workflows face sovereign data residency constraints for critical mineral site monitoring.
GIS software retains the deepest footprint. Machine learning is climbing the fastest.
Delivery Mode:
Volume concentration favors cloud architectures that absorb seasonal harvest window processing surges without permanent infrastructure commitment.
- Cloud-Based:Elastic compute for prairie agriculture analytics peaks during narrow harvest windows, exposing service providers to pricing volatility. Federal cloud-first procurement mandates are compressing vendor qualification timelines.
- Hybrid:Sovereign-hosted infrastructure with cross-border burst capacity balances latency optimization against security classification requirements for defense and intelligence contracts.
- On-Premise:Legacy municipal deployments resist migration due to decades of shapefile archive dependencies.
- Mobile:Drone-based field collection for environmental surveillance feeds directly into Health Canada certification workflows.
Cloud-based deployments capture new procurement. Hybrid architectures are gaining share fastest.
End User:
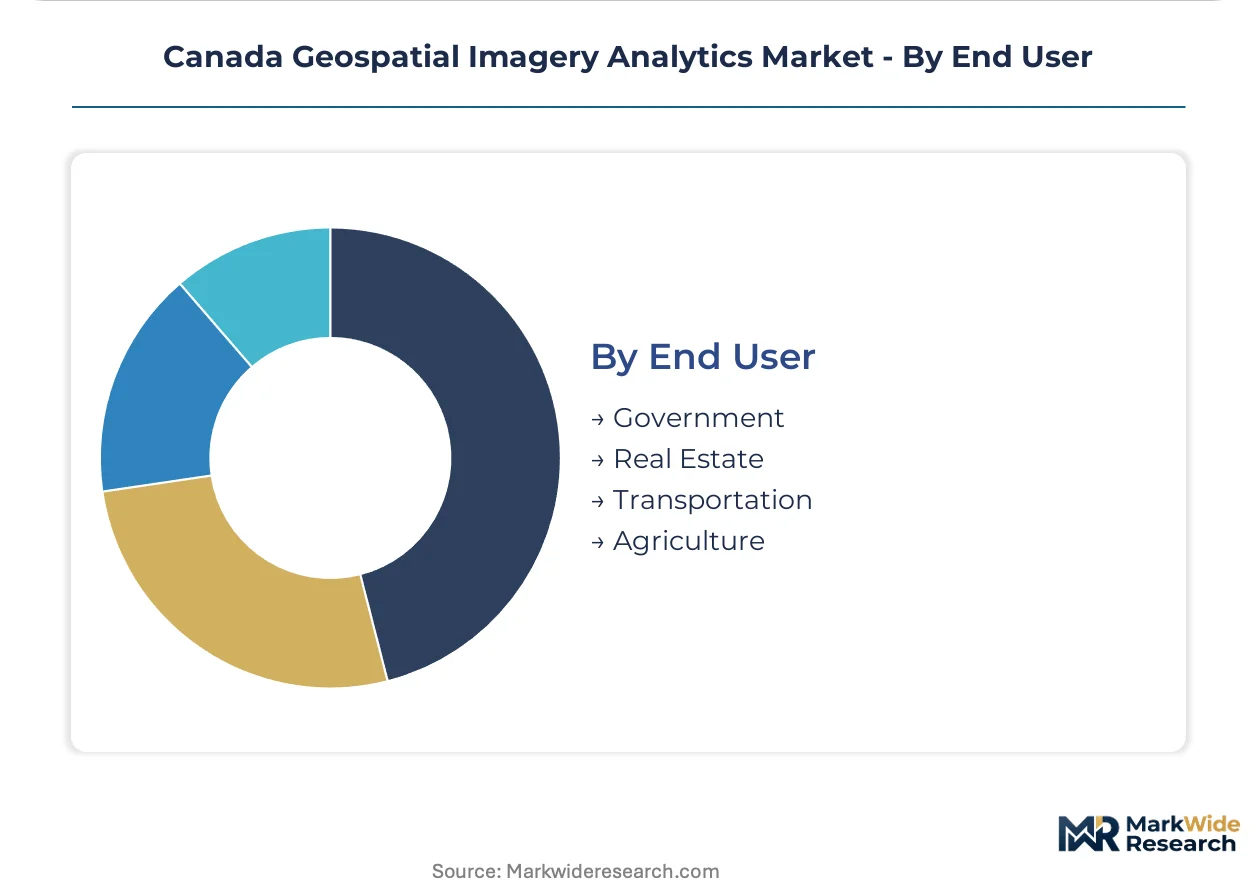
Customer type determines contract structure, with government procurement favoring multi-year platform commitments against agriculture's seasonal spot purchasing.
- Government:Federal security classifications for critical mineral monitoring and joint Health Canada-Canadian Space Agency data quality standards shape vendor technical roadmaps. Natural Resources Canada spectral resolution mandates directly influence product development priorities.
- Agriculture:Cooperative buying consortia among prairie grain growers are consolidating procurement into multi-year subscriptions, collapsing traditional per-acre processing fees.
- Transportation:Northern corridor monitoring for Arctic sovereignty applications remains commercially underdeveloped.
- Real Estate:Municipal planning integration lags behind provincial GIS infrastructure deployment schedules.
Government anchors procurement volume. Agriculture is where pricing power is shifting fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian geospatial imagery analytics flows primarily from Ontario and Quebec-based processing centers to prairie province agricultural cooperatives and federal resource ministries in Western Canada.
Ontario
Toronto-Waterloo corridor hosts the densest concentration of cloud-native pipeline vendors serving municipal GIS infrastructure deployments. Health Canada's joint guidance with the Canadian Space Agency on civilian earth observation data quality shapes vendor technical roadmaps for federal procurement eligibility. Ottawa anchors defense and intelligence contract streams where Maxar Technologies sustains high-resolution constellation service agreements.
Quebec
Provincial natural resource ministries adopt synthetic aperture radar-optical hybridization for annual timber supply reviews in boreal forest regions. Natural Resources Canada spectral resolution mandates directly influence product development priorities for vendors seeking provincial qualification. Montreal's aerospace cluster feeds specialized photogrammetry talent into metrology-grade analytics certification pipelines.
Alberta
Natural resource agencies institutionalize satellite-based wildfire perimeter tracking into seasonal operations across the Rocky Mountain foothills. Federal cloud-first procurement mandates compress deployment timelines for vendors serving provincial resource ministries. Calgary-based precision farming cooperatives integrate multispectral crop health analytics into seasonal input planning workflows.
British Columbia
Carbon inventory verification protocols drive spectral analytics procurement by forest tenure holders in coastal and interior timber supply areas. The Canadian Radio-television and Telecommunications Commission governs spectrum allocation for beyond-visual-line-of-sight drone operations feeding imagery analytics workflows. Vancouver's technology cluster concentrates cloud infrastructure providers balancing sovereign data residency against latency optimization.
Prairie Provinces
Saskatchewan and Manitoba grain growers consolidate analytics procurement into multi-year platform subscriptions through cooperative buying consortia. Seasonal peak processing demands for harvest window analytics expose service providers to elastic cloud pricing volatility. Regina and Winnipeg anchor agricultural service integrators bypassing traditional agronomic advisory intermediaries with direct-to-farm data delivery partnerships.
Canada Geospatial Imagery Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across federal procurement streams and provincial infrastructure deployments. The vendor landscape organizes around three strategic archetypes: constellation operators with defense contract anchoring, GIS platform incumbents with legacy migration capabilities, and precision agriculture specialists with cooperative channel penetration. Consolidation pressure concentrates among cloud-native pipeline vendors seeking scale to absorb seasonal compute volatility. Competitive moves center on sovereign-hosted infrastructure partnerships and automated feature extraction capability acquisition.
Within the constellation operator tier, Maxar Technologies and Harris Corporation exemplify players anchoring federal security-classified contracts through high-resolution sensing infrastructure. Esri Canada occupies a position bridging provincial GIS deployments with legacy shapefile migration requirements. Hexagon AB sits within the precision agriculture specialist archetype, serving metrology-grade photogrammetry demand from prairie cooperative clients.
| Leading Market Players |
|---|
| Harris Corporation |
| Maxar Technologies |
| ESRI Inc. |
| BAE Systems |
| Satellite Imaging Corporation |
| Trimble Inc. |
| Esri Canada |
| Hexagon AB |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
Constellation operator concentration in the United States and Europe feeds margin capture downstream into Canadian federal defense and intelligence contracts, while cloud infrastructure commoditization squeezes mid-tier analytics service providers. Sovereign data residency mandates for critical mineral monitoring fragment procurement into premium-compliant and standard non-compliant tiers, reshaping where value pools accumulate across the vendor stack.
Pricing Analysis
Next-generation synthetic aperture radar-optical hybridization commands substantial premiums over legacy optical-only offerings, while prior-generation multispectral analytics face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade certified pipelines from municipal GIS subscriptions and seasonal agricultural spot processing. Cost compression in standard-tier cloud analytics is intensifying because prairie cooperative buying consortia consolidate procurement into multi-year platform commitments. Agricultural service integrators demonstrate the highest price sensitivity, whereas federal security-classified contracts retain the lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates upstream risk for sensor component sourcing, particularly for high-resolution optical payloads and specialized photogrammetry hardware. Manufacturing concentration centers on the United States, Germany, and China for metrology-grade equipment, while cloud compute infrastructure draws from domestic Canadian facilities and cross-border burst capacity. Single-source vulnerability persists in synthetic aperture radar component supply. Distribution runs through provincial GIS infrastructure deployments and direct-to-farm agricultural service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prairie cooperative buying consortia are consolidating procurement leverage, shifting pricing power from vendors toward agricultural buyer archetypes and compressing margins for undifferentiated analytics providers.
For Market Incumbents: Entrench federal defense and intelligence contract positions through sovereign-hosted infrastructure partnerships that satisfy Natural Resources Canada security classifications for critical mineral monitoring. Deepen backward integration into cloud-native pipeline development to absorb seasonal compute volatility without elastic pricing exposure. Counter emerging pure-play machine learning entrants by anchoring provincial GIS infrastructure deployments with legacy shapefile migration capabilities. For New Entrants and Emerging Players: Arctic sovereignty corridor monitoring for northern transportation infrastructure represents the most penetrable entry point, given federal investment commitments and limited commercial provider presence. Precision agriculture cooperatives in Manitoba bypassing traditional agronomic advisory intermediaries offer a second white-space channel. A direct-to-farm data delivery partnership model with Regina and Winnipeg-based agricultural service integrators provides the most viable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native pipeline vendors with demonstrated seasonal capacity absorption and Health Canada-Canadian Space Agency joint guidance compliance for federal procurement eligibility. Long-term viability hinges on automated feature extraction capability depth and cooperative channel penetration in Saskatchewan and Manitoba. The signal to watch is consolidation velocity among prairie grain grower buying consortia, which indicates pricing power inflection toward platform-scale vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Partnership | Health Canada data residency mandates disqualify non-compliant vendors from federal procurement streams. |
| Automated Feature Extraction Acquisition | Machine learning-GIS convergence compresses analyst training requirements for prairie agricultural clients. |
| Cooperative Channel Direct Access | Saskatchewan precision farming groups demonstrate advanced collective bargaining structures collapsing per-acre fees. |
| Synthetic Aperture Radar Capability Buildout | Quebec and Ontario provincial ministries adopt fused datasets for annual timber supply reviews. |
| Legacy Archive Migration Service Launch | Municipal planning departments across Ontario and Quebec resist cloud migration without shapefile compatibility. |
Research Methodology
The analysis maps satellite constellation services, cloud-native pipeline platforms, GIS software deployments, and precision agriculture analytics, each validated through primary interviews with natural resource agency procurement officers, municipal GIS infrastructure managers, agricultural cooperative data directors, and photogrammetry certification specialists. Secondary sources include Natural Resources Canada procurement databases, Canadian Space Agency earth observation standards documentation, Health Canada PMRA drone certification records, and provincial timber supply review publications. Bottom-up segment sizing triangulates against top-down federal procurement budget allocations.
Assumptions held fixed include Health Canada-Canadian Space Agency joint guidance compliance requirements, Natural Resources Canada spectral resolution mandates, and prairie cooperative buying consolidation velocity; varied assumptions include cloud infrastructure pricing elasticity and synthetic aperture radar-optical hybridization adoption curves across provincial ministries. The analytical framework models use case, technology, delivery mode, and end user dimensions across the projection horizon, with CAGRs derived from segment-level procurement cycle analysis and seasonal processing demand patterns. Federal cloud-first mandate implementation pace and PMRA drone certification expansion rates serve as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure investment cycles or cross-border cloud compute pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding procurement consolidation and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Global Data Analysis Software Market
Analytics
Sweden ICT Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Speech and Voice Analytics Market
Analytics
Process Analytics Market
Analytics
Condition Monitoring Service Market
Analytics
Network Analytics Services Market
Analytics
Text Analytics Market
Analytics
Investigative Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Sentiment Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
Imagery Analytics Market
Analytics
Lead Intelligence Software Market