
 Taiwan Data Center Power Market | 2026-2036
Taiwan Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Power Market Insights
The divergence between premium and commodity tiers is hardening as liquid-cooled power infrastructure for AI workloads commands pricing multiples above legacy air-cooled systems for enterprise colocation. Delta Electronics leverages its captive semiconductor supply chain to dominate high-efficiency power module production. Schneider Electric anchors the island's switchgear and UPS ecosystem through localized manufacturing partnerships. Chunghwa Telecom competes by bundling power infrastructure with its dominant telecom fiber backbone across northern Taiwan.
Taiwan data center power encompasses the generation, conditioning, distribution, and backup systems that maintain continuous electrical supply to server infrastructure, typically operating at 380/400V three-phase with redundancy tiers from N+1 to 2N+1 per Uptime Institute standards. UPS systems lead product type demand as hyperscale operators replace aging valve-regulated lead-acid battery banks with lithium-ion configurations. Liquid cooling is displacing air cooling in new builds above 50kW per rack. Renewable energy power sourcing is accelerating fastest among cloud providers seeking green power purchase agreements with Taiwan Power Company and independent offshore wind developers.
Taiwan's Bureau of Energy enforces renewable energy certificate mandates that shape data center procurement timelines, while the National Communications Commission imposes uptime requirements on critical telecom infrastructure. CNS standards for electrical safety and energy efficiency filter market access for foreign equipment suppliers. Stakeholders must monitor grid interconnection queue positions and Taipower transmission upgrade schedules before committing to multi-hundred-megawatt campus developments.
Market Dynamics
Liquid cooling infrastructure for AI workloads is absorbing capital allocation that previously flowed to air-cooled legacy builds, compressing deployment timelines and rewiring supplier relationships across Taoyuan and New Taipei City.
Growth Catalysts
- Electricity Act Amendments:Taiwan's renewable energy mandates redirect data center procurement toward solar and offshore wind power purchase agreements, accelerating green campus development.
- Hyperscale Cloud Expansion:International cloud providers are building multi-hundred-megawatt campuses in Taipei and Taichung, pulling demand for high-redundancy power distribution systems.
- AI Training Clusters:Dense GPU deployments above 50kW per rack require liquid-cooled power modules, creating specialized demand for high-efficiency rectifiers and busbars.
Market Restraints
- Grid Interconnection Queues:Taipower transmission upgrade schedules delay campus energization by 18-36 months, freezing capital commitment timelines for developers.
- Lithium-Ion Supply Concentration:Battery cell production for UPS systems concentrates in mainland Chinese and South Korean suppliers, exposing procurement to geopolitical friction.
- Semiconductor Equipment Lead Times:Power module fabrication depends on captive silicon carbide wafer supply that Delta Electronics dominates, limiting second-source options.
Strategic Opportunities
- Taichung Science Park Expansion:Underdeveloped land banks and favorable grid infrastructure position central Taiwan for next-generation hyperscale clusters.
- Energy Storage Integration:Co-located battery systems enable peak shaving and grid services, creating new revenue streams beyond backup power provision.
- Submarine Cable Landing Stations:Bundling power infrastructure with fiber backhaul at cable landing points in Tamsui and Fangshan differentiates integrated service offerings.
Industry Challenges
- Electrical Engineering Talent Scarcity:Specialized expertise in 380/400V three-phase distribution and 2N+1 redundancy design remains concentrated at incumbent suppliers, constraining new entrant scaling.
- Legacy Air-Cooled Retrofit Complexity:Existing enterprise colocation facilities face prohibitive capex burdens to upgrade cooling and power density without tenant pre-commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Power Market |
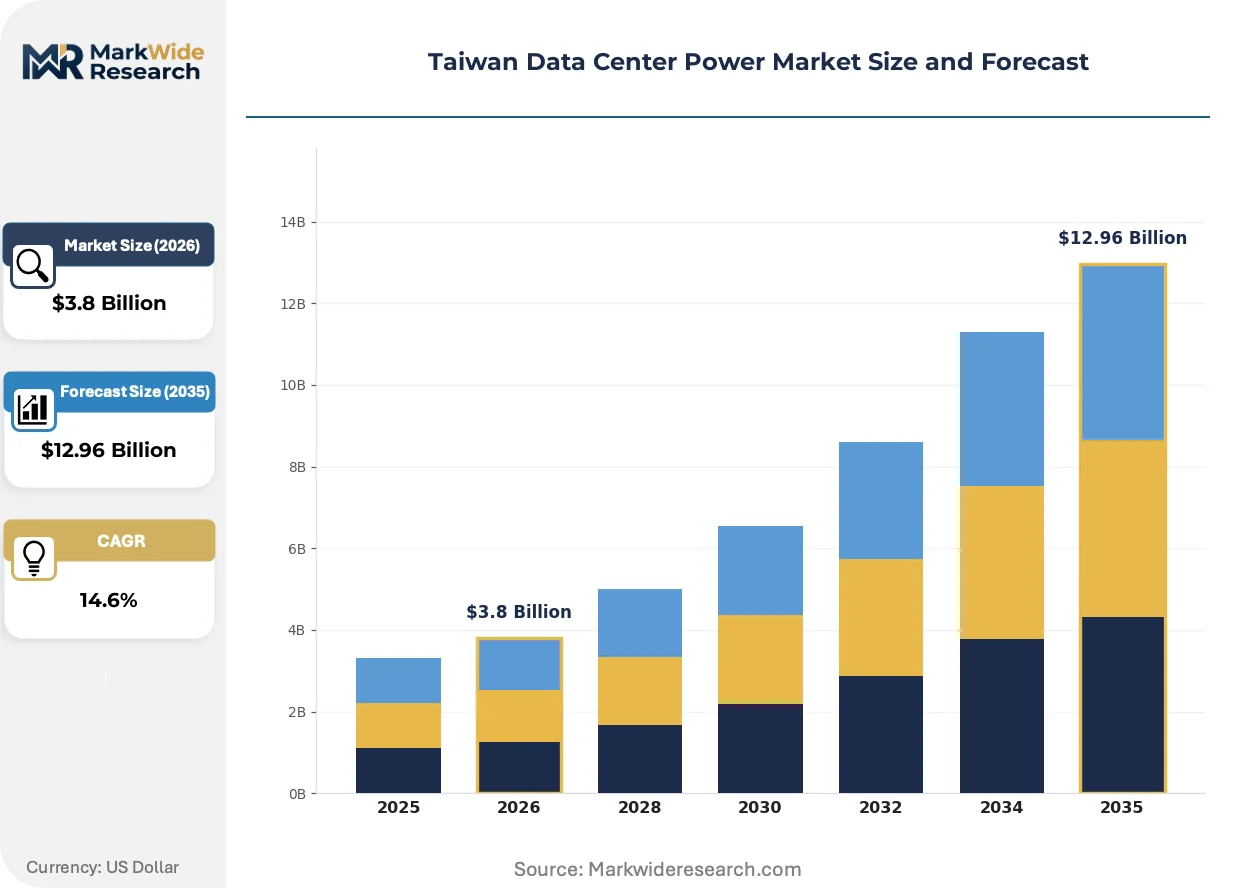
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UPS, Generators, Switchgear, PDUs Power Source: Renewable Energy, Diesel, Natural Gas, Grid Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling End User: Telecommunications, Cloud Providers, Enterprises, Colocation |
| Companies Covered | Delta Electronics, Schneider Electric, Vertiv, Eaton, ABB, Legrand, Caterpillar, Chunghwa Telecom, Chief Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Power Market Trends and Innovations
Power infrastructure architecture is bifurcating between legacy air-cooled designs and liquid-cooled systems purpose-built for AI, with procurement patterns diverging accordingly.
Immersion cooling dielectric fluids are absorbing thermal loads from 100kW-plus GPU racks that air handlers cannot address. Hyperscale operators in Taoyuan are deploying this technology at pilot scale now, with production rollouts accelerating through 2026. The shift is absorbing engineering talent and vendor attention that previously served enterprise colocation, compressing innovation cycles for legacy segments.
Taiwan's Bureau of Energy enforces renewable energy certificate mandates that shape data center procurement timelines and contract structures. These requirements force operators to secure long-term power purchase agreements with Taiwan Power Company and independent offshore wind developers before campus completion. Cloud providers with sustainability commitments face the tightest compliance windows, driving early engagement with certificate-tracking platforms.
Colocation buyers are unbundling power infrastructure from space leases, negotiating separate metered utility contracts and direct equipment ownership. This disintermediation strips traditional margin stacking from facility operators and pushes procurement decisions toward specialized power engineering teams within hyperscale tenant organizations. Northern Taiwan exhibits this pattern most acutely, where cloud provider concentration enables direct supplier relationships.
Taiwan Data Center Power Market Segmentation
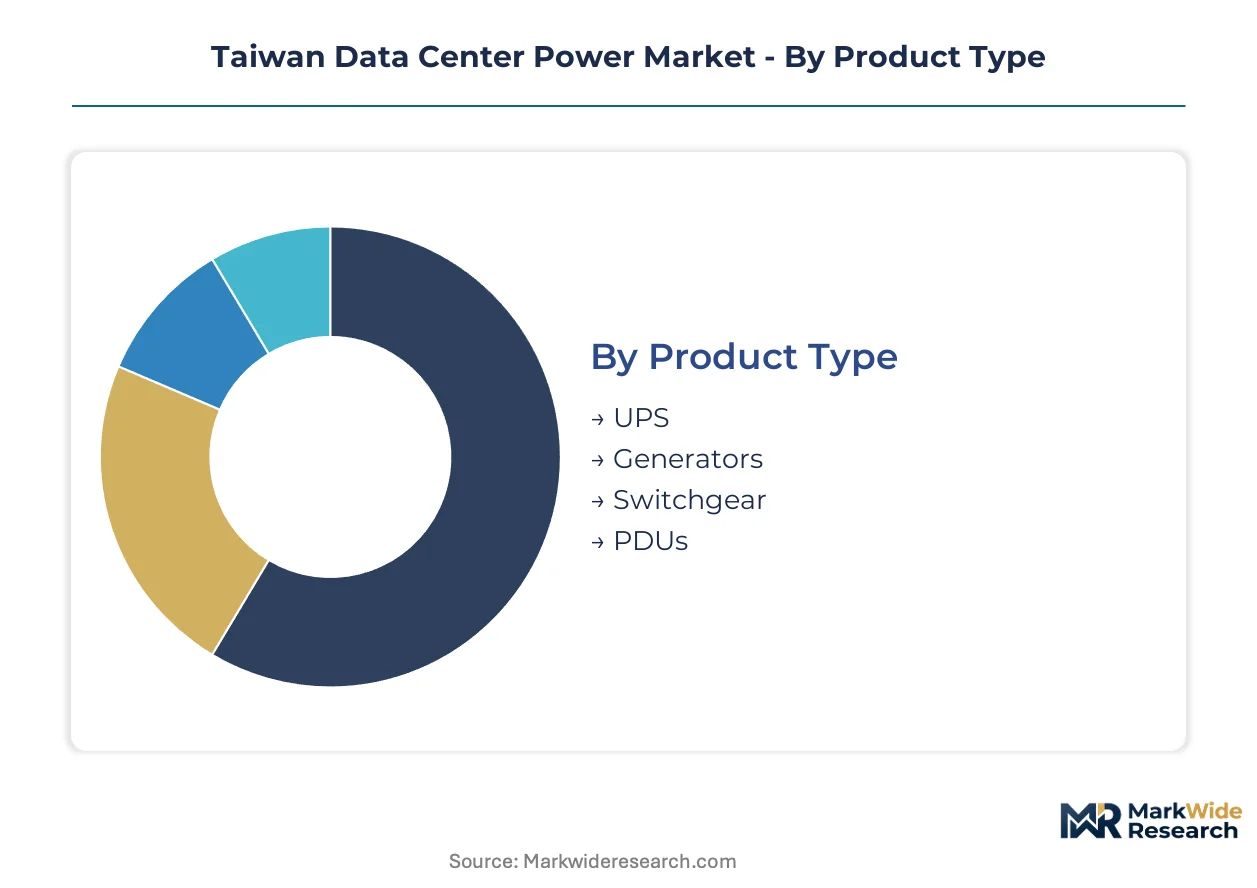
Segmentation in Taiwan's data center power market reveals how procurement decisions fragment across technical specifications, sustainability mandates, and workload density requirements. Each dimension carries distinct supplier relationships and regulatory compliance pathways that shape capital allocation.
Product Type:
Supply concentration in power electronics manufacturing concentrates procurement leverage among domestic Taiwanese producers with captive semiconductor fabrication capabilities.
- UPS:Lithium-ion battery configurations are displacing legacy valve-regulated lead-acid systems in hyperscale deployments. Taoyuan and New Taipei City campuses drive replacement cycles as cloud providers seek higher energy density and reduced footprint for multi-hundred-megawatt facilities.
- Switchgear:Localized manufacturing partnerships anchor Schneider Electric's presence across northern Taiwan's hyperscale clusters. Procurement teams prioritize 380/400V three-phase distribution with 2N+1 redundancy to meet Uptime Institute standards for AI training infrastructure.
- Generators:Diesel and natural gas backup systems serve Tier III and Tier IV facilities requiring sustained runtime during grid instability.
- PDUs:Rack-level power distribution units integrate monitoring and switching for remote management in high-density environments.
Today's leader: UPS. Tomorrow's challenger: Switchgear.
Power Source:
Cost tier differentiation separates premium renewable procurement from commodity grid-connected baseline supply.
- Renewable Energy:Solar and offshore wind power purchase agreements dominate new hyperscale campus development under Bureau of Energy certificate mandates. Cloud providers with sustainability commitments face compressed compliance windows that accelerate contract execution with Taiwan Power Company and independent developers.
- Grid:Taipower transmission infrastructure serves as primary feed for enterprise colocation and legacy facilities across Taipei and Taichung. Interconnection queue positions extending 18-36 months constrain campus energization timelines and freeze capital commitments.
- Diesel:Backup generation maintains regulatory minimums for critical telecom infrastructure under National Communications Commission uptime requirements.
- Natural Gas:Cleaner-burning alternative to diesel for extended runtime scenarios in facilities with pipeline access.
Renewable energy procurement is climbing the fastest as certificate mandates harden compliance requirements.
Cooling Technology:
Application-specific thermal management separates AI training clusters from enterprise workloads.
- Liquid Cooling:Direct-to-chip and immersion systems address GPU rack densities exceeding 100kW that air handlers cannot accommodate. Taoyuan hyperscale operators deploy at pilot scale with production acceleration through 2026, absorbing engineering talent previously serving legacy segments.
- Air Cooling:Legacy enterprise colocation facilities in Taipei maintain installed base despite prohibitive retrofit capex without tenant pre-commitment. Existing infrastructure faces compressed innovation cycles as vendor attention shifts to liquid-cooled designs.
- Evaporative Cooling:Water-efficient adiabatic systems reduce mechanical refrigeration load in moderate climate conditions.
- Hybrid Cooling:Combined air and liquid approaches bridge transition periods for mixed-density deployments.
Liquid cooling commands the steepest expansion trajectory as AI workload density requirements intensify.
End User:
Customer type determines redundancy tier requirements and procurement decision-making authority.
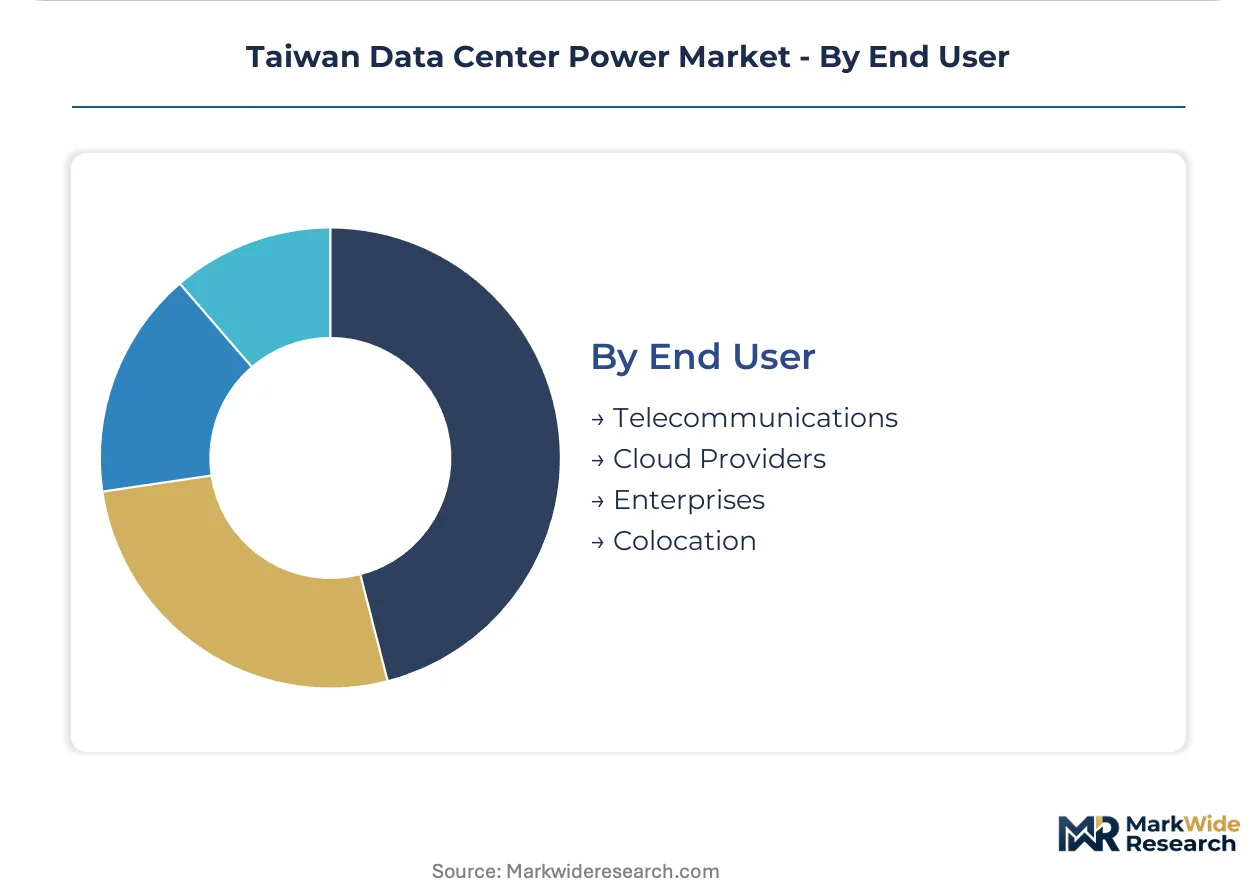
- Cloud Providers:Hyperscale operators unbundle power infrastructure from space leases, negotiating direct metered utility contracts and equipment ownership. Northern Taiwan concentration enables specialized power engineering teams to manage supplier relationships independently of colocation operators.
- Telecommunications:Chunghwa Telecom bundles power infrastructure with dominant fiber backbone across northern Taiwan, leveraging integrated service differentiation. National Communications Commission uptime requirements impose regulatory minimums on critical infrastructure design.
- Enterprises:Corporate data centers prioritize operational control over density optimization, sustaining demand for conventional redundancy architectures.
- Colocation:Multi-tenant facilities face margin compression as tenants disintermediate traditional power procurement stacking.
Cloud providers set procurement patterns today. Telecommunications operators represent the structural challenger as 5G edge infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineering talent for 380/400V three-phase distribution and 2N+1 redundancy design concentrates at incumbent suppliers across northern Taiwan, constraining new entrant scaling while anchoring procurement leverage among established vendors.
Taoyuan
Hyperscale cloud campuses drive lithium-ion UPS replacement cycles and liquid-cooled power module deployment. The Bureau of Energy enforces renewable energy certificate mandates that shape procurement timelines for solar and offshore wind power purchase agreements. Taoyuan's multi-hundred-megawatt facilities absorb engineering talent previously serving enterprise colocation segments.
New Taipei City
Dense GPU deployments above 50kW per rack require specialized high-efficiency rectifiers and busbars for AI training clusters. Grid interconnection queues extending 18-36 months freeze capital commitment timelines for campus developers. New Taipei City hosts the island's most concentrated hyperscale operator presence, enabling direct supplier relationships unbundled from colocation operators.
Taipei
Legacy enterprise colocation facilities maintain installed air-cooled infrastructure despite prohibitive retrofit capex without tenant pre-commitment. The National Communications Commission imposes uptime requirements on critical telecom infrastructure that shape backup power design. Chunghwa Telecom bundles power infrastructure with its dominant fiber backbone across northern Taiwan's integrated service offerings.
Taichung
Underdeveloped land banks and favorable grid infrastructure position central Taiwan for next-generation hyperscale cluster expansion. Taipower transmission upgrade schedules in this region offer shorter energization timelines compared to saturated northern corridors. International cloud providers are building multi-hundred-megawatt campuses, pulling demand for high-redundancy power distribution systems.
Taiwan Data Center Power Market Competitive Landscape
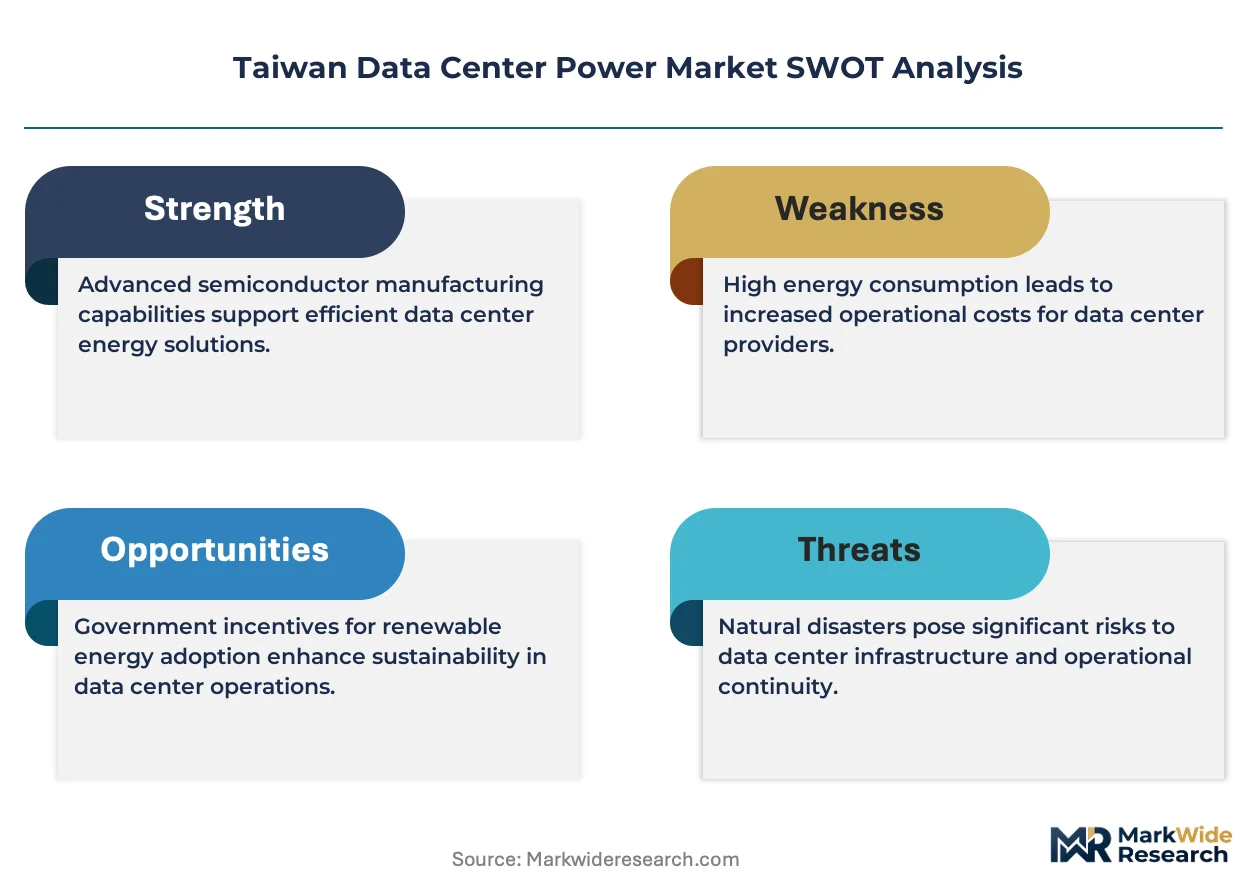
Top-tier vendors anchor the high-efficiency power module segment, while mid-tier suppliers compete on switchgear and UPS integration. The market structure concentrates procurement leverage among domestic Taiwanese producers with captive semiconductor fabrication capabilities. Three archetypes dominate: integrated power electronics manufacturers, localized switchgear fabricators, and telecom-backed infrastructure bundlers. Competitive moves center on backward integration into silicon carbide wafer supply and strategic partnerships for lithium-ion battery procurement.
Within the integrated electronics tier, Delta Electronics exemplifies the captive semiconductor supply chain model that dominates high-efficiency power module production. Schneider Electric occupies a position among localized manufacturing partnerships anchoring switchgear and UPS ecosystems through regional production arrangements. Chunghwa Telecom represents the telecom-integrated archetype, leveraging its fiber backbone dominance to bundle power infrastructure with connectivity services across northern Taiwan.
| Leading Market Players |
|---|
| Delta Electronics |
| Schneider Electric |
| Vertiv |
| Eaton |
| ABB |
| Legrand |
| Caterpillar |
| Chunghwa Telecom |
| Chief Telecom |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot prices cascade through Taiwan's data center power supply chain, compressing margins on lithium-ion UPS systems while amplifying pricing power for silicon carbide power module suppliers with captive wafer production.
Pricing Analysis
The bundled-versus-unbundled service split separates legacy colocation operators from hyperscale cloud tenants. Colocation providers historically stacked margins across space, power, and cooling in unified leases. Cloud providers now negotiate direct metered utility contracts and equipment ownership, stripping intermediary markups. Price differentiation rests on redundancy certification tier and volume commitment scale. Margins are tightening in commodity air-cooled segments as vendor attention shifts to liquid-cooled AI infrastructure. Enterprise colocation buyers exhibit highest price sensitivity; hyperscale operators with sustainability mandates accept premium pricing for renewable energy certificates.
Supply Chain Analysis
Reverse logistics for UPS battery refurbishment and generator component remanufacturing flow through specialized service networks concentrated in Taiwan and South Korea. Silicon carbide wafers and lithium-ion cells draw from Japanese and South Korean chemical suppliers, with power module fabrication anchored in Taiwanese foundries. Single-source vulnerability concentrates in Delta Electronics' captive silicon carbide supply. Distribution runs through direct OEM relationships with hyperscale operators in northern Taiwan, bypassing traditional electrical distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's data center power market functions as a regulatory compounder where Bureau of Energy renewable energy certificate mandates accelerate procurement velocity and reshape contract structures.
For Market Incumbents: Anchor defensive positioning through backward integration into silicon carbide wafer supply and lithium-ion cell procurement partnerships. Incumbent suppliers face emerging threat from cloud provider direct supplier relationships that disintermediate traditional channel structures. Priority lever sits with certification investment for liquid-cooled power modules addressing 100kW-plus GPU rack densities.
For New Entrants and Emerging Players: E-commerce-enabled direct sales channels offer lowest-friction entry path for specialized PDU and monitoring equipment vendors. Most penetrable white-space targets Taichung Science Park expansion where grid infrastructure offers shorter energization timelines than saturated northern corridors. Go-to-market angle should bundle power infrastructure with submarine cable landing station fiber backhaul at Tamsui and Fangshan.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier switchgear fabricators possessing localized manufacturing partnerships and Bureau of Energy compliance expertise. Long-term viability over five-to-ten year horizon hinges on renewable energy integration capabilities and AI workload density accommodation. Signal to watch is Taipower transmission upgrade queue position allocation as inflection indicator for campus development capital commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Scale-Up | Captive wafer supply secures margin control against Delta Electronics dominance in high-efficiency rectifiers. |
| Offshore Wind Power Purchase Agreement | Long-term contracts with Taiwan Power Company satisfy Bureau of Energy certificate mandates for hyperscale campuses. |
| Liquid Cooling Infrastructure Partnership | Immersion cooling dielectric fluid supply agreements address 100kW-plus GPU rack thermal loads in Taoyuan. |
| Energy Storage Integration Development | Co-located battery systems enable peak shaving revenue streams beyond backup power provision. |
| Electrical Engineering Talent Acquisition | Specialized 380/400V three-phase distribution expertise constrains new entrant scaling across northern Taiwan. |
Research Methodology
Direct dialogue with data center facility operators, electrical engineering contractors, Taipower grid planning officers, and renewable energy project developers grounded qualitative findings. Secondary validation drew from Bureau of Energy certificate issuance databases, Taipower transmission upgrade schedules, hyperscaler capital expenditure disclosures, and CNS electrical safety standards documentation. Bottom-up and top-down triangulation cross-checked facility-level power capacity installations against aggregate market sizing.
Bottom-up modeling aggregated individual hyperscale campus power requirements across Taoyuan, New Taipei City, and Taichung. Top-down analysis calibrated against Taiwan Power Company interconnection queue data and renewable energy certificate issuance trends. Segmentation dimensions spanned product type, power source, cooling technology, and end user archetype. CAGRs derived from facility energization timelines and equipment replacement cycle analysis. Industry-specific inputs included GPU rack density trajectories and Bureau of Energy mandate compliance deadlines.
Grid interconnection queue delays, lithium-ion supply concentration, and semiconductor equipment lead time extension are the dominant revision risks to modeled forecasts. Forecasts reflect assumptions on Taipower transmission upgrade execution and renewable energy certificate mandate enforcement intensity. Practitioners should monitor interconnection queue position allocation and offshore wind project commercial operation dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Virtual Infrastructure Manager Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Rack Market