
 Fiber Management Systems Market | 2026-2036
Fiber Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Management Systems Market Analysis
Hyperscale data center operators are unwinding legacy copper infrastructure budgets in favor of high-density fiber architectures. TE Connectivity Ltd. leverages its vertical integration into connector manufacturing to control costs across enclosure and patch panel lines. Corning Inc. anchors global supply through proprietary glass formulations that reduce signal attenuation in dense splice trays. Fujikura Ltd. specializes in fusion splicing equipment that integrates with rack-mounted management systems for telco central offices.
Fiber management systems encompass the physical hardware, cable routing infrastructure, and protective housings that organize, protect, and enable access to fiber optic connections in communications networks. These systems typically manage fiber counts from 12 to 3,456 strands, with bend-radius control specifications of 30mm minimum to prevent macro-bending losses in tight enclosures. Fiber enclosures and splice trays dominate installed value due to their role in protecting splices from environmental contamination and mechanical stress. Patch panels represent the fastest-growing product category as modular designs allow hot-swappable port reconfiguration without disrupting live circuits. Active optical cables are displacing passive components in high-performance computing clusters where signal regeneration at the cable assembly level reduces switch port complexity.
FCC broadband deployment mandates and the EU's F-Gas Regulation on cooling infrastructure shape data center fiber density requirements, while India's BIS certification for optical fiber cables governs import eligibility and product safety. The EU AI Act's infrastructure transparency rules will require documented cable management for audit trails in automated facilities. Stakeholders must monitor how national digital sovereignty frameworks fragment certification requirements across jurisdictions.
Market Dynamics
Hyperscale data center operators are unwinding legacy copper infrastructure budgets in favor of high-density fiber architectures, compressing deployment cycles from 18 months to 6 months for rack-level reconfigurations. This shift is concentrating procurement power among cloud operators while fragmenting vendor relationships across specialized component suppliers.
Growth Catalysts
- EU Green Deal energy mandates:Energy-efficient cabling standards favor advanced fiber management systems with lower attenuation losses, driving enclosure upgrades across German and French telecom infrastructure.
- India's telecom infrastructure buildout:Reliance Jio and Bharti Airtel are deploying massive fiber-to-the-home networks requiring splice tray densities above 1,000 fibers per enclosure.
- Fusion splicing automation:Rack-mounted management systems with integrated splicing equipment reduce central office labor hours by eliminating manual fiber preparation steps.
Market Restraints
- Proprietary glass supply concentration:Specialized low-attenuation formulations for dense splice trays depend on captive supply from a limited set of optical fiber manufacturers.
- EU F-Gas Regulation compliance costs:Cooling infrastructure modifications for high-density fiber environments add capital overhead before cable deployment can proceed.
- Active optical cable substitution:Signal regeneration at the cable assembly level reduces switch port complexity in high-performance computing clusters, compressing demand for passive management hardware.
Strategic Opportunities
- EU AI Act infrastructure transparency:Documented cable management for audit trails in automated facilities creates mandatory upgrade cycles for legacy installations.
- Modular patch panel hot-swappability:Port reconfiguration without disrupting live circuits enables telcos to monetize rapid service provisioning.
- BIS certification expansion:India's optical fiber cable import eligibility rules favor local assembly partnerships for enclosure and routing hardware.
Industry Challenges
- Fusion splicing technician scarcity:Central office automation requires skilled operators who can calibrate ribbon fiber cleavers and interpret OTDR traces under time pressure.
- Legacy copper-fiber integration complexity:Hybrid environments demand transitional enclosures that maintain bend-radius control across dissimilar cable types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Management Systems Market |
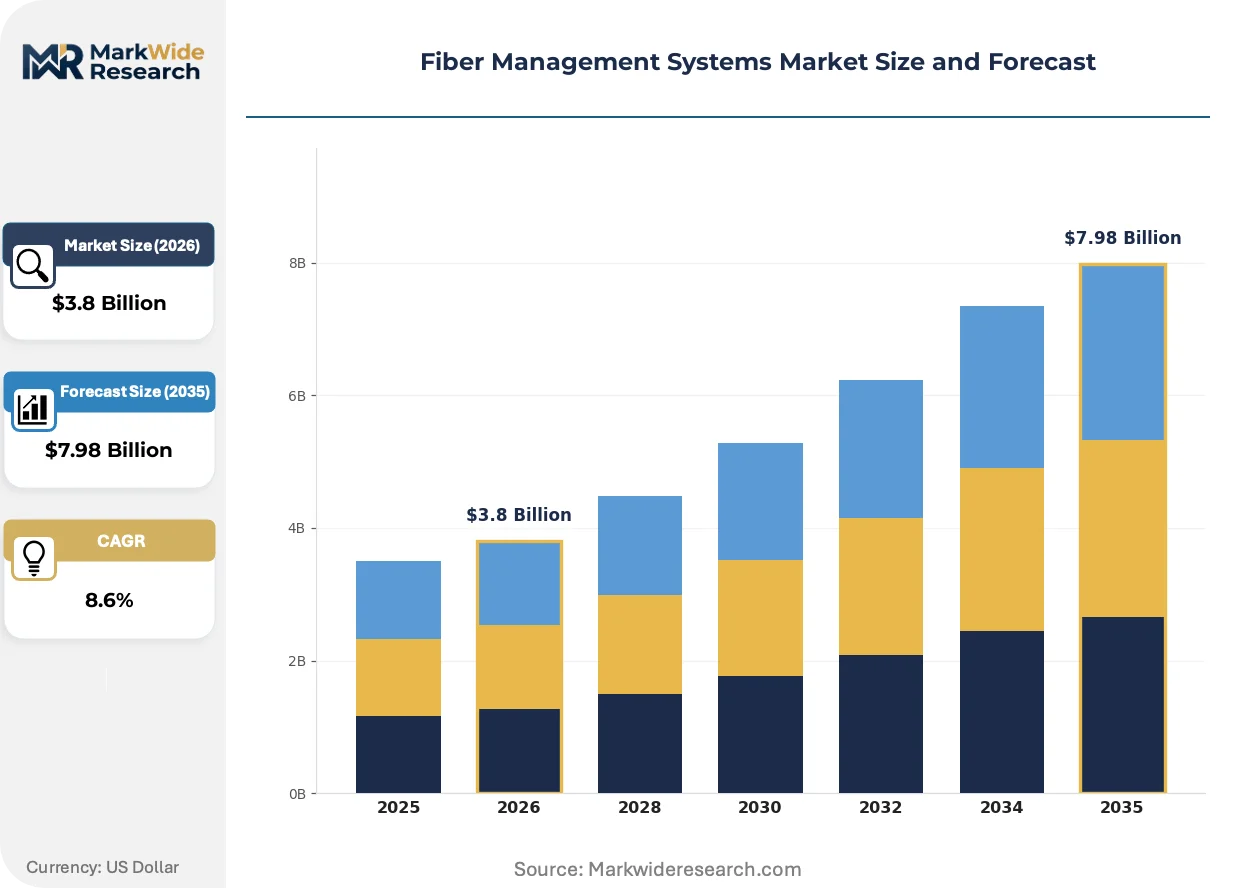
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Enclosures, Patch Panels, Splice Trays, Fiber Optic Splitters Technology: Active Optical Cables, Passive Components, Fiber Couplers, Optical Amplifiers End User: Telecommunications, Data Centers, IT Services, Enterprises Installation: Indoor, Outdoor, Wall-mounted, Rack-mounted |
| Companies Covered | TE Connectivity Ltd., HUBER+SUHNER, Corning Inc., 3M Co., Fujikura Ltd., Panduit Corp., Belden Inc., Schneider Electric SE, CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Management Systems Market Emerging Trajectories
Active optical cables are compressing the boundary between passive infrastructure and intelligent signal management, forcing enclosure manufacturers to accommodate powered assemblies within traditionally passive housings. This convergence is redrawing competitive boundaries between cable, connector, and management system suppliers.
Pre-terminated multi-fiber push-on assemblies are supplanting field-terminated connectors in hyperscale data centers, eliminating epoxy curing and polishing steps from deployment workflows. Cloud operators in Virginia and Oregon are specifying MPO-16 and MPO-32 configurations for 400G and 800G switch-to-switch links. This shift is compressing installation labor costs while elevating factory termination quality as the critical performance variable.
REACH substance restrictions and RoHS recast directives in Europe are banning specific flame retardants and plasticizers from enclosure polymers, forcing compound reformulation for splice tray housings. Manufacturers serving German and Dutch markets are accelerating halogen-free material transitions ahead of compliance deadlines. The regulatory pressure is fragmenting product lines into EU-certified and non-EU variants with diverging bill-of-materials.
Specification authority is migrating from general contractors to hyperscale network engineering teams, who now dictate bend-radius tolerances and port labeling standards directly to enclosure vendors. This disintermediation is compressing distributor margins while elevating technical sales support as the decisive commercial capability. The pattern is most visible in Northern Virginia's Data Center Alley, where Amazon Web Services and Microsoft Azure procurement teams maintain dedicated vendor engineering liaisons.
Fiber Management Systems Market Segmentation
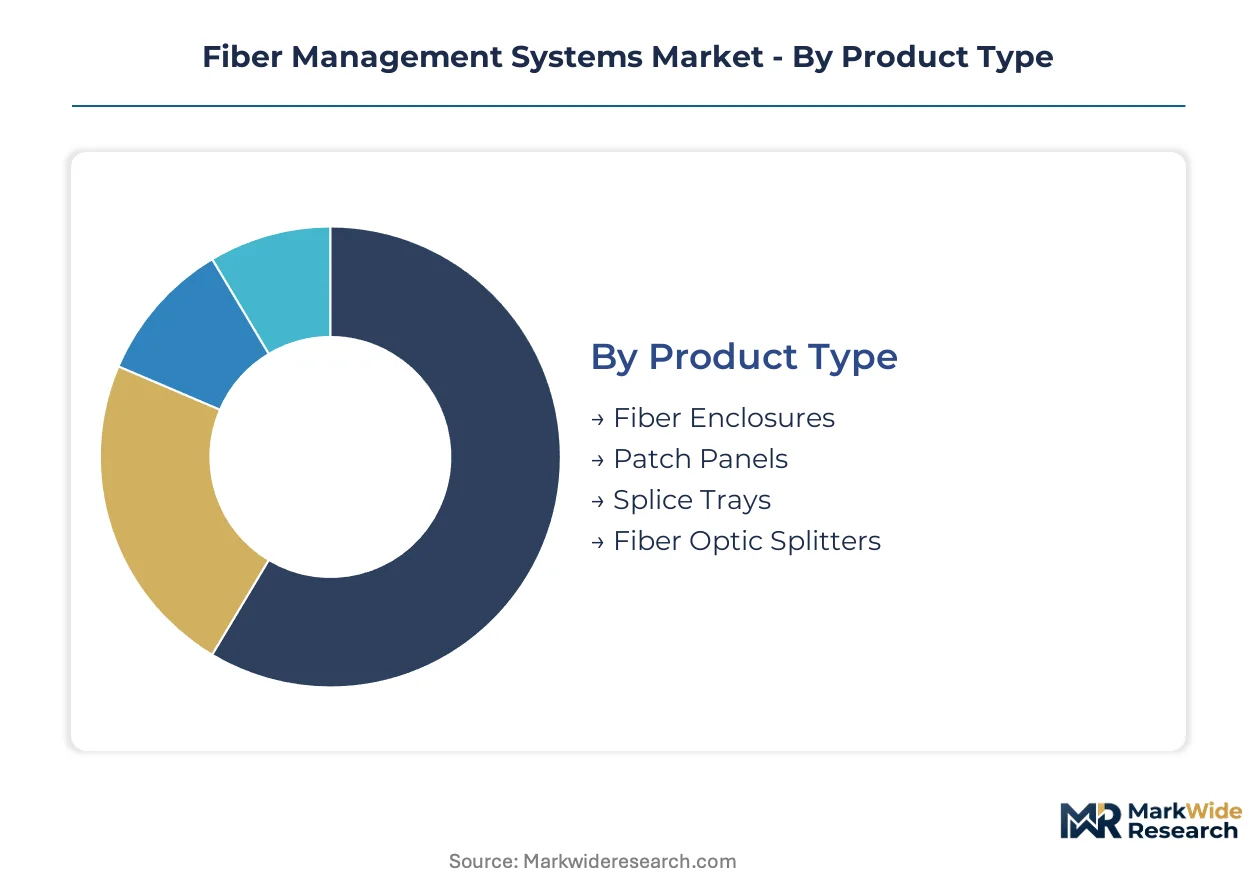
Fiber management systems fragment across multiple technical and commercial dimensions, with regulatory pressure on bend-radius specifications and splice density driving divergence between premium and standard tiers. Understanding these fault lines reveals where procurement power concentrates and which specifications command pricing premiums.
Product Type:
REACH substance restrictions and RoHS recast directives in Europe are fragmenting product lines into EU-certified and non-EU variants, with halogen-free compound reformulation elevating enclosure costs for splice tray housings.
- Fiber Enclosures:These protective housings organize fiber counts from 12 to 3,456 strands with minimum 30mm bend-radius control to prevent macro-bending losses. Demand concentrates in India's telecom infrastructure buildout where Reliance Jio and Bharti Airtel specify densities above 1,000 fibers per enclosure for fiber-to-the-home networks. EU Green Deal energy mandates are driving enclosure upgrades across German and French telecom infrastructure.
- Patch Panels:Modular designs enable hot-swappable port reconfiguration without disrupting live circuits, allowing telcos to monetize rapid service provisioning. Cloud operators in Virginia and Oregon are specifying MPO-16 and MPO-32 configurations for 400G and 800G switch-to-switch links, compressing installation labor costs while elevating factory termination quality.
- Splice Trays:Dense configurations protect splices from environmental contamination and mechanical stress in central offices.
- Fiber Optic Splitters:Passive optical network deployments rely on these for point-to-multipoint signal distribution in access networks.
Fiber enclosures handle the majority of throughput; patch panels are expanding most quickly on share.
Technology:
Cost tiers separate powered assemblies from passive infrastructure, with active components commanding 3-5x unit premiums over passive equivalents due to signal regeneration capabilities.
- Active Optical Cables:Signal regeneration at the cable assembly level reduces switch port complexity in high-performance computing clusters, compressing demand for passive management hardware. Hyperscale data center operators are unwinding legacy copper infrastructure budgets in favor of these high-density fiber architectures, compressing deployment cycles from 18 months to 6 months for rack-level reconfigurations.
- Passive Components:Fiber enclosures and splice trays dominate installed value due to their role in protecting splices from environmental contamination and mechanical stress. TE Connectivity leverages in-house production of connector manufacturing to control costs across enclosure and patch panel lines.
- Fiber Couplers:These devices combine or split optical signals in wavelength-division multiplexing systems.
- Optical Amplifiers:Erbium-doped fiber amplifiers extend transmission distances without electronic regeneration in long-haul networks.
Passive components handle the majority of throughput; active optical cables are climbing the fastest on share.
End User:
Customer type determines specification authority, with hyperscale network engineering teams now dictating bend-radius tolerances and port labeling standards directly to enclosure vendors rather than through general contractors.
- Telecommunications:Fusion splicing automation through rack-mounted management systems reduces central office labor hours by eliminating manual fiber preparation steps. India's BIS certification for optical fiber cables governs import eligibility and product safety, favoring local assembly partnerships for enclosure and routing hardware.
- Data Centers:Pre-terminated multi-fiber push-on assemblies are supplanting field-terminated connectors, eliminating epoxy curing and polishing steps from deployment workflows. FCC broadband deployment mandates shape fiber density requirements for hyperscale facilities.
- IT Services:Managed service providers require transitional enclosures that maintain bend-radius control across hybrid copper-fiber environments.
- Enterprises:Corporate networks prioritize wall-mounted and rack-mounted installations for campus and building connectivity.
Telecommunications handles the majority of throughput; data centers are gaining share fastest.
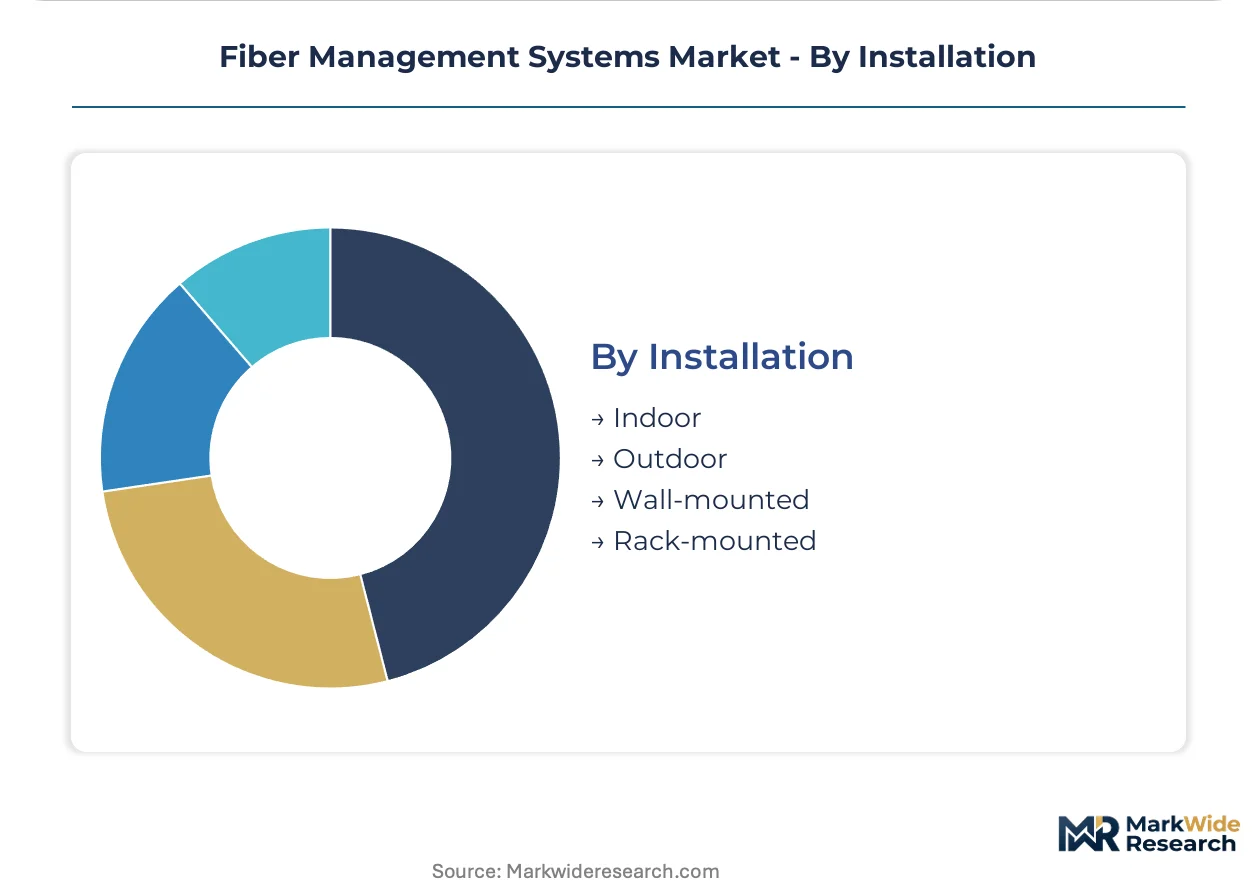
Installation:
Volume concentrates in rack-mounted configurations for data center and central office environments, with outdoor installations commanding weatherization premiums.
- Indoor:Climate-controlled environments enable higher fiber densities with reduced environmental protection requirements.
- Outdoor:Hardened enclosures withstand temperature extremes and moisture ingress for aerial and underground deployments.
- Wall-mounted:Space-constrained enterprise and residential applications favor these compact configurations.
- Rack-mounted:Standard 19-inch and 23-inch form factors dominate data center and telecom central office installations, with specification authority migrating from general contractors to hyperscale network engineering teams who maintain dedicated vendor engineering liaisons in Northern Virginia's Data Center Alley.
Rack-mounted installations handle the majority of throughput; outdoor configurations are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese enclosure manufacturers export high-density splice tray assemblies to German and French telecom operators upgrading infrastructure under EU Green Deal mandates. This trade corridor channels Asian production capacity into European energy-efficiency compliance cycles.
United States
FCC broadband deployment mandates and hyperscale data center construction in Northern Virginia's Data Center Alley concentrate demand for rack-mounted patch panels. AWS and Microsoft Azure procurement teams dictate bend-radius tolerances directly to enclosure vendors. Cloud operators specify MPO-16 and MPO-32 configurations for 400G and 800G switch links.
Germany
EU Green Deal energy mandates and the F-Gas Regulation drive enclosure upgrades across Deutsche Telekom infrastructure. REACH substance restrictions and RoHS recast directives ban specific flame retardants from splice tray housings. Manufacturers accelerate halogen-free material transitions ahead of compliance deadlines in Bavaria and North Rhine-Westphalia industrial clusters.
India
Reliance Jio and Bharti Airtel deploy massive fiber-to-the-home networks requiring splice tray densities above 1,000 fibers per enclosure. BIS certification for optical fiber cables governs import eligibility and favors local assembly partnerships. Infrastructure buildout concentrates in Maharashtra and Karnataka telecom corridors.
France
National digital sovereignty agendas mandate energy-efficient cabling standards favoring advanced fiber management. ANSM and CNIL data governance frameworks intersect with EU AI Act infrastructure transparency rules requiring documented cable management for audit trails. Deployment activity clusters around Paris-Saclay and Lyon digital infrastructure zones.
Netherlands
EU Green Deal implementation and Amsterdam data center expansion create dual demand for high-density fiber architectures. Cooling infrastructure modifications under F-Gas Regulation add capital overhead before cable deployment proceeds. The Randstad region hosts specification authority migration from contractors to hyperscale network engineering teams.
Fiber Management Systems Market Vendor Landscape
Listed leaders compete with private specialists across enclosure and connectivity portfolios, creating a tiered structure where scale-driven conglomerates face focused component fabricators. Market concentration splits between diversified electrical equipment groups and pure-play fiber infrastructure vendors. Three archetypes dominate: integrated connector-enclosure suppliers, proprietary glass formulation specialists, and fusion splicing equipment manufacturers. Competitive moves center on backward integration into raw materials and strategic partnerships for regional certification compliance.
Within the integrated supplier tier, TE Connectivity Ltd. and Corning Inc. occupy anchor positions, while Fujikura Ltd. exemplifies the splicing-specialist archetype. These three companies represent contrasting strategic postures: TE Connectivity leverages in-house production of connector manufacturing, Corning anchors global supply through captive optical fiber production, and Fujikura sits within the equipment-automation segment serving telco central offices. Their collective presence spans the value chain from raw glass to rack-mounted management systems.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| HUBER+SUHNER |
| Corning Inc. |
| 3M Co. |
| Fujikura Ltd. |
| Panduit Corp. |
| Belden Inc. |
| Schneider Electric SE |
| CommScope |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese enclosure manufacturers shapes both supply concentration and price floors across fiber management tiers. Dense splice tray production runs at scale in Asian industrial clusters, compressing unit economics for standard-density enclosures while premium EU-certified variants command substantial markups for halogen-free compound reformulation.
Pricing Analysis
400G-to-800G generation pricing gaps separate MPO-16 and MPO-32 patch panel configurations from legacy LC duplex assemblies by 2-3x unit premiums. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and fiber density specifications. Pricing pressure stems from active optical cable substitution in high-performance computing clusters, compressing margins for passive management hardware. Hyperscale cloud operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while regional telcos in India negotiate aggressively on enclosure volume contracts.
Supply Chain Analysis
Strategic stockpiling of specialized low-attenuation glass formulations prevails among enclosure manufacturers facing proprietary supply concentration. Production gravity centers on China, Japan, and the United States for optical fiber and connector components. Raw material dependencies include erbium-doped fiber for amplification, halogen-free polymer compounds for EU compliance, and precision ceramic ferrules for MPO assemblies. Single-source vulnerability from captive glass formulation supply creates structural risk. Distribution runs through direct vendor engineering liaisons to hyperscale procurement teams, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
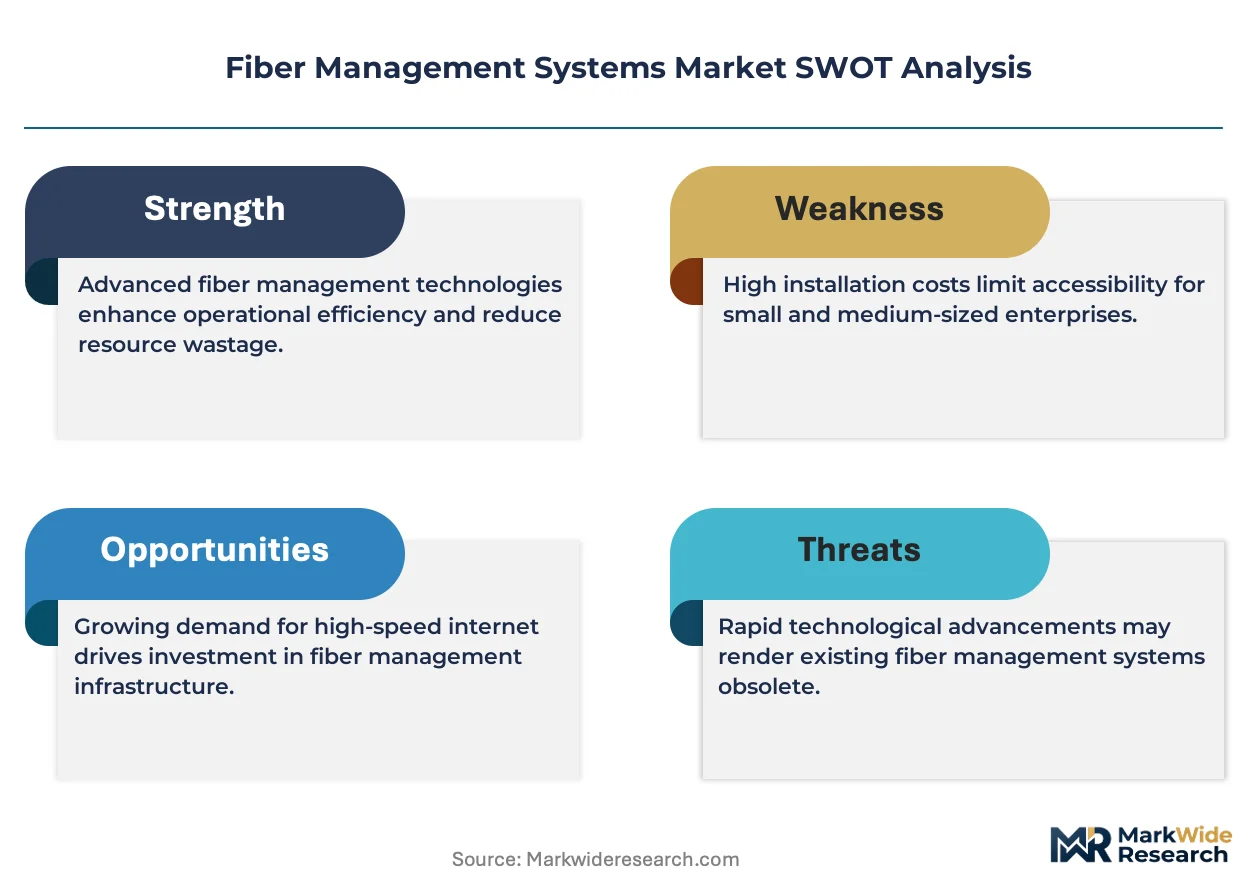
Fragmentation opportunity emerges from specification authority migration toward hyperscale network engineering teams, creating specialized niches for component fabricators outside integrated supplier hierarchies.
For Market Incumbents: Compound defensive positioning through backward integration into halogen-free polymer compounding for EU Green Deal compliance, and through captive supply agreements for low-attenuation glass formulations. Active optical cable substitution threatens passive management hardware margins; enclosure manufacturers must accommodate powered assemblies within traditionally passive housings. Capacity addition in Indian assembly partnerships addresses BIS certification requirements while deflecting price pressure from Chinese competitors. For New Entrants and Emerging Players: Differentiate on fusion splicing automation integration for telco central offices, where technician scarcity creates service-attach opportunities. White-space targets include modular patch panel hot-swappability for rapid service provisioning, and documented cable management systems for EU AI Act audit trail compliance. India's telecom infrastructure buildout offers the most penetrable geography; pursue local assembly partnerships to satisfy BIS certification for optical fiber cable import eligibility. For Investors and Strategic Acquirers: Fusion splicing equipment-automation specialists with rack-mounted management system integration capabilities present acquisition targets with defensive positioning against labor cost inflation. Long-term viability rests on central office automation penetration and hyperscale data center construction cycles. Signal to watch is MPO-32 configuration adoption velocity among cloud operators in Northern Virginia and Oregon, indicating next-generation port density demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Compounds | REACH and RoHS recast compliance in German and Dutch markets secures EU revenue streams. |
| Fusion Splicing Equipment Automation | Rack-mounted management systems reduce Deutsche Telekom central office labor hours substantially. |
| Local Assembly Partnerships in India | BIS certification compliance enables access to Reliance Jio and Bharti Airtel fiber-to-the-home deployments. |
| MPO-32 Configuration Factory Termination | AWS and Microsoft Azure 800G switch link specifications elevate quality as decisive performance variable. |
| Powered Assembly Enclosure Accommodation | Active optical cable convergence redraws competitive boundaries between cable and management suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center network engineering directors, telecom central office operations managers, fiber enclosure procurement leads, and fusion splicing equipment technicians. Secondary validation drew from FCC broadband deployment filings, EU Green Deal implementation documents, BIS certification registries, and hyperscaler capital expenditure disclosures. Bottom-up volume modeling and top-down value triangulation reconciled manufacturer shipment data with end-user deployment schedules.
Across the projection horizon, analytical frameworks segmented fiber management systems by product type, technology generation, end-user vertical, and installation environment. CAGRs were derived from regression analysis against broadband deployment mandates and data center construction pipelines. Industry-specific forecast inputs included MPO configuration adoption curves and EU F-Gas Regulation compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale data center construction or abrupt regulatory relaxation would require recalibration. Forecasts reflect documented assumptions regarding fiber density migration and active-passive technology substitution. Revision becomes warranted when active optical cable penetration in high-performance computing clusters crosses thresholds that structurally compress passive management hardware demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
US Data Center Construction Market