
 Next Generation Data Center Market | 2026-2036
Next Generation Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Data Center Market Analysis
The EU Green Deal is decoupling data center expansion from carbon-intensive power sourcing across European markets. Nvidia leverages its GPU dominance to anchor AI training clusters with specialized thermal architectures. Microsoft sustains hyperscale builds through direct renewable power contracts and liquid cooling pilots. Schneider Electric controls the physical infrastructure layer with prefabricated modular systems that compress deployment timelines.
Next generation data centers integrate high-density compute, advanced thermal management, and software-defined orchestration to support workloads exceeding 100 kW per rack. These facilities serve as the substrate for enterprise AI inference, real-time analytics, and distributed edge processing. Rack servers occupy the volume tier where margin compression forces OEMs toward service attach and lifecycle management. Edge computing solutions represent the fastest-expanding deployment mode as latency requirements harden for autonomous systems and industrial IoT. AI optimization sits at the premium tier where specialized silicon and workload scheduling command pricing power.
The EPA enforces Energy Star certification thresholds that filter inefficient designs from federal procurement pools. FERC interconnection queues in key US markets constrain power delivery timelines to 36-48 months, forcing developers toward behind-the-meter generation. ISO standards for IT equipment energy efficiency shape product roadmaps across OEM supply chains. Stakeholders must weigh stranded asset risk against the capital intensity of liquid-cooled infrastructure commitments.
Market Dynamics
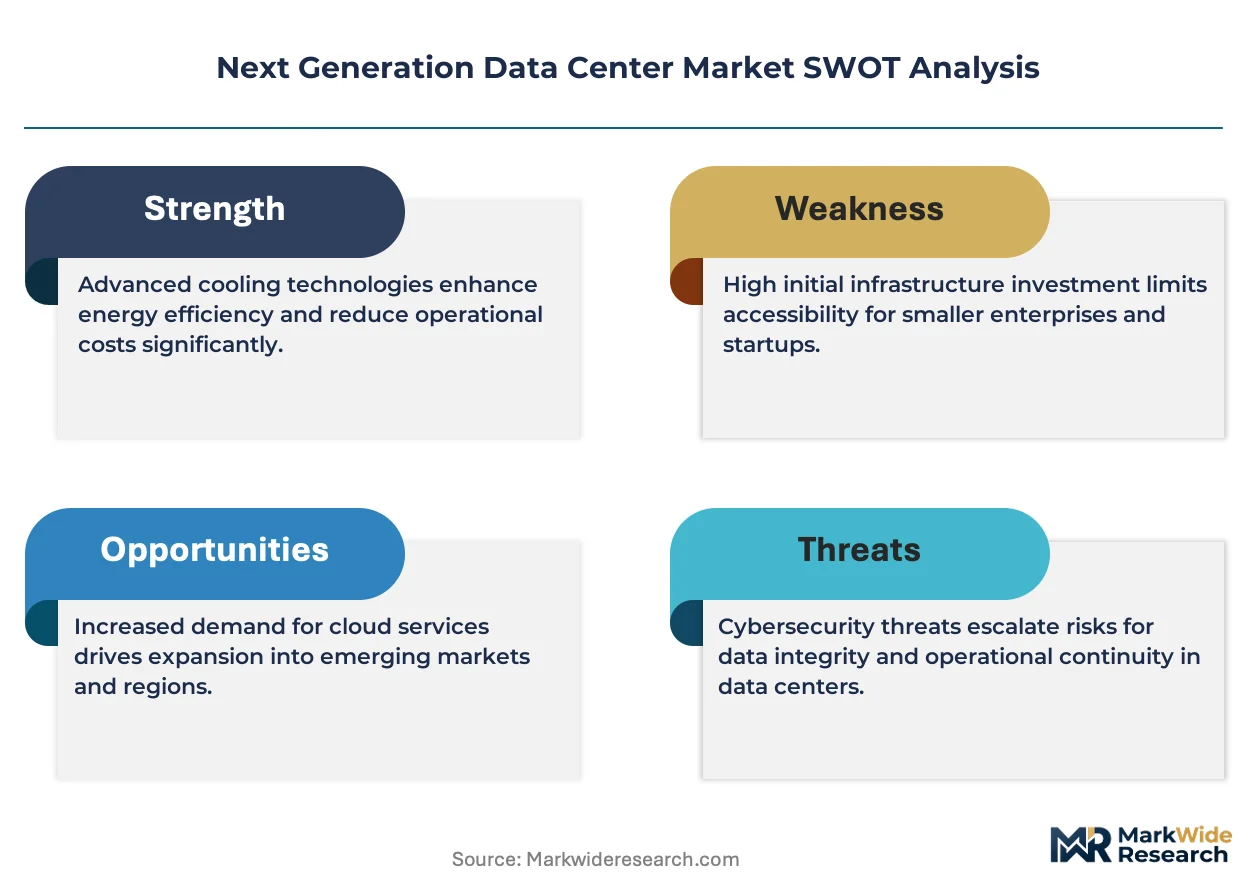
Power interconnection queues stretching to 48 months are compressing data center deployment timelines and forcing developers toward captive generation and modular construction methods that bypass traditional utility infrastructure.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale operators are commissioning facilities exceeding 100 MW to accommodate GPU-dense racks for foundation model development, with rack power densities climbing past 50 kW.
- EU Green Deal Mandates:The European Commission's tightening carbon intensity thresholds for digital infrastructure are accelerating renewable power procurement and liquid cooling adoption across continental facilities.
- Edge Latency Requirements:Autonomous vehicle systems and industrial IoT deployments are mandating sub-10 millisecond response times, pulling compute capacity toward distributed metro edge locations.
Market Restraints
- Copper and Electrical Steel Volatility:Transformer core materials and busbar commodities face supply tightness from mining concentration in Chile and Peru, inflating electrical infrastructure costs.
- Taiwan Semiconductor Concentration:Advanced GPU and custom ASIC fabrication remains concentrated with TSMC, creating single-source dependency for AI-optimized silicon.
- FERC Interconnection Backlogs:Federal Energy Regulatory Commission queue delays in Northern Virginia and Texas markets extend power delivery timelines beyond typical facility construction cycles.
Strategic Opportunities
- Nordic Renewable Arbitrage:Norway and Iceland offer sub-0.05 USD per kWh hydroelectric and geothermal power with ambient cooling advantages for high-density AI training deployments.
- Direct Liquid Cooling Convergence:Integration of single-phase and two-phase immersion systems with heat reuse networks is opening district heating revenue streams in Northern European markets.
- India PLI Scheme Incentives:The country's production-linked incentive scheme for IT hardware manufacturing is attracting server and storage OEM assembly operations to reduce import dependency.
Industry Challenges
- Thermal Engineering Talent Scarcity:Specialized expertise in computational fluid dynamics and two-phase heat transfer mechanics remains concentrated among a narrow cohort of vendors and research institutions.
- Liquid Cooling Retrofit Complexity:Existing air-cooled facilities face structural floor loading constraints and piping infrastructure gaps that complicate conversion to high-density liquid-cooled architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Data Center Market |
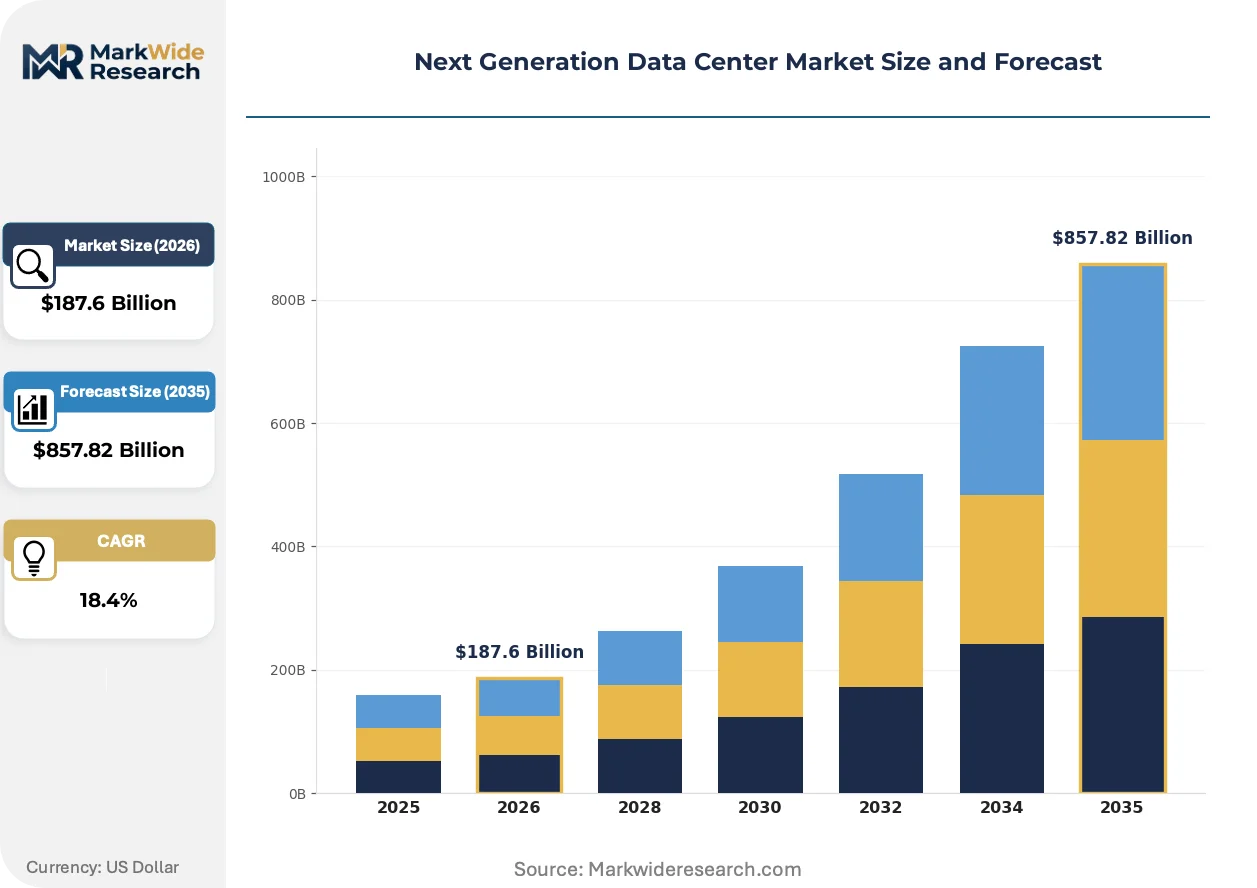
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Hyper-Converged Infrastructure, Edge Computing Solutions, Rack Servers Technology: AI Optimization, Cloud Integration, Virtualization, Cooling Solutions End User: Telecommunication, BFSI, Media & Entertainment, E-commerce Deployment: On-Premises, Co-location, Hybrid Cloud, Managed Service |
| Companies Covered | Nvidia, Microsoft, Dell Technologies, Equinix, HPE, Broadcom, Digital Realty, Schneider Electric, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Data Center Market Emerging Trajectories
Software-defined power and cooling orchestration is displacing static infrastructure provisioning, enabling real-time workload placement based on carbon intensity, thermal headroom, and electricity price signals.
Immersion cooling using engineered dielectric fluids is unifying heat capture and reuse functions in a single mechanical layer. Hyperscale operators in Singapore and the Netherlands are piloting two-phase systems for racks exceeding 80 kW. This unifying architecture is compressing the traditional separation between IT and facilities engineering teams into integrated platform operations.
The EPA's Energy Star certification thresholds for data center energy efficiency are filtering inefficient designs from federal procurement pools. Equipment manufacturers must now submit measured power usage effectiveness data rather than design specifications. Colocation providers serving government workloads are retrofitting legacy facilities to meet these thresholds or exiting the federal segment entirely.
Enterprise buyers are consolidating vendor relationships around full-stack infrastructure platforms that bundle compute, storage, networking, and management software. Systems integrators are displacing traditional value-added resellers in mid-market accounts. This concentration is most visible in Germany and Japan, where IT procurement teams face headcount constraints and prefer single-throat accountability for performance outcomes.
Next Generation Data Center Market Segmentation
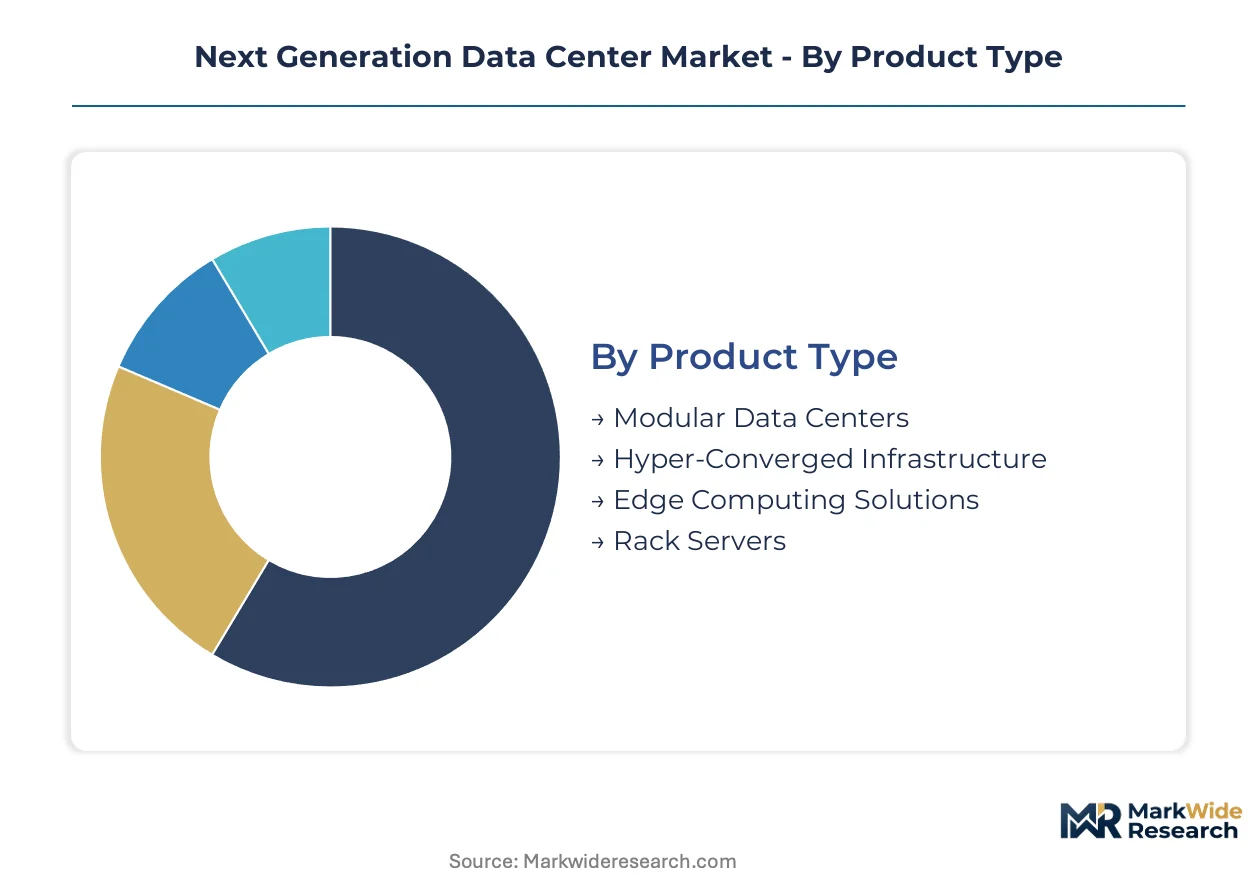
Next generation data center segmentation reveals how infrastructure investments fragment across performance tiers, thermal architectures, and operational models. Buyers optimize procurement across these axes based on workload density, latency requirements, and capital deployment preferences.
Product Type:
Rack density specifications and deployment velocity separate the four product architectures serving distinct commercial tiers.
- Modular Data Centers:Prefabricated steel enclosures integrate power distribution, cooling, and IT racks for rapid field assembly. Demand concentrates in Northern Virginia and Dallas-Fort Worth where FERC interconnection delays compress traditional construction timelines.
- Edge Computing Solutions:Micro-facilities under 500 kW deploy at cellular base stations and industrial sites. Autonomous vehicle infrastructure in Germany and Japan pulls compute toward metro edge locations with sub-10 millisecond latency requirements.
- Hyper-Converged Infrastructure:Software-defined compute-storage convergence reduces rack footprint for mid-market enterprises.
- Rack Servers:Standardized 19-inch enclosures remain the volume tier for enterprise refresh cycles.
Rack Servers lead on scale; Edge Computing Solutions lead on momentum.
Technology:
Energy efficiency mandates and thermal headroom constraints reshape technology procurement priorities across deployment scales.
- Cooling Solutions:Single-phase immersion and two-phase dielectric systems capture heat at rack densities exceeding 80 kW. Singapore and Netherlands pilots demonstrate heat reuse integration with district heating networks.
- AI Optimization:Workload scheduling algorithms and specialized silicon placement maximize inference throughput per watt. GPU-dense training clusters in Norway exploit sub-0.05 USD per kWh hydroelectric power with ambient cooling advantages.
- Cloud Integration:API-native orchestration layers unify multi-tenant resource pools.
- Virtualization:Hypervisor abstraction remains foundational for server consolidation ratios.
Virtualization leads on installed base; AI Optimization climbs the fastest.
End User:
Latency sensitivity and regulatory exposure differentiate sector investment intensity.
- BFSI:Real-time fraud detection and algorithmic trading drive sub-millisecond co-location proximity to financial exchanges. EU Green Deal carbon intensity thresholds accelerate renewable procurement across Frankfurt and London facilities.
- Telecommunication:5G core network functions and radio access virtualization mandate distributed edge presence. Indian PLI scheme incentives attract server assembly operations to reduce import dependency for domestic carrier infrastructure.
- E-commerce:Seasonal demand spikes favor hybrid burst capacity models.
- Media & Entertainment:Streaming encoding farms prioritize cost-optimized cloud regions.
Telecommunication leads on deployment count; BFSI leads on power density per square meter.
Deployment:
Capital efficiency requirements and data sovereignty rules determine operational model selection.
- Co-location:Wholesale and retail leasing transfers facility construction risk to specialized operators. EPA Energy Star certification thresholds filter inefficient designs from federal procurement pools, forcing retrofit investments or segment exit.
- Hybrid Cloud:Workload portability between on-premises and public cloud pools optimizes cost per transaction. Enterprise buyers in Germany and Japan consolidate vendor relationships around full-stack platforms bundling compute, storage, and management software.
- On-Premises:Dedicated facilities retain control for classified or regulated workloads.
- Managed Service:Outsourced operations reduce headcount requirements for mid-market enterprises.
Co-location leads on new capacity additions; Hybrid Cloud gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal engineering talent concentrates in Germany, the United States, and Singapore, anchoring design capabilities for liquid-cooled infrastructure. This workforce distribution shapes where next-generation facilities achieve technical validation before scaling to broader deployment.
United States
Hyperscale operators commission facilities exceeding 100 MW for GPU-dense training clusters. FERC interconnection queues in Northern Virginia and Texas extend power delivery timelines to 36-48 months, forcing developers toward captive generation. Dallas-Fort Worth and Northern Virginia host the densest construction activity as cloud providers expand capacity.
Germany
Automotive and industrial IoT deployments mandate sub-10 millisecond edge latency, pulling compute toward metro locations. EU Green Deal carbon intensity thresholds accelerate renewable procurement across Frankfurt facilities. Bavaria and Baden-Württemberg concentrate precision engineering talent for thermal management system design.
Netherlands
Heat reuse integration with district heating networks creates revenue streams for high-density deployments. REACH and F-Gas Regulation constrain dielectric fluid selection for immersion cooling systems. Amsterdam and Eindhoven pilot two-phase immersion for racks exceeding 80 kW.
Singapore
Tropical ambient conditions drive adoption of advanced thermal architectures for AI training infrastructure. The national energy regulator imposes strict power usage effectiveness thresholds on new facility approvals. The city-state hosts validation programs for single-phase immersion cooling before regional rollout.
Norway
Sub-0.05 USD per kWh hydroelectric power attracts AI training cluster investment with ambient cooling advantages. The country's grid operator prioritizes renewable interconnection for data center loads. Oslo and Bergen host facilities exploiting Nordic renewable arbitrage for foundation model development.
Next Generation Data Center Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the infrastructure stack. The market exhibits tiered concentration: semiconductor foundries and hyperscale operators anchor the premium tier, while modular fabricators and colocation specialists populate the mid-market. Three archetypes dominate—silicon suppliers commanding thermal design influence, facility operators controlling physical deployment velocity, and systems integrators bundling full-stack platforms. Competitive moves center on renewable power contracting and liquid cooling technology licensing.
Within the silicon-dominated tier, Nvidia and Broadcom exemplify specialized suppliers whose architectures shape facility thermal specifications. Microsoft and Google Cloud occupy positions as hyperscale operators vertically integrating renewable procurement with direct facility construction. Among physical infrastructure specialists, Schneider Electric represents the modular systems archetype compressing deployment timelines through prefabricated integration.
| Leading Market Players |
|---|
| Nvidia |
| Microsoft |
| Dell Technologies |
| Equinix |
| HPE |
| Broadcom |
| Digital Realty |
| Schneider Electric |
| Google Cloud |
| Others |
Supply Flow & Price Mechanics
Hyperscale operators' procurement consolidation around full-stack infrastructure platforms is forcing OEMs to unbundle hardware from lifecycle services or absorb margin compression entirely. This buyer-side concentration rewards vendors with captive renewable power contracting and liquid cooling integration capabilities while squeezing pure-play component suppliers.
Pricing Analysis
The bundled-versus-unbundled service split separates pricing power across the infrastructure stack. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EPA Energy Star thresholds filter federal procurement toward premium tiers while commodity rack servers face price erosion. Cost compression in the volume tier is intensifying because margin pressure forces OEMs toward service attach revenue. Mid-market enterprises exhibit highest price sensitivity; hyperscale operators with direct renewable contracts show lowest sensitivity due to operational savings capture.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand while systems integrators and value-added resellers serve mid-market accounts. Taiwan, China, and the United States concentrate advanced GPU, custom ASIC, and modular infrastructure fabrication. Copper from Chile, electrical steel for transformer cores, and engineered dielectric fluids for immersion cooling systems constitute critical input dependencies. Single-source vulnerability around TSMC advanced node production creates chokepoint exposure. Distribution runs through specialized physical infrastructure distributors in Northern Virginia and Dallas-Fort Worth clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next generation data center infrastructure functions as a stable compounder where AI training cluster expansion and EU Green Deal mandates drive steady capacity investment across the analysis window.
For Market Incumbents: Anticipate thermal engineering talent scarcity and FERC interconnection backlogs as structural constraints that favor early liquid cooling commitments and captive generation investments. Vertical integration into renewable power contracting and prefabricated modular system design preserves margin position against pure-play hardware commoditization. Prioritize certification engineering for EPA Energy Star thresholds to maintain federal procurement access. For New Entrants and Emerging Players: Capture Nordic renewable arbitrage opportunities in Norway and Iceland where sub-0.05 USD per kWh hydroelectric power attracts GPU-dense training cluster demand with minimal incumbent saturation. District heating integration in Northern European markets represents underexploited white space for heat reuse revenue streams. Lead with direct liquid cooling convergence as the go-to-market angle to bypass air-cooled incumbent relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal engineering firms and modular infrastructure fabricators holding validated two-phase immersion cooling IP. The 5-10 year investment horizon rewards platforms combining software-defined orchestration with physical deployment velocity. Watch FERC interconnection queue clearance rates as the inflection indicator for construction timeline normalization and capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Deployment | Enables rack densities exceeding 80 kW for AI training clusters in Singapore and Netherlands pilots. |
| Renewable Power Purchase Agreement | Secures sub-market electricity rates for hyperscale facilities in Norway and Iceland hydroelectric markets. |
| Prefabricated Modular System Expansion | Compresses deployment timelines in Northern Virginia where FERC queues extend beyond 36 months. |
| Thermal Engineering Talent Acquisition | Addresses scarcity in computational fluid dynamics expertise concentrated in Germany and Singapore. |
| Heat Reuse Network Integration | Opens district heating revenue streams through REACH-compliant dielectric fluid systems in Amsterdam. |
Methodological Framework
Direct dialogue with data center facility operators, hyperscale procurement executives, thermal engineering specialists, and physical infrastructure OEMs grounded the qualitative assessment. Secondary validation drew from EPA Energy Star certification databases, FERC interconnection queue filings, EU Green Deal regulatory texts, and hyperscaler capital expenditure disclosures. Bottom-up facility deployment tracking and top-down infrastructure investment flow analysis enabled triangulation across modeling approaches.
Bottom-up modeling of rack density specifications, cooling technology adoption curves, and regional power contracting patterns anchored volume projections. Segmentation across product type, technology tier, end-user sector, and deployment model shaped the analytical framework. CAGRs derived from facility construction pipeline analysis, renewable interconnection approval rates, and AI workload density trajectories. Power usage effectiveness thresholds and liquid cooling retrofit complexity served as industry-specific forecast modifiers.
Copper and electrical steel commodity volatility, Taiwan semiconductor concentration risk, and FERC queue clearance delays are the dominant revision risks to capacity deployment assumptions. Forecasts reflect baseline assumptions regarding EU Green Deal enforcement continuity and hyperscale renewable procurement momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Netherlands Data Center Power Market