
 Vietnam Data Center Rack Market | 2026-2036
Vietnam Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Rack Market Insights
Multi-source procurement is consolidating as the dominant sourcing pattern among Vietnamese colocation operators and cloud builders. Schneider Electric SE anchors the premium segment through its integrated power-and-cooling rack architectures. Rittal GMBH & Co.KG competes on thermal management specialization for tropical climates. Huawei Technologies Co. Ltd. leverages local assembly partnerships to control landed cost positions.
A data center rack is a standardized structural frame designed to house, organize, and protect servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA width specifications and load ratings from 1,000 to 3,000 pounds. Its primary purpose is to maximize spatial density while enabling airflow management, cable routing, and physical security in climate-controlled facilities. Enclosed rack and cabinet rack configurations command the widest deployment in Vietnam's enterprise and telecommunications sectors due to dust filtration requirements and tropical humidity conditions. High-density capacity designs represent the fastest-expanding category as GPU-intensive AI workloads reshape power-per-rack specifications.
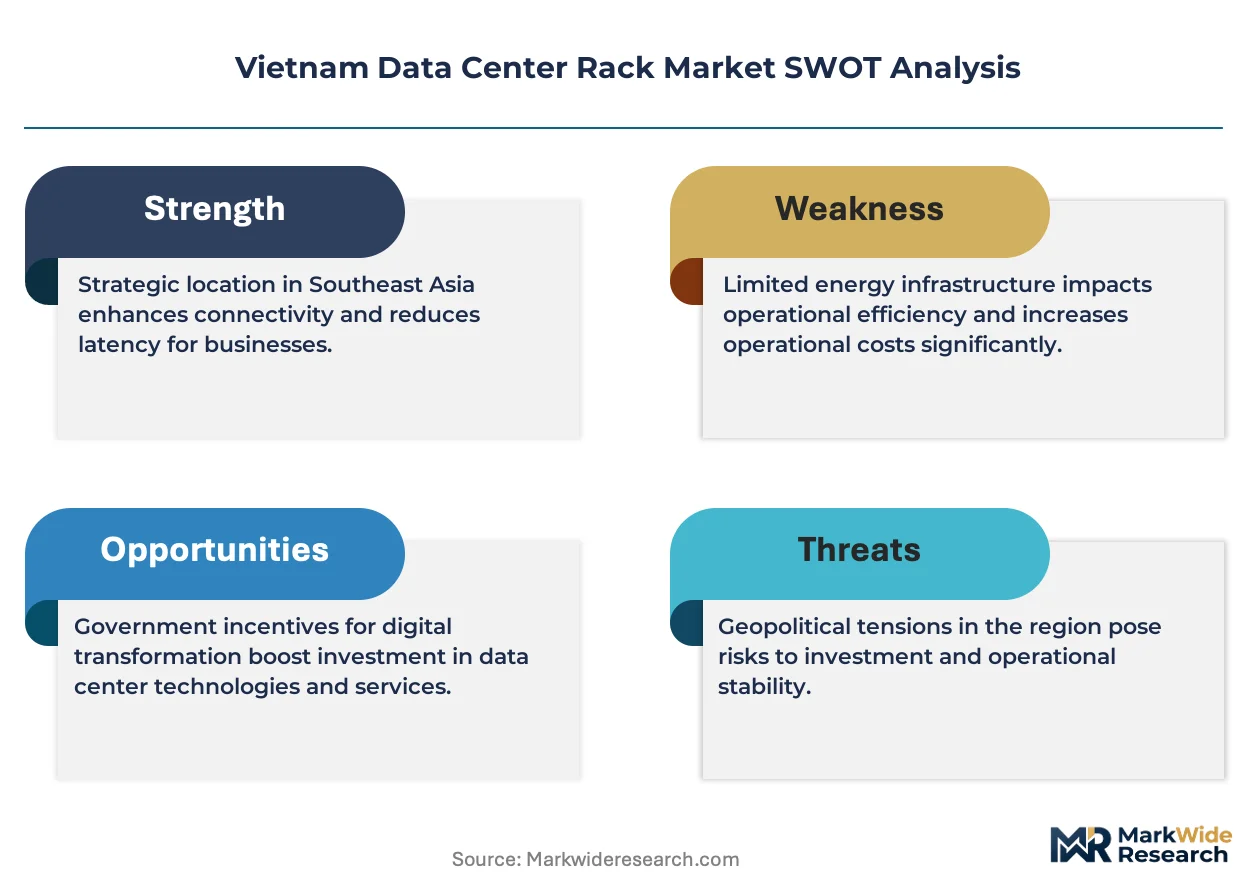
Vietnam's Ministry of Information and Communications and the national technical standards body shape data center construction through facility certification requirements and energy efficiency benchmarks. The country's central bank and cybersecurity regulators impose data localization mandates that directly expand domestic rack deployment. Stakeholders must monitor how evolving national digital infrastructure policies and provincial power allocation decisions affect site selection and rack specification timelines.
Market Dynamics
Hyperscale cloud deployments across northern Vietnam are compressing procurement cycles and forcing rack suppliers to certify high-density thermal architectures before facility construction begins.
Growth Catalysts
- National Digital Infrastructure Masterplan:Vietnam's government directive mandates domestic data localization, compelling foreign cloud operators to build owned facilities rather than lease cross-border capacity.
- GPU-intensive AI workloads:Machine learning training clusters now demand 50-100kW per rack, rendering legacy 10kW designs obsolete and triggering replacement cycles across Hanoi-Hai Phong corridor facilities.
- Provincial power allocation:Bac Giang and Thai Binh provinces offer prioritized grid connections for certified Tier III facilities, concentrating greenfield construction in these zones.
Market Restraints
- Steel and aluminum input volatility:Rack enclosure manufacturing faces margin compression from fluctuating Southeast Asian metal spot prices, forcing suppliers to index contracts quarterly.
- Cooling equipment supply concentration:Precision air conditioning units for tropical climates originate primarily from Chinese and South Korean manufacturers, creating single-source vulnerability during port congestion.
- Land cost escalation:Industrial zoned parcels within 50 kilometers of Hanoi have tripled in lease rates since 2022, squeezing facility economics for mid-scale colocation operators.
Strategic Opportunities
- Central Vietnam coastal corridor:Da Nang and Quang Nam offer submarine cable landing points with lower land costs than northern provinces, attracting disaster-recovery facility investments.
- Liquid cooling convergence:Integration of direct-to-chip cooling with traditional aisle containment allows retrofit of existing facilities without full infrastructure replacement.
- Energy efficiency certification incentives:Vietnam's revised building codes grant expedited permitting for facilities achieving PUE below 1.4, accelerating adoption of certified rack-integrated cooling designs.
Industry Challenges
- Certified technician scarcity:Installation and commissioning of high-density power distribution units requires electricians trained to IEC 61439 standards, with fewer than 200 certified practitioners currently active nationwide.
- Legacy facility retrofit complexity:Existing enterprise data centers built to 5-8kW per rack specifications cannot accommodate AI server densities without complete electrical and mechanical infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Rack Market |
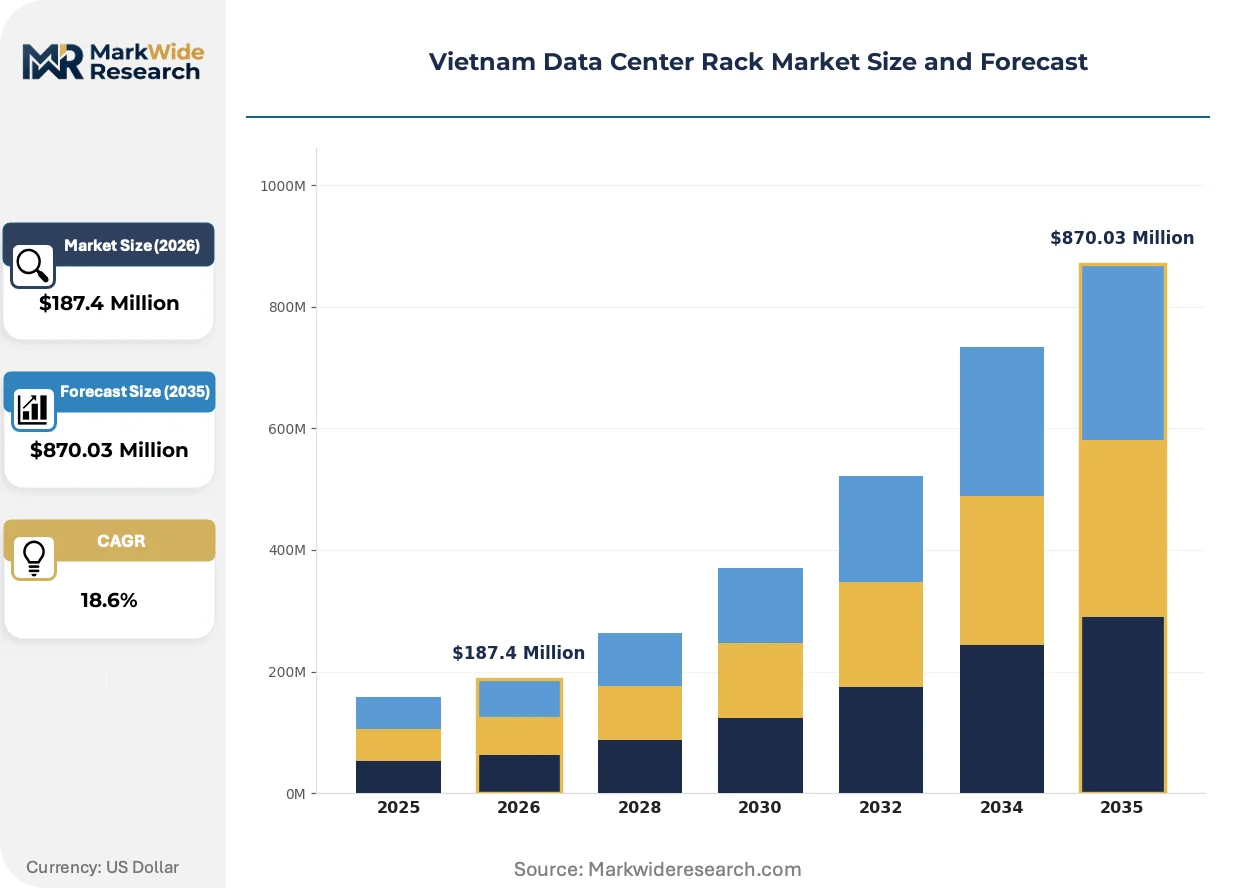
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mount Rack, Cabinet Rack Material: Steel, Aluminum, Plastic, Composite End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Providers Capacity: Standard, High Density, Ultra High Density, Modular |
| Companies Covered | Eaton Corporation, Rittal GMBH & Co.KG, Schneider Electric SE, Vertiv Group Corp., Dell Inc., Huawei Technologies Co. Ltd., ABB, Fujitsu Ltd., Lenovo Group Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Rack Market Trends and Innovations
Modular rack architectures are displacing fixed-configuration designs as Vietnamese operators prioritize scalability over initial capital efficiency. Three forces are compressing product lifecycles and reshaping supplier relationships.
Edge-distributed micro data centers are decentralizing infrastructure deployment patterns across Vietnam's manufacturing zones. These self-contained 10-50 rack units integrate power, cooling, and fire suppression into shipping-container footprints. Electronics manufacturers in Bac Ninh and Hai Duong provinces are adopting these systems for sub-10 millisecond latency to automated production lines. The technology is decentralizing site selection authority from central IT departments to plant operations managers.
Vietnam's Ministry of Information and Communications tightened energy efficiency disclosure requirements for facilities exceeding 1MW total power draw. Operators must now submit annual PUE audits to provincial authorities as a condition of operating licenses. Hyperscale campuses in Hanoi province face the steepest compliance timelines, with first submissions due within 18 months of commissioning. The regulation is forcing retroactive sensor installation in legacy facilities built before 2020.
Colocation buyers are consolidating vendor relationships from multi-source rack procurement to single-source integrated infrastructure contracts. This pattern compresses the traditional separation between rack, power, and cooling purchasing decisions. Cloud service providers now demand decade-long thermal performance guarantees binding original equipment manufacturers to operational outcomes. The behavioral shift is most visible among Vietnamese telecommunications operators spinning out data center assets into standalone entities.
Vietnam Data Center Rack Market Segmentation
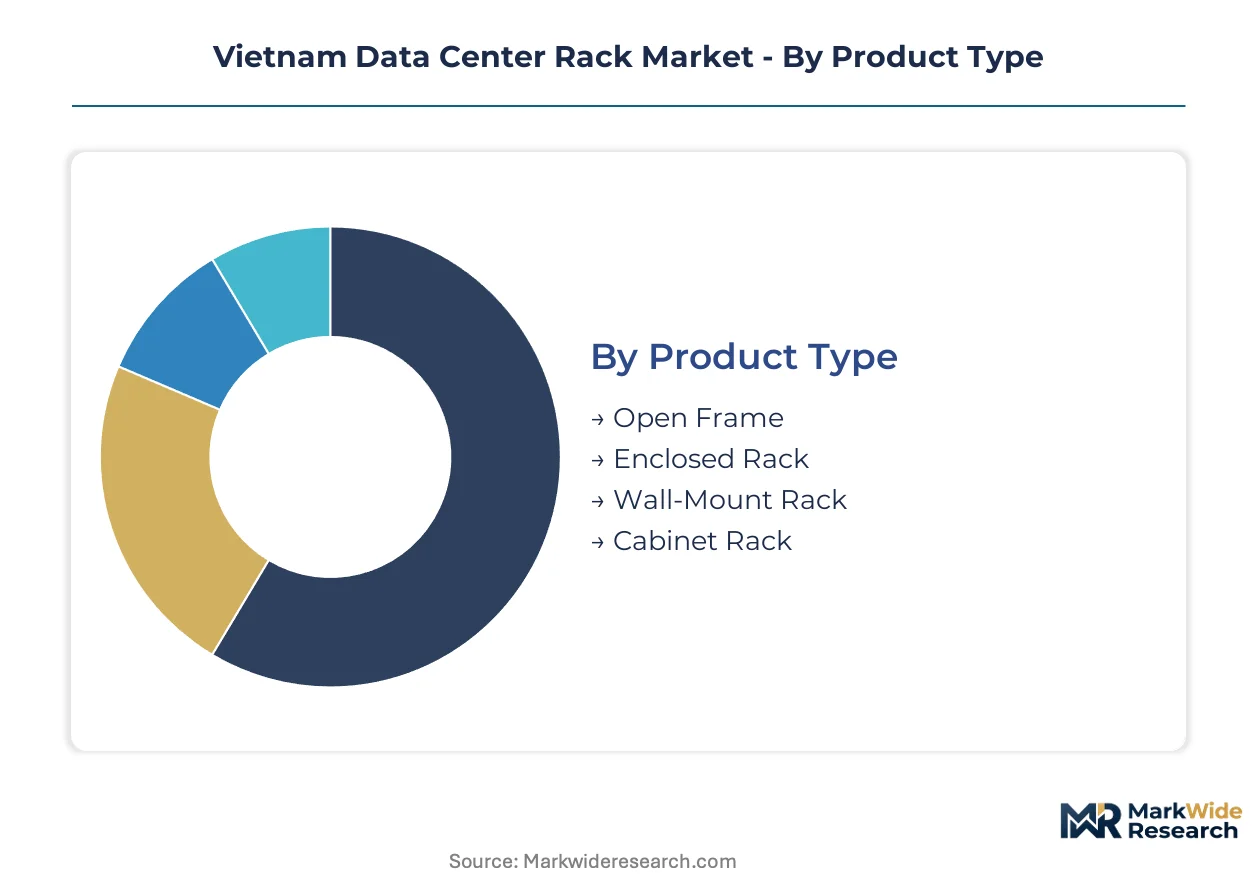
Rack specification in Vietnam diverges sharply between legacy enterprise installations and hyperscale cloud builds. Procurement teams now segment purchases by thermal load capacity and material resilience rather than footprint alone. Understanding these splits reveals where supplier margins concentrate and where technology transitions accelerate replacement cycles.
Product Type:
Supply concentration among Vietnamese distributors favors enclosed and cabinet configurations over open-frame alternatives. Local fabricators maintain limited inventories of specialized wall-mount units.
- Open Frame:Four-post skeleton structures without side panels maximize airflow for low-density legacy equipment. Demand persists in provincial government server rooms where dust exposure remains minimal and cooling infrastructure is underdeveloped.
- Enclosed Rack:Perforated metal enclosures with integrated cable management and lockable front-rear access. Bac Ninh electronics manufacturers specify these for cleanroom-adjacent production environments where particulate contamination threatens automated line uptime.
- Wall-Mount Rack:Compact swing-out or fixed brackets for network closets and retail branch locations. Vietnam's retail banking expansion drives procurement in Ho Chi Minh City district offices.
- Cabinet Rack:Fully sealed units with integrated power distribution and environmental monitoring. Hyperscale operators in Hanoi-Hai Phong corridor demand these for GPU clusters exceeding 30kW per enclosure.
Today's leader: Cabinet Rack. Tomorrow's challenger: Enclosed Rack as edge deployments multiply.
Material:
Cost tier differentiation separates premium aluminum builds from commodity steel offerings. Composite materials occupy a narrow niche in corrosion-sensitive coastal installations.
- Steel:Cold-rolled carbon steel dominates volume procurement through lower unit economics. Vietnamese colocation operators specify galvanized variants for humidity resistance in unconditioned warehouse conversions.
- Aluminum:Lightweight extrusions reduce shipping costs and enable tool-less rail adjustments. Cloud service providers in Hanoi province prioritize these for rapid deployment schedules where installation labor shortages bite hardest.
- Plastic:Thermoplastic enclosures serve temporary edge deployments and telecommunications outdoor cabinets. Limited thermal dissipation restricts application to sub-5kW loads.
- Composite:Fiberglass-reinforced polymers resist salt corrosion in Da Nang coastal facilities. Premium pricing limits adoption to disaster-recovery sites requiring extended environmental resilience.
Steel commands volume. Aluminum climbs fastest as density requirements escalate.
End User:
Application-driven procurement patterns separate centralized hyperscale builds from distributed enterprise deployments. Each vertical maintains distinct certification and service-level requirements.
- Telecommunications:State-owned operators and mobile network providers drive standardization around 19-inch EIA specifications. Viettel and VNPT data center spinouts are consolidating vendor panels toward single-source infrastructure contracts.
- Cloud Service Providers:Hyperscale operators including foreign entrants and domestic platforms demand 50-100kW rack densities for AI training clusters. These buyers compress procurement cycles and require decade-long thermal performance guarantees.
- Enterprises:Manufacturing conglomerates and financial institutions maintain fragmented purchasing across facility IT and plant operations. Legacy 5-8kW specifications predominate in facilities built before 2020.
- Colocation Providers:Third-party facility operators balance multi-tenant flexibility against power density standardization. Thai Binh province greenfield sites target these operators with prioritized grid connections.
Cloud Service Providers set the technology pace. Colocation Providers intermediate that pressure to enterprise buyers.
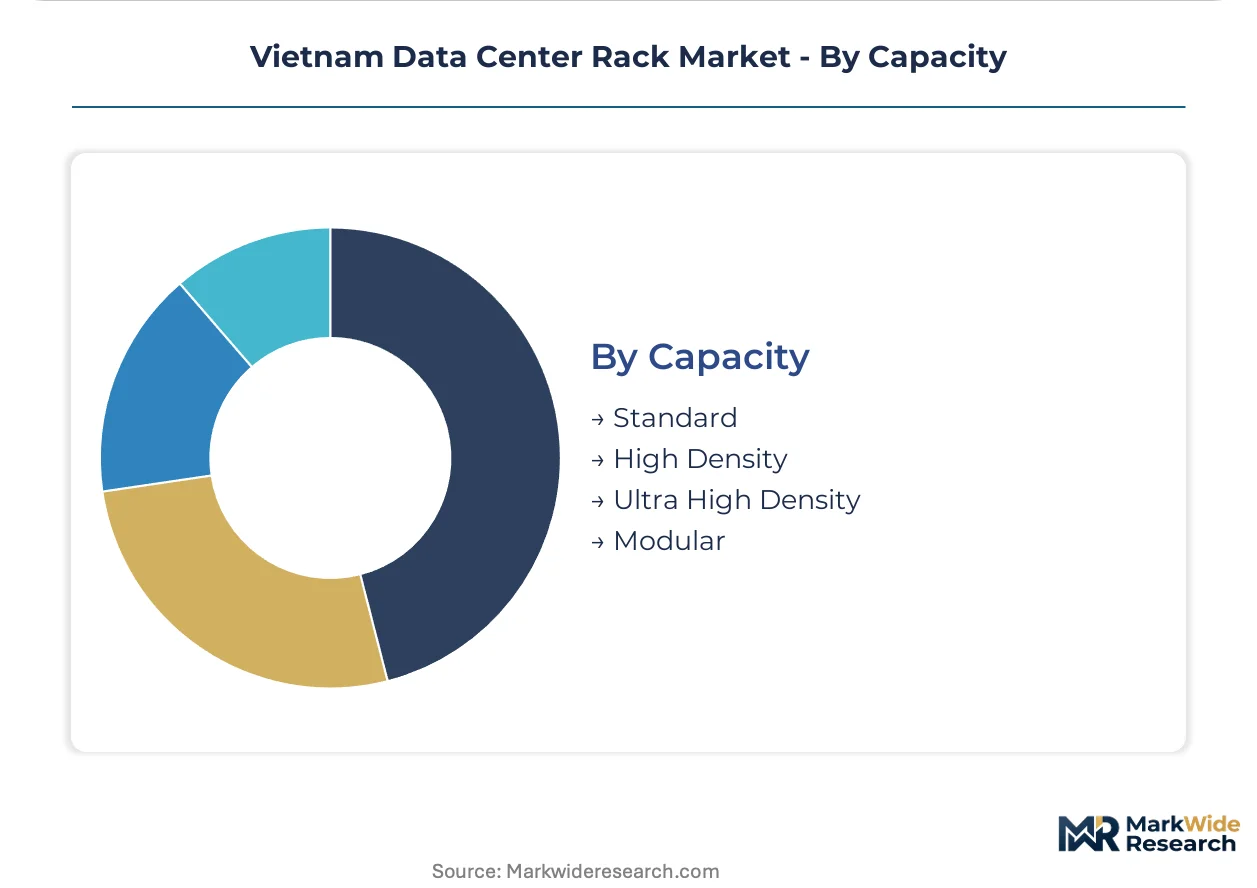
Capacity:
Technology maturity splits the market between established standard designs and emerging ultra-high-density architectures. Modular configurations bridge this transition for risk-averse operators.
- Standard:3-10kW per rack designs serve legacy enterprise workloads and storage-heavy applications. These units face replacement pressure as AI server deployments render power and cooling specifications obsolete.
- High Density:15-30kW enclosures with enhanced vertical airflow management and busbar power delivery. Hanoi-Hai Phong corridor facilities specify these for mainstream cloud compute and virtualization workloads.
- Ultra High Density:50-100kW liquid-cooled or direct-to-chip configurations for GPU-intensive training clusters. Supply scarcity for certified installation technicians constrains deployment velocity.
- Modular:Scalable rack architectures allowing field-upgradable power and cooling modules. Central Vietnam coastal developments favor these for phased capacity expansion against uncertain demand timing.
High Density anchors current investment. Ultra High Density represents the steepest expansion trajectory as AI workloads reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting data center rack procurement toward Vietnam as neighboring jurisdictions tighten energy efficiency compliance costs. Facility operators exploit Vietnam's phased implementation of PUE disclosure requirements against Singapore's immediate carbon pricing and Thailand's accelerated building code enforcement.
Thailand
Cloud service providers from Bangkok are expanding into Vietnam's northern corridor to escape Thailand's Board of Investment restrictions on data center power allocation. The country's revised building energy code mandates PUE below 1.5 for facilities exceeding 5MW, compressing margins for legacy rack specifications. Chonburi's Eastern Economic Corridor hosts retrofit projects where operators replace standard-density racks with liquid-cooled alternatives.
Singapore
Moratorium-driven capacity constraints have pushed hyperscale operators toward Vietnam for greenfield deployment. The Infocomm Media Development Authority's carbon neutrality timeline for data centers imposes cost structures that Vietnam's Ministry of Information and Communications has deferred until 2027. Temasek-linked entities now prioritize Vietnam's Bac Giang province for AI training clusters requiring 50-100kW rack densities.
Indonesia
Jakarta-based telecommunications operators are diversifying rack procurement across Vietnam to mitigate Indonesia's fragmented inter-island connectivity costs. The country's Ministry of Communication and Informatics data localization rules lack enforcement mechanisms that Vietnam's cybersecurity regulators have operationalized. Batam's proximity to Singapore has stalled as a data center hub due to power grid instability, redirecting investment toward Vietnam's Thai Binh province.
Malaysia
Iskandar Puteri's saturated land market is displacing colocation providers toward Vietnam's Da Nang coastal corridor. The Malaysian Communications and Multimedia Commission's licensing delays for Tier III facilities contrast with Vietnam's expedited permitting for PUE-certified designs. Cyberjaya's incumbent operators now specify Vietnam for disaster-recovery rack deployments leveraging submarine cable diversity.
Philippines
Manila's vulnerability to seismic activity and submarine cable cuts is driving rack procurement diversification toward Vietnam's Hanoi-Hai Phong corridor. The country's Department of Information and Communications Technology lacks equivalent facility certification requirements to Vietnam's national technical standards body. Clark Freeport Zone's power reliability issues have stalled hyperscale commitments, redirecting cloud builder attention to Vietnam's prioritized grid connections.
Vietnam Data Center Rack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-distributed micro data center integration. The market structures around three distinct capability clusters: integrated power-and-cooling architects, tropical climate thermal specialists, and cost-optimized local assemblers. Consolidation pressure intensifies as cloud service providers compress procurement cycles from multi-source to single-source contracts. Dominant competitive moves include decade-long thermal performance guarantees and field-upgradable modular architectures.
Within the integrated infrastructure tier, Schneider Electric SE and Rittal GMBH & Co.KG exemplify divergent specialization strategies. Schneider Electric SE anchors premium positioning through certified high-density rack systems. Rittal GMBH & Co.KG occupies thermal management specialization for tropical humidity conditions. Huawei Technologies Co. Ltd. represents cost-optimized local assembly partnerships controlling landed cost positions in northern Vietnam's hyperscale corridor.
| Leading Market Players |
|---|
| Eaton Corporation |
| Rittal GMBH & Co.KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Dell Inc. |
| Huawei Technologies Co. Ltd. |
| ABB |
| Fujitsu Ltd. |
| Lenovo Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up colocation operators in Vietnam's northern corridor are consolidating vendor relationships from multi-source to single-source contracts, compressing distributor margins while granting premium pricing power to integrated infrastructure architects with certified high-density thermal capabilities.
Pricing Analysis
Distributor margins in Vietnam's data center rack market compress as cloud service providers negotiate direct-to-OEM volume discounts bypassing traditional channel layers. Pricing stratifies across certified high-density, standard enterprise, and economy-grade steel configurations, with thermal performance certification and installation service bundling as primary differentiation levers. Cost compression in the standard-density tier intensifies because legacy 5-10kW designs face replacement pressure from GPU-intensive workloads. State-owned telecommunications operators exhibit highest price sensitivity due to fragmented procurement committees, while hyperscale cloud builders prioritize decade-long thermal guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by Vietnamese hyperscale operators force qualification of at least two precision air conditioning suppliers, mitigating single-source vulnerability from South Korean and Chinese manufacturers during port congestion events. Rack enclosure fabrication draws from cold-rolled steel mills in China, Vietnam, and South Korea, with aluminum extrusions imported primarily from Thai and Malaysian facilities. Supply chain risk centers on tariff exposure for Chinese-origin cooling equipment as Vietnam's Ministry of Industry and Trade evaluates preferential trade realignments. Distribution runs through Hanoi-based system integrators serving the Hai Phong corridor, with direct manufacturer relationships penetrating largest cloud campus developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's data center rack market functions as a regulatory compounder, with the Ministry of Information and Communications' mandatory PUE disclosure requirements for facilities exceeding 1MW creating sustained demand for certified high-density infrastructure upgrades.
For Market Incumbents: To counter liquid-cooling specialist entrants from Singapore, Schneider Electric SE and Rittal GMBH & Co.KG should deepen backward integration into tropical-grade precision air conditioning manufacturing and secure decade-long service contracts binding installation labor to operational outcomes. Certification investment in IEC 61439 standards for Vietnamese electrical contractors creates switching costs against emerging local assemblers. For New Entrants and Emerging Players: Begin with edge-distributed micro data center deployments in Bac Ninh and Hai Duong manufacturing zones, where plant operations managers bypass centralized IT procurement authority. The 10-50 rack containerized segment remains penetrable by foreign entrants lacking hyperscale reference sites. A go-to-market angle through electronics manufacturing automation vendors unlocks sub-10 millisecond latency specifications. For Investors and Strategic Acquirers: Cloud service providers spinning out infrastructure assets are the most active acquirer in this space, seeking integrated power-and-cooling capabilities for AI training clusters. Long-term viability rests on exposure to ultra-high-density rack architectures rather than legacy enterprise replacement cycles. The signal to watch is provincial power allocation priority shifts affecting Bac Giang and Thai Binh development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certified High-Density Rack Deployment | Vietnam's Tier III facility certification requirements from the national technical standards body mandate thermal architecture pre-qualification. |
| Liquid Cooling Integration Partnership | Direct-to-chip cooling convergence allows retrofit of existing Hanoi-Hai Phong corridor facilities without full infrastructure replacement. |
| Local Assembly Partnership Formation | Huawei Technologies Co. Ltd. demonstrates landed cost control through northern Vietnam manufacturing partnerships for hyperscale procurement cycles. |
| IEC 61439 Technician Certification Program | Scarcity of certified electricians for high-density power distribution units constrains deployment velocity across GPU cluster installations. |
| Submarine Cable Landing Site Development | Da Nang and Quang Nam coastal corridors offer disaster-recovery positioning with lower land costs than northern provinces. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility directors, cloud procurement officers, colocation operations managers, and electrical installation contractors with secondary validation from Vietnam Ministry of Information and Communications policy filings, provincial power allocation announcements, hyperscaler capital expenditure disclosures, and customs records for steel and aluminum import flows. Bottom-up rack deployment estimates triangulated against top-down facility power capacity projections.
Segment-weighting across the analysis window applied product type, material grade, end-user vertical, and thermal capacity specifications as core dimensions, with provincial regulatory cluster and grid connection priority as Vietnam-specific modifiers. CAGRs derived from installation volume trajectories indexed to national digital infrastructure masterplan milestones and AI server density adoption curves.
Several conditions sit outside the modeled scope, including potential relaxation of data localization mandates, acceleration of carbon pricing mechanisms, and geopolitical disruption to Chinese-origin cooling equipment supply. Deviation in provincial power allocation priority rankings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Denmark Data Center Rack Market