
 Denmark Data Center Power Market | 2026-2036
Denmark Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Power Market Insights
Modular unbundling of power infrastructure is hardening as the dominant procurement pattern among Danish colocation buyers. Schneider Electric SE leverages its prefabricated power module portfolio to anchor large-scale deployments near Fredericia. Vertiv Group Corp competes through thermal-electrical integration, while ABB Ltd specializes in medium-voltage switchgear configurations for hyperscale campuses.
Denmark data center power encompasses the generation, conditioning, distribution, and backup systems that deliver continuous electrical energy to server environments, typically operating at voltages from 400V AC to 1500V DC with redundancy tiers from N+1 to 2N+1. Its primary purpose is to eliminate downtime in digital infrastructure where power interruption causes immediate revenue loss and contractual penalties. Renewable energy sourcing leads the power source segment as PPA structures mature, while ultra high power capacity configurations represent the fastest-growing tier as Microsoft and Google expand their Danish footprints. UPS systems command concentrated margin pools due to lithium-ion battery substitution cycles and predictive maintenance service attach rates.
Denmark's Energy Agency enforces efficiency standards under the national climate agreement, while the Danish Building Regulation (BR18) mandates heat recovery integration for new data center power plants exceeding 1 MW thermal load. The EU Energy Efficiency Directive, transposed through Danish executive orders, requires power usage effectiveness reporting and drives demand for high-efficiency transformer and uninterruptible power supply specifications. Stakeholders must monitor grid reinforcement timelines and interconnection queue positions as electrification of transport and heating competes for transmission capacity.
Market Dynamics
Modular unbundling of power infrastructure hardens procurement patterns across Danish colocation facilities. Hyperscale cloud providers compress deployment timelines while demanding renewable energy integration through power purchase agreements.
Growth Catalysts
- EU Energy Efficiency Directive:Danish executive orders mandate power usage effectiveness reporting, driving demand for high-efficiency transformer and uninterruptible power supply specifications across new facilities.
- Submarine cable landings:Odense and Copenhagen harbor fiber optic convergence points that anchor hyperscale campus siting decisions and associated power infrastructure investment.
- Lithium-ion battery substitution:UPS systems capture concentrated margin pools as predictive maintenance service attach rates expand alongside electrochemical storage upgrades.
Market Restraints
- Grid interconnection queues:Electrification of transport and heating competes for transmission capacity, creating bottlenecks for data center power plant commissioning near Fredericia.
- Medium-voltage switchgear concentration:Specialized fabrication capabilities for 400V AC to 1500V DC configurations concentrate among limited European suppliers.
- District cooling dependency:Heat recovery integration mandates under BR18 tether facility economics to municipal infrastructure availability in Copenhagen metropolitan zones.
Strategic Opportunities
- Thermal-electrical integration:Waste heat capture systems converge with district heating networks, enabling revenue diversification for operators serving Odense municipal grids.
- Prefabricated power modules:Factory-integrated skid-mounted solutions compress field installation schedules and reduce commissioning risk for hyperscale buyers.
- Renewable energy sourcing:Maturing PPA structures allow direct contracting of offshore wind and solar generation, decoupling facility economics from wholesale electricity price volatility.
Industry Challenges
- Specialized commissioning expertise:2N+1 redundancy tier implementation requires scarce electrical engineers familiar with hyperscale synchronization protocols and islanding procedures.
- Legacy copper busbar integration:Retrofit projects face physical constraints when aluminum conductor upgrades must interface with existing 400V AC distribution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Power Market |
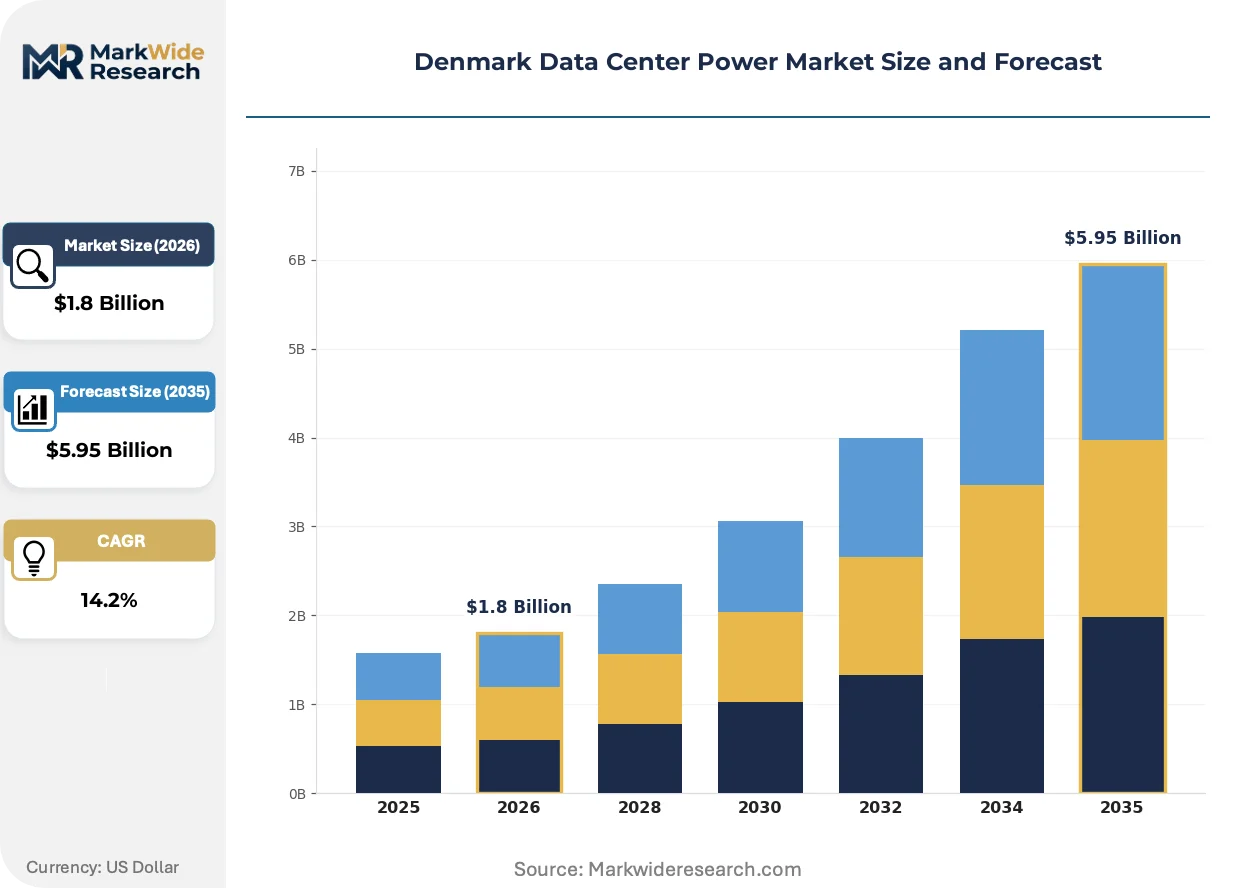
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Grid Power, UPS Systems Service Type: Design, Construction, Maintenance, Consulting End User: Telecommunications, Cloud Service Providers, Colocation Facilities, Enterprises Capacity: Low Power (up to 1 MW), Medium Power (1-5 MW), High Power (5-10 MW), Ultra High Power (10+ MW) |
| Companies Covered | ABB Ltd, Vertiv Group Corp, Eaton Corporation, Schneider Electric SE, Legrand Group, Caterpillar Inc, Cummins Inc, Rolls-Royce PLC, Rittal GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Power Market Trends and Innovations
Active reshaping of Denmark's data center power landscape centers on thermal-electrical convergence and procurement model compression. Facility operators and equipment vendors recalibrate around standardization pressures and renewable integration mandates.
Direct current microgrids at 750V and 1500V configurations are integrating server rack power distribution with battery energy storage systems. Hyperscale operators in the Copenhagen corridor adopt these topologies to eliminate AC-DC conversion losses. This architecture is integrating renewable generation sources at the point of consumption, compressing reliance on grid-tied infrastructure.
Denmark's Energy Agency enforces efficiency standards under the national climate agreement that mandate heat recovery for plants exceeding 1 MW thermal load. The Danish Building Regulation BR18 requires integration of waste heat capture with municipal district heating networks. Colocation providers respond by specifying modular power blocks with embedded heat exchangers, particularly in Odense where district cooling infrastructure converges with submarine cable landings.
Buying patterns among Danish colocation tenants compress toward power-as-a-service arrangements that unbundle capital expenditure from operational responsibility. Traditional equipment procurement with separate maintenance contracts yields to integrated ten-year service agreements with guaranteed availability metrics. This shift concentrates most visibly among financial services tenants in the greater Copenhagen area, where uptime penalties in outsourcing contracts drive risk transfer preferences.
Denmark Data Center Power Market Segmentation
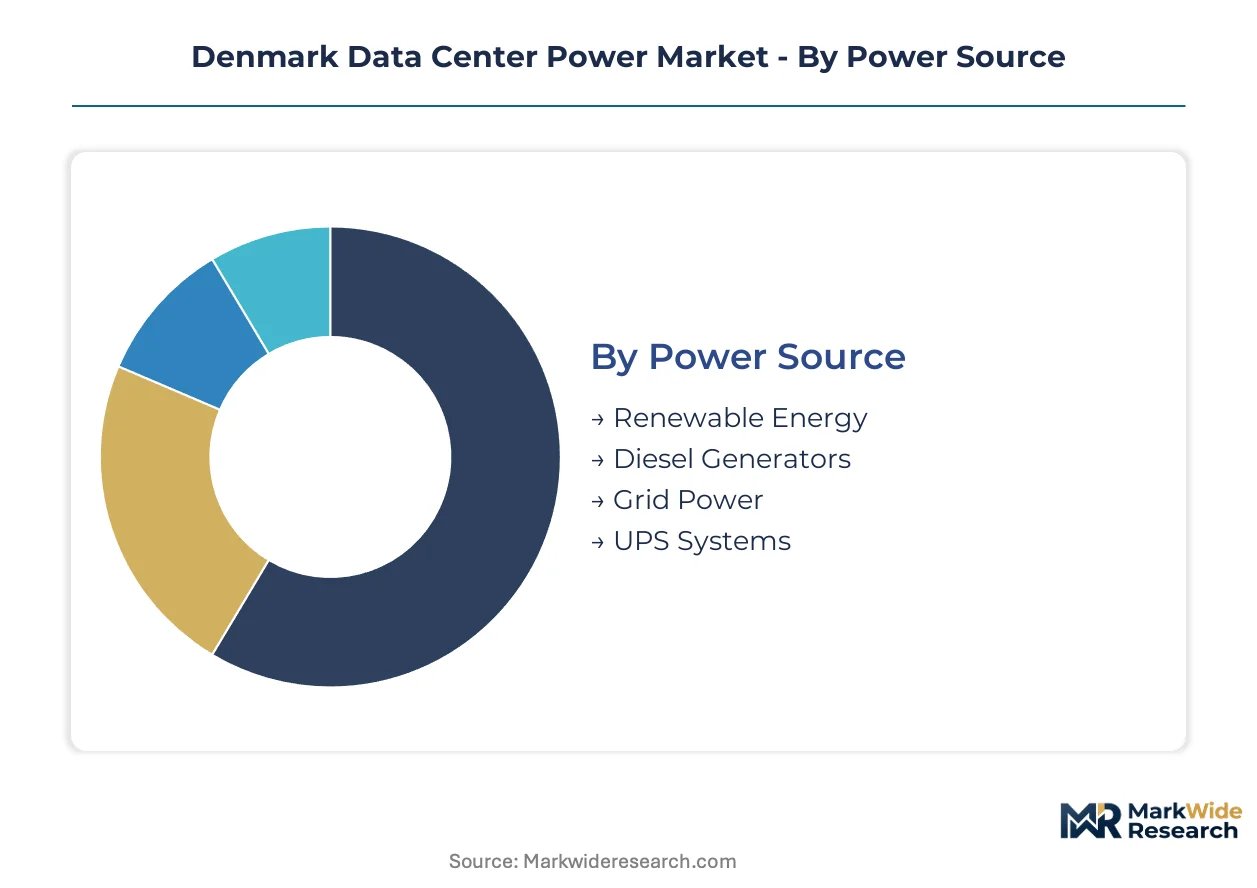
Power infrastructure segmentation in Denmark reflects the tension between hyperscale deployment velocity and municipal regulatory constraints. Procurement patterns diverge sharply across customer types, with renewable sourcing mandates and district heating integration requirements reshaping vendor specifications.
Power Source:
Voltage conditioning and generation topology defines capital allocation and operational compliance for Danish facility operators.
- Renewable Energy:Offshore wind and solar photovoltaic generation contracted through power purchase agreements dominate new hyperscale campus specifications. Google and Microsoft facilities near Fredericia anchor demand as PPA structures mature and grid interconnection agreements with Germany and Sweden enable sourcing flexibility.
- Diesel Generators:Backup combustion systems maintain N+1 to 2N+1 redundancy tiers for contractual uptime guarantees. Installation concentrates in Odense colocation facilities where submarine cable landings justify premium resilience investments despite national climate agreement emission constraints.
- Grid Power:Utility-sourced electricity at 400V AC to 1500V DC configurations supplies baseline load with medium-voltage switchgear integration.
- UPS Systems:Lithium-ion battery substitution cycles capture concentrated margin pools through predictive maintenance service attach rates.
Mature deployment sits with diesel generators. Newer deployment is concentrated in renewable energy.
Service Type:
Procurement compression across the project lifecycle reflects risk transfer preferences among financial services tenants in greater Copenhagen.
- Design:Electrical engineering specifications for 2N+1 redundancy tiers require scarce talent familiar with hyperscale synchronization protocols and islanding procedures. Demand clusters around Copenhagen metropolitan zones where BR18 heat recovery mandates complicate thermal-electrical integration.
- Construction:Factory-integrated skid-mounted power modules compress field installation schedules for hyperscale buyers near Fredericia. Prefabricated solutions reduce commissioning risk as deployment timelines compress.
- Maintenance:Ten-year service agreements with guaranteed availability metrics displace traditional equipment procurement with separate contracts.
- Consulting:Grid interconnection queue navigation and district cooling dependency assessment support facility siting decisions.
Established revenue streams flow through maintenance. Steepest expansion trajectory appears in design.
End User:
Customer scale and outsourcing risk tolerance determine power infrastructure specification intensity and service bundling preferences.
- Cloud Service Providers:Hyperscale operators including Microsoft and Google drive ultra high power capacity configurations through aggressive Nordic footprint expansion. Direct current microgrids at 750V and 1500V eliminate AC-DC conversion losses in Copenhagen corridor deployments.
- Colocation Facilities:Modular unbundling of power infrastructure hardens as the dominant procurement pattern among Danish buyers. District cooling infrastructure convergence in Odense anchors campus siting with embedded heat exchanger specifications.
- Telecommunications:Carrier-grade facilities prioritize UPS resilience for network infrastructure continuity.
- Enterprises:Captive data centers in Copenhagen financial services sector favor power-as-a-service arrangements transferring operational responsibility.
Volume concentration rests with cloud service providers. Margin expansion concentrates in colocation facilities.
Capacity:
Thermal load thresholds trigger BR18 heat recovery mandates and district heating network integration requirements.
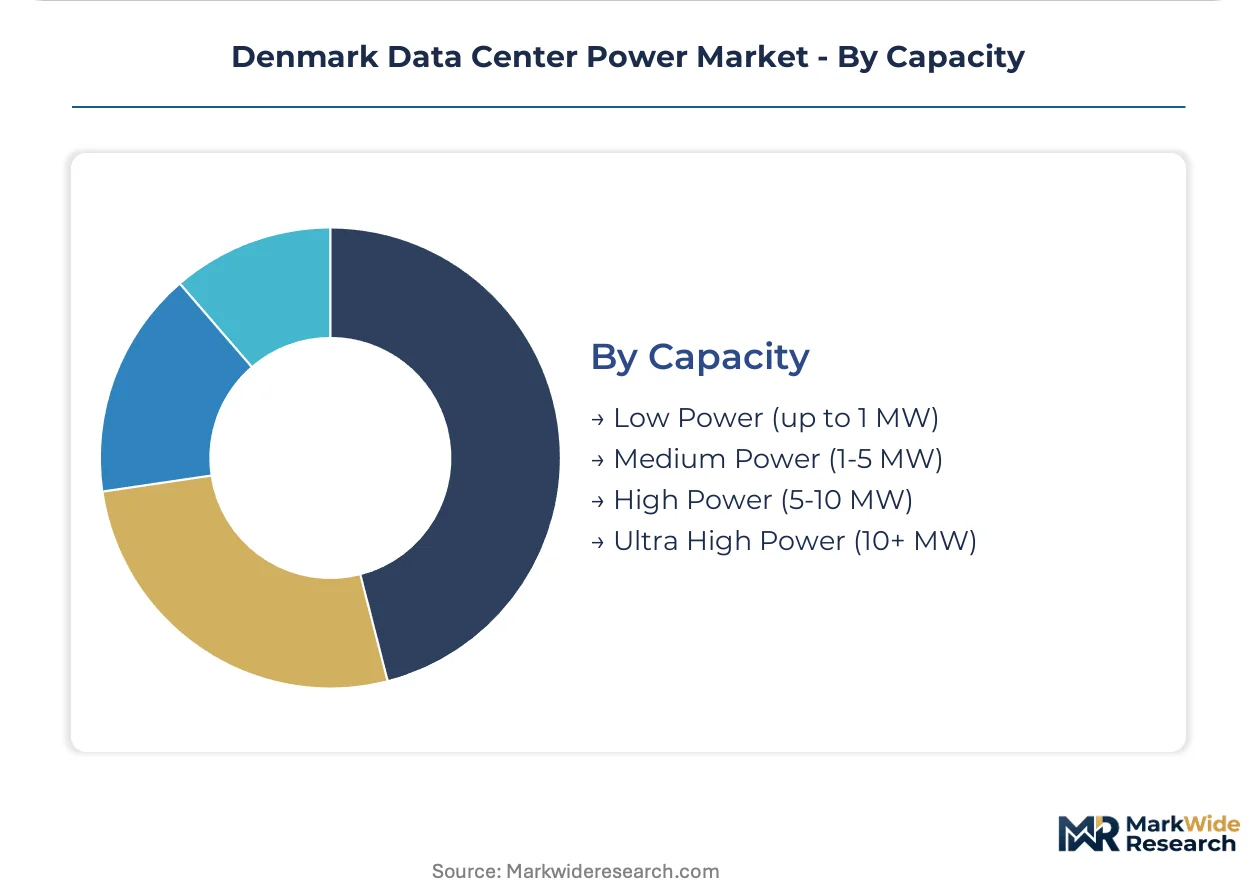
- Ultra High Power (10+ MW):Configurations expanding most quickly as hyperscale campuses multiply across the Copenhagen-Odense corridor. Waste heat capture systems converge with municipal district heating networks, enabling revenue diversification for operators serving Odense grids.
- High Power (5-10 MW):Mid-tier deployments face grid interconnection queue competition from transport electrification and heating sector demand near Fredericia.
- Medium Power (1-5 MW):Regional enterprise facilities balance redundancy requirements against capital efficiency constraints.
- Low Power (up to 1 MW):Edge and distributed infrastructure occupies sub-megawatt scale below BR18 thermal load thresholds.
Legacy installed base clusters in medium power. Capacity additions are climbing the fastest in ultra high power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark generates surplus renewable electricity from offshore wind while data center power consumption concentrates in eastern corridor clusters. This production-consumption geography shapes infrastructure investment patterns.
Greater Copenhagen
Submarine cable landings at Ballerup and Lyngby anchor hyperscale campus siting decisions for Microsoft and Google. The Danish Building Regulation BR18 mandates heat recovery integration for facilities exceeding 1 MW thermal load. District heating network convergence in Copenhagen metropolitan zones enables waste heat revenue diversification for operators.
Odense
Fiber optic convergence points and municipal district cooling infrastructure attract colocation investment from financial services tenants. The Danish Energy Agency enforces efficiency standards under the national climate agreement. Campus developments near the harbor cluster specify modular power blocks with embedded heat exchangers.
Fredericia
Grid interconnection agreements with Germany position this corridor for cross-border renewable sourcing through power purchase agreements. EU Energy Efficiency Directive transposition through Danish executive orders requires power usage effectiveness reporting. Prefabricated power module deployments compress field installation schedules for hyperscale buyers.
Aarhus
Emerging data center activity responds to Jutland peninsula wind generation proximity and lower land costs than eastern clusters. Municipal planning frameworks prioritize industrial heat recovery integration. Limited submarine cable landing density constrains hyperscale entry relative to Copenhagen-Odense corridor.
Denmark Data Center Power Market Competitive Landscape
The competitive structure tilts toward integrated electrical infrastructure specialists serving hyperscale deployment velocity. Market concentration reflects procurement consolidation among cloud service providers and colocation operators. Three archetypes dominate: full-stack power infrastructure vendors, thermal-electrical integration specialists, and medium-voltage switchgear fabricators. Capacity expansion and prefabricated solution development constitute the dominant competitive moves.
Among European-headquartered electrical infrastructure groups, ABB Ltd, Schneider Electric SE, and Vertiv Group Corp occupy differentiated positions within the vendor hierarchy. ABB Ltd anchors the medium-voltage switchgear configuration segment through specialized fabrication capabilities. Schneider Electric SE exemplifies the full-stack power infrastructure archetype with prefabricated module portfolios. Vertiv Group Corp represents thermal-electrical integration specialization for hyperscale campus requirements. Each sits within distinct procurement channels serving Danish colocation and cloud provider buyers.
| Leading Market Players |
|---|
| ABB Ltd |
| Vertiv Group Corp |
| Eaton Corporation |
| Schneider Electric SE |
| Legrand Group |
| Caterpillar Inc |
| Cummins Inc |
| Rolls-Royce PLC |
| Rittal GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Redundancy tier certification divergence between 2N+1 hyperscale specifications and N+1 colocation standards manifests in both pricing stratification and supplier qualification pathways across Danish deployments. BR18 heat recovery mandates and EU Energy Efficiency Directive compliance tiers create a dual-track procurement landscape where certified integrators command premium positioning while commodity power module vendors compete on compressed margins.
Pricing Analysis
Cost-down pressure on medium-voltage switchgear accelerates because hyperscale buyers consolidate procurement volumes through decade-long service agreements with guaranteed availability metrics. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by BR18 compliance certification and predictive maintenance service bundling. Cloud service providers exhibit lowest price sensitivity given contractual uptime penalty exposure, while regional enterprises in Aarhus prioritize capital efficiency over redundancy tier investment.
Supply Chain Analysis
CE marking and IEC 61439 compliance certification for 400V AC to 1500V DC configurations gate supplier participation in Danish hyperscale projects. Manufacturing concentration rests on Germany, France, and Switzerland for medium-voltage switchgear fabrication, while lithium-ion battery cells draw from South Korean and Chinese electrochemical suppliers. Single-source vulnerability concentrates in specialized 2N+1 commissioning expertise for islanding protocol implementation. Distribution runs through factory-integrated skid-mounted solutions shipped directly to Fredericia and Odense corridor sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark data center power operates as a cost-of-compliance market where BR18 heat recovery integration mandates and EU Energy Efficiency Directive reporting requirements erect regulatory moats favoring incumbent specialists with certified thermal-electrical integration capabilities.
For Market Incumbents: Extend prefabricated power module portfolios into district heating network convergence specifications for Odense municipal grid connections. Consolidate scarce 2N+1 commissioning engineering talent through captive training programs before hyperscale deployment timelines compress further. Vertical integration into lithium-ion battery predictive maintenance services captures recurring revenue pools as service attach rates expand. For New Entrants and Emerging Players: The price-point gap between premium hyperscale-certified integrators and economy-tier regional contractors opens white-space in Aarhus edge facility deployments below BR18 thermal load thresholds. Target financial services tenants in greater Copenhagen with power-as-a-service arrangements that transfer operational responsibility without requiring full 2N+1 capital commitment. Position through modular unbundling expertise rather than full-stack infrastructure competition. For Investors and Strategic Acquirers: Re-rating potential sits with thermal-electrical integration specialists given BR18 mandate expansion and district heating network monetization catalysts. Long-term viability favors vendors with embedded heat exchanger manufacturing capabilities and Odense harbor zone project references. Watch grid interconnection queue clearance timelines as the inflection signal for capacity addition feasibility across the Copenhagen-Fredericia corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Power Module Expansion | Factory-integrated solutions compress field schedules for hyperscale buyers near Fredericia. |
| Thermal-Electrical Integration Partnership | Waste heat capture convergence with Odense district heating networks enables revenue diversification. |
| Renewable Energy Sourcing Agreement | Direct PPA contracting with offshore wind decouples facility economics from wholesale volatility. |
| Predictive Maintenance Service Buildout | Lithium-ion battery substitution cycles capture margin pools through ten-year availability guarantees. |
| 2N+1 Commissioning Capability Acquisition | Scarce islanding protocol expertise commands premium positioning as hyperscale timelines compress. |
Research Methodology
Document review covered Danish Energy Agency executive orders, EU Energy Efficiency Directive transposition texts, and BR18 technical specifications, complemented by interviews with data center facility directors, electrical infrastructure procurement leads at hyperscale cloud providers, district heating network operators in Copenhagen and Odense, and medium-voltage switchgear engineering specialists. Secondary validation drew from Energinet grid development filings, municipal planning authority records, and offshore wind PPA disclosure databases. Bottom-up project pipeline assessment triangulated against top-down capacity installation tracking.
Cross-referencing historical deployment patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation modeling incorporated power source topology, service type procurement compression, end-user scale tier, and thermal load capacity thresholds. CAGRs were derived from installation run-rate analysis and interconnection queue position tracking. Forecast inputs included BR18 compliance cost curves and lithium-ion battery substitution cycle velocity assumptions.
Inputs from Danish municipal planning authorities and Energinet transmission system operators were available through the study window; gaps in proprietary hyperscale capex allocation decisions introduce uncertainty bands around capacity addition timing. Forecasts reflect documented assumptions regarding grid reinforcement timeline execution and PPA structure maturation. A model refresh is warranted upon material change in EU Energy Efficiency Directive enforcement intensity or district heating network tariff regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Europe Data Center Colocation Market