
 Sweet Whey Market | 2026-2036
Sweet Whey Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Whey Market Analytics
Direct procurement between dairy processors and nutritional formulators is narrowing as ingredient traceability requirements tighten. Fonterra Co-operative Group Limited leverages its New Zealand milk pool to sustain long-term whey concentrate supply contracts. Glanbia Nutritionals anchors North American sports nutrition channels through specialized isolate production. Arla Foods Ingredients competes in European infant formula-grade whey with advanced fractionation capabilities.
Sweet whey denotes the liquid remaining after casein coagulation during cheese manufacture, containing approximately 6.5% total solids with lactose as the dominant carbohydrate and protein fractions ranging 0.8-1.0%. Manufacturers spray-dry this permeate to produce functional ingredients for protein fortification across food systems. Whey Protein Concentrate retains the largest volume position in powder form due to cost-efficient inclusion in bakery and dairy applications. Hydrolyzed Whey commands premium positioning within sports nutrition where rapid amino acid absorption differentiates performance formulations. Sweet Whey Powder serves mature demand in confectionery and processed foods where emulsification properties outweigh protein density requirements.
FDA food additive regulations and USDA dairy grading standards govern whey ingredient safety and compositional claims in United States commerce, while EFSA novel food assessments shape European market access for advanced hydrolysates. Codex Alimentarius protein quality metrics influence international trade specifications for infant formula applications. Stakeholders must monitor evolving allergen labeling requirements and carbon intensity benchmarks as procurement criteria harden across major dairy importing regions.
Market Dynamics
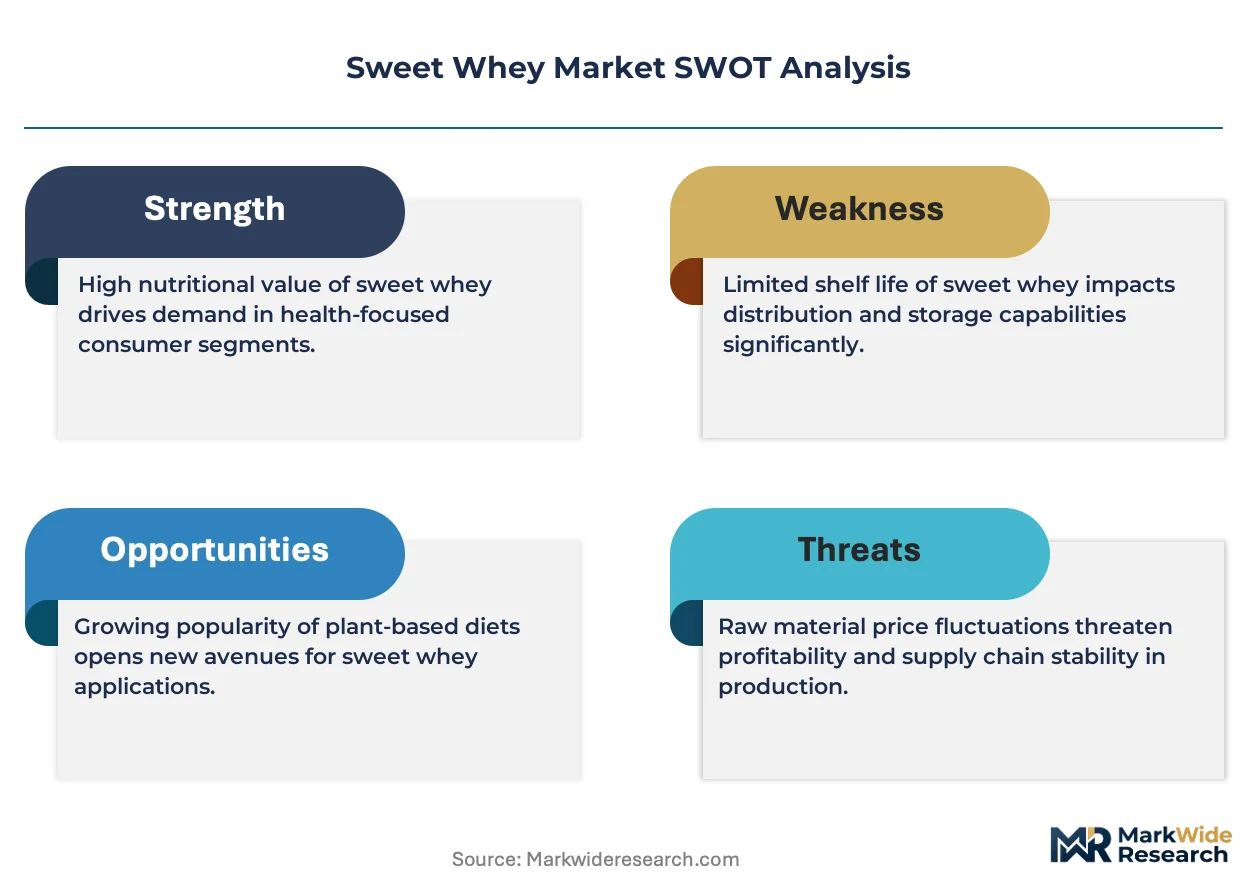
EU F-Gas Regulation mandates refrigerant phase-down across dairy drying operations, forcing processors to retrofit spray-dryer heat recovery systems or face capacity constraints. This single policy lever compresses capital deployment timelines while reshaping competitive access to infant-formula-grade whey fractions.
Growth Catalysts
- Sports nutrition fortification:Functional beverage brands standardize protein enrichment across ready-to-drink portfolios, pulling whey isolate demand through specialized fractionation contracts.
- REACH-aligned fractionation chemistry:European processors deploy membrane filtration advances that recover native protein structures without denaturing agents, opening infant formula access.
- German cooperative concentration:Dairy co-ops in Bavaria and Lower Saxony anchor continental whey permeate supply, securing backward integration into nutritional ingredient channels.
Market Restraints
- Energy input volatility:Natural gas price swings directly compress spray-drying margins, with German processors most exposed to spot-market procurement.
- Supply-side geographic concentration:New Zealand milk pool dominance creates single-source risk for long-term whey concentrate offtake agreements.
- Plant protein substitution:Pea and fava protein isolates displace whey in bakery and meat-analog applications where emulsification tolerates lower functionality.
Strategic Opportunities
- Indian sports nutrition underpenetration:FSSAI protein claim regulations are stabilizing, enabling whey isolate positioning in emerging gym-channel distribution.
- Precision fermentation convergence:Cell-culture lactose production couples with traditional whey processing to create hybrid ingredient systems for specialty nutrition.
- EU Green Deal carbon border adjustments:Low-emission drying technology investments qualify for transitional financing, advantaging early retrofit adopters in export markets.
Industry Challenges
- Fractionation engineering talent scarcity:Membrane process design expertise concentrates with retiring dairy technologists in the Netherlands and Denmark.
- Infant formula-grade certification timelines:Codex Alimentarius protein quality dossiers require 18-24 month validation cycles, delaying market entry for new hydrolysate variants.
- Legacy dryer integration complexity:Heat pump retrofits onto existing spray-dryer infrastructure demand custom engineering that extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Whey Market |
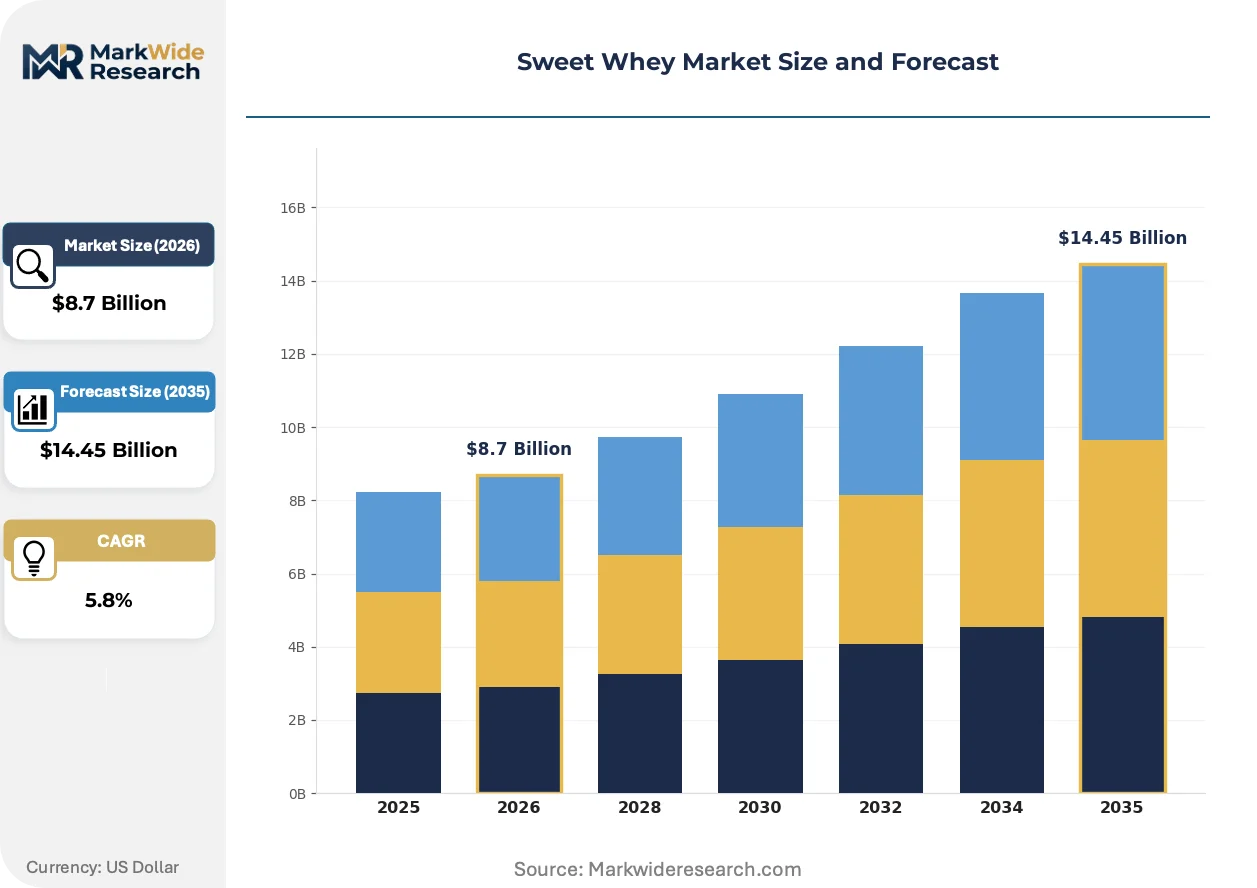
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey, Sweet Whey Powder End User: Food & Beverage, Nutritional Supplements, Bakery Products, Dairy Industry Form: Powder, Liquid, Solid, Granulated Application: Protein Fortification, Nutritional Products, Sports Nutrition, Infant Formulas |
| Companies Covered | Hilmar Ingredients, Royal FrieslandCampina, Fonterra Co-operative Group Limited, Kerry Group PLC, Saputo Inc., Lactalis Group, Glanbia Nutritionals, Carbery Group, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Whey Market Evolving Landscape
Membrane filtration advances and refrigerant-phase regulatory pressure are collapsing traditional process economics. These forces compress equipment replacement cycles while opening new application categories for fractionated whey ingredients.
Electrodialysis demineralization is collapsing the cost structure for infant-formula-grade whey production. Arla Foods Ingredients and FrieslandCampina deploy this technology at scale in Denmark and the Netherlands. The process eliminates ion-exchange resin consumption, collapsing operating expenditure differentials between standard and premium whey fractions.
F-Gas Regulation refrigerant phase-down mandates are reshaping capital allocation across European dairy processing. Installers now specify ammonia-carbon dioxide cascade systems or transcritical CO2 heat pumps for new spray-dryer projects. German processors face the steepest retrofit obligations, with several Bavarian sites accelerating 2024-2026 equipment replacement schedules.
Direct procurement contracts between dairy cooperatives and nutritional formulators are shortening traditional ingredient trading channels. Sports nutrition brands now embed quality auditors at fractionation facilities, displacing spot-market whey protein concentrate purchases. This pattern concentrates most visibly in North American and North European supply corridors where traceability requirements have hardened fastest.
Sweet Whey Market Segmentation
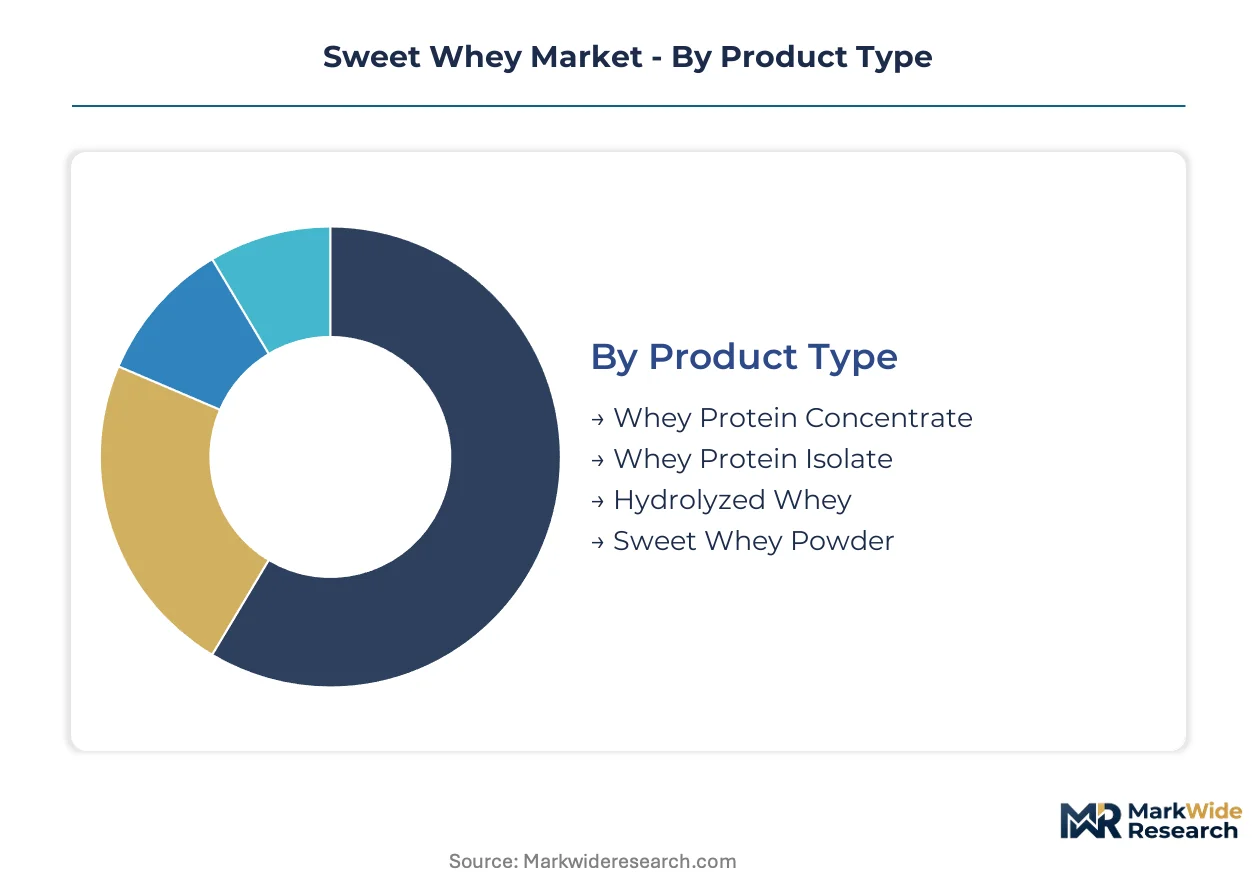
Sweet whey fractionation creates distinct value tiers based on protein concentration and functional purity. Procurement contracts now specify segment-grade certifications that determine eligibility for infant formula versus sports nutrition channels.
Product Type:
Cycle times vary sharply across this category, with commodity powders turning inventory weekly while hydrolysates sit in 18-month certification queues.
- Whey Protein Concentrate:Retains 34-80% protein content with native lactose and lipid fractions intact. Bakery and dairy manufacturers in Germany anchor demand for this cost-efficient fortification grade, though energy-intensive spray-drying compresses margins during natural gas price spikes.
- Hydrolyzed Whey:Enzymatic pre-digestion cleaves peptide bonds for rapid gastric emptying. Sports nutrition formulators in North America specify this grade for post-workout applications, paying premiums that justify complex fractionation investments.
- Whey Protein Isolate:Cross-flow microfiltration achieves 90%+ protein purity with minimal residual lactose. Specialized isolate production serves clinical nutrition and premium sports applications where allergen reduction commands price separation.
- Sweet Whey Powder:Standardized permeate solids at 11-13.5% protein serve confectionery emulsification needs. Mature demand in processed foods relies on this grade where protein density matters less than water-binding functionality.
Whey Protein Concentrate dominates installed base. Hydrolyzed Whey is where expansion concentrates.
End User:
Cost tier separation runs deepest here, with nutritional supplements commanding 3-4x the per-kilogram price of commodity food applications.
- Nutritional Supplements:Sports nutrition and clinical dietetic products demand certificate-of-analysis documentation for every lot. FSSAI stabilization in India is opening gym-channel distribution for isolate-grade products.
- Infant Formulas:Demineralization and protein ratio standardization to human milk specifications requires electrodialysis investment. Arla Foods Ingredients and FrieslandCampina have concentrated capability in Denmark and the Netherlands.
- Food & Beverage:Ready-to-drink protein beverages standardize enrichment across portfolios, pulling concentrate demand through long-term offtake contracts.
- Bakery Products:Emulsification and browning control drive inclusion where whey solids replace non-fat dry milk in cost-sensitive formulations.
- Dairy Industry:Standardized permeate backfills protein and solids in processed cheese and ice cream applications with minimal specification overhead.
Nutritional Supplements dominate installed base. Infant Formulas is where expansion concentrates.
Form:
Volume concentration favors powder formats, though liquid whey commands strategic importance in regional supply integration.
- Powder:Spray-dried permeate enables global trade logistics and year-round formulation consistency. EU F-Gas Regulation refrigerant mandates are reshaping dryer capital allocation across German processing sites.
- Liquid:Fresh whey requires 48-72 hour processing windows, anchoring regional co-op concentration in Bavaria and Lower Saxony for just-in-time fractionation.
- Solid:Compressed whey protein bars and extruded formats serve convenience nutrition channels with minimal rehydration requirements.
- Granulated:Agglomerated particles improve dispersibility in instant beverage applications, commanding modest premiums over standard powder.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Customer type separation distinguishes commodity fortification from premium positioning, with certification requirements determining market access.
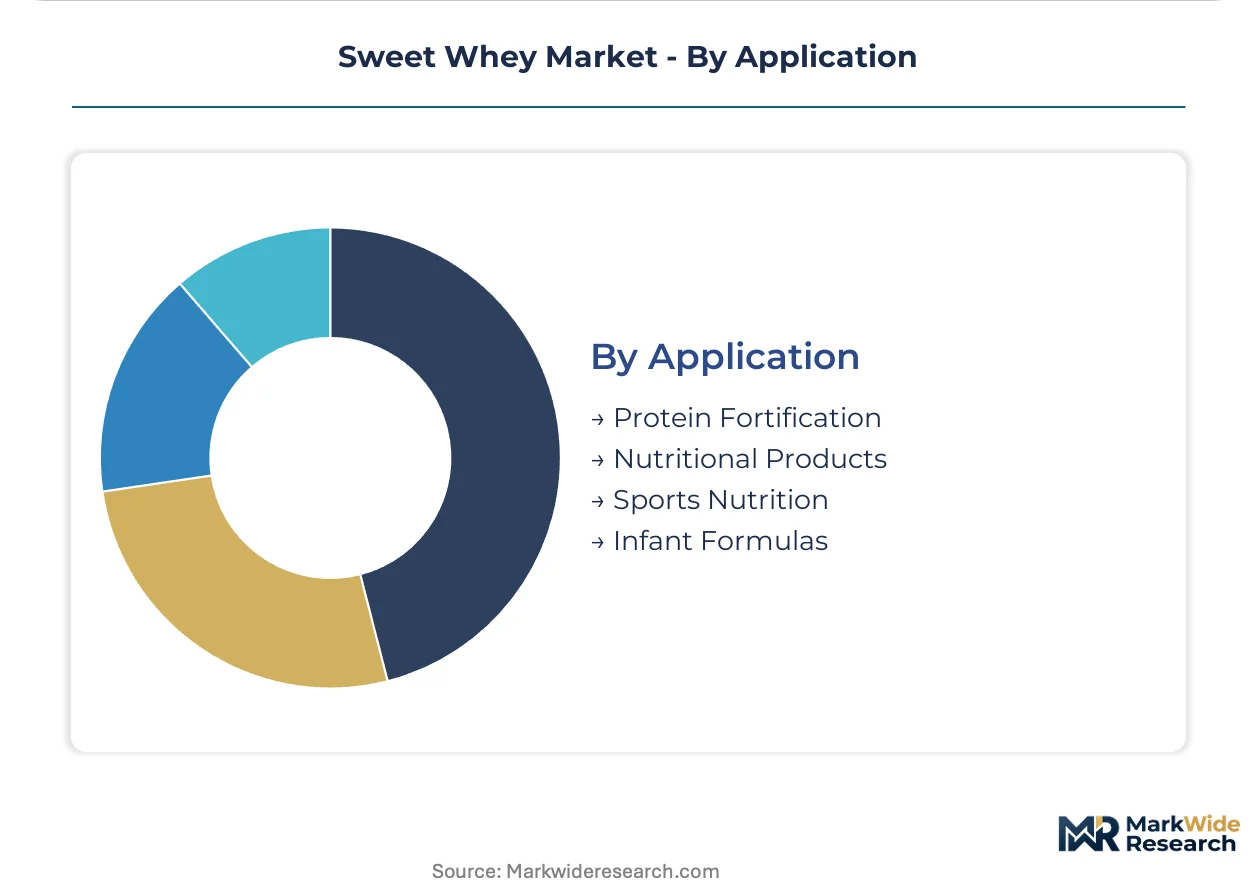
- Protein Fortification:Mass-market bakery and dairy applications standardize whey concentrate inclusion at 2-5% solids for nutritional label claims.
- Sports Nutrition:Rapid amino acid absorption specifications favor hydrolyzed and isolate grades. Direct procurement contracts now embed quality auditors at fractionation facilities, displacing spot-market purchases.
- Infant Formulas:Codex Alimentarius protein quality dossiers require 18-24 month validation cycles, creating steep barriers for new hydrolysate variants.
- Nutritional Products:Clinical and senior nutrition applications demand batch traceability and allergen documentation that commodity channels cannot supply.
Protein Fortification dominates installed base. Sports Nutrition is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments anchor European market access protocols for advanced whey hydrolysates. Dairy cooperatives in Germany concentrate fractionation capacity under tightening F-Gas Regulation compliance deadlines. Sports nutrition brands in North America and Asia-Pacific embed quality auditors directly at processing facilities, displacing traditional spot-market procurement channels.
Germany
Bavarian and Lower Saxony dairy cooperatives anchor continental whey permeate supply through backward integration into nutritional ingredient channels. EU F-Gas Regulation mandates force retrofit of spray-dryer heat recovery systems across processing sites, compressing capital deployment timelines through 2026. Electrodialysis demineralization investments concentrate in Danish and Dutch facilities serving German infant formula demand.
United States
FDA food additive regulations and USDA dairy grading standards govern whey ingredient safety and compositional claims across interstate commerce. Sports nutrition formulators standardize protein enrichment across ready-to-drink portfolios, pulling isolate demand through specialized fractionation contracts. Wisconsin and California processing clusters anchor North American whey concentrate offtake agreements.
India
FSSAI protein claim regulations are stabilizing, enabling whey isolate positioning in emerging gym-channel distribution networks. Sports nutrition underpenetration creates expansion vectors for concentrate and isolate grades in metropolitan fitness markets. Maharashtra and Karnataka dairy processors are building fractionation partnerships with international ingredient suppliers.
Netherlands
REACH-aligned fractionation chemistry advances enable membrane filtration systems that recover native protein structures without denaturing agents. FrieslandCampina deploys electrodialysis demineralization at scale, collapsing operating expenditure differentials between standard and premium whey fractions. Dutch membrane process design expertise concentrates with retiring dairy technologists, creating engineering talent scarcity.
New Zealand
Fonterra Co-operative Group Limited leverages its milk pool to sustain long-term whey concentrate supply contracts with global nutritional formulators. Supply-side geographic concentration creates single-source risk for international offtake agreements. Canterbury and Waikato processing regions anchor Southern Hemisphere whey permeate exports.
Sweet Whey Market Competitive Landscape
Dairy cooperatives and specialized nutrition ingredient divisions split the market between captive milk pool control and advanced fractionation capabilities. The vendor base organizes around three strategic archetypes: cooperative-owned processors with backward-integrated milk supply, standalone ingredient specialists with membrane technology leadership, and diversified dairy conglomerates with multi-product portfolios. Dominant competitive moves include direct procurement contract embedding of quality auditors at fractionation facilities and electrodialysis capacity investments for infant-formula-grade certification.
Within the cooperative processor tier, Fonterra Co-operative Group Limited and FrieslandCampina exemplify milk pool anchoring strategies that sustain long-term supply contract security. Arla Foods Ingredients occupies a position representing advanced fractionation specialization, particularly in European infant formula-grade whey production. Glanbia Nutritionals exemplifies the nutrition channel-focused archetype, with positioning in North American sports nutrition isolate supply. These three companies collectively represent the strategic spectrum from upstream milk control through downstream application-specific formulation partnerships.
| Leading Market Players |
|---|
| Hilmar Ingredients |
| Royal FrieslandCampina |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Saputo Inc. |
| Lactalis Group |
| Glanbia Nutritionals |
| Carbery Group |
| Arla Foods Ingredients |
| Others |
Value Network & Pricing Analysis
Bavarian dairy cooperative concentration anchors continental whey permeate supply, translating backward integration into pricing power over nutritional formulators. EU F-Gas Regulation compliance costs feed through to contract structures, with German processors embedding retrofit premiums into long-term offtake agreements.
Pricing Analysis
Price spreads between German and New Zealand whey concentrate contracts reflect energy input differentials and carbon intensity benchmarks. Three-tier pricing structure across infant-formula-grade, sports-nutrition-grade, and commodity-food-grade certifications drives differentiation, with electrodialysis demineralization investment separating premium tiers. Cost compression in commodity whey powder is intensifying because plant protein substitutes erode bakery application margins. Bakery manufacturers exhibit highest price sensitivity, while infant formula brands accept premiums for Codex Alimentarius-certified hydrolysates.
Supply Chain Analysis
Tariff exposure between New Zealand and major dairy importing regions dominates supply chain risk assessment for whey concentrate offtake. Production gravity centers on Germany, New Zealand, and the Netherlands, with Dutch membrane technology and German drying capacity feeding European demand. Raw material dependencies include fresh milk supply, natural gas for spray-drying energy, and ion-exchange resins for demineralization. Single-source vulnerability concentrates with Fonterra's milk pool dominance. Distribution runs through direct procurement contracts between dairy cooperatives and nutritional formulators, displacing traditional ingredient trading channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweet whey sits in early-cycle expansion as sports nutrition fortification standardizes across functional beverage portfolios, with Indian gym-channel penetration representing substantial untapped volume.
For Market Incumbents: Entrench fractionation capabilities through electrodialysis capacity additions in Denmark and the Netherlands, securing infant-formula-grade certification moats. Deepen backward integration into Bavarian and Lower Saxony milk pools to offset New Zealand supply concentration risk. Plant protein substitution in bakery applications threatens commodity whey powder margins, demanding quality auditor embedding at customer facilities to defend premium positioning. For New Entrants and Emerging Players: Build out membrane filtration partnerships with Maharashtra and Karnataka dairy processors to access Indian sports nutrition distribution. White-space concentration sits in clinical nutrition-grade isolate supply, where allergen documentation requirements create barriers for commodity processors. Precision fermentation hybrid ingredient systems offer differentiation angle for specialty nutrition channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane process design specialists with REACH-aligned fractionation chemistry capabilities. Five-to-ten year viability hinges on EU Green Deal carbon border adjustment qualification for low-emission drying investments. Acquisition targets should demonstrate F-Gas Regulation retrofit completion or transcritical CO2 heat pump commissioning. Signal to monitor: Codex Alimentarius protein quality dossier approval timelines for new hydrolysate variants.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodialysis Capacity Expansion | Collapses operating expenditure differentials between standard and premium whey fractions at FrieslandCampina scale. |
| Transcritical CO2 Heat Pump Retrofit | Qualifies German processors for EU Green Deal transitional financing and carbon border adjustment advantages. |
| Direct Procurement Contract Embedding | Displaces spot-market whey protein concentrate purchases as sports nutrition brands deploy quality auditors at fractionation facilities. |
| Indian Distribution Partnership Buildout | Captures gym-channel expansion as FSSAI protein claim regulations stabilize in Maharashtra and Karnataka markets. |
| Precision Fermentation Hybrid Development | Creates cell-culture lactose coupling with traditional whey processing for specialty nutrition ingredient systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across dairy cooperative executives, membrane process engineers, sports nutrition formulators, infant formula procurement managers, and FSSAI regulatory specialists. Secondary validation drew from EFSA novel food assessments, Codex Alimentarius protein quality dossiers, EU F-Gas Regulation implementation reports, and Fonterra supply contract disclosures. Bottom-up volume modeling triangulated against top-down dairy production statistics.
Calibration against historical fractionation capacity utilization and energy input cost series anchored projection parameters across the analysis window. Segmentation dimensions spanned product type, protein concentration tier, end-use application, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and infant formula demand elasticity modeling. Forecast inputs included natural gas price scenario sensitivity and plant protein substitution rate assumptions.
Sensitivities concentrate around EU F-Gas Regulation retrofit completion timelines, New Zealand milk pool supply disruptions, and FSSAI regulatory enforcement intensity in Indian states. Forecasts reflect documented assumptions on membrane technology adoption curves and carbon intensity benchmark evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ghee Market
Dairy Products
North America Yogurt Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Recombined Milk Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
White Cheese Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Cream Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Butter Powder Market
Dairy Products
Japan Casein Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Cheese Packaging Market
Dairy Products
Malted Milk Powder Market