
 North America Frozen Desserts Market | 2026-2036
North America Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Desserts Market Analytics
Subscription-based replenishment programs for home delivery of frozen desserts is repositioning how brands build recurring revenue and consumer lock-in. Unilever leverages its direct-to-consumer platform infrastructure to sustain repeat purchase rates in premium ice cream. Nestlé anchors its competitive stance through specialized gelato and sorbet lines targeting health-conscious households. General Mills competes aggressively on manufacturing scale and frozen yogurt innovation.
Frozen desserts comprise dairy and non-dairy formulations that are aerated, frozen, and stabilized to achieve specific overrun percentages and texture profiles, serving primarily as indulgent refreshment and meal-accompaniment products in both retail and food service channels. Ice cream occupies the dominant margin pool across the North American market due to established brand equity and premium pricing power, while frozen yogurt continues gaining traction among health-positioned consumers seeking lower-fat alternatives. Gelato and sorbet segments attract specialty channel placement and higher per-unit margins in urban food service locations.
FDA nutrition labeling requirements, USDA dairy grading standards, and Health Canada food safety regulations collectively shape formulation choices, ingredient sourcing, and cross-border market access for frozen dessert manufacturers operating across North America. The FDA's updated serving-size declarations and added-sugar disclosure mandates are forcing reformulation investments across legacy product portfolios. Stakeholders must monitor evolving clean-label certification demands and state-level dairy alternative labeling disputes to anticipate compliance costs and positioning opportunities.
Market Dynamics
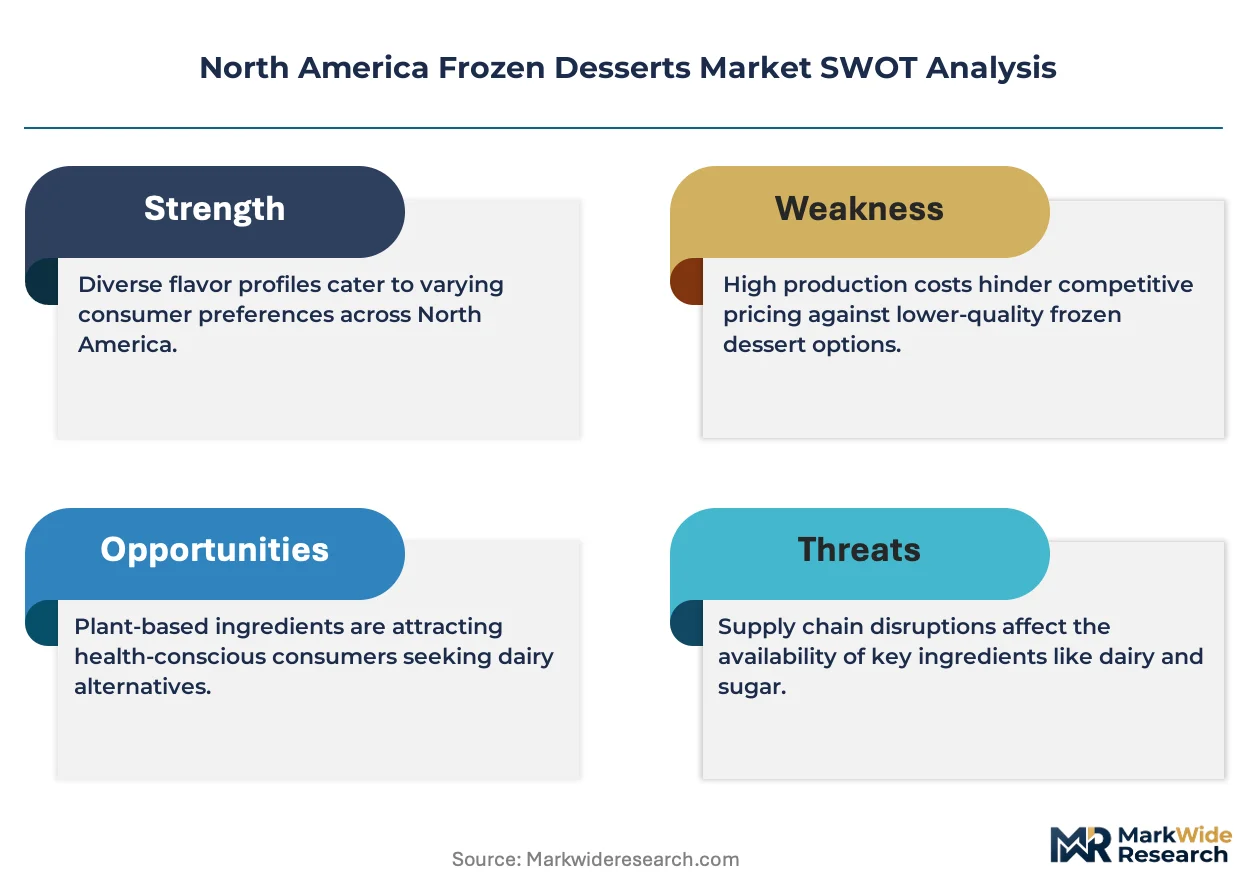
FDA's updated nutrition labeling mandates and added-sugar disclosure requirements are forcing systematic reformulation across legacy frozen dessert portfolios, compressing margins while accelerating clean-label investment cycles.
Growth Catalysts
- Clean-label certification momentum:USDA Organic and Non-GMO Project Verified standards are expanding shelf-space allocation in US retail channels, rewarding brands that eliminate artificial stabilizers.
- Quick-service menu expansion:Food service operators across the United States are adding premium gelato and sorbet lines to differentiate dessert offerings and capture higher check averages.
- Direct-to-consumer infrastructure:Subscription replenishment platforms are locking in recurring revenue streams for ice cream brands with specialized cold-chain logistics.
Market Restraints
- Dairy input cost volatility:Fluid milk and cream price swings tied to USDA commodity programs compress margin predictability for traditional ice cream manufacturers.
- Clean-label reformulation costs:Replacing artificial emulsifiers with natural alternatives such as locust bean gum requires capital-intensive process revalidation.
- Plant-based substitution threat:Oat and coconut milk frozen desserts are capturing shelf space previously reserved for dairy formulations in Canadian and US natural channel retailers.
Strategic Opportunities
- Mexico retail underpenetration:Modern trade expansion in Mexican metropolitan areas creates first-mover positioning for premium frozen dessert entrants with localized flavor development.
- Functional ingredient convergence:Probiotic cultures and adaptogenic botanicals are opening wellness-positioned frozen dessert subcategories targeting post-meal digestive health occasions.
- Ghost kitchen dessert channels:Virtual brands operating through third-party delivery aggregators are creating dedicated frozen dessert concepts without brick-and-mortary capex requirements.
Industry Challenges
- Cold-chain talent scarcity:Specialized refrigeration engineering and last-mile frozen logistics expertise remains concentrated among legacy dairy distributors, constraining new entrant scale-up.
- Dual certification timelines:Simultaneous FDA nutrition label compliance and USDA Organic recertification are extending product launch windows by 8-14 months for reformulated lines.
- Legacy ERP integration friction:Frozen dessert manufacturers with dated manufacturing execution systems face complexity connecting traceability data to retailer blockchain verification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Desserts Market |
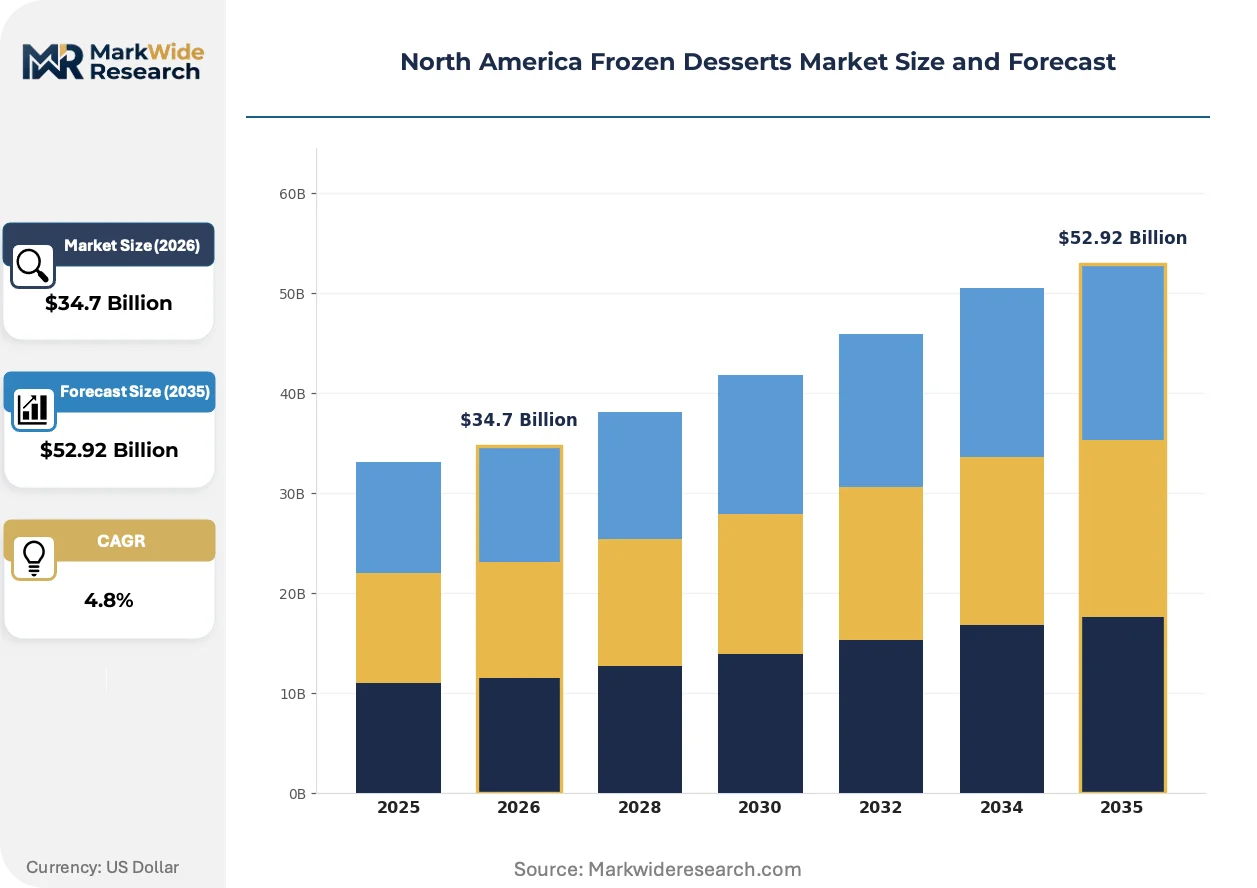
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Gelato, Frozen Yogurt Customer Type: Retail Consumers, Food Service, Wholesale Distributors, Online Shoppers Flavor Profile: Chocolate, Vanilla, Strawberry, Mint Packaging Type: Pints, Cups, Bars, Tubs |
| Companies Covered | Unilever, Nestlé, Froneri International Limited, General Mills, Blue Bell Creameries, Wells Enterprises, Dairy Farmers of America, The Kraft Heinz Company, Tillamook, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Desserts Market Evolving Landscape
Precision freezing technologies and alternative protein bases are converging to reshape texture standards and ingredient sourcing across North American frozen dessert manufacturing.
High-pressure processing (HPP) is electrifying clean-label preservation in premium ice cream and gelato production. Artisanal manufacturers in urban food service clusters are adopting HPP systems to eliminate thermal pasteurization while maintaining overrun stability. This technology is electrifying market segmentation by enabling raw-dairy positioning previously impossible under conventional processing constraints.
The FDA's updated Reference Amounts Customarily Consumed (RACC) regulations are restructuring serving-size declarations and added-sugar line-item disclosures on frozen dessert packaging. Manufacturers must recalculate entire nutritional panels and reformulate recipes to avoid front-of-package warning triggers. Full-service restaurants and retail pint brands face the steepest compliance costs, with many accelerating reduced-sugar recipe development to maintain permissible label claims.
Subscription-based replenishment is consolidating household purchasing into predictable auto-delivery cycles for premium frozen desserts. Direct-to-consumer platforms are displacing conventional grocery impulse purchases among urban millennials and health-conscious households. This behavioral shift concentrates most visibly in California and New York metropolitan corridors, where cold-chain logistics density supports reliable home delivery of ultra-premium gelato and functional frozen yogurt formats.
North America Frozen Desserts Market Segmentation
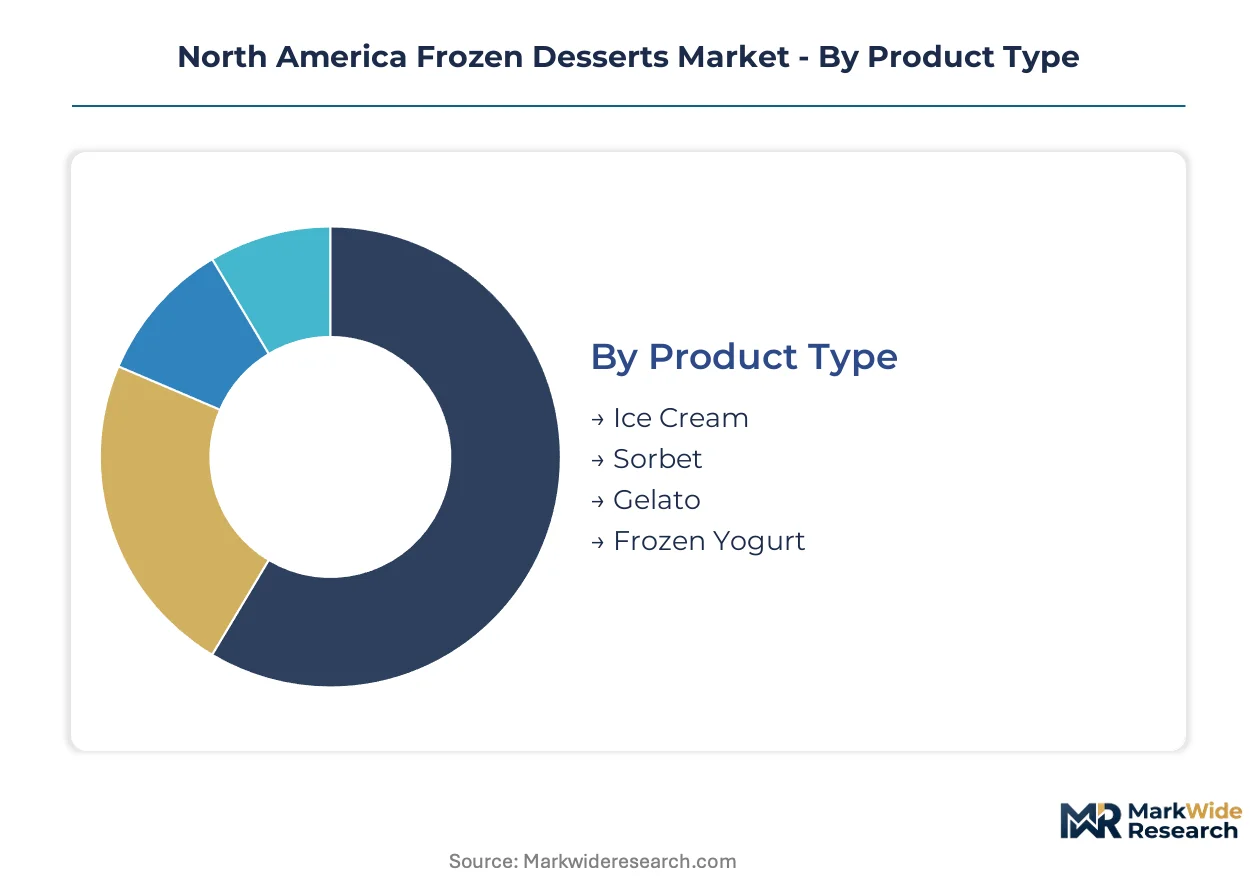
Segmentation in frozen desserts reveals distinct margin structures and cold-chain requirements that determine channel strategy and manufacturing investment priorities. Product formulation choices lock manufacturers into specific distribution partnerships and retail placement negotiations.
Product Type:
Reformulation cycles across product categories are accelerating as FDA added-sugar disclosures force legacy portfolio upgrades and clean-label repositioning.
- Ice Cream:Dairy-based formulations with overrun percentages typically ranging from 50% to 100% define texture standards and manufacturing capital intensity. United States retail channels concentrate demand for premium butterfat variants, though fluid milk price volatility under USDA commodity programs compresses margin predictability for traditional manufacturers.
- Frozen Yogurt:Live and active culture requirements differentiate this segment through probiotic positioning and lower-fat nutritional claims. Health-conscious households in California and New York metropolitan corridors drive demand concentration, with quick-service operators expanding self-serve formats to capture higher check averages.
- Sorbet:Dairy-free fruit-based formulations achieve clean-label positioning without allergen labeling complications.
- Gelato:Lower overrun and higher serving temperature requirements distinguish artisanal production methods and urban food service placement.
Ice cream sits at the top of the volume ranking, with frozen yogurt climbing the fastest.
Customer Type:
Channel economics diverge sharply based on cold-chain custody requirements and purchase frequency patterns across end-use segments.
- Retail Consumers:Grocery and convenience store purchases dominate volume flow, with impulse buying patterns concentrated in summer seasonal peaks. Canadian and US natural channel retailers are reallocating shelf space toward plant-based alternatives, pressuring traditional dairy formulation placement.
- Food Service:Quick-service and full-service operators command premium pricing power through portion-controlled dessert menu extensions. Mexican metropolitan modern trade expansion creates first-mover positioning for premium entrants with localized flavor development capabilities.
- Wholesale Distributors:Consolidated purchasing relationships with legacy dairy cold-chain infrastructure constrain new entrant market access.
- Online Shoppers:Subscription replenishment platforms concentrate household purchasing into predictable auto-delivery cycles for ultra-premium formats.
Retail consumers anchor absolute volume, while online shoppers gain share fastest through direct-to-consumer platform expansion.
Flavor Profile:
Flavor innovation cycles determine ingredient sourcing relationships and seasonal production scheduling across manufacturing facilities.
- Chocolate:Cocoa butter and cocoa powder specifications vary by premium tier, with single-origin positioning commanding ingredient traceability investments. United States retail channels sustain dominant placement for this flavor across all product categories.
- Vanilla:Bourbon and Tahitian vanilla bean sourcing faces price volatility from Madagascar and Indonesia supply disruptions.
- Strawberry:Fruit preparation inclusion rates and artificial color replacement drive clean-label reformulation complexity.
- Mint:Seasonal demand concentration around winter holidays requires flexible production line scheduling.
Chocolate maintains volume leadership, with mint expanding most quickly through limited-edition seasonal positioning.
Packaging Type:
Packaging format selection shapes distribution economics, consumption occasion targeting, and sustainability compliance investments.
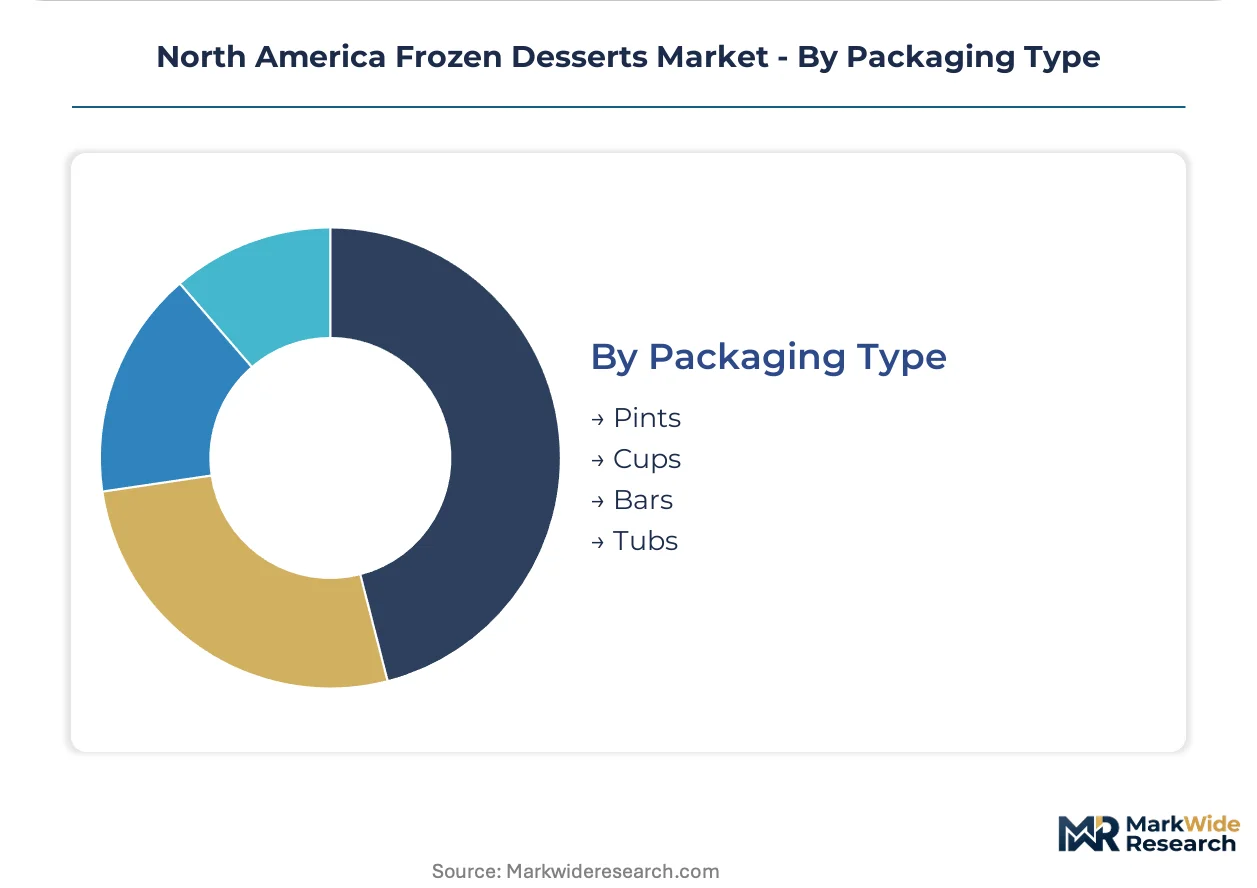
- Pints:Standardized 473ml containers dominate premium retail placement and direct-to-consumer shipping economics. Urban millennial households in dense metropolitan corridors favor this format for home consumption occasions.
- Bars:Individual portion formats capture impulse purchase occasions and food service single-serve requirements.
- Cups:Single-serve portions align with quick-service and convenience channel distribution.
- Tubs:Bulk formats serve family consumption and food service batch preparation needs.
Pints lead volume rankings, with bars gaining share fastest through convenience channel expansion and on-the-go consumption growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates impose steeper compliance costs than Health Canada or Mexican COFEPRIS standards, creating production-cost differentials that shape cross-border manufacturing location decisions. Brands reformulating for US market access often absorb disproportionate R&D burdens relative to Canadian or Mexican operations.
United States
Premium gelato and sorbet demand concentrates in California and New York metropolitan corridors where subscription replenishment platforms lock in recurring revenue. FDA added-sugar disclosure requirements and updated Reference Amounts Customarily Consumed regulations force systematic portfolio reformulation. Chicago anchors Midwest dairy processing infrastructure serving national retail distribution networks.
Canada
Health Canada food safety regulations and CFIA dairy grading standards shape cross-border ingredient sourcing for manufacturers serving both markets. Toronto and Vancouver metropolitan areas drive demand for plant-based frozen desserts as natural channel retailers reallocate shelf space. Quebec's dairy supply management system stabilizes input costs distinct from US commodity volatility.
Mexico
Modern trade expansion in Mexico City, Monterrey, and Guadalajara creates first-mover positioning for premium entrants with localized flavor development. COFEPRIS food safety regulations govern import clearance and domestic manufacturing licensing. Northern border states leverage proximity to US cold-chain infrastructure for cross-border distribution efficiency.
North America Frozen Desserts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG conglomerates commanding retail shelf space while regional dairies and co-manufacturers capture food service and private-label volume. Market structure tilts toward consolidation at the premium tier and fragmentation in specialty and private-label supply. Three archetypes dominate: vertically integrated dairy cooperatives, multinational brand houses with direct-to-consumer infrastructure, and regional artisanal specialists with urban food service placement. Competitive moves center on clean-label reformulation races and cold-chain logistics partnerships that secure last-mile frozen distribution.
Among multinational brand houses, Unilever and Nestlé occupy positions exemplifying scale-driven premium portfolio management, while General Mills represents manufacturing-scale competition targeting frozen yogurt innovation. These entities anchor the competitive set through distinct strategic postures rather than convergent operational models.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Froneri International Limited |
| General Mills |
| Blue Bell Creameries |
| Wells Enterprises |
| Dairy Farmers of America |
| The Kraft Heinz Company |
| Tillamook |
| Others |
Value Network & Pricing Analysis
FDA added-sugar disclosure mandates are forcing legacy manufacturers to reformulate entire portfolios, compelling supply chains to absorb natural stabilizer cost premiums while distributors negotiate shelf-space terms that reflect clean-label positioning investments.
Pricing Analysis
Retailer markup layers dominate final price formation, with grocery channels commanding 25-35 point spreads above manufacturer invoice. Three-tier pricing structure across premium, standard, and economy levels separates artisanal gelato from mass-market ice cream and private-label tubs. Pricing pressure stems from fluid milk commodity volatility under USDA programs, compressing margin predictability for traditional dairy formulations. Quick-service operators show highest price sensitivity due to portion-controlled menu economics, while direct-to-consumer subscription buyers accept premium positioning for specialized cold-chain reliability.
Supply Chain Analysis
Regional distribution centers in Wisconsin, California, and New York anchor hub-and-spoke cold-chain patterns serving national retail networks. Manufacturing concentrates in the United States, with Canada providing dairy inputs under supply-managed pricing and Mexico offering border-proximity advantages for southern distribution. Raw material dependencies include Madagascar vanilla beans, Indonesian coconut cream, and domestic fluid milk under federal pricing orders. Single-source vulnerability runs through specialized refrigeration engineering talent concentrated among legacy dairy distributors. Distribution runs through multi-temperature-controlled fleets serving quick-service, grocery, and direct-to-consumer channels with distinct custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA nutrition labeling mandates function as a regulatory compounder, with added-sugar disclosure requirements forcing systematic portfolio upgrades that reward first-mover reformulation investments.
For Market Incumbents: Hedge margin compression from clean-label reformulation costs by securing captive supply of natural stabilizers such as locust bean gum and tara gum. Accelerate USDA Organic certification timelines to capture shelf-space reallocation in United States natural channel retailers before dual certification backlogs extend launch windows further. For New Entrants and Emerging Players: Precision freezing technology offers a technology-first wedge into urban food service clusters seeking raw-dairy positioning without conventional pasteurization constraints. Target Mexican metropolitan modern trade expansion in Mexico City and Monterrey with localized flavor development capabilities. Pursue ghost kitchen partnerships with third-party delivery aggregators to bypass brick-and-mortar capex requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with regional artisanal specialists possessing USDA Organic certification and established urban food service placement. Long-term viability centers on cold-chain logistics partnerships that secure last-mile frozen distribution density. Monitor FDA enforcement patterns on added-sugar disclosure compliance as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | USDA Organic certification unlocks shelf-space reallocation in United States natural channel retailers. |
| Direct-to-Consumer Platform Launch | Subscription replenishment locks recurring revenue in California and New York metropolitan corridors. |
| Cold-Chain Logistics Partnership | Specialized last-mile frozen distribution secures placement in quick-service menu expansion programs. |
| Localized Flavor Development | Mexican metropolitan modern trade expansion demands region-specific taste profiles for premium positioning. |
| High-Pressure Processing Adoption | HPP systems enable raw-dairy positioning in urban food service clusters previously impossible under thermal constraints. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners at frozen dessert manufacturers. Secondary validation drew from FDA labeling guidance documents, USDA commodity price reports, Health Canada food safety directives, Nielsen retail audit data, and customs import records. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Granularity-level modeling addressed product type, customer channel, flavor profile, and packaging format dimensions at the country level. CAGRs were derived from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted price assumptions. Forecast inputs incorporated fluid milk commodity program pricing, clean-label certification adoption curves, and cold-chain logistics capacity expansion patterns.
The model holds under stable regulatory enforcement timelines; deviation in FDA added-sugar disclosure implementation pace or USDA dairy pricing volatility would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market