
 Seed Treatment Market | 2026-2036
Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Treatment Market Intelligence
Expanded agricultural production capacity in Brazil for soybean and corn is rewriting the competitive positioning for providers of fungicide and insecticide treatments. Bayer AG leverages its extensive portfolio in both chemical and biological solutions to capture value from large-scale farm operations. Syngenta sustains its market presence through advanced seed enhancement technologies, including film coating and pelleting. Meanwhile, Corteva Agriscience differentiates with integrated solutions that combine proprietary seed genetics with its own seed-applied technologies.
Seed treatment involves applying chemical or biological substances directly onto seeds before sowing to protect them from pests and diseases. This process ensures improved germination rates and early plant vigor by creating a protective zone around the seed. Insecticides and fungicides constitute the largest product segments, though biostimulants are expanding rapidly due to regulatory pressure on chemical inputs. Seed coating is the primary application method, offering superior dose accuracy and worker safety over traditional seed dressing.
Regulatory oversight from bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH dictates permissible active ingredients and maximum residue limits. In parallel, China's Ministry of Ecology and Environment (MEE) enforces stringent standards on pesticide residues, influencing formulation choices for all market participants. Decisions for agrochemical companies and seed producers will hinge on balancing the efficacy of new biological treatments against the proven performance of conventional chemical products.
Market Dynamics
The central structural force shaping the seed treatment market is the regulatory-driven substitution of conventional chemical pesticides with biological alternatives. This shift, exemplified by policies like the EU Green Deal, is compelling innovation in biostimulants and bio-fungicides across the entire value chain.
Growth Catalysts
- Favorable Regulatory Frameworks:Policies such as the EU's Farm to Fork strategy, which mandate reductions in chemical pesticide use, directly stimulate demand for biological seed treatments like bio-fungicides and biostimulants.
- Intensified Agricultural Production:Expansive cultivation of export-oriented crops, particularly soybean and corn in Brazil and Argentina, drives adoption of treatments that maximize yield and protect investments in high-value seeds.
- Advanced Seed Genetics:The proliferation of high-value hybrid and genetically modified seeds makes protective seed treatments an essential insurance policy for farmers to ensure optimal germination and early plant establishment.
Market Restraints
- Performance and Cost Disparity:Biological treatments can exhibit inconsistent efficacy under variable field conditions and often have a higher upfront cost compared to the proven, broad-spectrum performance of conventional chemical products.
- Stringent Registration Timelines:The lengthy and data-intensive approval processes for new active ingredients, enforced by bodies like the US EPA and ECHA, create significant barriers to market entry for novel treatments.
- Farmer Adoption Inertia:A deep-seated reliance on familiar chemical-based crop protection programs and a learning curve associated with integrating biologicals can slow the rate of adoption among conservative growers.
Strategic Opportunities
- Next-Generation Biologicals:Development of advanced microbial-based products, including synergistic consortia of bacteria and fungi, offers opportunities to provide multiple benefits such as nutrient uptake enhancement alongside pest control.
- Expansion in Specialty Crops:Targeting high-value fruit and vegetable markets, where growers can more easily absorb premium costs for superior crop quality and residue compliance, presents a significant growth avenue.
- Untapped Geographic Markets:Agricultural economies in Southeast Asia and Africa are undergoing modernization, creating new demand for seed enhancement technologies as they seek to improve food security and crop productivity.
Industry Challenges
- Biological Agent Viability:Ensuring the shelf life and on-seed survival of live microbial active ingredients through the coating, storage, and planting process remains a significant technical and logistical challenge for manufacturers.
- Navigating Residue Limits:Formulating products that comply with a patchwork of divergent maximum residue limits (MRLs) across key export markets, such as those enforced by China's MEE, complicates global product development.
- Agronomic Expertise Gap:Effective use of integrated pest management programs that combine biological and chemical treatments requires specialized knowledge, creating a challenge in farmer education and advisory services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Treatment Market |
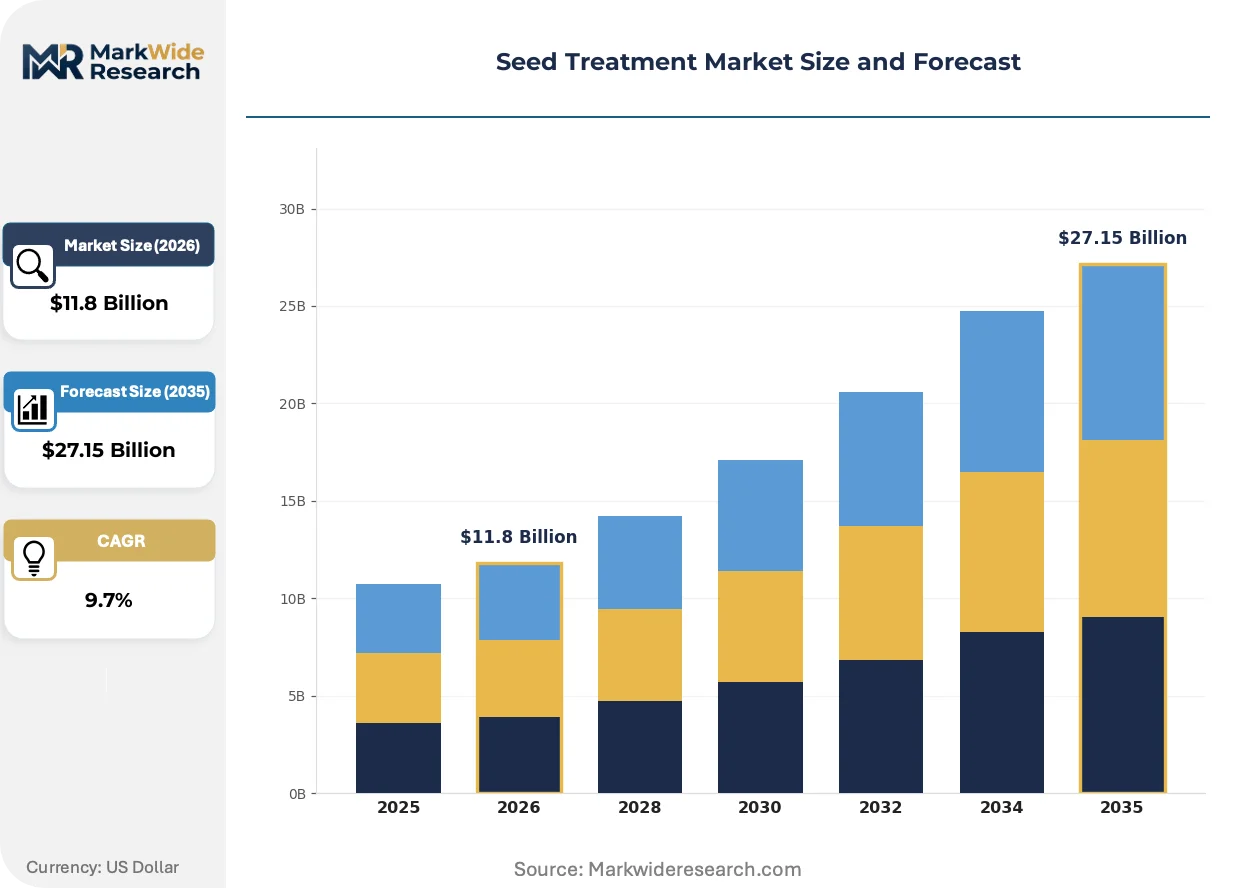
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $27.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Biostimulants, Nematicides, Herbicides Crop Type: Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Fiber Crops Application: Seed Coating, Film Coating, Pelleting, Dressing End User: Seed Producers, Agrochemical Companies, Agriculture Contractors, Research Institutes |
| Companies Covered | Corteva Agriscience, FMC Corporation, Syngenta, Sumitomo Chemical, Nufarm, BASF SE, UPL, Croda International, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Treatment Market Strategic Shifts & Innovations
A convergence of material science and biotechnology is redefining seed treatment formulations. The industry is moving toward solutions that enhance seed performance while minimizing environmental impact, responding directly to both regulatory pressures and changing grower expectations for sustainability.
Microplastic-free seed coatings are a primary area of product evolution. These advanced formulations use biodegradable materials to bind active ingredients to the seed, preventing dust-off and ensuring precise application. Major seed companies and agricultural cooperatives are adopting these technologies to meet new environmental standards. The market is migrating from traditional, persistent polymer films toward these sustainable alternatives to comply with impending restrictions, such as those under consideration by ECHA.
Regulatory mandates are accelerating the transition to bio-based solutions. The European Union's Farm to Fork strategy, for instance, sets ambitious targets for reducing synthetic pesticide use. This policy directly impacts product development pipelines, forcing a strategic pivot toward biological active ingredients. The chemical insecticide and fungicide segments are most affected, with development now prioritizing bio-insecticides and microbial fungicides to retain market access in Europe and other environmentally-conscious regions.
Farm-level procurement models are evolving toward integrated offerings. Large-scale agricultural enterprises increasingly prefer to purchase a single package combining proprietary seed genetics with compatible, factory-applied treatments. This disrupts the traditional channel of selling standalone chemical products through distributors, favoring seed companies that provide a complete solution. This trend is most visible in the high-volume corn and soybean markets of the Americas, where operational efficiency is paramount.
Seed Treatment Market Segmentation
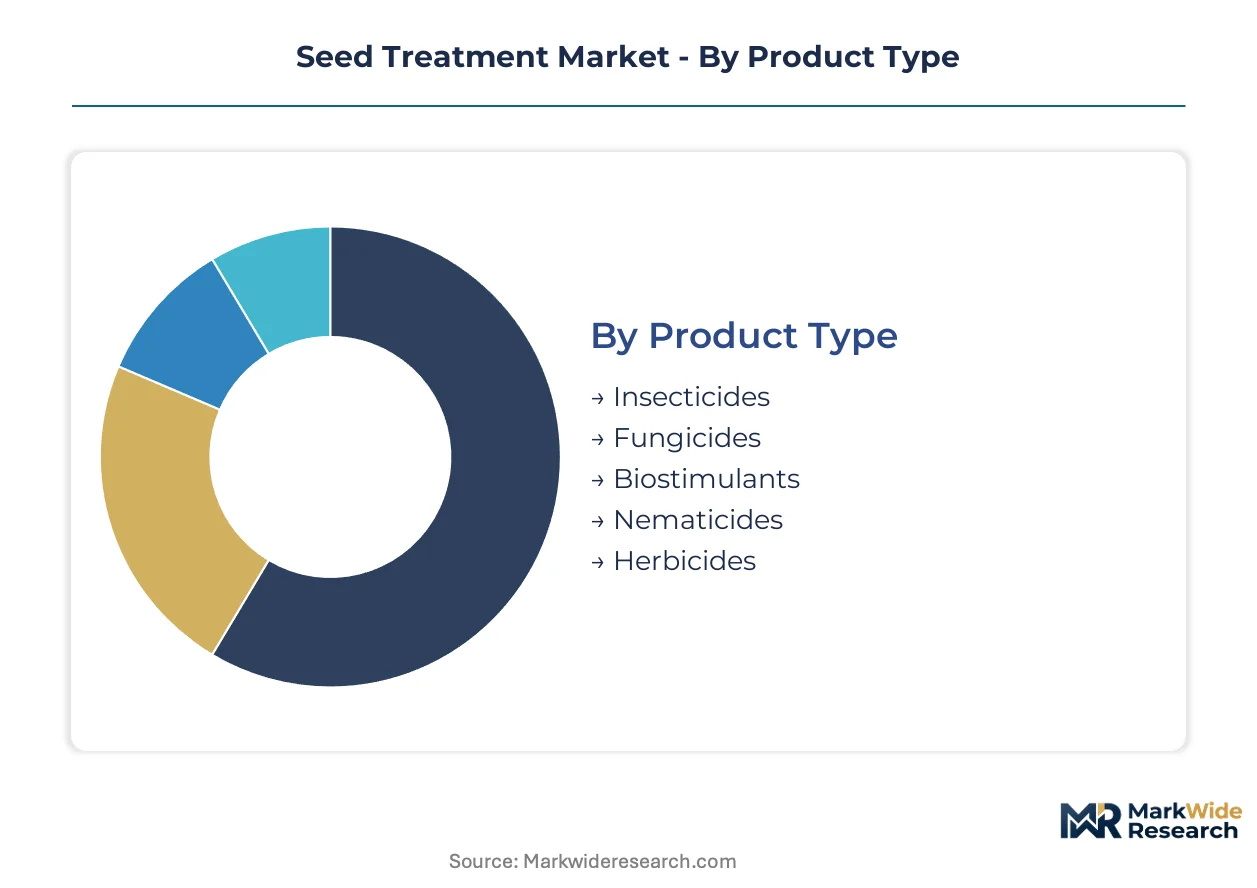
Segmentation provides a granular understanding of the seed treatment market's diverse components, revealing where innovation is concentrated and how different product types, crop applications, and end-user dynamics influence market evolution. This detailed breakdown helps stakeholders identify high-growth areas and critical technological shifts impacting agricultural productivity.
Product Type:
The product type segment spans a maturity spectrum, from established chemical solutions to rapidly evolving biological alternatives. These treatments protect seeds from various threats, ensuring optimal plant establishment and yield potential.
- Fungicides:These chemical or biological agents protect seeds and seedlings from fungal diseases, which can cause damping-off or root rot. Demand for bio-fungicides is climbing in Europe, driven by the EU Green Deal's mandates for reduced chemical input.
- Biostimulants:Comprising substances or microorganisms, biostimulants enhance nutrient uptake, stress tolerance, and crop quality, independent of nutrient content. Adoption is accelerating in Brazil and Argentina as farmers seek to maximize yield from high-value soybean and corn crops.
- Insecticides:These treatments shield seeds from insect pests during germination and early growth stages, preventing significant crop damage.
- Nematicides:Applied to seeds, nematicides control parasitic nematodes that attack plant roots, improving overall plant health.
- Herbicides:Seed-applied herbicides offer early-season weed control, reducing competition for resources for young plants.
Fungicides handle the majority of throughput; Biostimulants are the fastest mover on share.
Crop Type:
Crop type segmentation highlights the volume and value contribution of different agricultural commodities to the seed treatment market. Specific crop needs drive tailored treatment formulations and application strategies.
- Cereals & Grains:This segment includes crops like corn, wheat, and rice, which benefit from treatments that enhance germination and protect against early-season pests and diseases. Demand is concentrated in the Americas, where large-scale corn cultivation requires robust protection for hybrid seeds.
- Oilseeds & Pulses:Crops such as soybeans, canola, and lentils are highly susceptible to soil-borne pathogens and insect pests, necessitating advanced seed treatments. Soybean cultivation in Brazil and Argentina drives significant demand for protective solutions to safeguard export volumes.
- Fruits & Vegetables:These high-value crops often require specialized treatments that minimize chemical residues while ensuring crop quality and yield.
- Fiber Crops:Cotton and other fiber crops utilize seed treatments to protect against specific pests and diseases prevalent in their growing regions.
The integration of Cereals & Grains solutions offers enhanced protection for large-scale operations, while Fruits & Vegetables solutions deliver targeted benefits for specialized growers.
Application:
This category differentiates seed treatment by the precision and method of active ingredient delivery onto the seed surface. Each method offers distinct advantages in terms of adherence, dose accuracy, and worker safety.
- Seed Coating:This primary application method involves applying a thin, uniform layer of active ingredients directly onto the seed surface, ensuring precise dosage and reduced environmental exposure. It offers superior dose accuracy and worker safety compared to traditional methods.
- Film Coating:A more advanced form of seed coating, film coating uses polymer-based materials to bind active ingredients, creating a smooth, durable layer that minimizes dust-off and enhances seed flow. This technology is increasingly adopted by major seed companies for high-value seeds.
- Pelleting:Pelleting involves building up a layer of inert material around the seed to improve its shape, size, and weight, often incorporating active ingredients. This method facilitates precision planting for small or irregularly shaped seeds.
- Dressing:A basic application method where dry or wet formulations are mixed with seeds, offering fundamental protection but with less precision than coatings.
Technological advancements in Seed Coating are driving efficiency, as Dressing methods provide foundational protection.
End User:
The end-user segment reflects the strategic influence and procurement patterns of different entities within the agricultural value chain. Each end-user type has specific requirements and decision-making processes for seed treatments.
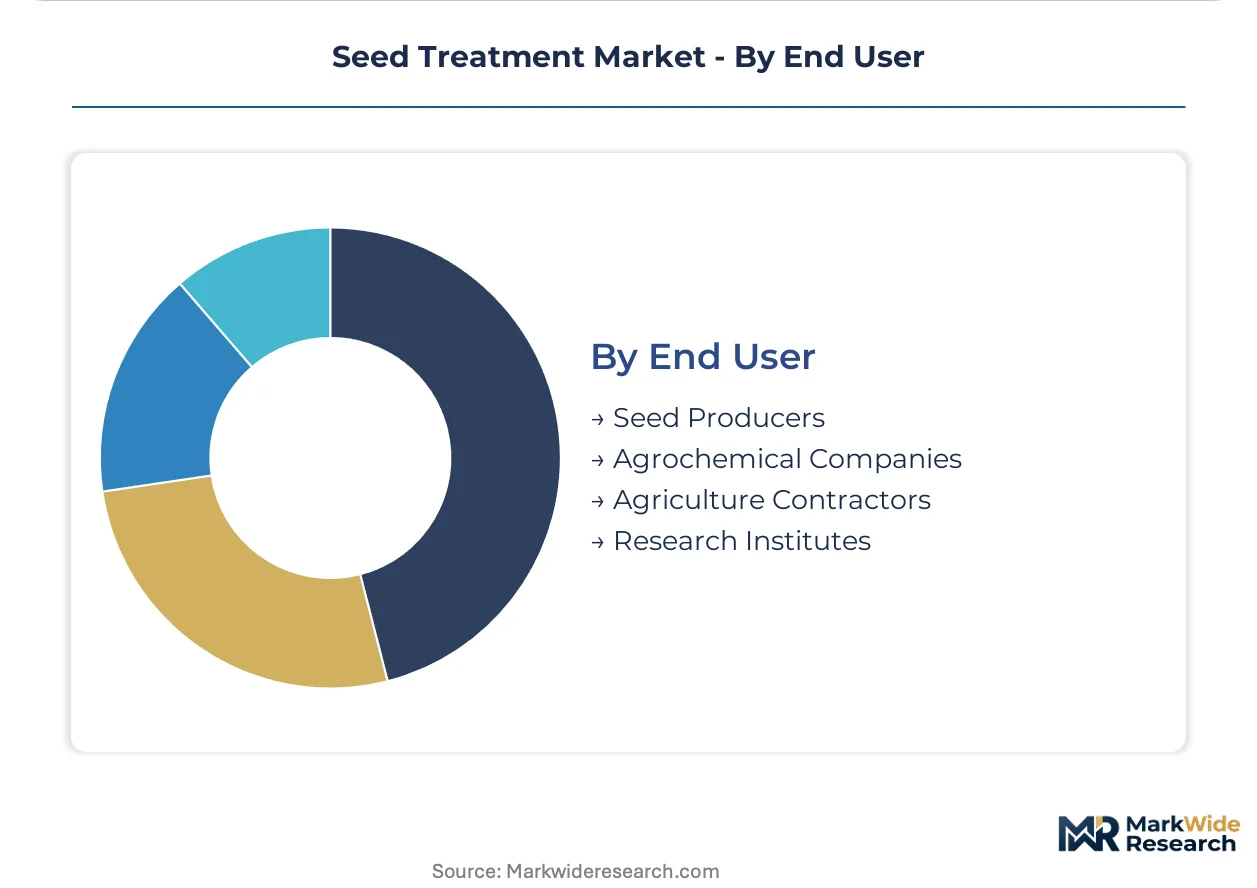
- Seed Producers:These entities apply treatments during seed processing to offer integrated solutions directly to farmers, often combining proprietary genetics with protective coatings. They drive innovation in factory-applied treatments for high-volume crops like corn and soybean.
- Agrochemical Companies:These firms develop and manufacture the active ingredients and formulations used in seed treatments, supplying both seed producers and agricultural contractors. Bayer AG leverages its broad portfolio to capture value from large-scale farm operations.
- Agriculture Contractors:These service providers apply seed treatments on behalf of farmers, offering expertise and specialized equipment for efficient application.
- Research Institutes:Academic and private research bodies focus on developing new active ingredients and application technologies, contributing to the long-term innovation pipeline.
Collaboration between Seed Producers and Agrochemical Companies is accelerating product innovation across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The seed treatment market shows significant regional variations in demand and regulatory pressures. Demand concentration for protective solutions is particularly strong in agricultural powerhouses. Local policies and crop cultivation patterns dictate adoption of advanced seed enhancement technologies.
United States
Demand for seed treatments in the United States stems from extensive corn and soybean cultivation for domestic and export markets. The US Environmental Protection Agency (EPA) sets strict guidelines for pesticide registration and maximum residue limits. Research clusters in the Midwest, particularly around Iowa, focus on developing new biological solutions for large-scale farming.
Brazil
Expansive soybean and corn cultivation in Brazil drives substantial demand for seed treatments, maximizing yield and protecting high-value seeds. ANVISA, the country's health surveillance agency, regulates agrochemical product approvals, influencing market access. Agricultural hubs in Mato Grosso and Paraná are key centers for applying advanced seed enhancement technologies.
Argentina
Argentina's large-scale export-oriented soybean and corn farming creates strong incentives for adopting protective seed treatments. The national plant health service, SENASA, oversees agrochemical registration and use, ensuring agricultural sustainability. Production in the Pampas region relies heavily on advanced seed-applied technologies for early plant vigor.
Germany
Stringent regulatory frameworks in Germany, including the EU Green Deal, accelerate the shift towards biostimulants and bio-fungicides. The European Chemicals Agency (ECHA) under REACH dictates permissible active ingredients, impacting market formulations. Research institutions in regions like Bavaria are at the forefront of developing next-generation biological seed treatments.
China
Stringent standards on pesticide residues enforced by China's Ministry of Ecology and Environment (MEE) influence formulation choices for all market participants. This regulatory environment drives innovation in seed treatment products complying with evolving environmental mandates. Agricultural research centers in provinces like Shandong actively explore sustainable seed enhancement technologies.
Seed Treatment Market Key Industry Players
Large diversified agrochemical companies and specialized seed enhancement technology providers split the seed treatment market. The competitive landscape features a tiered structure, with a few global players dominating significant market share. Strategic archetypes include integrated agricultural solution providers, dedicated seed treatment specialists, and emerging biological input developers. Dominant competitive moves involve extensive portfolio diversification into biologicals and strategic partnerships for integrated offerings.
At the scale-driven end, Germany-based Bayer AG represents a large diversified agrochemical player, leveraging its broad portfolio across chemical and biological solutions. Switzerland-based Syngenta exemplifies a provider focused on advanced seed enhancement technologies, including film coating and pelleting. Corteva Agriscience, an American entity, anchors the integrated agricultural solution archetype, combining proprietary seed genetics with its own seed-applied technologies to differentiate its offerings in key markets. These entities drive innovation through strategic investments in new product development and market expansion.
| Leading Market Players |
|---|
| Corteva Agriscience |
| FMC Corporation |
| Syngenta |
| Sumitomo Chemical |
| Nufarm |
| BASF SE |
| UPL |
| Croda International |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly those driven by environmental mandates like the EU Green Deal, determine both pricing tier spreads and the overall seed treatment supply chain shape. These policies compel innovation in biological alternatives, influencing their cost and market availability.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for seed treatments, accelerating the shift towards biologicals. A value-based pricing model dominates integrated offerings, while standalone chemical products often follow a transactional, per-unit structure. Price differentiation stems from product efficacy under variable field conditions and compliance with evolving maximum residue limits. Pricing pressure stems from the higher R&D costs of biologicals and regulatory restrictions on conventional chemical inputs. Large-scale farming operations, investing in high-value hybrid seeds, exhibit lower price sensitivity compared to smaller growers focused on commodity crops.
Supply Chain Analysis
Regulatory restrictions on active ingredients dominate the seed treatment supply chain risk profile. Geographic supply concentration centers on key agrochemical production hubs in Germany, Switzerland, and the United States. Raw material dependencies include specialized chemical compounds, live microbial cultures, and advanced polymer-based coating materials. The primary structural risk involves navigating divergent maximum residue limits across global export markets, such as those enforced by China's MEE. Distribution runs through a hybrid model, combining direct sales from seed producers with specialized agrochemical distributors and agricultural contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seed treatment market represents a significant service-attach opportunity, with advisory services for integrated pest management expanding faster than standalone product sales.
For Market Incumbents:
Build an integrated solution moat by deepening the proprietary seed genetics offering with compatible, factory-applied biological treatments. Expand the biological portfolio to counter regulatory threats against conventional chemistries. Invest in advanced R&D for microbial consortia to enhance multi-benefit offerings. Leverage established distribution channels and farmer relationships to accelerate the adoption of new biological solutions.
For New Entrants and Emerging Players:
Build out specialized biological solutions targeting specific, high-value crop segments like fruits and vegetables, where growers can absorb premium costs. Focus on developing next-generation microbial-based biostimulants with proven efficacy under diverse field conditions. The specialty crop segment in Southeast Asia represents a penetrable market due to increasing demand for residue-compliant produce. A direct-to-farmer advisory model, emphasizing agronomic expertise, can differentiate offerings.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors specialized biological input developers and integrated seed solution providers. Long-term viability hinges on companies with strong intellectual property in novel biological active ingredients and advanced application technologies. Acquisition targets should possess proven efficacy data and established regulatory pathways in key agricultural regions. A critical signal to watch is the accelerated regulatory approval of novel biological active ingredients by bodies like the US EPA and ECHA.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Next-Generation Biologicals | New biologicals provide sustainable alternatives, meeting regulatory demands for reduced chemical pesticide use. |
| Strategic Partnership: Seed Producers & Biologics Developers | Collaboration integrates proprietary seed genetics with advanced biological treatments, offering complete solutions to farmers. |
| Geographic Expansion: Southeast Asia | Modernizing agricultural economies in Southeast Asia create new demand for seed enhancement technologies. |
| R&D Investment: Microplastic-Free Coatings | Developing biodegradable seed coatings aligns with environmental regulations and enhances product sustainability. |
| Regulatory Pathway Optimization: ECHA/EPA Compliance | Streamlining approval processes for new active ingredients ensures faster market access and competitive advantage. |
Research Approach
A standing panel of agrochemical R&D directors, seed producer procurement leads, agricultural contractors, and farm cooperative managers provided ongoing calibration for market assumptions. This primary qualitative data was triangulated with extensive secondary research from regulatory databases like EPA, ECHA, and MEE, agricultural census data, and academic journals on crop science. Both bottom-up and top-down approaches validated market sizing and segmentation.
Scenario-bracketing framing informed the analytical framework across the projection horizon. The quantitative model integrated segmentation dimensions including product type, crop type, application method, and regional regulatory environment. Compound annual growth rates were derived through econometric modeling, incorporating industry-specific forecast inputs such as projected crop acreage and regulatory policy timelines for chemical phase-outs.
Practitioners should monitor new regulatory mandates, major crop disease outbreaks, and significant shifts in commodity prices for early signals of market revision. Forecasts reflect assumptions documented through primary and secondary research. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Japan Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Coating Materials Market
Seed Technology
China Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Seed Storage Systems Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
India Seed Treatment Market