
 Mexico Seed Treatment Market | 2026-2036
Mexico Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Seed Treatment Market Foresight
Consolidation among large-scale commercial farming cooperatives in Mexico's northern and central states is recalibrating procurement patterns for treated seed. Syngenta AG leverages its integrated seed-and-crop-protection platform to dominate distribution through dedicated agronomic service networks. Bayer CropScience AG anchors its position through deep R&D investment in novel fungicide seed coatings tailored to tropical disease pressure. BASF SE competes by extending its biological inoculant portfolio into Mexico's expanding organic transition zones.
Seed treatment encompasses the application of chemical or biological agents to seeds prior to planting to protect against soil-borne pathogens, early-season insects, and abiotic stress during germination, with formulations typically containing active ingredients at concentrations between 0.1% and 20% by seed weight depending on target pest spectrum and crop value. The process employs film-coating, pelleting, or slurry techniques to ensure uniform coverage without impairing seed flowability or germination rates. Insecticides remain the largest product category by volume due to persistent pressure from soil-dwelling pests in Mexico's tropical lowlands, while microbial treatments represent the fastest-expanding segment as organic certification requirements tighten across export-oriented vegetable operations. Coating dominates application methods for field crops, though seed pelleting commands premium pricing in high-value vegetable segments where precision planting demands uniform seed geometry.
CIBIOGEM, Mexico's intersecretarial biosafety commission, shapes market access through stringent evaluation of genetically modified seed traits that often accompany stacked treatment packages. COFEPRIS and SADER enforce residue limits and phytosanitary standards that determine which active ingredients gain registration for domestic use. SENASICA's import protocols for treated seed further filter competitive entry by foreign suppliers. Stakeholders must monitor pending revisions to Mexico's biosafety framework and anticipate how domestic substitution mandates for glyphosate could redirect formulation strategies across the sector.
Market Dynamics
Climate volatility across Mexico's agricultural heartland is forcing commercial growers to treat seed as a risk-mitigation instrument rather than a commodity input, compressing decision cycles and elevating technical service expectations from suppliers.
Growth Catalysts
- SADER Phytosanitary Mandates:Tightened import protocols for untreated seed are redirecting procurement budgets toward domestic treatment facilities and registered coating formulations.
- Bajío Vegetable Export Surge:Organic certification requirements from US and Canadian buyers are accelerating biological inoculant adoption among tomato and pepper growers in Guanajuato and Querétaro.
- Film-Coating Equipment Diffusion:Mid-scale cooperatives in Sinaloa are acquiring continuous-flow treaters that were previously accessible only to multinational operations, democratizing precision application.
Market Restraints
- Active Ingredient Import Dependency:Mexico lacks domestic synthesis capacity for neonicotinoid and strobilurin chemistries, exposing formulators to peso-dollar volatility and maritime logistics bottlenecks.
- CIBIOGEM Trait Evaluation Backlogs:Genetically modified seed packages incorporating stacked treatments face 18-24 month approval timelines, freezing commercialization pipelines for integrated offerings.
- Soil Microbiome Substitution Threat:Indigenous microbial inoculant producers in Michoacán are marketing direct-to-soil alternatives that bypass seed treatment entirely for certain legume crops.
Strategic Opportunities
- Yucatán Peninsula Underpenetration:Henequen and citrus operations across Campeche and Yucatán states remain underserved by technical distribution networks, creating first-mover terrain for biological treatment specialists.
- COFEPRIS Biopesticide Fast-Track:Expedited registration pathways for microbial and botanical actives are compressing time-to-market for domestic innovators targeting export vegetable zones.
- Drone-Applied Seed Coating Convergence:Integration of UAV-based micro-dosing with precision planting equipment is opening on-farm treatment services for late-season crop rotations in Chihuahua.
Industry Challenges
- Formulation Chemist Scarcity:Mexican universities produce agronomists at scale but few specialists in polymer science and active ingredient compatibility, forcing treaters to import technical talent.
- Equipment Amortization Pressure:Continuous-flow treaters require 8,000+ ton annual throughput to justify capital deployment, excluding smaller Jalisco vegetable cooperatives from in-house coating economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Seed Treatment Market |
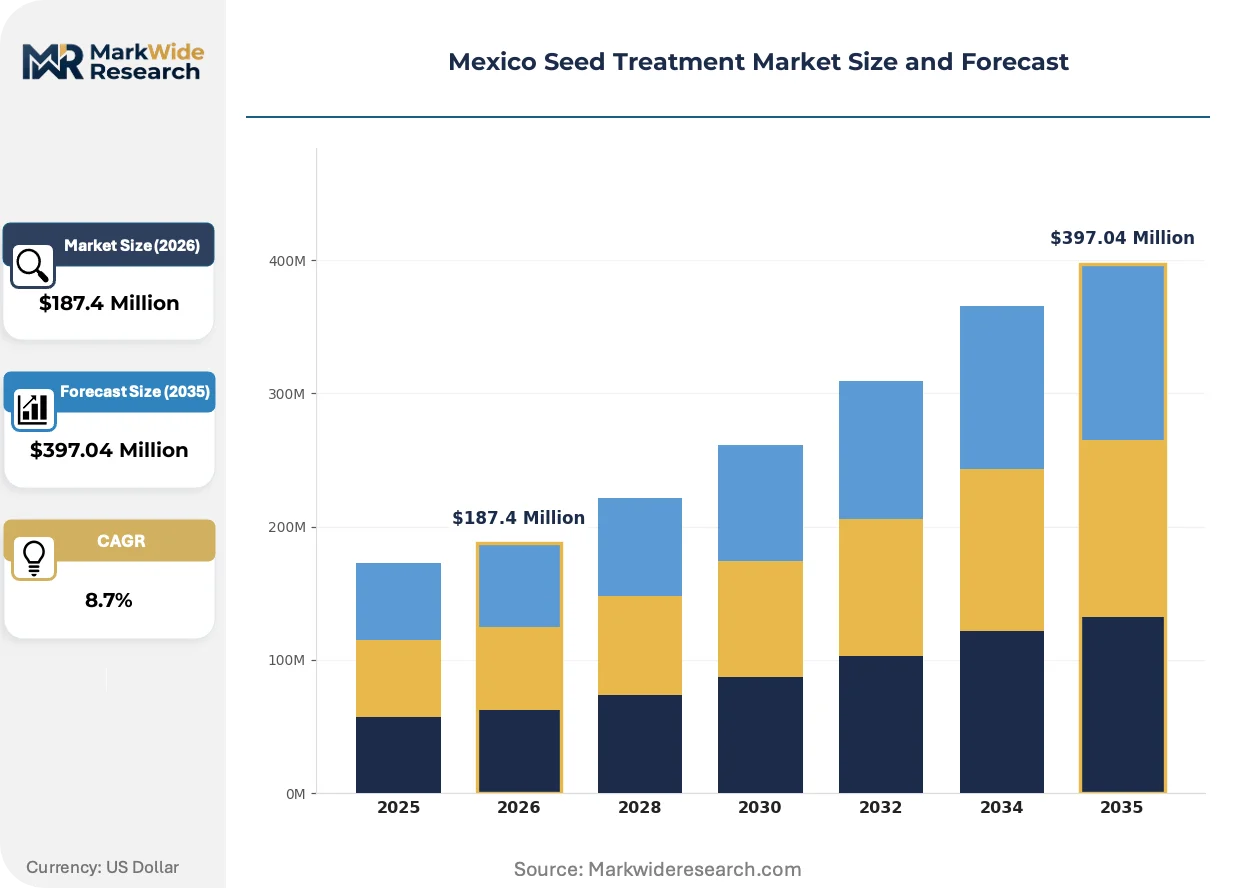
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Microbial Treatments Application Method: Drenching, Coating, Spraying, Seed Pelleting Crops: Cereals, Oilseeds, Pulses, Vegetables Distribution Channel: Online Retail, Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Syngenta AG, Bayer CropScience AG, BASF SE, Corteva Agriscience, FMC Corporation, UPL Limited, Sumitomo Chemical Co., Ltd., Croda International Plc, Adama Agricultural Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Seed Treatment Market Shifts & Advancements
Biological seed treatment technologies are crossing performance thresholds that position them as functional replacements for chemical prophylactics in Mexico's highest-value export crops.
Micro-encapsulation of Trichoderma and Bacillus strains is modularizing biological treatment from a standalone product category into a configurable component within integrated pest management programs. Guanajuato tomato exporters are specifying encapsulated inoculants in procurement contracts that previously demanded chemical fungicide coatings. This modularity is compressing supplier margins on standalone biologicals while expanding addressable market for platform providers who can bundle microbial and chemistries under single technical service agreements.
SENASICA's 2023 revision to import protocols for treated seed is mandating third-party laboratory verification of active ingredient concentrations at port of entry. Foreign suppliers must now pre-register analytical methods with Mexican accreditation bodies before shipment, adding 6-8 weeks to supply chain lead times. Vegetable seed importers in Baja California are responding by shifting procurement toward domestic treaters with SENASICA-certified laboratory partnerships, restructuring competitive access patterns.
Commercial maize cooperatives in Sinaloa are consolidating purchasing through centralized procurement offices that negotiate treatment specifications directly with formulators, bypassing traditional distributor intermediaries. These cooperatives are unbundling agronomic advisory from product supply, selecting treaters on coating precision metrics and residue compliance rather than bundled service relationships. The disintermediation is most advanced among irrigation district associations with 10,000+ hectare collective footprints, where volume concentration creates negotiating leverage unavailable to individual growers.
Mexico Seed Treatment Market Segmentation
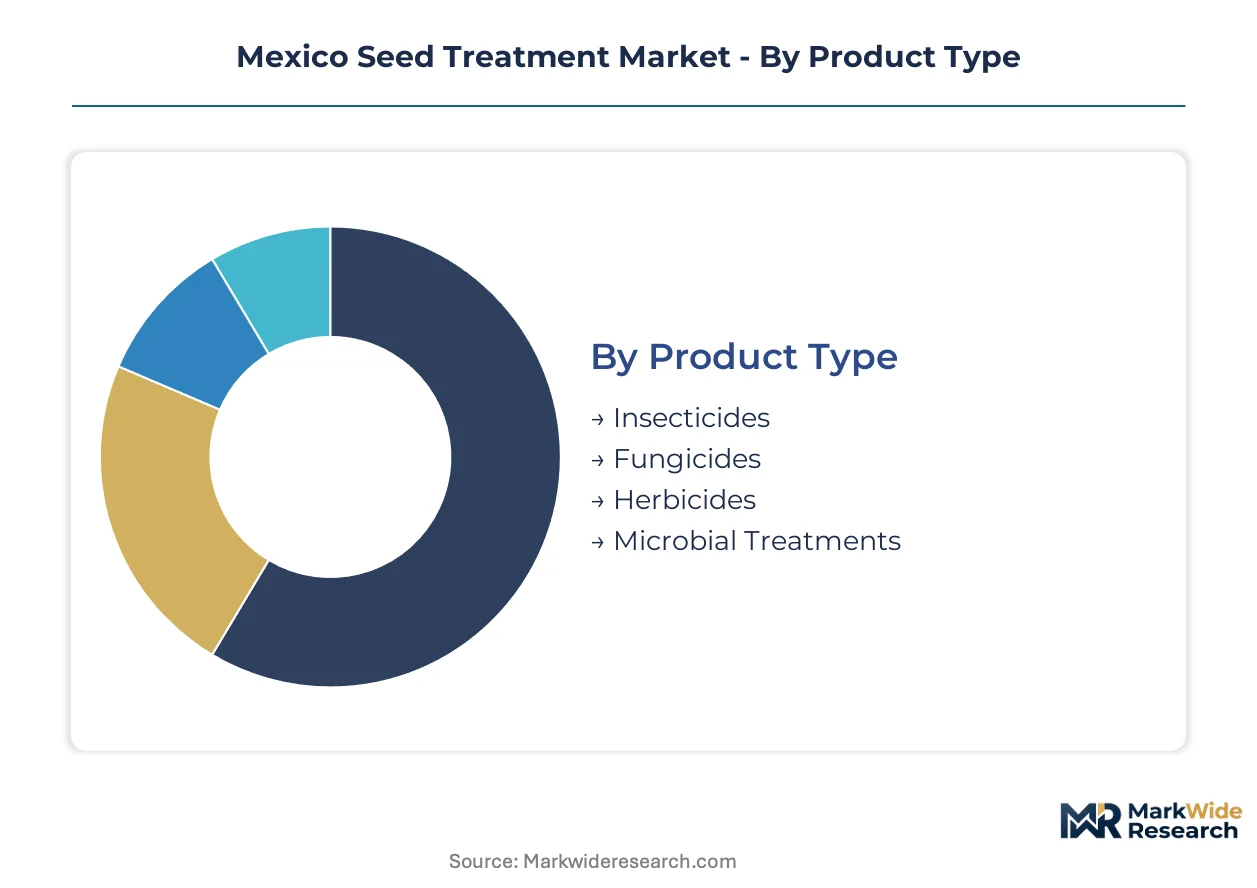
Segmentation in Mexico's seed treatment market reveals how regulatory pathways and crop-specific requirements fragment procurement strategies across distinct technical and commercial dimensions. Each category carries differentiated compliance burdens that reshape supplier access and farmer selection criteria.
Product Type:
COFEPRIS registration intensity varies sharply across this category, with synthetic chemistries facing residue limit scrutiny while microbial treatments navigate expedited biopesticide pathways.
- Insecticides:Neonicotinoid and pyrethroid formulations dominate commercial maize procurement in Sinaloa and Jalisco, where soil-dwelling pest pressure demands protective seed coatings at planting. SADER import protocols for active ingredient concentrates create supply chain exposure to peso-dollar volatility for domestic formulators lacking synthesis capacity.
- Microbial Treatments:Encapsulated Trichoderma and Bacillus strains are penetrating Guanajuato tomato export operations as US and Canadian organic certification requirements tighten. COFEPRIS fast-track registration for biological actives compresses commercialization timelines versus synthetic alternatives.
- Fungicides:Strobilurin and triazole chemistries anchor disease management in tropical lowland cereals.
- Herbicides:Pre-emergent safeners protect germinating seedlings in glyphosate-tolerant maize systems.
Insecticides sit at the top of the volume ranking, with microbial treatments climbing the fastest.
Application Method:
Capital deployment thresholds and precision requirements stratify adoption across cooperative scale tiers, with equipment economics filtering market access.
- Coating:Film-coating dominates field crop applications through continuous-flow treaters that demand 8,000+ ton annual throughput to justify capital deployment. Sinaloa irrigation district associations are consolidating procurement through centralized coating facilities that bypass traditional distributor networks.
- Seed Pelleting:Precision geometry requirements command premium pricing in Bajío vegetable segments where uniform seed sizing enables mechanical planting accuracy. Guanajuato pepper and tomato growers specify pelleted seed in export-oriented procurement contracts.
- Drenching:Liquid application persists in smallholder legume systems with limited equipment access.
- Spraying:On-farm treatment services are emerging for late-season crop rotations in Chihuahua through UAV-micro-dosing integration.
Coating captures the dominant share of treated volume, while seed pelleting generates the highest margin per treated ton.
Crops:
Export orientation and domestic consumption patterns create divergent treatment intensity profiles across agricultural sub-sectors.
- Vegetables:Tomato and pepper operations in Guanajuato and Querétaro are specifying biological inoculants under US and Canadian buyer organic certification requirements. CIBIOGEM biosafety protocols for stacked trait packages redirect investment toward advanced chemical and biological coatings in export belts.
- Cereals:Commercial maize growers in Sinaloa and Jalisco are expanding treated-seed procurement as climate volatility intensifies germination risk. SENASICA import protocols for treated seed are restructuring competitive access patterns toward domestic treaters with certified laboratory partnerships.
- Oilseeds:Soybean and sunflower treatment concentrates in northern irrigation districts.
- Pulses:Direct-to-soil microbial alternatives from Michoacán producers threaten seed treatment substitution for certain legume crops.
Cereals command the largest treated acreage base, with vegetables expanding most quickly on biological coating penetration.
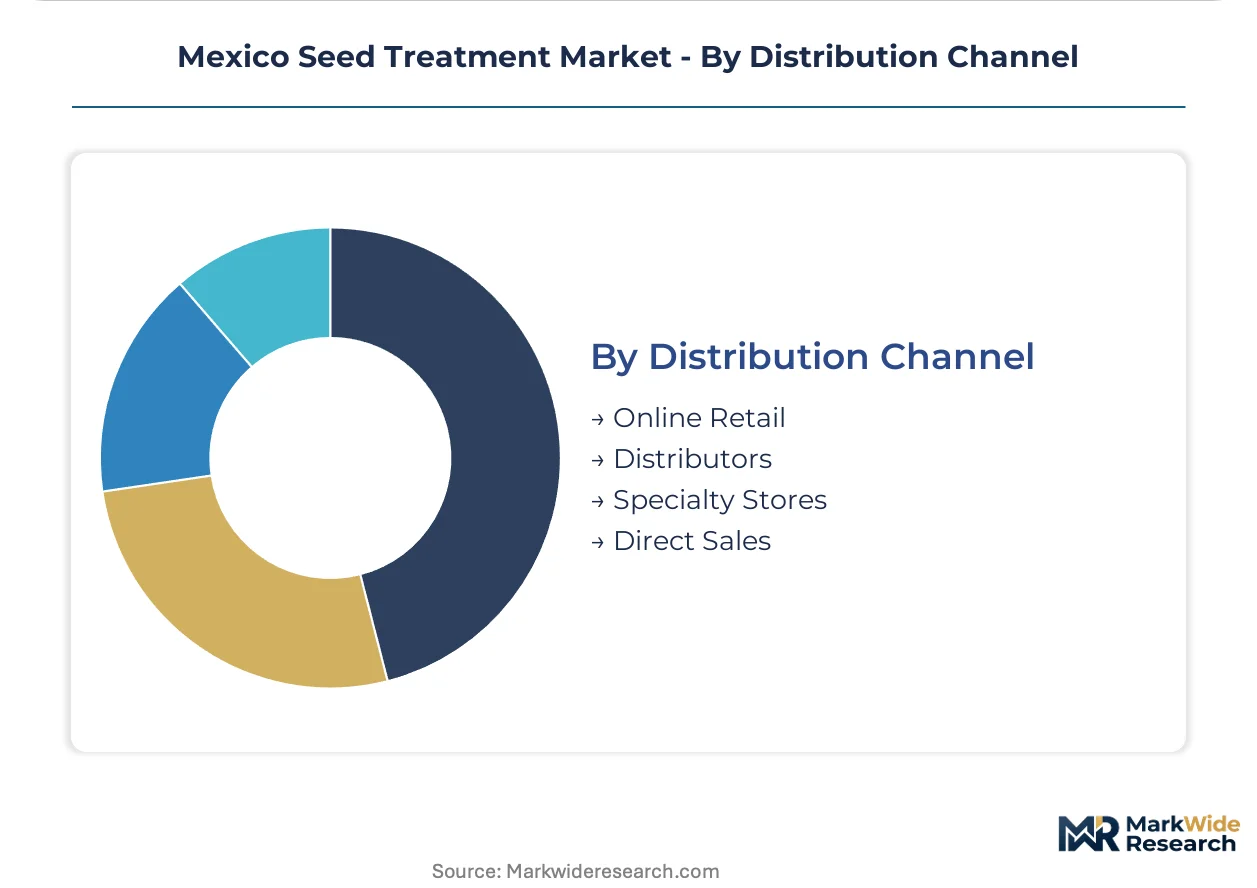
Distribution Channel:
Channel selection reflects cooperative scale consolidation and technical service unbundling trends across Mexico's agricultural heartland.
- Distributors:Traditional agronomic service networks face disintermediation as large-scale cooperatives negotiate treatment specifications directly with formulators. Technical advisory is unbundling from product supply, with selection criteria shifting toward coating precision metrics and residue compliance.
- Direct Sales:Centralized procurement offices in 10,000+ hectare irrigation district associations leverage volume concentration for negotiating power unavailable to individual growers. Sinaloa maize cooperatives are pioneering this model with dedicated agronomic service requirements.
- Specialty Stores:Mid-scale Jalisco vegetable cooperatives access treatment through regional input retailers.
- Online Retail:Digital procurement channels remain nascent for treated seed given SENASICA certification and phytosanitary documentation requirements.
Distributors retain the broadest geographic coverage, with direct sales gaining share fastest among consolidated cooperative structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical agronomists concentrate in Sinaloa's irrigation districts and Guanajuato's vegetable belts, anchoring demand for precision seed treatment services across Mexico's agricultural heartland.
Sinaloa
Commercial maize cooperatives in Sinaloa's Culiacán and Navolato irrigation districts are expanding treated-seed procurement as climate volatility intensifies germination risk. SADER phytosanitary mandates for imported seed are redirecting procurement toward domestic treatment facilities with certified laboratory partnerships. Large-scale irrigation district associations with 10,000+ hectare footprints are consolidating purchasing through centralized procurement offices that negotiate directly with formulators.
Bajío Region
Tomato and pepper operations in Guanajuato and Querétaro are specifying biological inoculants under tightening US and Canadian organic certification requirements. COFEPRIS fast-track registration pathways for microbial actives are compressing commercialization timelines versus synthetic alternatives. Irapuato-based exporters are unbundling agronomic advisory from product supply, selecting treaters on coating precision metrics rather than bundled service relationships.
Jalisco
Mid-scale vegetable cooperatives in Jalisco's Los Altos region access treatment through regional input retailers, though equipment amortization pressure excludes smaller operations from in-house coating economics. CIBIOGEM biosafety protocols for stacked trait packages are redirecting farmer investment toward advanced chemical and biological coatings. Tepatitlán pepper growers are pioneering procurement specifications that demand residue compliance verification.
Yucatán Peninsula
Henequen and citrus operations across Campeche and Yucatán states remain underserved by technical distribution networks, creating first-mover terrain for biological treatment specialists. SENASICA import protocols for treated seed filter competitive entry by requiring third-party laboratory verification at port of entry. Mérida-based citrus cooperatives are evaluating on-farm treatment services through UAV-micro-dosing integration for late-season rotations.
Nuevo León
Northern irrigation districts in Nuevo León are concentrating soybean and sunflower treatment demand as commercial growers seek risk-mitigation instruments against abiotic stress. The state's federal biosafety oversight through CIBIOGEM evaluation backlogs affects genetically modified seed package commercialization. Monterrey-based agronomic service networks are acquiring continuous-flow treaters previously accessible only to multinational operations.
Mexico Seed Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's seed treatment market, creating a tiered structure where integrated platforms clash with biological innovators. Multinational agrochemical majors leverage global R&D pipelines and established distribution infrastructure, while regional formulators exploit regulatory agility and domestic laboratory certifications. Three archetypes dominate: integrated seed-and-crop-protection platforms, biological inoculant specialists, and domestic toll-treatment service providers. Competitive dynamics center on M&A activity consolidating cooperative procurement relationships and capacity expansion in SENASICA-certified domestic coating facilities.
Among Switzerland-based integrated platforms, Syngenta AG exemplifies the seed-and-crop-protection convergence archetype, leveraging dedicated agronomic service networks to anchor distribution relationships. Bayer CropScience AG, a German conglomerate, occupies a position emphasizing novel fungicide development for tropical disease pressure. BASF SE, another German diversified chemical group, represents the biological portfolio extension strategy, targeting Mexico's expanding organic transition zones with microbial inoculant offerings. These three conglomerates sit within the premium-tier supplier category, though cooperative disintermediation is compressing their traditional bundled service margins.
| Leading Market Players |
|---|
| Syngenta AG |
| Bayer CropScience AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Sumitomo Chemical Co., Ltd. |
| Croda International Plc |
| Adama Agricultural Solutions |
| Others |
Supply & Pricing Matrix
Centralized procurement specifications from Sinaloa's 10,000+ hectare irrigation district associations are forcing domestic treaters to absorb SENASICA certification costs and laboratory partnerships, compressing margins on standard coating formulations while elevating premiums for precision application services.
Pricing Analysis
Capacity additions in Guanajuato's domestic treatment facilities are reshaping price floors for biological inoculants as COFEPRIS fast-track registrations accelerate competitive entry. Three-tier pricing structure across premium encapsulated microbial coatings, standard chemical film-coatings, and economy bulk insecticide treatments stratifies the market. Pricing pressure stems from cooperative disintermediation unbundling agronomic advisory from product supply. Mid-scale Jalisco vegetable cooperatives exhibit highest price sensitivity due to equipment amortization barriers, while export-oriented Bajío tomato operations prioritize residue compliance over unit cost.
Supply Chain Analysis
Return flows of unused active ingredient concentrates from port-of-entry rejections under SENASICA's third-party verification mandate are creating reverse-logistics burdens for foreign suppliers without Mexican laboratory partnerships. Domestic formulation draws from imported neonicotinoid and strobilurin chemistries sourced from China, India, and Germany, with polymer binders and encapsulation materials resting on German and Swiss specialty chemical supply. Single-source vulnerability concentrates in maritime logistics bottlenecks for active ingredient import. Distribution runs through SENASICA-certified domestic coating facilities that are consolidating procurement relationships with large-scale cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
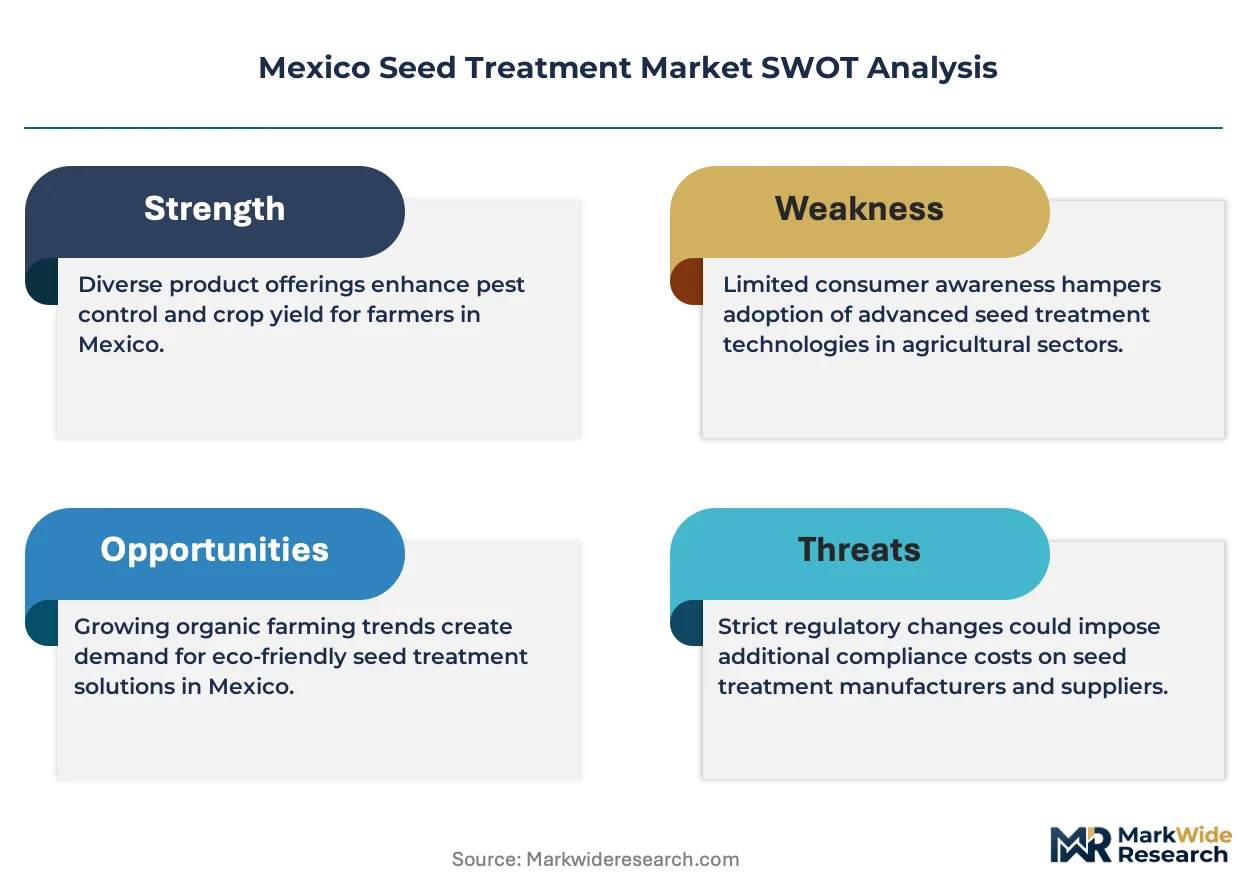
This market reads as a late-cycle quality story where organic certification requirements from US and Canadian buyers are redirecting procurement specifications toward biological coating premiums and precision residue compliance.
For Market Incumbents: Hedge against cooperative disintermediation by deepening technical service relationships with mid-scale Jalisco vegetable operations excluded from in-house coating economics. Invest in SENASICA-certified laboratory partnerships to defend against foreign supplier entry barriers, while accelerating microbial encapsulation R&D to capture organic transition premiums before domestic competitors exploit COFEPRIS fast-track pathways. For New Entrants and Emerging Players: Yucatán Peninsula citrus and henequen operations represent an underserved buyer archetype lacking technical distribution networks and biological treatment expertise. Penetrate this white-space through UAV-micro-dosing service models for late-season crop rotations, leveraging SENASICA import protocol friction to position domestic on-farm treatment capabilities against multinational coating facilities. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic toll-treatment service providers holding SENASICA laboratory certifications and cooperative procurement relationships in Sinaloa and Guanajuato. Long-term viability hinges on biological formulation capabilities aligning with organic export certification trends. Monitor CIBIOGEM biosafety framework revisions for signals on genetically modified seed package commercialization timelines that could redirect treatment investment flows.| Strategic Initiative | Industry Significance |
|---|---|
| SENASICA Laboratory Certification | Port-of-entry verification mandates favor domestic treaters with pre-registered analytical partnerships. |
| Microbial Encapsulation Scale-Up | COFEPRIS fast-track pathways compress biological product commercialization versus synthetic alternatives. |
| Cooperative Procurement Consolidation | 10,000+ hectare irrigation district associations bypass distributor intermediaries for direct formulator negotiations. |
| UAV-Micro-Dosing Service Launch | Drone-applied seed coating convergence opens on-farm treatment for late-season Chihuahua rotations. |
| Backward Integration into Polymer Supply | Encapsulation material sourcing from German and Swiss specialty chemical producers reduces formulation cost volatility. |
Research Methodology
Multiple input streams — primary interviews with seed treatment formulators, cooperative procurement managers, and SENASICA regulatory officials, alongside secondary validation through COFEPRIS registration databases, SADER import protocol filings, and agricultural customs records — were reconciled through bottom-up volume triangulation and top-down value estimation across product type, application method, crop, and distribution channel dimensions.
Cross-referencing historical procurement patterns from Sinaloa and Guanajuato cooperative associations against panel input from technical agronomists and distribution channel partners anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application method, crop category, and regional regulatory cluster variations. CAGRs were derived from trend extrapolation of treatment intensity metrics and biological adoption curves, with climate volatility indices and organic certification penetration serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; microbial treatment volumes carry tighter precision than chemical coating estimates due to COFEPRIS registration transparency. Forecasts reflect assumptions on CIBIOGEM approval timelines, peso-dollar exchange stability for active ingredient imports, and continued US-Canada organic certification demand for Bajío vegetable exports. Practitioners should monitor SENASICA protocol revisions, cooperative procurement consolidation rates, and domestic synthesis capacity investments for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
China Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
India Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Asia-Pacific Seed Coating Materials Market