
 Control Cable Market | 2026-2036
Control Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Control Cable Market Intelligence
A shift from multi-source procurement toward strategic single-sourcing for specialized applications is pivoting buyer behavior. This trend benefits large-scale manufacturers like Prysmian Group, which leverages its extensive product portfolio to secure long-term OEM contracts. Belden Inc. differentiates through its specialization in high-performance shielded cables for data-intensive industrial environments. Meanwhile, Nexans competes by offering customized solutions for complex robotics and automotive manufacturing lines.
Control cables are multi-conductor cables designed for transmitting low-voltage signals that control or monitor electrical equipment and automation systems. They often feature specific insulation materials like PVC or XLPE and may incorporate metallic shielding to prevent electromagnetic interference. Flexible cables command a significant share due to their necessity in robotics and moving machinery within industrial automation. While rigid cables serve static applications, the fastest growth is seen in shielded, multi-core variants essential for noise-free signal transmission.
Product standards are heavily influenced by multiple regulatory frameworks, including Europe's CE marking for safety and the United States' OSHA requirements for workplace electrical safety. In China, compliance with GB standards for flame retardancy and material composition is mandatory for market access. Vendor selection will increasingly depend on a supplier's ability to document full compliance with evolving environmental and material-sourcing regulations across jurisdictions.
Market Dynamics
The convergence of accelerated industrial automation and increasingly stringent regulatory frameworks for materials and safety is the central force shaping the control cable market. This duality pressures manufacturers to innovate on both performance for robotics and compliance with standards like the EU's CSRD.
Growth Catalysts
- Industrial Automation Expansion:The proliferation of robotics and automated systems in manufacturing, particularly in automotive and electronics sectors, necessitates advanced, flexible control cables capable of withstanding constant motion and electromagnetic interference.
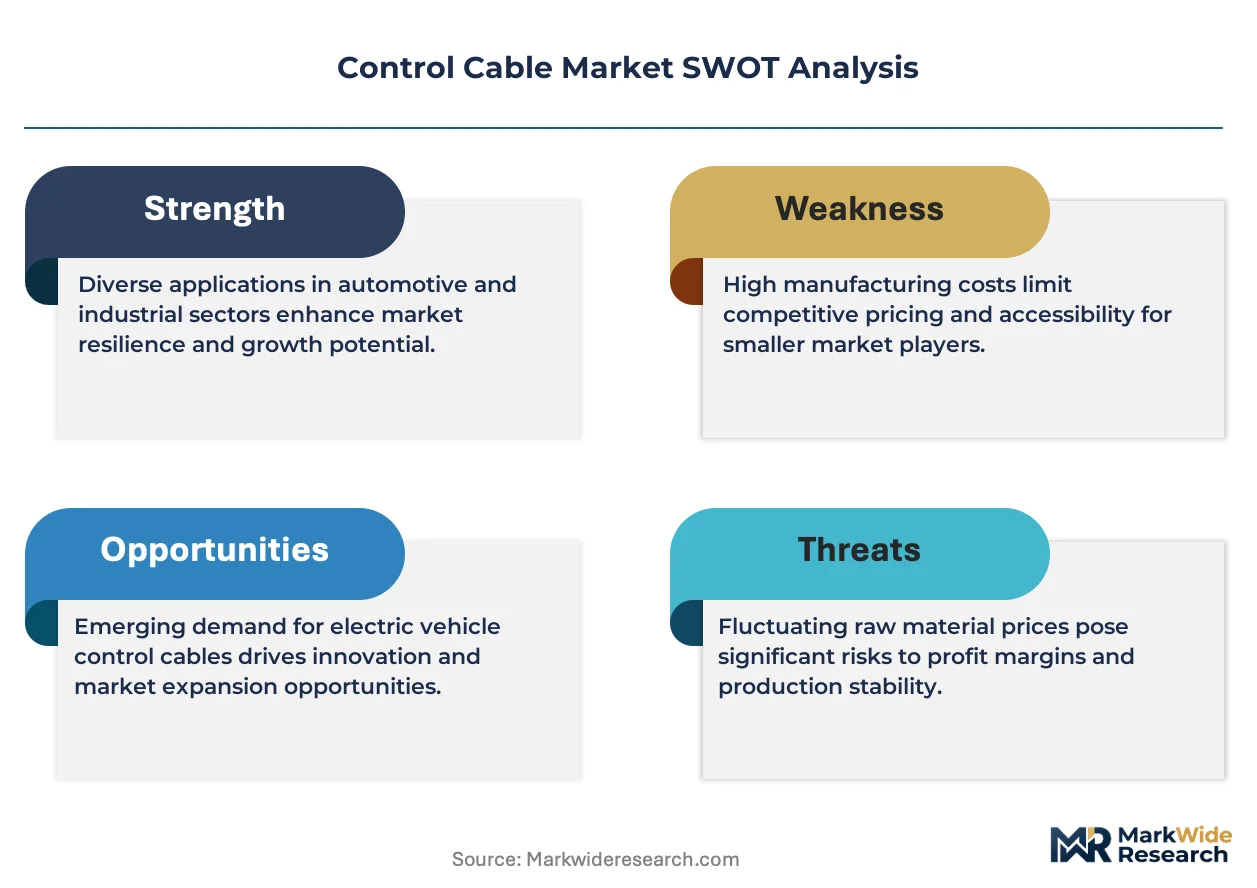
- Grid Modernization Initiatives:Government-led projects to upgrade electrical grids and integrate renewable energy sources are expanding the need for sophisticated control cables in substations and distribution networks, often requiring specific flame-retardant properties.
- Factory Modernization in Asia:Extensive factory upgrade programs in manufacturing hubs like China, driven by national industrial policies, create sustained demand for high-performance control cables to support new machinery and digitalized production lines.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the prices of copper and specialized polymers like PVC and XLPE creates significant cost pressure and margin uncertainty for cable manufacturers, impacting project bidding and long-term pricing stability.
- Threat from Wireless Technologies:The development of reliable industrial wireless communication protocols for monitoring and control functions presents a long-term substitution threat, particularly in less critical or non-moving applications where cabling complexity is a concern.
- Signal Integrity in Dense Environments:Ensuring noise-free signal transmission in environments with high electromagnetic interference, common in modern factories with numerous motors, remains a significant technical hurdle requiring complex and costly shielding designs.
Strategic Opportunities
- Electric Vehicle Infrastructure:The global build-out of EV charging stations and battery manufacturing plants creates a new, high-growth application for specialized control cables that can handle high-power signals and operate in outdoor environments.
- Cables for Sustainable Manufacturing:Developing cables using recycled materials or bio-based polymers that comply with emerging regulations like the EU's CSRD offers a key differentiation opportunity for environmentally conscious buyers.
- Underpenetrated Sectors in India:Targeting India's expanding data center and renewable energy sectors, supported by government initiatives like the PLI scheme, provides a significant growth avenue for suppliers of high-performance and fire-resistant control cables.
Industry Challenges
- Navigating Multi-Jurisdictional Standards:Managing compliance with a fragmented landscape of regional standards, such as Europe's CE marking, China's GB standards, and US OSHA requirements, creates significant administrative overhead and testing costs for vendors.
- Interfacing with Legacy Systems:Integrating new, advanced control cables with older industrial equipment during factory retrofits poses a significant challenge, often requiring custom connectors and signal conditioning to ensure compatibility and system reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Control Cable Market |
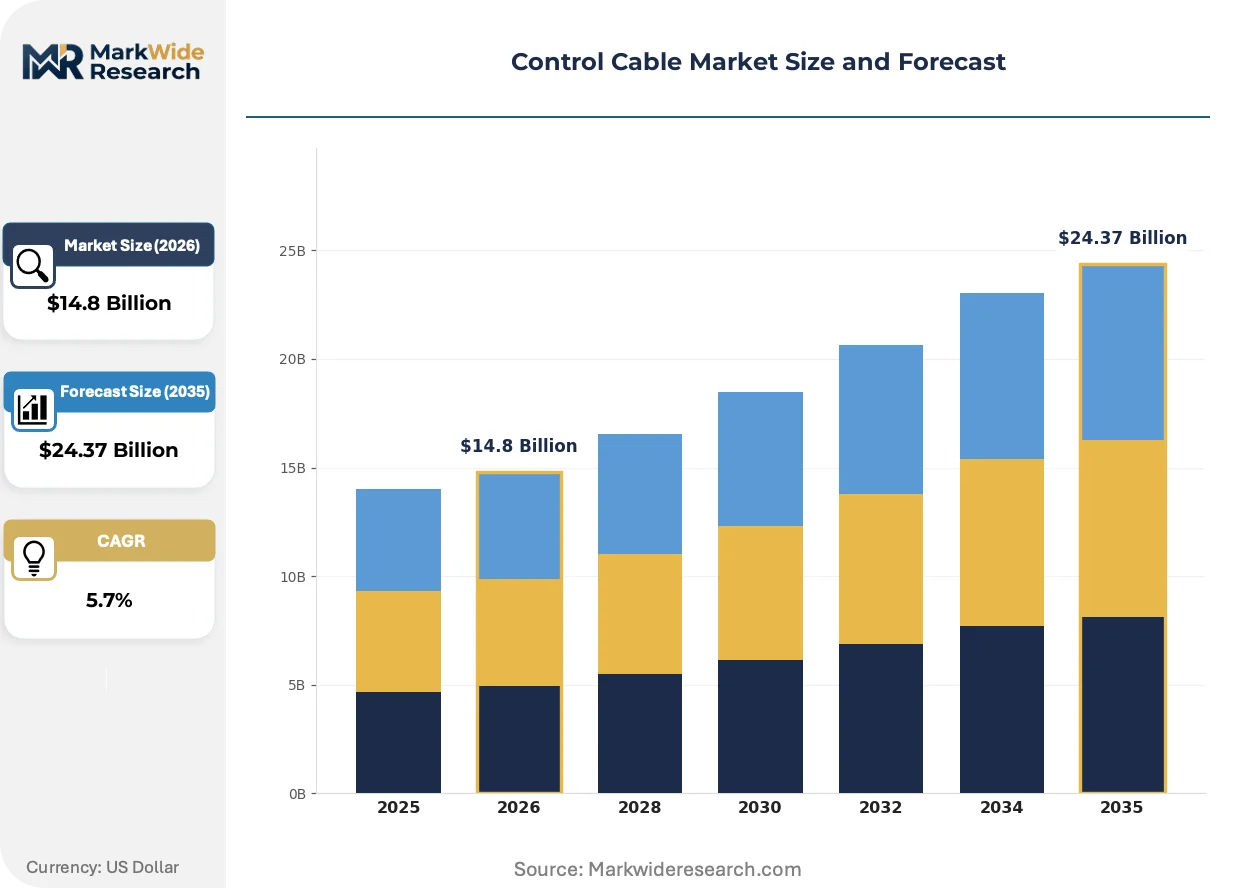
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Cables, Rigid Cables, Multi-core Cables, Shielded Cables Application: Automotive, Industrial Automation, Robotics, HVAC Systems End User: Manufacturers, OEMs, Contractors, Service Providers Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Prysmian Group, Belden Inc., Nexans, Sumitomo Electric Industries, NKT, Southwire Company, KEI Industries, Furukawa Electric, LS Cable & System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Control Cable Market Strategic Shifts & Innovations
Material science advancements and the data demands of Industry 4.0 are actively reshaping the control cable market. Cable design is evolving beyond simple signal transmission to incorporate intelligent features and sustainable materials, driven by new regulatory and operational pressures.
Single Pair Ethernet (SPE) technology utilizes a single twisted pair of wires to transmit both data and power, simplifying cabling infrastructure. Industrial automation integrators and automotive manufacturers are adopting SPE for sensor networks and in-vehicle systems to reduce cable weight and complexity. This technology is rewriting the rules for in-machine connectivity, enabling denser sensor deployment and easier integration with IIoT platforms by collapsing data and power lines into one.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on supply chain environmental impacts, including materials sourcing and product lifecycle. This regulation is forcing cable manufacturers to document the carbon footprint and recyclability of their products, from raw copper to insulation materials like PVC. Shielded and flexible cable segments used in European factories are most affected, with OEMs now prioritizing suppliers who can provide transparent sustainability data.
A move toward strategic single-sourcing for specialized cable applications is becoming more common among large original equipment manufacturers (OEMs). This trend disrupts traditional multi-vendor procurement strategies, favoring large-scale manufacturers who can offer a complete portfolio of control, data, and power cables. This purchasing behavior is most visible in Germany's automotive and machinery sectors, where OEMs seek to streamline supply chains and ensure consistent performance across their global production lines.
Control Cable Market Segmentation
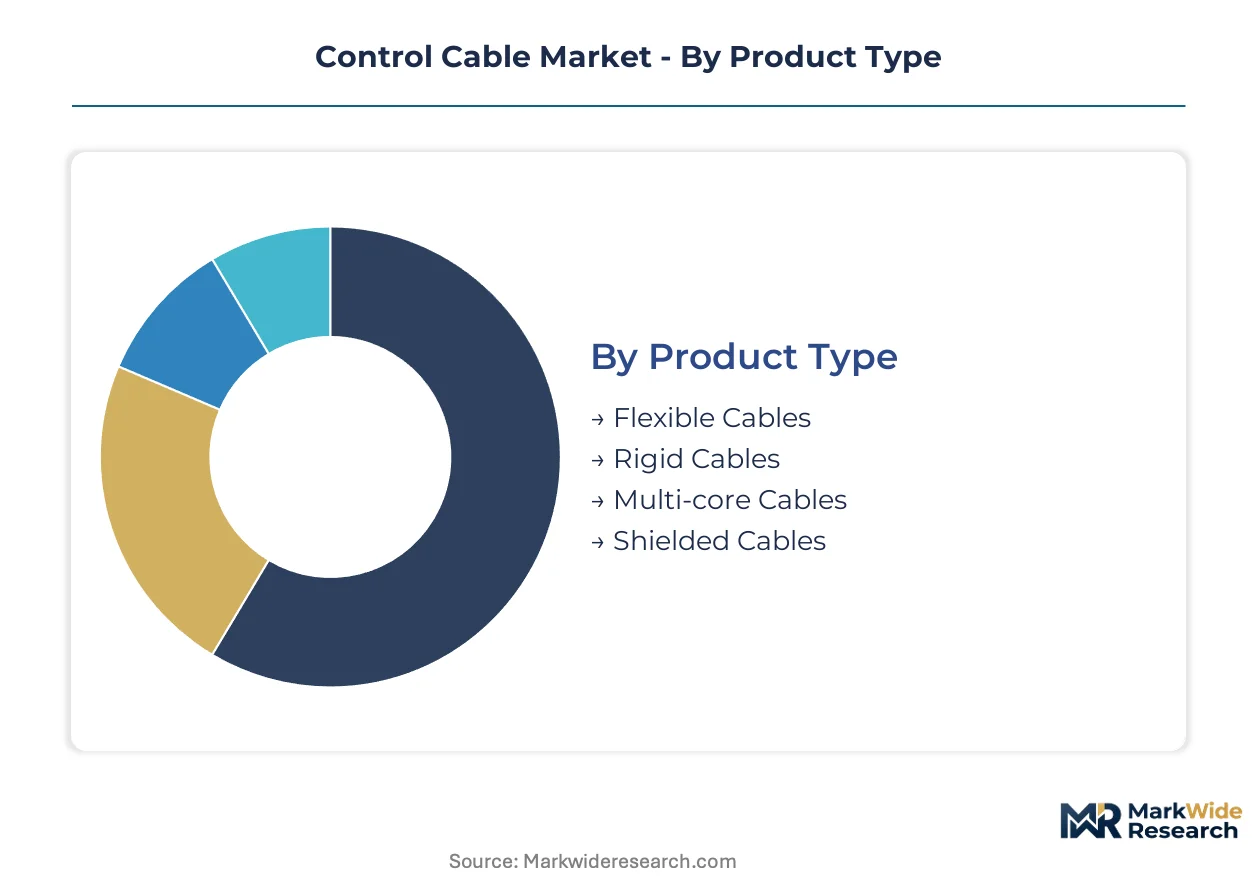
The control cable market's structure reflects the diverse technical requirements and application specificities across industrial sectors. Understanding these segments helps manufacturers tailor product development and market entry strategies, addressing distinct demand patterns from various end-users.
Product Type:
Supply concentration in control cable manufacturing favors producers capable of delivering a diverse product type portfolio.
- Flexible Cables:These multi-conductor cables feature specialized insulation materials like PVC or XLPE, designed to withstand continuous motion without degradation. Demand for flexible cables concentrates heavily in robotics and automated production lines within Germany's automotive sector, driven by constant movement requirements.
- Shielded Cables:Incorporating metallic shielding, these cables prevent electromagnetic interference, ensuring signal integrity in noisy industrial environments. OEMs in China's electronics manufacturing hubs prioritize shielded variants for data-intensive applications, crucial for maintaining performance in complex machinery.
- Rigid Cables:Primarily used in static installations, these cables provide stable signal transmission for fixed electrical equipment and infrastructure.
- Multi-core Cables:Containing multiple insulated conductors within a single jacket, these cables simplify wiring in complex control systems across various industrial settings.
Rigid cables absorb the bulk of installed capacity; flexible cables are expanding most quickly.
Application:
Demand for control cables differentiates significantly across various industrial applications, each presenting unique performance challenges.
- Industrial Automation:This segment encompasses cables for factory automation, process control, and material handling systems, requiring robust, often flexible, and shielded designs. The expansion of Industry 4.0 initiatives in European factories drives demand for these high-performance control cables.
- Robotics:Specialized control cables for robotic arms and automated guided vehicles (AGVs) demand extreme flexibility, high fatigue resistance, and compact designs. Automotive manufacturing lines in Germany and Japan are primary consumers, necessitating cables that endure millions of bending cycles.
- Automotive:Control cables are integral to vehicle manufacturing, including assembly lines, painting robots, and quality control systems.
- HVAC Systems:These cables manage heating, ventilation, and air conditioning controls in commercial and industrial buildings, often requiring specific fire safety and environmental ratings.
Industrial automation represents the largest demand segment, while robotics applications demonstrate the steepest expansion trajectory.
End User:
Control cable procurement patterns vary significantly among different end-user categories, influencing product specifications and supply chain relationships.
- Manufacturers:Industrial manufacturers, particularly in automotive and electronics, purchase control cables for their production lines and machinery. Large-scale manufacturers in China and Germany drive substantial volume, often seeking customized solutions.
- OEMs:Original Equipment Manufacturers integrate control cables directly into their machinery and systems before sale to end-users. OEMs like those served by Prysmian Group often seek long-term, single-sourcing contracts for consistent cable performance.
- Contractors:Electrical and industrial contractors install control cables during new facility construction or modernization projects.
- Service Providers:Companies offering maintenance, repair, and operational services for industrial equipment regularly procure control cables for replacements and upgrades.
Manufacturers account for the primary purchasing volume, with service providers showing consistent incremental demand.
Distribution Channel:
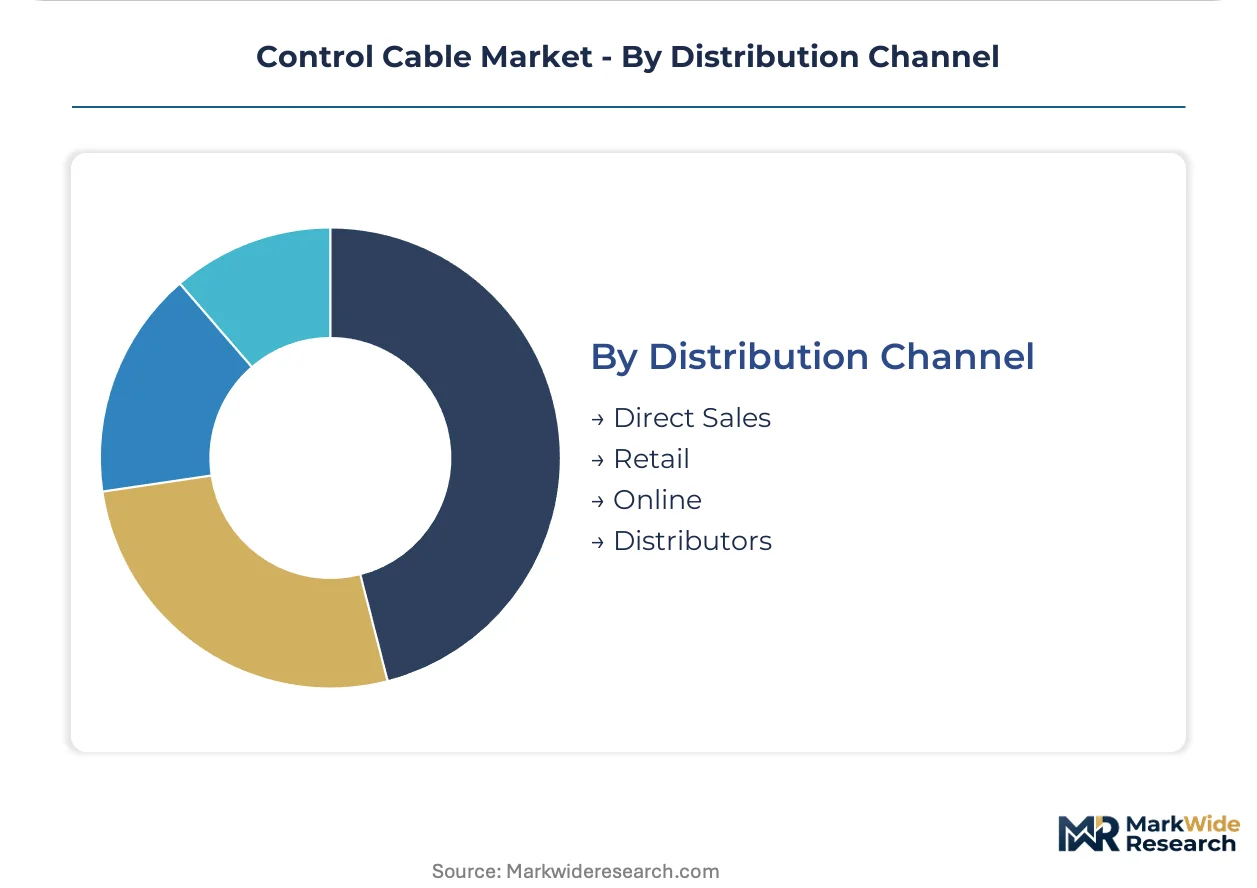
The distribution landscape for control cables reflects diverse market access strategies, from direct engagement to broad retail availability.
- Distributors:Industrial distributors serve as intermediaries, providing a wide range of control cable products to various end-users and smaller contractors. This channel is critical for market penetration in fragmented regions like India, offering local stock and technical support.
- Direct Sales:Large cable manufacturers engage in direct sales to major OEMs and industrial clients, often securing long-term contracts for specialized or high-volume orders. This channel is prominent for customized solutions provided by companies like Nexans.
- Retail:Retail channels cater to smaller businesses and individual purchasers, offering standard control cable types for general applications.
- Online:E-commerce platforms provide a convenient channel for purchasing control cables, particularly for standard products and smaller order quantities, reaching a broader customer base.
Distributors serve as the primary conduit for market reach, while direct sales secure large-scale OEM contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper, a primary raw material, is sourced globally, but its processing and cable manufacturing often concentrate near end-use industries. This geographical alignment ensures efficient supply chains for specialized control cables. The global control cable market finds significant demand in key manufacturing regions, where robust industrial activity drives extensive factory modernization.
China
Extensive factory upgrade programs in China, driven by national industrial policies, create sustained demand for high-performance control cables. Compliance with GB standards for flame retardancy and material composition is mandatory for market access. Electronics manufacturing hubs like Shenzhen prioritize shielded variants for data-intensive applications, crucial for maintaining performance in complex machinery.
Germany
German automotive and machinery sectors drive significant demand for control cables, particularly for complex robotics and automation. The EU's Corporate Sustainability Reporting Directive (CSRD) influences material and performance specifications for cables. Automotive manufacturing lines in Bavaria necessitate cables enduring millions of bending cycles within automated systems.
United States
Industrial automation expansion and grid modernization initiatives drive control cable demand across the United States. OSHA requirements for workplace electrical safety heavily influence product standards and specifications. Data center expansion in Northern Virginia demands high-performance and fire-resistant control cables for critical infrastructure.
India
Expanding data center and renewable energy sectors in India present a significant growth avenue for control cable suppliers. The PLI scheme supports domestic manufacturing, increasing demand for local cable production. Manufacturing zones in Gujarat are seeing sustained investment in new machinery requiring advanced cabling solutions.
Japan
Advanced robotics and automotive manufacturing lines in Japan require specialized control cables with extreme flexibility and fatigue resistance. JIS standards ensure quality and safety for industrial electrical components. Precision machinery production in Aichi Prefecture integrates specialized control cables into automated systems for enhanced efficiency.
Control Cable Market Key Industry Players
Global majors compete with regional champions across product portfolio breadth and technological specialization within the control cable market. The market exhibits a tiered structure, with a few large-scale manufacturers dominating extensive product lines. Mid-sized specialized providers carve out niches in high-performance segments. Competitive dynamics often involve strategic partnerships to access new markets and portfolio diversification to meet evolving industrial demands.
Specialists in high-performance cabling include Belden Inc., which exemplifies differentiation through its focus on shielded cables for data-intensive environments. Large-scale manufacturers like Prysmian Group occupy a position of strength, leveraging their extensive product portfolios to secure long-term OEM contracts. Nexans represents a provider of customized solutions, particularly for complex robotics and automotive manufacturing lines.
| Leading Market Players |
|---|
| Prysmian Group |
| Belden Inc. |
| Nexans |
| Sumitomo Electric Industries |
| NKT |
| Southwire Company |
| KEI Industries |
| Furukawa Electric |
| LS Cable & System |
| Others |
Cost & Logistics Intelligence
Consolidated manufacturing entities, often publicly traded, dictate control cable supply dynamics, influencing both pricing stability and long-term procurement strategies across the market. This structure allows major players to leverage economies of scale in raw material sourcing and production. Pricing power concentrates among suppliers capable of meeting stringent regulatory and performance specifications.
Pricing Analysis
Bundled after-sales support and extended warranties often influence control cable pricing, particularly for specialized industrial applications. The dominant pricing model is contract-based long-term offtake for large OEMs, complemented by transactional per-unit pricing for standard products. Price differentiation stems from certification levels like CE marking and UL, alongside the degree of customization required for specific machinery. Pricing pressure stems from raw material price volatility, especially for copper and specialized polymers like XLPE. Industrial contractors are generally more price-sensitive for standard cables, while automotive OEMs prioritize performance and reliability over cost for critical components.
Supply Chain Analysis
Compliance with CE marking, GB standards, and UL certifications gates entry into key control cable markets, impacting supplier selection and regional distribution. Geographic supply concentration for finished cables is notable in manufacturing powerhouses like Germany, China, and Japan. The supply chain relies on critical raw materials such as copper, PVC, and XLPE, making it vulnerable to commodity price volatility. Single-source vulnerability for highly specialized components poses a structural risk for some OEMs. Downstream distribution runs through a hybrid model of direct sales to major industrial clients and broad market reach via industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The control cable market is increasingly a cost-of-compliance narrative, where the EU's Corporate Sustainability Reporting Directive (CSRD) establishes a significant barrier to entry for non-compliant manufacturers.
For Market Incumbents: Hedge against raw material price volatility through long-term supplier agreements for copper and specialized polymers. Reinforce market position by investing in R&D for advanced shielding technologies and sustainable cable materials. Secure long-term OEM contracts for flexible and shielded cables, leveraging extensive product portfolios to counter the threat from wireless technologies. Expand production capacity in regions with strong industrial automation growth, such as China and India.
For New Entrants and Emerging Players: A significant price-point gap exists between highly specialized, certified control cables and standard offerings, presenting an entry opportunity. Target underpenetrated sectors in India, such as data centers and renewable energy, where government initiatives like the PLI scheme support domestic manufacturing. Focus on developing customized, high-performance cables for niche applications in electric vehicle infrastructure. Leverage agile manufacturing and a strong focus on sustainability to differentiate from established players.
For Investors and Strategic Acquirers: Accelerated adoption of Single Pair Ethernet (SPE) in new factory builds is the leading indicator that the market is ready for further cabling infrastructure simplification. The long-term viability of this market remains strong, driven by ongoing industrial automation and grid modernization. Identify acquisition targets among specialized manufacturers of high-performance, shielded, or flexible cables with strong intellectual property in material science. Watch for increasing consolidation among mid-sized players as regulatory compliance costs rise.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Flexible Cables | Addresses the growing demand from robotics and advanced industrial automation. |
| R&D in Bio-based Polymers | Positions manufacturers to meet evolving EU CSRD requirements for sustainable materials. |
| Strategic Partnerships for SPE Integration | Drives adoption of Single Pair Ethernet technology for simplified in-machine connectivity. |
| Acquisition of Certification Expertise | Strengthens market access by ensuring compliance with diverse global regulatory frameworks like GB standards. |
| Geographic Expansion into India | Capitalizes on government-backed initiatives like the PLI scheme for local manufacturing. |
Research Approach
National industrial policy documents, industry association reports, and regulatory body publications formed the secondary backbone for this control cable market analysis. This was complemented by primary interviews with key stakeholders including OEM procurement managers, industrial automation engineers, cable material scientists, and regulatory compliance officers. Data triangulation across these diverse sources ensured comprehensive coverage and validated market insights through both top-down and bottom-up approaches.
Historical trendline analysis of control cable demand, production capacity, and technological shifts informed the overall forecast framework. The study modeled market growth across the analysis window based on segmentation dimensions including product type, application, end-user, distribution channel, and regional industrial output. Compound Annual Growth Rates (CAGRs) were derived by integrating projected industrial automation investment and raw material price forecasts.
Inputs from major cable manufacturers and industrial automation integrators were available through the study window; gaps in comprehensive raw material price forecasts introduce uncertainty bands. Forecasts reflect assumptions regarding industrial policy stability and technological adoption rates. Geopolitical trade tensions and rapid advancements in wireless communication technologies represent key risk factors that could revise future projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Testing and Certification Market
Cables
High-Temperature Superconducting Cables Market
Cables
Cable Management System Market
Cables
Global Industrial Automation Cable Market
Cables
Europe Cable Accessories Market
Cables
Power Cable Accessories Market
Cables
Global Cable Blowing Equipment Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Cable Accessories Market
Cables
Cable Testers Market
Cables
Latin America Wire and Cable Market
Cables
Cable Carrier Market
Cables
LED Cable Market
Cables
Cable Trunking Market
Cables
Global Cable Gland Market