
 Global Mold Inhibitors Market | 2026-2036
Global Mold Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mold Inhibitors Market Foresight
Subscription-based technical advisory services for formulation optimization are repositioning how mold inhibitor suppliers capture recurring revenue alongside commodity chemical sales. BASF SE leverages its global manufacturing scale to dominate bulk quaternary ammonium compound supply for industrial coatings. Corbion anchors its position through specialized calcium propionate production tailored to bakery preservation requirements. Kemin Industries differentiates via R&D intensity in natural-origin inhibitor blends for clean-label food applications.
Mold inhibitors are biocidal or biostatic chemical additives, typically organic acids or organometallic compounds delivered at active concentrations between 0.1% and 2.0%, designed to disrupt fungal cell membrane integrity and sporulation in moisture-exposed substrates. Their primary commercial purpose is extending product shelf life and structural integrity across packaged goods, building envelopes, and coated surfaces where humidity exceeds critical thresholds. Calcium propionate and potassium sorbate command the largest volume pools within food preservation applications where margin compression is acute and supplier consolidation is accelerating. Zinc pyrithione occupies the highest-value tier in paints and coatings formulations for construction materials, driven by specification requirements in moisture-prone climate zones.
FDA food additive regulations under 21 CFR and EPA antimicrobial pesticide registration under FIFRA jointly determine market access pathways and efficacy claim permissibility for mold inhibitor suppliers operating in the United States. ECHA REACH compliance and the EU Green Deal chemical sustainability criteria are reshaping formulation portfolios among suppliers serving European building materials and apparel manufacturing end users. China's MEE enforcement of GB standards for interior decoration materials limits volatile organic compound emissions while mandating fungal resistance performance in residential and commercial construction applications. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or region-specific product lines deliver superior returns on compliance investment.
Market Dynamics
Regulatory divergence between food safety and environmental protection frameworks is fragmenting formulation strategies, forcing suppliers to maintain parallel product portfolios rather than unified global platforms. This structural tension between efficacy requirements and chemical sustainability mandates now determines capital allocation across R&D and manufacturing footprints.
Growth Catalysts
- GB Standard 18582:China's mandatory fungal resistance specifications for interior wall coatings mandate zinc pyrithione incorporation in residential construction projects across moisture-prone provinces.
- Clean-label bakery preservation:Consumer rejection of synthetic additives in packaged bread drives calcium propionate demand from industrial bakeries seeking recognized GRAS status.
- Quaternary ammonium compound innovation:Advances in cationic surfactant chemistry enable lower-application-rate solutions for marine coatings exposed to tropical humidity cycles.
Market Restraints
- Propionic acid feedstock volatility:Calcium propionate manufacturers face margin compression from petrochemical-derived precursor price swings tied to refinery utilization rates.
- REACH authorization bottlenecks:ECHA's evolving substance evaluation timelines delay market entry for novel organometallic inhibitors targeting European building materials.
- Natural extract substitution:Rosemary and oregano oil extracts gain traction in artisanal food segments, displacing synthetic potassium sorbate in premium positioning channels.
Strategic Opportunities
- Indonesia's expanding cold chain:Rapid supermarket format penetration creates unmet need for modified-atmosphere packaging inhibitors in tropical fruit exports.
- EU Green Deal chemical transition:Biobased organic acid production pathways qualify for carbon border adjustment exemptions, rewarding early capital deployment.
- Technical advisory subscriptions:Formulation optimization services bundled with commodity chemical supply generate recurring revenue streams from mid-sized coating formulators.
Industry Challenges
- FIFRA registration timelines:EPA antimicrobial pesticide approvals average 36-48 months, freezing product launch schedules and consuming technical dossier preparation resources.
- Cross-contamination protocols:Food-grade and industrial-grade production lines require segregated manufacturing assets, comulating capacity planning for multi-segment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mold Inhibitors Market |
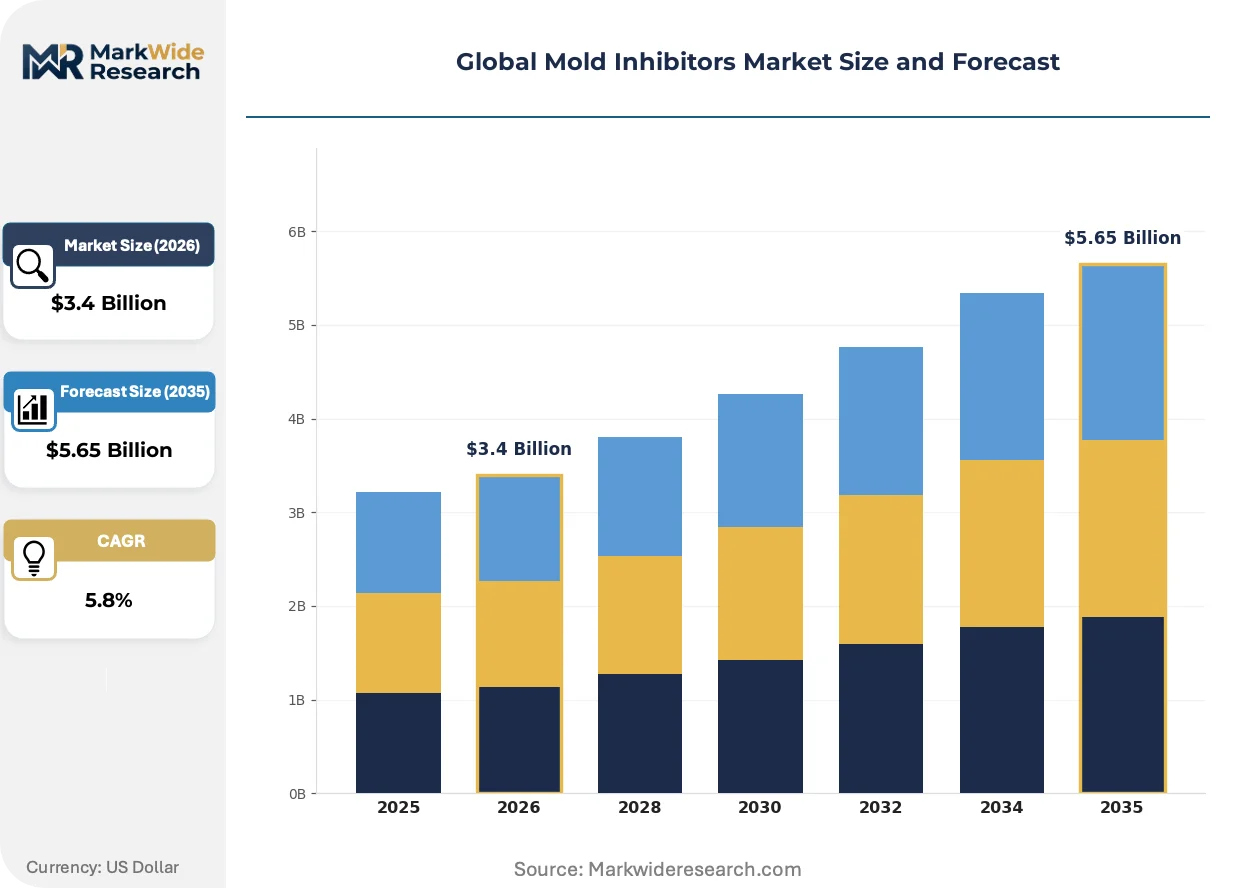
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Sodium Benzoate, Calcium Propionate, Potassium Sorbate, Zinc Pyrithione Form: Liquid, Powder, Aerosol, Emulsion, Gel Application: Food Preservation, Paints & Coatings, Construction Materials, Textiles, Adhesives End User Industry: Food Processing, Building Materials, Apparel Manufacturing, Chemical Manufacturing, Packaging |
| Companies Covered | BASF SE, Corbion, Koninklijke DSM N.V., Kemin Industries Inc., Eastman Chemical Company, Kerry Group plc, Archer Daniels Midland Company, Cargill, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mold Inhibitors Market Shifts & Advancements
Biotechnology-enabled production methods and digital formulation tools are compressing development cycles while regulatory pressure on synthetic chemistries accelerates portfolio rotation toward fermentation-derived alternatives.
Encapsulation technology for controlled-release organic acids is decentralizing preservation efficacy across extended shelf-life applications. Regional dairy processors in Southeast Asia adopt microencapsulated potassium sorbate to maintain inhibitor activity through variable cold chain conditions. This capability shift reduces dependence on centralized industrial bakery customers and opens fragmented artisanal segments previously unreachable by bulk chemical suppliers.
ECHA REACH restriction proposals targeting organotin compounds are forcing coating formulators to eliminate dibutyltin dilaurate catalysts from polyurethane systems. Industrial paint manufacturers in Germany and the Netherlands accelerate zinc pyrithione qualification programs to maintain antifungal performance without restricted substances. The regulatory pressure compresses reformulation windows to 18-24 months for products previously stable over decade-long lifecycle horizons.
Specification-driven procurement now dominates large construction projects, with fungal resistance testing certificates becoming mandatory bid prerequisites. General contractors in Australia's Queensland and Florida's Miami-Dade County reject coating submissions lacking ISO 846 methodology compliance. This behavioral shift transfers technical validation burden upstream from applicators to raw material suppliers, reshaping sales engagement models toward laboratory partnership structures.
Global Mold Inhibitors Market Segmentation
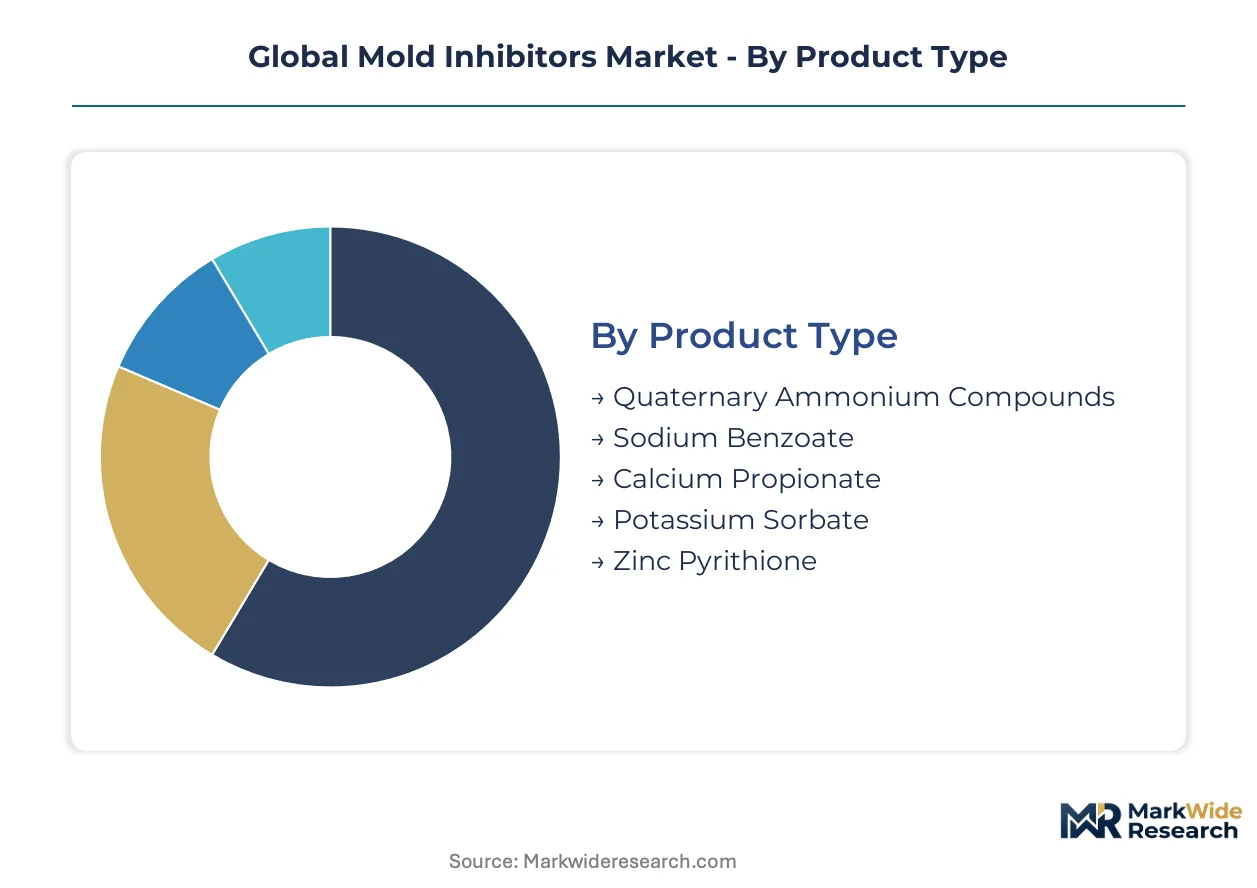
Mold inhibitor segmentation reflects divergent technical requirements across moisture-sensitive substrates. Suppliers calibrate formulation portfolios to balance efficacy thresholds against regulatory constraints in target geographies.
Product Type:
Volume concentration clusters around commodity organic acids while premium value concentrates in organometallic compounds serving specification-driven construction applications.
- Calcium Propionate:Propionic acid salt delivered at 0.1-0.4% active concentration disrupts fungal metabolic enzyme function in bread and baked goods. Industrial bakeries in the United States specify this GRAS-designated additive under tightening FDA mycotoxin prevention guidelines.
- Potassium Sorbate:Sorbic acid potassium salt inhibits mold sporulation through membrane permeability disruption at pH below 6.5. China's dairy processors deploy this compound in yogurt and cheese applications where SAMR food safety audits intensify.
- Quaternary Ammonium Compounds:Cationic surfactant biocides for industrial coating preservation in marine and tropical environments.
- Sodium Benzoate:Benzoic acid salt for acidic food matrices including beverages and condiments.
- Zinc Pyrithione:Organometallic complex commanding premium pricing in moisture-prone construction zones.
Mature deployment sits with calcium propionate in industrial bakery chains. Newer deployment is concentrated in zinc pyrithione for GB Standard 18582 compliance in Chinese residential construction.
Form:
Physical delivery systems segment by substrate compatibility and application equipment requirements across manufacturing and field-use contexts.
- Liquid:Aqueous solutions enable spray application in coating manufacturing and food processing equipment integration. BASF SE and Corbion supply bulk liquid formats to industrial customers seeking automated dosing systems.
- Powder:Dry granular forms facilitate dry-blend incorporation in flour milling and cementitious construction materials. Southeast Asian flour mills specify powder potassium sorbate for tropical storage stability.
- Aerosol:Pressurized spray systems for post-manufacturing surface treatment in specialized industrial maintenance.
- Emulsion:Oil-in-water dispersions for water-based coating compatibility.
- Gel:Thickened formulations for controlled-release applications in high-humidity environments.
Volume leadership belongs to liquid formats in automated food processing. Powder demand is climbing fastest in emerging market construction material manufacturing.
Application:
End-use segmentation tracks moisture exposure severity and regulatory oversight intensity across consumer and industrial domains.
- Food Preservation:Direct additive incorporation in packaged goods to extend shelf life through fungal growth suppression. Clean-label positioning pressures in European retail channels accelerate natural-origin inhibitor development.
- Paints & Coatings:In-can preservation and dry-film antifungal performance for building envelope protection. Queensland and Florida contractors now require ISO 846 test certificates as mandatory bid prerequisites.
- Construction Materials:Admixtures for concrete, mortar, and insulation facing tropical humidity degradation.
- Textiles:Fiber and fabric treatments for apparel and technical textile fungal resistance.
- Adhesives:Water-based glue and sealant preservation in high-moisture assembly applications.
Specification maturity characterizes food preservation with established GRAS pathways. Construction materials represent the steepest expansion trajectory as GB standards and EU Green Deal criteria proliferate.
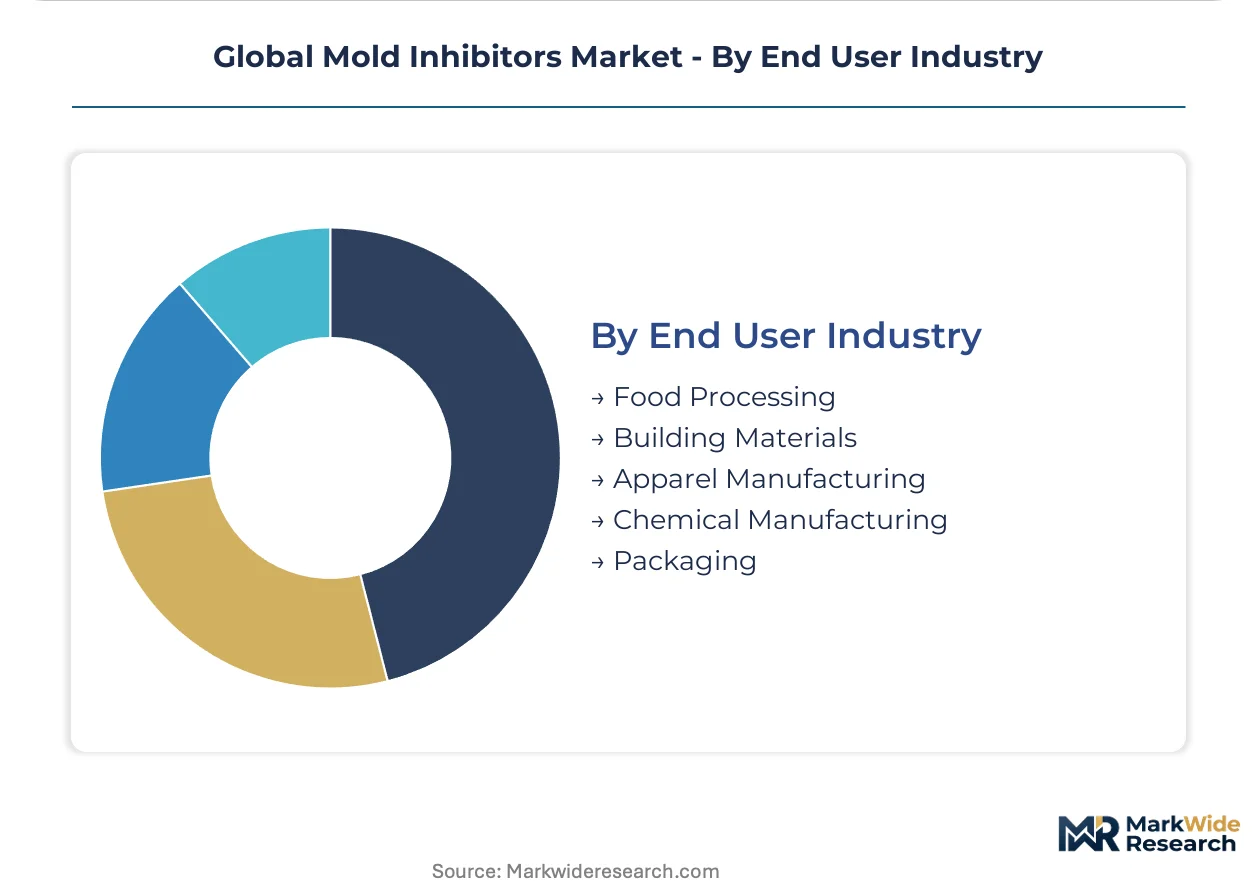
End User Industry:
Customer segmentation distinguishes between formulation-integrated supply and direct manufacturing consumption patterns.
- Food Processing:Industrial bakeries, dairy processors, and beverage manufacturers integrating inhibitors at production scale. United States facilities face intensified FDA inspection frequency under modernized food safety protocols.
- Building Materials:Cement, insulation, and coating manufacturers specifying fungal resistance for code-compliant construction. China's MEE enforcement of interior air quality standards drives zinc pyrithione procurement.
- Apparel Manufacturing:Textile mills and garment finishers requiring antimicrobial fiber treatments.
- Chemical Manufacturing:Coating and adhesive formulators purchasing bulk biocides for product preservation.
- Packaging:Film and container producers incorporating vapor-phase inhibitors for modified-atmosphere applications.
Procurement consolidation dominates food processing with supplier rationalization toward dual-source contracts. Building materials purchasing is fragmenting across regional construction booms in Indonesia and Vietnam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of calcium propionate and potassium sorbate concentrates in Germany and the United States, while consumption gravity shifts toward China's construction sector and Southeast Asia's food processing clusters. Regulatory divergence between FDA food safety protocols and China's GB standards for interior air quality is fragmenting formulation strategies across major demand centers.
United States
Industrial bakeries in the Midwest and Southeast are expanding calcium propionate procurement as FDA inspection frequency intensifies under modernized food safety protocols. EPA FIFRA registration timelines averaging 36-48 months constrain novel antimicrobial pesticide market entry for coating applications. The Chicago-Milwaukee corridor anchors bulk organic acid distribution to national bakery chains.
Germany
ECHA REACH restriction proposals targeting organotin compounds are forcing coating formulators in North Rhine-Westphalia to eliminate restricted catalysts from polyurethane systems. The EU Green Deal chemical sustainability criteria are reshaping formulation portfolios for building materials manufacturers. Bavaria's industrial paint producers accelerate zinc pyrithione qualification programs to maintain antifungal performance.
China
MEE enforcement of GB Standard 18582 mandates fungal resistance specifications for interior wall coatings across moisture-prone provinces. Zinc pyrithione procurement is climbing fastest in the Yangtze River Delta residential construction boom. SAMR food safety audits intensify demand for potassium sorbate among dairy processors in the Pearl River Delta.
Indonesia
Rapid supermarket format penetration is creating unmet need for modified-atmosphere packaging inhibitors in tropical fruit exports from Java and Sumatra. The country's national food safety regulator is tightening mycotoxin prevention guidelines for packaged goods. Surabaya's flour mills specify powder potassium sorbate for tropical storage stability.
Australia
General contractors in Queensland now reject coating submissions lacking ISO 846 methodology compliance as mandatory bid prerequisites. The country's building code adoption of fungal resistance testing certificates transfers technical validation burden upstream to raw material suppliers. Melbourne's coating formulators are restructuring sales engagement models toward laboratory partnership structures.
Global Mold Inhibitors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the mold inhibitor value chain, with bulk chemical manufacturers maintaining integrated propionic acid-to-salt operations while specialized blenders outsource fermentation-derived precursors. The supplier base stratifies into three tiers: multinational chemical conglomerates with global manufacturing footprints, mid-cap specialists focused on single-product verticals, and regional compounders serving fragmented artisanal segments. Dominant competitive moves include backward integration into bio-based feedstock production and geographic expansion through technical advisory subscription models.
Among European-based chemical conglomerates, BASF SE and Koninklijke DSM N.V. occupy positions exemplifying scale-driven supply dominance, while Corbion represents the specialist archetype anchored in organic acid fermentation expertise. These three entities collectively illustrate how supplier positioning diverges between unified global platforms and region-specific formulation portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Corbion |
| Koninklijke DSM N.V. |
| Kemin Industries Inc. |
| Eastman Chemical Company |
| Kerry Group plc |
| Archer Daniels Midland Company |
| Cargill |
| Tate & Lyle PLC |
| Others |
Supply & Pricing Matrix
Biotechnology-enabled fermentation pathways for calcium propionate and potassium sorbate are compressing production economics while redistributing supply concentration away from petrochemical-dependent integrated producers toward specialized fermentation facilities in Germany and the United States. This manufacturing-method transition simultaneously lowers unit costs for organic acid salts and fragments upstream supply control, forcing legacy producers to defend pricing power through certification-tier differentiation rather than feedstock dominance.
Pricing Analysis
Margin tightening in commodity organic acid salts reflects propionic acid feedstock volatility tied to European refinery utilization swings. Contract-based long-term offtake agreements dominate industrial bakery procurement, with price differentiation hinging on FDA GRAS certification tier and volume scale rather than brand premium. Pricing pressure intensifies in synthetic potassium sorbate as rosemary and oregano oil extracts displace share in premium European retail channels. Mid-sized coating formulators exhibit highest price sensitivity due to technical advisory bundling requirements, while specification-driven construction contractors absorb premium zinc pyrithione costs for GB Standard 18582 compliance.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification mold inhibitor batches concentrate in Germany and the Netherlands, where ECHA-registered waste handlers reclaim propionic acid salts for reprocessing into lower-tier construction applications. Primary production concentrates in Germany, the United States, and China, with raw material dependencies spanning petrochemical-derived propionic acid, corn-sugar fermentation feedstocks, and zinc oxide for organometallic complexes. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade calcium propionate certified under FDA food additive regulations. Distribution runs through bulk liquid tanker networks for automated food processing integration and dry bulk rail for powder construction material manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA FIFRA registration timelines averaging 36-48 months erect formidable barrier-to-entry moats, rewarding incumbents with approved antimicrobial pesticide dossiers while freezing capital deployment for unregistered challengers.
For Market Incumbents: Hedge against natural-extract substitution in European food retail by accelerating R&D intensity in microencapsulated organic acid delivery systems that replicate clean-label positioning without sacrificing shelf-life performance. Defend margin position through backward integration into bio-based propionic acid production pathways that qualify for EU Green Deal carbon border adjustment exemptions, locking in cost advantages over petrochemical-dependent rivals.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in zinc pyrithione for Chinese residential construction invites focused entry through technical advisory subscription models bundled with commodity supply. Target Indonesia's expanding cold chain infrastructure for modified-atmosphere packaging inhibitors, where supermarket format penetration outpaces qualified supplier presence. Pursue laboratory partnership structures with Queensland and Florida coating contractors as the primary go-to-market angle, transferring ISO 846 certification burden upstream to secure specification-driven procurement.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational chemical conglomerates seeking fermentation-derived organic acid capabilities, with financial sponsor interest secondary due to capital intensity. Long-term viability favors specialists with captive bio-based feedstock production and ECHA REACH-compliant organometallic portfolios over commodity synthetic producers facing regulatory restriction. Monitor ECHA substance evaluation timelines for novel organometallic inhibitors as the critical inflection signal for European building materials market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock | Corn-sugar fermentation pathways in Germany secure EU Green Deal carbon border exemptions. |
| Technical Advisory Subscription Launch | Formulation optimization services generate recurring revenue from mid-sized coating formulators. |
| GB Standard 18582 Certification Investment | Zinc pyrithione qualification programs unlock Yangtze River Delta residential construction demand. |
| Microencapsulation R&D Scale-Up | Controlled-release potassium sorbate penetrates Southeast Asian artisanal dairy segments. |
| Long-term Supply Agreement with Industrial Bakeries | Dual-source contracts with national bakery chains lock in calcium propionate volume commitments. |
Research Methodology
Document review covered FDA 21 CFR food additive registrations, EPA FIFRA antimicrobial pesticide filings, ECHA REACH substance dossiers, and GB Standard 18582 compliance certificates, complemented by interviews with plant managers at calcium propionate fermentation facilities, procurement leads at industrial bakery chains, technical R&D directors at coating formulators, and regulatory affairs specialists at multinational chemical suppliers. Secondary validation drew from customs trade data, SEC 10-K chemical segment disclosures, and ACC/Cefic specialty chemicals reports. Bottom-up volume modeling triangulated against top-down market sizing from production capacity aggregation.
Historical volume trajectories were cross-referenced against panel input from industry participants to calibrate growth assumptions across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, physical form, application substrate, and end-use industry, with additional granularity on regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and substitution dynamics. Forecast inputs incorporated propionic acid feedstock price elasticity and ECHA authorization timeline probability distributions.
Inputs from FDA registration databases and ECHA dossier submissions were available through the study window; gaps in real-time industrial bakery procurement contract terms introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions on regulatory enforcement consistency and feedstock price normalization. Practitioners should monitor ECHA restriction proposal advancement and China's MEE inspection frequency for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Preservatives Market