
 In Vitro Toxicity Testing Market | 2026-2036
In Vitro Toxicity Testing Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Toxicity Testing Market Intelligence
Buyer concentration among contract research organizations is broadening as mid-tier pharmaceutical developers and specialty biotechs establish direct assay development partnerships. Charles River Laboratories International leverages its integrated discovery-to-safety platform to anchor high-value client relationships across North America and Europe. Eurofins Scientific competes through decentralized laboratory networks that reduce turnaround times for genotoxicity and cytotoxicity panels. Thermo Fisher Scientific controls instrument-reagent bundling strategies that lock in downstream consumable demand from academic and institutional end users.
In vitro toxicity testing comprises cell-based and biochemical assay systems designed to predict adverse biological effects of chemicals, pharmaceuticals, or cosmetic ingredients without intact-animal models. These systems employ human-derived hepatocytes, reconstructed skin epidermis, or organotypic co-cultures with defined endpoint readouts such as ATP depletion, cytokine release, or transcriptomic perturbation to satisfy regulatory safety thresholds. Cytotoxicity assays occupy the largest product segment due to their foundational role in early-phase pharmaceutical screening, while organs-on-chips technology represents the fastest-expanding platform as microfluidic designs enable physiologically relevant tissue-tissue interfaces. High-throughput screening sustains dominant technology share through decades of validated protocol libraries, though 3D cell culture differentiates on margin capture by commanding premium pricing for complex metabolism and genotoxicity studies that flat monolayers cannot replicate.
The FDA and EPA jointly shape United States market access through the ICCVAM validation framework and Tox21 federal partnership, which mandate method qualification before regulatory submission acceptance. The European Medicines Agency enforces REACH and EU Cosmetics Regulation testing bans that prohibit animal-based endpoints for cosmetic ingredients, forcing formulation houses toward validated in vitro alternatives. Stakeholders must monitor divergence between FDA guidance on New Approach Methodologies and EMA qualification opinions, as misaligned acceptance criteria threaten to fragment development investment across Atlantic regulatory zones.
Market Dynamics
Microfluidic organ-on-chip platforms are compressing validation timelines for pharmaceutical safety assessment, forcing contract research organizations to rebuild service architectures around continuous perfusion models rather than static well-plate formats.
Growth Catalysts
- ICCVAM Validation Framework:The US FDA and EPA joint qualification pathway accelerates regulatory acceptance of human-relevant cell-based assays, reducing submission preparation cycles for sponsors.
- EU Cosmetics Testing Ban:REACH and EU Cosmetics Regulation prohibitions on animal endpoints mandate validated in vitro alternatives for formulation safety, channeling R&D investment toward reconstructed tissue models.
- Biotech Cluster Density:Concentrated pharmaceutical development in Boston and San Francisco generates sustained contract research volume for localized assay development partnerships.
Market Restraints
- Primary Human Cell Sourcing:Donor variability and limited batch-to-batch consistency in hepatocyte supplies create qualification overhead that delays study initiation.
- Equipment Capital Intensity:High-content imaging platforms and microfluidic controllers require seven-figure facility investments that exclude mid-tier academic laboratories from advanced assay development.
- Cross-Atlantic Regulatory Divergence:Misaligned acceptance criteria between FDA New Approach Methodologies guidance and EMA qualification opinions fragment development investment and duplicate validation costs.
Strategic Opportunities
- India CDSCO Alignment:Emerging pharmaceutical manufacturing hubs in Hyderabad and Mumbai present untapped demand for localized toxicity screening services as domestic regulatory frameworks mature.
- 3D Bioprinting Convergence:Integration of organ-on-chip microfluidics with bioprinted vascular networks enables multi-organ metabolism studies that command premium positioning in safety pharmacology.
- Cloud-Based Data Architectures:Distributed computational toxicology platforms allow contract research organizations to unbundle analysis from physical laboratory capacity, opening subscription revenue streams.
Industry Challenges
- Microfluidic Engineering Talent Scarcity:The intersection of cell biology and chip fabrication expertise remains critically undersupplied, extending recruitment cycles for platform development teams.
- Multi-Site Validation Coordination:ICCVAM and OECD test guideline requirements for inter-laboratory reproducibility impose complex project management overhead across geographically dispersed facilities.
- Legacy Assay Integration:Established high-throughput screening protocols resist migration to organ-on-chip formats due to sunk investment in compound libraries and automation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Toxicity Testing Market |
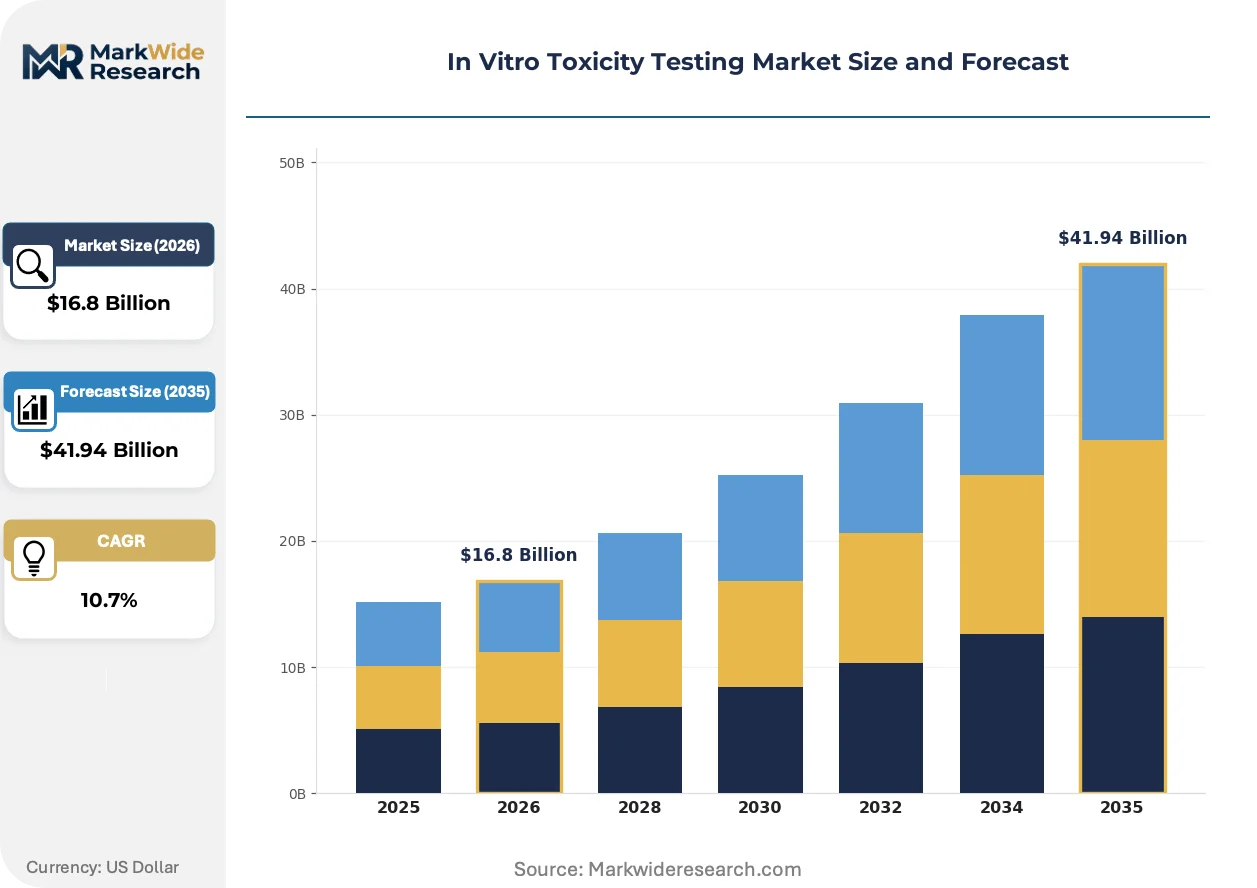
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $41.94 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cytotoxicity Assays, Genotoxicity Assays, Hemocompatibility Tests, Metabolic Assays Technology: High-Throughput Screening, Microarray Technology, 3D Cell Culture, Organs-on-Chips Application: Pharmaceutical Development, Cosmetic Testing, Chemical Safety, Environmental Risk Assessment End User: Biotechnology Companies, Research Institutions, Contract Research Organizations, Academic Laboratories |
| Companies Covered | Charles River Laboratories International, Thermo Fisher Scientific, Eurofins Scientific, Merck KGaA, Agilent Technologies, Bio-Rad Laboratories, SGS, Laboratory Corporation of America Holdings, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Toxicity Testing Market Strategic Shifts & Innovations
Biomimetic tissue interfaces are displacing static monocultures as the reference standard for predictive toxicology, compressing the gap between preclinical signals and clinical outcomes while reconfiguring competitive positioning around physiological fidelity rather than throughput volume.
Organ-on-chip technology is modularizing complex organ-organ interaction studies through standardized microfluidic cartridge formats that interconnect liver, kidney, and intestinal tissue compartments. Mid-tier biotechnology developers are adopting these platforms for lead optimization screening, accelerating migration away from animal models. The technology is modularizing service offerings by allowing contract research organizations to configure custom tissue combinations without rebuilding entire assay architectures.
REACH authorization procedures and EU Cosmetics Regulation enforcement are tightening compliance windows for chemical safety dossiers, compelling formulation houses to front-load in vitro validation investment. Industrial consequences include expanded internal assay development teams and reduced reliance on external animal testing facilities. Cosmetic ingredient suppliers in France and Germany are responding by acquiring dedicated genotoxicity screening capabilities to secure supply chain positions.
Biopharmaceutical procurement departments are consolidating vendor relationships around integrated discovery-to-safety platforms, displacing fragmented point-solution contracting. Large-molecule developers in Massachusetts and California are compressing supplier panels to three-to-five preferred partners with end-to-end capabilities. This concentration is most visible in United States biotechnology clusters where platform loyalty programs and volume commitments now dominate sourcing decisions.
In Vitro Toxicity Testing Market Segmentation
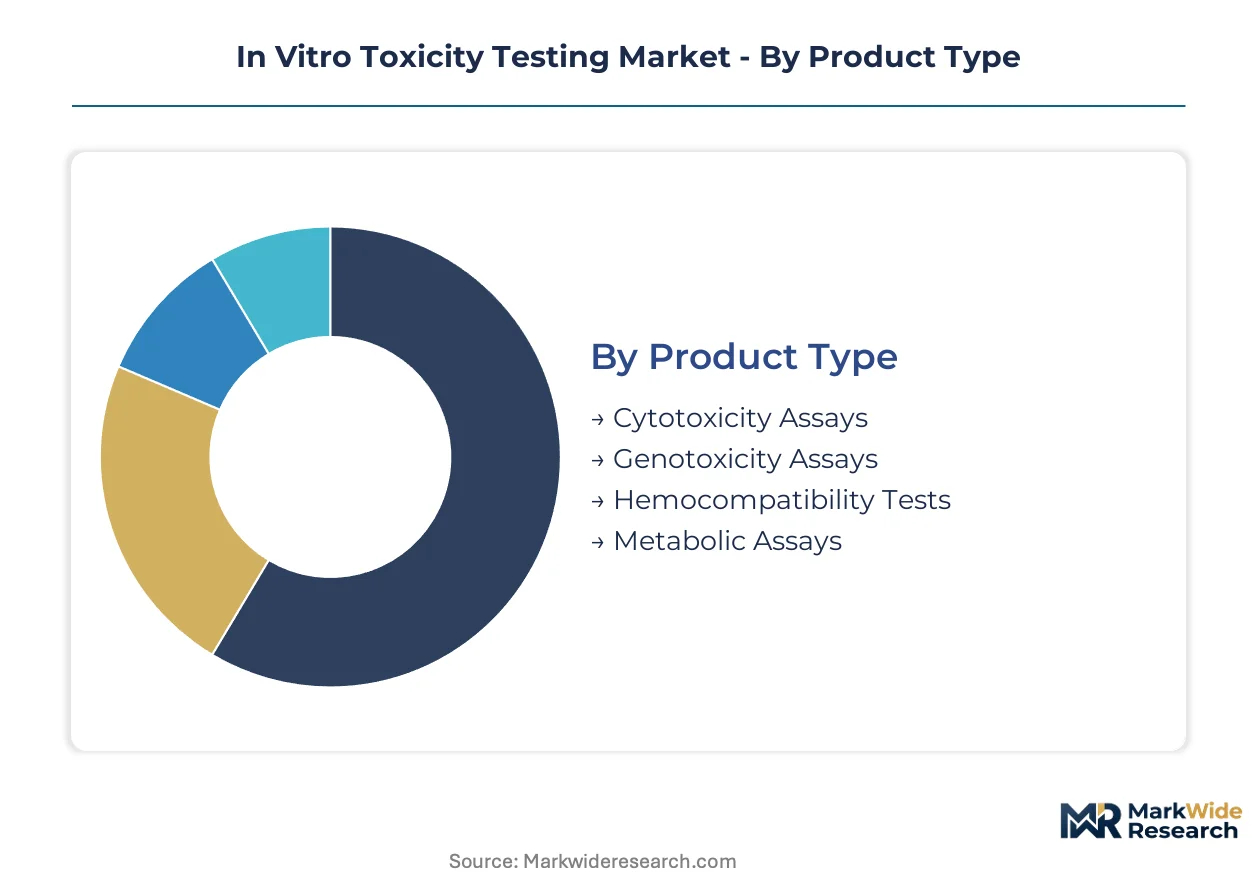
In vitro toxicity testing segments reflect divergent technical requirements across regulatory submission pathways. Product configurations range from standardized off-the-shelf assay kits to custom-developed organotypic platforms demanding months of qualification. Technology selection directly determines capital deployment, regulatory acceptance timelines, and the ability to replace animal reference data.
Product Type:
Customization intensity varies sharply across this category, from commodity biochemical readouts to bespoke reconstructed tissue models requiring donor-specific qualification.
- Cytotoxicity Assays:ATP depletion and membrane integrity readouts using transformed cell lines provide foundational safety screening for pharmaceutical lead optimization. Demand concentrates among contract research organizations in Massachusetts and North Carolina serving mid-tier biotechnology developers with compressed IND timelines. ICCVAM-validated protocols reduce regulatory submission preparation cycles.
- Genotoxicity Assays:Chromosomal aberration and gene mutation detection systems employ bacterial reverse mutation or mammalian cell micronucleus endpoints. European formulation houses in France and Germany drive procurement volume following REACH authorization tightening and EU Cosmetics Regulation enforcement. Batch-to-batch consistency in engineered reporter cell lines remains a sourcing constraint.
- Hemocompatibility Tests:Platelet activation and hemolysis assays using fresh human blood or validated substitutes.
- Metabolic Assays:Hepatocyte-based clearance and metabolite identification panels for drug-drug interaction prediction.
Most installed capacity flows through cytotoxicity assays. Expansion is steepest in genotoxicity assays.
Technology:
Capital intensity and physiological fidelity create distinct cost tiers, separating high-throughput commodity platforms from premium microfluidic systems commanding seven-figure facility investments.
- High-Throughput Screening:Automated liquid handling and multi-well plate readers enable rapid compound library profiling with decades of validated protocol libraries. Biotechnology companies in San Francisco and Boston sustain dominant deployment volume for early-phase pharmaceutical screening. Sunk automation infrastructure resists migration to advanced formats.
- Organs-on-Chips:Microfluidic platforms with continuous perfusion and tissue-tissue interfaces replicate organ-level physiology for safety pharmacology. Academic laboratories at Stanford and MIT anchor adoption, with contract research organizations rebuilding service architectures around cartridge-based liver-kidney interaction models. FDA New Approach Methodologies guidance accelerates regulatory qualification investment.
- Microarray Technology:Transcriptomic and proteomic endpoint detection for mechanistic toxicity pathway analysis.
- 3D Cell Culture:Spheroid and organoid formats capturing metabolic zonation absent in flat monolayers.
High-throughput screening retains the largest installed base. Organs-on-chips are gaining share fastest among safety pharmacology service providers.
Application:
Regulatory mandate strength determines customer willingness to pay, with cosmetic and chemical safety applications facing stricter animal testing prohibitions than pharmaceutical development.
- Pharmaceutical Development:IND-enabling safety packages and lead optimization screening across small-molecule and biologic pipelines. United States biotechnology clusters in Boston and San Francisco generate sustained contract research volume for integrated discovery-to-safety platforms. FDA modernization initiatives on animal testing alternatives redirect method validation investment.
- Chemical Safety:REACH dossier preparation and industrial chemical hazard classification requiring standardized OECD test guideline compliance. European formulation houses front-load in vitro validation investment following ECHA authorization procedure tightening. Cosmetic ingredient suppliers acquire dedicated screening capabilities to secure supply chain positions.
- Cosmetic Testing:EU Cosmetics Regulation-mandated safety assessment for personal care formulations.
- Environmental Risk Assessment:Aquatic toxicity and bioaccumulation screening for agrochemical and industrial discharge permitting.
Pharmaceutical development commands the largest revenue share. Chemical safety applications are expanding most quickly under REACH enforcement pressure.
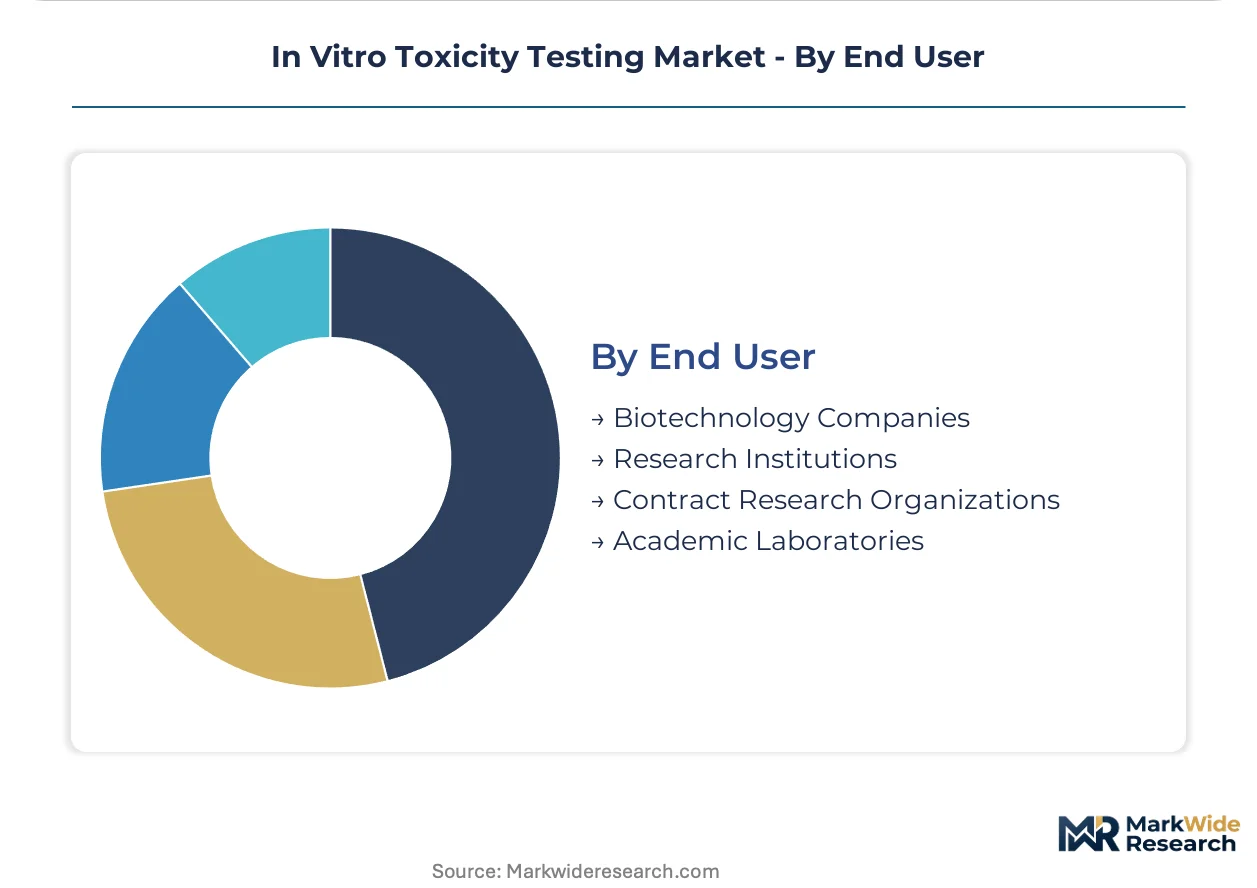
End User:
Procurement sophistication separates institutional buyers with dedicated assay development teams from price-sensitive academic laboratories dependent on grant funding cycles.
- Contract Research Organizations:Integrated discovery-to-safety platforms serving pharmaceutical and biotechnology sponsors with end-to-end service capabilities. Charles River Laboratories and Eurofins Scientific compete through decentralized laboratory networks and platform loyalty programs. Vendor consolidation trends compress supplier panels to three-to-five preferred partners with volume commitment structures.
- Biotechnology Companies:Mid-tier developers establishing direct assay development partnerships for proprietary therapeutic modalities. Massachusetts and California clusters drive localized service demand with compressed timeline requirements. Internal assay development teams expand to reduce reliance on external animal testing facilities.
- Research Institutions:Government and nonprofit laboratories contributing to ICCVAM and Tox21 federal partnership validation studies.
- Academic Laboratories:University-based groups with limited capital access constrained to standardized kit-based formats.
Contract research organizations represent the largest customer segment. Biotechnology companies are expanding procurement fastest as internal capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States contract research volume exceeds German pharmaceutical safety spending by a factor of three, yet both markets exhibit divergent regulatory validation priorities that reshape service provider footprints.
United States
FDA modernization initiatives on animal testing alternatives and Tox21 federal partnership funding accelerate method qualification investment. The ICCVAM validation framework mandates inter-laboratory reproducibility standards that compress submission preparation cycles for sponsors. Boston and San Francisco biotechnology clusters generate sustained demand for integrated discovery-to-safety platforms with compressed IND timelines.
Germany
REACH authorization tightening and EU Cosmetics Regulation enforcement channel formulation houses toward validated in vitro alternatives for industrial chemical safety dossiers. ECHA qualification opinions on New Approach Methodologies create compliance windows that front-load validation investment. Frankfurt and Munich cosmetic ingredient suppliers acquire dedicated genotoxicity screening capabilities to secure supply chain positions against tightening enforcement.
United Kingdom
Post-Brexit divergence from EMA qualification pathways forces parallel validation strategies for sponsors seeking dual FDA and UK Medicines and Healthcare products Regulatory Agency acceptance. London and Cambridge contract research organizations rebuild service architectures around organ-on-chip microfluidic platforms to capture safety pharmacology premium pricing. MHRA guidance on human-relevant cell-based assays accelerates technology migration from static well-plate formats.
India
Domestic pharmaceutical manufacturing expansion in Hyderabad and Mumbai generates untapped demand for localized toxicity screening services as CDSCO regulatory frameworks mature. Central Drugs Standard Control Organization alignment with OECD test guidelines creates qualification pathways for contract research organizations serving export-oriented formulation houses. Bangalore academic laboratories anchor adoption of 3D cell culture formats for mechanistic toxicity pathway analysis.
Japan
PMDA guidance on non-clinical safety evaluation encourages adoption of human-derived hepatocyte assays for drug-drug interaction prediction. Tokyo and Osaka pharmaceutical developers consolidate vendor relationships around integrated platforms with end-to-end capabilities. METI funding for microfluidic organ-on-chip development accelerates academic-commercial partnerships for multi-organ metabolism studies.
In Vitro Toxicity Testing Market Key Industry Players
United States producers anchor the integrated platform tier; European specialists hold position in decentralized laboratory networks and regulatory validation services. The vendor base separates into three concentration layers: multinational conglomerates with instrument-reagent bundling capabilities, mid-tier contract research organizations with geographic density advantages, and boutique assay developers serving proprietary therapeutic modalities. Two strategic archetypes dominate competitive positioning: platform loyalty programs that lock in volume commitments through end-to-end service integration, and technology licensing arrangements that transfer microfluidic chip designs to regional service providers. Consolidation pressure intensifies as procurement departments compress supplier panels to three-to-five preferred partners with multi-year contracts.
Among diversified laboratory service providers, Charles River Laboratories International and Eurofins Scientific exemplify contrasting geographic strategies. Charles River occupies a position within the integrated discovery-to-safety archetype, anchoring high-value client relationships through platform breadth. Eurofins sits within the decentralized network specialization, competing on turnaround time compression for standardized assay panels. Thermo Fisher Scientific represents the instrument-reagent bundling archetype, locking in downstream consumable demand through hardware placement strategies. Merck KGaA and Agilent Technologies occupy positions in the analytical instrumentation tier, serving academic and institutional end users with capital-intensive platform sales.
| Leading Market Players |
|---|
| Charles River Laboratories International |
| Thermo Fisher Scientific |
| Eurofins Scientific |
| Merck KGaA |
| Agilent Technologies |
| Bio-Rad Laboratories |
| SGS |
| Laboratory Corporation of America Holdings |
| Catalent |
| Others |
Cost & Logistics Intelligence
EU Cosmetics Regulation enforcement gates both qualified supply and premium-tier pricing access, as REACH authorization procedures compel formulation houses to source only ICCVAM-validated assay components while absorbing qualification overhead into service premiums. Contract research organizations with certified hepatocyte supplies command pricing power over mid-tier competitors dependent on variable donor batches.
Pricing Analysis
Capacity additions in India are reshaping price floors for standardized cytotoxicity panels, forcing established North American providers into three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ICCVAM validation status and geographic proximity to Boston or San Francisco biotechnology clusters. Cost compression in economy-tier biochemical assays is intensifying because of microplate commoditization. Academic laboratories exhibit highest price sensitivity; integrated pharmaceutical sponsors prioritize validation pedigree over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO framework are reshaping sourcing for contract research organizations serving export-oriented formulation houses. Primary human hepatocyte supply concentrates in the United States, Germany, and Japan, with microfluidic chip fabrication anchored in Taiwan and South Korea. Raw material dependencies include donor tissue logistics, specialized cell culture media, and photolithography-grade polymers. Single-source vulnerability in qualified hepatocyte suppliers threatens study initiation timelines. Distribution runs through decentralized laboratory networks with regional cryogenic logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA modernization initiatives on animal testing alternatives creating sustained demand inflection for human-relevant cell-based assays.
For Market Incumbents: Anticipate margin compression from organ-on-chip platform commoditization by locking in hepatocyte supply contracts and accelerating ICCVAM validation investment. Charles River Laboratories and Eurofins Scientific must defend against biotech developers building internal assay capabilities through platform loyalty programs with volume commitment structures. Certification investment represents the critical lever for pricing power retention.
For New Entrants and Emerging Players: Cloud-based data architectures offer the most penetrable entry vector, unbundling computational toxicology from physical laboratory capacity. Target biotechnology companies in Massachusetts and California with compressed IND timelines lacking internal bioinformatics infrastructure. A subscription-based go-to-market angle bypasses capital-intensive facility buildout requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract research organizations with geographic density advantages but limited end-to-end platform breadth. Long-term viability across the analysis window favors integrated discovery-to-safety providers with FDA and EMA dual-qualification capabilities. Monitor CDSCO alignment with OECD test guidelines as the signal for Indian market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| ICCVAM Validation Investment | FDA acceptance accelerates sponsor submission cycles and locks in regulatory premium positioning. |
| Hepatocyte Supply Contracting | Donor tissue security differentiates service reliability against batch-to-batch variability competitors. |
| Organ-on-Chip Platform Integration | Microfluidic cartridge standardization enables modular multi-organ studies commanding safety pharmacology premiums. |
| Cloud-Based Data Architecture | Computational toxicology subscriptions unbundle analysis from laboratory capacity constraints. |
| CDSCO Regulatory Alignment | OECD test guideline qualification opens localized service demand in Hyderabad and Mumbai manufacturing hubs. |
Research Approach
Coverage spans the United States, Germany, the United Kingdom, India, and Japan, with primary inputs from each regional cluster combining structured interviews with regulatory affairs leads at contract research organizations, platform development directors at biotechnology companies, hepatocyte procurement specialists, and academic laboratory principal investigators. Secondary validation draws from FDA New Approach Methodologies guidance documents, EMA qualification opinions, CDSCO regulatory circulars, OECD test guidelines, and ICCVAM validation study archives. Bottom-up assay deployment counts triangulate against top-down pharmaceutical R&D spending allocations.
Rate-of-change decomposition separates volume expansion from value capture across technology tiers, with segmentation modeling across product type, technology platform, application pathway, and end-user archetype. CAGRs derive from fitted adoption curves for organ-on-chip migration against high-throughput screening replacement rates. Forecast inputs include biotech cluster formation timelines, regulatory validation queue depths, and primary human cell donor availability constraints.
The model assumes a particular technology adoption path; alternative pathways for 3D bioprinting convergence with microfluidic platforms would alter the outlook for static well-plate obsolescence. Forecasts reflect documented assumptions on ICCVAM validation throughput and EMA qualification opinion alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Japan Material Testing Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Paint Tester Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Chemical Detector Market