
 Castor Wax Market | 2026-2036
Castor Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Castor Wax Market Analysis
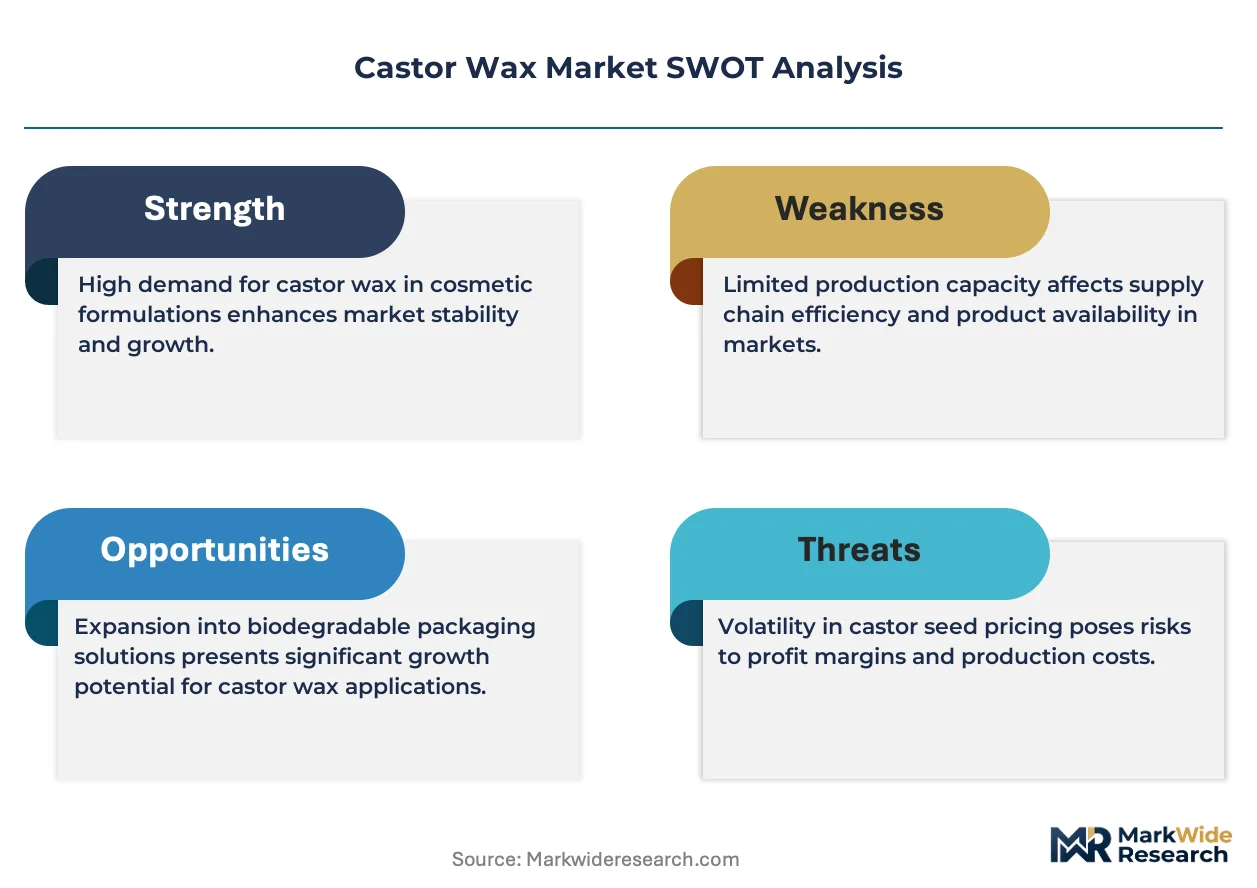
Indian castor seed processing capacity is hardening as the dominant supply base for hydrogenated derivatives. Jayant Agro Organics leverages backward integration from seed crushing to refined wax output, securing feedstock priority during volatile harvest cycles. Koster Keunen anchors European distribution through specialized cosmetic-grade refining, while ITOH Oil Chemicals Co. Ltd. competes on technical service depth for Japanese coatings formulators.
Castor wax is a hard, brittle vegetable wax produced by hydrogenating castor oil triglycerides, yielding a melting point near 85 degrees Celsius and exceptional viscosity stability across temperature ranges. It functions primarily as a rheology modifier, opacifier, and moisture barrier in stick cosmetics, protective coatings, and adhesive systems. Hydrogenated castor wax dominates product-type value pools due to its established certification pipeline for cosmetic and pharmaceutical grades, while modified castor wax represents the fastest-growing category as industrial clients seek custom hardness profiles for hot-melt adhesive applications. Flake form leads volume distribution because of handling efficiency in compounding operations, though granule demand is accelerating among pharmaceutical companies automating tablet coating lines.
REACH registration requirements in Europe and FDA indirect food-contact rules in the United States shape product purity specifications and limit unverified supplier entry. India's BIS certification for hydrogenated castor oil derivatives adds a domestic compliance layer that filters small-scale refiners from institutional procurement channels. Stakeholders must monitor evolving biobased content thresholds in EU Green Deal procurement guidelines and assess captive seed supply strategies against monsoon-driven Indian harvest volatility.
Market Dynamics
Castor wax procurement is tightening around hydrogenation capacity clusters in India as cosmetic formulators enforce feedstock traceability clauses and reject multi-source blended shipments.
Growth Catalysts
- REACH Registration:ECHA's substance registration requirements are disqualifying unverified Asian refiners from European cosmetic supply chains, concentrating demand on certified hydrogenation facilities.
- Hot-melt Adhesive Formulation:Industrial coatings manufacturers are specifying modified castor wax for custom hardness profiles in temperature-variable bonding applications.
- Seed Processing Concentration:Gujarat's crushing-to-refining corridor is capturing margin from volatile harvest cycles through captive hydrogenation infrastructure.
Market Restraints
- Monsoon-Driven Feedstock Volatility:Indian castor seed yields fluctuate with rainfall patterns, compressing margin predictability for non-integrated refiners.
- Palm Wax Substitution:Cost-sensitive packaging coatings formulators are trialing palm-derived alternatives where barrier properties permit.
- BIS Certification Barriers:India's domestic quality standards filter small-scale hydrogenators from institutional pharmaceutical procurement channels.
Strategic Opportunities
- EU Green Deal Biobased Thresholds:Procurement guidelines for renewable content in public-sector adhesives are opening preferential access for certified plant-derived waxes.
- Pharmaceutical Tablet Coating Automation:Granule-format castor wax demand is accelerating among drug manufacturers retrofitting continuous coating lines.
- Japanese Technical Service Depth:Coatings formulators in Japan are contracting for application-specific rheology support beyond commodity supply.
Industry Challenges
- Cross-Contamination Controls:Cosmetic-grade hydrogenation facilities must segregate pharmaceutical and industrial process streams under FDA indirect food-contact rules.
- Specialized Hydrogenation Talent:Operating pressure vessels for triglyceride hardening requires certified technicians scarce outside Gujarat's established processing corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Castor Wax Market |
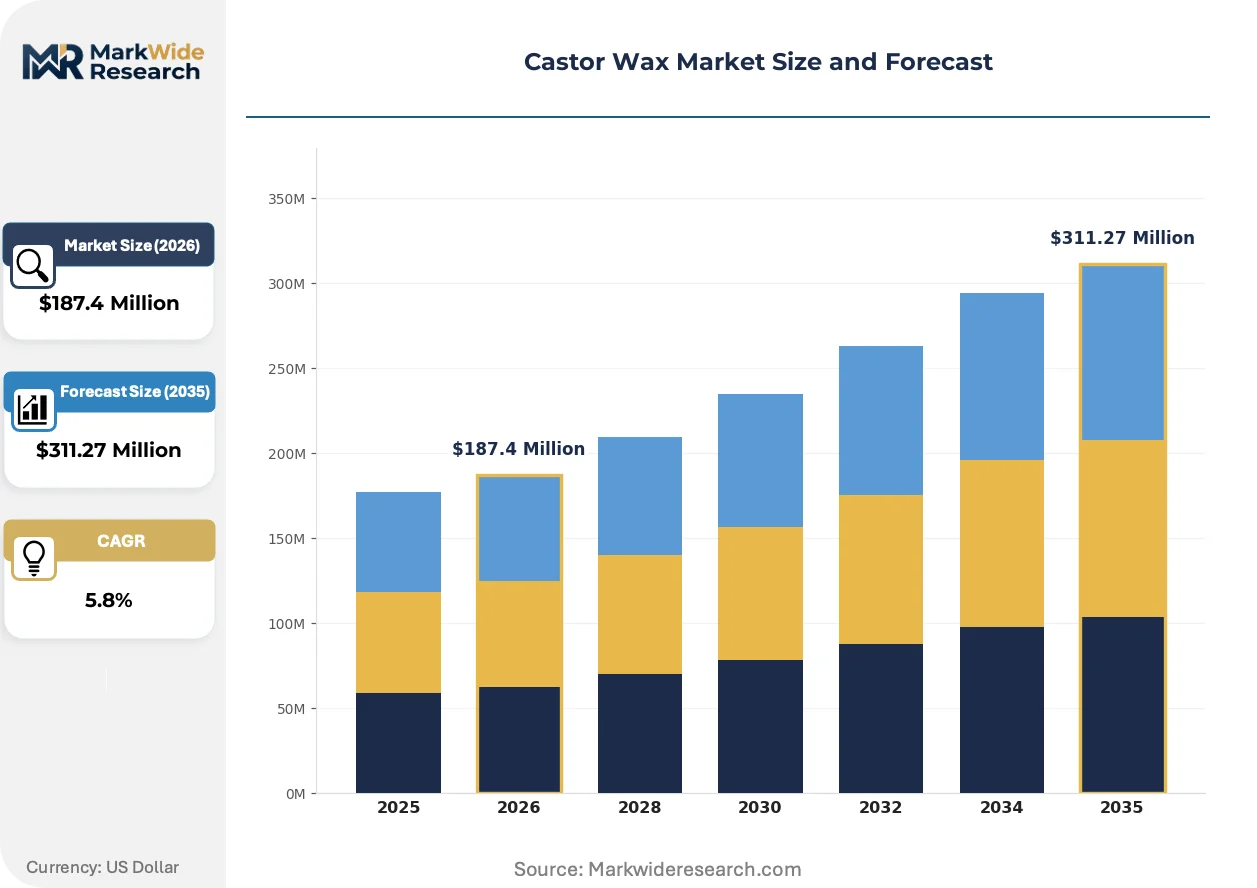
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated Castor Wax, Refining Grade, Modified Castor Wax, Emulsifying Agent Application: Cosmetics, Coatings, Adhesives, Personal Care End User: Cosmetic Manufacturers, Pharmaceutical Companies, Industrial Clients, Food Producers Form: Flakes, Granules, Powders, Liquids |
| Companies Covered | Hokoku Corporation, Natural Pigments, Jayant Agro Organics, Liaoyang Huaxing Chemical, Adya Oils and Chemicals, Koster Keunen, ITOH Oil Chemicals Co. Ltd., BOM Brazil, Gokul Refoils and Solvent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Castor Wax Market Emerging Trajectories
Formulation science is diverging along certification-grade lines as end-users reject commodity sourcing and demand batch-level traceability from seed origin through hydrogenation.
Modified castor wax with custom hardness profiles is expanding into hot-melt adhesive systems for automotive interior bonding. Tier-one suppliers are qualifying these materials for dashboard assembly lines requiring viscosity stability across temperature extremes. The technology is expanding into specification sheets previously dominated by synthetic polyamide alternatives.
REACH compliance deadlines are compressing supplier qualification timelines for European cosmetic manufacturers. ECHA's updated registration dossier requirements are forcing reformulation teams to document hydrogenation catalyst residues at parts-per-million thresholds. Color cosmetics divisions are responding by consolidating procurement onto refiners with pre-validated certification pipelines.
Buyer concentration among multinational cosmetic houses is shortening supplier approval cycles and demanding dedicated hydrogenation capacity. Stick-formulation R&D teams are embedding castor wax suppliers earlier in product development timelines. This pattern is most visible in lipstick and balm launches targeting clean-label positioning in North American and European retail channels.
Castor Wax Market Segmentation
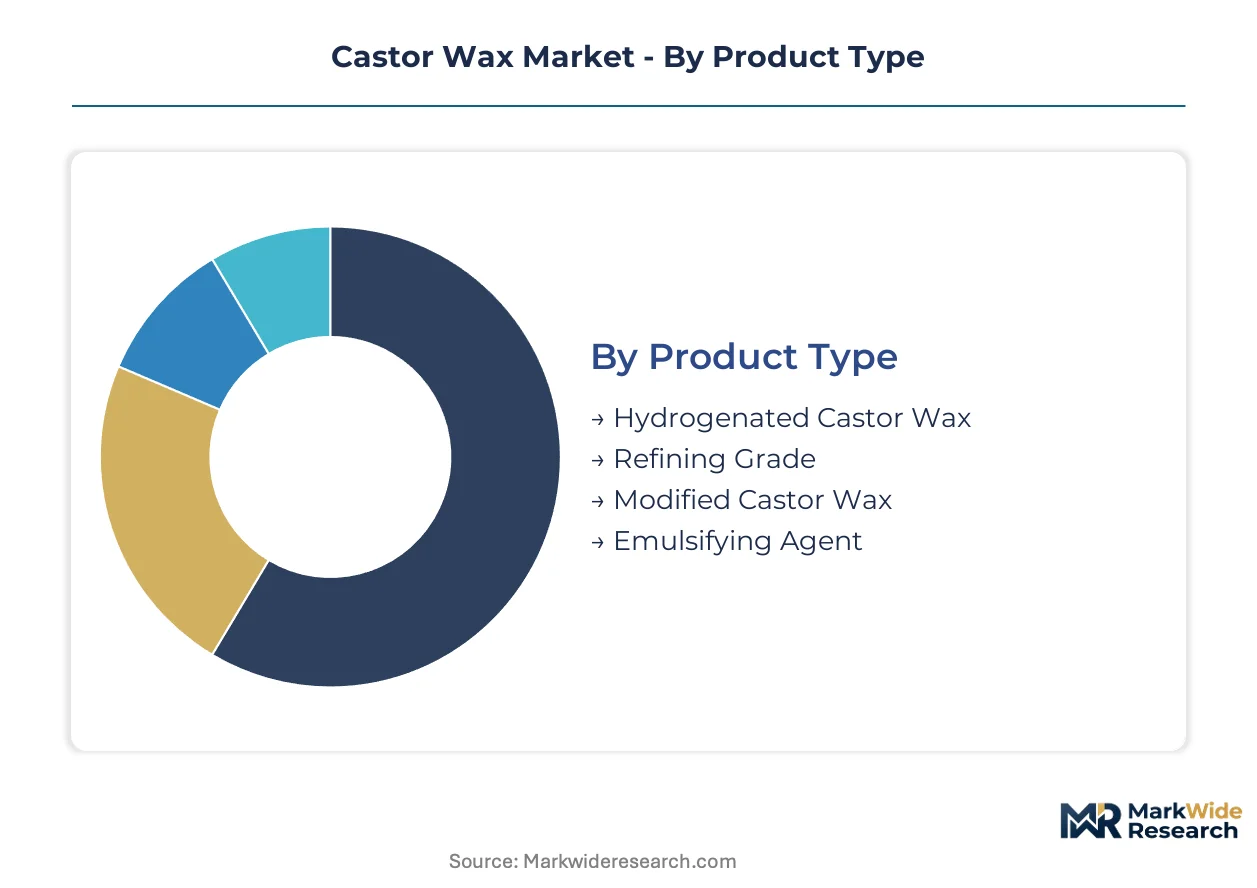
Castor wax buyers segment procurement by certification grade, hardness specification, and handling format. Each dimension carries distinct margin profiles and supplier qualification barriers that reshape competitive positioning across cosmetic, pharmaceutical, and industrial channels.
Product Type:
Cost tiers separate commodity hydrogenation outputs from premium modified grades requiring custom catalyst protocols and application engineering.
- Hydrogenated Castor Wax:Standard triglyceride hardening yields melting points near 85°C with established REACH and FDA certification pipelines. Cosmetic formulators in France and Germany consolidate procurement onto Indian refiners with pre-validated dossiers to compress ECHA registration timelines.
- Modified Castor Wax:Custom hardness profiles engineered through controlled oxidation or esterification expand into hot-melt adhesive specifications for automotive dashboard bonding. Japanese coatings houses contract ITOH Oil Chemicals for rheology support beyond commodity supply.
- Refining Grade:Intermediate purification stage for downstream pharmaceutical and food-contact applications requiring residual catalyst removal below parts-per-million thresholds.
- Emulsifying Agent:Functional derivatives for water-in-oil formulations in skin-care emulsions where viscosity stability across temperature ranges is critical.
Hydrogenated castor wax leads volumes today; modified castor wax is climbing the fastest as industrial buyers specify custom performance profiles.
Application:
End-use maturity determines whether buyers prioritize batch traceability or cost minimization in supplier selection.
- Cosmetics:Lipstick and balm formulators enforce seed-origin documentation through hydrogenation as clean-label requirements tighten in North American and European retail channels. Stick-formulation R&D teams embed suppliers earlier in product development timelines.
- Coatings:Protective coatings manufacturers trial palm wax substitution where barrier properties permit, though castor derivatives retain specification in moisture-critical applications.
- Adhesives:Hot-melt systems for packaging and assembly specify modified grades with viscosity stability across temperature extremes previously served by synthetic polyamides.
- Personal Care:Skin-care and hair-care formulations leverage emulsifying grades for texture modification in rinse-off and leave-on products.
Cosmetics commands the largest value pool; adhesives shows the steepest expansion trajectory as automotive interior specifications convert to biobased bonding agents.
End User:
Regulatory exposure and volume scale create four distinct procurement postures with incompatible supplier qualification requirements.
- Cosmetic Manufacturers:Multinational houses shorten supplier approval cycles and demand dedicated hydrogenation capacity with batch-level seed-to-wax traceability for clean-label positioning.
- Pharmaceutical Companies:Tablet coating automation drives granule-format demand among drug manufacturers retrofitting continuous coating lines; BIS certification filters small-scale Indian hydrogenators from institutional procurement.
- Industrial Clients:Cost-sensitive packaging coatings formulators test palm-derived alternatives where barrier performance permits, though modified castor wax retains position in temperature-variable bonding.
- Food Producers:Indirect food-contact compliance under FDA rules limits unverified refiner entry; hydrogenation facilities must segregate cosmetic, pharmaceutical, and industrial process streams.
Cosmetic manufacturers dominate procurement value; pharmaceutical companies are expanding volumes fastest through coating line automation.
Form:
Handling efficiency in compounding operations versus dosing precision in automated lines differentiates format selection.
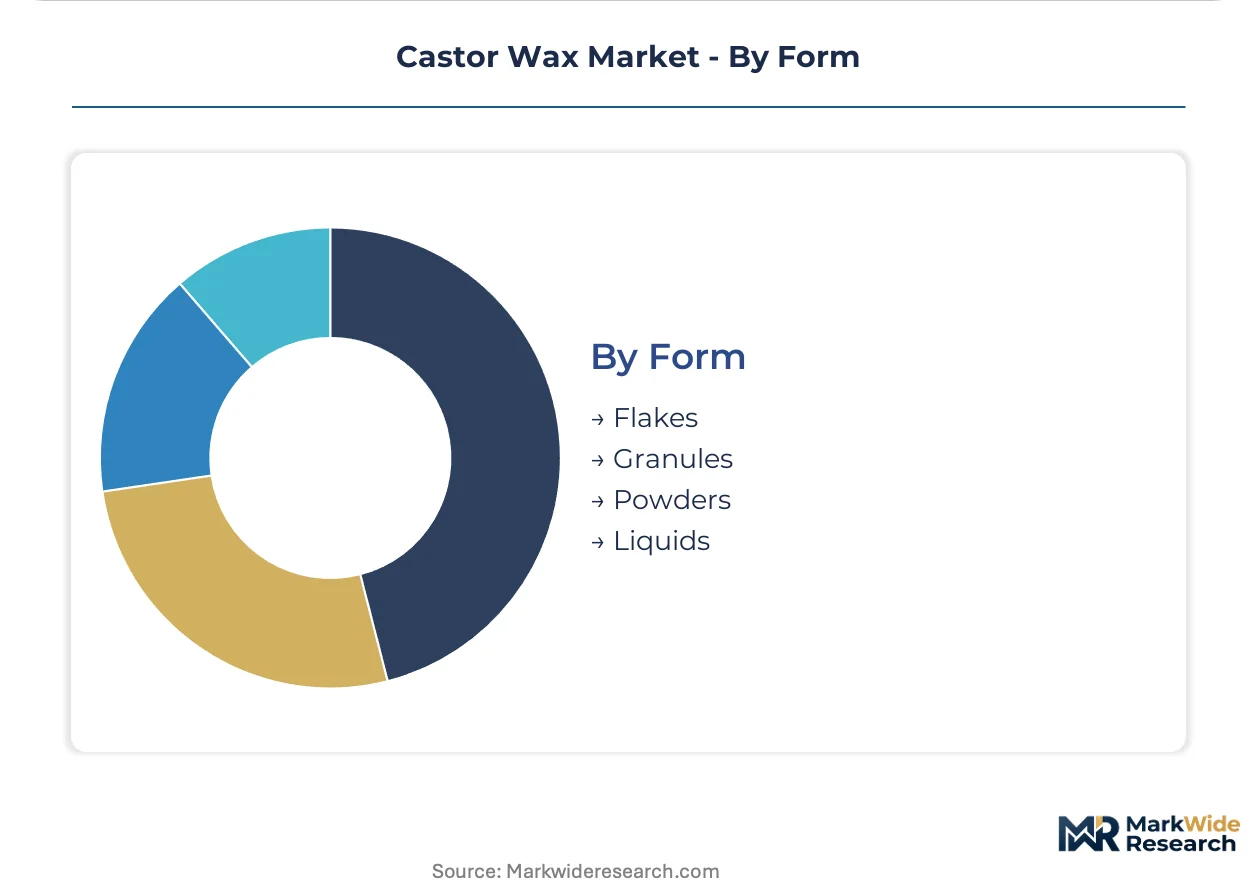
- Flakes:Dominates volume distribution for handling efficiency in cosmetic and coatings compounding operations where melt incorporation is standard.
- Granules:Accelerating demand among pharmaceutical companies automating tablet coating lines for consistent feed and reduced dust generation.
- Powders:Micronized grades for specific rheology modification in powder-to-liquid personal care formulations.
- Liquids:Pre-dispersed or low-melt variants for specialized adhesive and coating applications requiring pumpable feedstocks.
Flake format leads distribution volumes today; granule demand is gaining share fastest through pharmaceutical automation retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes over three-quarters of global castor seed supply, while Germany's REACH enforcement redirects European procurement toward certified hydrogenation facilities. Japan's coatings sector demands technical service depth that commodity traders cannot satisfy.
India
Gujarat's crushing-to-refining corridor supplies hydrogenated castor wax to cosmetic formulators demanding batch-level seed traceability. BIS certification for hydrogenated castor oil derivatives filters small-scale refiners from pharmaceutical procurement channels. Kandla and Jamnagar host integrated facilities where Jayant Agro Organics maintains captive hydrogenation capacity.
Germany
Cosmetic manufacturers in Hamburg and Frankfurt consolidate procurement onto Indian refiners with pre-validated REACH dossiers. ECHA's updated registration requirements document hydrogenation catalyst residues at parts-per-million thresholds. The Ruhr region's coatings specialists trial modified castor wax for automotive adhesive specifications.
United States
FDA indirect food-contact rules limit unverified refiner entry for tablet coating and packaging applications. New Jersey and California cosmetic houses enforce seed-origin documentation through hydrogenation for clean-label lipsticks. Midwest industrial coatings formulators test palm-derived alternatives where barrier performance permits.
Japan
Tokyo and Osaka coatings houses contract for application-specific rheology support beyond commodity wax supply. METI guidelines on biobased content influence procurement specifications for automotive interior bonding. Chubu region adhesive manufacturers specify modified castor wax for dashboard assembly lines requiring viscosity stability.
Brazil
São Paulo's cosmetic manufacturers source hydrogenated grades for balm formulations targeting export markets. ANVISA pharmaceutical regulations drive demand for granule-format wax among tablet coating operations. Minas Gerais agricultural regions are expanding castor cultivation to reduce import dependency on Asian supply.
Castor Wax Market Vendor Landscape
Indian producers anchor the integrated supply tier; European and Japanese specialists hold certification and technical service positions. The vendor base separates into three strata: seed-to-wax integrators with captive crushing, regional refiners with cosmetic-grade hydrogenation capacity, and application-focused modifiers serving industrial specifications. Competitive moves concentrate on backward integration into seed procurement and dedicated hydrogenation capacity commitments to multinational cosmetic houses.
Among India-based integrators, Jayant Agro Organics exemplifies the seed-to-wax archetype through Gujarat corridor infrastructure. Koster Keunen occupies a position within the European certification tier, while ITOH Oil Chemicals Co. Ltd. represents the technical-service specialist model for Japanese coatings formulators. These three anchors illustrate how geographic concentration and regulatory proximity shape competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Hokoku Corporation |
| Natural Pigments |
| Jayant Agro Organics |
| Liaoyang Huaxing Chemical |
| Adya Oils and Chemicals |
| Koster Keunen |
| ITOH Oil Chemicals Co. Ltd. |
| BOM Brazil |
| Gokul Refoils and Solvent |
| Others |
Supply Flow & Price Mechanics
Certified hydrogenation technicians concentrated in Gujarat's processing corridor command wage premiums that widen pricing spreads between pharmaceutical-grade and industrial-grade castor wax tiers. Labor-cost differentials between integrated seed-to-wax facilities and standalone refiners compound these tier separations as buyers enforce certification requirements.
Pricing Analysis
Capacity additions in Maharashtra are reshaping price floors for standard hydrogenated grades while premium modified wax retains margin insulation through custom catalyst protocols. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial certification levels separates buyers by traceability requirements and residue thresholds. Price differentiation hinges on REACH dossier completeness and BIS certification status. Cost compression in packaging coatings is intensifying because palm wax substitution trials are expanding; industrial clients show highest price sensitivity while cosmetic multinationals prioritize batch documentation over unit cost.
Supply Chain Analysis
Reverse-logistics flows for catalyst recovery and hydrogenation vessel refurbishment cycle through Gujarat's equipment maintenance networks, extending asset life for integrated processors. Supply concentrates in India, Brazil, and China as crushing-to-refining corridors capture margin from seed volatility. Raw material dependencies center on castor seed harvests, hydrogen gas supply, and nickel catalyst feedstocks. Single-source vulnerability runs through Indian monsoon patterns that compress seed availability. Distribution runs through direct long-term contracts to multinational cosmetic houses and pharmaceutical compounders, bypassing commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification-grade premiums are widening as REACH compliance deadlines compress supplier qualification timelines toward certified hydrogenation facilities.
For Market Incumbents: To counter palm wax substitution in packaging coatings, incumbents must deepen captive seed procurement through monsoon hedge contracts and expand dedicated hydrogenation capacity commitments to multinational cosmetic houses. Certification investment in ECHA pre-validated dossiers anchors pricing power against commodity traders. For New Entrants and Emerging Players: Enter via pharmaceutical granule-format supply to automated tablet coating lines in Brazil and Southeast Asia, where ANVISA and national pharmaceutical regulators are filtering small-scale refiners from institutional procurement. Technical service partnerships with Japanese coatings formulators offer the most penetrable wedge against established commodity suppliers. For Investors and Strategic Acquirers: Specialty chemical houses with cosmetic ingredient portfolios are the most active acquirer in this space, targeting seed-to-wax integrators with captive Gujarat infrastructure. Long-term viability over a multi-year horizon rests on backward integration depth and certification pipeline maturity. Practitioners should monitor EU Green Deal biobased procurement threshold announcements for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Captive supply from Gujarat crushing corridors hedges monsoon-driven harvest volatility for hydrogenation facilities. |
| REACH Dossier Pre-validation | ECHA-compliant documentation accelerates supplier qualification timelines for European cosmetic manufacturers. |
| Granule Format Capacity Addition | Pharmaceutical automation retrofits in São Paulo and Tokyo drive consistent-feed demand for tablet coating lines. |
| Modified Wax R&D Partnership | Automotive adhesive specifications for dashboard bonding require custom hardness profiles beyond commodity grades. |
| Technical Service Center Establishment | Japanese coatings formulators contract ITOH Oil Chemicals for application-specific rheology support beyond supply. |
Methodological Framework
Direct dialogue with hydrogenation plant managers, cosmetic procurement leads, pharmaceutical formulation scientists, and coatings R&D directors grounded qualitative findings in operational reality. Secondary validation drew from ECHA registration databases, BIS certification records, Indian customs export data, and SEC filings of publicly traded seed processors. Bottom-up volume builds across product type, application, and format segments were cross-checked against top-down trade flow analysis.
Bottom-up modeling of hydrogenation capacity utilization, seed crush rates, and grade-specific offtake volumes across the analysis window anchored value projections. Segmentation dimensions included certification tier, hardness specification, handling format, and end-use industry. CAGRs were derived from trend extrapolation of procurement consolidation patterns and regulatory deadline impacts. Forecast inputs incorporated monsoon cycle variability and EU Green Deal procurement guideline evolution.
The model holds under stable REACH enforcement intensity and consistent Indian seed harvest ranges; deviation in ECHA registration timeline compression or extreme monsoon disruption would shift supply availability assumptions. Practitioners should monitor Kharif season rainfall forecasts and EU public-sector biobased tender announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Acrylamide Market