
 North America Acetic Acid Market | 2026-2036
North America Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acetic Acid Market Intelligence
Market Context
US Gulf Coast capacity additions are narrowing the supply-demand gap for merchant acetic acid. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to sustain cost leadership along the Texas-Louisiana corridor. Dow Chemical Company anchors regional supply through its downstream vinyl acetate integration. Eastman Chemical Company differentiates via specialty acetate esters for coatings and adhesives.
Technical Definition and Segment Structure
Acetic acid is a two-carbon carboxylic acid with the formula CH₃COOH, produced industrially through methanol carbonylation at concentrations typically exceeding 99.5 weight percent for glacial grades; it functions primarily as a chemical intermediate for vinyl acetate monomer, purified terephthalic acid, and acetate ester synthesis. Glacial acetic acid dominates value generation due to its role in high-purity chemical synthesis, while acetate esters capture expanding demand from paint reformulation trends. Methanol carbonylation technology leads capacity economics, though catalytic oxidation retains share in food-grade and preservation applications.
Regulatory Frame and Outlook
The EPA enforces Clean Air Act standards that limit volatile organic compound emissions from acetic acid production and storage, while OSHA governs workplace exposure limits at eight-hour time-weighted averages. State-level regulators in Texas and Louisiana layer additional air quality permits on Gulf Coast facilities, creating compliance complexity for capacity expansions. Stakeholders must weigh methanol carbonylation upgrades against fermentation pathway investments as carbon intensity rules tighten.
Market Dynamics
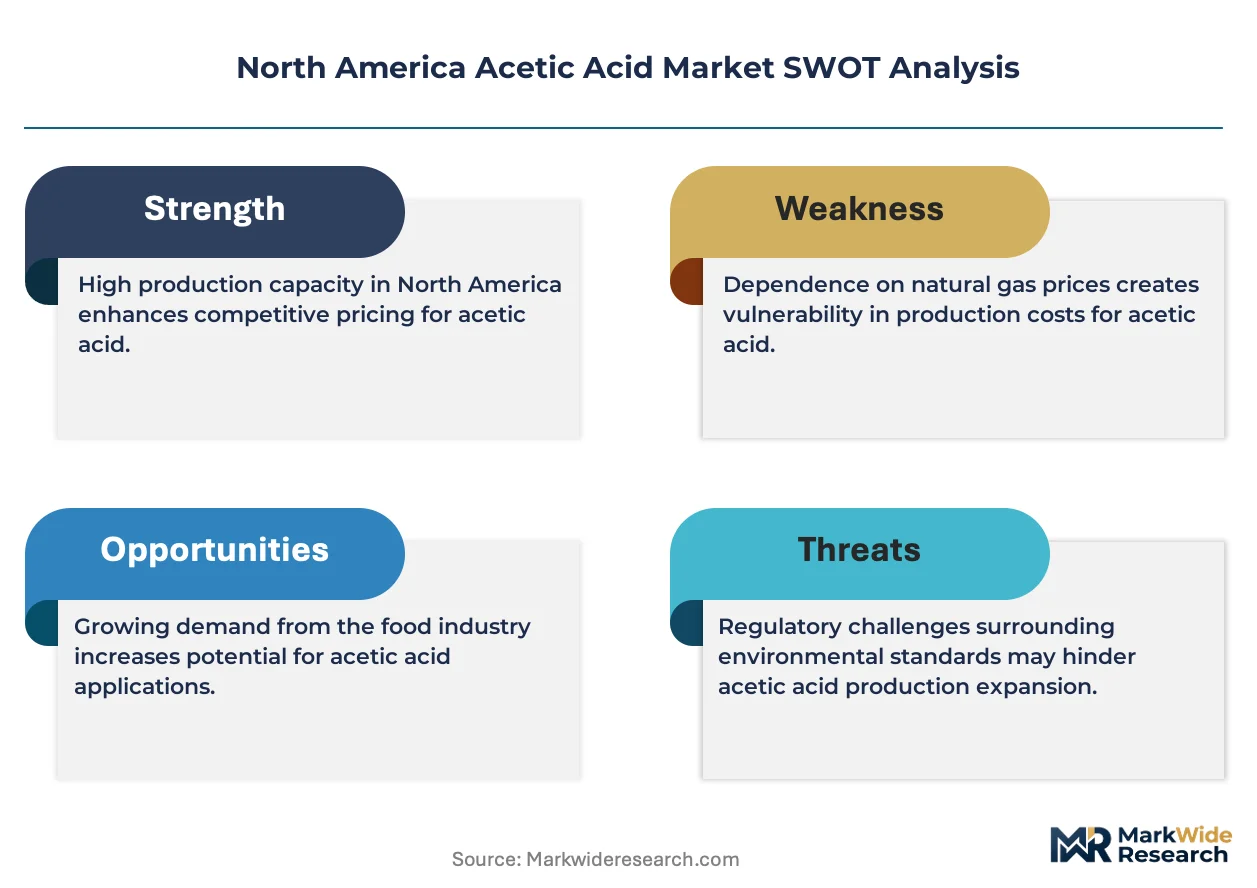
Methanol carbonylation upgrades along the US Gulf Coast petrochemical corridor are compressing production costs while EPA emissions standards under the Clean Air Act force simultaneous capital deployment into abatement systems.
Growth Catalysts
- Vinyl acetate monomer demand:Construction adhesives and water-based coatings in the US housing sector absorb rising acetic acid volumes as builders shift from solvent-based systems.
- EPA Clean Air Act enforcement:Tightened volatile organic compound limits accelerate methanol carbonylation retrofits that simultaneously expand nameplate capacity and reduce per-unit emissions intensity.
- Texas-Louisiana corridor concentration:Pipeline-integrated feedstock access and shared hydrogen networks lower delivered costs for merchant acid buyers in the region.
Market Restraints
- Methanol price volatility:Natural gas feedstock swings and international methanol trade imbalances transmit directly to acetic acid variable costs, compressing margin predictability for non-integrated producers.
- Gulf Coast supply concentration:Hurricane exposure and shared infrastructure dependencies create correlated outage risks that strain regional inventory buffers during peak demand windows.
- Catalytic oxidation persistence:Food-grade and preservation applications retain fermentation-based supply chains that resist carbonylation economics due to purity certification requirements.
Strategic Opportunities
- Carbon intensity accounting:California's LCFS and emerging federal clean hydrogen production tax credits create premium pricing windows for low-carbon acetic acid certified through mass-balance chain of custody.
- Bio-based feedstock pathways:Syngas-from-biomass and captured carbon monoxide streams enable fermentation-carbonylation hybrid processes that qualify for renewable chemical offtake contracts.
- Specialty acetate esters:High-purity grades for electronics solvents and pharmaceutical intermediates command price premiums that offset commodity acid margin pressure.
Industry Challenges
- Process control engineering scarcity:Methanol carbonylation unit optimization requires rare expertise in rhodium-iridium catalyst management and carbon monoxide purity management that outpaces training pipeline output.
- Air permitting timelines:Texas Commission on Environmental Quality and Louisiana Department of Environmental Quality review cycles for expansion projects extend 18-24 months, delaying capacity response to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acetic Acid Market |
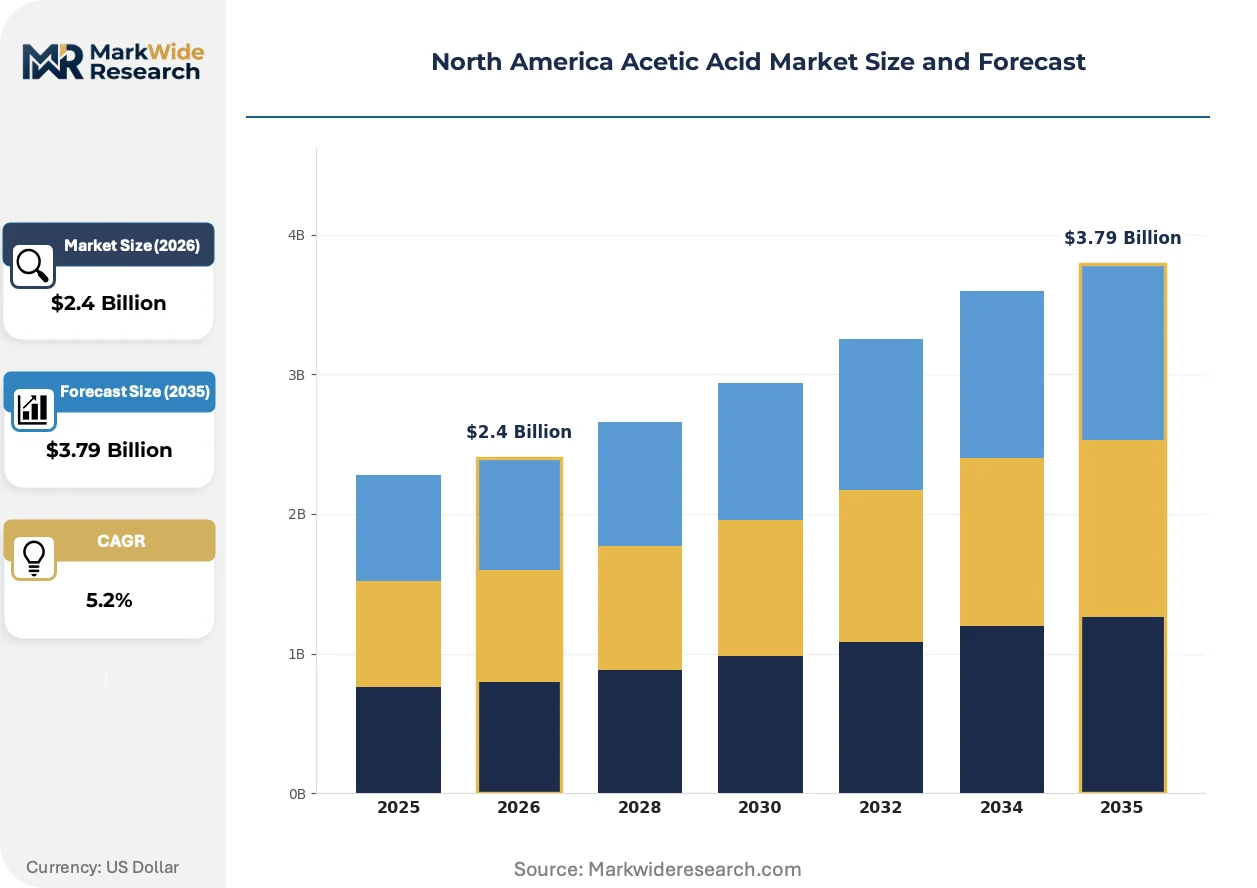
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Dilute Acetic Acid, Acetic Anhydride, Acetate Esters Application: Chemical Synthesis, Food Preservation, Textile Manufacturing, Paint Production End User: Food Industry, Textile Industry, Chemical Industry, Pharmaceutical Sector Technology: Traditional Fermentation, Catalytic Oxidation, Carbonylation, Methanol Carbonylation |
| Companies Covered | LyondellBasell Industries Holdings B.V., Dow Chemical Company, Celanese Corporation, Daicel Corporation, BP Chemicals, Eastman Chemical Company, SABIC, HELM de México, S.A., INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acetic Acid Market Strategic Shifts & Innovations
Carbon accounting integration is rewriting procurement specifications across chemical downstream sectors, forcing acetic acid suppliers to validate emissions intensity through third-party certification rather than traditional assay reporting alone.
Membrane separation technology for carbon monoxide purification is collapsing the capital cost barrier for smaller-scale methanol carbonylation units. Mid-sized chemical processors in Ohio and Illinois are piloting modular 50,000-ton-per-year systems that bypass pipeline-dependent Gulf Coast supply. This distributed production model is compressing freight costs for inland buyers and eroding the historical freight-advantage moat of Texas-Louisiana producers.
OSHA's proposed lower eight-hour time-weighted average exposure limits for acetic acid vapor are forcing storage and handling infrastructure redesigns across the Great Lakes and Midwest manufacturing belt. Facilities in Michigan and Indiana face simultaneous compliance deadlines with state-level process safety management audits. The coatings and adhesives segment is responding fastest, accelerating investments in closed-loop transfer systems and vapor recovery units ahead of enforcement phase-in.
Long-term offtake contracting is displacing spot market purchasing among vinyl acetate monomer producers seeking supply security amid Gulf Coast hurricane season volatility. Buyers in the Ohio River Valley and Southeast construction corridors are locking in three-to-five-year supply agreements with fixed-price escalators tied to natural gas indices rather than methanol benchmarks. This hedging behavior is most pronounced among integrated building materials conglomerates with multi-year infrastructure project backlogs.
North America Acetic Acid Market Segmentation
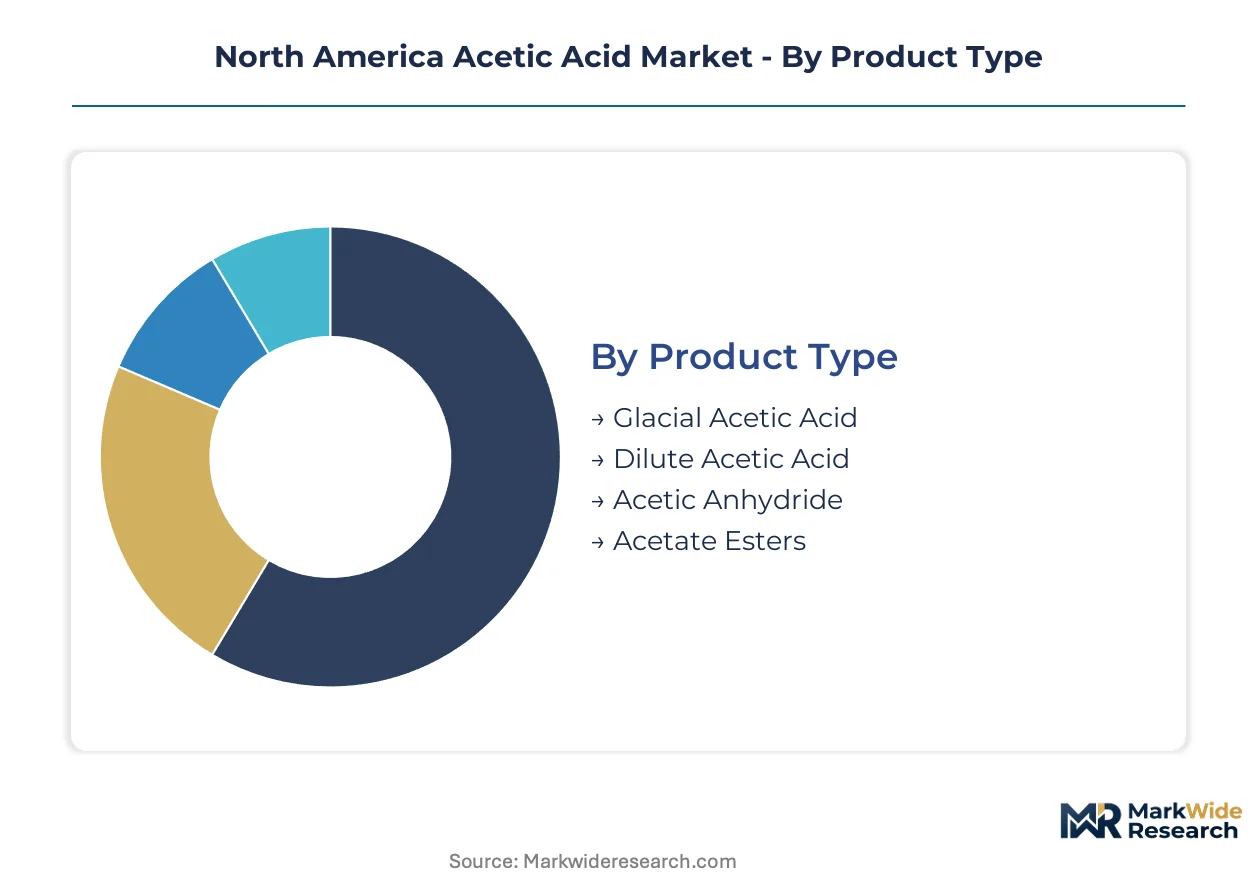
Acetic acid segmentation in North America reflects divergent purity requirements and production economics across chemical synthesis, food-grade, and preservation applications. Distinct technology pathways and end-use specifications create tiered value pools that reward specialization along the Texas-Louisiana corridor and Midwest manufacturing belt.
Product Type:
Product differentiation tracks concentration thresholds and derivative chemistry complexity, with high-purity grades commanding premium positioning in industrial synthesis chains.
- Glacial Acetic Acid:Concentration exceeds 99.5 weight percent, serving as the foundational feedstock for vinyl acetate monomer and purified terephthalic acid production. Demand concentrates along the US Gulf Coast petrochemical corridor where Celanese and Dow maintain integrated methanol-to-acid-to-derivative chains.
- Acetate Esters:Derived through esterification with corresponding alcohols, these solvents absorb expanding volumes from water-based paint reformulation trends in Ohio and Michigan coatings manufacturing. EPA volatile organic compound limits are accelerating substitution of traditional hydrocarbon thinners.
- Dilute Acetic Acid:Lower concentration solutions for food preservation and pickling applications, produced through fermentation pathways that retain share despite carbonylation cost advantages due to organic certification requirements.
- Acetic Anhydride:Dehydrated derivative serving cellulose acetate and pharmaceutical acetylation reactions, with demand anchored in Eastman Chemical's Kingsport, Tennessee specialty chemicals complex.
The dominant share belongs to glacial acetic acid, while acetate esters are closing the gap fastest.
Application:
Application segmentation mirrors downstream industry exposure, with chemical synthesis absorbing the majority of merchant acid volumes while food preservation retains stable baseline demand.
- Chemical Synthesis:Intermediate consumption for vinyl acetate monomer, acetic anhydride, and chloroacetic acid production, concentrated in Texas and Louisiana integrated petrochemical complexes. Methanol carbonylation upgrades are expanding nameplate capacity while EPA Clean Air Act compliance drives simultaneous abatement investments.
- Paint Production:Solvent and coalescent applications in water-based architectural coatings, with demand clustering in Ohio River Valley manufacturing corridors serving Midwest construction markets. OSHA's proposed lower exposure limits are forcing closed-loop transfer system investments.
- Food Preservation:Acidulant and antimicrobial applications in pickling, condiments, and baked goods, supplied through fermentation-based pathways resistant to carbonylation economics due to non-GMO and organic certification requirements.
- Textile Manufacturing:Dyeing auxiliaries and finishing agents, with declining share in North America as apparel production migrates offshore while technical textiles in Georgia and the Carolinas sustain residual demand.
Chemical synthesis holds the volume anchor position, though paint production is expanding most quickly as housing construction drives water-based coating substitution.
End User:
End-user segmentation reveals divergent procurement patterns, with chemical industry buyers leveraging long-term offtake contracts while food sector purchasers prioritize certification compliance.
- Chemical Industry:Integrated vinyl acetate monomer producers and merchant derivative manufacturers along the Gulf Coast, locking in three-to-five-year supply agreements with natural gas-indexed pricing to hedge hurricane season volatility.
- Food Industry:Processors and preservative blenders requiring fermentation-derived acid with organic and non-GMO chain-of-custody documentation, paying premiums that resist carbonylation cost convergence.
- Pharmaceutical Sector:Acetic anhydride and high-purity acid consumers for active pharmaceutical ingredient synthesis, with demand concentrated in New Jersey and Massachusetts contract manufacturing clusters.
- Textile Industry:Dye houses and finishing operations in Georgia and the Carolinas, facing margin pressure from offshore competition that constrains acid price tolerance.
The chemical industry commands the dominant procurement volume, while the pharmaceutical sector is gaining share fastest through specialty purity requirements.
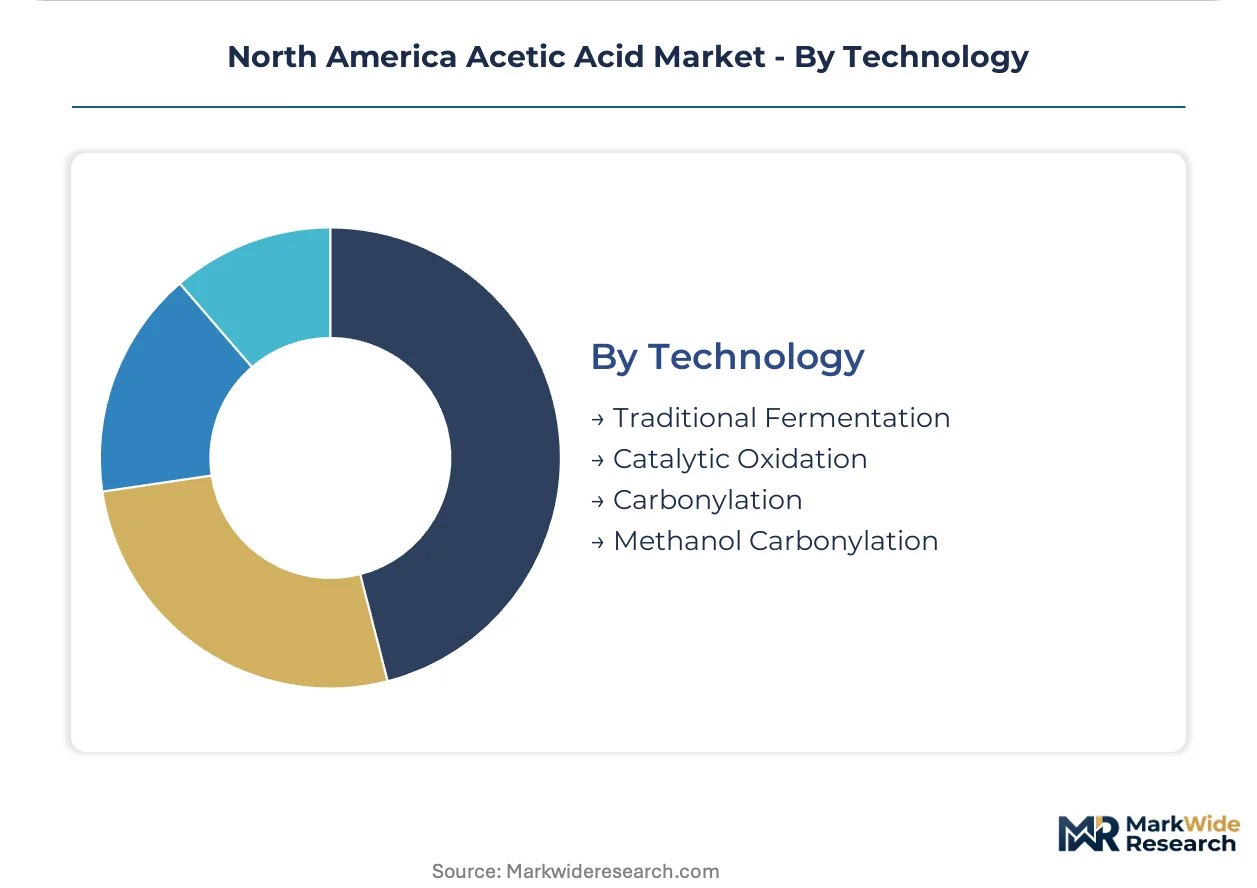
Technology:
Technology segmentation captures the economic divergence between legacy fermentation, transitional oxidation, and modern carbonylation pathways.
- Methanol Carbonylation:Rhodium-iridium catalyzed process achieving lowest variable costs at scale, dominating Gulf Coast capacity expansions by Celanese and BP-Amoco joint ventures. EPA emissions standards are accelerating retrofits that expand output while reducing per-unit volatile organic compound releases.
- Carbonylation:Broader category encompassing methanol-based and syngas-based routes, with emerging biomass-syngas hybrids qualifying for California LCFS credits and federal clean hydrogen production tax incentives.
- Catalytic Oxidation:Ethylene or acetaldehyde oxidation retaining niche share for food-grade acid where fermentation pathway certification is not required, primarily in legacy Midwest facilities.
- Traditional Fermentation:Biological ethanol oxidation to acetic acid, constrained to food preservation and organic applications where carbonylation-derived acid cannot satisfy certification requirements.
Methanol carbonylation anchors the technology base, while carbonylation variants incorporating bio-syngas feedstocks are climbing the fastest as carbon intensity accounting reshapes procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methanol carbonylation capacity clusters along the US Gulf Coast, concentrating variable-cost advantages for integrated producers while EPA Clean Air Act compliance drives simultaneous abatement investments across the corridor.
United States
Vinyl acetate monomer producers along the Texas-Louisiana corridor absorb rising volumes as water-based coatings displace solvent systems in residential construction. OSHA's proposed lower eight-hour time-weighted average exposure limits are forcing closed-loop transfer system investments across Michigan and Ohio manufacturing belts. Celanese Corporation leverages its integrated methanol-to-acetic acid chain at Clear Lake, Texas to sustain cost leadership.
Canada
Ontario-based paint manufacturers source merchant acid through long-term offtake contracts hedging against Gulf Coast hurricane season volatility. Environment and Climate Change Canada layers federal carbon pricing on provincial industrial emissions programs, raising compliance complexity for Ontario chemical processors. Toronto-area coatings formulators are accelerating water-based system investments ahead of federal volatile organic compound limits.
Mexico
HELM de México anchors regional distribution through Nuevo León-based storage and blending operations serving northern industrial corridors. SEMARNAT air quality permits for chemical expansions in Tamaulipas and Veracruz face extended review cycles that delay capacity response to demand spikes. Monterrey-area adhesives manufacturers are locking in three-year supply agreements with fixed-price escalators tied to natural gas indices.
North America Acetic Acid Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in catalyst management and carbon monoxide purification. The North American acetic acid market structures around three to four integrated petrochemical conglomerates with captive methanol supply, creating tiered competition between Gulf Coast scale players and inland merchant acid distributors. Strategic archetypes include methanol-integrated producers, specialty ester differentiators, and regional distribution intermediaries. Dominant competitive moves encompass methanol carbonylation retrofits expanding nameplate capacity and long-term offtake contracting displacing spot market purchasing.
Within the integrated producer tier, Celanese Corporation and Dow Chemical Company exemplify methanol-to-derivative platform control. Eastman Chemical Company occupies a specialty position through acetate ester differentiation for coatings and adhesives applications. These three anchors represent divergent strategic postures: Gulf Coast scale integration, downstream vinyl acetate capture, and high-purity ester specialization respectively.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| Dow Chemical Company |
| Celanese Corporation |
| Daicel Corporation |
| BP Chemicals |
| Eastman Chemical Company |
| SABIC |
| HELM de México, S.A. |
| INEOS |
| Others |
Cost & Logistics Intelligence
The Texas-Louisiana petrochemical corridor freight differential compresses delivered costs for Gulf Coast integrated producers while amplifying price premiums for inland buyers sourcing from merchant distributors. This logistics geometry concentrates pricing power among methanol-integrated operators and forces non-integrated processors to absorb higher landed costs or accept lower purity grades.
Pricing Analysis
EPA Clean Air Act enforcement dictates the pricing tier structure across the North American acetic acid market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification requirements and volume scale, with food-grade fermentation acid commanding premiums that resist carbonylation cost convergence. Pricing pressure stems from methanol feedstock volatility transmitted through natural gas index fluctuations, squeezing margin predictability for non-integrated merchant producers. Chemical industry buyers exhibit lowest price sensitivity due to long-term offtake contracting with fixed-price escalators, while textile dye houses in Georgia and the Carolinas face acute cost pressure from offshore competition.
Supply Chain Analysis
Extended payment terms from integrated Gulf Coast producers to Midwest distributors compress working capital cycles for regional intermediaries. Supply concentrates in the United States, Canada, and Mexico, with methanol feedstock, rhodium-iridium catalysts, and carbon monoxide purification membranes anchoring upstream dependencies. Single-source vulnerability runs through the Texas-Louisiana corridor's shared hydrogen networks and pipeline infrastructure, exposing buyers to correlated outage risks during hurricane season. Distribution runs through tanker truck and railcar networks serving Ohio River Valley coatings manufacturers and Great Lakes adhesives formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American acetic acid market requires substitution defense against bio-based fermentation pathways that capture food-grade and organic certification premiums. Incumbents must navigate this bifurcation while defending carbonylation scale advantages in chemical synthesis applications.
For Market Incumbents: Build captive methanol supply moats through backward integration into natural gas feedstock or long-term pipeline contracts. Expand methanol carbonylation capacity at existing Texas-Louisiana sites to exploit shared hydrogen networks and EPA-compliant abatement systems already deployed. Defend against bio-based fermentation substitutes by securing mass-balance chain-of-custody certifications that qualify for California LCFS credits and federal clean hydrogen production tax incentives. For New Entrants and Emerging Players: Modular 50,000-ton-per-year methanol carbonylation units in Ohio and Illinois represent the most penetrable entry point, bypassing pipeline-dependent Gulf Coast supply and compressing freight costs for inland buyers. Target electronics solvents and pharmaceutical intermediates requiring high-purity acetate esters that command price premiums above commodity acid margins. Pursue joint development agreements with membrane separation technology providers to collapse capital cost barriers for carbon monoxide purification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core acetic acid assets amid portfolio rationalization pressures. Long-term viability hinges on carbon intensity accounting integration and low-carbon certification capabilities that align with downstream procurement specifications. Watch for inflection signals in California LCFS credit pricing and federal clean hydrogen production tax credit implementation timelines that would accelerate bio-syngas hybrid pathway investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Celanese and Dow anchor cost leadership through captive methanol production along the Texas-Louisiana corridor. |
| Long-term Supply Agreement | Vinyl acetate monomer producers lock in three-to-five-year contracts with natural gas-indexed pricing to hedge hurricane season volatility. |
| Green Manufacturing Transition | Bio-syngas hybrid carbonylation processes qualify for California LCFS credits and federal clean hydrogen incentives. |
| Capacity Expansion | Membrane separation technology enables modular 50,000-ton-per-year units in Ohio and Illinois bypassing Gulf Coast dependence. |
| Joint Venture | BP-Amoco partnerships combine rhodium-iridium catalyst expertise with shared carbon monoxide purification infrastructure. |
Research Approach
The analysis maps glacial acetic acid, acetate esters, dilute acid, and acetic anhydride segments, each validated through plant managers at Gulf Coast petrochemical complexes, procurement leads at downstream coatings manufacturers, distribution channel partners serving the Great Lakes region, and technical R&D directors specializing in carbonylation catalyst systems. Primary interview insights triangulate against customs and trade data from the American Chemistry Council, SEC 10-K filings from integrated producers, EPA Clean Air Act compliance disclosures, and OSHA exposure limit documentation. Bottom-up capacity and demand modeling reconciles with top-down macroeconomic indicators across the North American chemicals sector.
Assumptions held fixed include EPA Clean Air Act enforcement trajectories, OSHA eight-hour time-weighted average exposure limits, and natural gas feedstock pricing correlations, while methanol carbonylation retrofit timelines and bio-syngas hybrid technology maturation were varied across sensitivity scenarios. Segmentation dimensions span grade tier, end-use industry, technology pathway, and regional production hub. CAGRs derive from capacity utilization trends, derivative demand elasticity, and substitution dynamics across the projection horizon. Industry-specific inputs include vinyl acetate monomer consumption patterns, water-based paint reformulation rates, and fermentation pathway certification premiums.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, construction activity indices, or carbon credit valuation would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines, technology adoption curves, and feedstock market integration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market