
 North America Controlled Release Fertilizer Market | 2026-2036
North America Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Controlled Release Fertilizer Market Analytics
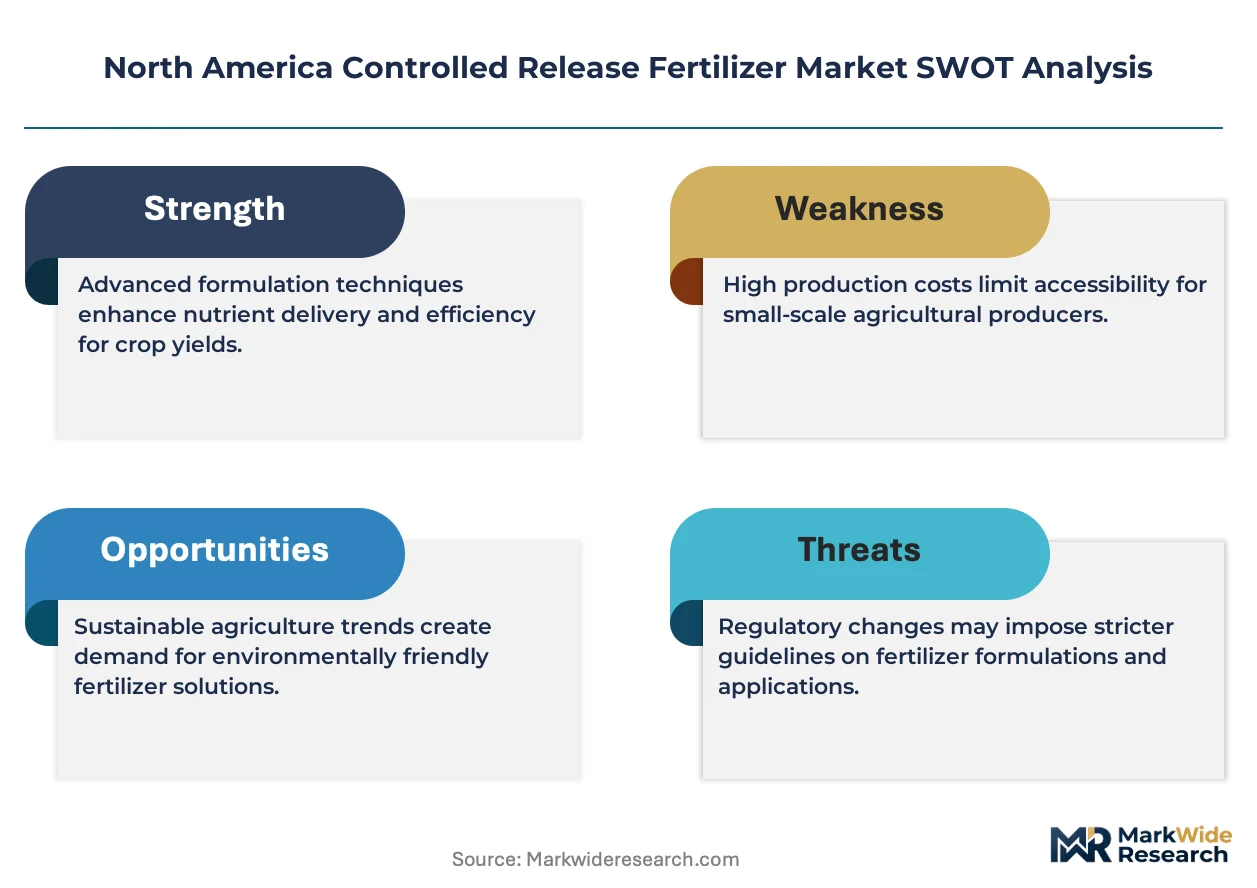
North American fertilizer manufacturing is shifting toward coated and encapsulated production lines as domestic producers respond to import substitution pressures. Nutrien Ltd. leverages its Saskatchewan potash backbone to anchor polymer-coated fertilizer supply chains across the Prairie provinces. ICL Group Ltd. competes through specialty phosphate integration and controlled release R&D facilities in the US Southeast. ScottsMiracle-Gro dominates consumer-facing turf and ornamental channels through retail distribution density.
Controlled release fertilizers deploy polymer membranes, sulfur coatings, or urea-formaldehyde matrices to meter nutrient availability across weeks or months rather than days. Polymer-coated formulations command premium positioning due to predictable release curves and reduced leaching losses in sensitive watersheds. Sulfur-coated urea occupies mature, cost-driven demand among broadacre row crops where price sensitivity limits coating sophistication. Turf and ornamentals generate concentrated margin pools as golf courses and landscape professionals prioritize uniform greening and labor reduction over per-ton nutrient cost.
EPA Clean Water Act provisions and state-level nutrient loss reduction strategies in Illinois, Iowa, and Minnesota shape product registration and application timing. USDA Natural Resources Conservation Service cost-share programs incentivize enhanced efficiency fertilizers on enrolled acreage. FDA food safety audits downstream create traceability expectations that favor documented nutrient management plans. Stakeholders must monitor evolving state fertilizer use restrictions and carbon accounting methodologies that could recast product value propositions.
Market Dynamics
US EPA nutrient loss reduction strategies and state-level 4R Nutrient Stewardship mandates are restructuring product registration timelines and application protocols across the Corn Belt and specialty crop zones.
Growth Catalysts
- 4R Nutrient Stewardship programs:Illinois, Iowa, and Minnesota cost-share initiatives reimburse farmers adopting enhanced efficiency fertilizers on enrolled acreage.
- Precision agriculture targets:California specialty crop producers deploy polymer-coated formulations to meet irrigation efficiency mandates and reduce nitrogen leaching into sensitive watersheds.
- Greenhouse vegetable clusters:Ontario and British Columbia operations integrate controlled release systems to automate nutrient delivery and cut labor inputs.
Market Restraints
- Polymer resin cost volatility:Petroleum-derived coating materials expose manufacturers to feedstock price swings that compress margin pools.
- Saskatchewan potash concentration:North American potassium supply chains hinge on Prairie province extraction, creating geographic vulnerability to rail bottlenecks.
- Sulfur-coated urea substitution ceiling:Broadacre corn-soy operations resist premium polymer upgrades where commodity crop margins limit input expenditure.
Strategic Opportunities
- Florida citrus rehabilitation:Huanglongbing recovery programs create demand for precision nutrient delivery in tree replanting operations.
- Carbon accounting methodologies:Emerging protocols for agricultural emissions verification position documented nutrient management plans as credit-generating assets.
- Drone-enabled topdressing:UAV application services open channel access to mid-size farms previously unreachable through traditional dealer networks.
Industry Challenges
- Formulation chemist scarcity:Polymer science expertise concentrates among legacy agricultural chemical employers, constraining R&D expansion at emerging manufacturers.
- USDA-NRCS enrollment documentation:Cost-share program qualification demands extensive field records that strain agronomic advisory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Controlled Release Fertilizer Market |
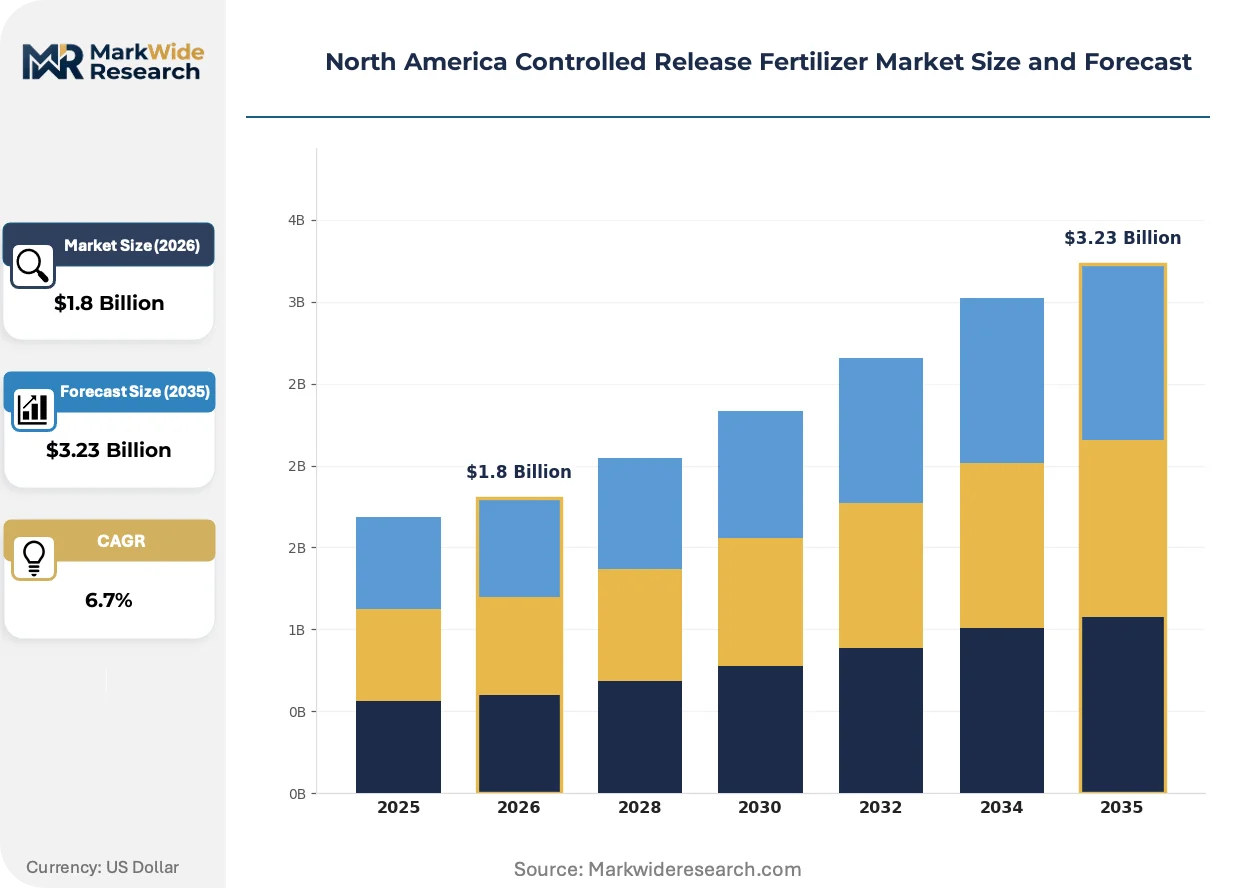
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Formaldehyde, Sulfur-Coated Urea, Polymer-Coated Fertilizer, Osmo-Release Fertilizer Application: Agricultural Crops, Turf and Ornamentals, Horticulture, Greenhouses Delivery Mode: Soil Application, Foliar Spray, Fertigation, Granular End User: Farmers, Retailers, Agricultural Cooperatives, Landscape Professionals |
| Companies Covered | Nutrien Ltd., ICL Group Ltd, Yara International ASA, ScottsMiracle-Gro, Koch Industries, Helena Agri-Enterprises, The Mosaic Company, Haifa Group, Grupa Azoty S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Controlled Release Fertilizer Market Evolving Landscape
Coating chemistry advances and application automation are compressing the performance gap between premium controlled release formulations and conventional fertilizers while expanding addressable farm segments.
Biodegradable polymer membranes derived from polylactic acid and starch blends are electrifying nutrient release predictability in vegetable and turf applications. Golf course superintendents in Arizona and California are adopting these materials to eliminate synthetic residue concerns while maintaining uniform greening. The technology is electrifying contract specifications for municipal park maintenance bids across the US Southwest.
EPA Clean Water Act Section 319 nonpoint source pollution grants are redirecting state fertilizer management programs toward enhanced efficiency product mandates. Industrial consequence includes accelerated product registration reviews for polymer-coated and stabilized nitrogen formulations. The US Midwest row-crop belt faces the most acute compliance pressure, with Minnesota and Iowa requiring documented 4R implementation for watershed district eligibility.
Direct-to-farm digital procurement platforms are consolidating input purchasing decisions among large-scale corn-soy operations. Dealer networks in Nebraska and Kansas face disintermediation as cooperatives and private equity-backed farm operators negotiate volume contracts directly with manufacturers. The shift is most visible among operations exceeding 10,000 acres where agronomic staff internalize fertility planning previously outsourced to retail agronomists.
North America Controlled Release Fertilizer Market Segmentation
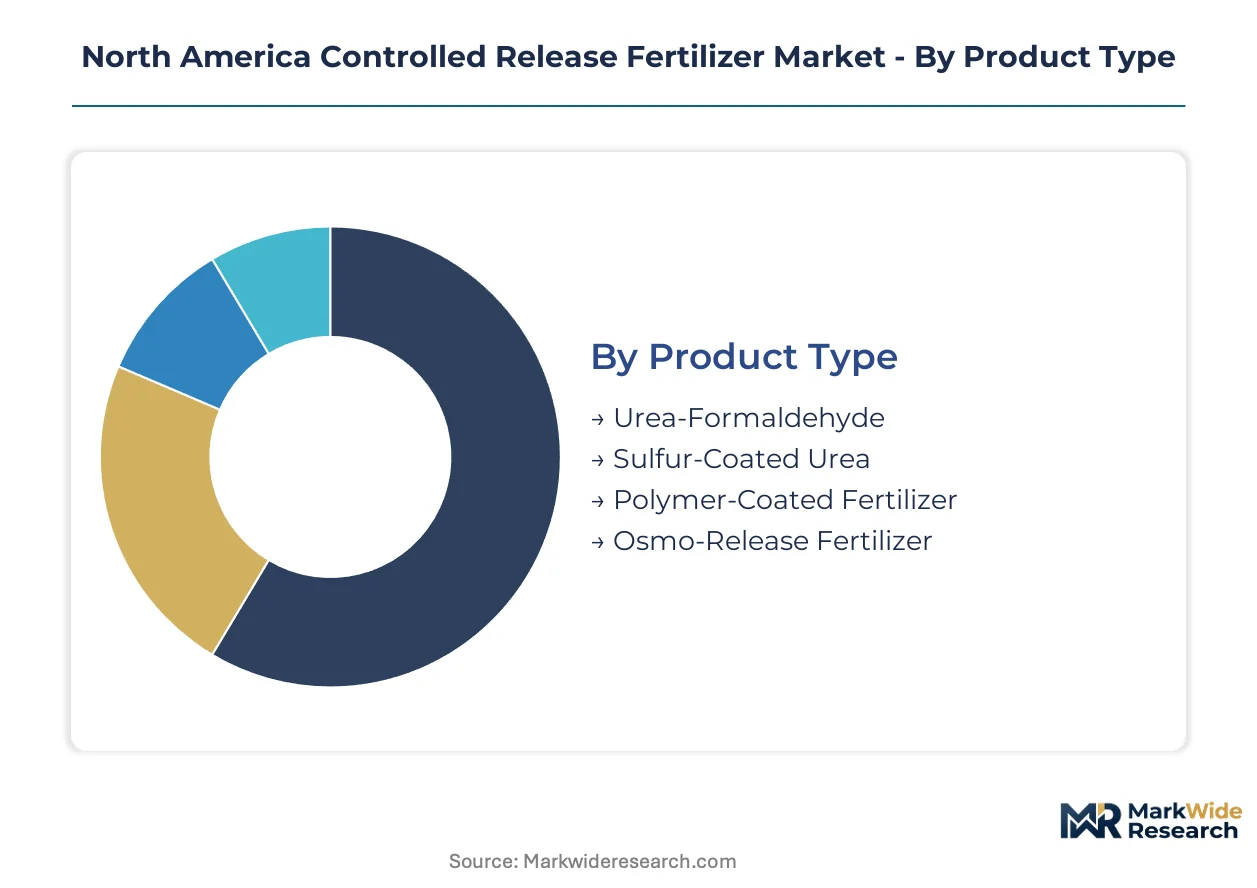
Controlled release fertilizer segmentation in North America tracks divergent buyer priorities across cost-sensitive broadacre operations and premium-seeking specialty crop producers. Understanding these category boundaries clarifies why polymer-coated formulations command margin premiums while sulfur-coated variants dominate volume.
Product Type:
Buyers in this category separate by price tolerance and performance predictability requirements.
- Polymer-Coated Fertilizer:Thermoplastic or resin membranes meter nutrient diffusion across 30-120 day windows with temperature-dependent release curves. California almond and pistachio growers deploy these formulations to comply with Central Valley Regional Water Quality Control Board nitrate leaching limits.
- Sulfur-Coated Urea:Molten sulfur barriers encapsulate urea prills, creating 6-12 week release profiles at roughly half the polymer cost. Iowa and Illinois corn-soy operations purchase sulfur-coated variants through USDA-NRCS cost-share programs where per-acre input ceilings constrain coating sophistication.
- Urea-Formaldehyde:Methylene-urea condensation products deliver nitrogen through microbial degradation rather than physical barrier dissolution. Golf course superintendents in Arizona specify these materials for fairway maintenance where synthetic polymer residues trigger municipal contract scrutiny.
- Osmo-Release Fertilizer:Semi-permeable membranes respond to soil moisture gradients rather than temperature alone. British Columbia greenhouse tomato operations integrate osmo-release systems with drip irrigation automation to synchronize nutrient pulses with plant uptake cycles.
Polymer-coated formulations lead volumes today; osmo-release variants are gaining share fastest among precision agriculture adopters.
Application:
Application-based segmentation reflects divergent labor economics and environmental compliance exposure across end-uses.
- Turf and Ornamentals:Golf courses, municipal parks, and landscape maintenance operations prioritize uniform greening and reduced mowing frequency over per-ton nutrient cost. Florida retirement community common areas specify controlled release products to minimize grounds crew labor inputs.
- Agricultural Crops:Corn, soybean, and wheat producers in Minnesota and Wisconsin face Minnesota Department of Agriculture fertilizer management certification requirements that favor documented enhanced efficiency product use. These buyers balance yield response against commodity price volatility when selecting coating tiers.
- Horticulture:Container nursery operations in Oregon and Washington deploy controlled release to reduce irrigation runoff and extend feeding intervals between potting cycles.
- Greenhouses:Ontario pepper and cucumber producers integrate controlled release substrates with automated climate control to eliminate manual fertigation labor.
Turf and ornamentals concentrate margin pools; greenhouse applications are expanding most quickly as protected agriculture acreage climbs.
Delivery Mode:
Delivery mode selection hinges on existing equipment infrastructure and precision placement requirements.
- Soil Application:Broadcast or banded incorporation remains dominant across US Midwest row-crop operations where conventional spreader fleets limit delivery flexibility.
- Fertigation:Liquid or soluble controlled release formulations inject through drip and pivot systems. Central Valley vegetable producers pair fertigation with soil moisture sensors to time nutrient pulses with crop demand curves.
- Foliar Spray:Micronutrient-enriched controlled release suspensions address mid-season deficiency correction in high-value potato and sugar beet crops.
- Granular:Physical prill or pellet forms suit mechanical spreader compatibility and storage stability requirements across Prairie province grain operations.
Soil application dominates tonnage; fertigation is climbing the fastest as irrigation infrastructure modernizes.
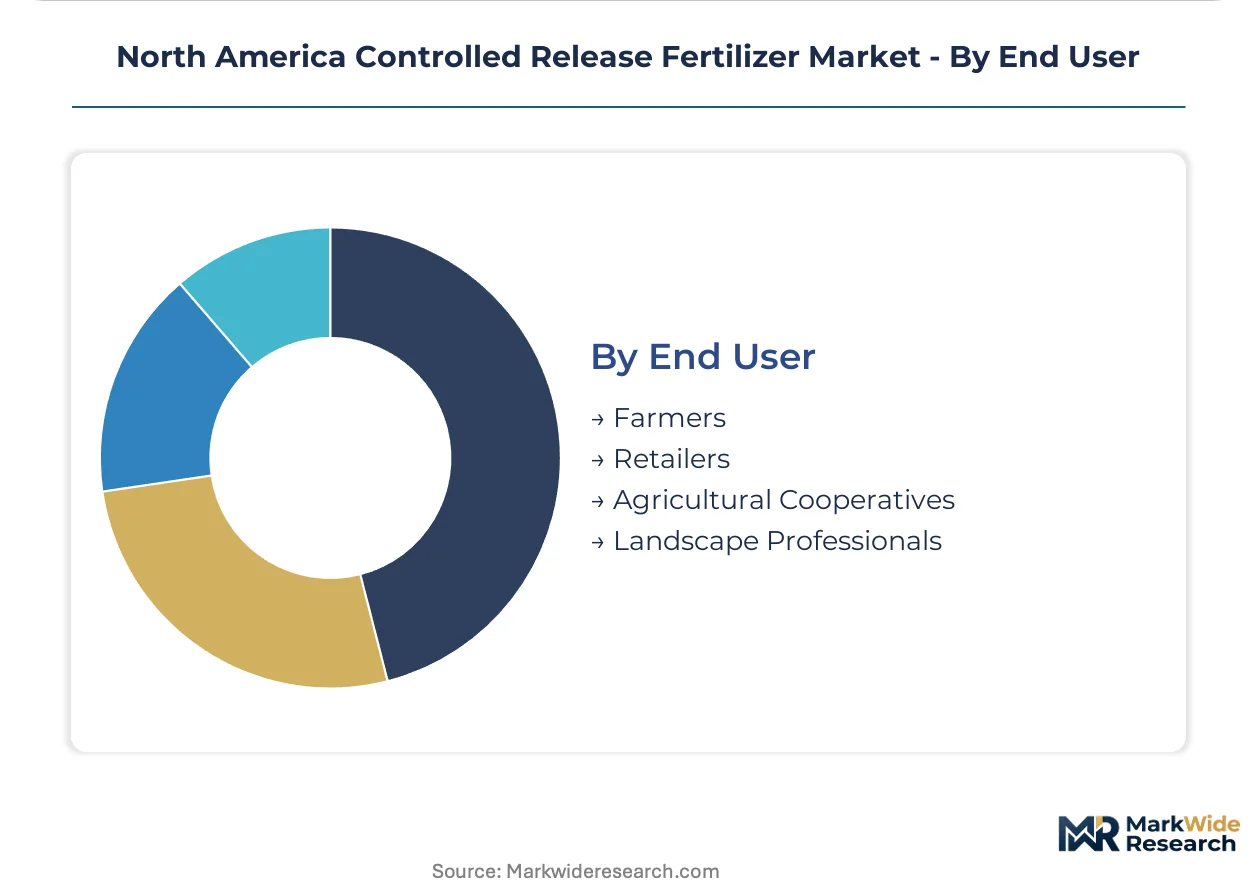
End User:
End user categories separate by procurement scale, technical sophistication, and advisory dependency.
- Farmers:Owner-operators below 2,000 acres rely on retail agronomist recommendations and cooperative volume purchasing to access controlled release products.
- Agricultural Cooperatives:CHS and Growmark member systems aggregate demand across thousands of patrons to negotiate direct manufacturer contracts and private-label coating specifications.
- Retailers:Independent farm supply dealers in Nebraska and Kansas face margin compression as large operators bypass traditional distribution through digital procurement platforms.
- Landscape Professionals:Commercial maintenance contractors and golf course superintendents purchase through specialty turf distribution channels where technical service relationships outweigh price sensitivity.
Agricultural cooperatives lead volume procurement; landscape professionals generate the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers relocate coating operations to jurisdictions with streamlined EPA registration pathways and lower compliance overhead relative to European REACH-equivalent regimes.
United States
Illinois and Iowa corn-soy operations drive sulfur-coated urea volumes through USDA-NRCS Environmental Quality Incentives Program reimbursements. The EPA's Clean Water Act Section 319 grants mandate documented 4R Nutrient Stewardship for watershed district eligibility. Minnesota's Red River Valley grain belt concentrates polymer-coated adoption where nitrate leaching limits tighten fastest.
Canada
Ontario greenhouse vegetable clusters integrate osmo-release systems with automated climate control to cut labor inputs in pepper and cucumber production. Health Canada's PMRA maintains accelerated review pathways for enhanced efficiency fertilizers meeting reduced-risk criteria. Saskatchewan's Prairie potash belt anchors Nutrien Ltd.'s polymer-coated supply chains serving Prairie province grain operations.
Mexico
Sinaloa and Sonora vegetable export zones deploy controlled release to meet US buyer traceability requirements under FDA food safety audits. The country's national agricultural regulator supports fertilizer efficiency programs targeting irrigation districts in water-stressed northern states. Guanajuato's berry production corridor is adopting polymer-coated formulations to reduce fertigation frequency in high-value raspberry and blackberry operations.
North America Controlled Release Fertilizer Market Competitive Landscape
Canadian producers anchor one tier through captive potash integration; US Southeast specialists hold polymer R&D concentration. The vendor base separates into three tiers: integrated nutrient majors with coating capabilities, regional blenders serving cost-share program channels, and turf-focused distributors with technical service relationships. Consolidation pressure concentrates among mid-scale blenders as direct procurement platforms disintermediate traditional dealer networks. Capacity expansion and portfolio diversification dominate competitive moves as players respond to import substitution incentives.
Within the integrated nutrient tier, Nutrien Ltd. exemplifies Prairie-based vertical control over potash-to-coating supply chains. ICL Group Ltd. occupies a position among specialty phosphate-integrated players with US Southeast R&D concentration. ScottsMiracle-Gro represents the consumer-facing archetype through retail distribution density in turf and ornamental channels.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| ICL Group Ltd |
| Yara International ASA |
| ScottsMiracle-Gro |
| Koch Industries |
| Helena Agri-Enterprises |
| The Mosaic Company |
| Haifa Group |
| Grupa Azoty S.A. |
| Others |
Value Network & Pricing Analysis
US Midwest corn-soy cooperatives purchasing through USDA-NRCS cost-share channels anchor North American controlled release fertilizer pricing around volume-tiered contract structures rather than spot-market premiums. Their procurement scale forces manufacturers into competitive bidding formats that compress coating-tier margins while shifting price differentiation toward technical advisory bundling.
Pricing Analysis
Distributor margins in the agricultural channel typically absorb 12-18 percentage points before farm-gate delivery, with cooperative direct-buying programs compressing this layer for qualifying acreage. Price differentiation separates polymer-coated premium tiers from sulfur-coated standard offerings based on leaching predictability and documented 4R compliance value. Cost compression in sulfur-coated urea is intensifying because petroleum-derived resin feedstock volatility has manufacturers hedging through long-term polymer supply agreements. Broadacre row-crop operations in Illinois and Iowa exhibit the highest price sensitivity, while Florida turf maintenance contractors prioritize labor-reduction value over per-ton nutrient cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from California almond processors and Ontario greenhouse cooperatives force coating manufacturers to maintain redundant polymer resin suppliers across domestic and import channels. Geographic supply concentration centers on Saskatchewan for potash backbone, Texas and Louisiana for petrochemical-derived coating materials, and Ohio for sulfur processing infrastructure. Raw material dependencies include thermoplastic resins, molten sulfur feedstock, and urea prill substrates sourced from integrated ammonia operations. Tariff exposure on imported polymer precursors creates margin vulnerability for non-vertically integrated blenders. Distribution runs through agricultural cooperative networks in the Prairie provinces and independent dealer systems in the US Corn Belt, with direct-to-farm digital platforms disintermediating traditional retail layers among operations exceeding 5,000 acres.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American controlled release fertilizer demand has shifted decisively toward polymer-coated and biodegradable membrane specifications as watershed district eligibility rules harden around documented nitrate leaching reduction. This quality migration rewards manufacturers with coating R&D depth and punishes commodity sulfur-coated blenders.
For Market Incumbents: Hedge against sulfur-coated urea substitution ceilings by accelerating biodegradable polymer pilot lines for California and Arizona turf markets where municipal contract specifications now exclude synthetic residue concerns. Backward integration into Saskatchewan potash processing or Texas petrochemical supply agreements secures margin control against feedstock volatility. Channel control through exclusive agronomic advisory relationships defends positioning as direct-procurement platforms disintermediate traditional dealer networks among large-scale operators. For New Entrants and Emerging Players: Launch via drone-enabled application service partnerships targeting mid-size Midwest farms below 2,000 acres that remain unreachable through cooperative volume channels. White-space concentrates in Florida citrus rehabilitation zones where Huanglongbing recovery programs demand precision nutrient delivery for tree replanting operations, and in British Columbia greenhouse clusters integrating osmo-release systems with automated climate control. A technical service-led go-to-market angle bypasses price-driven commodity competition by embedding formulation expertise into subscription-based fertility planning. For Investors and Strategic Acquirers: Agricultural cooperatives with captive member demand and private equity-backed farm operators consolidating acreage are the most active acquirer categories in this space, seeking coating capabilities to internalize margin pools. The five-to-ten-year viability window favors targets with EPA Section 319 grant alignment and documented 4R implementation track records. Acquisition target archetypes include mid-scale blenders with USDA-NRCS enrollment expertise and regional polymer-coating specialists serving specialty crop zones. Monitor carbon accounting methodology finalization from the USDA and state agricultural departments as the inflection signal that recasts nutrient management plans as credit-generating assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Capacity Expansion | California municipal turf contracts now exclude synthetic membrane residues, redirecting R&D budgets toward polylactic acid and starch-blend coating lines. |
| Backward Integration into Potash Processing | Saskatchewan extraction assets anchor supply security for Prairie province cooperative networks facing rail bottleneck vulnerability. |
| Direct-to-Farm Digital Platform Launch | Nebraska and Kansas operations exceeding 10,000 acres now bypass dealer networks through manufacturer-negotiated volume contracts. |
| Drone-Enabled Application Service Partnership | UAV topdressing services open channel access to mid-size farms previously dependent on retail agronomist recommendations. |
| Carbon Accounting Certification Investment | Documented 4R Nutrient Stewardship plans position controlled release formulations as agricultural emissions credit assets under emerging verification protocols. |
Research Methodology
Bottom-up acreage adoption modeling reconciled against top-down coating capacity tracking forms the analytical core of this study. Primary interviews with fertilizer formulation chemists, agricultural cooperative procurement directors, EPA regional water quality staff, and turf maintenance contractors informed demand-side assumptions. Secondary validation drew from USDA-NRCS program enrollment databases, EPA Clean Water Act Section 319 grant disbursement records, Health Canada PMRA registration filings, and state-level 4R implementation reports. Triangulation across these sources calibrated polymer-coated versus sulfur-coated adoption rates by crop type and geography.
Historical trendline analysis of coating technology penetration rates across the Corn Belt and specialty crop zones established baseline growth patterns. The projection framework segments demand by product type, application end-use, delivery mode, and end-user procurement scale, with CAGRs derived from regression-adjusted trend extrapolation moderated by regulatory implementation timelines. Key forecast inputs include EPA nutrient loss reduction strategy enforcement intensity, Illinois and Iowa cost-share program budget trajectories, and biodegradable polymer cost curves relative to conventional resin formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in commodity crop margins or federal cost-share funding suspension. Assumptions regarding 4R Nutrient Stewardship mandate expansion and carbon credit market development shape trajectory sensitivity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
United States Fertilizers Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market