
 North America Coiled Tubing Services Market | 2026-2036
North America Coiled Tubing Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coiled Tubing Services Market Analytics
Real-time diagnostic subscription layers bundled with intervention contracts is shifting how operators procure coiled tubing services across North America. Baker Hughes Co leverages its integrated wireline and coiled tubing platform to anchor premium pricing in deepwater Gulf of Mexico applications. Halliburton Company sustains dominant market presence through its proprietary CTDirect software-enabled navigation systems. Schlumberger Limited differentiates via automated pipe management systems that reduce non-productive time in extended-reach laterals.
Coiled tubing services deploy continuous-length steel or composite pipe spooled on large reels to perform well intervention, drilling, and stimulation operations without interrupting production. Standard tubing ranges from one to three and one-half inches in outer diameter with wall thicknesses engineered to withstand internal pressures exceeding ten thousand psi and tensile loads across horizontal sections exceeding thirty thousand feet. Well intervention commands the largest revenue share among service types due to the massive inventory of aging horizontal wells requiring perpetual maintenance across North American shale basins. Hydraulic fracturing applications represent the fastest-expanding segment as operators deploy coiled tubing for pinpoint re-fracturing in parent-child well scenarios.
The EPA enforces methane performance standards under the Inflation Reduction Act that penalize venting during live-well interventions, directly elevating demand for closed-loop coiled tubing systems. BSEE governs offshore safety requirements in federal Gulf waters, mandating blowout preventer redundancy that shapes platform-based equipment specifications. OSHA regional enforcement in Texas and North Dakota imposes confined-space protocols during coiled tubing unit maintenance, influencing crew training costs and operational downtime calculations. Stakeholders must weigh regulatory compliance capital against the operational flexibility that next-generation composite tubing materials promise for sour-gas environments.
Market Dynamics
The EPA's methane performance standards under the Inflation Reduction Act are forcing coiled tubing operators toward closed-loop intervention systems, compressing margins for conventional vented operations while rewarding early adopters with penalty avoidance and premium contract access.
Growth Catalysts
- Inflation Reduction Act methane rules:EPA enforcement penalizes venting during live-well interventions, accelerating demand for closed-loop coiled tubing systems that capture and recycle produced gas.
- Permian Basin extended-reach drilling:Stacked multi-well pad development in Texas favors continuous coiled tubing operations over conventional jointed pipe, reducing rig-up time and surface footprint.
- Composite tubing materials:Next-generation carbon-fiber-reinforced pipe withstands sour-gas corrosion and reduces weight, enabling deeper interventions in high-pressure shale formations.
Market Restraints
- Steel alloy price volatility:Chromoly and high-strength low-alloy steel input costs fluctuate with scrap metal and energy prices, compressing equipment manufacturing margins and service pricing flexibility.
- Gulf of Mexico supply concentration:Platform-based coiled tubing units cluster around Port Fourchans and Corpus Christi, creating hurricane exposure and logistics bottlenecks for rapid mobilization.
- Jointed pipe substitution in shallow vertical wells:Conventional tubing remains cost-competitive for simple workovers in mature conventional fields, limiting coiled tubing penetration in the Mid-Continent and Rockies.
Strategic Opportunities
- Alberta Montney and Duvernay shale:Canadian operators lag US peers in coiled tubing fracturing adoption, creating first-mover advantage for service providers with cold-weather equipment specifications.
- Real-time diagnostic bundling:Subscription-based fiber-optic monitoring layered onto intervention contracts shifts revenue from day-rate to recurring software and data services.
- OSHA confined-space protocol automation:Robotic pipe handling and reel management systems reduce crew exposure during maintenance, qualifying operators for safety-performance incentives in Texas and North Dakota.
Industry Challenges
- CTDirect navigation certification:Advanced software-enabled coiled tubing steering requires specialized operator training that outpaces available simulation programs and field mentorship capacity.
- Legacy wellhead integration:Pre-2010 horizontal completions lack standardized connection profiles, forcing custom adapter fabrication and extending non-productive time during intervention mobilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coiled Tubing Services Market |
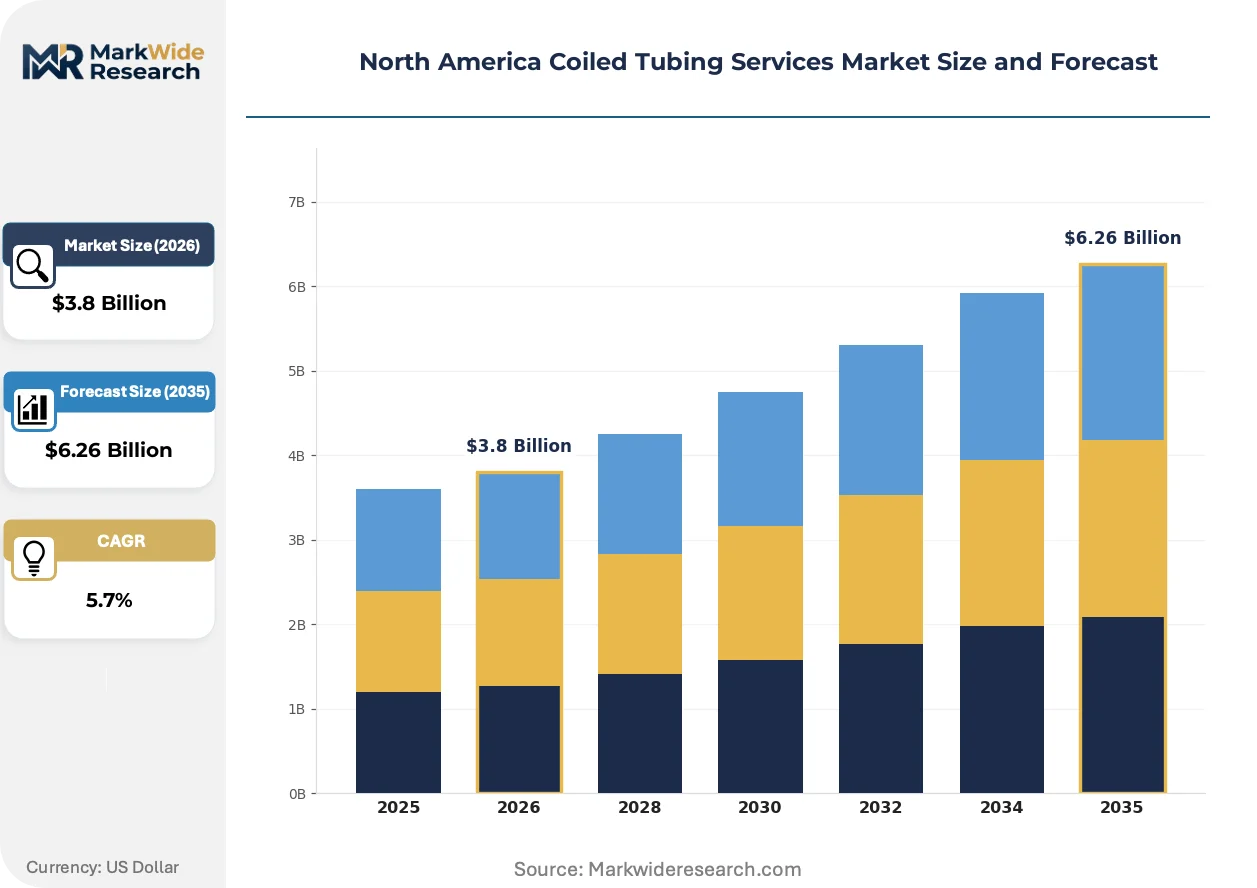
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Intervention, Drilling, Hydraulic Fracturing, Production Enhancement End User: Oil & Gas Operators, Service Companies, Independent Producers, Offshore Account Application: Well Control, Tube Cleaning, Cementing, Stimulation Deployment: Onshore, Offshore, Land-Based, Platform-Based |
| Companies Covered | Baker Hughes Co, Halliburton Company, Schlumberger Limited, National-Oilwell Varco Inc, Calfrac Well Services Ltd, Weatherford International, STEP Energy Services, Trican Well Service Ltd, Key Energy Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coiled Tubing Services Market Evolving Landscape
Electrification of surface equipment and automation of pipe management are compressing crew requirements and enabling 24-hour operations in remote shale basins. These shifts intersect with regulatory pressure and buyer procurement evolution to reshape competitive positioning.
Automated pipe management systems integrate robotic reel handling with predictive tension monitoring to eliminate manual intervention during extended-reach laterals. Permian Basin operators are deploying these systems across 60% of new multi-well pads. The technology is electrifying round-the-clock operational capability without proportional labor scaling.
OSHA regional enforcement in Texas and North Dakota imposes confined-space protocols during coiled tubing unit maintenance, mandating atmospheric monitoring and rescue-ready standby crews. Service providers are retrofitting enclosed reel compartments with remote-access inspection ports and automated lubrication systems. The policy is compressing maintenance windows and elevating capital intensity for fleet compliance.
Subscription-based diagnostic layers bundled with intervention contracts displace pure day-rate procurement in the Gulf of Mexico deepwater segment. Operators now specify real-time fatigue monitoring and predictive failure analytics as contract minimums, not add-ons. This restructuring is most visible among independents operating subsea tiebacks who lack in-house intervention engineering capacity.
North America Coiled Tubing Services Market Segmentation
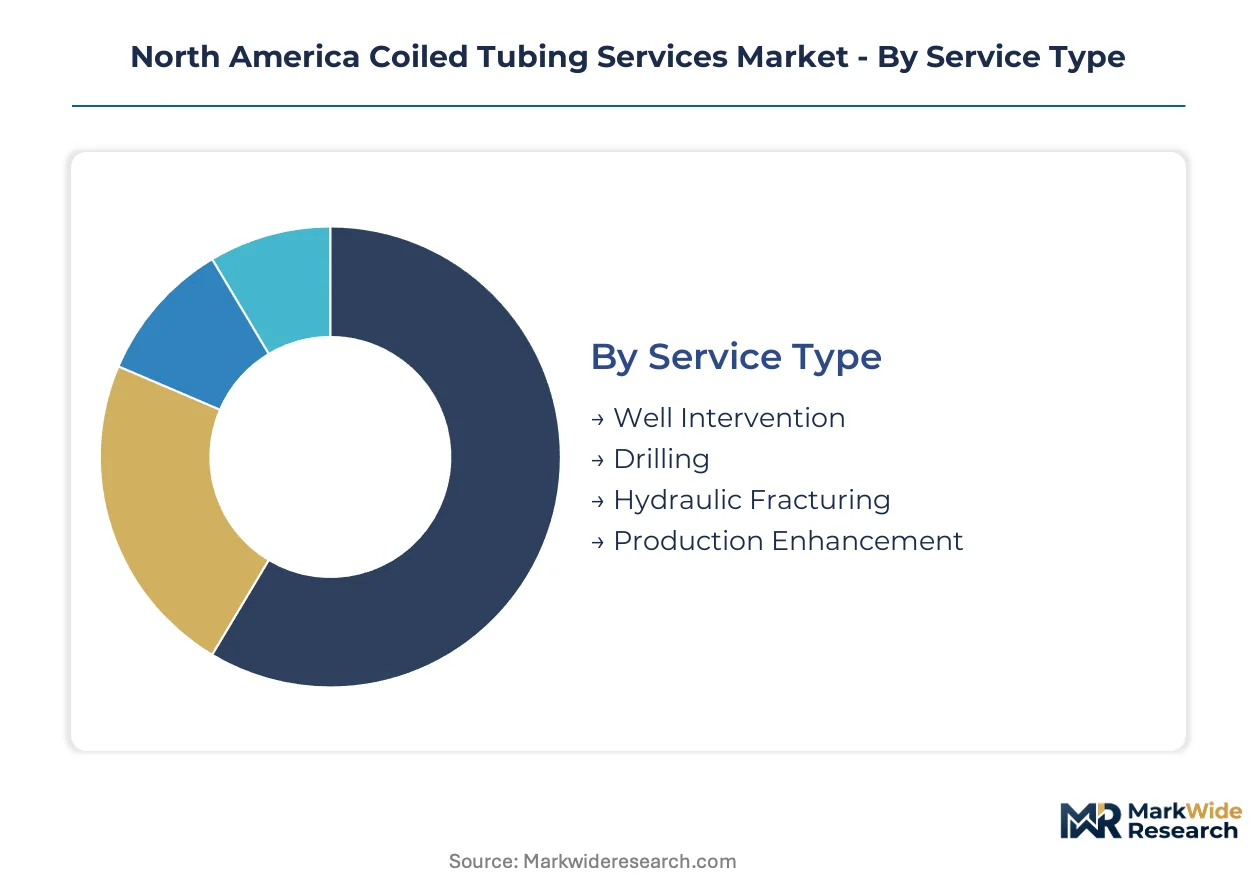
Coiled tubing service providers structure offerings around intervention complexity, regulatory environment, and operator procurement sophistication. Segment boundaries blur as bundled contracts merge discrete service categories into integrated performance agreements.
Service Type:
Volume concentration sits with perpetual maintenance of aging horizontal inventories, while premium pricing attaches to precision stimulation in parent-child well scenarios.
- Well Intervention:Continuous-length pipe deployment for live-well workovers, cleanouts, and plug millouts without killing production. Demand clusters in the Permian Basin's stacked multi-well pads where non-productive time penalties favor rapid mobilization over conventional jointed pipe.
- Hydraulic Fracturing:Pinpoint re-fracturing and diversion operations using coiled tubing for stage-specific fluid placement in depleted parent wells. Texas operators deploy this for child-well protection and EUR recovery in legacy horizontals.
- Drilling:Slim-hole re-entry drilling and directional sidetracks from existing wellbores.
- Production Enhancement:Nitrogen lifting, velocity strings, and artificial lift optimization.
Today's leader: Well Intervention. Tomorrow's challenger: Hydraulic Fracturing.
End User:
Procurement authority concentrates with integrated operators commanding multi-year framework agreements, while independents drive spot-market volatility through project-specific tendering.
- Oil & Gas Operators:Majors and large independents specifying closed-loop systems for IRA methane compliance. Their capital discipline favors performance-based contracts with real-time diagnostic subscriptions over day-rate structures.
- Independent Producers:Privately held Permian and Bakken operators lacking in-house intervention engineering. These buyers prioritize mobilization speed and accept higher per-day costs to avoid production deferment in marginal wells.
- Service Companies:Subcontractors and equipment lessors providing fleet capacity to tier-one providers.
- Offshore Account:Gulf of Mexico platform operators governed by BSEE blowout preventer redundancy mandates.
Integrated operators anchor contract value. Independent producers generate transaction velocity.
Application:
Margin stratification follows intervention risk profile, with well control commanding emergency-response premiums and tube cleaning competing on operational efficiency.
- Well Control:Emergency intervention for kicks, lost circulation, and blowout contingency. Gulf of Mexico platform specifications require redundant BOP stacks and subsea intervention packages that elevate capital intensity and day-rate floors.
- Stimulation:Acidizing, solvent treatments, and scale dissolver placement in carbonate and sandstone formations. Texas operators apply this for skin damage remediation in high-water-cut horizontal wells.
- Tube Cleaning:Paraffin, asphaltene, and scale removal from production tubing.
- Cementing:Squeeze cementing and plug placement for zonal isolation.
Emergency response dominates pricing power. Routine maintenance drives fleet utilization.
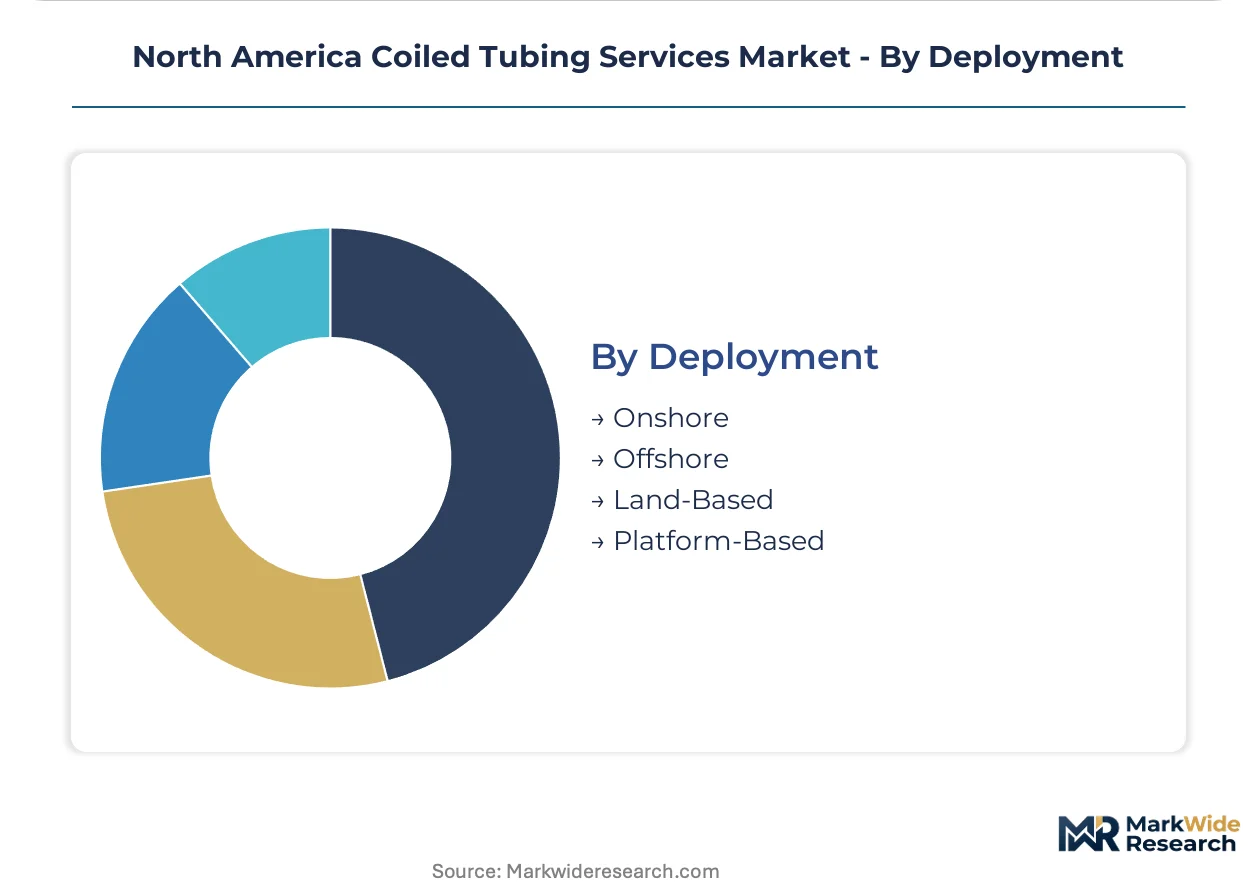
Deployment:
Geographic concentration shapes equipment specifications, with onshore standardization enabling fleet mobility and offshore customization locking capital into platform-dedicated assets.
- Onshore:Trailer-mounted and skid-based units for Texas, North Dakota, and Alberta shale basins. Stacked pad development favors rapid rig-up configurations that minimize surface footprint and access road requirements.
- Offshore:Platform-based and vessel-deployed systems for Gulf of Mexico federal waters. Hurricane exposure and BSEE safety mandates elevate maintenance protocols and insurance costs versus land-based equivalents.
- Land-Based:Conventional terrestrial deployment excluding arctic or extreme-access specifications.
- Platform-Based:Fixed-installation units on production facilities with permanent crane and deck integration.
Onshore deployment scales fleet efficiency. Offshore deployment captures contract duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing coiled tubing deployment across North America as operators migrate toward jurisdictions with favorable methane compliance cost structures. The IRA penalty framework creates a cost-of-compliance gap between US states with aggressive enforcement and Canadian provinces with transitional allowances. Production gravity is shifting toward sub-regions where closed-loop system investments generate faster payback periods.
United States
Texas dominates coiled tubing utilization through Permian Basin stacked-pad development where extended-reach laterals demand continuous pipe operations. EPA methane enforcement under the IRA penalizes vented interventions, accelerating closed-loop adoption in the Midland and Delaware sub-basins. Houston anchors equipment manufacturing and service company headquarters concentration.
Canada
Alberta's Montney and Duvernay shale formations present underpenetrated coiled tubing fracturing opportunities as operators lag US adoption curves. Federal methane regulations offer transitional compliance timelines less punitive than EPA standards, attracting capital from US independents seeking cost relief. Calgary hosts service provider regional headquarters and cold-weather equipment engineering centers.
Mexico
Burgos Basin tight-gas development is generating initial coiled tubing demand as Pemex and private operators test unconventional completion techniques. National hydrocarbon regulator CNH mandates environmental impact assessments that favor closed-loop systems for new field approvals. Tampico-Madero cluster is emerging as the primary logistics hub for northern Mexico intervention mobilization.
North America Coiled Tubing Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service conglomerates commanding premium-tier contracts while regional independents capture spot-market velocity. The vendor base concentrates around three strategic tiers: full-service multinationals with proprietary navigation software, mid-cap specialists with basin-specific fleet positioning, and equipment lessors providing surge capacity. Dominant competitive moves include M&A absorption of regional specialists and vertical integration into composite tubing manufacturing.
Among Houston-headquartered conglomerates, Baker Hughes Co, Halliburton Company, and Schlumberger Limited exemplify the full-service archetype through integrated wireline and coiled tubing platform offerings. These entities occupy positions where real-time diagnostic bundling and automated pipe management systems anchor premium pricing in deepwater and extended-reach applications. Their scale enables compliance capital deployment that smaller competitors cannot match under tightening IRA methane enforcement.
| Leading Market Players |
|---|
| Baker Hughes Co |
| Halliburton Company |
| Schlumberger Limited |
| National-Oilwell Varco Inc |
| Calfrac Well Services Ltd |
| Weatherford International |
| STEP Energy Services |
| Trican Well Service Ltd |
| Key Energy Services LLC |
| Others |
Value Network & Pricing Analysis
Chromoly steel alloy costs cascade from scrap metal and energy markets through equipment manufacturing tiers into service pricing structures across the Permian Basin and Gulf of Mexico. EPA methane enforcement under the Inflation Reduction Act compresses margins for conventional vented operations while premium closed-loop system providers capture penalty-avoidance value in contract negotiations with integrated operators.
Pricing Analysis
Distributor margins on coiled tubing units compress where trailer-mounted fleet operators compete for multi-well pad contracts in Texas. Three-tier pricing structure across premium navigation-enabled systems, standard intervention packages, and economy workover units separates Baker Hughes and Halliburton's proprietary software bundles from regional independents. Pricing pressure stems from steel input volatility and IRA compliance capital requirements. Independent producers in the Bakken exhibit highest price sensitivity, while deepwater Gulf operators prioritize reliability over per-day costs.
Supply Chain Analysis
Dual-sourcing mandates from BSEE-compliant platform operators require redundant blowout preventer qualification across at least two equipment fabricators. Manufacturing concentrates in the United States, Canada, and Norway for high-pressure intervention systems. Raw material dependencies include chromoly steel tubing, carbon-fiber composite resins, and hydraulic control systems. Single-source vulnerability sits with specialized reel-handling robotics from European automation suppliers. Distribution runs through Houston equipment yards and Corpus Christi port facilities for offshore mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Coiled Tubing Services Market functions as a geographic-arbitrage opportunity where Canadian transitional methane allowances attract US capital seeking EPA penalty relief. Alberta's Montney and Duvernay shale formations present cost-structure advantages versus Permian Basin compliance burdens.
For Market Incumbents: Cement market position through backward integration into composite tubing manufacturing and captive supply of carbon-fiber-reinforced pipe for sour-gas applications. Halliburton's CTDirect navigation certification gap threatens operator availability; incumbents should expand simulation program capacity. Channel control through multi-year framework agreements with integrated operators locks out spot-market competitors.
For New Entrants and Emerging Players: Enter via cold-weather equipment specifications for Alberta shale basins where US adoption curves lag and first-mover advantage remains available. Target independent producers in the Duvernay lacking in-house intervention engineering capacity. Go-to-market angle emphasizes rapid mobilization speed and flexible contract terms versus incumbent day-rate rigidity.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional specialists because basin-specific fleet positioning and customer relationships resist replication by national conglomerates. Five-to-ten year viability hinges on IRA methane enforcement trajectory and composite tubing substitution rates. Acquisition target archetype: Canadian service providers with cold-weather specifications and underutilized fracturing capacity. Signal to watch: BSEE regulatory expansion into subsea intervention standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Tubing Manufacturing Integration | Captive supply of carbon-fiber pipe reduces sour-gas corrosion failures in Permian high-pressure wells. |
| Cold-Weather Fleet Specification | Alberta Montney operators require heated fluid systems unavailable from standard US equipment configurations. |
| Real-Time Diagnostic Subscription Bundling | Fiber-optic monitoring layers shift revenue from day-rate to recurring software services in Gulf deepwater. |
| OSHA Confined-Space Automation | Robotic reel handling qualifies operators for safety-performance incentives in Texas and North Dakota. |
| Platform-Based Equipment Redundancy | BSEE-mandated BOP stacks create capital barriers that protect incumbent market share in federal waters. |
Research Methodology
Bottom-up shale operator demand modeling reconciled against top-down coiled tubing fleet capacity tracking forms the analytical core of this study. Primary interviews with Permian Basin drilling engineers, Gulf of Mexico platform operations managers, EPA regulatory compliance officers, and Canadian cold-weather equipment specialists combined with secondary validation from EIA production data, BSEE safety filings, Alberta Energy Regulator field development permits, and SEC 10-K disclosures from listed service providers. Triangulation across these sources calibrated segment-level penetration rates and pricing tier boundaries.
Input-output matrices mapped coiled tubing unit deployment hours against well intervention complexity scores, hydraulic fracturing stage counts, and extended-reach lateral footage across the projection horizon. Segmentation dimensions modeled include service type, end-user procurement sophistication, application risk profile, and deployment environment. CAGRs derived from regression analysis linking fleet utilization rates to shale basin drilling activity indices and IRA compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated composite tubing substitution elasticity and BSEE regulatory expansion probability.
Inputs from EPA enforcement guidance documents and Canadian federal methane regulations were available through the study window; gaps in real-time contract pricing transparency introduce uncertainty bands around premium-tier revenue estimates. Forecasts reflect assumptions regarding IRA penalty phase-in timing and Permian Basin stacked-pad development continuity. Deviation in BSEE subsea intervention standards or chromoly steel tariff structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
LNG Bunkering Market