
 Uzbekistan Oil and Gas Market | 2026-2036
Uzbekistan Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Oil and Gas Market Analytics
Uzbekistan's updated Subsoil Use Code is realigning the cost-of-entry calculus for international operators seeking upstream access. JSC Uzbekneftegaz leverages its dominant position across the majority of producing acreage and pipeline infrastructure. TotalEnergies SE anchors its presence through the Aral Sea exploration block and gas-to-liquids partnerships. Lukoil Uzbekistan Operating Co. specializes in mature field rehabilitation and enhanced recovery techniques in the Bukhara region.
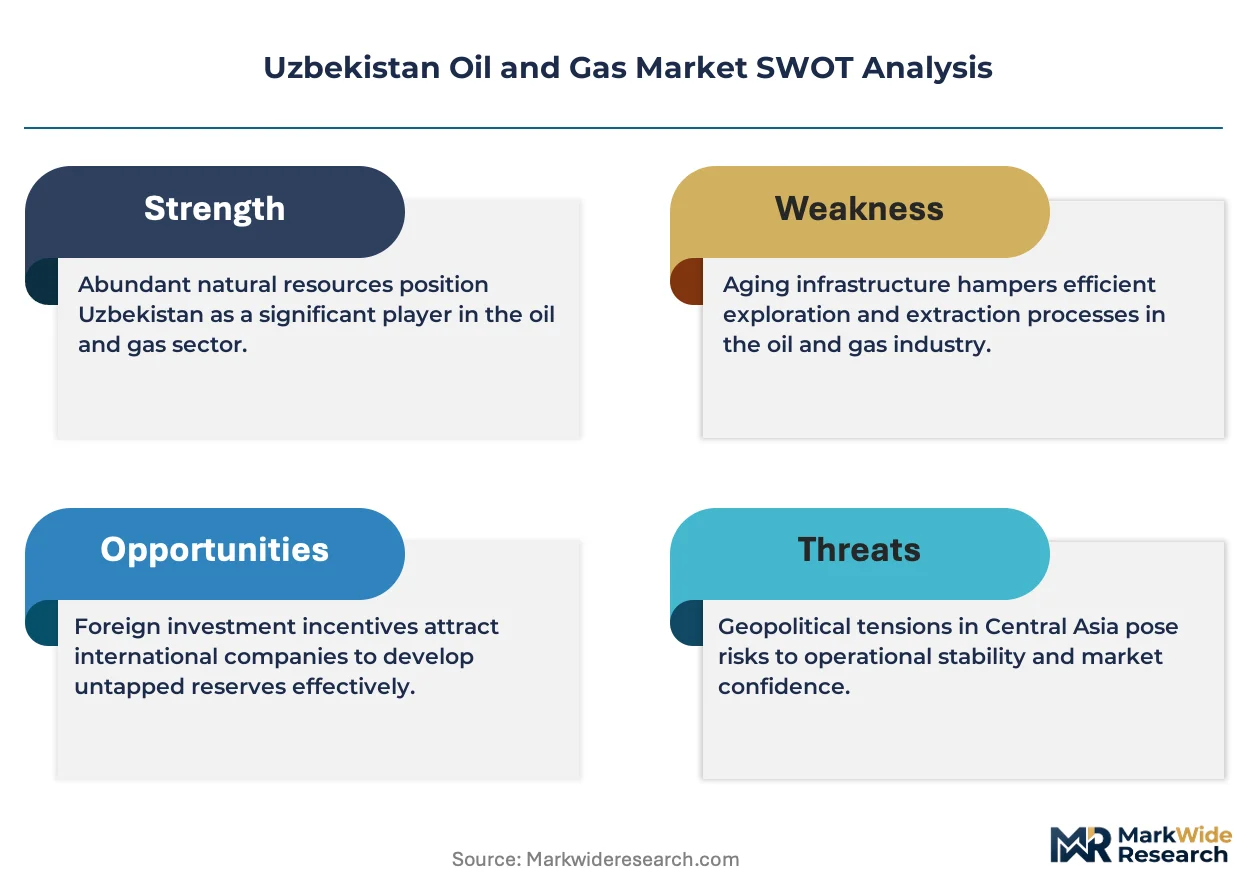
Uzbekistan oil and gas encompasses hydrocarbon exploration, extraction, processing, and distribution of crude oil, natural gas, and associated products with sulfur content specifications typically below 0.5 percent for domestic refined fuels. The sector serves power generation, petrochemical feedstock supply, and residential heating across Central Asian distribution networks. Natural gas dominates product type volumes given Uzbekistan's estimated 1.8 trillion cubic meters of proven reserves, while crude oil output remains constrained by aging Soviet-era infrastructure requiring modernization. Exploration services within the service type dimension attract the most capital commitment as international partners seek untapped reserves in the Ustyurt Plateau and South Turgay Basin.
The State Committee for Geology and Mineral Resources administers licensing rounds and production-sharing contract terms, while Uztransgaz JSC operates under directives from the Ministry of Energy that mandate domestic supply obligations before export allocation. The country's technical regulation framework aligns equipment standards with GB-influenced specifications from Chinese project finance partners, creating dual-compliance requirements for contractors. Stakeholders must monitor how Tashkent balances foreign investment attraction against local content requirements that tighten with each licensing cycle.
Market Dynamics
Uzbekistan's oil and gas sector is being fundamentally restructured by the State Committee for Geology and Mineral Resources' streamlined production-sharing agreements, which are redrawing entry economics for upstream operators and accelerating field development timelines in underexplored basins.
Growth Catalysts
- Energy transition mandates:The Ministry of Energy's directives require power generation utilities to expand gas-fired capacity, creating guaranteed offtake for domestic producers. This policy pull concentrates demand in the Bukhara-Khiva corridor.
- Enhanced recovery techniques:Mature field rehabilitation using modern secondary and tertiary recovery methods is unlocking stranded reserves in Soviet-era developments. Technical service providers are deploying these solutions across aging infrastructure.
- Ustyurt Plateau exploration:Untapped conventional and unconventional prospects in this underexplored basin are attracting seismic survey investment and wildcat drilling commitments from international joint venture partners.
Market Restraints
- Aging Soviet-era infrastructure:Crude oil output remains constrained by corroded pipelines, obsolete refining units, and depleted reservoir pressure maintenance systems requiring complete overhaul.
- Local content tightening:Each licensing cycle imposes stricter domestic procurement and workforce quotas, elevating project costs and extending contractor qualification timelines.
- Capital intensity of greenfield development:Frontier exploration in the South Turgay Basin demands extended payback periods and carries high dry-hole risk relative to mature basin comparables.
Strategic Opportunities
- Gas-to-liquids partnerships:Technology convergence between Fischer-Tropsch synthesis and modular small-scale GTL plants offers pathways to monetize stranded gas reserves for higher-value refined products.
- Aral Sea block expansion:Underpenetrated acreage in this northern frontier contains prospective structures that remain lightly tested by historical Soviet campaigns.
- Chinese project finance integration:GB-influenced equipment specifications from Beijing-backed lenders create dual-compliance pathways for contractors seeking non-traditional capital sources.
Industry Challenges
- Dual-standard equipment compliance:Contractors must simultaneously satisfy Russian GOST legacy requirements and Chinese GB specifications, complicating procurement and certification workflows.
- Reservoir engineering expertise scarcity:Specialized skills in carbonate reservoir characterization and fractured basement interpretation remain concentrated among a limited pool of regional specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Oil and Gas Market |
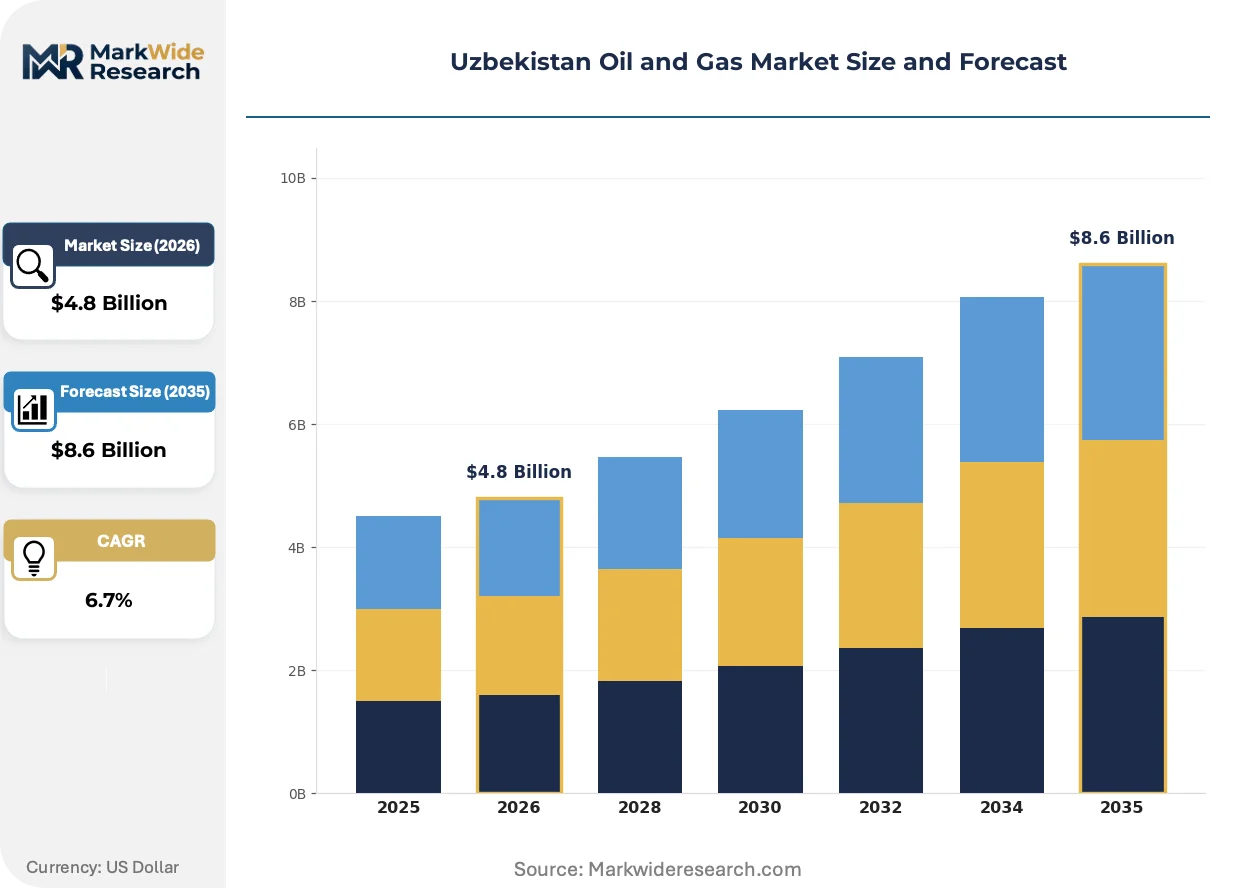
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, LPG, Refined Products Service Type: Exploration, Production, Refining, Distribution End User: Power Generation, Manufacturing, Transportation, Residential Technology: Drilling, Extraction, Seismic, Processing |
| Companies Covered | TotalEnergies SE, Sanoat Energetika Guruhi (Saneg), JSC Uzbekneftegaz, AD Ports Group, Uztransgaz JSC, Gazprom PAO, Lukoil Uzbekistan Operating Co., Karakul GTL Complex Consortium, China National Petroleum Corporation (CNPC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Oil and Gas Market Evolving Landscape
Digital reservoir surveillance and modular processing architectures are compressing development cycles across Uzbekistan's upstream segment, while regulatory alignment with Eurasian Economic Union technical standards is reshaping equipment procurement norms.
Advanced seismic imaging combining full-azimuth acquisition with machine-assisted interpretation is expanding into exploration programs across the Ustyurt Plateau and South Turgay Basin. Uzbekneftegaz and its joint venture partners are deploying these surveys to reduce dry-hole rates in structurally complex targets. The technology is expanding into frontier acreage previously written off as uneconomic under conventional appraisal methods.
Uzbekistan's updated Subsoil Use Code is mandating transparent production-sharing terms and dispute resolution mechanisms that align with Eurasian Economic Union commercial law frameworks. This regulatory harmonization is reducing contractual uncertainty for international operators. Upstream licensing rounds are now attracting diversified bidding pools as a direct response to these clarified ground rules.
Integrated service contracting is displacing fragmented procurement of discrete seismic, drilling, and completion services across Uzbekistan's greenfield developments. NOC joint ventures are consolidating vendor relationships under single-point accountability structures. This consolidation is most visible in the Bukhara-Khiva region where accelerated field development timelines demand coordinated execution.
Uzbekistan Oil and Gas Market Segmentation
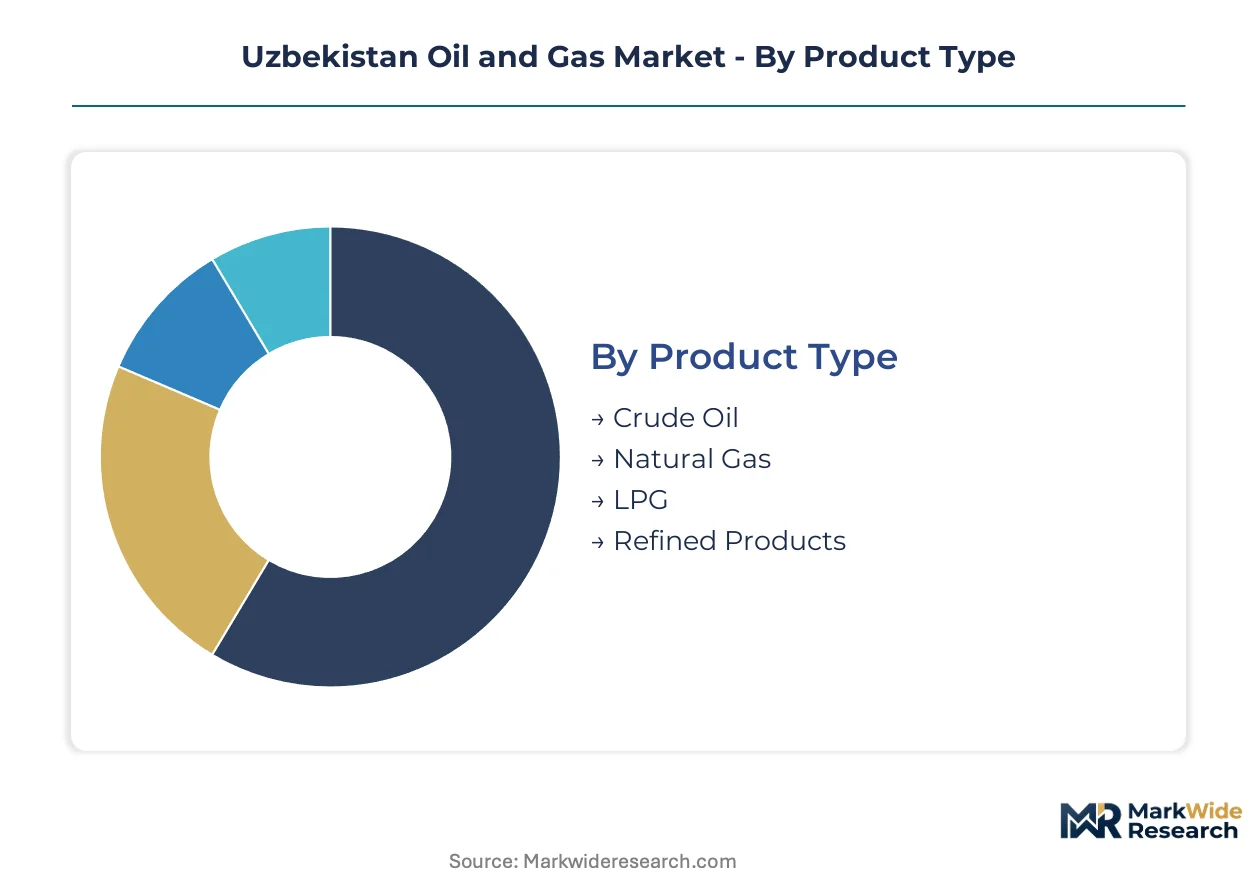
Segmentation across Uzbekistan's oil and gas market reveals how resource allocation, infrastructure maturity, and regulatory mandates concentrate activity in specific operational layers. Understanding these divisions clarifies where capital deployment encounters friction versus acceleration.
Product Type:
Specification profiles and reserve chemistry differentiate commercial viability across hydrocarbon categories, with sulfur content and calorific value determining end-use matching.
- Natural Gas:Proven reserves estimated at 1.8 trillion cubic meters anchor domestic energy security and export positioning. Power generation utilities in the Bukhara-Khiva corridor absorb the largest offtake volumes under Ministry of Energy transition mandates.
- Crude Oil:Output remains constrained by aging Soviet-era infrastructure and depleted reservoir pressure systems requiring modernization. Refining capacity limitations force reliance on imported refined products despite domestic extraction.
- LPG:Residential heating and distributed fuel applications drive demand in rural distribution networks beyond pipeline reach.
- Refined Products:Domestic supply gaps persist due to obsolete refining units, creating import dependency for transport fuels and petrochemical feedstocks.
Mature deployment sits with Natural Gas. Newer deployment is concentrated in Refined Products as modernization investments advance.
Service Type:
Cost tier stratification separates frontier exploration from established production economics, with capital intensity escalating sharply across the value chain.
- Exploration:Seismic survey investment and wildcat drilling commitments concentrate in the Ustyurt Plateau and South Turgay Basin. International joint venture partners deploy advanced full-azimuth acquisition to reduce dry-hole rates in structurally complex targets.
- Production:Mature field rehabilitation using enhanced recovery techniques unlocks stranded reserves in Soviet-era developments across the Bukhara region. Technical service providers specialize in secondary and tertiary recovery methods.
- Refining:Obsolete units require complete overhaul to meet sulfur content specifications below 0.5 percent for domestic fuels.
- Distribution:Pipeline infrastructure operated by Uztransgaz JSC carries domestic supply obligations before export allocation.
Capital absorption peaks with Exploration. Operational margin stability concentrates in Production.
End User:
Application-specific demand patterns create divergent growth trajectories tied to national energy transition timelines and industrial development priorities.
- Power Generation:Gas-fired capacity expansion absorbs the dominant share of domestic natural gas output. Ministry of Energy directives mandate this prioritization, creating guaranteed offtake for upstream producers.
- Manufacturing:Petrochemical feedstock supply supports fertilizer and chemical production clusters. Industrial gas demand tracks broader manufacturing output fluctuations.
- Transportation:Refined product consumption reflects vehicle fleet expansion and logistics sector growth.
- Residential:Heating demand concentrates in distribution networks serving urban centers and LPG-dependent rural areas.
Volume concentration favors Power Generation. Steepest expansion trajectory appears in Manufacturing as downstream industrial capacity builds out.
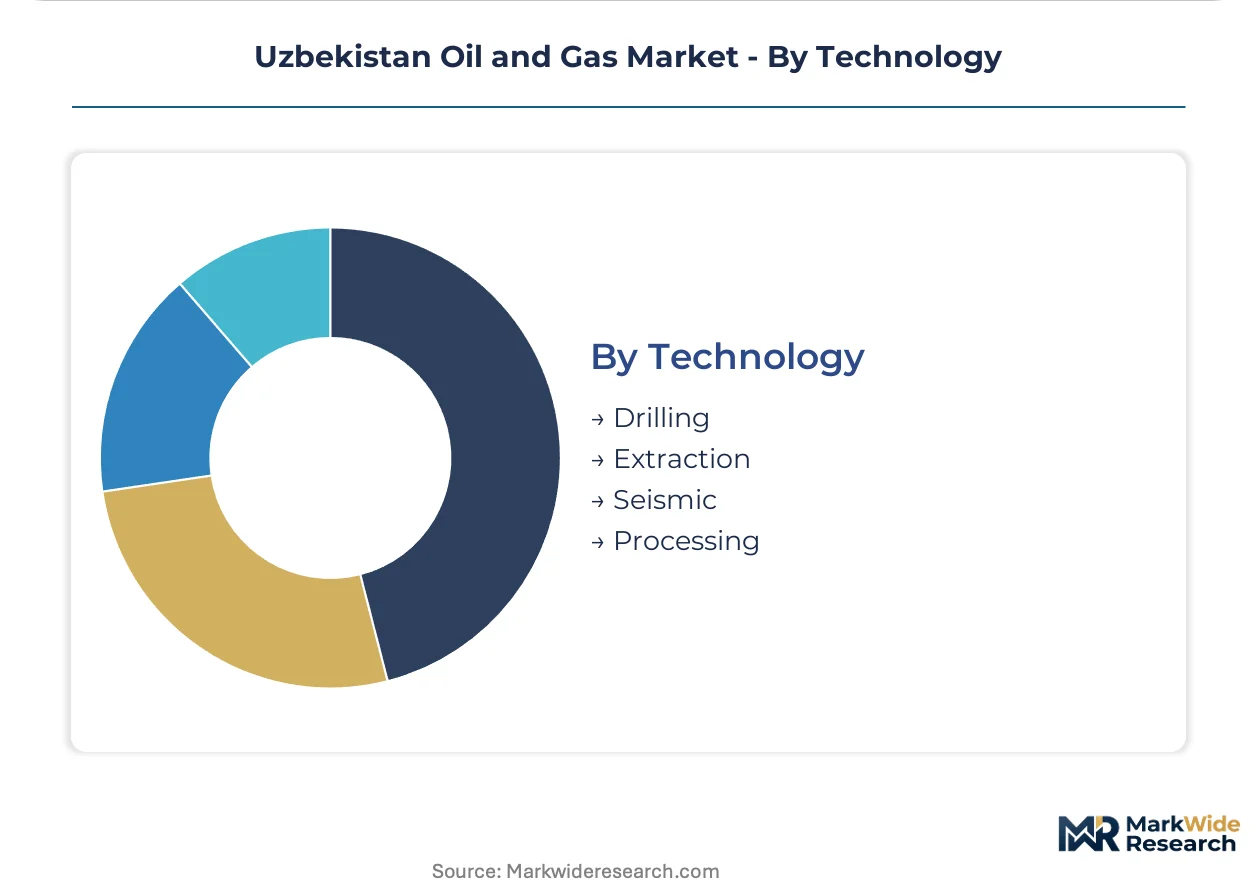
Technology:
Technology maturity curves separate proven deployment from emerging capability gaps, with digital integration reshaping competitive differentiation.
- Drilling:Advanced directional and horizontal techniques enable access to complex reservoir geometries in fractured basement formations. Deployment concentrates in joint venture blocks with international operator participation.
- Extraction:Enhanced oil recovery methods including gas injection and thermal stimulation address declining production from mature fields. Technical expertise scarcity limits deployment velocity.
- Seismic:Machine-assisted interpretation of full-azimuth surveys is expanding into frontier acreage previously written off as uneconomic.
- Processing:Modular architectures compress development cycles and enable scalable deployment across greenfield developments.
Established capability sits with Drilling. Capability buildout concentrates in Seismic as digital integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bukhara-Khiva Special Economic Zone concentrates upstream investment through production-sharing incentives and streamlined licensing protocols administered by Tashkent.
Bukhara Region
Mature field rehabilitation and enhanced recovery operations dominate activity, with Lukoil Uzbekistan Operating Co. deploying secondary and tertiary methods across Soviet-era reservoirs. The State Committee for Geology and Mineral Resources enforces local content quotas tightening with each licensing cycle. Industrial clusters around Bukhara city host technical service providers specializing in carbonate reservoir characterization.
Karakalpakstan
The Aral Sea exploration block anchors frontier activity, with untapped conventional prospects attracting seismic survey investment from international joint venture partners. Uzbekistan's updated Subsoil Use Code mandates transparent dispute resolution mechanisms aligned with Eurasian Economic Union frameworks. The Ustyurt Plateau contains underexplored basin acreage where full-azimuth acquisition reduces dry-hole rates.
Ferghana Valley
Refining capacity limitations and obsolete Soviet-era processing units create supply gaps for transport fuels and petrochemical feedstocks. Ministry of Energy directives prioritize domestic supply obligations before export allocation through Uztransgaz JSC pipeline infrastructure. Manufacturing demand from fertilizer and chemical production clusters tracks broader industrial output fluctuations.
Tashkent Metropolitan Area
Administrative and regulatory functions concentrate here, with the State Committee for Geology and Mineral Resources administering licensing rounds and production-sharing contract terms. GB-influenced equipment specifications from Chinese project finance partners create dual-compliance requirements for contractors. The capital hosts procurement decision-making for integrated service contracting across greenfield developments.
Surkhandarya Region
South Turgay Basin exploration demands extended payback periods and carries high dry-hole risk relative to mature basin comparables. Frontier wildcat drilling commitments from international partners target structurally complex targets requiring machine-assisted seismic interpretation. Gas-to-liquids partnership opportunities offer pathways to monetize stranded gas reserves for higher-value refined products.
Uzbekistan Oil and Gas Market Competitive Landscape
Russian operators anchor one tier through mature field rehabilitation expertise; Chinese state-backed entities hold project finance and equipment supply positions. The structure concentrates around national oil company dominance with joint venture partnerships for frontier acreage. Three archetypes emerge: integrated NOCs with pipeline control, international majors with GTL technology access, and regional specialists in enhanced recovery. Competitive moves center on integrated service contracting consolidation and dual-standard equipment certification workflows.
Among French-based integrated majors, TotalEnergies SE exemplifies the international archetype through Aral Sea block positioning and gas-to-liquids partnership structures. State-backed Russian operators occupy positions in mature basin rehabilitation, with Lukoil Uzbekistan Operating Co. representing specialized enhanced recovery deployment. Chinese national oil companies anchor non-traditional capital pathways, with China National Petroleum Corporation sitting within the project finance-integrated tier. These entities collectively illustrate how geographic origin and state backing determine strategic positioning rather than pure commercial differentiation.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Sanoat Energetika Guruhi (Saneg) |
| JSC Uzbekneftegaz |
| AD Ports Group |
| Uztransgaz JSC |
| Gazprom PAO |
| Lukoil Uzbekistan Operating Co. |
| Karakul GTL Complex Consortium |
| China National Petroleum Corporation (CNPC) |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers including JSC Uzbekneftegaz and Gazprom PAO anchor supply-side ownership patterns, enabling long-term offtake contracting that disciplines spot-market volatility while compressing margins for service-tier competitors lacking equivalent balance-sheet depth.
Pricing Analysis
Premium pricing attaches to short-lead-time equipment procurement, while spot inventory of Soviet-era surplus components trades at discounts. Contract-based long-term offtake dominates upstream gas sales, with price differentiation driven by sulfur content grade and delivery reliability guarantees. Pricing pressure stems from Chinese GB-standard equipment flooding procurement channels. Exploration service buyers exhibit highest price sensitivity; integrated operators with captive engineering capacity show lowest.
Supply Chain Analysis
Specialized drilling equipment supply rests on manufacturing clusters in China, Russia, and Germany. Critical inputs include high-grade steel casings, downhole pumps, and seismic acquisition sensors. Single-source vulnerability concentrates in advanced directional drilling packages sourced from limited international vendors. Distribution runs through Tashkent-based procurement hubs coordinating field logistics to Bukhara-Khiva and Karakalpakstan development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uzbekistan's oil and gas sector sits in a technology-transition phase, with digital reservoir surveillance and machine-assisted seismic interpretation displacing legacy Soviet-era manual interpretation workflows.
For Market Incumbents: Hedge against margin erosion in mature field services by securing exclusive enhanced-recovery technology licenses and consolidating technical service contracts under single-point accountability structures. The State Committee for Geology and Mineral Resources' tightening local content quotas threaten unintegrated foreign operators. Backward integration into seismic data processing capabilities offers defensive positioning. For New Entrants and Emerging Players: Uzbekistan's updated Subsoil Use Code in Tashkent opens a window for frontier exploration specialists to bid underpenetrated Ustyurt Plateau acreage with transparent production-sharing terms. White-space targets include modular gas-to-liquids plant deployment and carbonate reservoir characterization services. A joint venture structure with established regional drilling contractors accelerates contractor qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor enhanced-recovery technology specialists with proprietary thermal stimulation or gas-injection capabilities in the Bukhara region. Long-term viability hinges on positioning for gas-fired capacity expansion mandates. Watch licensing round participation rates from non-Russian international operators as inflection indicator for regulatory credibility.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting Consolidation | Single-point accountability reduces coordination friction across Bukhara-Khiva greenfield timelines. |
| Dual-Standard Equipment Certification | Simultaneous GOST and GB compliance unlocks Chinese project finance for pipeline modernization. |
| Gas-to-Liquids Partnership Formation | Fischer-Tropsch technology access monetizes stranded Aral Sea block reserves. |
| Digital Reservoir Surveillance Deployment | Real-time pressure monitoring extends recovery factors from Soviet-era carbonate formations. |
| Local Content Capability Buildout | Domestic procurement quotas from the Ministry of Energy secure licensing round eligibility. |
Research Methodology
Regulatory filings from the State Committee for Geology and Mineral Resources, production-sharing contract disclosures, and Ministry of Energy directive archives formed the secondary backbone. Primary interviews with upstream project developers, EPC contractors, reservoir engineering specialists, and Uztransgaz JSC planning officers combined with customs and trade data to enable bottom-up and top-down triangulation.
Bottom-up modeling aggregated field-level production estimates across natural gas, crude oil, and LPG categories, while top-down verification cross-checked against national energy balance projections. Segmentation dimensions included product type, service tier, end-use application, and regional development corridor. CAGRs derived from production growth trajectories, capacity expansion pipelines, and demand elasticity assumptions tied to power generation utility offtake commitments.
The model assumes a particular technology adoption path for digital seismic interpretation; alternative pathways for machine-learning-assisted reservoir characterization would alter the outlook. Forecasts reflect assumptions about licensing round cadence, local content enforcement intensity, and Chinese financing availability. A small set of triggers—production-sharing term disputes, equipment import restriction shifts, and major dry-hole results—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market