
 Peanut Butter Market | 2026-2036
Peanut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Butter Market Intelligence
Product formulation expertise is bifurcating the competitive landscape between mass-market producers and niche, health-focused brands. The J.M. Smucker Company leverages its brand heritage and vast retail presence to maintain a dominant market position. Kraft Heinz competes on manufacturing scale and cost control in the high-volume creamy and crunchy segments. Unilever differentiates its offerings through investments in sustainable sourcing and natural product innovations.
Peanut butter is a food spread produced from ground, dry-roasted peanuts. Food safety regulations often stipulate a minimum of 90% peanut content, limiting the use of added oils, sweeteners, and emulsifiers. While creamy and crunchy product types form the market's high-volume core, natural and flavored varieties are seeing accelerated adoption. Supermarkets remain the primary distribution channel, but online retail is gaining share, particularly for specialized and premium products.
The US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate stringent controls on aflatoxin contamination and enforce clear allergen labeling. Regulations from bodies like the Food Safety and Standards Authority of India (FSSAI) also shape product composition through fortification guidelines. Navigating these varied regional standards is a critical challenge. Success depends on balancing clean-label formulations with growing consumer interest in functional and fortified spreads.
Market Dynamics
The market's structure is being defined by a dual pressure: increasingly stringent allergen labeling regulations from bodies like the US FDA and EFSA, coupled with a significant geographic demand shift toward developing economies, particularly India, altering global trade flows.
Growth Catalysts
- Fortification Mandates:Guidelines from the Food Safety and Standards Authority of India (FSSAI) encouraging food fortification are prompting producers to add micronutrients to peanut butter, aligning products with public health initiatives and boosting consumption.
- Food Manufacturing Demand:The expanding use of peanut butter as a core ingredient in the confectionery and snack bar industries provides a consistent, high-volume demand channel for both standard and specialized formulations.
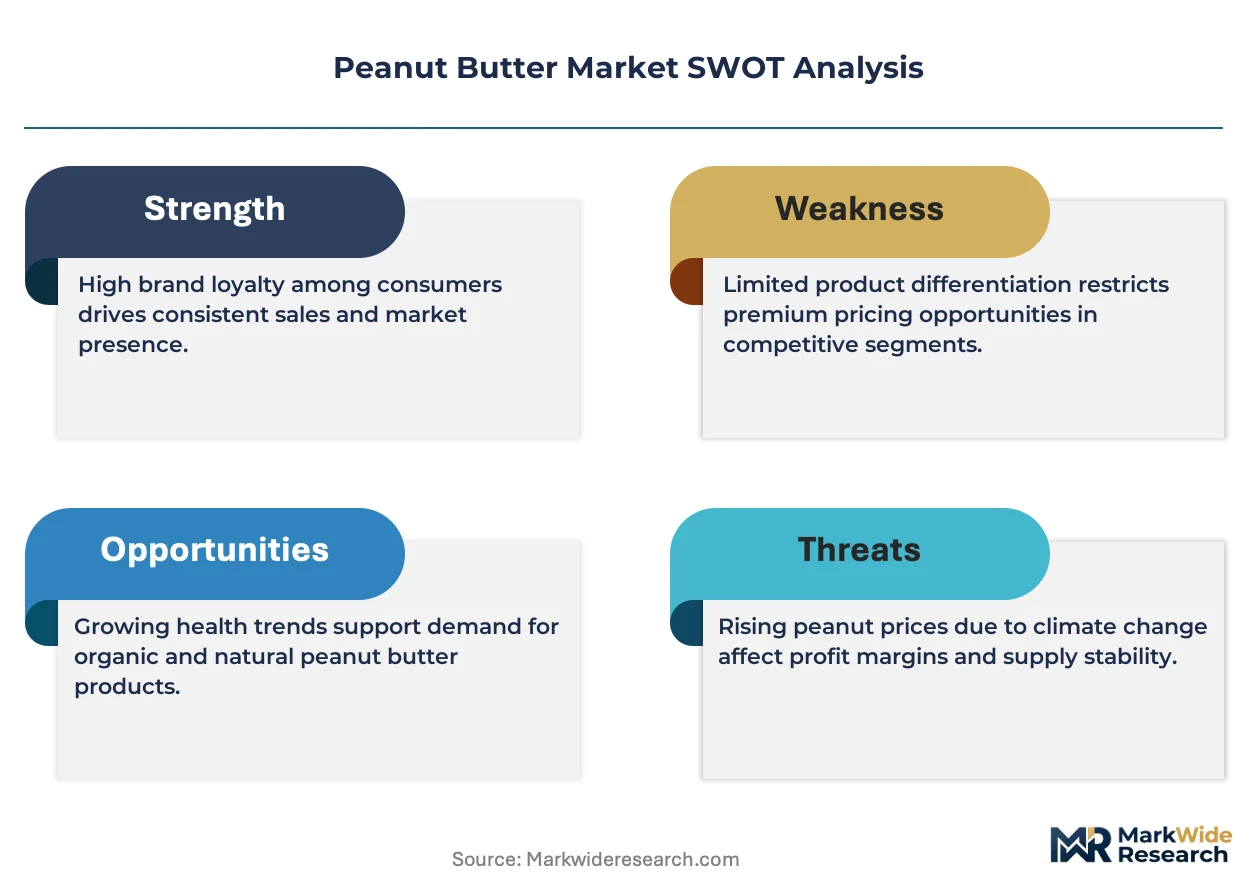
- Clean-Label Consumerism:A pronounced consumer shift toward natural products with minimal ingredients is driving growth for varieties free from added sugars, hydrogenated oils, and artificial emulsifiers, particularly in developed markets.
Market Restraints
- Input Cost Volatility:Peanut crop yields are highly susceptible to weather patterns and agricultural diseases, leading to fluctuating raw material prices that can compress manufacturer margins and create price instability for consumers.
- Aflatoxin Contamination Risk:The natural occurrence of aflatoxins in peanuts requires rigorous, costly testing and quality control to meet strict international limits set by regulators like the EFSA, acting as a barrier to market entry.
- Alternative Spread Competition:A growing array of tree nut and seed butters, including almond, cashew, and sunflower seed varieties, directly competes for shelf space and consumer attention, especially within health and wellness retail channels.
Strategic Opportunities
- Geographic Expansion:Significant underpenetration in Southeast Asian and African markets presents an opportunity for expansion, driven by urbanization, dietary diversification, and rising disposable incomes in countries like Nigeria and Indonesia.
- Functional Formulations:The development of peanut butters enriched with functional ingredients such as plant-based protein, probiotics, or omega-3 fatty acids can capture demand from health-conscious consumers seeking enhanced nutritional benefits.
- Channel Diversification:Launching direct-to-consumer (DTC) subscription services for niche and premium peanut butter products allows brands to build direct customer relationships and bypass the competitive constraints of traditional supermarket retail.
Industry Challenges
- Supply Chain Traceability:Establishing and maintaining a fully traceable supply chain to guarantee non-GMO or organic certification and verify origin is a complex operational challenge that requires substantial investment in logistics and data management systems.
- Packaging and Labeling Compliance:Constantly adapting packaging and marketing materials to comply with evolving food labeling regulations, such as the FDA's front-of-pack nutrition labeling initiatives, imposes recurring costs and logistical hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Butter Market |
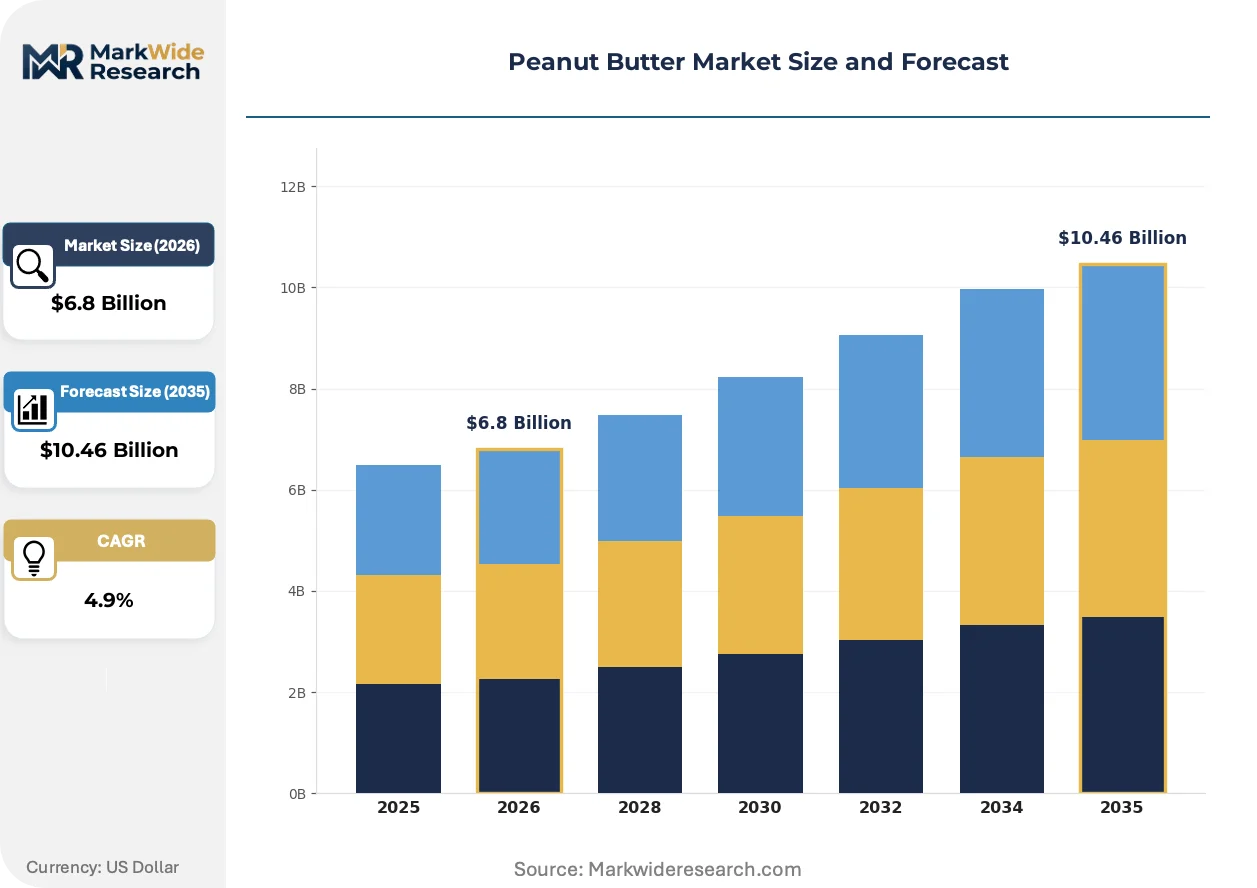
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Creamy, Crunchy, Flavored End User: Households, Restaurants, Bakeries, Food Manufacturers Packaging Type: Glass Jars, Plastic Containers, Pouches, Bulk Packaging Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | Conagra Brands, Unilever, J.M. Smucker Company, Mars Incorporated, The Hershey Company, Kraft Heinz, Procter & Gamble, Nestlé, Hormel Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Butter Market Strategic Shifts & Innovations
Product innovation is pivoting toward functional benefits and clean-label attributes. This movement is driven by both regulatory pressures on food safety and a fundamental change in consumer expectations regarding health and wellness in staple food products.
Advanced milling techniques and natural stabilizers are enabling the creation of smooth, no-stir natural peanut butters without hydrogenated oils. Health-focused brands and private-label producers are rapidly adopting these formulation methods to meet clean-label demand from consumers. This focus on achieving desirable texture and stability without artificial additives is displacing traditional formulations that rely on partially hydrogenated oils for shelf life and consistency.
Stringent regulations on aflatoxin contamination, enforced by bodies like the European Food Safety Authority (EFSA) and the US FDA, set a high bar for raw material sourcing. These rules mandate rigorous testing and certification protocols, adding complexity and cost to the supply chain for all producers. Processors targeting the European Union face the most significant impact, often requiring separate, higher-grade supply chains to meet the bloc's strict import standards.
A consumer-led shift toward ingredient transparency is altering purchasing decisions in the supermarket channel. Shoppers are increasingly scrutinizing labels for minimal ingredients, rejecting products with added sugars, palm oil, and artificial preservatives. This behavior is most prominent in North American and European markets, forcing even mass-market brands to launch natural or "simple" product lines to retain market share.
Peanut Butter Market Segmentation
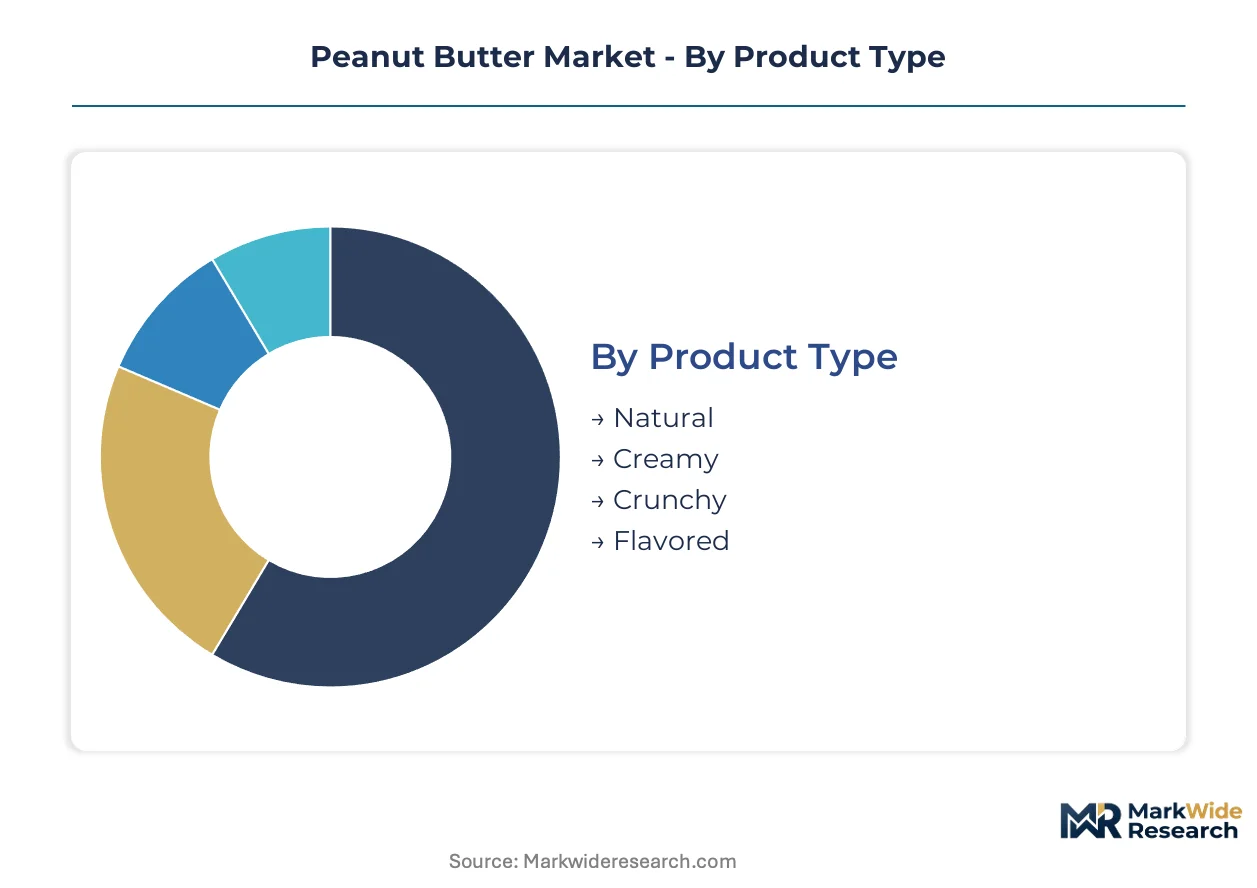
The peanut butter market's segmentation reflects diverse consumer preferences and varied industrial applications. Understanding these distinct segments illuminates where value creation concentrates and where competitive pressures are most pronounced for producers.
Product Type:
Product type segmentation faces substitution pressure from alternative spreads, particularly for health-conscious consumers seeking novel textures or ingredients.
- Natural:This product type consists primarily of ground peanuts, often without added sugars, oils, or emulsifiers. Demand concentrates in developed markets like North America and Europe, driven by clean-label consumerism.
- Creamy:Characterized by a smooth, uniform texture achieved through fine milling, creamy peanut butter represents a high-volume core product. This traditional variety sees consistent demand across household consumption and food manufacturing applications.
- Crunchy:Crunchy varieties incorporate small pieces of roasted peanuts into the spread, offering a distinct textural experience. This segment maintains a loyal consumer base, particularly in established markets.
- Flavored:Flavored peanut butters include additional ingredients such as chocolate, honey, or spices to create unique taste profiles. Innovation in this segment targets younger demographics and dessert applications.
Creamy retains volume leadership; Natural holds the steepest expansion curve.
End User:
Demand patterns across end-user segments are shaped by application-specific requirements, from bulk ingredient sourcing to individual consumer consumption habits.
- Food Manufacturers:This segment utilizes peanut butter as a key ingredient in confectionery, snack bars, and baked goods. High-volume, consistent supply and specific formulation properties are critical for these industrial buyers.
- Households:Individual consumers purchase peanut butter for direct consumption as a spread or ingredient in home cooking. This segment is sensitive to brand reputation, price points, and nutritional claims.
- Restaurants:Food service establishments incorporate peanut butter into sandwiches, desserts, and sauces. Bulk and convenient packaging formats are often preferred in this setting.
- Bakeries:Bakeries use peanut butter for fillings, toppings, and flavorings in various baked goods. Product consistency and shelf stability are important factors for these businesses.
Food Manufacturers command the largest share of market volume, while Household consumption remains broadly distributed.
Packaging Type:
Packaging type differentiation often hinges on cost-efficiency, shelf-life requirements, and consumer convenience, influencing purchasing decisions across channels.
- Bulk Packaging:Large containers, such as pails or drums, are designed for industrial use by food manufacturers and food service providers. Cost-effectiveness per unit and ease of handling in commercial kitchens are primary considerations.
- Plastic Containers:These lightweight, shatter-resistant containers are prevalent in retail, offering durability and ease of transport for consumers. This packaging type dominates the mass-market retail shelves.
- Glass Jars:Glass jars are often associated with premium or natural peanut butter products, conveying a sense of quality and freshness. They are favored by brands emphasizing clean-label attributes and aesthetic appeal.
- Pouches:Flexible pouches offer convenience for single-serve portions or on-the-go consumption, reducing waste and providing portability. This format is gaining traction in snack and health-focused segments.
Plastic Containers secure the highest retail penetration, while Bulk Packaging optimizes for industrial scale.
Distribution Channel:
Distribution channel dynamics are influenced by consumer access, product specialization, and the evolving landscape of retail purchasing behaviors.
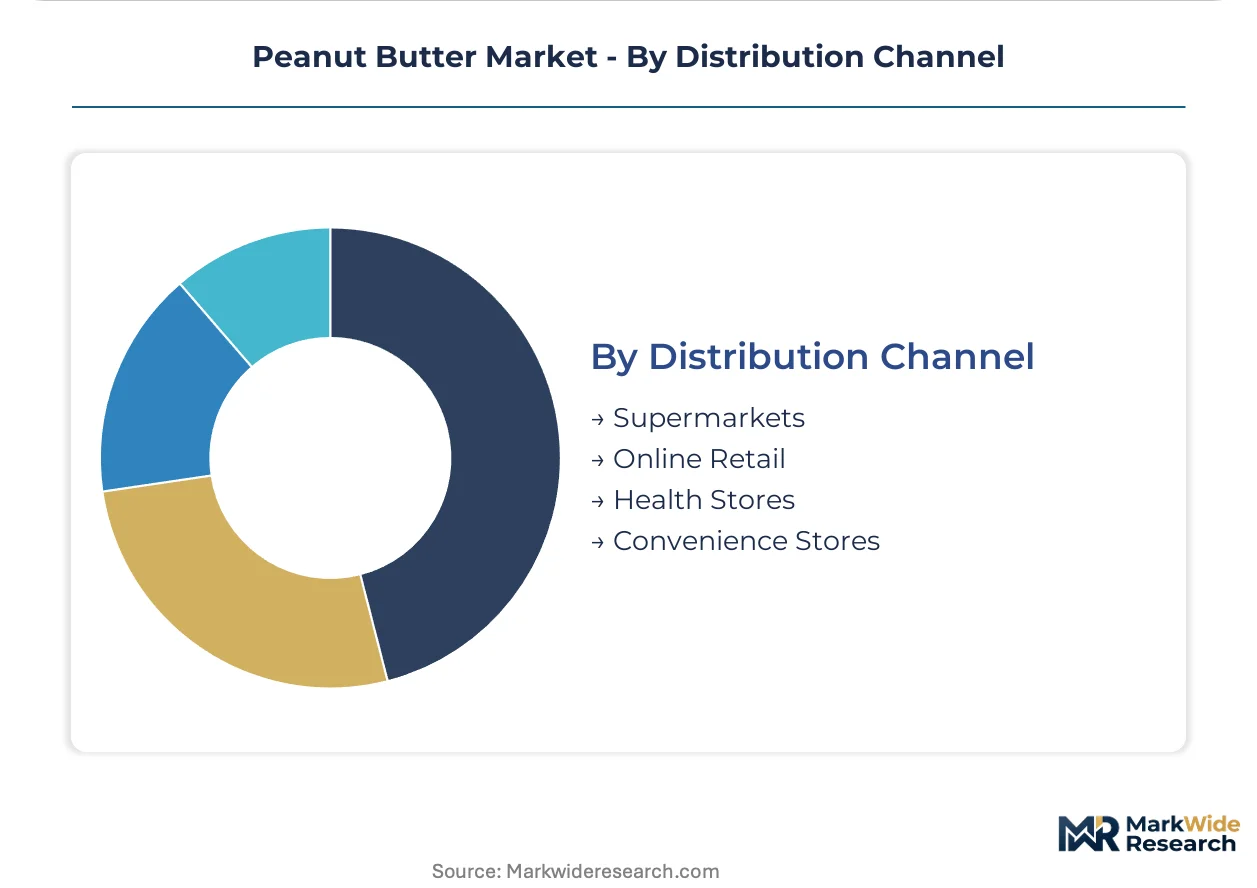
- Supermarkets:These large retail outlets serve as the primary channel for mass-market peanut butter products, offering wide selection and competitive pricing. Supermarkets provide essential visibility for established brands.
- Online Retail:E-commerce platforms are gaining share, especially for niche, organic, or specialized peanut butter varieties. Online channels enable direct-to-consumer models and broader geographic reach for unique offerings.
- Health Stores:Specialized health food stores cater to consumers seeking organic, non-GMO, or allergen-free peanut butter options. These stores often stock premium brands with specific dietary claims.
- Convenience Stores:Smaller retail formats offer quick access to standard peanut butter products, often in smaller sizes. These stores serve immediate consumer needs and impulse purchases.
Supermarkets maintain significant market presence, as online retail is accelerating its market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing dynamics show a significant asymmetry between emerging markets like India and mature markets such as the United States. While India's expanding consumer base drives volume growth, stringent regulatory compliance in developed economies influences premium pricing. This divergence shapes global investment and supply chain strategies for peanut butter producers.
India
Demand for peanut butter in India stems from dietary shifts and government-backed fortification mandates. The Food Safety and Standards Authority of India (FSSAI) encourages producers to add micronutrients, boosting consumption. The Delhi-NCR region sees increased processing and distribution activities for fortified peanut butter products.
United States
High household consumption and expanding use in snack bar manufacturing characterize the United States market. The US Food and Drug Administration (FDA) enforces strict allergen labeling regulations, influencing product formulation. California's food manufacturing hubs integrate peanut butter into diverse snack and confectionery product lines.
Germany
Strong clean-label consumerism and a preference for natural products drive demand in Germany. The European Food Safety Authority (EFSA) sets rigorous limits on aflatoxin contamination, impacting sourcing strategies. Hamburg's port facilities manage specialized imports for distribution across the European Union.
China
Urbanization and westernized dietary trends contribute to peanut butter market expansion in China. The State Administration for Market Regulation (SAMR) oversees food safety standards and labeling requirements. Shanghai's retail sector experiences growth in premium and imported peanut butter sales.
Brazil
Rising disposable incomes and diversified food consumption patterns fuel demand for peanut butter in Brazil. The National Health Surveillance Agency (ANVISA) mandates specific food safety and labeling requirements. São Paulo's food processing industry expands peanut butter production for both domestic and regional markets.
Peanut Butter Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the peanut butter market. The competitive structure features a mix of multinational food conglomerates and agile, health-focused niche brands. Multinational players prioritize manufacturing scale and retail presence, while niche brands focus on product innovation and sustainable sourcing. Dominant competitive moves include strategic partnerships for distribution and continuous portfolio diversification into functional spreads.
On the multinational conglomerate vector, J.M. Smucker Company leverages extensive brand heritage and broad retail networks to maintain its market footprint. Kraft Heinz exemplifies a strategy focused on manufacturing scale and cost control across high-volume segments like creamy and crunchy varieties. Unilever differentiates its market offerings through investments in sustainable sourcing and natural product innovations, representing a commitment to evolving consumer preferences.
| Leading Market Players |
|---|
| Conagra Brands |
| Unilever |
| J.M. Smucker Company |
| Mars Incorporated |
| The Hershey Company |
| Kraft Heinz |
| Procter & Gamble |
| Nestlé |
| Hormel Foods Corporation |
| Others |
Cost & Logistics Intelligence
US Food and Drug Administration (FDA) and European Food Safety Authority (EFSA) regulations on aflatoxin contamination and allergen labeling gate both supply qualification and price differentiation simultaneously. These stringent standards necessitate rigorous testing, influencing sourcing decisions and creating premium pricing for compliant products.
Pricing Analysis
A significant geographic price spread exists between emerging markets like India and mature markets such as the United States. Pricing predominantly follows a transactional model, with long-term contracts common for industrial buyers. Price differentiation stems from quality grade, brand premium, and volume scale for food manufacturers. Input cost volatility, driven by peanut crop yields, creates upward pricing pressure. Household consumers exhibit high price sensitivity, while food manufacturers prioritize consistent supply and specific formulation properties.
Supply Chain Analysis
Rising inbound logistics costs, particularly for intercontinental shipping from major peanut-producing regions, impact overall supply chain economics. Geographic supply concentration for peanuts centers on countries like India, the United States, and China, which also have significant processing capabilities. The industry relies heavily on raw peanuts and packaging materials such as glass and plastic. Commodity price volatility for peanuts, influenced by weather patterns and agricultural diseases, represents a primary structural risk. Downstream distribution runs predominantly through supermarkets and increasingly via online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peanut butter market presents an early-cycle expansion story, driven by clean-label consumerism across developed markets. This fundamental shift underpins sustained volume growth.
For Market Incumbents:
Compound existing brand loyalty through continuous product innovation, particularly in functional formulations. Invest in sustainable sourcing practices to meet evolving consumer expectations and mitigate supply chain risks. Prioritize R&D in natural stabilizers to develop clean-label, no-stir products, thereby fending off alternative spread competition. Expand manufacturing capacity in key growth regions like India to leverage local demand and fortification mandates.
For New Entrants and Emerging Players:
Organic certification fast-tracks enable new entrants to capture premium segments with strong clean-label appeal. Target underpenetrated Southeast Asian markets with localized flavor profiles and convenient packaging formats. Focus on online retail channels and direct-to-consumer subscription models to build brand equity and bypass traditional supermarket gatekeepers. Develop specialized products for specific dietary needs, such as high-protein or low-sugar varieties.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across processing and quality control, reflecting heightened regulatory demands. The market offers long-term viability as a staple food, with growing adjacencies in health and wellness. Acquisition targets should include agile, health-focused niche brands possessing strong clean-label formulations and established online distribution. The signal to watch is the sustained growth rates of natural and organic product lines within mass-market retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification (Functional Formulations) | Captures demand from health-conscious consumers seeking enhanced nutritional benefits. |
| Geographic Market Entry (Southeast Asia) | Leverages underpenetrated markets with rising disposable incomes and dietary diversification. |
| Supply Chain Traceability Investment | Ensures compliance with stringent food safety and origin verification regulations. |
| Direct-to-Consumer Channel Development | Builds direct customer relationships and bypasses traditional retail constraints. |
| Natural Stabilizer R&D | Enables clean-label, no-stir formulations without artificial additives, meeting consumer demand. |
Research Approach
Initial hypotheses were tested against primary input from food manufacturers' procurement leads, retail category managers, R&D specialists, and consumer behavior analysts. This primary research was rigorously validated through extensive secondary data sources, including government food safety reports from bodies like the FDA, EFSA, and FSSAI, trade association publications, company financial statements, and retail scanner data. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Variance decomposition analysis isolated key drivers across product type, end-user, packaging type, distribution channel, and regional consumption patterns. The analytical framework projected market dynamics over the projection horizon, with Compound Annual Growth Rates (CAGRs) derived from historical trends and future growth catalysts. Key industry-specific forecast inputs included peanut crop yields and evolving consumer health trends, which directly influence product development and market demand.
Decision-makers should treat outputs as directional under current regulatory stability and agricultural productivity assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging that major crop failures, sudden shifts in food safety regulations, or significant competitive disruption from alternative spreads could alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Club Store Packs Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Burritos Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market