
 Heart Lung Machine Market | 2026-2036
Heart Lung Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Lung Machine Market Outlook
A capital-intensity divergence between integrated manufacturers and component assemblers is collapsing as oxygenator membrane technology commoditizes. Medtronic leverages its end-to-end perfusion portfolio to sustain pricing power across bypass circuits. LivaNova anchors its competitive position through deep specialization in autotransfusion and monitoring subsystems. Getinge AB competes by controlling sterile disposable supply chains that feed into its broader critical care ecosystem.
A heart lung machine is a mechanical device that temporarily assumes the functions of the heart and lungs during open-chest surgical procedures, typically incorporating a pump, oxygenator, heat exchanger, and tubing circuit capable of maintaining blood flow rates exceeding five liters per minute while regulating temperature and gas exchange. Its primary commercial purpose is to enable cardiac surgeons to operate on a still, bloodless field while preserving systemic perfusion and oxygen delivery. Cardiopulmonary bypass machines retain the largest installed base but face margin compression as disposable oxygenators capture recurring revenue streams. Extracorporeal membrane oxygenation technology represents the fastest-expanding segment as intensivists adopt prolonged circulatory support beyond traditional surgical timeframes. Mobile systems are penetrating ambulatory surgical centers where capital budgets constrain fixed-installation purchases.
FDA premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers seeking multi-territory registration. ISO 13485 quality management standards and IEC 60601 electrical safety protocols establish baseline compliance thresholds that differentiate established suppliers from emerging entrants. Stakeholders must monitor how evolving oxygenator biocompatibility benchmarks and extended-duration ECMO indications reshape R&D allocation and regulatory submission strategies.
Market Dynamics
Oxygenator membrane commoditization is collapsing the historical capital-intensity divergence between integrated manufacturers and component assemblers, forcing margin compression across bypass circuit producers while accelerating R&D investment in next-generation ECMO platforms.
Growth Catalysts
- EU MDR clearance acceleration:Streamlined technical documentation pathways for next-generation oxygenators are shortening product refresh cycles and enabling faster market access for innovative perfusion technologies across European tertiary hospitals.
- Japan's aging surgical population:Demographic compression in cardiac patient cohorts is sustaining procedure volumes at established surgical centers, anchoring demand for extracorporeal support infrastructure in Tokyo and Osaka medical clusters.
- ECMO duration extension:Intensivist adoption of prolonged circulatory support beyond traditional surgical timeframes is expanding the addressable patient population for membrane oxygenation systems in critical care settings.
Market Restraints
- Polymer membrane input volatility:Specialized fluoropolymer and silicone supply concentration in East Asian chemical producers creates cost instability for oxygenator manufacturers dependent on biocompatible membrane substrates.
- FDA premarket notification friction:510(k) substantive equivalence requirements for pump-oxygenator interface modifications impose documentation burdens that delay iterative product improvements and extend development timelines.
- Minimally invasive cardiac surgery substitution:Off-pump coronary artery bypass techniques and transcatheter valve replacement procedures are reducing dependence on full cardiopulmonary bypass in select patient populations.
Strategic Opportunities
- Ambulatory surgical center penetration:Mobile perfusion systems are capturing capital-constrained facilities seeking bypass capability without fixed-installation infrastructure, particularly in Germany's distributed hospital network.
- Autotransfusion-monitoring convergence:Integration of cell salvage systems with real-time hematocrit and coagulation monitoring creates bundled value propositions for high-volume cardiac programs.
- US IRA hospital infrastructure incentives:Federal funding for rural cardiac care expansion is creating procurement opportunities for transportable ECMO platforms in underserved geographic zones.
Industry Challenges
- Perfusionist workforce scarcity:Specialized extracorporeal technologist training programs are failing to match retirement attrition, constraining operational capacity at expanding cardiac surgery programs.
- ISO 13485 certification timeline compression:Accelerated quality management system audits for multi-territory registration are straining regulatory affairs resources at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Lung Machine Market |
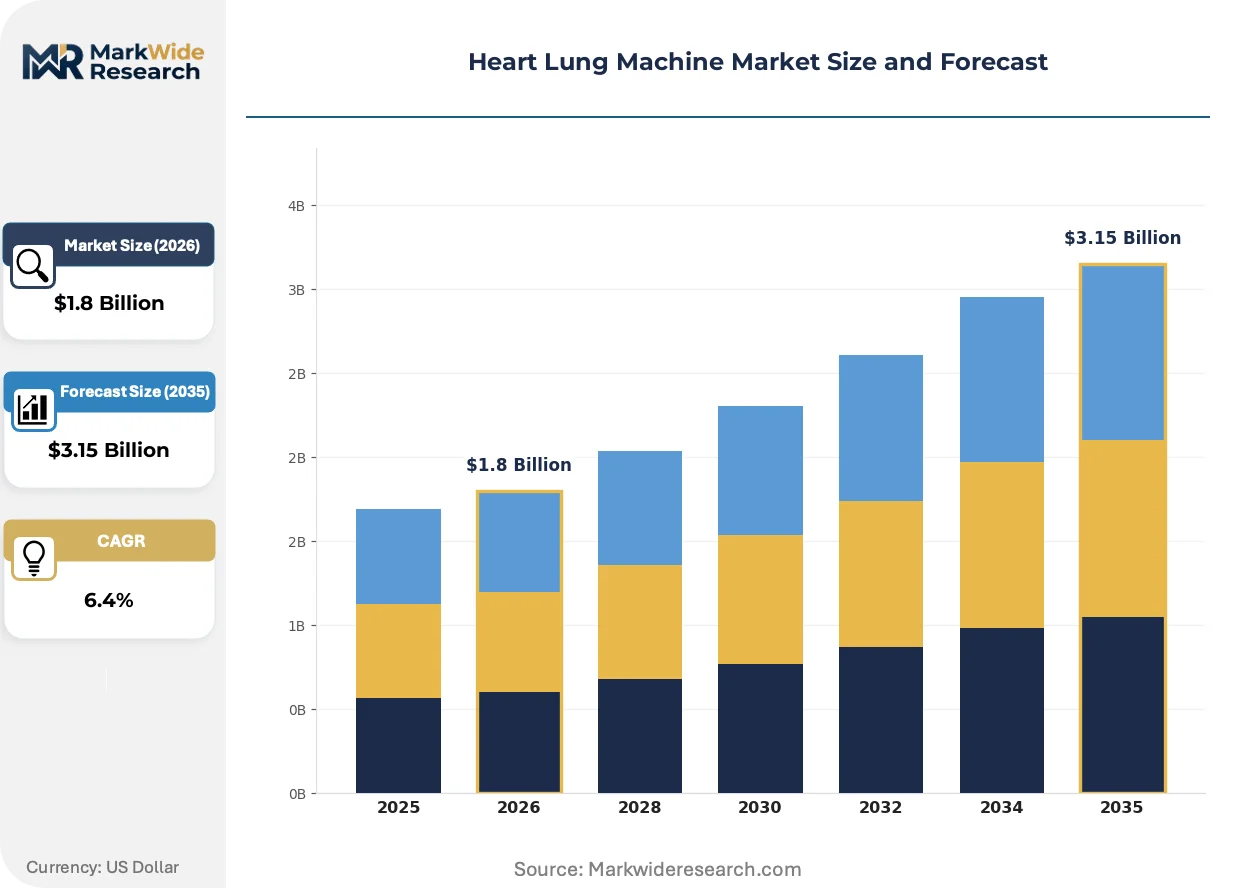
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiopulmonary Bypass Machine, Oxygenator, Cannula, Monitoring System End User: Hospitals, Surgical Centers, Cardiac Care Units, Research Institutions Technology: Mechanically Assisted, Extracorporeal Membrane Oxygenation, Mobile Systems, Disposable Systems Application: Cardiac Surgery, Organ Transplantation, Pulmonary Surgery, Critical Care |
| Companies Covered | Medtronic, LivaNova, Getinge AB, Terumo Corporation, Fresenius Medical Care, Braile Biomedica, NIPRO Corporation, Edwards Lifesciences Corporation, Tianjin Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Lung Machine Market Strategic Shifts
Membrane oxygenation technology is fragmenting into divergent performance tiers while regulatory frameworks harden biocompatibility benchmarks and procurement patterns shift toward outcome-accountable contracting models.
Hollow-fiber oxygenator design is bifurcating between plasma-resistant microporous membranes for short-duration bypass and diffusion-silicone configurations for extended ECMO support. Academic medical centers in the United States are adopting dual-platform strategies that match oxygenator selection to anticipated support duration. This technical segmentation is compressing pricing power for standardized products while creating premium tiers for specialized indications.
EU MDR technical documentation obligations are mandating expanded clinical evidence packages for legacy oxygenator designs previously cleared under the Medical Device Directive. Manufacturers with substantial European revenue exposure are reallocating regulatory affairs resources toward post-market surveillance systems and periodic safety update reports. The burden falls heaviest on disposable circuit producers lacking dedicated clinical affairs infrastructure.
Hospital procurement committees are consolidating vendor relationships through multi-year total perfusion service agreements that bundle capital equipment, disposable circuits, and on-site technical support. This aggregation is displacing transactional purchasing of individual bypass components at integrated delivery networks in Germany and Japan. The shift is most pronounced at tertiary centers seeking to standardize perfusion protocols across multiple cardiac surgical teams.
Heart Lung Machine Market Segmentation
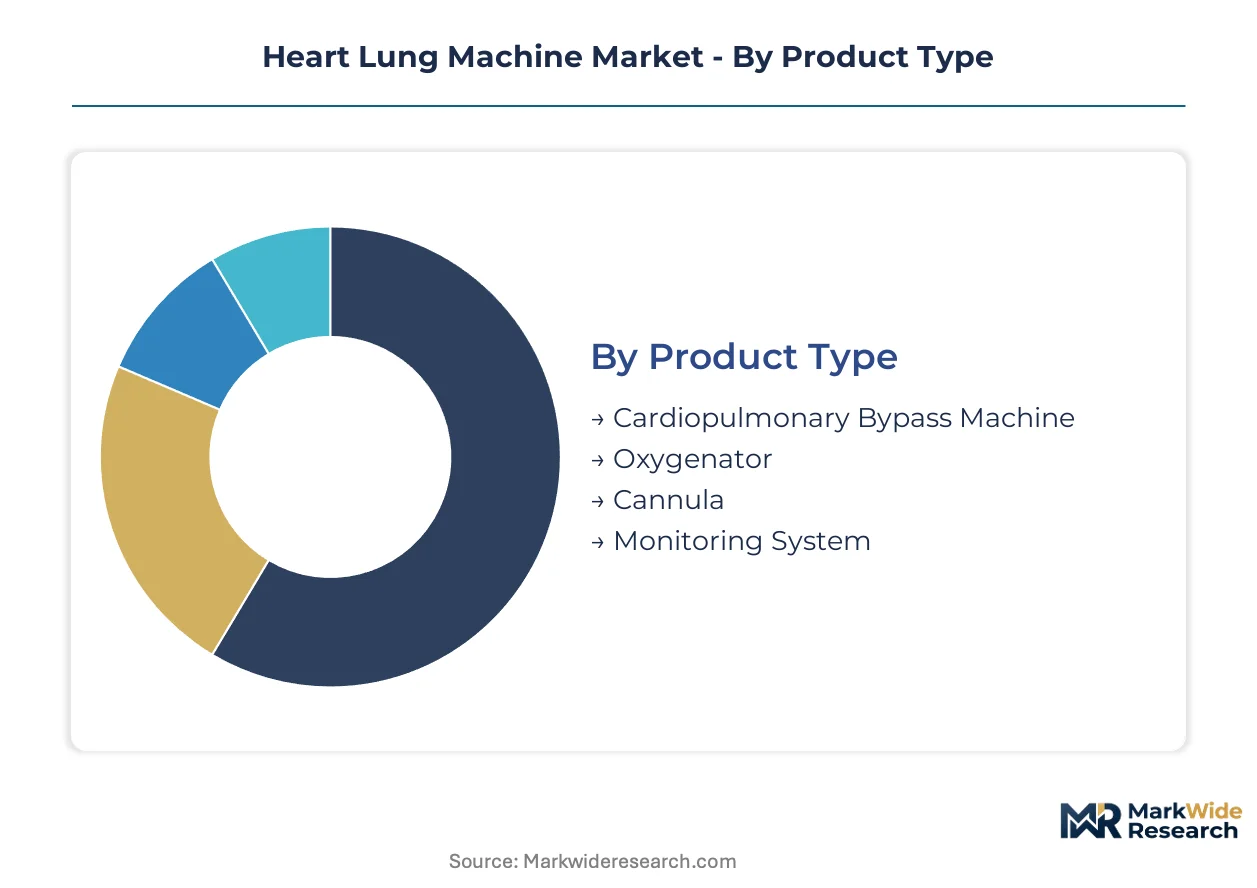
Segmentation in the heart lung machine market reveals divergent procurement patterns across acute care settings. Product type and technology choices vary sharply between high-volume tertiary centers and resource-constrained ambulatory facilities.
Product Type:
Cardiopulmonary bypass machines concentrate demand in domestic markets with established cardiac surgical infrastructure, while oxygenator exports flow disproportionately to emerging perfusion programs in Asia-Pacific.
- Cardiopulmonary Bypass Machine:These integrated systems incorporate roller or centrifugal pumps with heat exchangers and reservoir assemblies capable of maintaining full circulatory support for six-plus hours. Demand clusters at university hospitals in the United States, Germany, and Japan where complex aortic procedures sustain installed base refresh cycles amid capital budget constraints.
- Oxygenator:Hollow-fiber membrane devices govern gas exchange efficiency through microporous polypropylene or silicone diffusion matrices. German and Japanese manufacturers dominate export flows to Southeast Asian surgical centers building de novo bypass capabilities, though fluoropolymer input costs compress margins.
- Cannula:Biocompatible polymer insertion devices ranging from aortic arch to femoral configurations.
- Monitoring System:Real-time hematocrit, blood gas, and flow measurement interfaces bundled with premium bypass contracts.
Cardiopulmonary bypass machines hold the largest share; momentum sits with oxygenator disposables capturing recurring revenue streams.
End User:
Cost tier stratification separates capital-intensive tertiary hospitals from surgical centers seeking mobile or leased perfusion solutions.
- Hospitals:Tertiary academic medical centers with dedicated cardiac surgery departments represent the core installed base for fixed-configuration bypass systems. These facilities in the United States and Germany absorb premium pricing for integrated monitoring and autotransfusion modules amid ECMO duration extension trends.
- Surgical Centers:Ambulatory facilities with constrained capital budgets favor mobile perfusion platforms and disposable-heavy operational models. German distributed hospital networks particularly favor transportable systems enabling bypass capability without dedicated pump room infrastructure.
- Cardiac Care Units:Intensive care settings adopting prolonged ECMO support beyond surgical timeframes.
- Research Institutions:Preclinical and perfusion technology development centers driving next-generation oxygenator biocompatibility testing.
Hospitals command the dominant revenue share; surgical centers are climbing the fastest as mobile platform adoption accelerates.
Technology:
Application context determines technology selection, with mechanically assisted systems anchoring scheduled cardiac surgery and ECMO platforms penetrating emergency critical care.
- Mechanically Assisted:Conventional roller pump and centrifugal pump configurations optimized for predictable bypass durations under two hours. These systems retain dominance at high-volume Japanese surgical centers where standardized coronary bypass protocols minimize perfusionist labor intensity.
- Extracorporeal Membrane Oxygenation:Prolonged circulatory support platforms utilizing diffusion-silicone oxygenators for multi-day critical care maintenance. United States intensivist adoption drives steepest expansion trajectory as veno-venous and veno-arterial configurations displace traditional ventilator-refractory respiratory failure management.
- Mobile Systems:Transportable perfusion units with compact pump-oxygenator assemblies for field deployment.
- Disposable Systems:Single-use circuit components eliminating reprocessing infrastructure requirements.
Mechanically assisted technology retains volume leadership; ECMO platforms gain share fastest through critical care indication expansion.
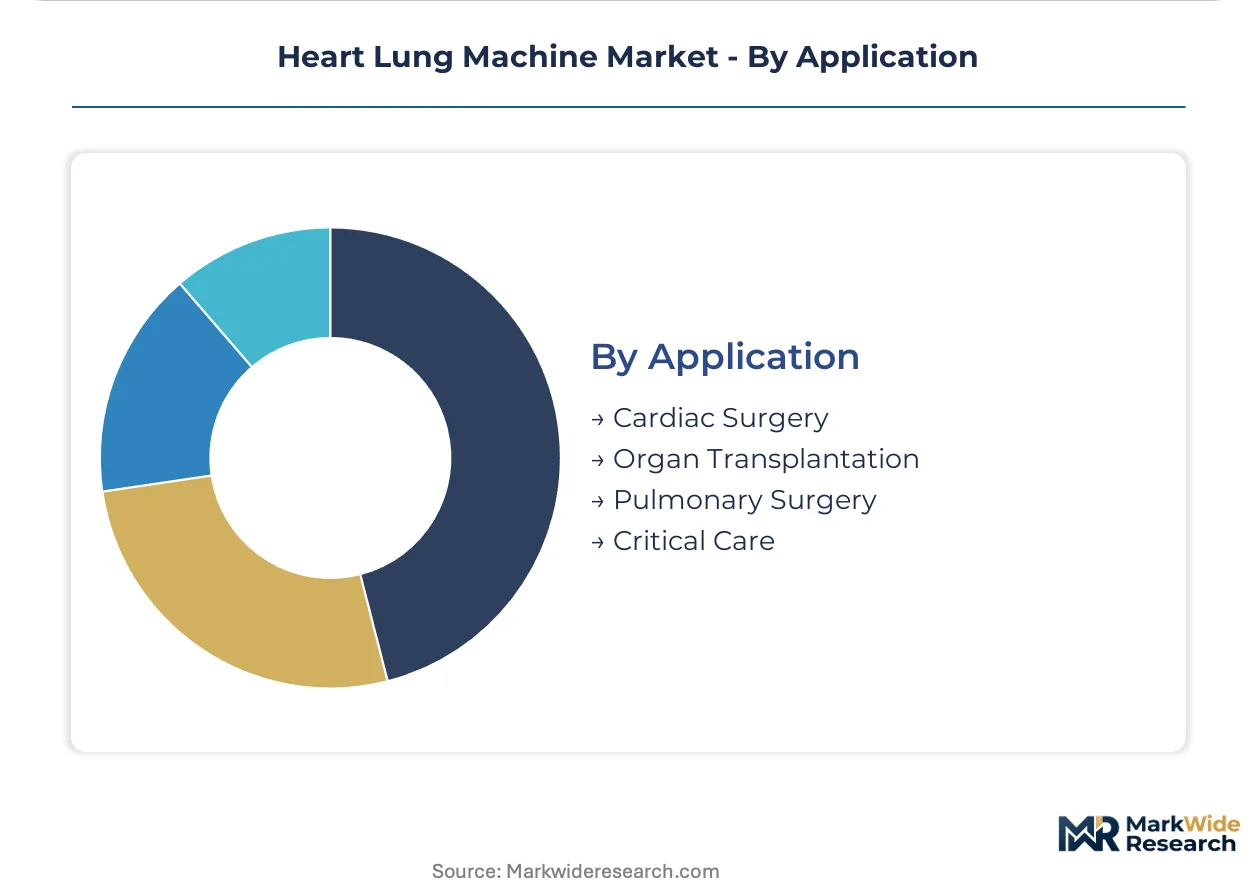
Application:
Procedure complexity and reimbursement environment shape application-level demand concentration across cardiac and non-cardiac surgical domains.
- Cardiac Surgery:Coronary artery bypass grafting, valve replacement, and aortic reconstruction procedures constitute the foundational use case for full cardiopulmonary bypass. German and Japanese tertiary centers sustain procedure volumes through aging demographic surgical demand, though off-pump techniques and transcatheter alternatives erode growth in select patient cohorts.
- Organ Transplantation:Ex-vivo organ perfusion and recipient support during heart-lung transplantation require specialized bypass configurations with extended support tolerance. United States transplant centers drive specialized oxygenator demand as thoracic organ allocation volumes expand.
- Pulmonary Surgery:Lung resection and tracheal reconstruction procedures utilizing partial bypass support.
- Critical Care:ECMO deployment for refractory cardiogenic shock and respiratory failure independent of surgical indication.
Cardiac surgery anchors revenue concentration; critical care ECMO applications show the steepest volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing clusters while cost-sensitive procurement dominates emerging Asian markets. This asymmetry shapes regional investment patterns and technology transfer flows. Manufacturers calibrate product portfolios to match reimbursement environments and surgical infrastructure maturity.
United States
FDA 510(k) clearance pathways and IRA hospital infrastructure incentives drive ECMO platform deployment at rural cardiac centers. Tertiary academic medical centers in Boston and Houston sustain premium pricing for integrated perfusion systems through complex aortic procedure volumes.
Germany
EU MDR technical documentation requirements accelerate oxygenator refresh cycles while compressing margins for disposable circuit producers. Distributed hospital networks in Bavaria and North Rhine-Westphalia favor mobile perfusion platforms that bypass fixed-installation capital constraints.
Japan
PMDA regulatory harmonization with ISO 13485 standards streamlines multi-territory registration for domestic manufacturers. Tokyo and Osaka medical clusters anchor demand through aging demographic surgical volumes and standardized coronary bypass protocols.
China
NMPA medical device classification rules and domestic innovation incentives reshape procurement toward locally manufactured oxygenator components. Yangtze River Delta surgical centers build de novo bypass capabilities through technology licensing agreements with European suppliers.
India
CDSCO import registration requirements and PLI scheme medical device incentives attract contract manufacturing investment for membrane oxygenator assembly. Maharashtra and Karnataka cardiac programs expand extracorporeal support infrastructure through public-private hospital partnerships.
Heart Lung Machine Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with end-to-end perfusion portfolios command premium positioning at tertiary centers, while component specialists capture recurring revenue through disposable oxygenator supply. Three archetypes dominate: full-system integrators, disposable circuit specialists, and regional equipment fabricators. Competitive moves concentrate on strategic partnerships for membrane technology access and geographic licensing arrangements to penetrate emerging surgical markets.
Among diversified medical technology conglomerates, Medtronic and LivaNova exemplify contrasting strategic positions. Medtronic anchors the integrated-systems tier through its comprehensive perfusion portfolio spanning pumps, oxygenators, and monitoring subsystems. LivaNova occupies a specialized position emphasizing autotransfusion and real-time hematologic monitoring convergence. Getinge AB represents the critical-care ecosystem approach, leveraging sterile disposable supply chain control to bundle perfusion components with broader hospital infrastructure contracts.
| Leading Market Players |
|---|
| Medtronic |
| LivaNova |
| Getinge AB |
| Terumo Corporation |
| Fresenius Medical Care |
| Braile Biomedica |
| NIPRO Corporation |
| Edwards Lifesciences Corporation |
| Tianjin Medical |
| Others |
Value Chain & Pricing Dynamics
Long-term total perfusion service agreements lock in oxygenator supply access while anchoring price visibility across multi-year hospital contracts in Germany and Japan. These bundled arrangements bundle capital equipment, disposable circuits, and on-site technical support, compressing transactional flexibility for component assemblers while securing volume commitments for integrated manufacturers.
Pricing Analysis
The customization-premium spread separates configured-to-order bypass systems from standard oxygenator configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and after-sales service bundling. Cost compression in standard disposable tiers is intensifying because fluoropolymer membrane commoditization erodes differentiation. Ambulatory surgical centers exhibit highest price sensitivity; tertiary academic medical centers absorb premium pricing for integrated monitoring modules.
Supply Chain Analysis
Inbound logistics costs from East Asian chemical producers fluctuate with container availability on transpacific trade lanes serving oxygenator membrane substrate flows. Manufacturing concentrates in Germany, Japan, and the United States for finished systems, while fluoropolymer and silicone raw materials draw from Chinese and South Korean chemical producers. Single-source vulnerability in specialized membrane substrates creates supply chain risk. Distribution runs through sterile disposable supply chains feeding into critical care ecosystem bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECMO duration extension represents an early-cycle expansion story as intensivist adoption of prolonged circulatory support creates new addressable patient populations beyond traditional surgical timeframes.
For Market Incumbents: Secure perfusionist workforce pipelines through specialized training partnerships to counter retirement attrition threatening operational capacity. Deepen backward integration into fluoropolymer membrane substrate production to defend margin position against polymer input volatility from East Asian chemical producers. For New Entrants and Emerging Players: Autotransfusion-monitoring convergence gaps in mid-tier cardiac programs offer white-space entry where incumbents under-serve with bundled premium offerings. Target German distributed hospital networks seeking mobile perfusion platforms without fixed-installation infrastructure. Pursue EU MDR technical documentation pathway acceleration as differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a platform-expansion phase that favors disposable circuit specialists with regulatory affairs infrastructure. Long-term viability over the coming decade hinges on oxygenator biocompatibility benchmark evolution and extended-duration ECMO indication expansion. Monitor FDA 510(k) clearance velocity for pump-oxygenator interface modifications as inflection indicator for product refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Accelerated clearance timelines enable faster oxygenator refresh cycles across European tertiary hospitals. |
| Hospital System Partnership | Multi-year total perfusion service agreements displace transactional purchasing at integrated delivery networks. |
| Software Companion Development | Real-time hematocrit and coagulation monitoring integration creates bundled value propositions for high-volume programs. |
| Reimbursement Strategy | US IRA hospital infrastructure incentives create procurement opportunities for transportable ECMO platforms in underserved zones. |
| CE Marking Pathway | Expanded clinical evidence packages for legacy oxygenator designs reshape regulatory affairs resource allocation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and GPO contract archives. Interviews with perfusionists, biomedical engineers, hospital purchasing committee members, and regulatory affairs directors at oxygenator manufacturers inform demand-side and supply-side perspectives. Bottom-up sizing of oxygenator disposable volumes triangulates against top-down cardiac surgery procedure estimates.
Segmentation dimensions modeled include product type, end user facility tier, technology platform, and application context across the projection horizon. CAGRs derive from procedure volume trajectories, technology substitution rates, and pricing trend analysis. ECMO indication expansion and minimally invasive cardiac surgery penetration serve as key demand-side forecast inputs alongside fluoropolymer cost pass-through assumptions.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Global Cardiac Mapping Market