
 Heart Scan Market | 2026-2036
Heart Scan Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Scan Market Analysis
High-resolution 3D imaging specification tiers are rotating toward premium diagnostic workflows. Siemens Healthineers leverages its dual-source CT platform to dominate advanced cardiac protocols across European and North American installations. GE Healthcare anchors its position through deep integration of AI Diagnostics into echocardiography consoles, streamlining point-of-care workflows.
Heart scan modalities encompass non-invasive imaging technologies that measure cardiac structure, perfusion, and electrical activity using ionizing radiation, magnetic fields, or ultrasonic waves with spatial resolutions reaching sub-millimeter scales. These systems enable coronary artery disease detection, myocardial viability assessment, and arrhythmia source localization for clinical treatment planning. Echocardiography occupies the largest installed base due to portability and lower capital requirements, while CT Angiography captures expanding share in emergency department rule-out protocols. AI Diagnostics represents the fastest-growing technology segment as algorithmic analysis reduces interpretation variability and shortens reporting turnaround.
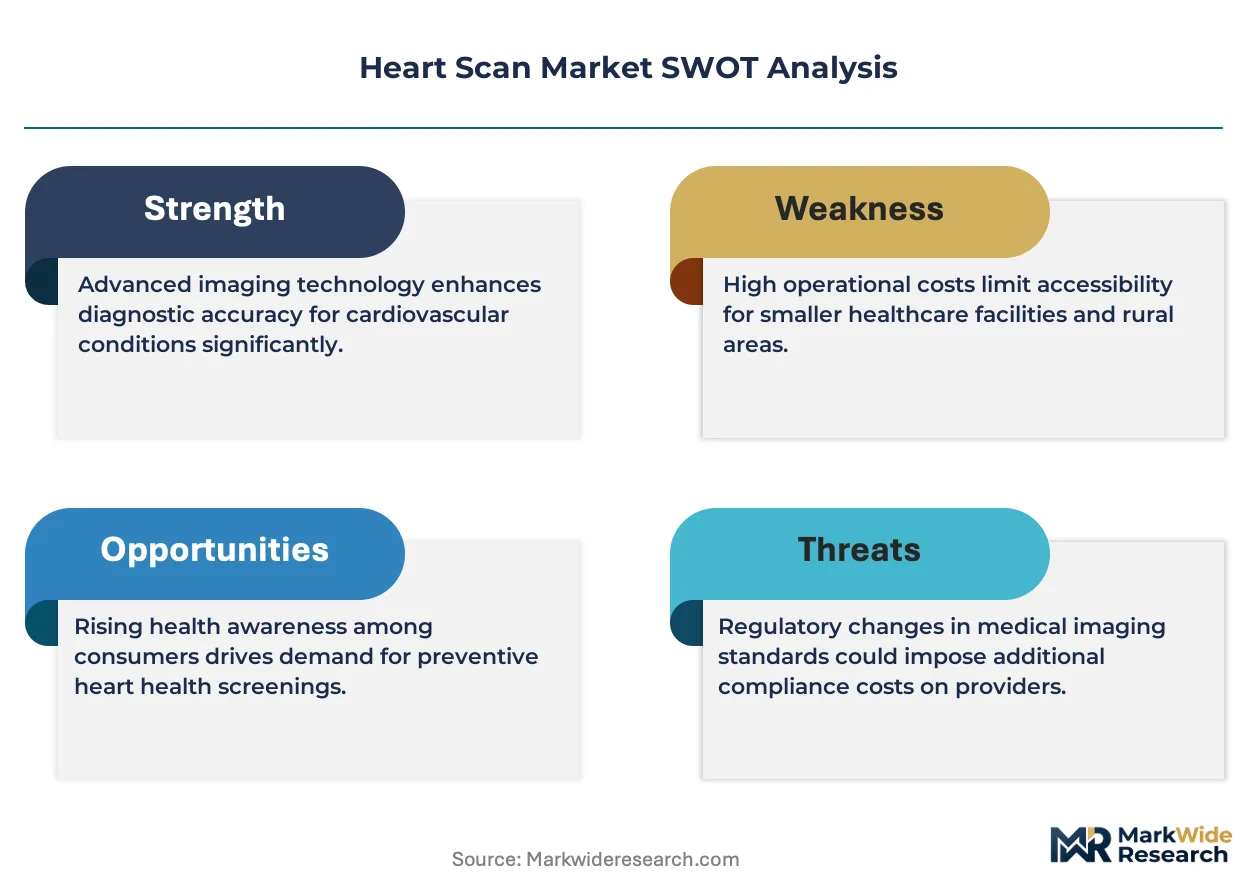
FDA premarket notification pathways and CE marking under the EU MDR govern device commercialization, with both frameworks tightening clinical evidence requirements for software-as-a-medical-device components. HIPAA and GDPR impose parallel constraints on patient data flows from connected imaging systems, elevating cybersecurity investment priorities. Stakeholders must weigh capital deployment timing against evolving reimbursement codes for AI-augmented reads and remote monitoring delivery modes.
Market Dynamics
AI Diagnostics is compressing interpretation timelines while FDA premarket notification pathways accelerate clearance velocity for algorithmic cardiac imaging tools.
Growth Catalysts
- EU MDR framework:Streamlined CE marking pathways for software-as-a-medical-device components reduce time-to-market for AI-enhanced cardiac algorithms across European hospital networks.
- Emergency department protocols:CT Angiography rule-out workflows for acute chest pain are expanding installed base requirements in tertiary care facilities.
- Japan's aging demographic:Replacement cycles for echocardiography systems are shortening as cardiology departments upgrade to AI-integrated consoles.
Market Restraints
- Gadolinium supply concentration:Magnetic resonance perfusion imaging faces input cost volatility tied to rare earth processing capacity in China.
- GDPRI data localization:Cross-border cloud processing of cardiac imaging datasets faces structural friction from European patient data flow restrictions.
- Interventional cardiology substitution:Fractional flow reserve wire-based measurements compete with non-invasive CT-FFR algorithms in coronary lesion assessment.
Strategic Opportunities
- India's tier-2 cities:Underpenetrated cardiac imaging infrastructure creates whitespace for portable echocardiography deployment in state-run hospitals.
- Remote monitoring convergence:Wearable ECG patches paired with AI triage algorithms enable post-discharge arrhythmia surveillance outside traditional hospital settings.
- US IRA imaging incentives:Medicare reimbursement stability for AI-augmented reads supports outpatient cardiac center expansion.
Industry Challenges
- Algorithm validation timelines:Multi-site clinical evidence requirements for FDA 510(k) clearance extend development cycles for machine learning-based perfusion quantification tools.
- Legacy PACS integration:Hospital IT departments face execution friction connecting cloud-native AI platforms to on-premise archival systems from prior procurement generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Scan Market |
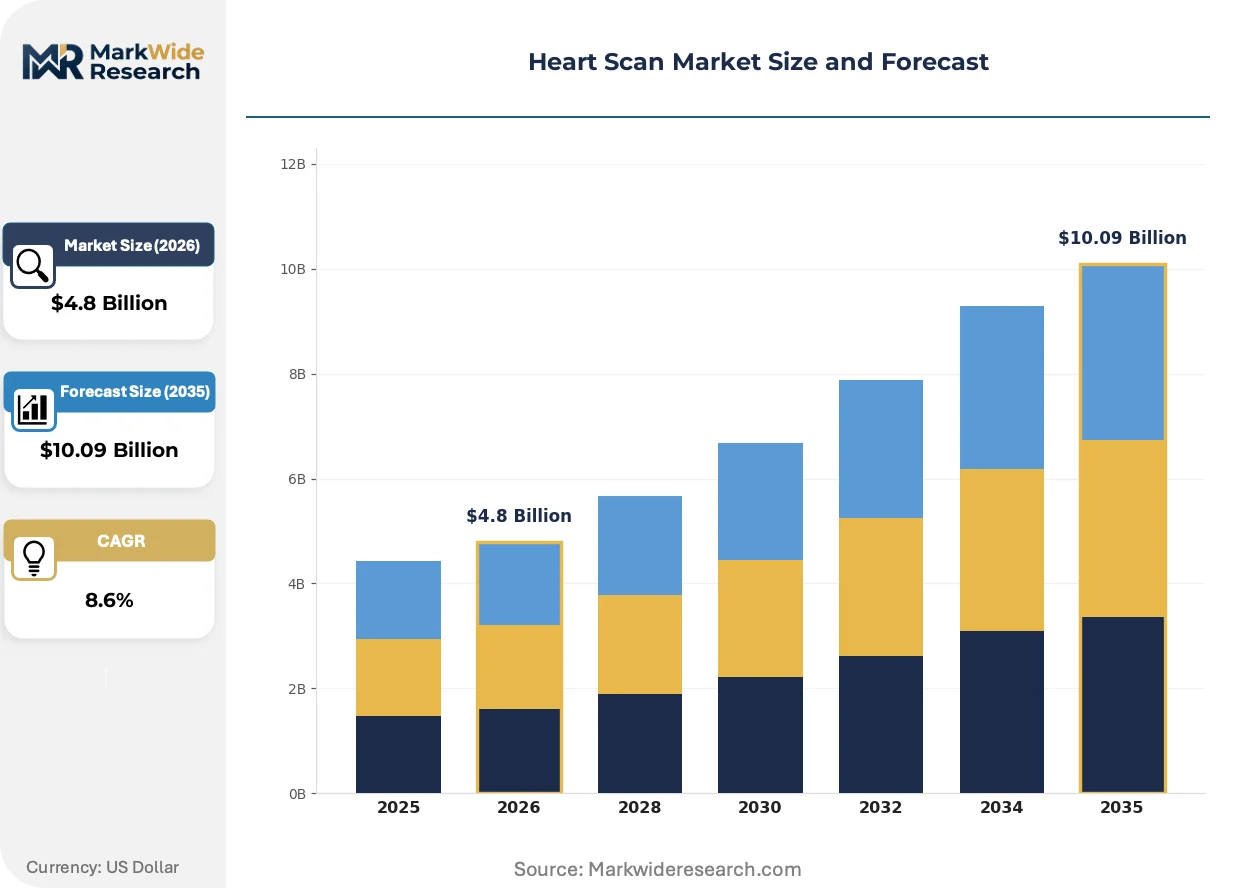
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Angiography, MRI, Echocardiography, Nuclear Stress Testing Technology: 3D Imaging, Digital Tomosynthesis, Portable Devices, AI Diagnostics End User: Cardiology Clinics, Hospitals, Research Institutions, Outpatient Centers Delivery Mode: In-Hospital, At-Home, Remote Monitoring, Mobile Units |
| Companies Covered | Toshiba Corporation, Schiller AG, Siemens Healthineers, Midmark Corporation, F. Hoffmann-La Roche Ltd, GE Healthcare, Hitachi Corporation, Welch Allyn Inc, Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Scan Market Emerging Trajectories
Cardiac imaging workflows are pivoting toward algorithmic automation while regulatory frameworks tighten evidence standards for software-enabled diagnostics.
Photon-counting CT detectors are displacing energy-integrating sensor architectures in coronary angiography protocols. Tertiary cardiac centers in Germany and the United States are retrofitting scanner gantries at compressed capital cycles. The technology is displacing conventional spatial resolution limitations that previously required invasive catheterization for distal vessel assessment.
EU AI Act risk classification tiers are reshaping commercialization requirements for diagnostic algorithms. High-risk cardiac analysis tools now face mandatory conformity assessment procedures before CE marking. European radiology departments are prioritizing vendors with established quality management systems to preempt regulatory bottlenecks.
Hospital procurement committees are unbundling hardware acquisition from software subscription terms. Cardiology departments now negotiate algorithm licensing separately from scanner capital leases, compressing vendor lock-in duration. This pattern is most visible in United States academic medical centers pursuing multi-vendor AI marketplaces.
Heart Scan Market Segmentation
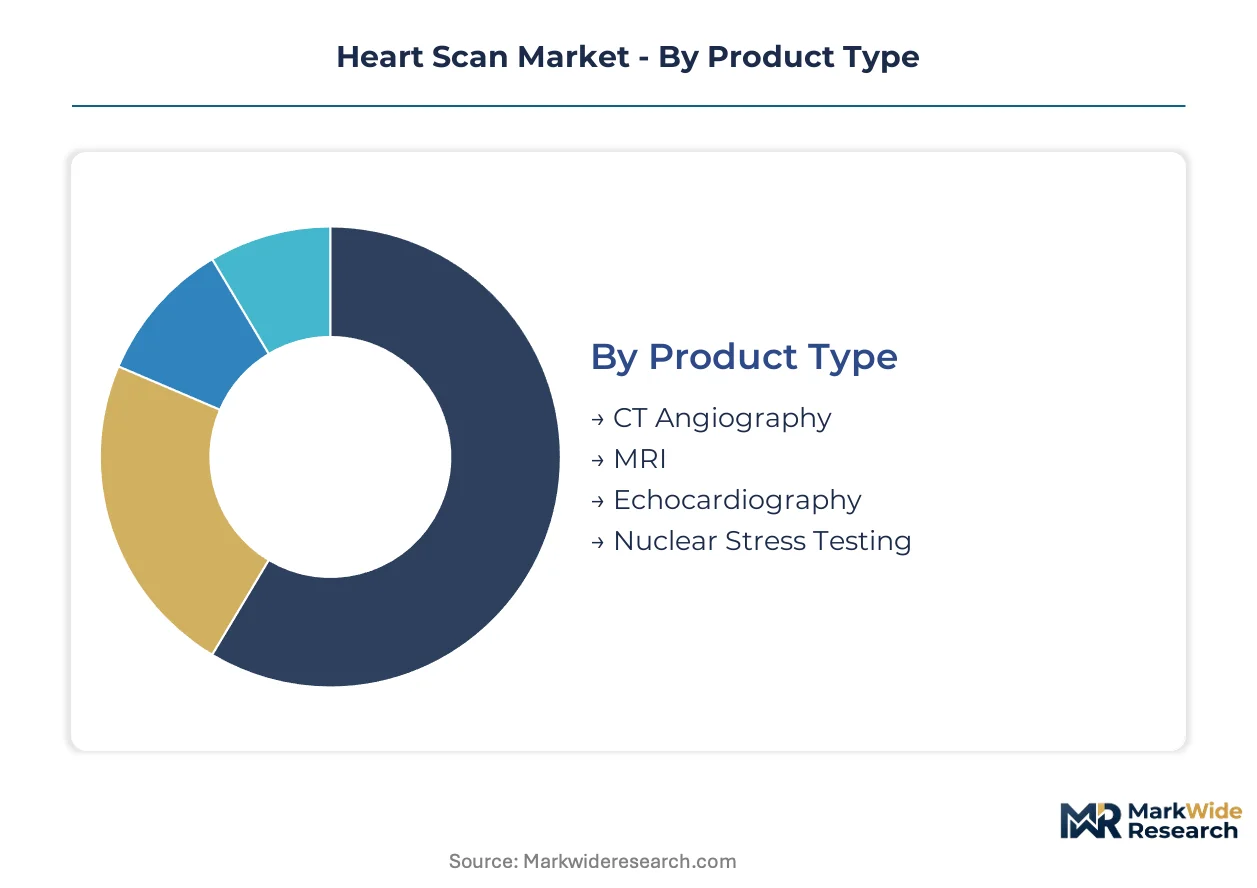
Cardiac imaging procurement splits across hardware modalities, algorithmic layers, care settings, and patient touchpoints. Each segmentation axis reveals distinct margin profiles, regulatory pathways, and vendor competitive dynamics that shape capital allocation decisions.
Product Type:
Channel flow varies sharply by imaging modality — CT Angiography and MRI concentrate through hospital capital committees, while Echocardiography penetrates outpatient networks via distributor relationships.
- CT Angiography:Dual-source and photon-counting detector architectures deliver sub-millimeter coronary spatial resolution. Demand clusters in United States and German tertiary emergency departments executing chest pain rule-out protocols under compressed turnaround requirements.
- Echocardiography:Portable console configurations dominate installed base expansion with lower capital thresholds and point-of-care deployment flexibility. Japan's cardiology departments are replacing legacy systems with AI-integrated consoles as reimbursement codes stabilize for algorithm-augmented reads.
- MRI:Magnetic resonance perfusion imaging requires gadolinium-based contrast agents tied to rare earth supply chains.
- Nuclear Stress Testing:SPECT protocols maintain presence in outpatient cardiac centers despite radiation exposure tradeoffs.
Echocardiography dominates installed base. CT Angiography is where expansion concentrates.
Technology:
Cost tiering separates premium visualization stacks from scaled algorithmic deployments, with hardware-software bundling patterns diverging across customer segments.
- AI Diagnostics:Machine learning algorithms reduce interpretation variability and compress reporting timelines for perfusion quantification and wall motion analysis. FDA 510(k) premarket notification pathways and EU MDR software-as-a-medical-device frameworks are accelerating clearance velocity for cardiac imaging tools.
- 3D Imaging:High-resolution volumetric reconstruction enables structural heart intervention planning without invasive catheterization. German and United States cardiac centers are retrofitting scanner gantries at compressed capital cycles to capture distal vessel assessment previously requiring invasive procedures.
- Digital Tomosynthesis:Limited-angle reconstruction methods supplement conventional projection imaging in select coronary applications.
- Portable Devices:Handheld ultrasound probes and wearable ECG patches extend cardiac monitoring beyond fixed installation footprints.
3D Imaging commands premium pricing tiers. AI Diagnostics is climbing the fastest as procurement committees unbundle software subscriptions from hardware leases.
End User:
Application intensity varies by care setting — emergency throughput demands differ from elective procedural planning and longitudinal research cohorts.
- Hospitals:Tertiary cardiac centers consolidate multi-modality suites under unified PACS infrastructure, driving enterprise-scale AI platform procurement. United States academic medical centers are pioneering multi-vendor algorithm marketplaces to reduce vendor lock-in duration.
- Cardiology Clinics:Focused outpatient facilities prioritize echocardiography throughput and CT Angiography rule-out efficiency over research-grade MRI capabilities.
- Outpatient Centers:Ambulatory surgical and diagnostic sites exploit Medicare reimbursement stability for AI-augmented reads under IRA imaging incentives.
- Research Institutions:Longitudinal imaging biobanks and clinical trial endpoints require standardized acquisition protocols across multi-site networks.
Hospitals anchor capital deployment volume. Outpatient Centers are gaining share fastest as site-of-care migration accelerates.
Delivery Mode:
Geographic reach constraints shape channel economics — fixed infrastructure carries depreciation schedules while mobile and remote configurations face connectivity and reimbursement verification hurdles.
- In-Hospital:Fixed installation base maintains highest reimbursement rates and regulatory clarity for complex cardiac protocols. Germany's hospital networks are expanding photon-counting CT retrofit programs under regional procurement frameworks.
- Remote Monitoring:Wearable ECG patches paired with AI triage algorithms enable post-discharge arrhythmia surveillance outside traditional facility settings. GDPR data localization requirements in Europe create structural friction for cross-border cloud processing of cardiac datasets.
- Mobile Units:Trailer-mounted CT and echocardiography systems serve rural and event-based screening populations with limited fixed infrastructure access.
- At-Home:Consumer-grade ECG wearables operate below medical device thresholds in most jurisdictions, creating regulatory gray zones for diagnostic claims.
In-Hospital retains reimbursement premiums. Remote Monitoring is where technology investment is concentrating as post-acute surveillance contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export photon-counting CT systems to United States emergency departments under compressed procurement timelines. Japanese vendors supply AI-integrated echocardiography consoles to Southeast Asian hospital networks. Cross-border regulatory alignment between FDA and PMDA accelerates dual-market clearance velocity for algorithmic cardiac tools.
United States
Medicare reimbursement stability under IRA imaging incentives drives outpatient cardiac center expansion. FDA 510(k) premarket notification pathways compress clearance timelines for AI-augmented diagnostic algorithms. Tertiary emergency departments in Boston and Houston retrofit scanner gantries for chest pain rule-out protocols.
Germany
Regional hospital procurement frameworks fund photon-counting CT retrofit programs across university-affiliated cardiac centers. EU MDR software-as-a-medical-device pathways streamline CE marking for algorithmic perfusion analysis tools. The Munich-Stuttgart corridor concentrates dual-source CT manufacturing and clinical validation sites.
Japan
Aging demographics shorten replacement cycles for echocardiography systems in metropolitan cardiology departments. PMDA regulatory harmonization with FDA accelerates dual-market submissions for AI-integrated consoles. Tokyo and Osaka academic medical centers pioneer multi-vendor algorithm marketplaces to reduce vendor lock-in.
India
State-run hospitals in tier-2 cities generate whitespace demand for portable echocardiography deployment. CDSCO medical device registration requirements create compliance friction for imported AI diagnostic platforms. Maharashtra and Karnataka urban clusters concentrate private cardiology clinic expansion and distributor network buildouts.
United Kingdom
NHS England procurement frameworks prioritize AI-augmented read reimbursement in outpatient diagnostic pathways. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance requirements for software-enabled cardiac tools. The London-Oxford-Cambridge triangle anchors clinical validation partnerships between academic medical centers and algorithm developers.
Heart Scan Market Vendor Landscape
Listed leaders compete with private specialists across capital deployment cycles and algorithmic innovation timelines. Siemens Healthineers and GE Healthcare anchor the consolidated imaging hardware tier through dual-source CT and AI-integrated echocardiography platforms. Mid-sized specialists concentrate on portable device configurations and regional service networks. Dominant competitive moves include unbundling software subscriptions from hardware leases and establishing multi-vendor AI marketplaces within academic medical centers.
Within the diversified health technology tier, Siemens Healthineers and GE Healthcare exemplify integrated platform strategies spanning hardware and algorithmic layers. Koninklijke Philips NV occupies a position in connected care ecosystems. Toshiba Corporation and Hitachi Corporation represent Japanese industrial conglomerates with imaging divisions. Schiller AG and Welch Allyn Inc sit within the portable diagnostic specialist archetype, while F. Hoffmann-La Roche Ltd anchors laboratory diagnostics convergence with cardiac biomarker workflows.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Schiller AG |
| Siemens Healthineers |
| Midmark Corporation |
| F. Hoffmann-La Roche Ltd |
| GE Healthcare |
| Hitachi Corporation |
| Welch Allyn Inc |
| Koninklijke Philips NV |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) premarket notification pathways and EU MDR software-as-a-medical-device frameworks gate both vendor qualification and price differentiation in cardiac imaging procurement. Hospital capital committees and outpatient center administrators face tiered cost structures where regulatory clearance tier directly correlates with algorithm licensing premiums and hardware lease terms.
Pricing Analysis
Hospital capital committees anchor pricing negotiations for CT Angiography and MRI platforms through multi-year equipment leases bundled with service contracts. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting CT configurations from dual-source systems and conventional detector architectures. Cost compression in portable echocardiography segments intensifies as distributor networks compete for state-run hospital contracts in emerging markets. Outpatient cardiac centers exhibit highest price sensitivity due to reimbursement verification uncertainties, while tertiary academic medical centers prioritize AI-augmented read capabilities over capital cost minimization.
Supply Chain Analysis
Extended lead times for photon-counting CT detector arrays and gadolinium-based contrast agents compress inventory buffers across German and United States manufacturing hubs. Rare earth processing capacity in China and specialized semiconductor fabrication in Taiwan and South Korea anchor upstream supply for magnetic resonance perfusion imaging and AI inference hardware. Single-source vulnerability for gadolinium concentrates creates input cost volatility that propagates through MRI system pricing. Distribution runs through regional hospital procurement frameworks in Germany, GPO contracts in the United States, and distributor networks in Japan and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac imaging procurement is shifting toward platform-economics dynamics where multi-vendor AI marketplaces within hospital systems reduce vendor lock-in and enable algorithm interoperability across hardware modalities.
For Market Incumbents: Compound defensive positioning through backward integration into photon-counting CT detector manufacturing and captive AI algorithm development pipelines. Siemens Healthineers and GE Healthcare face substitution pressure from portable echocardiography specialists and cloud-native AI platforms; priority levers include CE marking pre-emption under EU AI Act high-risk classification tiers and PACS infrastructure control through legacy archival system integration. For New Entrants and Emerging Players: Anchor in India's tier-2 state-run hospitals where portable echocardiography deployment whitespace meets CDSCO registration compliance friction for established multinational vendors. Remote monitoring convergence through wearable ECG patches paired with AI triage algorithms offers the most penetrable segment; go-to-market execution should prioritize hospital-at-home contracting partnerships over direct capital equipment sales. For Investors and Strategic Acquirers: EU AI Act risk classification tiers and FDA 510(k) pathway compressions reshape the acquisition landscape toward vendors with established quality management systems and multi-site clinical validation datasets. Five-to-ten year viability favors algorithm developers with HIPAA-compliant cloud architectures and GDPR data localization capabilities. Signal to watch: Medicare reimbursement code finalization for AI-augmented reads under IRA imaging incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor AI Marketplace Development | Hospital IT committees in Boston and Houston reduce vendor lock-in through interoperable algorithm platforms. |
| Photon-Counting CT Retrofit Programs | German regional procurement frameworks accelerate capital cycles across university-affiliated cardiac centers. |
| Portable Echocardiography Distributor Networks | Maharashtra and Karnataka urban clusters enable state-run hospital penetration with lower capital thresholds. |
| CE Marking Pre-emption Under EU AI Act | European radiology departments prioritize vendors with established high-risk conformity assessment procedures. |
| Reimbursement Strategy for AI-Augmented Reads | Medicare stability under IRA incentives supports outpatient cardiac center expansion in United States ambulatory settings. |
Methodological Framework
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and cardiology department heads provided ongoing calibration across primary interview rounds and secondary source validation. FDA 510(k) premarket notification databases, EU MDR CE marking registries, CMS Medicare reimbursement filings, and hospital procurement contract disclosures supplied quantitative anchors. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation converged on segment-level estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include imaging modality, technology layer, care setting, patient touchpoint, and regional regulatory cluster. CAGRs derived from logistic adoption curves for AI Diagnostics penetration and replacement cycle compression for aging echocardiography systems. Industry-specific forecast inputs encompassed PMDA-FDA harmonization timelines and gadolinium supply chain concentration metrics.
Decision-makers should treat outputs as directional under assumptions of reimbursement code stability and rare earth processing capacity continuity; material deviation in Medicare AI-read finalization or China export restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market