
 Lemonade Market | 2026-2036
Lemonade Market Size, Share, and Industry Trends Forecast 2026-2036
Lemonade Market Analysis
Premium ingredient sourcing is rotating the lemonade category toward cleaner-label positioning. The Coca-Cola Company leverages its fountain and retail distribution infrastructure to sustain volume leadership in food service channels. PepsiCo Inc. anchors its portfolio through multi-brand lemonade offerings that span mainstream and reduced-sugar tiers. Keurig Dr Pepper Inc. differentiates via regional flavor extensions and private-label manufacturing partnerships.
Lemonade is a lemon-juice-based beverage typically containing water, sweetener, and citric acid, with pH levels ranging from 2.0 to 3.5 depending on formulation; it serves as a refreshment beverage, mixer, and functional hydration option across consumer and commercial settings. Sparkling lemonade occupies the fastest-expanding product tier as carbonated refreshment demand migrates from colas toward fruit-based alternatives. Tetra pack formats capture structural margin advantages through ambient distribution economics and reduced logistics cost per unit across emerging retail channels.
FDA enforces juice content labeling standards that define lemonade authenticity thresholds, while USDA organic certification governs premium tier positioning and price architecture. The EU Green Deal and F-Gas Regulation indirectly shape packaging material transitions as brands evaluate aseptic carton versus recyclable plastic pathways. Stakeholders must monitor evolving sugar taxation frameworks and biodegradable packaging mandates to align portfolio investment with compliance trajectories.
Market Dynamics
Sugar-content disclosure mandates from the FDA and parallel EU nutrition labeling rules are forcing simultaneous reformulation across conventional and premium lemonade tiers, compressing margin structures while accelerating clean-label ingredient substitution.
Growth Catalysts
- Carbonation Migration:Consumer preference displacement from cola-based refreshment toward fruit-forward sparkling alternatives is expanding addressable occasions for lemonade variants in fountain and packaged formats.
- REACH Chemical Compliance:European packaging material standards under ECHA oversight are accelerating transitions from conventional plastics toward aseptic carton and fiber-based substrates with superior shelf-life economics.
- Quick-Service Restaurant Fountain Expansion:Food service channel operators are deploying lemonade as a margin-accretive beverage option with lower syrup cost per serving versus carbonated soft drink alternatives.
Market Restraints
- Lemon Concentrate Price Volatility:Weather-driven harvest variability in Argentina and Spain concentrates supply risk for primary raw material, compressing processor margins during deficit cycles.
- Refrigerated Distribution Cost Burden:Cold-chain logistics requirements for fresh-squegmented lemonade impose per-unit cost penalties that ambient-stable alternatives avoid through tetra pack aseptic processing.
- Reduced-Sugar Taste Threshold Limitation:Stevia and monk fruit formulations encounter consumer rejection above specific bitterness perception thresholds, constraining formulation flexibility for FDA-compliant reduced-sugar claims.
Strategic Opportunities
- India Urban Modern Trade Penetration:Organized retail expansion in Mumbai, Delhi, and Bangalore creates shelf-space access for premium imported and domestic craft lemonade variants targeting affluent metro consumers.
- Functional Hydration Positioning:Electrolyte fortification and adaptogenic ingredient integration enables migration from refreshment-only positioning toward sports and wellness adjacent occasions.
- EU Green Deal Packaging Incentives:Biodegradable mandate trajectories and extended producer responsibility frameworks reward early adopters of fiber-based or compostable packaging substrates with preferential retail access.
Industry Challenges
- Clean-Label Formulation Expertise Scarcity:Food science talent capable of delivering stability, taste, and shelf-life without artificial preservatives commands premium compensation and limited availability.
- USDA Organic Certification Timeline:Three-year transition requirements for ingredient supply chain conversion delay premium tier entry for conventional processors seeking organic positioning.
- Legacy Equipment Retrofit Complexity:Aseptic filling line installation and hot-fill system modification demand capital deployment with extended payback periods relative to existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lemonade Market |
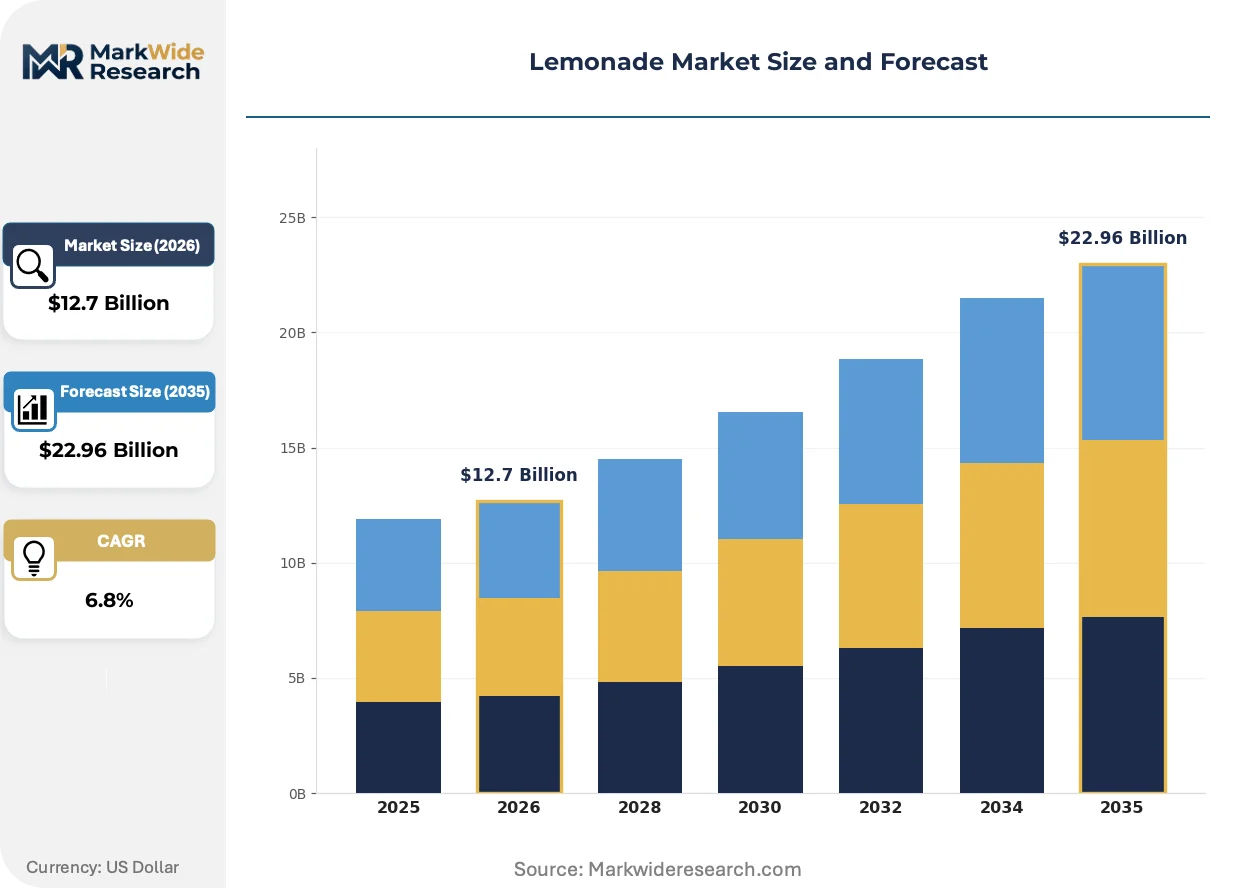
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Lemonade, Sparkling Lemonade, Organic Lemonade, Sugar-Free Lemonade Packaging Type: Bottles, Cans, Tetra Packs, Pouches Sales Channel: Retail, Online, Food Service, Vending Machines Flavor Type: Traditional Lemon, Strawberry Lemonade, Mint Lemonade, Raspberry Lemonade |
| Companies Covered | AriZona Beverages USA LLC, Nestlé S.A., The Coca-Cola Company, Britvic Soft Drinks Limited, Snapple Beverage Corp., PepsiCo Inc., The Kraft Heinz Company, Suntory Holdings Ltd., Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lemonade Market Emerging Trajectories
Formulation science and packaging engineering are converging to enable sugar reduction without sensory compromise, while regulatory pressure on single-use plastics accelerates material substitution timelines across both premium and value tiers.
High-pressure processing technology is fragmenting traditional thermal pasteurization dominance in premium lemonade segments. Cold-pressed juice operators and regional craft brands adopt HPP to extend refrigerated shelf life without heat degradation of volatile aromatic compounds. This capability compression enables smaller-scale entrants to compete on freshness claims previously reserved for food service fountain formats.
The EU F-Gas Regulation and parallel EPA hydrofluorocarbon phase-down mandates are reshaping refrigeration-dependent supply chains. Processors must evaluate alternative cooling technologies or ambient-stable formulations to maintain distribution economics. Tetra Pak and SIG Combibloc aseptic carton systems capture structural advantage as brands seek to decouple from refrigerated logistics intensity.
Direct-to-subscription models are displacing conventional retail stocking agreements for premium lemonade variants. Specialty beverage curators and wellness-focused platforms aggregate niche consumer demand outside mass-channel slotting fee structures. This channel innovation concentrates most visibly in California and New York metro corridors where delivery density supports unit economics.
Lemonade Market Segmentation
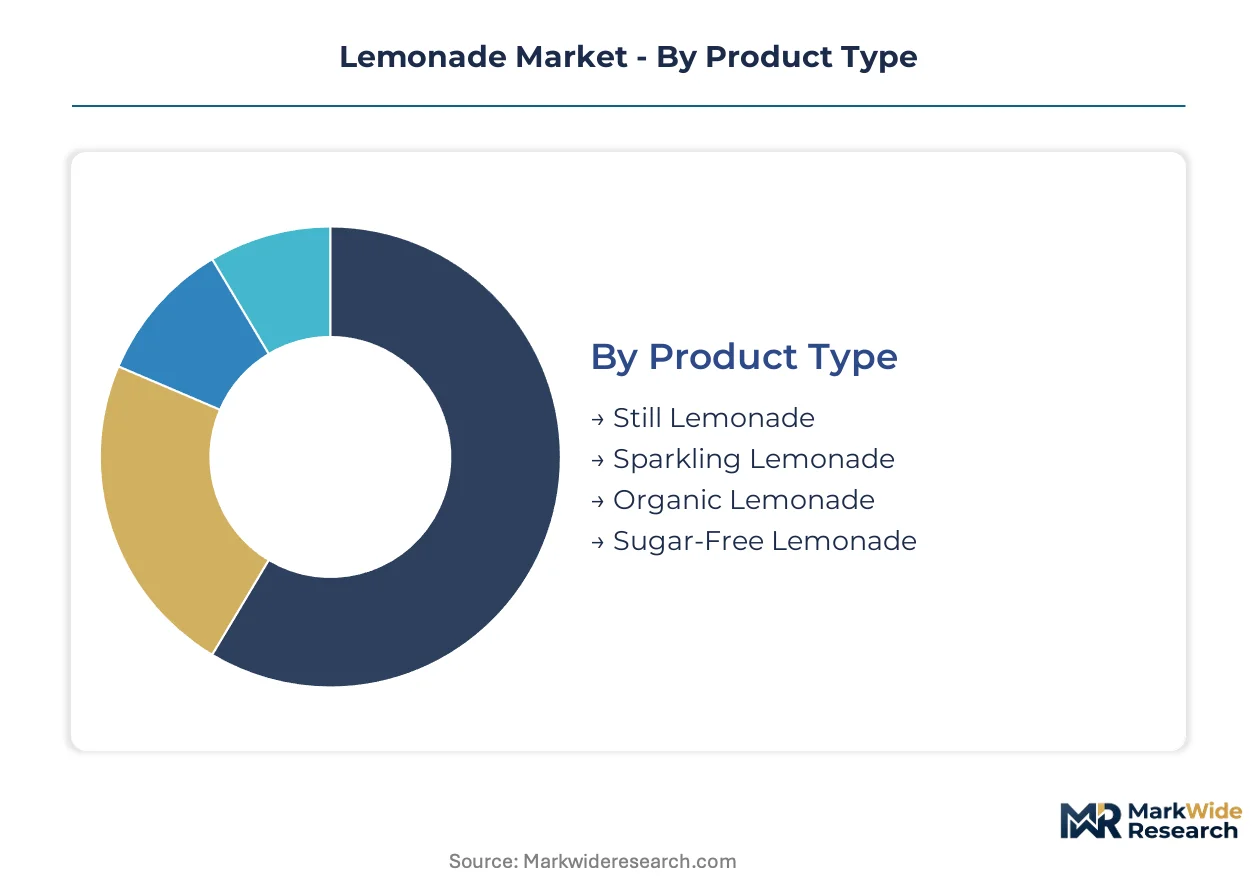
Segmentation in the lemonade market reveals divergent margin architectures across formulation chemistry, packaging physics, and channel economics. Each dimension carries distinct regulatory exposure and capital intensity requirements that reshape competitive entry barriers.
Product Type:
Margin pools concentrate in carbonated and certified-organic formulations where ingredient cost premiums sustain pricing power against commodity alternatives.
- Still Lemonade:Non-carbonated formulations rely on thermal pasteurization or high-pressure processing for shelf stability. Demand clusters in conventional retail and food service fountain formats across the United States, constrained by refrigerated distribution cost burdens.
- Sparkling Lemonade:Carbonated variants blend lemon juice with carbonated water and natural sweeteners, occupying the fastest-expanding product tier as consumer preference migrates from colas toward fruit-based refreshment alternatives.
- Organic Lemonade:USDA-certified formulations command premium shelf positioning through three-year supply chain conversion requirements, limiting rapid scaling for conventional processors.
- Sugar-Free Lemonade:Stevia and monk fruit formulations face taste threshold limitations that constrain FDA-compliant reduced-sugar claim viability.
The dominant share belongs to Still Lemonade, while Sparkling Lemonade is closing the gap fastest.
Packaging Type:
Cost tier stratification separates ambient-stable formats from cold-chain-dependent alternatives, with aseptic carton systems capturing structural logistics advantages.
- Bottles:PET and glass formats dominate premium positioning in conventional retail, though glass imposes weight penalties that elevate freight costs per unit.
- Cans:Aluminum formats align with sparkling variants and on-premise consumption occasions, offering recycling economics that satisfy EU Green Deal packaging mandates.
- Tetra Packs:Aseptic carton systems enable ambient distribution with reduced logistics intensity, capturing margin advantages through extended shelf life without refrigeration.
- Pouches:Flexible formats target single-serve convenience and child-oriented consumption occasions with lower material cost per unit.
Tetra Packs hold the largest volume position, though Cans are expanding most quickly in sparkling applications.
Sales Channel:
Customer type differentiation separates institutional procurement from individual purchase behaviors, each with distinct pricing transparency and loyalty dynamics.
- Retail:Supermarket and convenience store distribution requires slotting fee structures and promotional calendar compliance, concentrating volume in mainstream formulations.
- Online:Direct-to-subscription models aggregate niche demand outside conventional retail economics, with California and New York metro corridors supporting viable delivery density.
- Food Service:Quick-service restaurant fountain placements leverage lemonade as a margin-accretive alternative to carbonated soft drinks with lower syrup cost per serving.
- Vending Machines:Automated retail captures impulse consumption in transit corridors and institutional settings with limited brand selection.
Food Service commands the highest absolute margin contribution, while Online is climbing the fastest.
Flavor Type:
Maturity gradients separate established variants from emerging formulations, with fruit fusion extensions requiring supply chain complexity that challenges regional operators.
- Traditional Lemon:Single-fruit formulations anchor volume through ingredient sourcing simplicity and universal taste familiarity across demographic segments.
- Strawberry Lemonade:Berry fusion variants require dual-source procurement that concentrates production among processors with established fruit concentrate relationships.
- Mint Lemonade:Botanical infusions target wellness-positioned consumption occasions with limited shelf-life stability that favors food service or refrigerated retail.
- Raspberry Lemonade:Premium berry variants command specialty retail placement with higher per-unit pricing that justifies complex supply chain management.
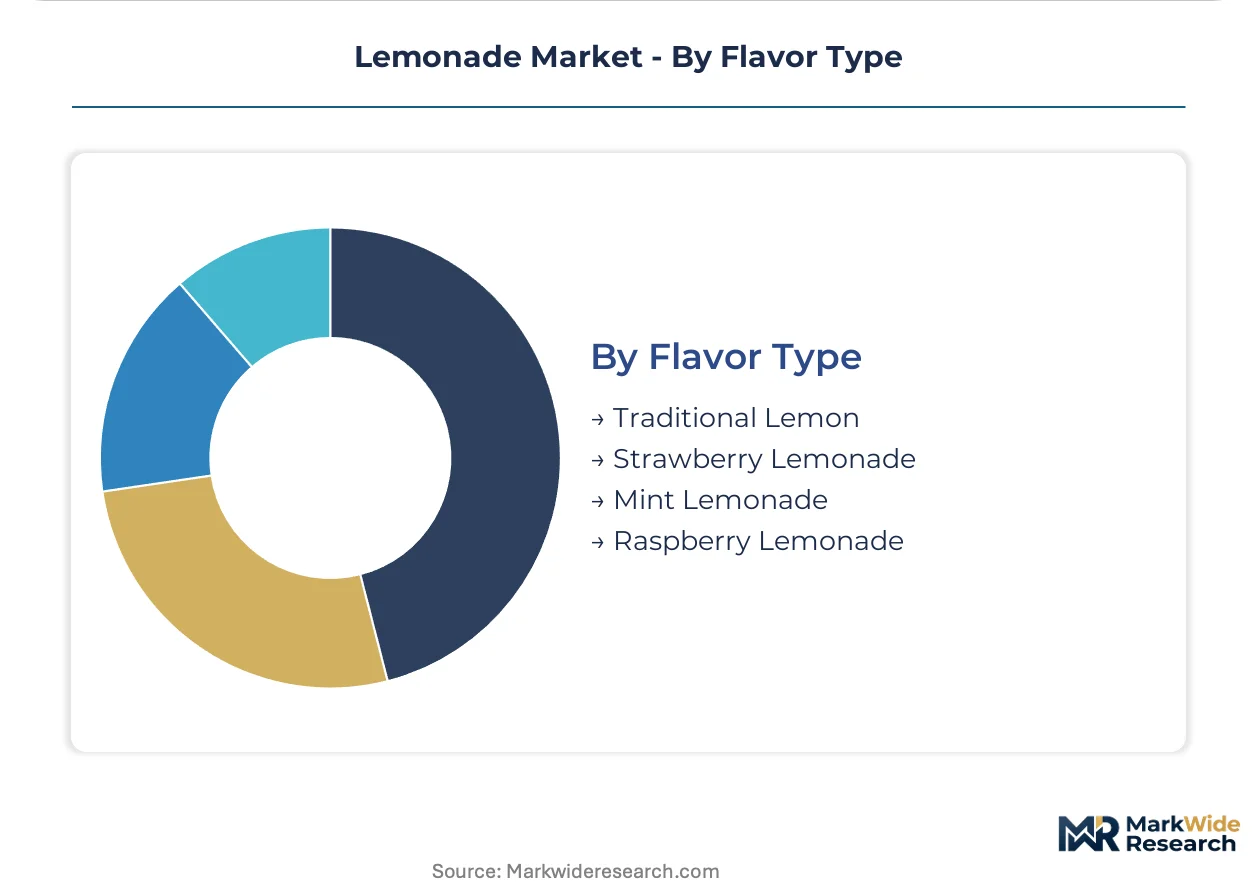
Traditional Lemon retains the dominant volume position, though Strawberry Lemonade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina and Spain supply concentrated lemon juice to bottlers across the United States and Germany, forming the primary trade-flow corridor for raw material inputs in the lemonade value chain.
United States
Quick-service restaurant fountain placements and premium craft variants drive volume concentration. FDA nutrition labeling requirements and sugar-content disclosure mandates reshape formulation priorities across conventional and reduced-sugar tiers. California and New York metro corridors host direct-to-subscription distribution models that aggregate niche consumer demand outside mass-channel economics.
Germany
Sparkling lemonade variants capture carbonation migration from cola-based refreshment toward fruit-forward alternatives. EU Green Deal packaging incentives and F-Gas Regulation compliance accelerate transitions from conventional plastics toward aseptic carton substrates. Bavaria and North Rhine-Westphalia concentrate processing capacity for ambient-stable formulations with extended shelf-life economics.
India
Organized retail expansion in Mumbai, Delhi, and Bangalore creates shelf-space access for premium domestic and imported craft variants. FSSAI labeling standards govern juice content thresholds and sugar disclosure requirements. Maharashtra and Karnataka anchor urban modern trade penetration targeting affluent metro consumers with functional hydration positioning.
Brazil
Weather-driven harvest variability in Argentine lemon concentrate supply creates procurement risk for downstream processors. ANVISA beverage regulations align with Mercosur standards for juice content authenticity and additive disclosure. São Paulo and Minas Gerais concentrate bottling infrastructure for both domestic consumption and regional export.
Japan
High-pressure processing technology adoption extends refrigerated shelf life without thermal degradation of volatile aromatic compounds. METI energy efficiency standards and container recycling mandates shape packaging material selection. Kanto and Kansai regions host cold-pressed juice operators competing on freshness claims previously reserved for food service formats.
Lemonade Market Vendor Landscape
Listed leaders compete with private specialists across formulation tiers, creating a bifurcated structure where scale-driven beverage conglomerates anchor volume through fountain and retail distribution while craft operators capture margin in premium positioning. Strategic archetypes span multi-brand portfolio holders, regional flavor specialists, and private-label manufacturing partners. Competitive moves concentrate on clean-label reformulation capabilities and aseptic packaging line retrofits that reduce refrigerated logistics intensity.
Among North American beverage conglomerates, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven archetypes with multi-brand lemonade portfolios spanning mainstream and reduced-sugar tiers. Keurig Dr Pepper Inc. occupies a position within the regional flavor specialist tier, differentiating through private-label manufacturing partnerships and geographic flavor extensions that serve fragmented retail channels.
| Leading Market Players |
|---|
| AriZona Beverages USA LLC |
| Nestlé S.A. |
| The Coca-Cola Company |
| Britvic Soft Drinks Limited |
| Snapple Beverage Corp. |
| PepsiCo Inc. |
| The Kraft Heinz Company |
| Suntory Holdings Ltd. |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Argentine lemon concentrate processors and North American bottlers lock in supply access while providing twelve-month price visibility against weather-driven harvest volatility. These arrangements concentrate procurement power among scale beverage conglomerates while compressing margin flexibility for regional craft operators lacking volume guarantees.
Pricing Analysis
Current-generation aseptic carton formats command premium positioning against prior-generation refrigerated bottle alternatives, while next-generation fiber-based compostable substrates target EU Green Deal compliance premiums. Three-tier pricing structure across premium organic, standard conventional, and economy private-label tiers stratifies by USDA certification status and brand equity depth. Pricing pressure stems from lemon concentrate cost volatility originating in Argentina and Spain growing regions. Food service fountain operators exhibit lowest price sensitivity due to syrup cost-per-serving economics, while conventional retail channels demonstrate highest sensitivity to promotional calendar pressures.
Supply Chain Analysis
Port congestion on Atlantic trade lanes elevates inbound logistics costs for European processors sourcing Argentine lemon concentrate through Buenos Aires container terminals. Supply concentrates in Argentina, Spain, and California growing regions for primary raw material inputs. Downstream bottling draws from PET resin, aluminum sheet, and aseptic carton substrate suppliers. Single-source vulnerability concentrates in Argentine lemon concentrate supply exposed to El Niño precipitation pattern disruption. Distribution runs through food service fountain networks, conventional retail warehousing, and direct-to-subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lemonade market is recovering from cyclical input cost compression as lemon harvests normalize and aseptic packaging capacity expands. Weather-driven agricultural commodity volatility remains the primary cyclical swing factor.
For Market Incumbents: Fortify fountain distribution exclusivity through multi-year quick-service restaurant syrup supply agreements that preempt private-label displacement. Deepen backward integration into lemon concentrate processing through Argentine agricultural asset partnerships that hedge against spot market volatility. Prioritize aseptic filling line retrofit investments to reduce refrigerated logistics intensity and recover margin compression.
For New Entrants and Emerging Players: Anchor in direct-to-subscription wellness platforms targeting California and New York metro corridors where delivery density supports unit economics outside mass-channel slotting fee structures. Exploit white-space in functional hydration positioning through electrolyte fortification and adaptogenic ingredient integration. Pursue white-label manufacturing partnerships with regional retailers seeking clean-label private-label alternatives.
For Investors and Strategic Acquirers: Cold-pressed juice operators with high-pressure processing capabilities and established DTC subscriber bases represent priority acquisition targets for portfolio beverage conglomerates seeking freshness positioning. Long-term viability hinges on decoupling from refrigerated supply chain intensity through ambient-stable formulation science. Monitor EU biodegradable packaging mandate enforcement timelines as inflection indicator for aseptic carton system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Packaging Line Retrofit | Reduces refrigerated logistics costs and extends shelf-life economics for ambient distribution. |
| Organic Certification Investment | Unlocks USDA three-year supply chain conversion for premium tier pricing power. |
| Functional Hydration Repositioning | Migrates lemonade from refreshment-only toward sports and wellness adjacent occasions. |
| Direct-to-Subscription Launch | Bypasses mass-channel slotting fees through California and New York metro delivery density. |
| EU Green Deal Packaging Transition | Captures preferential retail access through biodegradable fiber-based substrate adoption. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with beverage brand managers, category buyers at quick-service restaurant chains, lemon concentrate procurement leads, and aseptic packaging equipment specialists; and secondary validation against FDA juice content labeling standards, USDA organic certification databases, EU F-Gas Regulation compliance filings, and customs trade flow records for Argentine lemon concentrate exports. Bottom-up volume triangulation across formulation tiers, packaging formats, and channel economics converged with top-down market sizing anchored in food service fountain deployment data and retail scanner audit trends.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning product type chemistry, packaging physics, channel economics, and flavor variant maturity. CAGRs derived from regression analysis against historical lemon concentrate price cycles, carbonated refreshment demand migration patterns, and regulatory compliance timeline assumptions. Industry-specific inputs incorporated high-pressure processing technology adoption curves and EU extended producer responsibility framework implementation schedules.
Material uncertainties — weather-driven Argentine harvest variability, stevia formulation taste threshold rejection rates, and biodegradable packaging cost parity achievement — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding clean-label ingredient substitution velocity and aseptic carton system capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Ice Tea Market