
 Low- and No-Calorie Soda Market | 2026-2036
Low- and No-Calorie Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Low- and No-Calorie Soda Market Analysis
Multi-source sweetener procurement is hardening as manufacturers diversify beyond aspartame to stevia, monk fruit, and allulose supply chains. The Coca-Cola Company leverages its captive botanical extraction partnerships to secure stevia volumes. PepsiCo anchors North American fountain dispenser networks through exclusive quick-service restaurant agreements. Zevia differentiates via its allulose-based formulations targeting clean-label retail shelves.
Low- and no-calorie soda denotes carbonated beverages containing non-nutritive or reduced-calorie sweeteners, typically formulated with less than five calories per serving through aspartame, sucralose, steviol glycosides, or allulose replacement of sucrose or high-fructose corn syrup. These beverages serve commercial purposes spanning diabetic dietary management, weight control regimens, and sugar-reduction public health campaigns. Sparkling water commands the fastest expansion among product types as consumers migrate from sweetened colas to unsweetened carbonated alternatives. Health-conscious consumers represent the deepest margin pool within end-user segments due to their willingness to pay premium prices for clean-label certifications. Aluminum can packaging dominates volume throughput, though glass bottle formats sustain higher per-unit profitability in specialty retail channels.
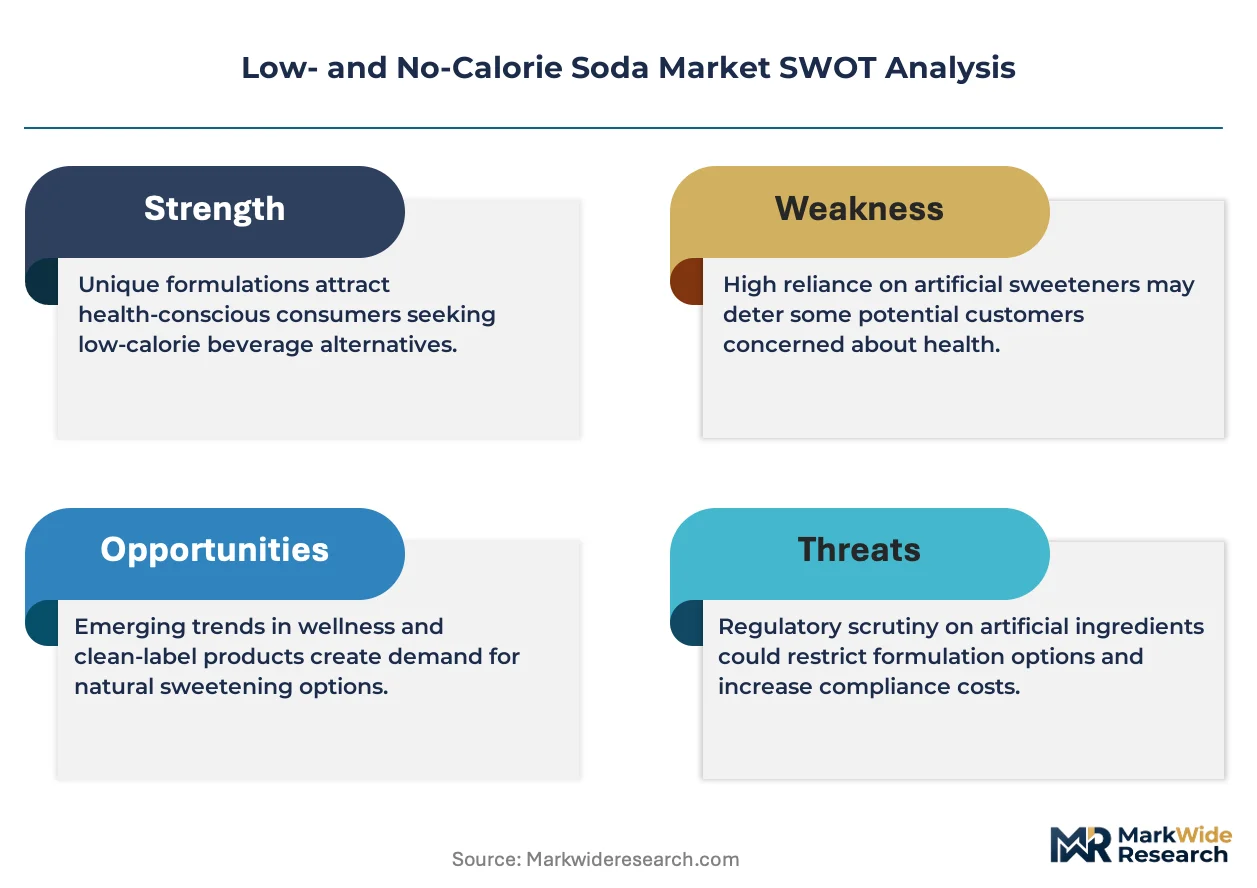
FDA nutrition labeling mandates and municipal sugar taxation regimes in Philadelphia, Seattle, and San Francisco directly shape product formulation decisions and geographic market access conditions for reduced-calorie variants. The USDA Dietary Guidelines and IRS eligibility of no-calorie beverages under certain health savings arrangements further influence institutional procurement patterns. Stakeholders must monitor evolving FDA guidance on novel sweetener safety assessments and state-level excise tax expansion proposals to anticipate reformulation requirements and channel profitability shifts.
Market Dynamics
Sweetener supply chain diversification is compressing formulation windows as manufacturers accelerate away from aspartame toward botanical and rare-sugar alternatives, forcing simultaneous qualification of multiple sensory profiles across identical product lines.
Growth Catalysts
- USDA Dietary Guidelines:Federal sugar-reduction recommendations institutionalize no-calorie beverage procurement in school nutrition programs and federal feeding initiatives.
- Steviol glycoside extraction advances:Biotech-enabled stevia leaf processing yields cleaner-tasting Reb M and Reb D variants that eliminate bitter aftertaste barriers.
- Quick-service restaurant fountain networks:Exclusive dispenser agreements with major QSR chains embed volume commitments that stabilize manufacturer capacity planning.
Market Restraints
- Allulose cost volatility:Corn-derived feedstock pricing and limited domestic enzymatic conversion capacity constrain margin expansion for rare-sugar formulations.
- Municipal sugar tax patchwork:Philadelphia, Seattle, and San Francisco impose divergent excise structures that fragment pricing architecture and complicate national distribution.
- Aspartame safety perception:Ongoing WHO reclassification discussions generate retailer hesitation and reformulation insurance costs regardless of FDA position.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging stevia and monk fruit approval frameworks open formulation flexibility for export-oriented production.
- Direct-to-subscription channels:E-commerce replenishment models bypass slotting-fee barriers and capture full retail margin on specialty SKUs.
- Functional ingredient convergence:Probiotic and adaptogenic additive integration positions no-calorie sodas within wellness beverage adjacencies.
Industry Challenges
- Flavor chemist talent scarcity:Cross-functional expertise bridging organic chemistry and sensory science commands premium compensation and extends R&D timelines.
- Legacy fountain infrastructure retrofit:Existing quick-service dispenser valve configurations require hardware modification for allulose-compatible syrup viscosity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low- and No-Calorie Soda Market |
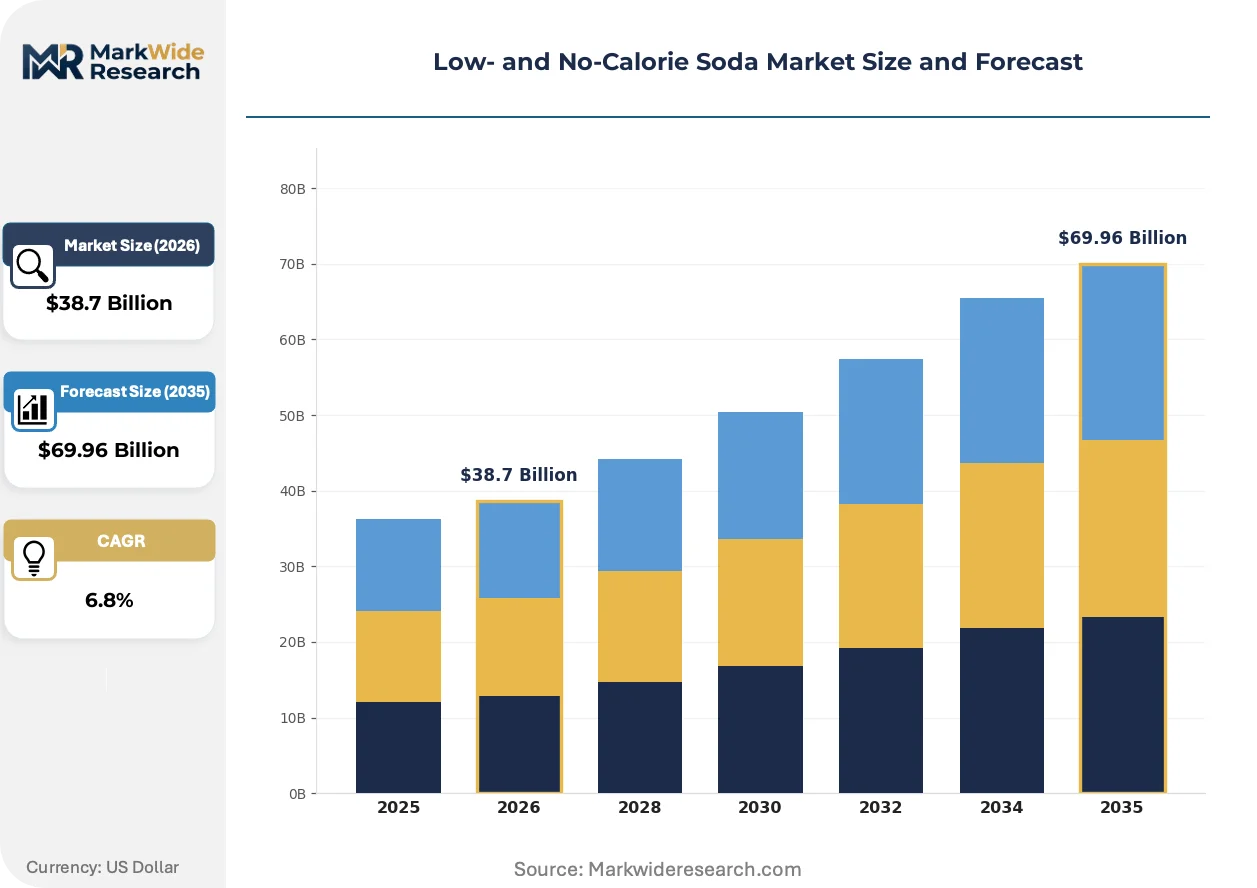
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diet Cola, Sparkling Water, Flavored Soda, Tonic Water End User: Health-Conscious Consumers, Diabetics, Athletes, Weight Watchers Packaging Type: Aluminum Can, Plastic Bottle, Glass Bottle, Fountain Dispenser Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Restaurants |
| Companies Covered | Nestlé, Polar Beverages, The Coca-Cola Company, Cott Corporation, Kirin Holdings Company, PepsiCo, Zevia, Genki Forest Beverage, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low- and No-Calorie Soda Market Emerging Trajectories
Formulation science is converging with clean-label certification regimes to redefine competitive differentiation beyond caloric reduction alone.
Allulose-stevia blends are unifying sweetness delivery curves that previously required three or more sweetener compounds. Mid-tier manufacturers adopting these dual-sweetener systems compress development cycles from eighteen to nine months. The structural consequence is collapsing premium pricing tiers that once separated patented formulations from commodity alternatives.
REACH-compliant botanical extraction standards are mandating solvent-residue thresholds for European-imported stevia that exceed FDA requirements. European bottlers now require supply-chain documentation through leaf origin that adds three to four weeks to procurement lead times. Stevia-sourced SKUs bound for EU markets carry reformulation costs that divert R&D resources from taste optimization.
Clean-label certification is displacing traditional low-calorie positioning as the primary purchase trigger among health-conscious millennials. Specialty retailers are de-listing products lacking Non-GMO Project or USDA Organic verification regardless of caloric content. California and Pacific Northwest retail channels demonstrate the most pronounced certification-driven assortment compression.
Low- and No-Calorie Soda Market Segmentation
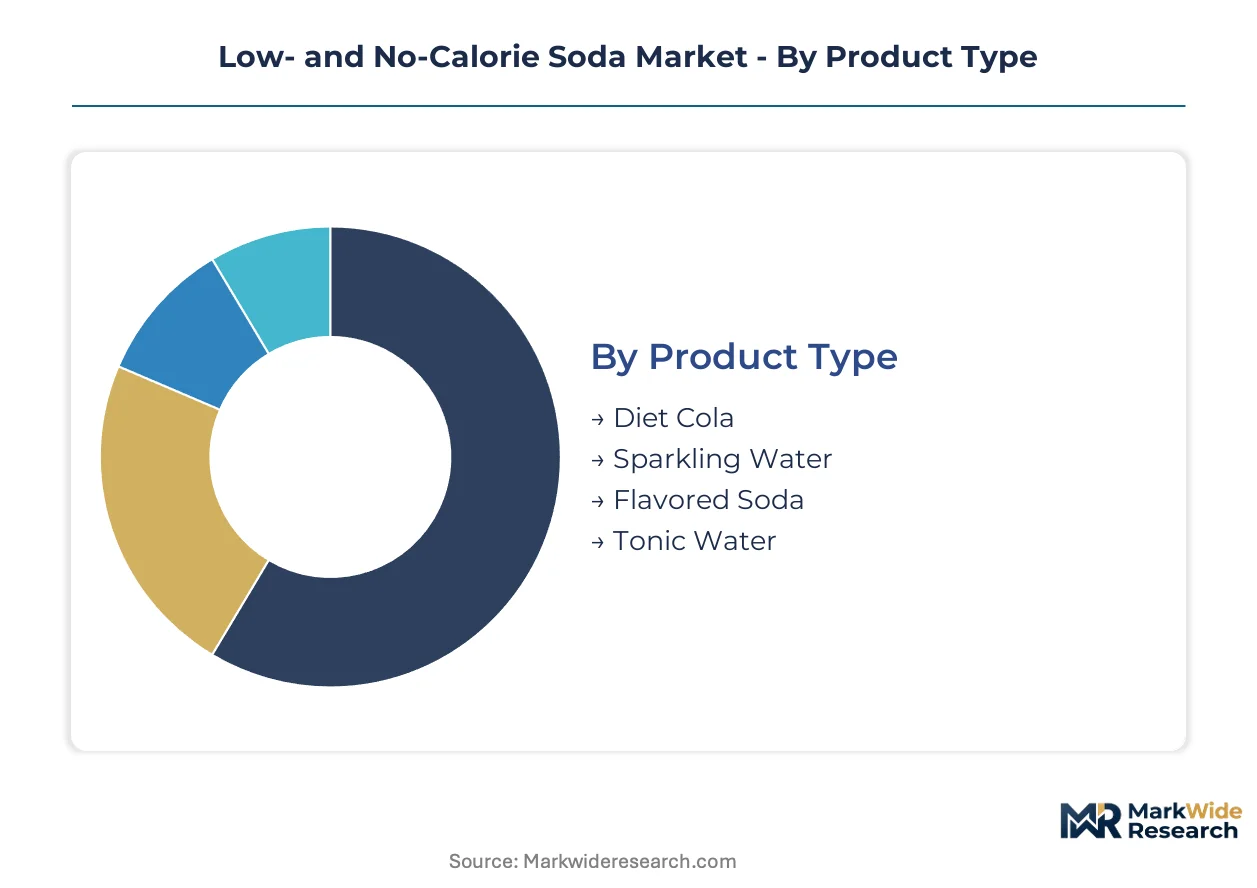
Sweetener chemistry and packaging physics create distinct margin profiles across the low- and no-calorie soda market. Manufacturers must align formulation investments with channel-specific velocity patterns rather than treating segments as interchangeable volume pools.
Product Type:
Sweetener technology and carbonation intensity differentiate the competitive terrain.
- Diet Cola:Aspartame- and sucralose-sweetened formulations dominate fountain dispenser throughput in quick-service restaurant chains. Legacy brand equity and established supply contracts anchor volume concentration in the United States, though aspartame safety debates are accelerating reformulation timelines.
- Sparkling Water:Unsweetened or minimally sweetened carbonated water variants are expanding most quickly as consumers migrate from sweetened colas. Clean-label positioning and premium pricing in specialty retail channels drive margin concentration among health-conscious millennials.
- Flavored Soda:Fruit-forward and botanical variants using stevia or allulose blends target retail shelf differentiation.
- Tonic Water:Quinine-bittered formulations serve mixer applications in on-premise channels.
Diet Cola leads on scale; Sparkling Water leads on momentum.
End User:
Health motivation intensity segments willingness-to-pay thresholds.
- Health-Conscious Consumers:Clean-label certification seekers pay premium prices for Non-GMO Project and USDA Organic verification. California and Pacific Northwest retail channels demonstrate the most pronounced certification-driven assortment compression.
- Diabetics:Glycemic management requirements create institutional procurement through healthcare reimbursement channels.
- Athletes:Electrolyte-enhanced variants align with fitness-oriented consumption occasions.
- Weight Watchers:Calorie-tracking behavior drives volume in portion-controlled packaging formats.
Health-Conscious Consumers anchor margin expansion; Diabetics anchor institutional volume.
Packaging Type:
Material science and cold-chain requirements shape distribution economics.
- Aluminum Can:Lightweight, infinitely recyclable format dominates volume throughput in supermarkets and convenience stores. Ball Corporation and Crown Holdings supply concentration creates procurement leverage for national brands.
- Plastic Bottle:PET formats balance portability with production flexibility.
- Glass Bottle:Premium positioning in specialty retail sustains higher per-unit profitability despite logistics constraints.
- Fountain Dispenser:Quick-service restaurant installations drive concentrate economics through exclusive syrup supply agreements.
Aluminum Can leads on throughput; Glass Bottle leads on unit margin.
Distribution Channel:
Slotting fee structures and replenishment velocity determine SKU viability.
- Supermarkets:Category captains command end-cap placement and promotional calendars. Clean-label certification increasingly gates assortment approval in California-based retail chains.
- Convenience Stores:Immediate consumption occasions favor single-serve aluminum can formats.
- Online Retailers:Subscription replenishment models bypass slotting-fee barriers and capture full retail margin on specialty SKUs.
- Restaurants:Fountain dispenser agreements lock in syrup volume commitments through multi-year contracts.
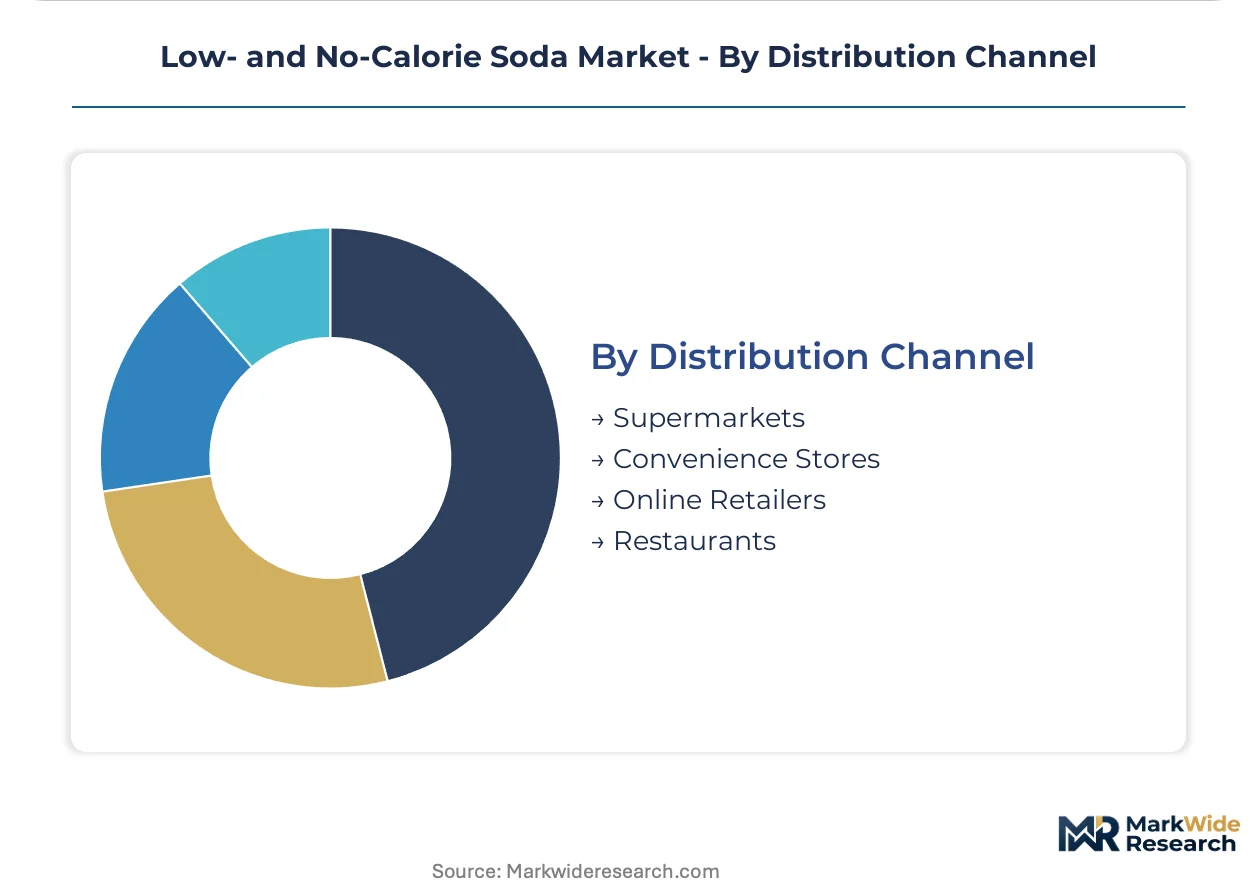
Supermarkets lead on absolute volume; Online Retailers lead on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting low- and no-calorie soda production toward jurisdictions with favorable sweetener approval frameworks and lower excise-tax burdens, compressing cost-of-compliance gaps between established and emerging manufacturing bases.
United States
Quick-service restaurant fountain networks concentrate demand in the Southeast and Southwest, where dispenser installations drive syrup volume commitments. FDA nutrition labeling mandates and municipal sugar taxes in Philadelphia, Seattle, and San Francisco fragment pricing architecture across state lines. Atlanta and Dallas anchor concentrate production and regional distribution hubs serving the domestic market.
Germany
REACH-compliant botanical extraction standards mandate solvent-residue thresholds for stevia imports that exceed FDA requirements, extending procurement lead times by three to four weeks. EFSA novel food approvals govern allulose market entry, creating formulation lag versus North American counterparts. The Rhine-Ruhr industrial corridor hosts carbonation equipment manufacturing and stevia processing facilities serving EU distribution.
Japan
PMDA food additive assessments and METI functional food labeling frameworks shape steviol glycoside adoption curves in premium retail channels. Aging demographics and diabetic population growth institutionalize no-calorie beverage procurement in healthcare and institutional feeding programs. The Kanto region around Tokyo concentrates R&D activity for clean-label sweetener applications.
Brazil
ANVISA stevia and monk fruit approval pathways are accelerating, opening formulation flexibility for export-oriented production targeting North American clean-label demand. Sugar-sector political economy creates tension between traditional sucrose interests and reduced-calorie alternatives. São Paulo state anchors both conventional soft drink manufacturing and emerging botanical extraction partnerships.
India
FSSAI clean-label frameworks and emerging stevia approval pathways are attracting contract manufacturing investment from multinational brands seeking cost-advantaged production. Domestic diabetic population growth and urban health-consciousness expand addressable market beyond traditional carbonated beverages. Maharashtra and Gujarat host concentrated beverage bottling capacity and stevia cultivation trials.
Low- and No-Calorie Soda Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and functional adjacencies through botanical sweetener differentiation. The market structure consolidates around multinational beverage conglomerates with captive fountain networks and retail shelf presence, while specialty players fragment across premium-positioned subsegments. Two dominant archetypes prevail: scale-driven syrup suppliers with QSR exclusivity agreements, and certification-focused challengers leveraging direct-to-consumer channels. Competitive moves concentrate on multi-sweetener formulation portfolios and geographic expansion through regulatory-first market entry.
Within the scale-driven tier, The Coca-Cola Company and PepsiCo anchor North American volume through exclusive quick-service restaurant dispenser agreements and multi-brand portfolio breadth. Zevia exemplifies the clean-label challenger archetype, occupying a position in allulose-based specialty retail with subscription replenishment models that bypass traditional slotting-fee barriers. Keurig Dr Pepper sits within the diversified beverage platform category, representing hybrid positioning across conventional and reduced-calorie segments.
| Leading Market Players |
|---|
| Nestlé |
| Polar Beverages |
| The Coca-Cola Company |
| Cott Corporation |
| Kirin Holdings Company |
| PepsiCo |
| Zevia |
| Genki Forest Beverage |
| Keurig Dr Pepper |
| Others |
Supply Flow & Price Mechanics
REACH-compliant botanical extraction standards gate qualified stevia supply for European-bound production while simultaneously enabling premium-tier pricing access for clean-label certified SKUs in California and Pacific Northwest retail channels. Manufacturers lacking solvent-residue documentation face automatic delisting from specialty retail assortments regardless of formulation quality.
Pricing Analysis
Input-cost pass-through from corn-derived allulose feedstock and enzymatic conversion capacity shortages compress margins for rare-sugar formulations. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified glass-bottle SKUs from conventional aluminum-can formats and fountain dispenser concentrate. Pricing pressure stems from municipal sugar tax fragmentation across Philadelphia, Seattle, and San Francisco, which forces state-specific pricing architectures. Health-conscious consumers demonstrate lowest price sensitivity; quick-service restaurant procurement committees exhibit highest sensitivity due to volume contract renegotiation cycles.
Supply Chain Analysis
Freight cost volatility from stevia leaf shipments originating in Paraguay, Brazil, and China extends procurement lead times for European bottlers requiring REACH-compliant documentation. Raw material dependencies center on steviol glycoside extracts, allulose enzymatic conversion outputs, and aluminum can sheet from Ball Corporation and Crown Holdings. Single-source vulnerability concentrates in domestic allulose enzymatic conversion capacity. Distribution runs through quick-service restaurant fountain networks for concentrate economics, with direct-to-subscription channels capturing full retail margin for specialty SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between ANVISA-approved Brazilian stevia extraction and FDA-regulated North American formulation, exploiting a regulatory cost differential that opens export-oriented production pathways.
For Market Incumbents: Cement exclusive quick-service restaurant dispenser agreements through multi-year syrup volume commitments that lock out challenger brands. Deepen captive botanical extraction partnerships to secure stevia volumes against supply competition. The Coca-Cola Company and PepsiCo anchor North American volume through these mechanisms. Threats from allulose-based clean-label entrants like Zevia demand certification investment in Non-GMO Project verification to defend shelf position.
For New Entrants and Emerging Players: A mid-tier price-point gap between premium USDA Organic glass-bottle SKUs and economy fountain dispenser concentrates creates white-space opportunity. Target direct-to-subscription channels for specialty allulose formulations bypassing supermarket slotting-fee barriers. India FSSAI clean-label pathways offer regulatory-first market entry for export-oriented production. Functional ingredient convergence with probiotics or adaptogens provides differentiation angle.
For Investors and Strategic Acquirers: Roll-up economics work for clean-label certification-focused challengers because specialty retail assortment compression concentrates buyer power around verified SKUs. Long-term viability hinges on five-to-ten year stevia and monk fruit approval framework maturation in India and Brazil. Acquisition target archetype: allulose-formulation specialists with established direct-to-consumer replenishment infrastructure. Signal to watch: FDA guidance on novel sweetener safety assessments triggering reformulation insurance cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | Non-GMO Project verification gates California and Pacific Northwest retail assortment approval. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models bypass supermarket slotting-fee barriers entirely. |
| Botanical Extraction Partnership | Captive stevia supply secures volume against Reb M and Reb D demand surges. |
| Quick-Service Restaurant Exclusivity | Fountain dispenser agreements embed multi-year syrup volume commitments stabilizing capacity. |
| Functional Ingredient Integration | Probiotic and adaptogenic additives reposition no-calorie sodas within wellness adjacencies. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged beverage formulation scientists, quick-service restaurant procurement directors, specialty retail category buyers, and stevia extraction facility operators. Secondary validation drew from FDA nutrition labeling guidance documents, USDA Dietary Guidelines, municipal sugar tax ordinance filings, and FSSAI clean-label framework publications. Bottom-up volume modeling triangulated against top-down market sizing across sweetener chemistry and packaging format segments.
Segment-weighting approach distributed value and volume across diet cola, sparkling water, flavored soda, and tonic water product types; health-conscious consumers, diabetics, athletes, and weight watchers end-user categories; aluminum can, plastic bottle, glass bottle, and fountain dispenser packaging formats; and supermarket, convenience store, online retailer, and restaurant distribution channels. CAGRs were derived from historical trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated steviol glycoside extraction yield improvements and allulose enzymatic conversion capacity expansion curves.
The model assumes a particular technology adoption path; alternative pathways for allulose-stevia blend formulation would alter the outlook if biotech-enabled Reb D production costs collapse faster than projected. Forecasts reflect assumptions about FDA novel sweetener safety assessment timelines and state-level sugar tax expansion trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market