
 Europe Sports Drink Market | 2026-2036
Europe Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports Drink Market Foresight
Sporting goods retail shelf space is narrowing across European hypermarkets as discounters and direct-to-consumer platforms capture larger hydration beverage volumes. PepsiCo leverages its pan-European bottling infrastructure to sustain refrigerated distribution in Southern Europe. Britvic plc anchors the UK convenience channel through Lucozade's longstanding brand equity in team sports. The Coca-Cola Company competes via Powerade's sponsorship density at UEFA competitions, while Red Bull differentiates through extreme sports event activation rather than traditional athletic positioning.
Europe sports drinks comprise electrolyte-fortified, carbohydrate-modulated beverages formulated to osmolality specifications matching human plasma at approximately 280-310 mOsm/kg, with primary commercial purpose of rapid fluid and energy substrate replenishment during or after physical exertion. Isotonic formulations dominate volume sales due to their absorption rate parity with blood serum, though recovery-type products with added protein isolates capture disproportionate margin pools in premium gym channels. Flavor segmentation shows berry variants leading in Nordic markets while citrus profiles anchor Mediterranean consumption patterns, with packaging type shifts toward flexible pouches gaining traction among trail runners and obstacle-course participants seeking reduced weight burden.
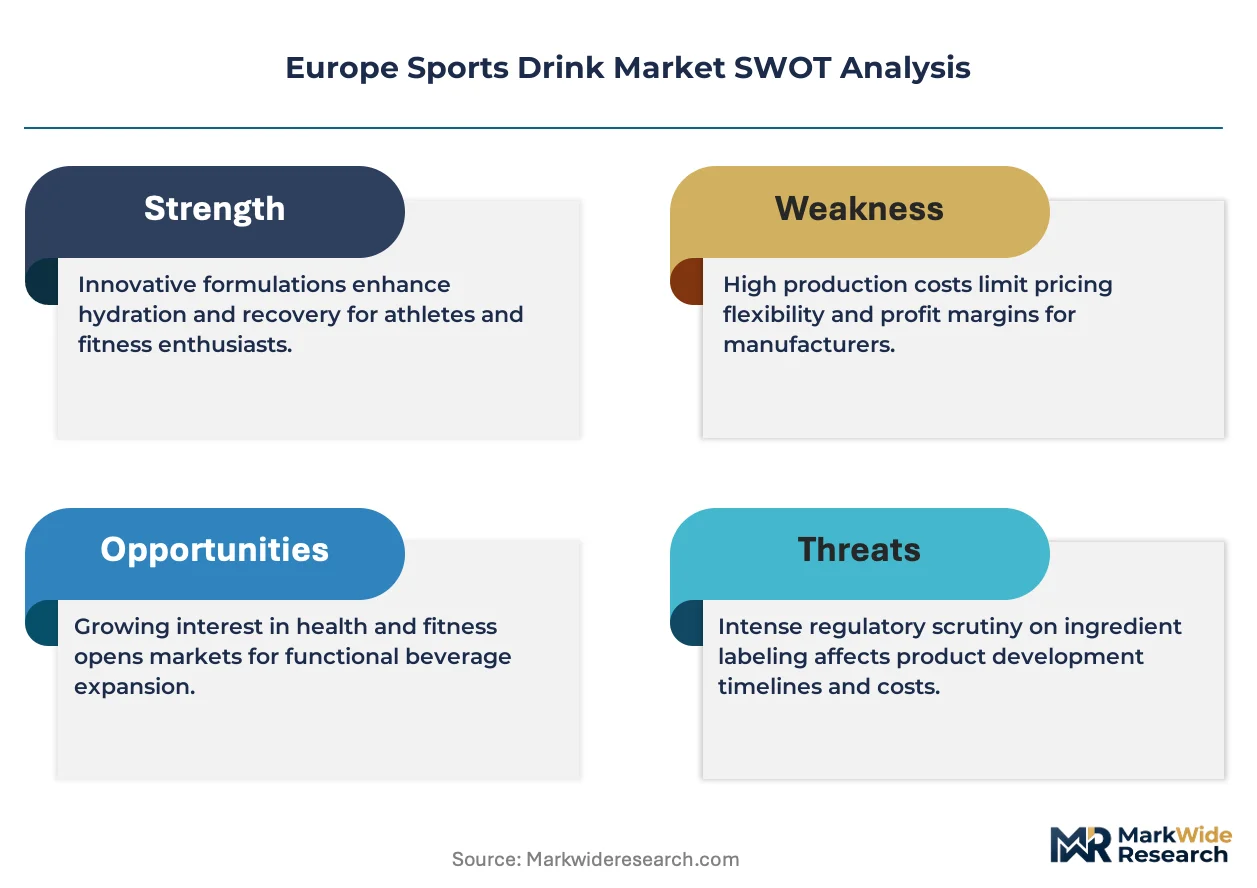
EFSA nutrition and health claims regulation constrains marketing language around performance benefits, while the EU Packaging and Packaging Waste Directive mandates recycled content minimums that reshape bottle procurement decisions. The EU Green Deal's carbon border adjustments indirectly elevate transport costs for imported concentrate formulations. Stakeholders must monitor ECHA evaluations of artificial sweetener safety profiles and the F-Gas Regulation's impact on cold-chain refrigeration costs as determinants of future product accessibility and pricing architecture.
Market Dynamics
The EU Single-Use Plastics Directive is compressing traditional PET bottle economics while simultaneously accelerating capital flows into flexible packaging formats and closed-loop aluminum systems across European beverage supply chains.
Growth Catalysts
- EFSA nutrition claims framework:Recent clarifications on carbohydrate-electrolyte solutions enable substantiated performance messaging in Germany's fitness studio networks and UK amateur rugby leagues.
- Obstacle-course racing formats:Spartan Race and Tough Mudder participation across France, Spain, and Italy creates concentrated demand for lightweight, puncture-resistant pouch packaging.
- Refrigerated distribution infrastructure:PepsiCo's pan-European bottling network sustains cold-chain penetration in Southern European markets where ambient distribution previously dominated.
Market Restraints
- Concentrate import cost volatility:The EU Green Deal's carbon border adjustment mechanism elevates transport costs for imported flavor and electrolyte formulations from non-EU suppliers.
- F-Gas Regulation compliance:Cold-chain refrigeration asset upgrades impose capital intensity on small-format convenience retailers across Poland and Romania.
- Artificial sweetener safety reviews:ECHA evaluations of sucralose and acesulfame potassium profiles create formulation uncertainty and label revision cycles.
Strategic Opportunities
- Underpenetrated Nordic trail-running segments:Sweden and Norway's ultramarathon communities show minimal brand loyalty and demand berry-variant flavor profiles absent from current portfolios.
- Paper-based carton formats:The EU Packaging and Packaging Waste Directive's recycled content minimums position Tetra Pak-style aseptic cartons as compliant alternatives to plastic.
- Direct-to-consumer subscription models:UK cycling teams and German football academies seek bulk, personalized electrolyte formulations bypassing traditional retail markup structures.
Industry Challenges
- Formulation chemist talent scarcity:Osmolality calibration expertise matching 280-310 mOsm/kg specifications concentrates in Netherlands and Switzerland, creating recruitment bottlenecks for new market entrants.
- Legacy refrigeration asset stranding:Convenience channel retailers face accelerated obsolescence of HFC-based cooling systems ahead of F-Gas phase-down timelines.
- Multi-jurisdiction label harmonization:Divergent national implementations of EFSA health claims guidance between France, Germany, and the UK complicate pan-European SKU management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports Drink Market |
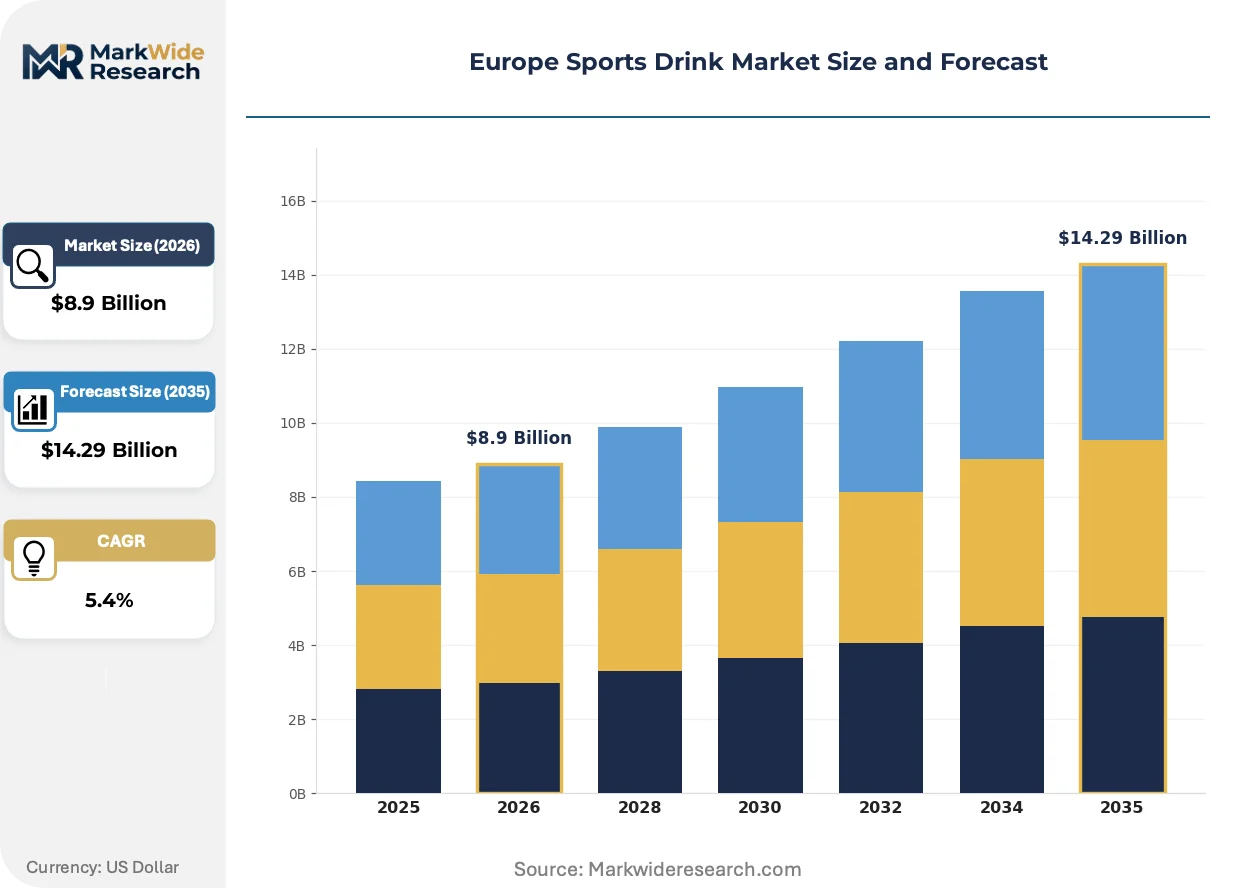
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Isotonic, Hypertonic, Hypotonic, Recovery Flavor: Citrus, Berry, Tropical, Green Apple Packaging Type: Bottle, Can, Pouch, Cube End User: Athletes, Fitness Enthusiasts, Casual Consumers, Team Sports |
| Companies Covered | Lucozade, Suntory Holdings Limited, Red Bull, Otsuka Holdings Co Ltd, Britvic plc, PepsiCo, Monster Beverage Corporation, Carabao Group Public Company Limited, The Coca-Cola Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports Drink Market Shifts & Advancements
Packaging material science and digital supply chain instrumentation are converging to reshape how European sports drink manufacturers balance regulatory compliance with athlete-centric functionality.
Smart bottle technology embedding NFC chips and hydration-tracking sensors is digitizing consumption pattern data capture. German fitness chains and UK rugby academies are piloting these connected formats at scale. Real-time electrolyte intake monitoring is digitizing personalization capabilities that previously required manual logging.
The EU F-Gas Regulation's phasedown schedule is forcing refrigeration infrastructure decisions across Southern European convenience networks. Retailers in Spain and Italy face compressed timelines for HFC equipment replacement. Isotonic beverage categories dependent on cold-chain visibility are absorbing disproportionate compliance costs relative to ambient-stable alternatives.
Amateur team sports leagues are consolidating procurement through centralized hydration officers rather than individual athlete purchasing. UK rugby leagues and German football clubs now negotiate annual supply contracts directly with manufacturers. This concentration is most visible in England's county-level rugby structures where Lucozade's historical brand equity faces direct-to-club competitor pitches.
Europe Sports Drink Market Segmentation
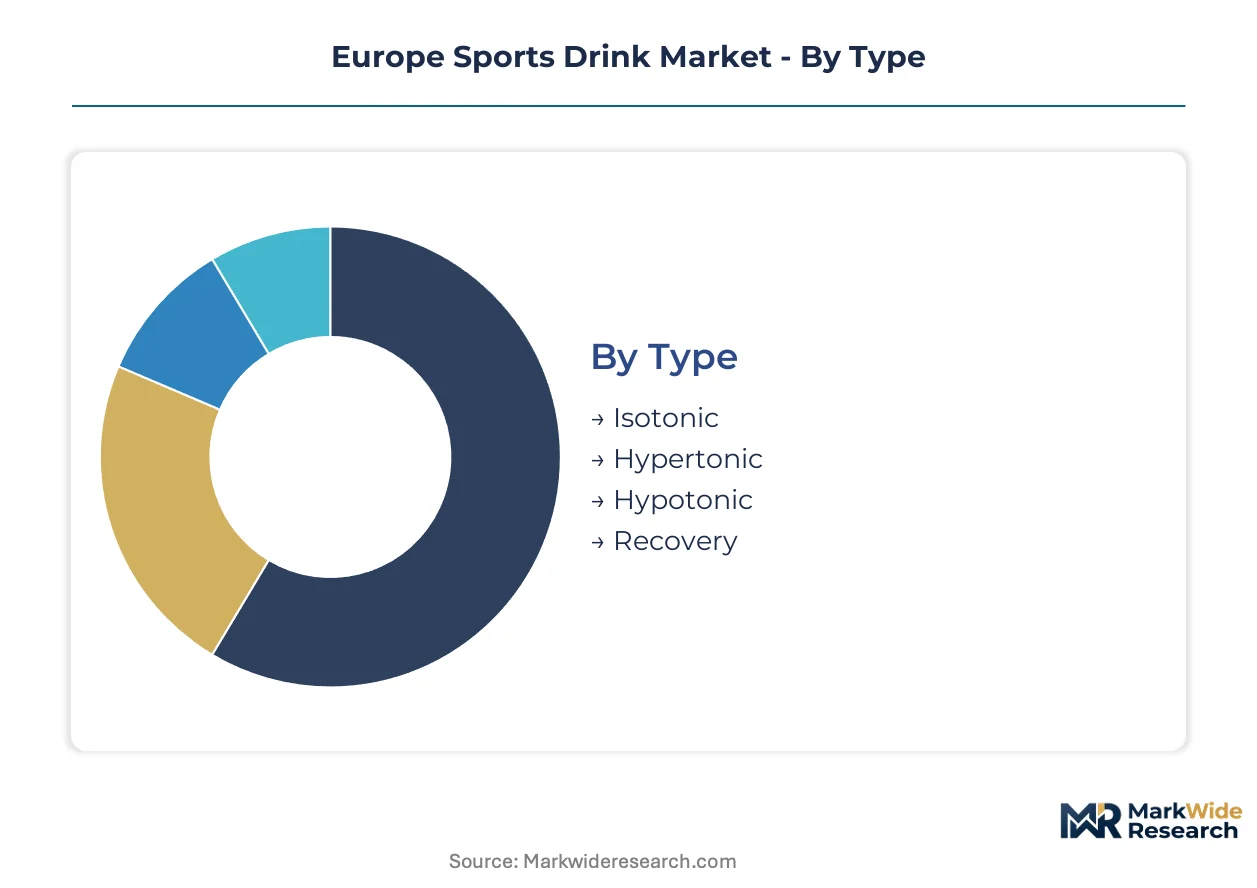
Segmentation in the Europe Sports Drink Market reveals how formulation science, consumption context, and packaging engineering intersect to create distinct value pools. Manufacturers calibrate osmolality, flavor chemistry, and format portability against specific exertion profiles and retail channel requirements.
Type:
Mature isotonic formulations anchor volume sales while recovery and hypotonic variants emerge as specialized growth vectors across European performance channels.
- Isotonic:Formulated to 280-310 mOsm/kg osmolality matching human plasma for rapid gastric emptying and intestinal absorption. Germany's fitness studio networks and UK amateur rugby leagues concentrate procurement here due to EFSA-permitted carbohydrate-electrolyte performance claims.
- Recovery:Protein isolate fortification targets post-exertion muscle glycogen resynthesis and tissue repair. Premium gym channels in France and the Netherlands absorb disproportionate margin pools as personalized nutrition protocols displace generic hydration.
- Hypertonic:Elevated carbohydrate density exceeding blood serum concentration suits endurance athletes requiring energy density over fluid volume.
- Hypotonic:Reduced solute concentration accelerates absorption for low-intensity or heat-stress conditions where electrolyte replacement outweighs caloric needs.
Isotonic retains volume leadership; Recovery holds the steepest expansion curve.
Flavor:
Geographic taste architecture splits the European market between Nordic berry preferences and Mediterranean citrus anchoring.
- Berry:Sweden and Norway's ultramarathon communities demonstrate minimal brand loyalty and unmet demand for specialized berry-variant portfolios absent from current manufacturer offerings.
- Citrus:Lemon-lime and orange profiles dominate ambient-stable distribution across Spain and Italy where refrigerated infrastructure remains capital-constrained.
- Tropical:Mango-passionfruit blends target younger fitness demographics in UK boutique studio chains seeking sensory differentiation from legacy formulations.
- Green Apple:Tart profiles capture trail-running and obstacle-course segments in France where reduced sweetness perception signals functional purity.
Citrus commands the broadest geographic penetration; Berry climbs the fastest in underpenetrated Nordic segments.
Packaging Type:
Cost tier stratification separates premium convenience formats from economy bulk channels as regulatory pressure reshapes material procurement.
- Pouch:Flexible, puncture-resistant construction reduces weight burden for Spartan Race and Tough Mudder participants across France, Spain, and Italy. EU Single-Use Plastics Directive compliance advantages accelerate capital flows into this format.
- Bottle:PET and recycled-content variants retain dominance in hypermarket and convenience retail despite compressing economics under packaging waste mandates.
- Can:Aluminum closed-loop systems gain traction in German football club procurement and UK rugby league centralized purchasing for durability and recyclability.
- Cube:Tetra Pak-style aseptic cartons satisfy EU Packaging and Packaging Waste Directive recycled content minimums for ambient distribution in Southern European markets.
Bottle maintains installed base dominance; Pouch gains share fastest through obstacle-course and trail-running adoption.
End User:
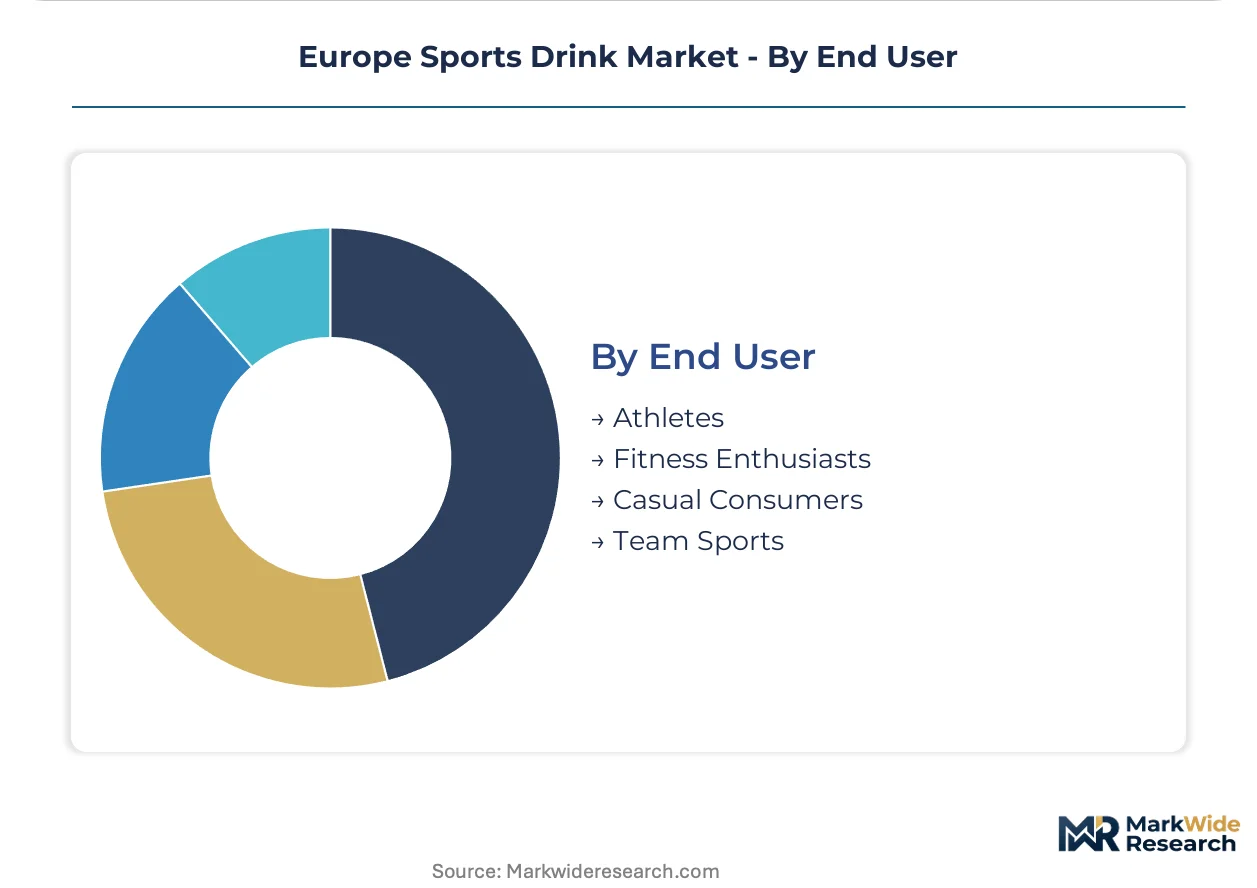
Customer type concentration is shifting from individual athlete purchasing toward institutional procurement consolidation.
- Team Sports:England's county-level rugby structures and German football academies now negotiate annual supply contracts directly with manufacturers, bypassing retail markup. Hydration officers centralize procurement decisions previously fragmented across individual players.
- Fitness Enthusiasts:German fitness chains pilot smart bottle technology with embedded NFC chips and real-time electrolyte monitoring, digitizing personalization capabilities.
- Athletes:Professional cycling teams and football clubs across Germany, France, and the United Kingdom expand hydration procurement budgets with formulation customization requirements.
- Casual Consumers:Discounter channels and direct-to-consumer platforms capture volumes previously routed through sporting goods retail shelf space.
Team Sports captures the steepest procurement consolidation trajectory; Fitness Enthusiasts drive premium format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's fitness studio networks while Southern European markets absorb elevated cold-chain compliance costs. The UK leverages Lucozade's historical brand equity for team sports procurement consolidation. France and Spain navigate obstacle-course racing demand alongside EU Single-Use Plastics Directive pressures.
Germany
Fitness studio networks and football academies drive isotonic formulation demand with EFSA-permitted carbohydrate-electrolyte performance claims. The EU Green Deal's carbon border adjustment mechanism elevates transport costs for imported electrolyte concentrates. Bavaria's industrial clusters host osmolality calibration expertise concentrated in Netherlands and Switzerland recruitment pipelines.
United Kingdom
Amateur rugby leagues and county-level rugby structures consolidate procurement through hydration officers bypassing retail markup. EFSA nutrition claims framework clarifications enable substantiated performance messaging in team sports channels. England's Midlands and North regions anchor Lucozade's longstanding convenience channel presence against direct-to-club competitor pitches.
France
Spartan Race and Tough Mudder participation creates concentrated demand for lightweight pouch packaging across obstacle-course racing formats. The EU Packaging and Packaging Waste Directive mandates recycled content minimums reshaping bottle procurement decisions. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur host trail-running segments driving green apple flavor preference for reduced sweetness perception.
Spain
Ambient-stable citrus profiles dominate distribution where refrigerated infrastructure remains capital-constrained in convenience networks. The F-Gas Regulation's phasedown schedule forces accelerated HFC equipment replacement timelines. Catalonia and Madrid retail clusters absorb disproportionate cold-chain compliance costs relative to Northern European markets.
Sweden
Ultramarathon communities demonstrate minimal brand loyalty with unmet demand for specialized berry-variant portfolios. ECHA evaluations of artificial sweetener safety profiles create formulation uncertainty requiring label revision cycles. Stockholm and Gothenburg fitness demographics pilot smart bottle technology with embedded NFC chips for real-time electrolyte monitoring.
Europe Sports Drink Market Competitive Landscape
Pan-European beverage conglomerates and specialized functional drink specialists split the market through divergent channel strategies. Consolidation pressure intensifies as refrigeration asset upgrades and packaging compliance costs disadvantage sub-scale entrants. Three archetypes dominate: legacy soft drink multinationals leveraging bottling infrastructure, energy drink specialists activating extreme sports sponsorships, and regional hydration specialists serving institutional procurement. Competitive moves center on direct-to-club supply contract capture and flexible packaging format transitions.
Within the multinational beverage tier, PepsiCo and The Coca-Cola Company exemplify scale-driven distribution architectures. Britvic plc occupies a position representing UK-centric brand equity consolidation. Red Bull sits within the energy drink specialist archetype differentiated through extreme sports event activation rather than traditional athletic positioning. These three anchors demonstrate how geographic origin and corporate structure map to divergent competitive postures across European hydration channels.
| Leading Market Players |
|---|
| Lucozade |
| Suntory Holdings Limited |
| Red Bull |
| Otsuka Holdings Co Ltd |
| Britvic plc |
| PepsiCo |
| Monster Beverage Corporation |
| Carabao Group Public Company Limited |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Bavaria's industrial clusters concentrate electrolyte concentrate formulation capacity, connecting upstream chemical processing to downstream pricing power across German fitness studio networks and UK amateur rugby leagues. The EU Green Deal's carbon border adjustment mechanism elevates transport costs for imported flavor formulations, compressing margins for non-integrated distributors while rewarding regional production proximity.
Pricing Analysis
The customization-premium spread separates configured-to-order electrolyte formulations for professional cycling teams from standard isotonic SKUs in convenience retail. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, EFSA-permitted performance claims, and packaging format durability. Cost compression in standard isotonic tiers is intensifying because discounter channels and direct-to-consumer platforms displace traditional sporting goods retail. Amateur team sports leagues demonstrate highest price sensitivity through centralized hydration officer procurement, while professional football clubs absorb premium pricing for personalized osmolality calibration.
Supply Chain Analysis
Tariff exposure between Netherlands-based flavor houses and German bottling facilities dominates supply chain risk assessment for electrolyte concentrate sourcing. Manufacturing concentration in Germany, Switzerland, and the Netherlands feeds European demand, with osmolality calibration expertise anchoring in Swiss and Dutch technical centers. Raw material dependencies on citric acid, maltodextrin, and sodium chloride draw from established chemical supply bases. Single-source vulnerability concentrates in specialized pouch film formulations for obstacle-course racing formats. Distribution runs through PepsiCo's pan-European refrigerated bottling network and Britvic's UK convenience channel infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement consolidation as UK rugby leagues and German football academies centralize hydration officer roles, fragmenting individual athlete purchasing concentration.
For Market Incumbents: Insulate formulation expertise advantages by capturing osmolality calibration talent in Netherlands and Switzerland recruitment pipelines before competitor expansion. Deepen backward integration into electrolyte concentrate production to offset EU Green Deal carbon border adjustment cost elevation. Channel control through direct-to-club supply contracts defends against emerging regional hydration specialists pitching England's county-level rugby structures. For New Entrants and Emerging Players: Pursue underpenetrated Nordic ultramarathon segments in Sweden and Norway where berry-variant portfolios remain absent from incumbent offerings. Target obstacle-course racing formats across France, Spain, and Italy with lightweight pouch packaging formats gaining regulatory advantage under EU Single-Use Plastics Directive. Direct-to-consumer subscription models for German cycling teams and UK football academies bypass retail markup structures. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because refrigeration asset upgrades and packaging compliance costs disadvantage sub-scale entrants across Southern European convenience networks. Acquisition target archetype: regional hydration specialists with established direct-to-club supply contracts and flexible packaging format capabilities. Signal to watch: ECHA artificial sweetener safety review outcomes driving formulation revision cycles and label compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Flexible Packaging Transition | EU Single-Use Plastics Directive compliance accelerates pouch and paper-based carton adoption for obstacle-course racing segments. |
| Direct-to-Club Supply Contracts | Centralized hydration officer procurement in UK rugby leagues and German football academies bypasses traditional retail markup structures. |
| Smart Bottle Technology Integration | NFC-embedded hydration tracking digitizes personalization for German fitness chains and UK rugby academies piloting connected formats. |
| Refrigerated Distribution Expansion | PepsiCo's pan-European bottling network sustains cold-chain penetration in Southern European markets where ambient distribution previously dominated. |
| Regional Formulation Customization | Berry-variant development for Nordic ultramarathon communities addresses unmet demand absent from current manufacturer portfolios. |
Research Methodology
Operator-level perspectives from beverage formulation chemists, fitness studio procurement managers, rugby club hydration officers, and convenience channel category buyers anchored the qualitative base. Primary interviews combined with secondary validation from EFSA guidance documents, EU Packaging and Packaging Waste Directive regulatory filings, and Nielsen retail audit data. Customs records tracking electrolyte concentrate imports and SEC filings from listed beverage conglomerates provided demand-side calibration. Bottom-up volume builds across formulation types, flavor profiles, and packaging formats triangulated against top-down market sizing from trade association disclosures.
Scenario-bracketing framed demand projections across regulatory compliance timelines and cold-chain infrastructure investment cycles. Segmentation dimensions modeled include isotonic/recovery/hypotonic formulation types, berry/citrus/tropical/green apple flavor profiles, pouch/bottle/can/cube packaging formats, and team sports/fitness enthusiasts/athletes/casual consumers end-user categories. CAGRs derived from elasticity-adjusted volume trajectories incorporating EFSA nutrition claims framework adoption rates and EU Single-Use Plastics Directive implementation phases. Forecast inputs incorporated F-Gas Regulation refrigeration asset replacement costs and carbon border adjustment mechanism transport cost impacts.
Sensitivities concentrate around ECHA artificial sweetener safety review outcomes, F-Gas Regulation phasedown acceleration, and EU Green Deal carbon border adjustment scope expansion. Forecasts reflect assumptions on regulatory implementation timelines, institutional procurement consolidation velocity, and packaging format transition rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market