
 Global Dental Adhesives and Sealants Market | 2026-2036
Global Dental Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Adhesives and Sealants Market Intelligence
The rise of equipment leasing models for dental clinics is reshaping competitive positioning among material suppliers. Kuraray Noritake Dental leverages its deep R&D in polymer chemistry to offer specialized bonding agents. 3M competes with a broad portfolio spanning multiple dental product categories. Ivoclar Vivadent differentiates through its focus on integrated systems for restorative and prosthetic dentistry.
Dental adhesives and sealants are resin-based materials formulated to create a durable bond between a restorative material and tooth structures like enamel and dentin. Their function relies on micromechanical interlocking and chemical adhesion, often involving methacrylate monomers within a solvent carrier. Light-cure product types command the largest share due to their on-demand polymerization and clinical control. Restorative dentistry applications represent the primary end-use, while demand for preventive care sealants is also expanding.
Market access requires compliance with stringent medical device regulations, including those from the US FDA and Japan's PMDA. In Europe, CE marking under the Medical Device Regulation (MDR) mandates rigorous clinical evidence and post-market surveillance for biocompatibility. Suppliers must continually adapt formulations to meet evolving international standards for materials like bisphenol A (BPA) derivatives.
Market Dynamics
The evolution toward minimally invasive dentistry is the central force defining the market. This clinical philosophy prioritizes tooth structure preservation, directly increasing the reliance on high-performance adhesives and sealants for both restorative and preventive procedures, steering material development toward stronger, more durable bonding agents.
Growth Catalysts
- Universal Adhesives:The development of single-bottle, universal adhesive systems that combine etch, prime, and bond steps is simplifying clinical workflows. This streamlines procedures in restorative dentistry, reducing technique sensitivity and application time for general practitioners.
- Preventive Pediatric Care:A rising focus on preventive oral health in pediatric dentistry is expanding the use of pit and fissure sealants. School-based dental sealant programs, particularly in the United States, create consistent demand for these materials.
- Aging Demographics:Advanced economies like Germany and Japan face a growing elderly population with a higher prevalence of root caries and need for complex restorations. This demographic trend sustains demand for reliable dentin and enamel bonding agents.
Market Restraints
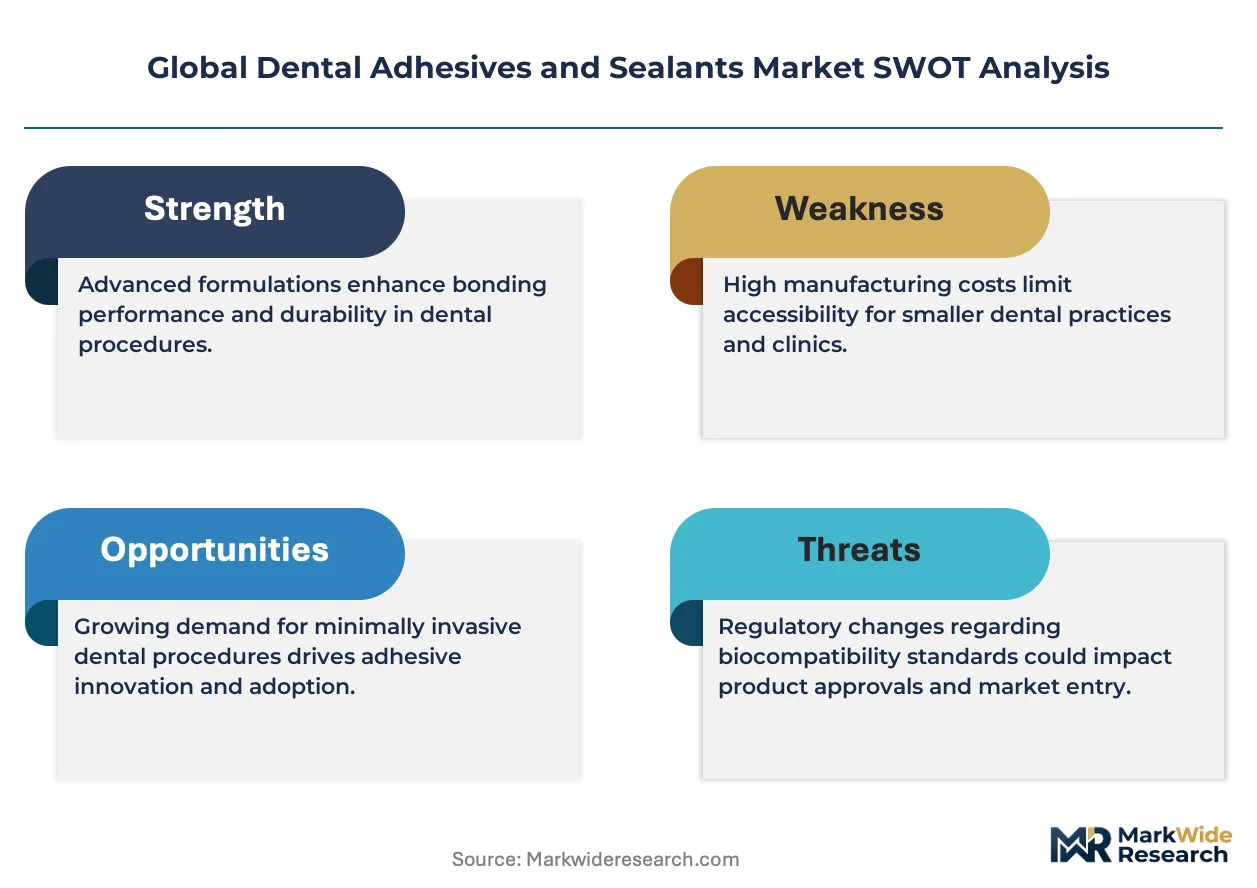
- Technique Sensitivity:The clinical success of many dental adhesives is highly dependent on meticulous application technique and moisture control. This sensitivity can lead to premature bond failure, limiting consistent outcomes for some practitioners and slowing adoption of certain products.
- Regulatory Hurdles:Gaining market access requires adherence to strict regulatory frameworks, such as Europe's Medical Device Regulation (MDR). The mandate for extensive clinical data and post-market surveillance for biocompatibility increases development costs and lengthens time-to-market.
- Input Cost Volatility:The market is exposed to price fluctuations for key petrochemical-derived raw materials, including methacrylate monomers and photoinitiators. These shifts can compress manufacturer margins or lead to price increases for end-users.
Strategic Opportunities
- Bioactive Formulations:There is a significant opportunity in developing "smart" adhesives with bioactive properties, such as fluoride release or ion-releasing capabilities that can help remineralize surrounding tooth structure and inhibit secondary caries formation.
- Emerging Market Penetration:Underpenetrated markets across Southeast Asia and Latin America present substantial growth avenues. As dental infrastructure and disposable incomes rise in countries like Brazil and India, demand for modern restorative materials will accelerate.
- Orthodontic Applications:Formulating specialized adhesives for orthodontic bonding represents a key growth vector. Products tailored for bonding brackets and retainers, offering easy cleanup and reliable bond strength, can capture a dedicated segment.
Industry Challenges
- Evolving Material Regulations:Manufacturers face the continuous challenge of reformulating products to comply with changing international standards for substances like bisphenol A (BPA) and its derivatives, requiring constant R&D investment to maintain compliance across multiple regions.
- Practitioner Training and Education:The rapid introduction of new adhesive technologies necessitates ongoing education for dental professionals. Ensuring clinicians are proficient in the specific protocols for next-generation systems is critical for achieving optimal clinical performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Adhesives and Sealants Market |
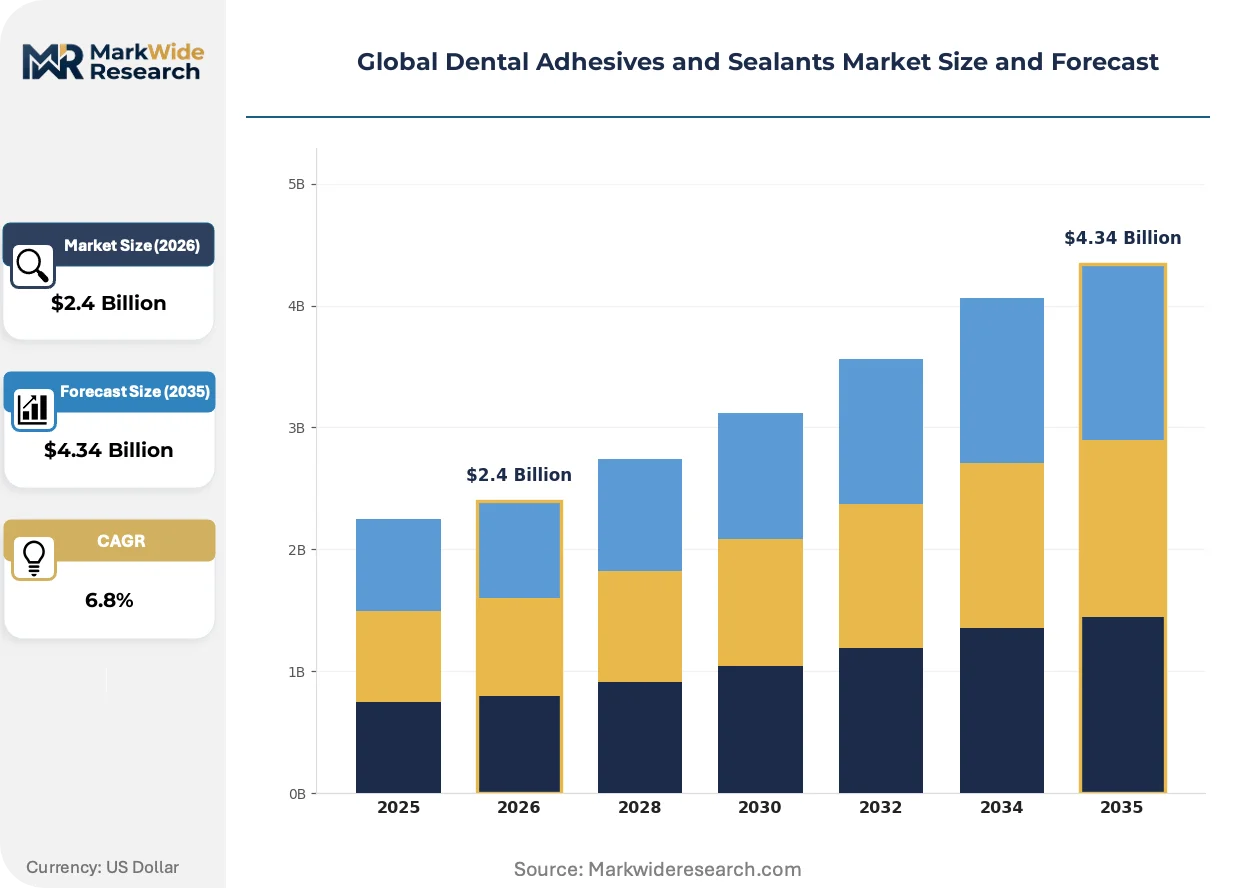
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Cure, Self Cure, Dual Cure, Resin Modified Glass Ionomer, Conventional Glass Ionomer, Polycarboxylate Application: Restorative Dentistry, Orthodontics, Endodontics, Prosthodontics, Preventive Care, Cosmetic Procedures End User: Dental Clinics, Dental Laboratories, Oral Surgery Centers, Academic Research Institutions Packaging Type: Syringe, Brush, Capsule, Bottle, Unit Dose, Cartridge |
| Companies Covered | Kuraray Noritake Dental, GC Corporation, 3M, SDI Limited, Ultradent Products, Ivoclar Vivadent, BISCO, Tokuyama Dental Corporation, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Adhesives and Sealants Market Strategic Shifts & Innovations
The convergence of digital dentistry workflows with advanced material science is fundamentally altering product development and selection criteria. This integration demands adhesives that not only provide strong, durable bonds but also offer aesthetic predictability and compatibility with CAD/CAM-milled and 3D-printed restorations.
Digital smile design (DSD) software enables precise virtual planning of cosmetic and restorative treatments by integrating patient scans and photographs. Prosthodontists and cosmetic dental clinics are the primary adopters of DSD for complex full-mouth rehabilitation cases. This trend is virtualizing the entire treatment planning phase, creating demand for adhesive systems with proven color stability and shade matching to ensure the final restoration perfectly aligns with the digital blueprint.
Japan's Pharmaceuticals and Medical Devices Agency (PMDA) has intensified its requirements for long-term clinical evidence demonstrating the biocompatibility of dental materials. This regulatory pressure forces manufacturers to invest in more rigorous pre-market studies and robust post-market surveillance programs. The restorative adhesives segment is particularly affected, compelling suppliers targeting the Japanese market to prioritize the development and validation of Bis-GMA-free and HEMA-free formulations.
Large dental service organizations (DSOs) and multi-clinic groups are standardizing material procurement around integrated product systems from a single manufacturer. This behavior disrupts the traditional model of purchasing individual items like bonding agents and composites from multiple vendors based on preference or price. This shift is most visible in the United States, where the operational efficiency and clinical consistency offered by a complete, validated workflow are highly valued.
Global Dental Adhesives and Sealants Market Segmentation
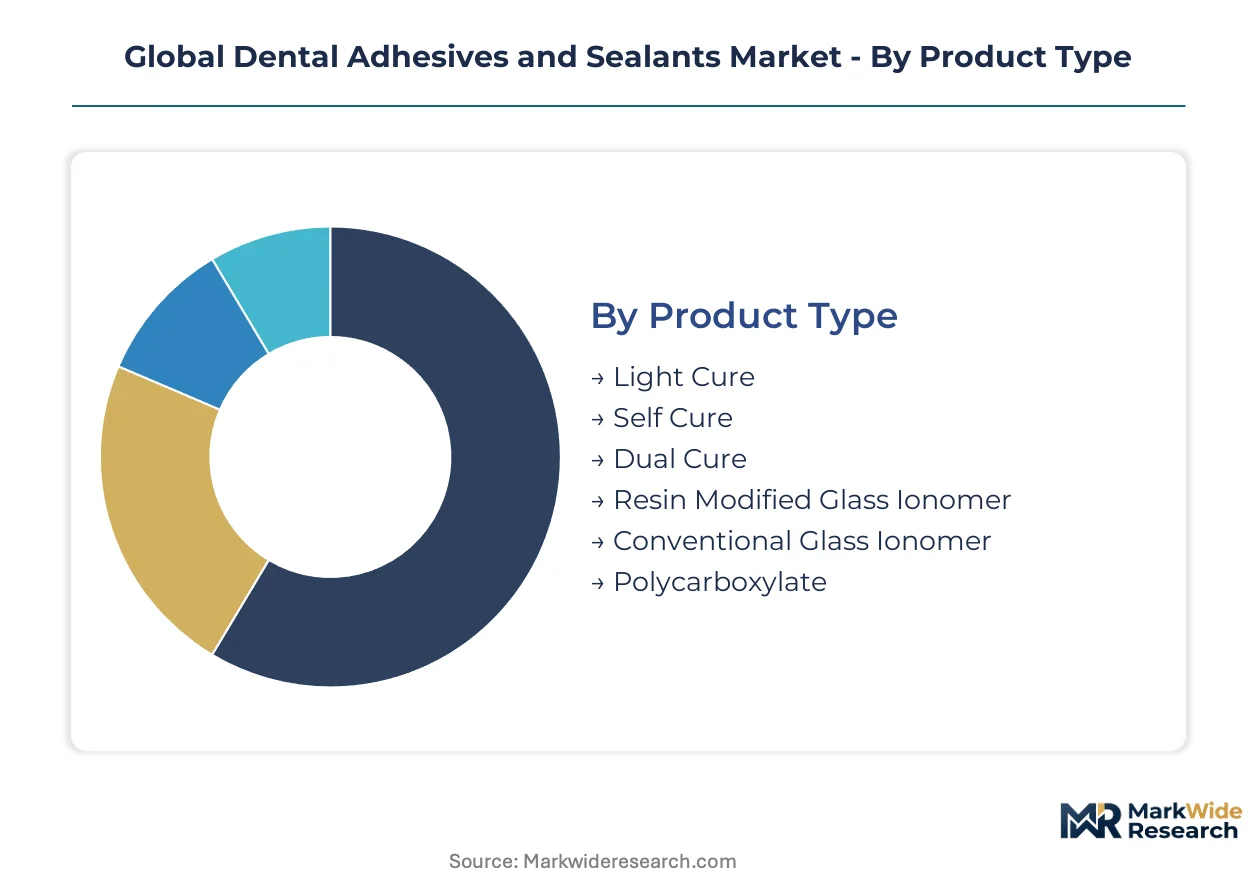
The segmentation of the global dental adhesives and sealants market reveals distinct drivers and user requirements across various product forms and clinical applications. Understanding these segments is crucial for manufacturers to tailor product development and market penetration strategies effectively.
Product Type:
The after-sales-service intensity for dental adhesives and sealants varies significantly across product types, influencing clinical training and material handling protocols.
- Light Cure:These resin-based materials polymerize on demand when exposed to specific wavelengths of light, offering clinicians precise control over working time. Demand concentrates in restorative dentistry applications where general practitioners prioritize clinical efficiency and predictable outcomes.
- Resin Modified Glass Ionomer:These materials combine the fluoride-releasing properties of glass ionomers with the strength of resin, forming a strong bond to dentin and enamel. Pediatric dentistry and preventive care drive demand for these formulations, particularly in school-based sealant programs across the United States.
- Self Cure:These adhesives polymerize through a chemical reaction between two components, suitable for areas where light access is challenging.
- Dual Cure:Combining light-curing and self-curing mechanisms, these products ensure complete polymerization in deep cavities or opaque restorations.
- Conventional Glass Ionomer:Known for their fluoride release and biocompatibility, these materials bond chemically to tooth structure, especially in non-stress-bearing areas.
- Polycarboxylate:These early dental cements offer chemical adhesion to tooth structure and are primarily used for luting crowns and bridges.
Light Cure products hold the largest market share; momentum sits with Resin Modified Glass Ionomer formulations.
Application:
Application diversity in dental adhesives and sealants directly reflects the range of clinical procedures where these materials are indispensable.
- Restorative Dentistry:This application involves bonding various restorative materials like composites and ceramics to prepared tooth structures for fillings, inlays, and onlays. Minimally invasive dentistry and the needs of an aging demographic in countries like Germany sustain demand for high-performance bonding agents.
- Preventive Care:This segment includes pit and fissure sealants applied to occlusal surfaces to prevent caries, particularly in pediatric patients. Growing awareness of oral health and school-based programs in the United States expand the use of these sealants.
- Orthodontics:Specialized adhesives are formulated for bonding brackets, bands, and retainers to tooth surfaces, requiring reliable bond strength and easy debonding.
- Endodontics:Adhesives and sealants are used in root canal procedures to seal the root canal system, preventing microbial leakage.
- Prosthodontics:These materials facilitate the bonding of crowns, bridges, veneers, and other prosthetic devices to natural teeth or implants.
- Cosmetic Procedures:Adhesives are essential for bonding aesthetic restorations such as veneers and direct composite buildups, requiring excellent color stability.
Restorative dentistry applications continue to define the core market, while preventive care is expanding rapidly.
End User:
The specific end-user category dictates the procurement scale and technical support requirements for dental adhesives and sealants.
- Dental Clinics:These facilities represent the primary point of application for dental adhesives and sealants, serving general practitioners and specialists across a broad patient base. Demand is influenced by the adoption of integrated product systems and universal adhesives for streamlined workflows.
- Oral Surgery Centers:Specialized centers performing complex surgical procedures utilize specific bonding agents for postsurgical applications and advanced restorative needs. The large network of these centers in the United States contributes significantly to demand.
- Dental Laboratories:Laboratories use adhesives and sealants for fabricating and repairing indirect restorations like crowns, bridges, and dentures before delivery to clinics.
- Academic Research Institutions:These institutions focus on the development and testing of new dental materials, including advanced adhesive formulations and their biocompatibility.
Dental clinics remain the largest end-user segment, with oral surgery centers showing significant growth.
Packaging Type:
Packaging type for dental adhesives and sealants often aligns with clinical efficiency demands and volume requirements.
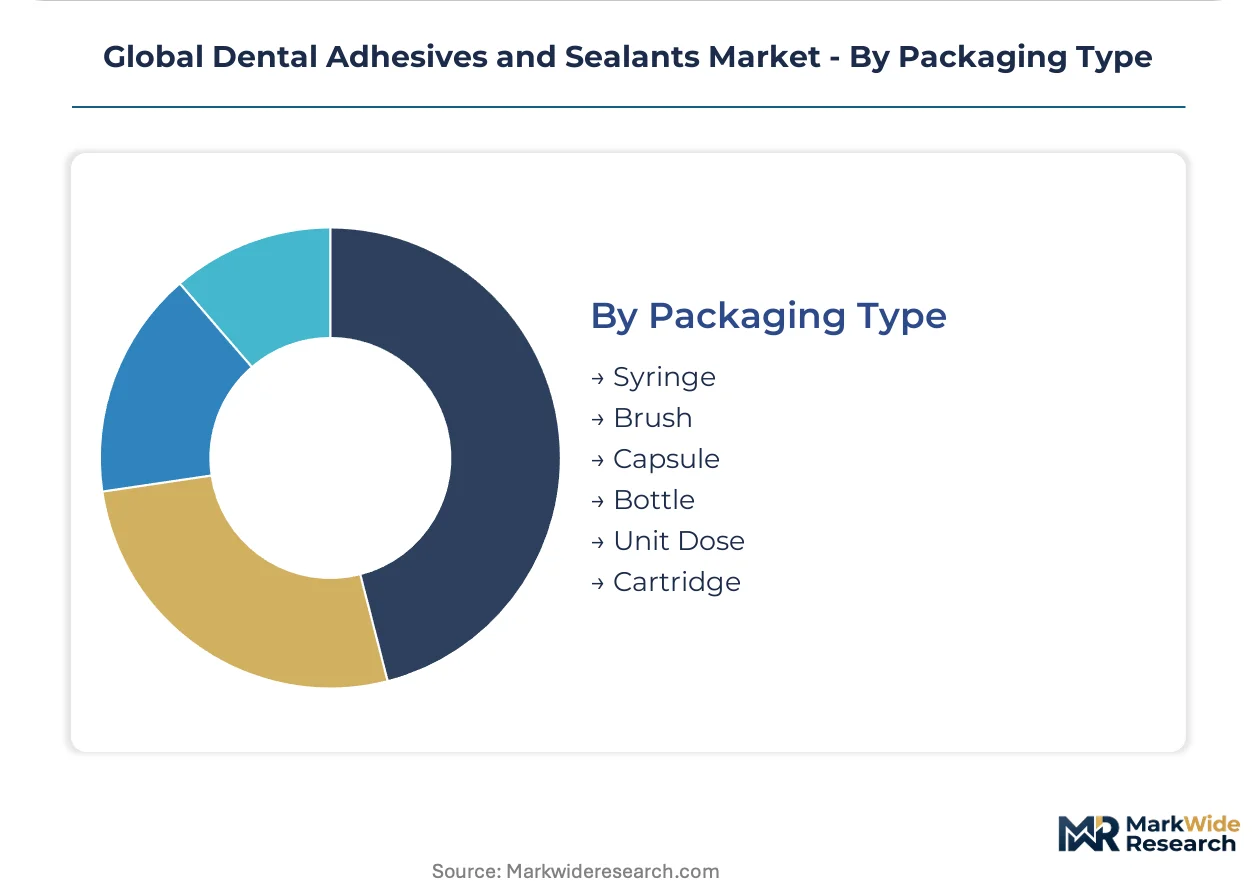
- Syringe:This packaging allows for precise, controlled dispensing of viscous materials, often used for pit and fissure sealants or specialized bonding agents in orthodontics. This format minimizes waste and ensures targeted application.
- Unit Dose:These single-use packages contain pre-measured amounts of adhesive, enhancing infection control and reducing material waste in busy clinical settings. Large dental service organizations increasingly favor unit dose formats for operational efficiency.
- Brush:Adhesives supplied with brush applicators facilitate thin, even coats across tooth surfaces, commonly found with single-bottle systems.
- Capsule:Self-contained capsules often mix components automatically, providing consistent material properties and simplifying application for glass ionomer cements.
- Bottle:Traditional bottle packaging provides bulk material for multiple applications, requiring separate dispensing and mixing accessories.
- Cartridge:Dual-barrel cartridges are used for two-component systems, ensuring precise mixing ratios for self-cure or dual-cure adhesives.
Syringe packaging offers precision for specific applications, while unit dose formats gain traction for clinical efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for dental adhesives and sealants exhibits asymmetry, with the United States commanding premium values due to its advanced dental infrastructure. Conversely, markets like India prioritize cost-effectiveness for broader access and expanding dental care initiatives. This dynamic influences product development and market entry strategies across different regions.
United States
Demand for dental adhesives and sealants in the United States stems from a large network of dental clinics and oral surgery centers. School-based dental sealant programs, supported by public health initiatives, drive consistent demand for preventive materials. The US FDA mandates rigorous pre-market approval for all dental devices, including bonding agents. Major metropolitan areas like New York and Los Angeles serve as hubs for advanced restorative and cosmetic dentistry, fostering innovation in material application.
Germany
Germany's market for dental adhesives and sealants is sustained by an aging demographic with a higher prevalence of root caries and complex restorations. The country's adherence to CE marking under the Medical Device Regulation (MDR) requires extensive clinical evidence for biocompatibility. Dental material research and development clusters in cities such as Cologne and Munich contribute to the evolution of high-performance bonding agents.
Japan
Japan's demand for dental adhesives and sealants is significantly influenced by its elderly population and stringent regulatory environment. The PMDA has intensified requirements for long-term clinical evidence, compelling manufacturers to develop Bis-GMA-free and HEMA-free formulations. Tokyo and Osaka host key research and development centers, focusing on advanced polymer chemistry for dental applications.
Brazil
Brazil represents a substantial growth avenue for dental adhesives and sealants, driven by rising disposable incomes and expanding dental infrastructure. ANVISA regulates dental products, ensuring compliance with national health standards for material safety and efficacy. São Paulo's dental industry cluster supports local manufacturing and distribution, catering to a growing consumer base for modern restorative materials.
India
India's market expansion for dental adhesives and sealants is propelled by increasing awareness of oral health and a rising focus on preventive pediatric care. The Bureau of Indian Standards (BIS) sets quality benchmarks for dental materials, guiding product development for local and international suppliers. Major cities like Mumbai and Bangalore are experiencing rapid growth in dental clinics, accelerating the adoption of contemporary bonding agents.
Global Dental Adhesives and Sealants Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential materials. The market structure for dental adhesives and sealants exhibits a tiered consolidation, with a few global players dominating significant segments. This landscape features diversified global corporations, specialized dental material manufacturers, and regional niche players. Dominant competitive moves include portfolio diversification into integrated systems and strategic partnerships for technology co-development.
On the global stage, 3M exemplifies broad portfolio diversification across multiple dental product categories, leveraging its extensive material science expertise. Kuraray Noritake Dental represents a focus on deep R&D in polymer chemistry for specialized bonding agents, emphasizing performance and biocompatibility. Ivoclar Vivadent occupies a position as an integrator, differentiating through integrated systems for restorative and prosthetic dentistry, streamlining clinical workflows for practitioners.
| Leading Market Players |
|---|
| Kuraray Noritake Dental |
| GC Corporation |
| 3M |
| SDI Limited |
| Ultradent Products |
| Ivoclar Vivadent |
| BISCO |
| Tokuyama Dental Corporation |
| Dentsply Sirona |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes for petrochemical-derived raw materials impact dental adhesive pricing, affecting regional differentiation and manufacturer margins. This dynamic influences how manufacturers manage inventory and optimize their distribution networks.
Pricing Analysis
Custom-formulated bonding agents command premium pricing over standard universal adhesives, reflecting specialized R&D. The dominant pricing model is per-unit transactional, influenced by volume and brand reputation. Price differentiation stems from biocompatibility certifications, such as Bis-GMA-free formulations, and after-sales support. Cost compression in standard formulations is intensifying due to increasing competition and input cost volatility. Large dental service organizations exhibit the most price sensitivity for bulk purchases, while specialized oral surgery centers prioritize performance over cost.
Supply Chain Analysis
Upstream petrochemical feedstocks, particularly for methacrylate monomers and photoinitiators, originate primarily from China and the United States. Key raw material dependencies include Bis-GMA, HEMA, and various photoinitiators. Commodity price volatility for these petrochemical derivatives poses a structural risk to manufacturer margins. Distribution runs through specialized dental distributors and direct sales channels, reaching clinics and laboratories globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental adhesives and sealants market is experiencing a cyclical recovery, driven by deferred dental procedures post-pandemic. This rebound creates opportunities across the value chain.
For Market Incumbents:
Insulate core market share by investing in next-generation biocompatible formulations, particularly Bis-GMA-free systems, to counter evolving material regulations. Strengthen relationships with large dental service organizations (DSOs) through integrated product systems, mitigating new entrant price competition. Deepen vertical integration into key raw material production to mitigate input cost volatility. Develop comprehensive training programs for clinicians to ensure optimal product application and consistent outcomes, reducing technique sensitivity.
For New Entrants and Emerging Players:
Pursue niche market opportunities in specialized bioactive formulations for remineralization, addressing unmet clinical needs. Target underpenetrated emerging markets in Southeast Asia and Latin America with cost-effective, high-performance universal adhesives. Develop products specifically for orthodontic applications, focusing on easy cleanup and reliable bond strength. Leverage digital marketing and direct-to-dentist sales models to efficiently reach practitioners in specific segments.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core dental material divisions. Long-term viability for dental adhesives and sealants remains strong over the next five to ten years due to persistent oral health needs and an aging demographic. Identify specialized bonding agent manufacturers with strong R&D pipelines in bioactive or Bis-GMA-free technologies. The signal to watch is accelerating adoption rates of universal adhesives in new geographic markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates new biocompatible formulations for expanded market acceptance and regulatory compliance. |
| Integrated System Development | Streamlines clinical workflows for dental practitioners, enhancing product adoption and efficiency. |
| Geographic Expansion (Emerging Markets) | Captures demand in regions with rising dental infrastructure and disposable incomes. |
| Bioactive Material R&D | Addresses secondary caries prevention, improving patient outcomes and material longevity. |
| Regulatory Certification Investment | Ensures compliance with stringent standards like Europe's MDR, enabling market access. |
Research Approach
Operator-level perspectives from dental practitioners, oral surgeons, material scientists, and regulatory specialists anchored the qualitative base. Primary interviews were combined with secondary validation from peer-reviewed journals and dental association reports. This approach ensured bottom-up insights were triangulated with top-down market intelligence. Public financial filings of key manufacturers provided additional data points for market sizing.
Scenario-bracketing provided a comprehensive view of potential market trajectories over the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and anticipated technological advancements in restorative dentistry. Industry-specific inputs included dental visit frequency and material adoption rates.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or raw material prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological adoption within dental practices. Cross-checking against national dental health surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Sealants Market