
 2K Epoxy Adhesives Market | 2026-2036
2K Epoxy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
2K Epoxy Adhesives Market Analysis
Subscription-based technical support and predictive maintenance software is restructuring how adhesive suppliers monetize customer relationships. Henkel leverages its global service infrastructure to lock in long-term automotive contracts. Sika anchors its position through specialized construction application expertise. 3M competes on technology leadership in high-performance bonding formulations.
Two-component epoxy adhesives consist of a resin base and a hardener that chemically cure when mixed, delivering tensile shear strengths exceeding 20 MPa and chemical resistance for structural load-bearing applications. Rigid formulations dominate aerospace and automotive assembly where structural integrity is paramount, while flexible variants capture expanding share in electronics and vibration-dampening uses. Water-based technology segments face margin compression from environmental compliance costs, whereas UV-curable systems command premium positioning in precision electronics manufacturing.
EPA regulations in the United States restrict volatile organic compound emissions from solvent-based formulations, while REACH in Europe mandates disclosure of Substances of Very High Concern in chemical compositions. ECHA's evolving restriction proposals on bisphenol derivatives are forcing reformulation investments across multiple supplier portfolios. ISO 10993 biocompatibility standards increasingly govern medical device applications, creating new qualification barriers. Stakeholders must monitor regulatory divergence between jurisdictions and pre-position compliant product lines before restriction deadlines crystallize.
Market Dynamics
Automotive lightweighting mandates and electric vehicle platform proliferation are compressing traditional mechanical fastening cycles, forcing structural adhesive specification at the design stage rather than as aftermarket alternatives.
Growth Catalysts
- REACH Substance of Very High Concern disclosure mandates:European formulators investing in bisphenol-free chemistries capture first-mover certification advantages for medical and food-contact applications.
- Battery pack assembly standardization:Electric vehicle manufacturers specify thermally conductive 2K epoxies for cell-to-cell bonding and thermal management module fixation.
- Germany's industrial corridor concentration:Precision engineering clusters in Baden-Württemberg and Bavaria consolidate procurement volumes for high-performance structural grades.
Market Restraints
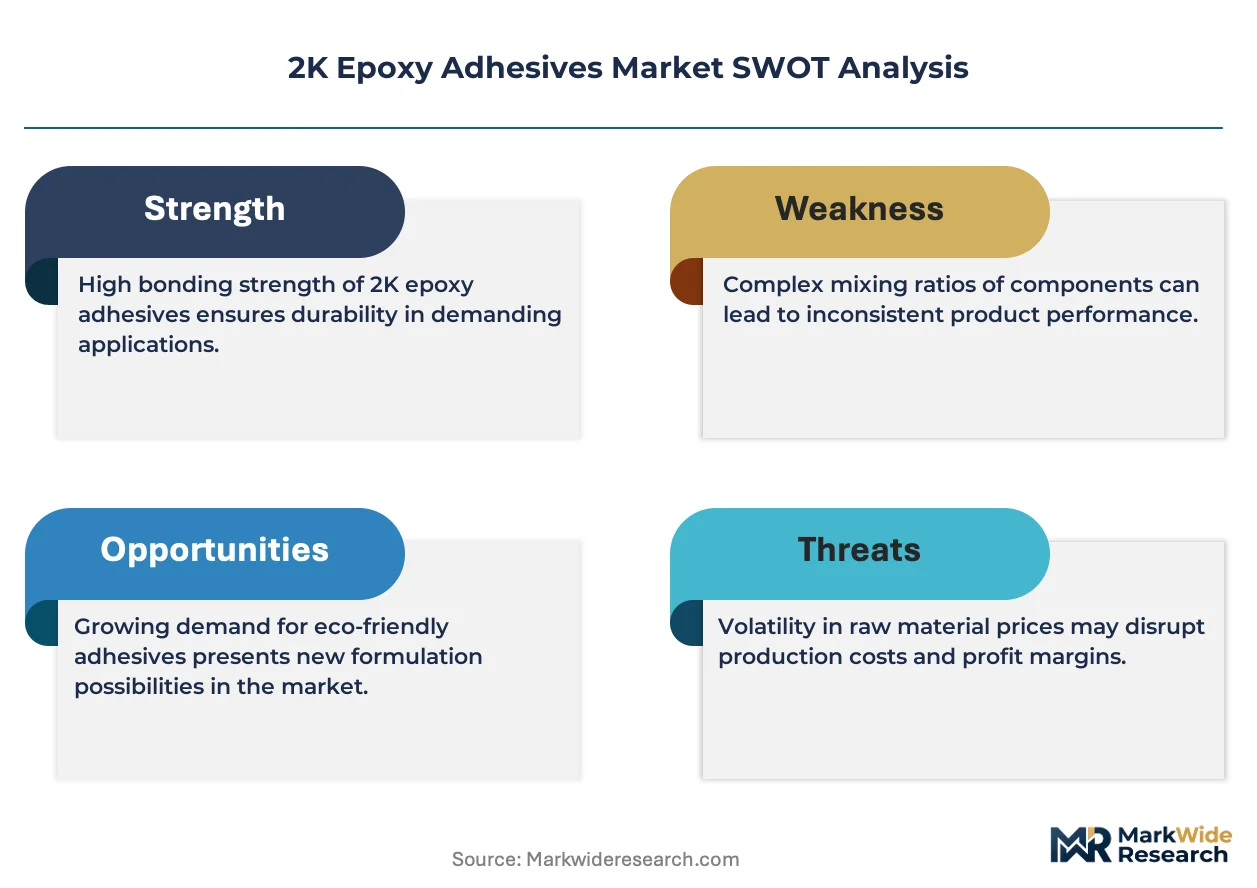
- Petrochemical feedstock volatility:Epichlorohydrin and bisphenol-A price swings compress formulation margins unpredictably.
- Specialized hardener supply concentration:Aliphatic amine production clusters in China create single-source vulnerability for Western compounders.
- Cure time inflexibility:Room-temperature curing formulations require 24-72 hour fixture periods, limiting high-volume assembly line throughput.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic electric vehicle manufacturing incentives create localized adhesive demand without import duty exposure.
- Wind turbine blade repair:Offshore wind expansion in the North Sea drives structural composite bonding services.
- UV-thermal dual-cure convergence:Hybrid curing systems enable rapid tack followed by full thermal crosslinking for electronics miniaturization.
Industry Challenges
- Formulation chemist scarcity:Polymer science programs produce insufficient talent for custom adhesive development pipelines.
- ISO 10993 biocompatibility timeline:Medical device qualification cycles extend 18-36 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2K Epoxy Adhesives Market |
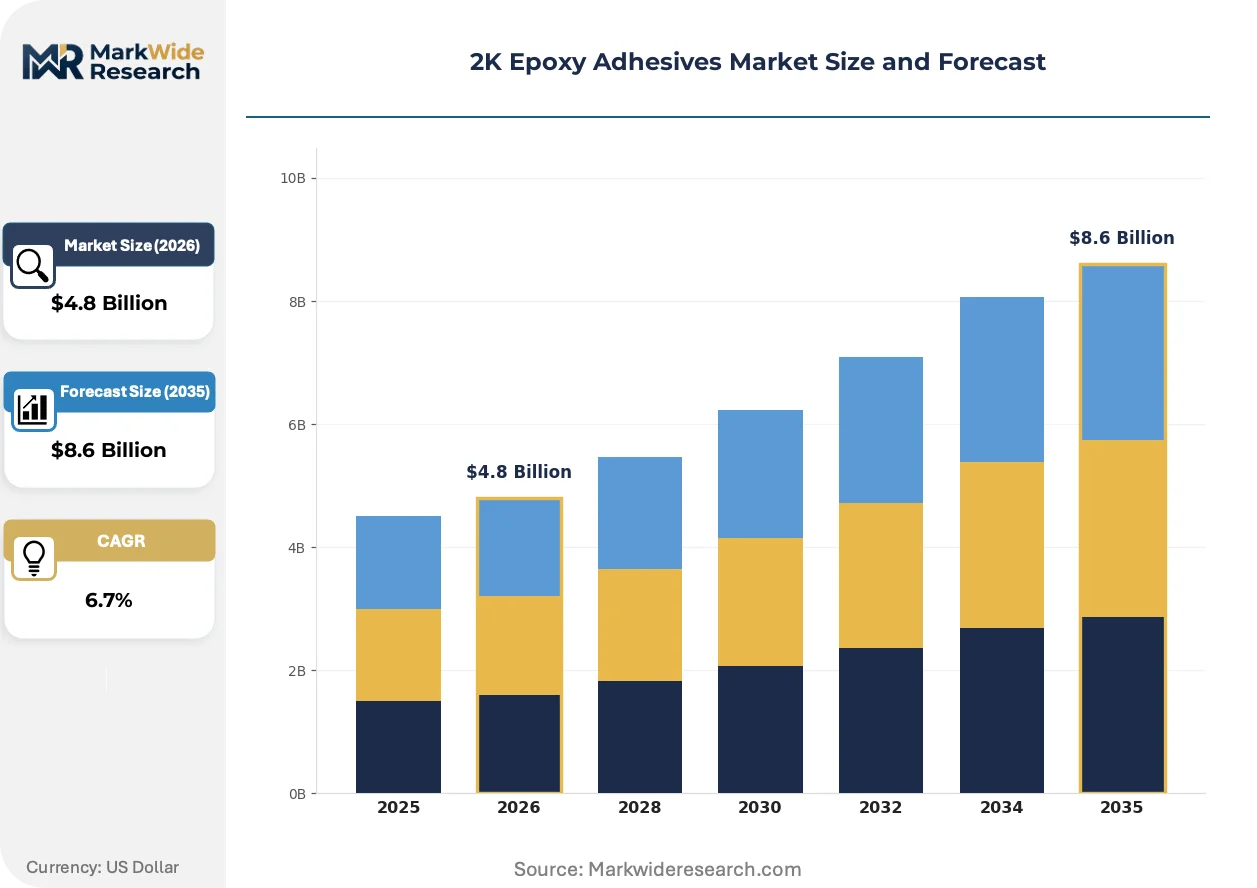
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Gel, Paste Application: Aerospace, Automotive, Electronics, Construction End User: Manufacturers, DIY Enthusiasts, Contractors, Engineers Technology: Solvent-Based, Water-Based, UV-Curable, Hot Melt |
| Companies Covered | 3M, Henkel, H.B. Fuller Company, Sika, Huntsman, Arkema, DuPont, Master Bond, Permabond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2K Epoxy Adhesives Market Emerging Trajectories
Bio-based feedstock substitution and cure-on-demand technologies are restructuring formulation economics and application workflows across transportation and electronics assembly.
Thermally conductive fillers such as boron nitride and aluminum oxide are integrating into battery-grade epoxy systems to manage cell-level heat dissipation. Electric vehicle battery pack assemblers specify these materials for module-to-coolant plate bonding. The technology is integrating thermal management and structural functions into single material layers, reducing part count and assembly labor.
EPA volatile organic compound emission thresholds for solvent-based adhesives are tightening industrial hygiene requirements in US manufacturing facilities. Formulators face reformulation costs or capital expenditure for emission control systems. Automotive assembly plants in Michigan and Ohio are accelerating water-based and 100% solid epoxy transitions to avoid permitting delays.
Subscription technical support and predictive shelf-life monitoring are displacing transactional product sales in high-value applications. Aerospace and medical device manufacturers contract for guaranteed performance rather than per-kilogram pricing. This pattern concentrates in German and Swiss precision manufacturing clusters where downtime costs exceed material premiums.
2K Epoxy Adhesives Market Segmentation
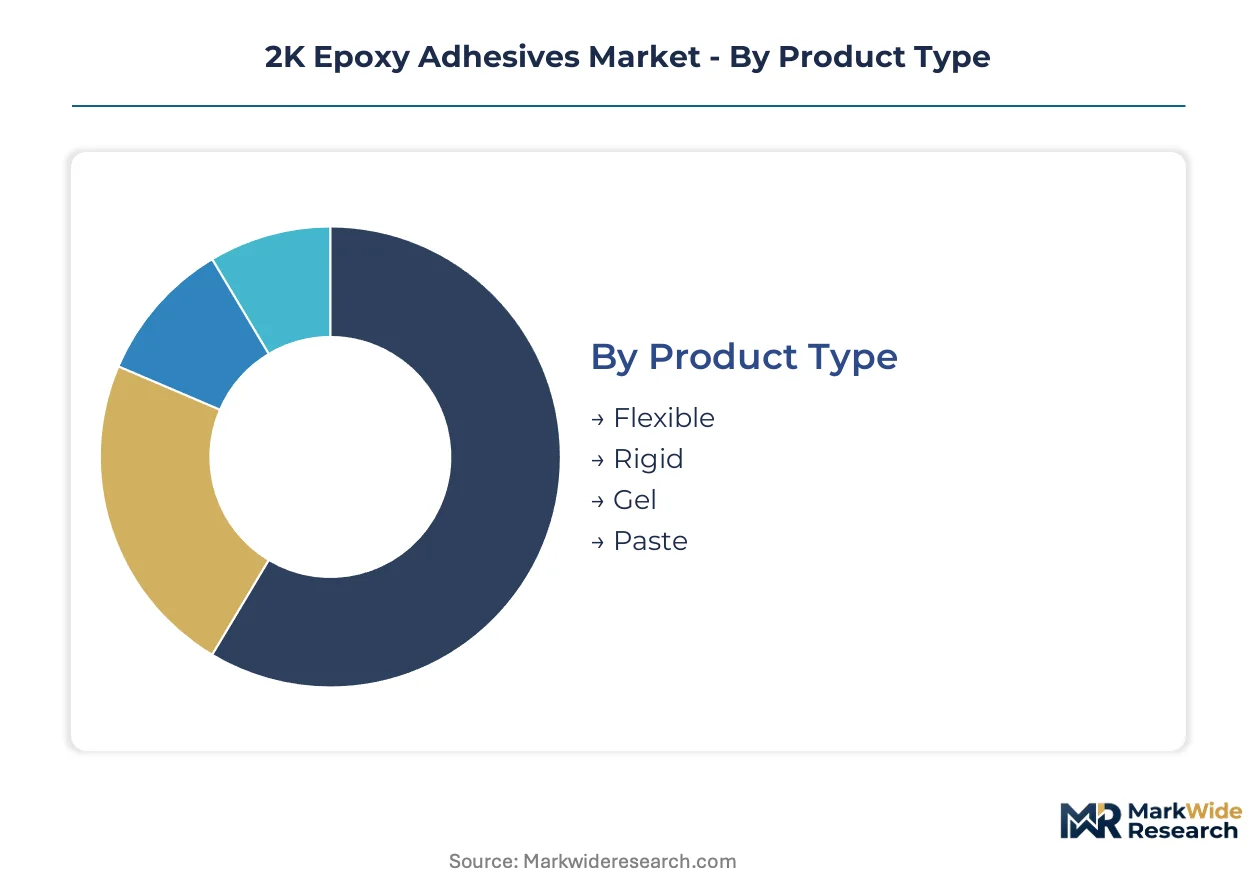
Segmentation in 2K epoxy adhesives determines which formulations qualify for regulated applications. Certification requirements vary sharply across product types and end-uses, creating divergent margin structures and qualification timelines for suppliers.
Product Type:
ISO 10993 biocompatibility governs medical-grade flexible formulations, while aerospace rigid grades demand FAA-compliant flame resistance documentation. REACH Substance of Very High Concern screening affects gel and paste variants differently based on amine hardener selection.
- Flexible:Modified with aliphatic amines and rubber tougheners to achieve elongation at break exceeding 50%. Electric vehicle battery pack assemblers in Germany's industrial corridor specify these grades for cell-to-cell bonding where thermal cycling tolerance is critical.
- Rigid:High crosslink density delivers tensile shear strengths above 25 MPa with minimal elongation. Aerospace structural bonding programs in Toulouse and Hamburg mandate these formulations for primary airframe assembly where load-bearing integrity is non-negotiable.
- Gel:Thixotropic consistency enables vertical surface application without sag. Wind turbine blade repair services in the North Sea favor gel formulations for leading edge erosion protection.
- Paste:High viscosity supports gap-filling in irregular joint geometries. Construction contractors specify paste grades for concrete crack injection and masonry restoration.
Rigid formulations sit at the top of the volume ranking, with flexible variants climbing the fastest.
Application:
Cost tier stratification separates aerospace qualification expenses from construction commodity pricing. Electronics applications command mid-tier positioning driven by precision dispensing equipment requirements.
- Aerospace:Qualification cycles extend 24-48 months for OEM-approved supplier status. FAA flame-smoke-toxicity standards and OEM process specifications create insurmountable barriers for non-specialized compounders.
- Automotive:OEM direct specification is displacing tier-supplier procurement for structural bonding. Michigan and Ohio assembly plants are consolidating adhesive suppliers to reduce qualification redundancy.
- Electronics:Miniaturization trends favor low-outgassing formulations for optical and sensor applications. Swiss precision manufacturing clusters drive specification for UV-thermal dual-cure systems.
- Construction:Project-scale procurement favors bulk pricing over technical service bundling. German infrastructure rehabilitation programs concentrate demand for high-durability structural grades.
Automotive applications generate the highest revenue concentration, with electronics expanding most quickly.
End User:
Customer type determines service intensity and pricing architecture. Manufacturers contract for guaranteed performance; contractors transact on per-kilogram terms.
- Manufacturers:Aerospace and automotive OEMs demand predictive shelf-life monitoring and technical support subscriptions. These contracts lock in multi-year supply relationships with penalty clauses for batch failure.
- DIY Enthusiasts:Retail packaging and simplified mixing ratios dominate this channel. Hardware store distribution in suburban US markets concentrates volume for small-format twin-syringe products.
- Contractors:Project-based procurement with price sensitivity and limited technical support requirements. Construction adhesive demand clusters with infrastructure spending cycles.
- Engineers:Specification authority without procurement control creates influence without volume commitment. Design-stage involvement is critical for adhesive selection in new product development.
Manufacturers represent the dominant revenue pool, with engineers gaining specification influence fastest.
Technology:
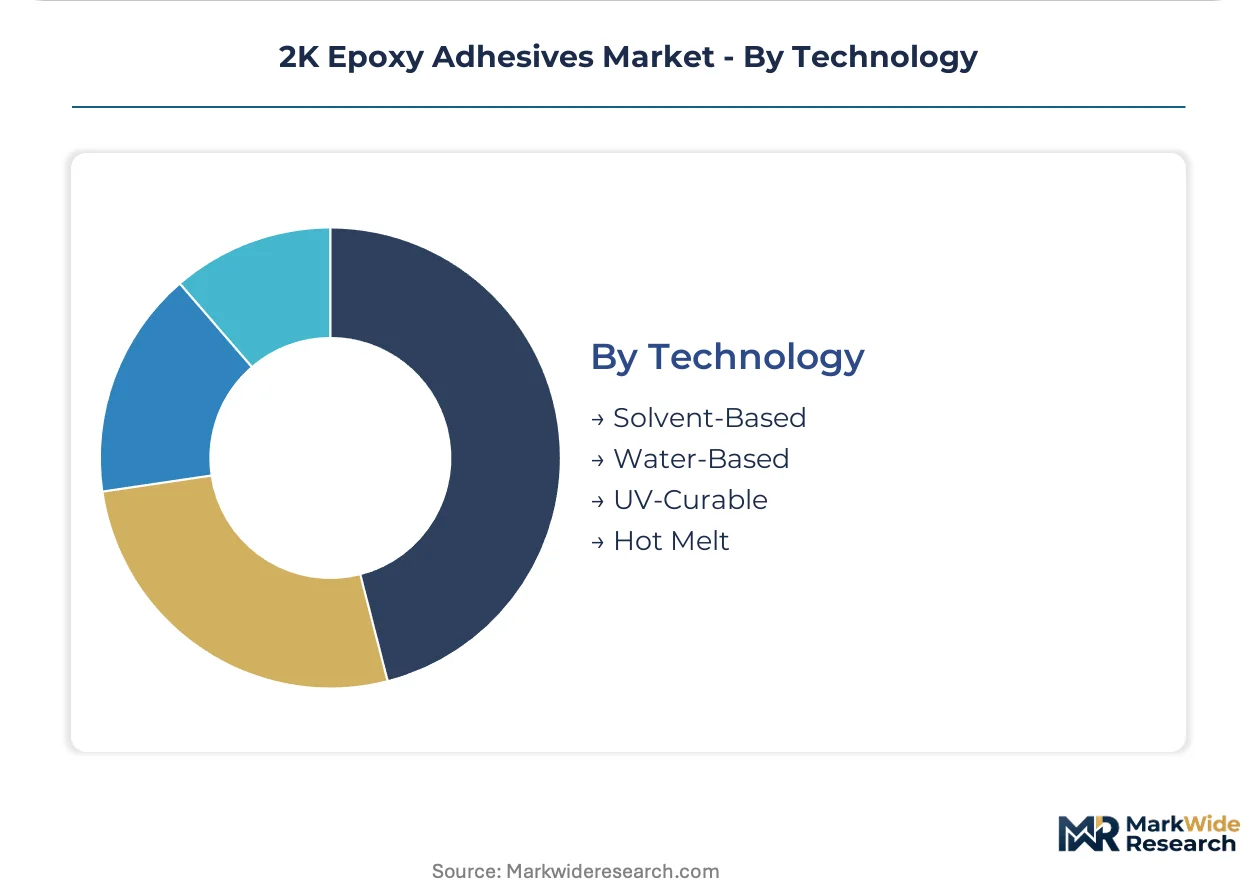
Environmental compliance costs are compressing solvent-based margins while UV-curable systems capture premium positioning. Water-based formulations face performance limitations in structural applications.
- Solvent-Based:EPA volatile organic compound emission thresholds are forcing capital expenditure for emission control systems or reformulation investment. Automotive plants in Michigan and Ohio are accelerating transitions to avoid permitting delays.
- Water-Based:Reduced volatile organic compound profiles satisfy environmental regulations but compromise moisture resistance. Indoor construction applications with controlled humidity represent the viable addressable market.
- UV-Curable:Instant surface tack enables high-throughput electronics assembly. Precision manufacturing in Baden-Württemberg specifies these systems for miniaturized component bonding.
- Hot Melt:Thermoplastic reversion limits structural load-bearing applications. Packaging and temporary fixturing represent primary end-uses with limited overlap to structural epoxy markets.
Solvent-based technology retains the largest installed base, with UV-curable systems gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting 2K epoxy adhesive production toward jurisdictions with lower compliance-cost burdens. Formulators in China and India capture margin advantages as European REACH implementation tightens. Automotive and electronics manufacturers are diversifying supply footprints to hedge against single-source exposure.
United States
Electric vehicle battery assembly in Michigan and Ohio drives thermally conductive epoxy procurement. EPA volatile organic compound thresholds force solvent-based reformulation or capital expenditure for emission controls. Detroit-area automotive clusters consolidate adhesive suppliers to streamline OEM qualification cycles.
Germany
Precision engineering demand concentrates in Baden-Württemberg and Bavaria for high-performance structural grades. ECHA restriction proposals on bisphenol derivatives accelerate reformulation investments across supplier portfolios. Stuttgart and Munich industrial corridors standardize procurement for electric vehicle platform bonding.
China
Domestic electric vehicle manufacturing scales adhesive consumption for battery pack thermal management. MIIT industrial standards and dual carbon goals pressure emission-intensive production methods. Yangtze River Delta chemical clusters expand aliphatic amine hardener capacity to reduce import dependency.
India
PLI scheme incentives for automotive manufacturing create localized adhesive demand without import duty exposure. BIS certification requirements and DGFT trade regulations shape formulation compliance pathways. Tamil Nadu and Gujarat vehicle assembly hubs concentrate procurement for structural bonding applications.
Japan
Electronics miniaturization favors low-outgassing formulations for optical and sensor bonding. METI technology roadmaps and JIS standards govern material qualification for precision manufacturing. Kansai and Chubu industrial regions specify UV-thermal dual-cure systems for high-throughput assembly.
2K Epoxy Adhesives Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The market structure consolidates around diversified chemical conglomerates with adhesive divisions, while regional compounders capture niche specification authority. Three archetypes dominate: integrated material science conglomerates, construction-specialized adhesive formulators, and precision electronics bonding specialists. M&A activity targets hardener technology access and geographic footprint expansion.
Within the integrated conglomerate tier, 3M and Henkel exemplify technology leadership archetypes. Sika occupies a position representing construction-specialized expertise. These three anchors demonstrate how scale-driven players, application-focused specialists, and innovation-led formulators coexist without direct segment overlap.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| H.B. Fuller Company |
| Sika |
| Huntsman |
| Arkema |
| DuPont |
| Master Bond |
| Permabond |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between aerospace-qualified structural epoxies and construction commodity grades manifests in both pricing power and supply chain depth. Premium formulations command subscription-based technical support bundling while commodity tiers transact on spot pricing through distributor networks.
Pricing Analysis
Distributor margin layers absorb 15-25 points between formulator ex-works and end-user delivered pricing across standard grades. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from construction bulk volumes. Pricing pressure stems from REACH-driven reformulation investments in European supply bases. Automotive OEMs exhibit lowest price sensitivity due to penalty-clause contracts; construction contractors transact with highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with aliphatic amine hardener production concentrated in China's Yangtze River Delta chemical clusters. Epichlorohydrin supply draws from China, South Korea, and Germany; bisphenol-A feedstock rests on petrochemical complexes in the US Gulf Coast and Rotterdam. Tariff exposure compounds margin risk for Western compounders dependent on Asian hardener imports. Distribution runs through authorized distributor networks for qualified grades, direct mill-to-OEM contracts for automotive structural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on bisphenol-free chemistry transitions capturing medical-device certification premiums ahead of ECHA restriction deadlines.
For Market Incumbents: To counter feedstock volatility compressing formulation margins, Henkel and 3M should deepen backward integration into specialty amine production and lock long-term offtake agreements with Yangtze River Delta suppliers. Certification investment in ISO 10993 biocompatibility tiers opens medical-device pricing premiums unreachable by commodity competitors. For New Entrants and Emerging Players: The mid-tier price-point gap between aerospace-qualified epoxies and construction commodity grades offers white-space targeting for India PLI-scheme automotive suppliers and North Sea wind turbine repair service providers. A technical-service-subscription go-to-market model displaces transactional pricing in German precision manufacturing clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with hardener technology specialists possessing aliphatic amine synthesis capabilities outside China. Long-term viability over a 5-10 year window favors targets with REACH-compliant bisphenol-free portfolios pre-positioned for ECHA restriction implementation. The signal to watch is OEM qualification cycle acceleration for electric vehicle battery-pack thermal management grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Amine Production | Reduces single-source dependency on Yangtze River Delta hardener clusters for Western compounders. |
| REACH-Compliant Bisphenol-Free Reformulation | Captures first-mover certification advantage for medical-device and food-contact adhesive applications. |
| Subscription Technical Support Launch | Locks multi-year automotive OEM contracts with predictive shelf-life monitoring in German industrial corridors. |
| India PLI-Scheme Manufacturing Footprint | Avoids import duty exposure for domestic electric vehicle battery assembly demand. |
| UV-Thermal Dual-Cure System Development | Enables Swiss precision electronics manufacturers to miniaturize component bonding workflows. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from adhesive formulation chemists, automotive OEM procurement leads, construction contractor purchasing managers, and medical device regulatory affairs specialists. Secondary validation drew from ECHA restriction proposal databases, EPA VOC emission threshold filings, SEC 10-K disclosures from listed chemical conglomerates, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting distributed value and volume projections across product type, application, end-user category, and technology platform dimensions. CAGRs derived from regression analysis of historical consumption patterns and forward-looking qualification pipeline visibility. Electric vehicle production forecasts and ECHA regulatory timeline assumptions shaped regional growth differentials.
The model assumes a particular technology adoption path; alternative pathways for UV-thermal dual-cure convergence would alter the outlook. Forecasts reflect assumptions about REACH implementation timing and battery pack standardization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Medical Adhesives Market
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
North America Laminating Adhesives Market