
 North America Bio Succinic Acid Market | 2026-2036
North America Bio Succinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bio Succinic Acid Market Analytics
Specialized fermentation technologists and metabolic engineering talent is rotating from pharmaceutical biotech toward industrial bio-based chemical platforms. BASF leverages its integrated petrochemical infrastructure to co-locate bio-succinic pilot capacity with existing polymer intermediates operations. DSM North America sustains microbial strain development programs that anchor its position in high-purity bio-based building blocks.
Bio succinic acid is a four-carbon dicarboxylic acid produced via microbial fermentation of renewable feedstocks such as corn-derived glucose or lignocellulosic biomass, functioning as a drop-in replacement for petroleum-derived succinic acid in polyester polyols, plasticizers, and solvent formulations. Industrial grade material dominates current volume flows, while pharmaceutical grade commands concentrated margin pools due to stringent USP and FCC purity thresholds. Biological fermentation processes are capturing investment preference over chemical synthesis routes, though hybrid processes retain relevance for cost-sensitive industrial applications.
The EPA regulates bio-succinic acid manufacturing facilities under the Clean Air Act and TSCA Section 5 for new chemical notifications, while the USDA BioPreferred program creates federal procurement preference for certified biobased content. FDA food additive and GRAS pathways govern food grade and pharmaceutical grade market access, with FCC monograph compliance serving as a de facto commercial gatekeeper. Stakeholders must monitor state-level renewable chemical tax credit competition between Illinois, Minnesota, and Iowa, as these incentives are reshuting capital allocation across the Midwest bioprocessing belt.
Market Dynamics
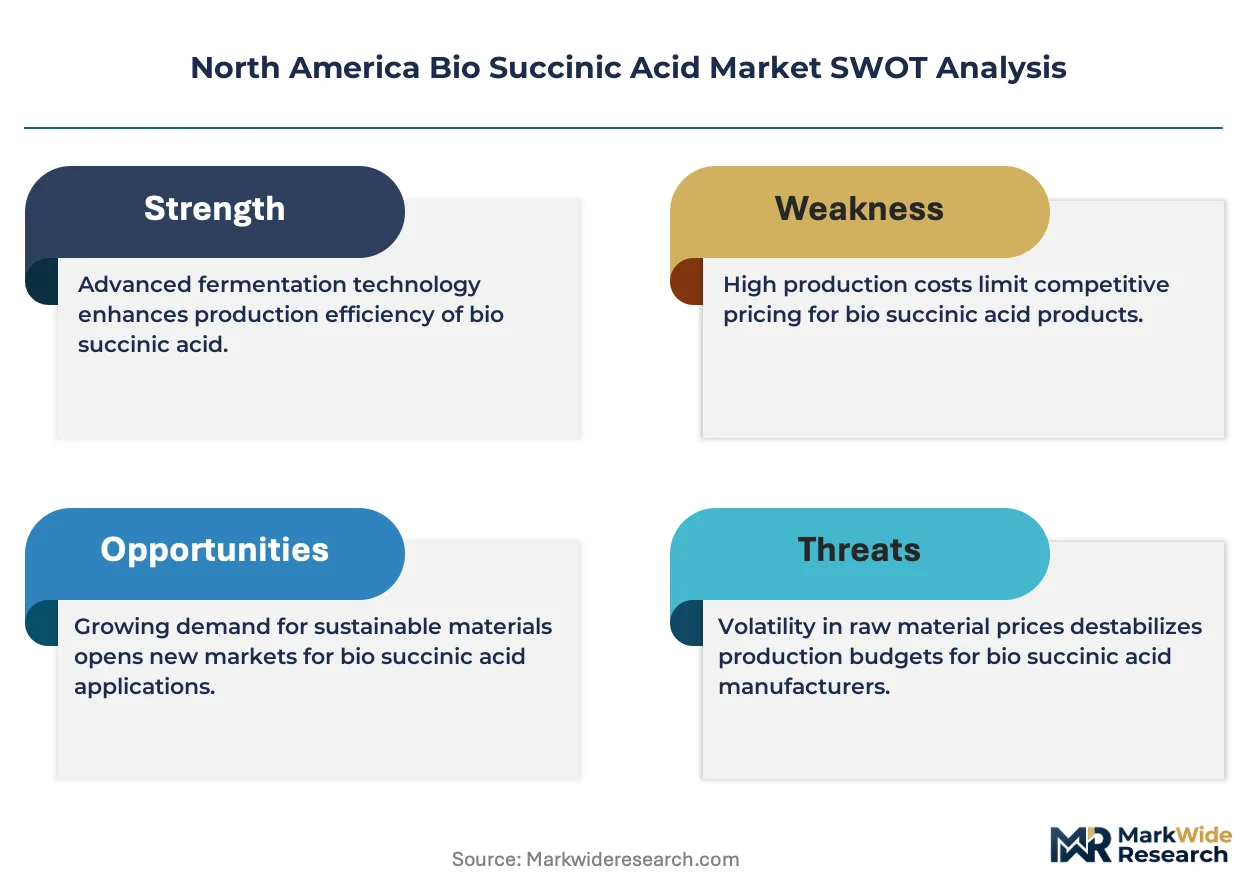
The Great Lakes industrial corridor is concentrating bio-succinic acid production capacity as integrated biorefinery operations exploit existing chemical processing infrastructure and fermentation-derived platform chemical registrations accelerate under streamlined EPA pathways.
Growth Catalysts
- USDA BioPreferred Program:Federal procurement preference for certified biobased content creates guaranteed offtake volume for domestic fermentation facilities serving polyester polyol manufacturers.
- Polyester Polyol Demand:Polyurethane foam and coating producers in the United States and Canada are expanding specifications to include bio-based feedstocks for sustainability reporting compliance.
- Great Lakes Infrastructure:Concentrated chemical processing assets around Detroit, Chicago, and Sarnia enable shared utilities and logistics networks that reduce unit production costs for fermentation operations.
Market Restraints
- Corn Glucose Price Volatility:Feedstock costs for industrial fermentation fluctuate with Midwest agricultural commodity markets and ethanol policy arbitrage.
- Petroleum-Derived Succinic Acid:Established petrochemical producers in the Gulf Coast maintain cost advantages through scale and integrated refinery economics that bio-based routes cannot yet match.
- Purification Bottlenecks:FCC monograph compliance for pharmaceutical grade material requires capital-intensive downstream processing that limits supplier participation in high-margin segments.
Strategic Opportunities
- State Tax Credit Arbitrage:Renewable chemical production incentives in Illinois, Minnesota, and Iowa are reshaping capital allocation across the Midwest bioprocessing belt.
- Lignocellulosic Feedstock Transition:Agricultural residue streams from corn stover and wheat straw offer pathway diversification beyond food-grade glucose dependence.
- Pharmaceutical Grade Expansion:USP-grade material for active pharmaceutical ingredient synthesis commands concentrated margin pools with limited qualified supplier base.
Industry Challenges
- Metabolic Engineering Talent Scarcity:Specialized fermentation technologists are rotating toward pharmaceutical biotech, creating recruitment competition for industrial bio-based chemical platforms.
- TSCA Section 5 Registration Timelines:New chemical notifications for novel microbial strains create uncertainty in product launch schedules despite EPA pathway streamlining efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bio Succinic Acid Market |
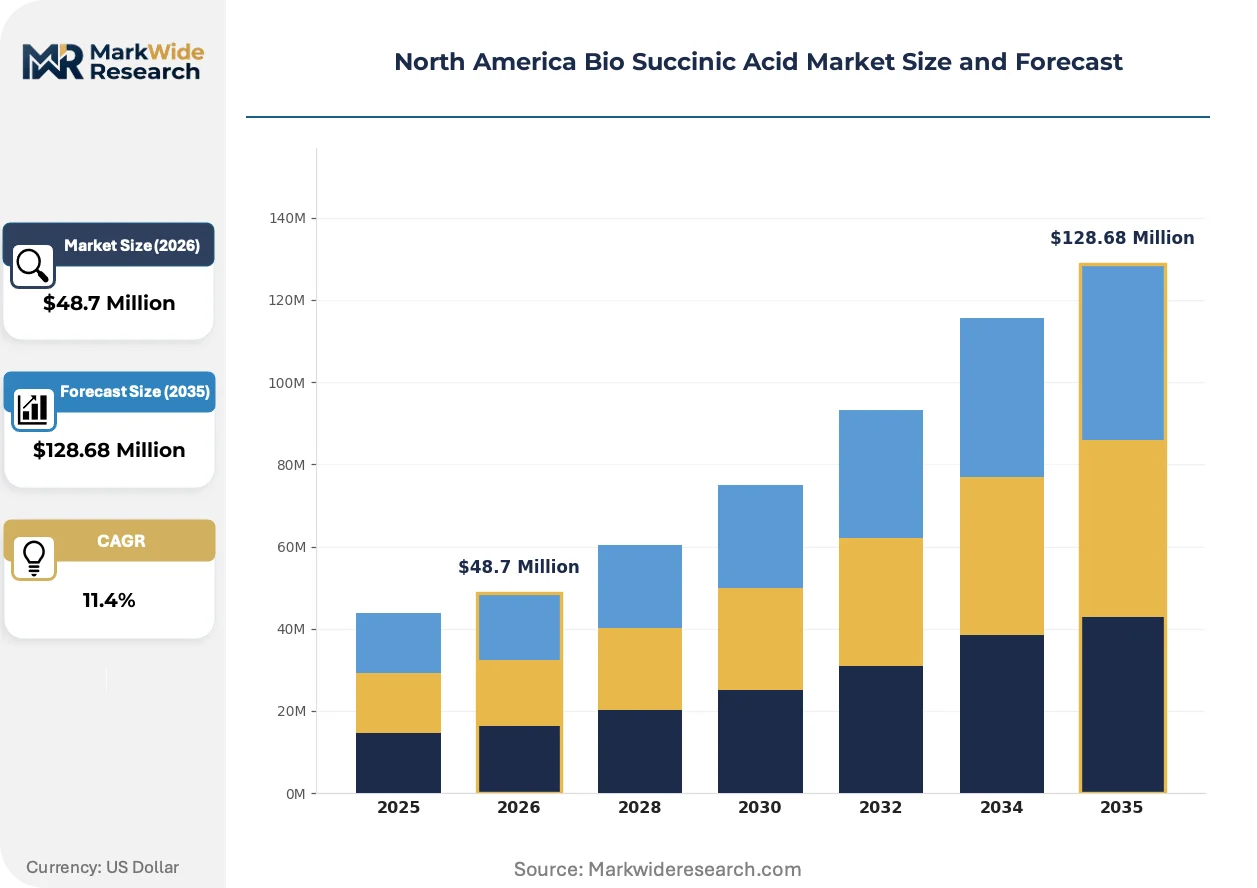
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade End User: Food & Beverage, Pharmaceuticals, Personal Care, Plastics Manufacturing Process: Chemical Synthesis, Biological Fermentation, Hybrid Processes, Others Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | BASF, Corbion, Archer-Daniels-Midland Company, Cargill, DSM North America, DuPont Industrial Biosciences, BioAmber, Myraint, Roquette Freres, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bio Succinic Acid Market Evolving Landscape
Fermentation technology architectures are diversifying as metabolic engineering capabilities mature and regulatory pathways clarify, creating new competitive entry points beyond incumbent petrochemical-adjacent players.
Continuous fermentation systems are fragmenting traditional batch process economics in bio-succinic acid production. Midwest bioprocessing facilities are piloting integrated cell retention and in-situ product recovery configurations that reduce downtime and improve titers. This technology is fragmenting the capital barrier that previously concentrated production among integrated petrochemical operators with existing infrastructure leverage.
The EPA's renewable chemical pathways under the Toxic Substances Control Act are compressing registration timelines for fermentation-derived platform chemicals. Industrial biotechnology developers now navigate pre-manufacture notification requirements with greater predictability, accelerating commercial deployment. Small and mid-scale producers in the Great Lakes corridor are responding most aggressively, filing multiple strain and process variations to build patent thickets.
Polymer manufacturers are consolidating supplier relationships around vertically integrated fermentation-to-polyol operations. Long-term offtake agreements with fixed biobased content specifications are displacing spot market purchasing for industrial grade material. This concentration is most visible in automotive seating and flexible foam applications where original equipment manufacturers enforce tier-one sustainability reporting obligations.
North America Bio Succinic Acid Market Segmentation
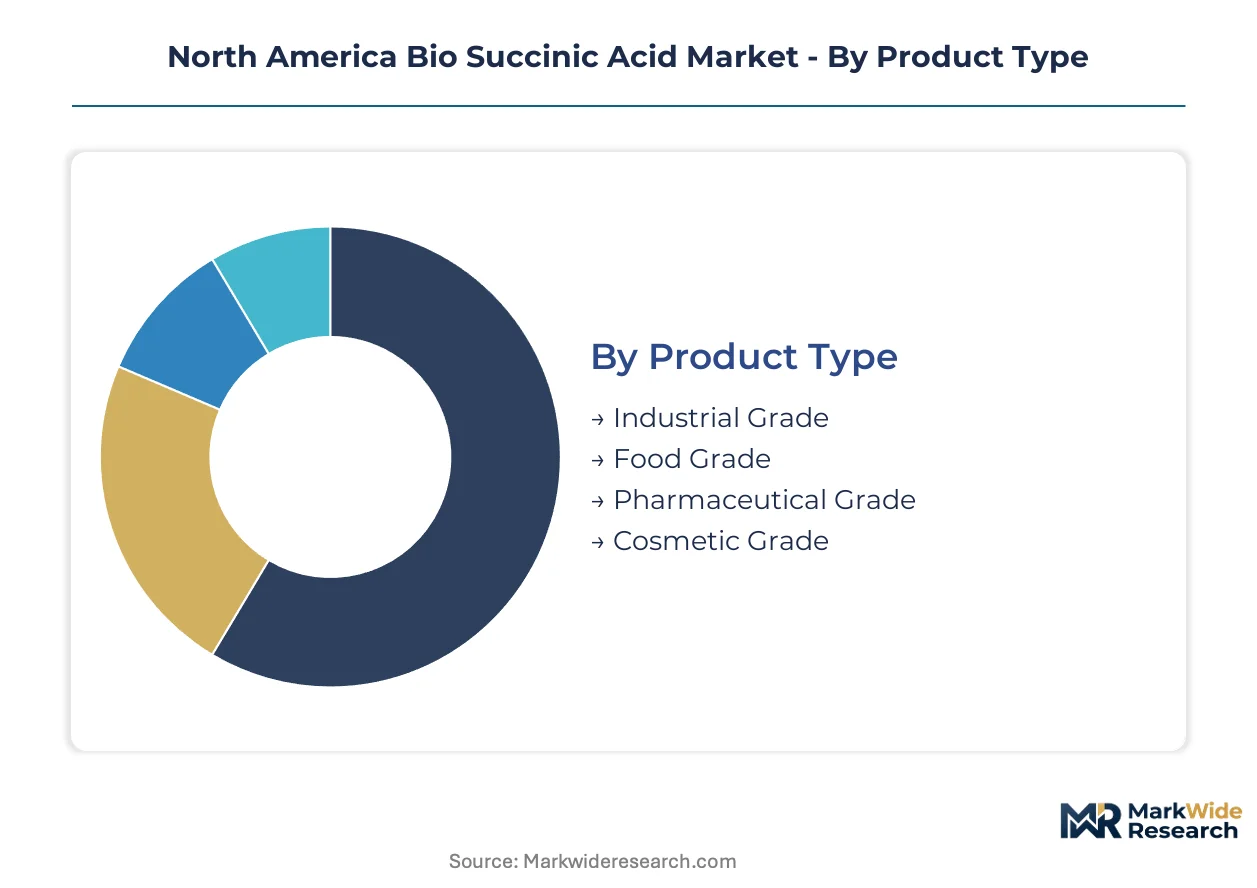
Segmentation in the North American bio succinic acid market reveals how purity specifications, end-use applications, and manufacturing economics create divergent margin structures. Each dimension exposes different vulnerability to petroleum-derived substitutes and shapes capital deployment priorities across the Great Lakes bioprocessing corridor.
Product Type:
Substitution pressure from petrochemical succinic acid concentrates most intensely in lower-purity segments where Gulf Coast refiners exploit scale advantages, while FCC and USP compliance create defensive moats for premium grades.
- Industrial Grade:Material with 99% minimum purity serves polyester polyol manufacturers and solvent formulators. Demand concentrates in automotive seating and flexible foam applications around Detroit and Chicago, where tier-one sustainability reporting obligations enforce biobased content minimums.
- Pharmaceutical Grade:USP-grade material meets stringent monograph requirements for active pharmaceutical ingredient synthesis. High-purity specifications limit qualified supplier participation, creating concentrated margin pools for producers with capital-intensive downstream processing capabilities.
- Food Grade:FCC-compliant material functions as acidulant and flavoring agent in food formulations. FDA GRAS pathway compliance governs market access.
- Cosmetic Grade:Refined material for pH adjustment and preservative systems in personal care formulations. Clean-label positioning drives specification adoption.
Industrial grade retains volume leadership; pharmaceutical grade holds the steepest expansion curve.
End User:
Cost tier differentiation separates commodity-driven volume buyers from specification-sensitive premium segments where purity premiums justify fermentation economics.
- Plastics:Polyurethane foam and coating producers across the United States and Canada specify bio-based feedstocks for sustainability compliance. Long-term offtake agreements with fixed biobased content minimums displace spot purchasing.
- Pharmaceuticals:API manufacturers require USP-grade material with documented chain-of-custody for regulatory submissions. Limited qualified supplier base sustains pricing power.
- Food & Beverage:Acidulant applications in processed foods drive steady demand for FCC-compliant material. USDA BioPreferred procurement preference supports domestic fermentation capacity.
- Personal Care:Formulators leverage bio-succinic acid for clean-label positioning in skincare and haircare products. Premium positioning tolerates higher unit costs.
Plastics commands volume concentration; pharmaceuticals generates the highest unit margins.
Manufacturing Process:
Volume concentration favors biological fermentation as EPA pathway streamlining accelerates commercial deployment, though hybrid processes retain relevance for cost-sensitive industrial applications.
- Biological Fermentation:Microbial conversion of corn-derived glucose or lignocellulosic biomass dominates new capacity investment. Midwest bioprocessing facilities pilot continuous fermentation with integrated cell retention and in-situ product recovery.
- Chemical Synthesis:Traditional petrochemical routes from maleic anhydride maintain cost advantages through integrated refinery economics. Gulf Coast producers exploit scale positions.
- Hybrid Processes:Combined biological and chemical steps optimize yield for specific industrial applications. Process flexibility addresses feedstock price volatility.
- Others:Emerging electrochemical and enzymatic approaches remain pre-commercial. Technology risk limits near-term deployment.
Biological fermentation captures investment preference; hybrid processes defend niche cost-sensitive positions.
Distribution Channel:
Customer type segmentation separates integrated polymer manufacturers seeking direct supply relationships from fragmented buyers dependent on intermediaries.
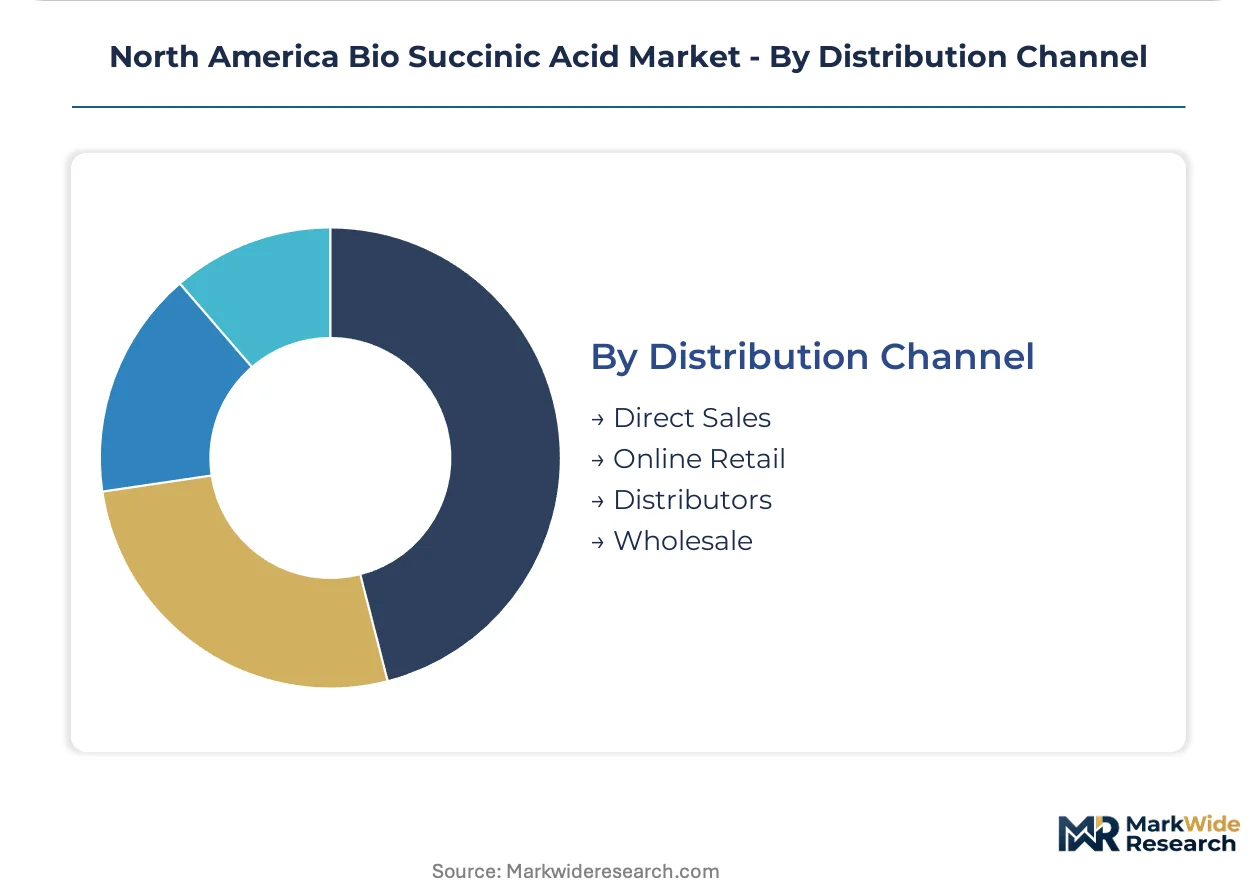
- Direct Sales:Vertically integrated fermentation-to-polyol operations consolidate supplier relationships through long-term contracts. Automotive and construction sector procurement teams enforce sustainability specifications.
- Distributors:Regional chemical distributors serve mid-scale processors lacking volume for direct negotiations. Inventory positioning in Chicago and Sarnia reduces lead times.
- Wholesale:Bulk volume transactions serve commodity industrial applications with standardized specifications. Price transparency pressures margins.
- Online Retail:Small-lot sales for R&D and specialty formulation work. Limited relevance for industrial-scale demand.
Direct sales anchors volume flows; distributors retain relevance for geographic and customer fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA pathway streamlining under TSCA Section 5 anchors United States dominance, while Health Canada and PMRA frameworks govern Canadian bioprocessing compliance. Cross-border supply chains concentrate around the Great Lakes industrial corridor.
United States
Polyester polyol manufacturers in Michigan and Illinois drive procurement volume for automotive seating applications. USDA BioPreferred program mandates federal biobased content minimums for designated product categories. Detroit-Chicago chemical processing corridor hosts integrated fermentation-to-polyol operations with shared utility infrastructure.
Canada
Polyurethane foam producers in Ontario specify bio-succinic acid for tier-one automotive supplier sustainability reporting. Health Canada and PMRA regulate novel microbial strain introductions under the Canadian Environmental Protection Act. Sarnia petrochemical complex enables co-location of fermentation capacity with existing polymer intermediates infrastructure.
Mexico
Automotive OEM assembly expansion in Nuevo León and Bajío Region creates downstream demand for bio-based polyurethane components. Mexican environmental regulator SEMARNAT implements bioprocessing facility permitting aligned with USMCA technical barriers chapters. Querétaro industrial corridor attracts supplier co-location for just-in-time resin delivery.
North America Bio Succinic Acid Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated petrochemical conglomerates leverage existing infrastructure for fermentation co-location, while specialized biotech developers advance metabolic engineering capabilities. Three archetypes dominate: diversified chemical majors with backward integration into fermentation, dedicated industrial biotechnology platforms, and agricultural processors with captive glucose supply. Capacity expansion and strategic partnerships constitute the primary competitive moves, with state tax credit arbitrage reshaping geographic positioning.
Within the diversified chemical major tier, BASF and DSM North America exemplify infrastructure-leveraged positioning. Archer-Daniels-Midland Company represents the agricultural processor archetype with integrated feedstock advantages. Corbion occupies a specialized biotechnology position focused on high-purity fermentation-derived building blocks.
| Leading Market Players |
|---|
| BASF |
| Corbion |
| Archer-Daniels-Midland Company |
| Cargill |
| DSM North America |
| DuPont Industrial Biosciences |
| BioAmber |
| Myraint |
| Roquette Freres |
| Others |
Value Network & Pricing Analysis
FCC monograph compliance gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where pharmaceutical-grade material commands substantial premiums over industrial-grade alternatives. USDA BioPreferred procurement mandates anchor volume demand for certified biobased content, while state-level renewable chemical tax credits in Illinois, Minnesota, and Iowa reshape geographic cost competitiveness across the Midwest bioprocessing belt.
Pricing Analysis
Great Lakes corridor producers maintain pricing premiums over Gulf Coast petrochemical alternatives due to proximity advantages for automotive and construction sector buyers. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects purity-driven cost structures, with USP-grade material sustaining the widest margins. Cost compression in industrial-grade segments intensifies as maleic anhydride-derived succinic acid exploits refinery scale economics. Small-scale polyurethane foam manufacturers exhibit highest price sensitivity, while API manufacturers demonstrate lowest sensitivity due to regulatory submission requirements.
Supply Chain Analysis
Inbound logistics costs from Midwest agricultural zones to Great Lakes fermentation facilities fluctuate with rail container availability and Chicago hub congestion. Supply concentrates in the United States and Canada, with Mexico emerging as a downstream assembly location for bio-based polyurethane components. Corn-derived glucose, lignocellulosic biomass, and specialized microbial strains constitute critical input dependencies. Single-source vulnerability around engineered yeast strains licensed from biotechnology developers threatens operational continuity. Distribution runs through direct long-term offtake agreements with tier-one automotive suppliers, supplemented by regional chemical distributors serving mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in bio-succinic acid hinge on fermentation-to-polyol vertical integration, with interoperability standards across automotive OEM sustainability reporting systems creating winner-take-most dynamics for qualified suppliers.
For Market Incumbents: Fortify defensive moats through captive microbial strain development programs and FCC-certified downstream processing capacity expansion in Michigan and Illinois. Petroleum-derived succinic acid cost advantages from Gulf Coast refiners threaten industrial-grade margins, necessitating backward integration into lignocellulosic feedstock preprocessing to decouple from corn glucose price volatility.
For New Entrants and Emerging Players: Anchor in pharmaceutical-grade production where USP compliance barriers limit qualified competition and sustain premium pricing. The personal care and cosmetic segments offer penetrable white-space with clean-label positioning tolerance for higher unit costs. Pursue toll manufacturing arrangements with existing Great Lakes fermentation assets to bypass capital-intensive facility construction.
For Investors and Strategic Acquirers: EPA's streamlined TSCA Section 5 registration pathways reshape the acquisition landscape by reducing regulatory uncertainty for novel strain portfolios. Five-to-ten year viability favors platforms with demonstrated metabolic engineering capabilities and established automotive OEM relationships. Monitor state renewable chemical tax credit expiration schedules as inflection indicators for geographic cost competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignocellulosic Feedstock | Corn stover and wheat straw preprocessing reduces glucose cost exposure and satisfies automotive OEM circularity requirements. |
| Continuous Fermentation Technology Deployment | Integrated cell retention systems at Midwest facilities fragment capital barriers that previously favored petrochemical incumbents. |
| USP-Grade Downstream Processing Investment | Pharmaceutical-grade purification capacity captures concentrated margin pools with limited qualified supplier competition. |
| Long-Term Offtake Agreement Structuring | Fixed biobased content contracts with Detroit and Chicago automotive seating manufacturers displace spot market volatility. |
| State Tax Credit Arbitrage Positioning | Illinois, Minnesota, and Iowa incentive competition enables facility siting optimization for production cost minimization. |
Research Methodology
A spread of perspectives from fermentation technologists, polyester polyol procurement leads, EPA regulatory affairs specialists, and automotive tier-one sustainability officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA BioPreferred program databases, EPA TSCA Section 5 filing records, customs trade data, and SEC disclosures from diversified chemical majors. Bottom-up capacity assessments across Great Lakes bioprocessing facilities were triangulated against top-down demand modeling from automotive and construction end-use sectors.
Segmentation dimensions modeled include product purity grade, end-use industry application, manufacturing process architecture, and distribution channel configuration across the analysis window. CAGRs were derived from trend extrapolation of fermentation capacity expansion announcements, state incentive program allocations, and automotive OEM sustainability reporting adoption curves. Forecast inputs incorporated corn glucose futures price trajectories, EPA registration timeline distributions, and polymer manufacturer biobased content specification diffusion rates.
Material uncertainties — feedstock price volatility, regulatory pathway delays for novel microbial strains, and petroleum-derived succinic acid cost competitiveness shifts — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market