
 US Biochar Market | 2026-2036
US Biochar Market Size, Share, and Industry Trends Forecast 2026-2036
US Biochar Market Intelligence
The substitution of traditional soil amendments like peat moss with biochar is consolidating its role in sustainable agriculture due to superior water retention and carbon sequestration properties. Aries Clean Technologies leverages its patented gasification systems to convert various waste streams into high-grade biochar. Pacific Biochar Benefit Corporation specializes in producing material from forestry biomass for the West Coast agricultural sector. Biochar Now LLC operates one of the largest US production facilities, anchoring a significant portion of domestic supply.
Biochar is a stable, carbon-rich solid created through the pyrolysis of organic biomass in a low-oxygen environment. Its highly porous physical structure allows it to retain water and nutrients, making it a valuable material for enhancing soil health and sequestering atmospheric carbon. Soil amendment represents the principal application, driving volume across the US market. Among production technologies, pyrolysis remains the most established and widely used method, though gasification is gaining ground for its energy co-generation capabilities.
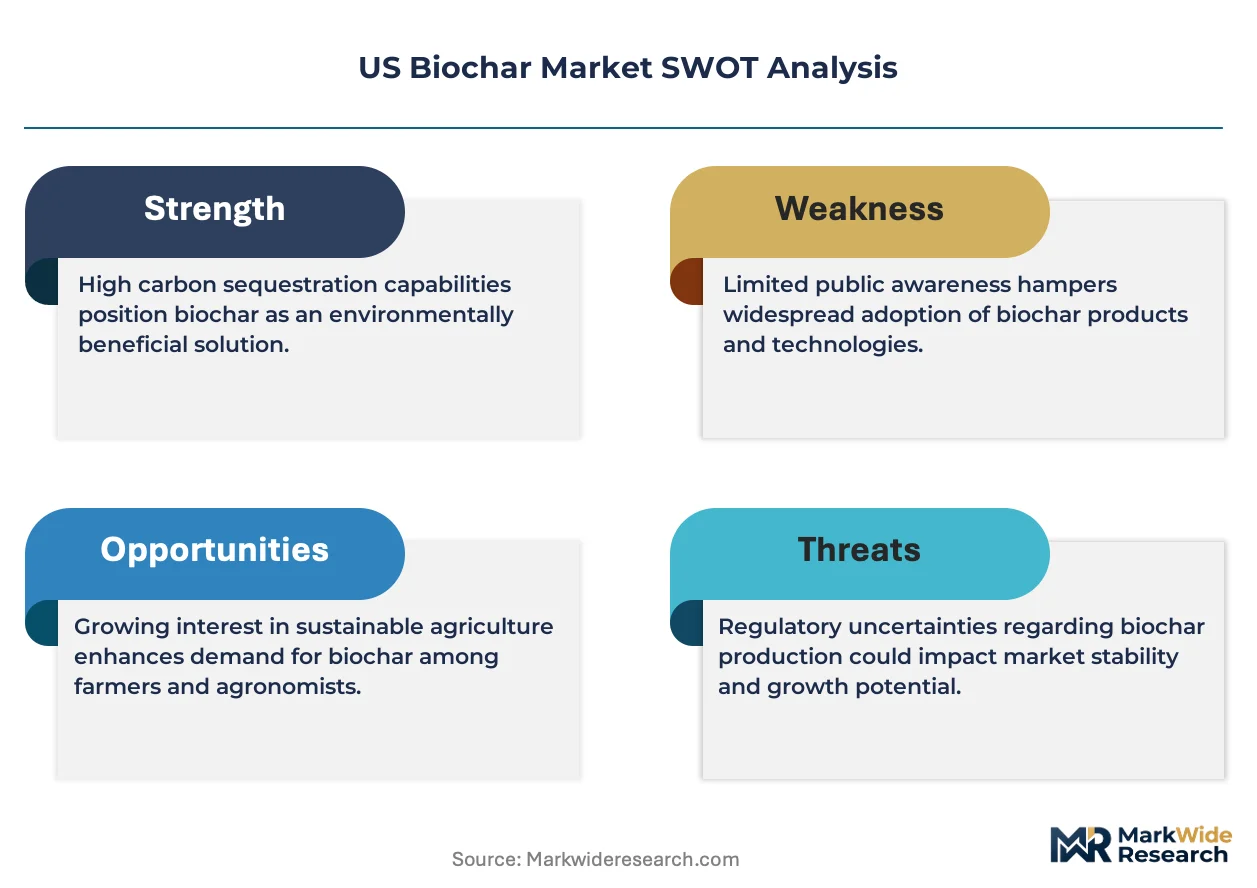
The US Environmental Protection Agency (EPA) oversees regulations related to biomass conversion and waste management, influencing feedstock availability. The US Department of Agriculture (USDA) promotes biochar's use through various soil health and conservation programs. State-level initiatives, particularly in California and Oregon, provide further incentives for its application in agriculture and environmental remediation. Future success for producers depends on their ability to scale production efficiently while navigating the evolving standards for carbon credit verification.
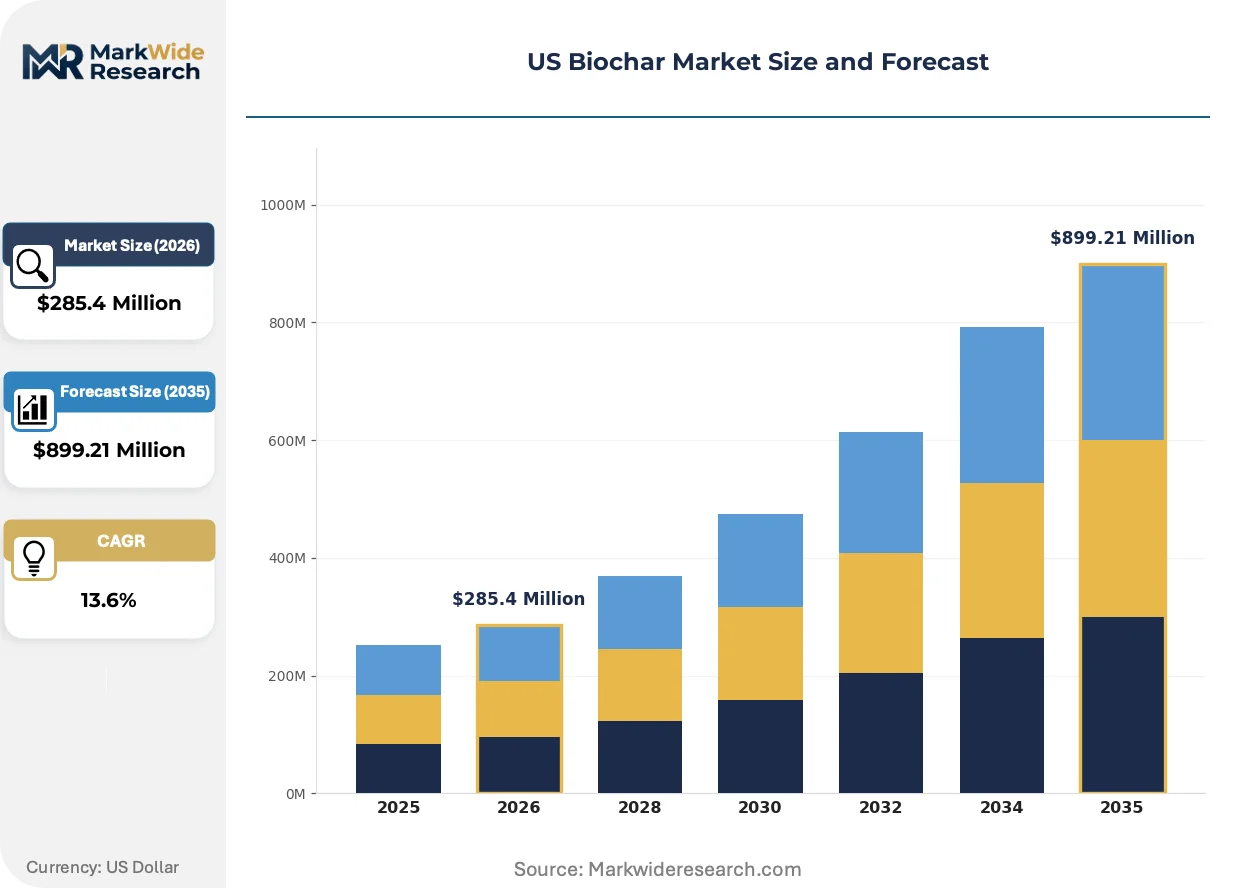
Market Dynamics
The convergence of federal climate policy, specifically the Inflation Reduction Act, and state-level agricultural water conservation mandates is the central force structuring the US biochar market. This creates dual value streams from both soil amendment product sales and carbon sequestration credits.
Growth Catalysts
- Federal Tax Incentives:The Inflation Reduction Act (IRA) provides significant tax credits for carbon capture and sequestration, directly benefiting producers who can verify the carbon permanence of their biochar, making production more economically viable.
- Agricultural Water Scarcity:In states like California, extreme drought conditions and water use restrictions are pushing agricultural producers to adopt biochar for its proven water retention capabilities, reducing irrigation needs. t
- Material Substitution:Biochar's superior performance in carbon stability and nutrient holding capacity is driving its substitution for less sustainable traditional amendments like peat moss in horticulture and specialty crop applications.
Market Restraints
- Production Cost Structure:The high capital expenditure required for industrial-scale pyrolysis and gasification systems presents a significant barrier to entry, making biochar's upfront cost higher than many conventional soil amendments.
- Feedstock Logistics:The economic viability of biochar production is constrained by the cost of transporting bulky, low-density biomass from source to a centralized processing facility, limiting the feasible radius of operations.
- Standardization Gaps:A lack of universally accepted quality standards and characterization protocols for biochar leads to product inconsistency, creating uncertainty for large-scale agricultural buyers regarding performance and application rates.
Strategic Opportunities
- Environmental Remediation:Biochar's porous structure and adsorptive properties create opportunities for its use in new applications, such as filtering contaminants from stormwater runoff or remediating polluted industrial sites.
- Energy Co-Generation:Advanced gasification systems that co-produce biochar and a renewable synthesis gas (syngas) allow producers to generate electricity or thermal energy, creating an additional revenue stream and improving overall plant economics.
- Midwest Market Penetration:Expanding beyond the established West Coast markets into the vast agricultural regions of the Midwest offers a significant opportunity to increase volume sales for application in large-scale corn and soybean farming systems.
Industry Challenges
- Carbon Credit Verification:Producers face the operational challenge of navigating complex, costly, and evolving methodologies for measuring, reporting, and verifying the carbon sequestration value of their biochar to qualify for high-quality carbon credits.
- Scaling Production Efficiently:A primary challenge is scaling production from small, localized operations to large, continuous-output facilities that can meet the volume and consistency demands of major agricultural distributors and consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biochar Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $899.21 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Biochar, Hardwood Biochar, Softwood Biochar, Nut Shell Biochar, Agricultural Residue Biochar Application: Soil Amendment, Water Filtration, Livestock Farming, Waste Management, Carbon Sequestration Production Technology: Pyrolysis, Gasification, Hydrothermal Carbonization, Torrefaction, Slow Carbonization End User Industry: Agriculture, Aquaculture, Waste Treatment Services, Environmental Management, Landscaping |
| Companies Covered | Airex Energy Inc., Black Owl Biochar, Aries Clean Technologies, Pacific Biochar Benefit Corporation, Biochar Now LLC, Biochar Supreme LLC, Avello Bioenergy, Oregon Biochar Solutions, CharGrow USA LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biochar Market Strategic Shifts & Innovations
The US biochar market is evolving from a niche soil amendment to a recognized tool for industrial-scale carbon management and sustainable agriculture. This transition is defined by technological decentralization, policy integration, and a demand-side flight to quality and verification.
Mobile pyrolysis units allow for the on-site conversion of biomass waste into biochar. Agricultural cooperatives and forestry management firms are early adopters of this technology to process residues directly in the field. This innovation is decentralizing production away from large, centralized plants, reducing feedstock transportation costs and creating localized supply for rural end-users.
The Inflation Reduction Act (IRA) provides a durable financial backbone for the industry through its Section 45Q tax credits for carbon oxide sequestration. This policy directly monetizes the climate benefit of biochar, altering the core business model for producers. Agricultural operations in states with strong environmental programs are most affected, re-evaluating biochar's ROI based on both soil health and carbon revenue.
A preference shift among buyers toward certified biochar is creating a distinct market tier. This demand for material with verified carbon sequestration and specific physical properties is disrupting the undifferentiated bulk commodity channel. This pattern is most visible within California's specialty crop sector, where corporate sustainability reporting and water stewardship goals drive procurement decisions.
US Biochar Market Segmentation
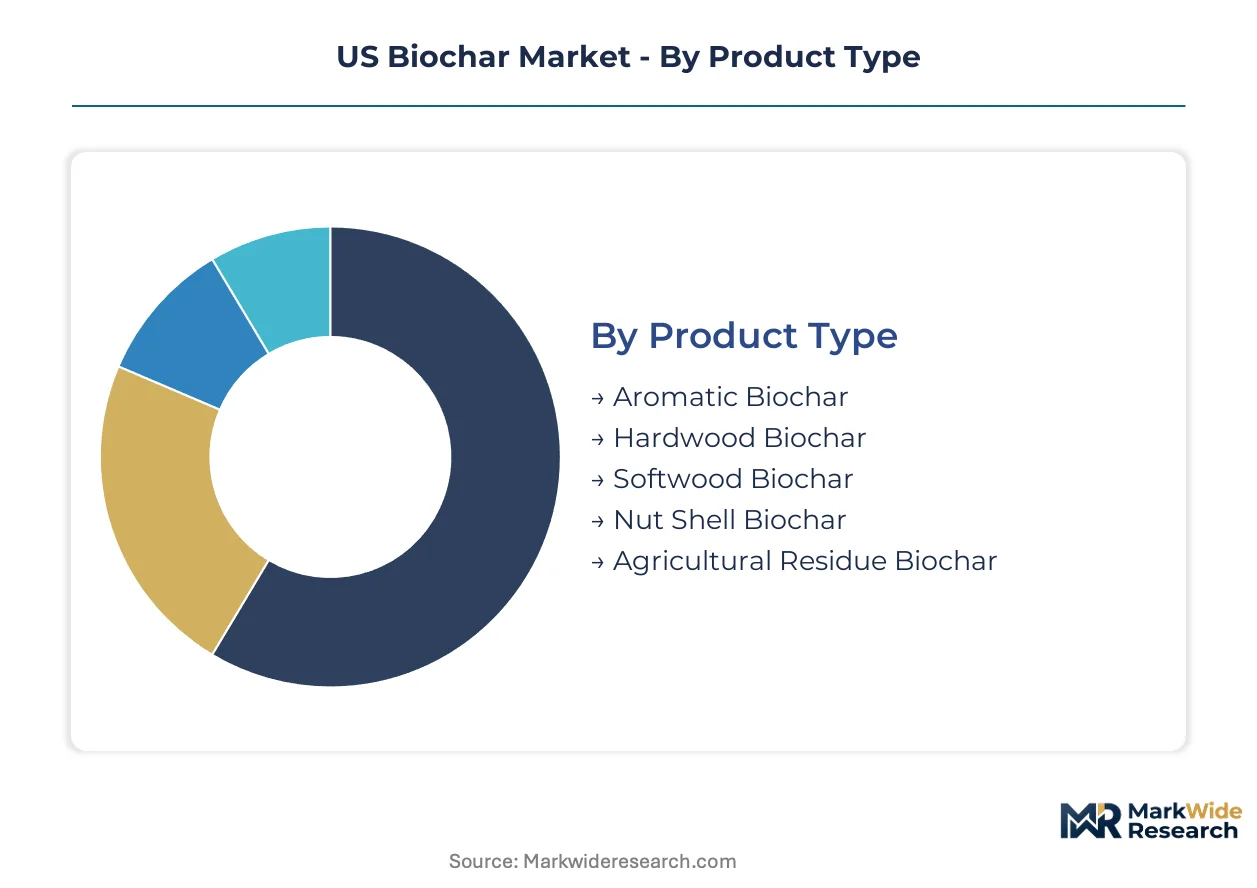
The US biochar market exhibits diverse characteristics across its product forms, applications, production methods, and end-user industries. Understanding these segments provides clarity on demand drivers and technological preferences shaping the domestic landscape. Each segment contributes uniquely to the market's overall value and growth trajectory.
Product Type:
Product type segmentation in the US biochar market distinguishes material based on its biomass origin and processing characteristics.
- Aromatic Biochar:This category encompasses biochar derived from feedstocks rich in lignin and cellulose, often exhibiting higher carbon stability and surface area. Demand concentrates in specialized agricultural applications across California, where its long-term soil enhancement properties are valued for high-value crops.
- Hardwood Biochar:Produced from dense wood sources like oak or maple, hardwood biochar offers a robust, stable structure ideal for long-term soil amendment. Agricultural producers in the Midwest prioritize this type for its nutrient retention capabilities in large-scale farming systems.
- Softwood Biochar:Biochar derived from coniferous trees or other soft woods often features a lower density and varied pore structure.
- Nut Shell Biochar:This biochar type utilizes agricultural waste streams like pecan or walnut shells as feedstock, contributing to circular economy principles.
- Agricultural Residue Biochar:Biochar created from crop residues such as corn stover or rice hulls offers a sustainable waste management solution for farmers.
Aromatic Biochar leads on scale; Hardwood Biochar leads on momentum.
Application:
Application segments reflect the primary functional use cases for biochar across various economic sectors.
- Soil Amendment:Biochar's primary application involves its incorporation into agricultural soils to improve fertility, water retention, and microbial activity. Demand is strongest in states with water scarcity issues, such as California, where it directly addresses irrigation efficiency concerns.
- Carbon Sequestration:This application leverages biochar's stable carbon content to remove atmospheric carbon dioxide and store it long-term in soils. Federal incentives under the Inflation Reduction Act significantly enhance the economic viability of biochar projects focused on carbon removal.
- Water Filtration:Biochar's porous structure makes it effective at adsorbing contaminants, positioning it as a filtration medium for stormwater runoff and industrial wastewater.
- Livestock Farming:Biochar can be incorporated into animal feed or bedding, improving animal health and reducing emissions from manure management.
- Waste Management:Biochar production converts organic waste into a valuable product, reducing landfill volume and methane emissions.
Soil Amendment represents the largest volume segment, while Carbon Sequestration is expanding most quickly.
Production Technology:
Production technology segments highlight the various thermal conversion processes used to create biochar from biomass feedstocks.
- Pyrolysis:This established method involves heating biomass in the absence of oxygen to produce biochar, syngas, and bio-oil. Pyrolysis systems remain the most common technology for commercial biochar production across the US.
- Gasification:Gasification systems convert biomass into syngas and biochar through partial oxidation, often allowing for energy co-generation. This technology is gaining traction for its efficiency and dual revenue streams in the US market.
- Hydrothermal Carbonization:This process uses water under high pressure and moderate temperatures to convert wet biomass into a char-like material.
- Torrefaction:Torrefaction is a mild pyrolysis process that produces a charcoal-like product with improved grindability and hydrophobicity.
- Slow Carbonization:This traditional method involves slow, controlled burning of biomass, often in kilns, yielding biochar with specific properties.
Pyrolysis holds the dominant market share, and Gasification shows the steepest expansion trajectory.
End User Industry:
End user industry segmentation categorizes biochar consumption based on the primary sector applying the material for its specific benefits.
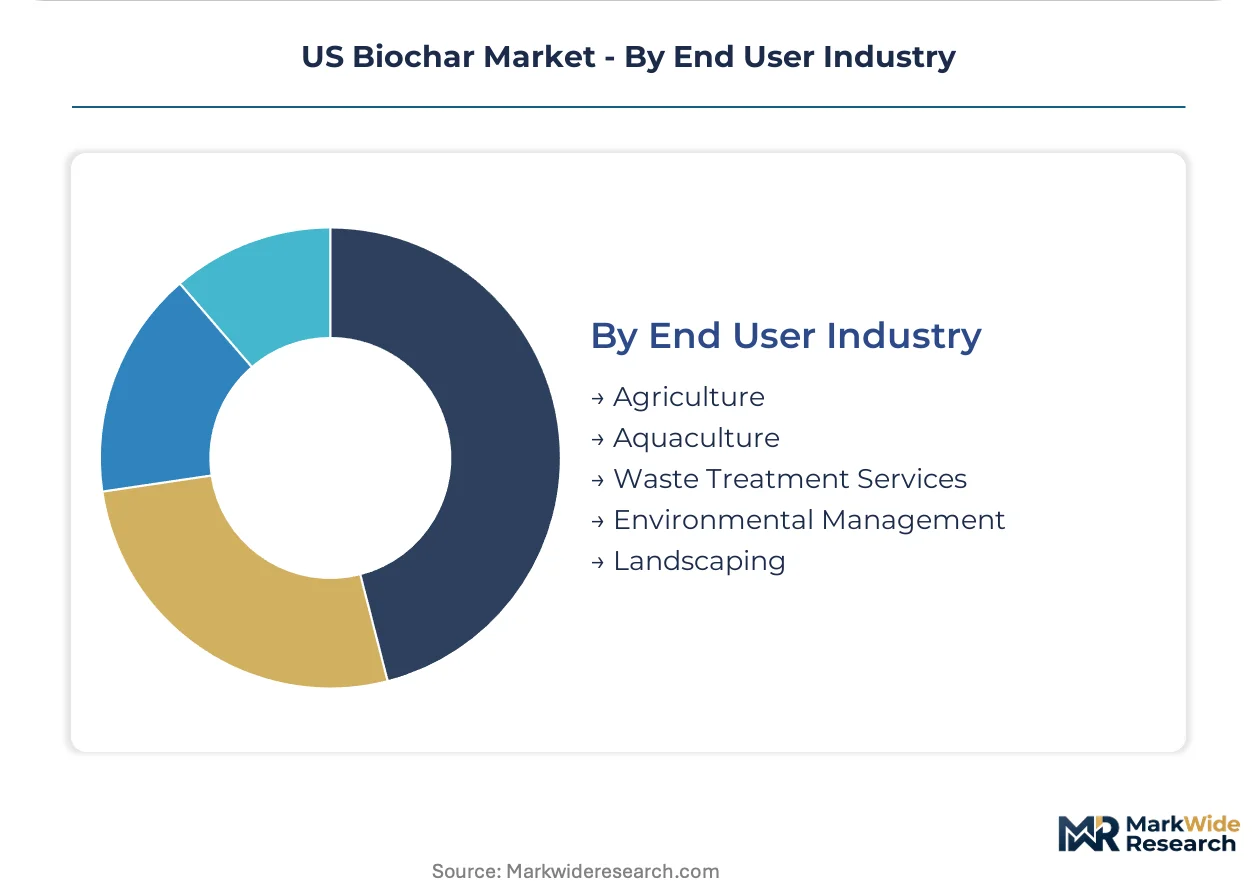
- Agriculture:The agricultural sector is the primary consumer of biochar, utilizing it for soil enhancement, crop yield improvement, and water conservation. Large-scale farming operations in states like Iowa and Nebraska are increasingly exploring biochar applications.
- Environmental Management:This sector uses biochar for applications such as land remediation, stormwater treatment, and carbon removal projects. US EPA regulations and state-level environmental initiatives drive demand in this segment.
- Aquaculture:Biochar finds applications in aquaculture for water purification and improving the health of aquatic environments.
- Waste Treatment Services:Companies involved in waste management and resource recovery use biochar for its ability to stabilize waste and capture pollutants.
- Landscaping:Professional landscapers and nurseries incorporate biochar into growing media to enhance plant vitality and reduce water requirements.
Agriculture commands the largest share of biochar consumption, and Environmental Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's agricultural sector anchors demand for biochar in the US market, driven by critical water conservation needs. The state's environmental programs and specialty crop cultivation prioritize sustainable soil amendments. Federal incentives from the Inflation Reduction Act further boost biochar's economic viability across the region.
California
California's extensive agricultural operations require biochar for superior water retention, particularly in high-value specialty crops. State-level initiatives and water conservation mandates encourage biochar adoption, complementing federal IRA tax credits for carbon sequestration. The Central Valley, a major agricultural hub, sees significant biochar procurement driven by corporate sustainability goals.
Midwest
Agricultural regions in the Midwest leverage biochar for enhancing soil fertility and nutrient retention in large-scale corn and soybean systems. The US Department of Agriculture promotes biochar use through various soil health and conservation programs, aligning with regional farming practices. States like Iowa and Nebraska represent significant volume opportunities for biochar application in their vast agricultural lands.
Pacific Northwest
Oregon and other Pacific Northwest states utilize biochar for sustainable forestry management and environmental remediation projects. State-level incentives in Oregon support biochar application, particularly for converting forestry biomass into valuable soil amendments. The region's focus on natural resource conservation drives demand for biochar in both agricultural and ecological restoration efforts.
Texas
Texas faces significant water management challenges, driving interest in biochar for agricultural water retention and land remediation. The state's expansive agricultural sector and industrial footprint create opportunities for biochar applications and energy co-generation. Large ranches and developing industrial zones across Texas explore biochar for both soil improvement and waste valorization.
US Biochar Market Key Industry Players
Global majors compete with regional champions across production scale and technological specialization in the US biochar market. The market exhibits a tiered structure, with established players focusing on large-scale production alongside numerous specialized regional producers. Strategic archetypes include technology innovators, feedstock-integrated producers, and application-focused suppliers. Companies are primarily engaged in capacity expansion and forming strategic partnerships to secure feedstock supply chains.
Specialists in advanced thermal conversion technologies include Aries Clean Technologies, which leverages patented gasification systems for diverse waste streams. Pacific Biochar Benefit Corporation exemplifies a regional producer, focusing on forestry biomass for the West Coast agricultural sector. Biochar Now LLC anchors a significant portion of domestic supply, occupying a position as one of the largest US production facilities for biochar. These entities represent different approaches to feedstock sourcing, processing technology, and market penetration within the evolving US biochar landscape. Their operations highlight the varied strategies employed to meet demand from agricultural and environmental end-users.
| Leading Market Players |
|---|
| Airex Energy Inc. |
| Black Owl Biochar |
| Aries Clean Technologies |
| Pacific Biochar Benefit Corporation |
| Biochar Now LLC |
| Biochar Supreme LLC |
| Avello Bioenergy |
| Oregon Biochar Solutions |
| CharGrow USA LLC |
| Others |
Cost & Logistics Intelligence
The Inflation Reduction Act (IRA) provides a durable financial backbone for the US biochar market, gating access to qualified carbon credit supply and enabling premium-tier pricing for verified material. This policy directly monetizes the climate benefit of biochar, altering the core business model for producers.
Pricing Analysis
High capital expenditure for industrial-scale pyrolysis and gasification systems directly impacts the cost structure, with producers passing through significant input costs to buyers. The dominant pricing model for large-volume transactions is contract-based long-term offtake agreements. Price differentiation stems from the biochar's quality grade, specifically its certified carbon permanence, and the geographic delivery cost to end-users. Pricing softness emerges from the lack of universally accepted quality standards, creating uncertainty for large-scale agricultural buyers. Agricultural producers in the Midwest represent the most price-sensitive segment, while specialty crop growers in California often prioritize certified biochar for its superior performance.
Supply Chain Analysis
Single-source vulnerability sits with feedstock availability for specific biochar types, particularly high-density woody biomass in certain regions. The US biochar supply chain depends on organic biomass, including forestry residues and agricultural waste streams like corn stover. Feedstock logistics present a significant structural risk due to the cost of transporting bulky, low-density materials from source to processing facilities. Geographic supply concentration exists in regions like California, the Pacific Northwest, and the Midwest, driven by both biomass availability and agricultural demand. Distribution runs through direct sales from producers to large agricultural operations and through regional distributors for smaller-scale agricultural and horticultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US biochar market is a late-cycle quality story, with a demand-side flight toward certified biochar material with verified carbon sequestration properties. This shift is disrupting the undifferentiated bulk commodity channel.
For Market Incumbents: Anticipate continued pressure for carbon credit verification by investing in robust measurement, reporting, and verification (MRV) systems. Consolidate market share by expanding production capacity in high-demand agricultural regions like the Midwest. Form strategic partnerships with forestry management firms and agricultural cooperatives to secure consistent, high-quality feedstock supply. This approach mitigates the threat of feedstock logistics constraints and product inconsistency.
For New Entrants and Emerging Players: Mobile pyrolysis units offer a technology-first wedge into the US biochar market, enabling on-site conversion of biomass waste. Target underpenetrated agricultural regions in the Midwest with localized supply solutions for large-scale corn and soybean farming systems. A compelling go-to-market angle involves showcasing the direct economic benefits of reduced irrigation needs and enhanced soil fertility for specific crop types. Niche environmental remediation projects also present accessible entry points.
For Investors and Strategic Acquirers: Roll-up economics work for regional biochar producers because the market exhibits structural fragmentation and strong local feedstock dependencies. Long-term viability for the US biochar market is anchored by federal climate policy, particularly the Inflation Reduction Act, and state-level agricultural water conservation mandates. Identify acquisition targets that possess patented gasification systems or established feedstock-integrated operations, like Aries Clean Technologies or Pacific Biochar Benefit Corporation. The signal to watch is the maturation of carbon credit verification methodologies and the widespread adoption of certified biochar standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production efficiently addresses the growing volume demands from major agricultural distributors and consumers. |
| Feedstock Partnership | Securing reliable biomass sources mitigates supply chain risks and ensures consistent product quality for biochar producers. |
| Certification Investment | Robust carbon credit verification systems enable producers to monetize the climate benefit of biochar, enhancing revenue streams. |
| Mobile Unit Deployment | Decentralized production using mobile pyrolysis units reduces feedstock transportation costs for rural end-users. |
| R&D for Remediation | Developing new biochar applications for environmental remediation expands market opportunities beyond traditional soil amendments. |
Research Approach
Coverage spans key US regions, including California, the Midwest, Pacific Northwest, and Texas, with primary inputs from each. The analysis combines in-depth primary interviews with industry stakeholders such as agricultural producers, biochar technology providers, environmental consultants, and USDA program managers. Secondary validation draws from US EPA reports, USDA publications, academic journals, and company financial statements. This approach ensures bottom-up and top-down triangulation for comprehensive market insights.
The market analysis modeled granularity across product type, application, production technology, end-user industry, and US state-level adoption patterns. The analytical framework derived compound annual growth rates from historical data, market drivers, and expert projections across the analysis window. Key forecast inputs included feedstock availability, carbon credit pricing, and the uptake of federal incentives like the Inflation Reduction Act.
The model holds under current regulatory frameworks and anticipated technological advancements; deviation in federal climate policy or unexpected feedstock supply disruptions would shift outcomes. Forecasts reflect a synthesis of qualitative and quantitative inputs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Global Biofungicides Market