
 Poultry Manure Biofertilizers Market | 2026-2036
Poultry Manure Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Manure Biofertilizers Market Intelligence
Modular packaging configurations for liquid poultry manure biofertilizers is rebalancing buyer choice toward subscription-based refill systems rather than one-time bulk purchases. Lallemand Inc. leverages its microbial inoculant expertise to strengthen product efficacy claims across North American row-crop segments. National Fertilizers Limited anchors its position through government-mandated distribution networks reaching smallholder farmers. Olmix Group differentiates via integrated algae-bacteria biorefinery technology that enriches standard poultry manure substrates.
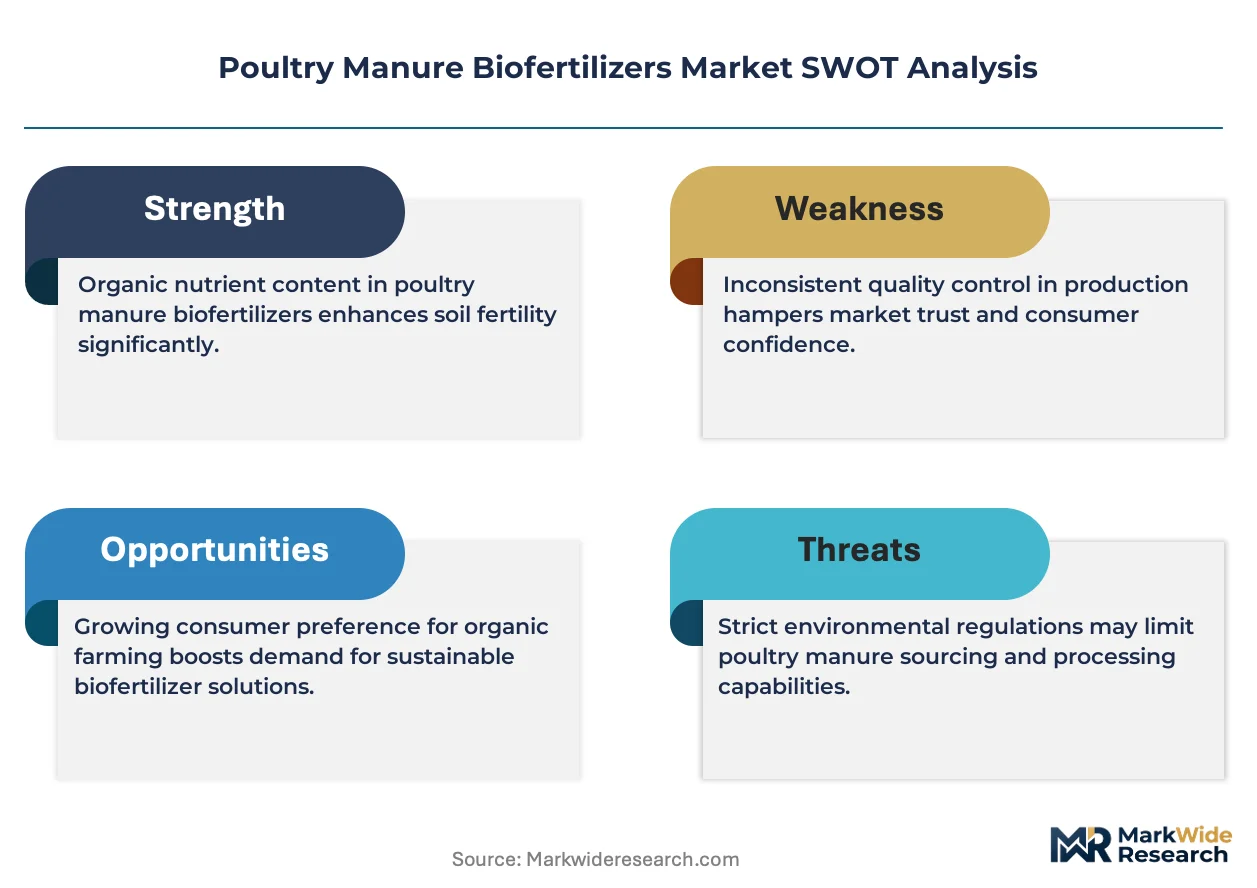
Poultry manure biofertilizers comprise processed excreta from layer and broiler operations, typically composted or anaerobically digested to stabilize nitrogen content between one and four percent by dry weight while eliminating Salmonella and E. coli pathogens through thermophilic phases exceeding fifty-five degrees Celsius. These products restore soil organic carbon and replace synthetic nitrogen-phosphorus-potassium formulations in commercial agriculture. Pellet formulations currently dominate volume due to mechanical spreading compatibility with existing farm equipment, while liquid variants represent the fastest-expanding configuration because of fertigation integration in precision agriculture systems. Organic farming applications command premium positioning through OMRI and national organic program certifications that constrain supplier pools and protect margin structures.
The EU F-Gas Regulation and REACH frameworks govern ammonia emissions and contaminant thresholds in imported organic amendments, compelling exporters to document full supply chain composting protocols. India's FSSAI and BIS standards for heavy metal limits in organic fertilizers shape product acceptance at state agricultural depots. The US EPA and USDA NRCS conservation programs partially offset farmer adoption costs through environmental quality incentives. Stakeholders must monitor evolving carbon credit methodologies for soil carbon sequestration claims, as verification protocols will determine which processing technologies qualify for offset revenue streams.
Market Dynamics
EU Green Deal mandates on synthetic fertilizer reduction are compressing farmer choice toward certified organic amendments, forcing processors to document full composting thermodynamics for cross-border shipments.
Growth Catalysts
- Anaerobic digestion technology:Thermophilic processing above fifty-five degrees Celsius stabilizes nitrogen at one-to-four percent dry weight while eliminating Salmonella and E. coli pathogens, satisfying FSSAI and BIS standards for heavy metal thresholds in finished products.
- India's PLI scheme for organic fertilizers:Production-linked incentives redirect state agricultural depot procurement toward bio-based soil amendments, concentrating demand acceleration in Gujarat, Punjab, and Haryana smallholder networks.
- Precision agriculture fertigation systems:Liquid poultry manure biofertilizer variants integrate with drip irrigation infrastructure, displacing pellet spreading in protected cultivation operations across Spain, Italy, and the Netherlands.
Market Restraints
- Feedstock supply concentration:Layer and broiler operation density clusters in specific agricultural zones, creating transport radius constraints for raw manure collection that inflate logistics costs beyond three hundred kilometers.
- EU F-Gas Regulation and REACH compliance:Ammonia emission documentation and contaminant threshold verification for imported organic amendments impose testing burdens that exclude smaller processors from export eligibility.
- Synthetic nitrogen substitution economics:Urea price volatility following natural gas market fluctuations periodically narrows the cost gap with processed biofertilizers, delaying farmer conversion timelines in price-sensitive segments.
Strategic Opportunities
- Carbon credit methodology qualification:Evolving verification protocols for soil carbon sequestration claims will determine which thermophilic composting and anaerobic digestion technologies qualify for offset revenue streams, creating first-mover advantage for documented processors.
- Subscription-based refill systems:Modular packaging configurations for liquid variants enable recurring revenue models that improve customer lifetime value versus one-time bulk pellet purchases in commercial greenhouse operations.
- USDA NRCS conservation program expansion:Environmental Quality Incentives Program cost-sharing for nutrient management plans partially offsets farmer adoption expenses, accelerating penetration in Corn Belt row-crop segments.
Industry Challenges
- OMRI and national organic program certification timelines:Multi-year approval processes for new processing facilities constrain capacity expansion velocity, creating order backlogs during seasonal application windows.
- Microbial inoculant formulation stability:Shelf-life degradation of algae-bacteria consortia in integrated biorefinery outputs requires cold-chain distribution infrastructure that conflicts with existing dry fertilizer logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Manure Biofertilizers Market |
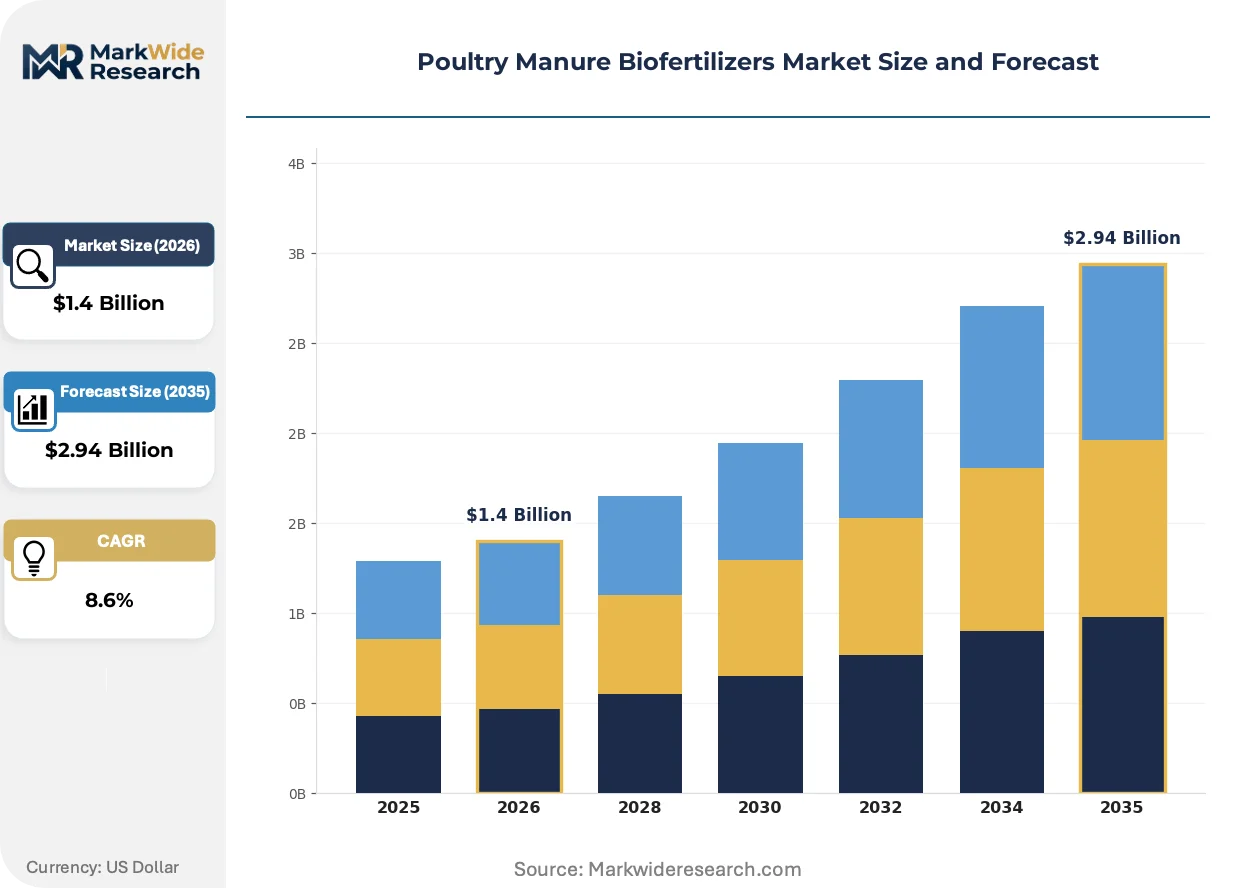
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Liquids, Granules, Powders Application: Crops, Organic Farming, Horticulture, Turf Management Distribution Channel: Online, Retail Stores, Agricultural Cooperatives, Direct Sales End User: Farmers, Commercial Growers, Greenhouses, Organic Producers |
| Companies Covered | Lallemand Inc., OMRI, Fabon Agro, Biola, Australian Bio Fert Pty Ltd, Jaipur Bio Fertilizers, National Fertilizers Limited, Olmix Group, Ductor Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Manure Biofertilizers Market Strategic Shifts & Innovations
Processing technology convergence with precision agriculture infrastructure is redefining product-form specifications and service bundling expectations across commercial farming operations.
Integrated algae-bacteria biorefinery technology enriches standard poultry manure substrates with bioactive compounds that enhance nitrogen mineralization rates in soil applications. Large-scale vegetable producers in the Netherlands and Spain are piloting these enhanced formulations at commercial scale. The technology is expanding into contract growing arrangements where processors retain agronomic advisory responsibilities alongside physical product delivery.
REACH frameworks governing contaminant thresholds in imported organic amendments now require full supply chain composting protocol documentation from thermophilic phase initiation through finished product stabilization. This regulatory tightening excludes non-compliant exporters from EU member state agricultural input registrations. Pellet formulations face heightened scrutiny relative to liquid variants due to longer storage intervals between processing and field application.
Farmer purchasing committees at cooperative procurement hubs are consolidating input sourcing decisions previously fragmented across individual household orders. This buyer concentration shifts negotiation leverage toward volume-discount structures and technical service bundling in India's state agricultural depot networks. Gujarat and Maharashtra cooperative federations demonstrate the most advanced procurement centralization, with implications for supplier margin compression.
Poultry Manure Biofertilizers Market Segmentation
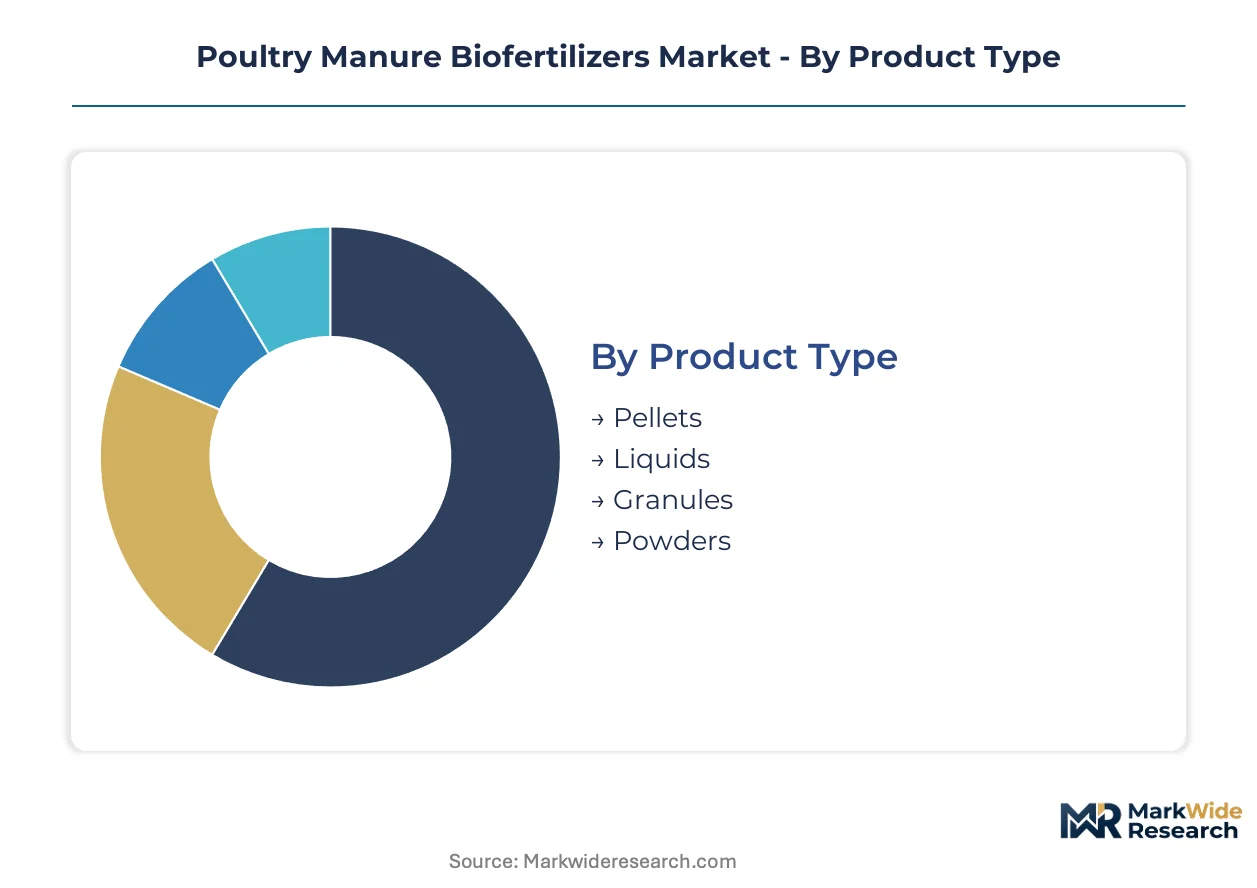
Product-form specifications and distribution infrastructure determine adoption economics across farming scales. Segmentation reveals where precision agriculture integration, organic certification premiums, and cooperative procurement power reshape competitive dynamics.
Product Type:
Standalone spreading applications favor dry formulations compatible with existing farm machinery, while embedded fertigation systems drive liquid integration depth.
- Pellets:Compressed extrusions with mechanical spreading compatibility dominate volume in North American row-crop and European cereal operations. Corn Belt farmers in Iowa and Illinois prefer pelletized poultry manure for uniform field application without specialized equipment retrofit.
- Liquids:Suspended organic matter formulations integrate with drip irrigation infrastructure in protected cultivation. Spanish greenhouse operators in Almeria and Dutch vegetable producers accelerate procurement for fertigation precision in tomato and pepper operations.
- Granules:Agglomerated particles with controlled-release coatings serve specialty crop segments requiring delayed nutrient availability.
- Powders:Fine-ground substrates target compost blending operations and soil amendment mixing facilities rather than direct field application.
Pellets lead volumes today; liquids are gaining share fastest.
Application:
Margin structures diverge sharply between certified organic premiums and conventional substitution economics.
- Crops:Broad-acre cereal and oilseed applications concentrate procurement volumes through cooperative aggregation. Indian wheat and rice farmers in Punjab and Haryana access subsidized pellet supplies through state agricultural depot networks.
- Organic Farming:OMRI and EU organic program certifications constrain supplier pools and protect margin structures. German and Austrian biodynamic operations pay premiums for documented thermophilic processing protocols exceeding regulatory minimums.
- Horticulture:High-value fruit and vegetable production in Italy's Po Valley and California's Central Valley drives demand for low-salt liquid formulations compatible with sensitive root systems.
- Turf Management:Golf course and sports field maintenance in Florida and Arizona purchases odor-controlled pellet products for aesthetic compliance.
Crops anchor revenue today; organic farming commands the steepest expansion trajectory.
Distribution Channel:
Customer scale and technical service requirements determine channel selection across farming typologies.
- Agricultural Cooperatives:Consolidated procurement hubs in Gujarat and Maharashtra federations negotiate volume discounts and bundled agronomic advisory. Cooperative concentration shifts supplier negotiation leverage toward technical service inclusion.
- Direct Sales:Large commercial growers in Brazil's Mato Grosso and Ukraine's Black Belt regions contract directly with processors for customized formulation blending and application scheduling.
- Retail Stores:Independent garden centers and farm supply dealers serve hobby farmers and small-scale organic producers with bagged pellet SKUs.
- Online:E-commerce platforms capture specialty organic amendments for urban agriculture and peri-urban greenhouse operators seeking direct-to-farm delivery.
Agricultural cooperatives dominate procurement volumes; direct sales channels are expanding most quickly.
End User:
Operational scale and certification requirements segment purchasing behavior and price sensitivity.
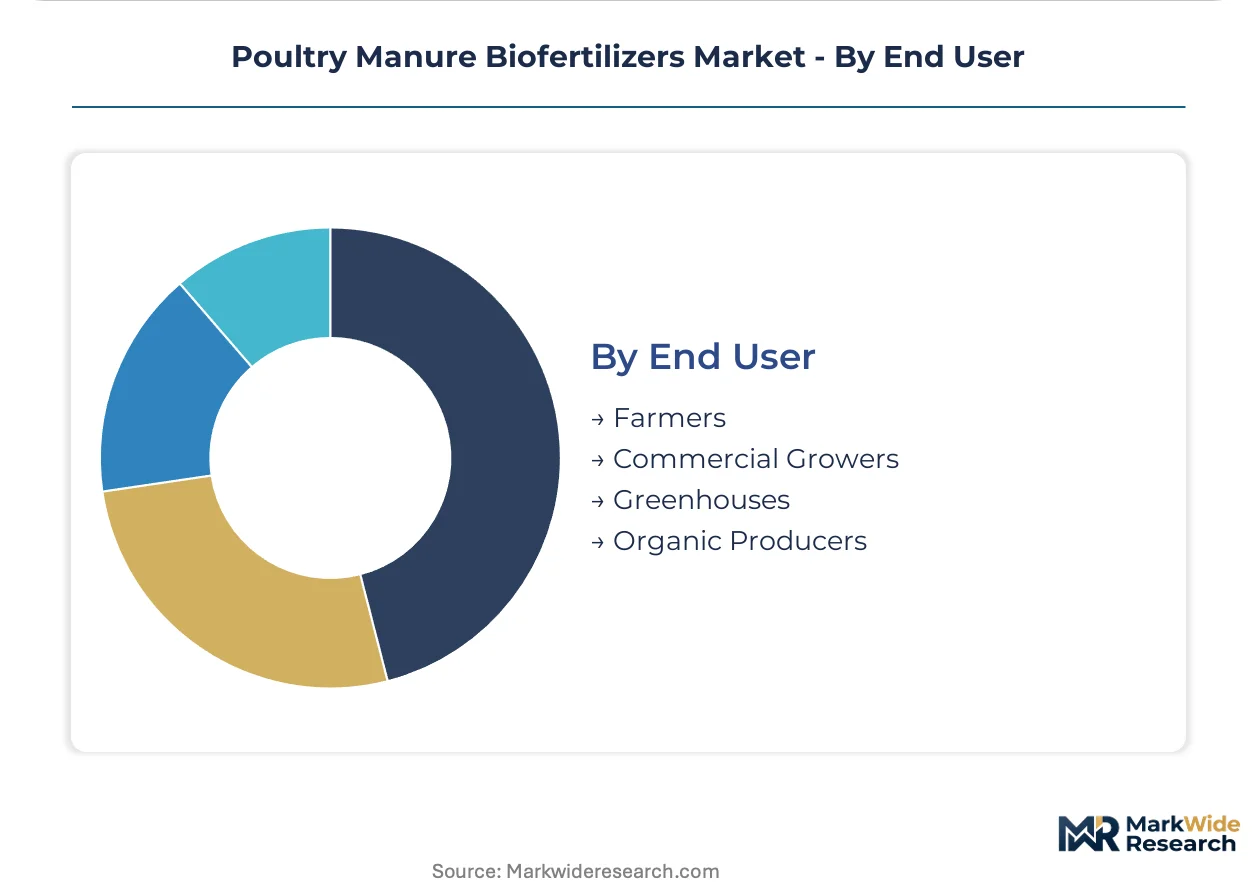
- Farmers:Smallholder networks in India's National Mission for Sustainable Agriculture depend on government-subsidized depot distribution for cost-accessible organic amendments.
- Commercial Growers:Large-scale vegetable and grain operations in Spain's Murcia region and Australia's Riverina prioritize supply security through multi-year offtake agreements.
- Greenhouses:Controlled-environment agriculture facilities in the Netherlands and Canada specify liquid formulations with filtration compatibility for closed-loop irrigation systems.
- Organic Producers:Certified operations across Denmark and Switzerland require full supply chain documentation for EU organic program and Bio Suisse label compliance.
Farmers represent the largest addressable base; greenhouses are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The poultry manure biofertilizer industry traces its commercial scaling to European anaerobic digestion investments during the 1990s, with thermophilic processing protocols later exported to North American and South Asian markets. Today, regulatory mandates on synthetic fertilizer reduction and carbon sequestration verification are redrawing procurement patterns across distinct national agricultural systems.
United States
Corn Belt row-crop operators in Iowa and Illinois drive pellet formulation demand for mechanical spreading compatibility. The USDA NRCS Environmental Quality Incentives Program partially offsets farmer adoption costs through conservation practice cost-sharing. Large-scale vegetable producers in California's Central Valley increasingly specify liquid variants for fertigation precision in high-value specialty crop operations.
Germany
Biodynamic farming operations in Bavaria and Baden-Württemberg pay substantial premiums for documented thermophilic processing exceeding EU regulatory minimums. The EU F-Gas Regulation and REACH frameworks govern ammonia emissions and contaminant thresholds, compelling full supply chain protocol documentation from processors. Berlin-Brandenburg agricultural cooperatives consolidate procurement decisions previously fragmented across individual farm households.
India
Punjab and Haryana smallholder networks access subsidized supplies through state agricultural depot distribution under the PLI scheme for organic fertilizers. The National Mission for Sustainable Agriculture redirects farmer subsidies toward bio-based soil amendments. Gujarat cooperative federations demonstrate the most advanced procurement centralization, with volume-discount negotiations shifting supplier leverage toward technical service bundling.
Spain
Almeria greenhouse operators accelerate liquid biofertilizer procurement for drip irrigation integration in tomato and pepper protected cultivation. The EU Green Deal's Farm to Fork Strategy compresses farmer choice toward certified organic amendments. Murcia region commercial growers prioritize supply security through multi-year offtake agreements with documented processors.
Netherlands
Vegetable producers in the Westland and Noord-Brabant clusters pilot algae-bacteria enriched formulations at commercial scale. REACH compliance requirements for imported organic amendments exclude non-compliant exporters from agricultural input registrations. Closed-loop irrigation systems in controlled-environment agriculture facilities specify filtration-compatible liquid formulations with stringent particulate thresholds.
Poultry Manure Biofertilizers Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and supply chain documentation capabilities. The vendor base stratifies between integrated biorefinery operators with proprietary microbial consortia and regional composting facilities serving localized agricultural zones. Three archetypes dominate: government-mandated distribution anchors, microbial inoculant specialists, and algae-bacteria biorefinery integrators. Competitive moves concentrate on multi-year offtake contracting for feedstock security and thermophilic processing technology licensing for regulatory compliance acceleration.
Within the microbial inoculant tier, Lallemand Inc. and Biola occupy positions leveraging fermentation expertise for product efficacy claims. National Fertilizers Limited exemplifies the government-anchored archetype through state depot network penetration. Olmix Group represents integrated biorefinery differentiation via algae-bacteria substrate enrichment technology. These three companies span the strategic spectrum from public-sector distribution capture to proprietary bioprocessing innovation.
| Leading Market Players |
|---|
| Lallemand Inc. |
| OMRI |
| Fabon Agro |
| Biola |
| Australian Bio Fert Pty Ltd |
| Jaipur Bio Fertilizers |
| National Fertilizers Limited |
| Olmix Group |
| Ductor Oy |
| Others |
Cost & Logistics Intelligence
Subscription-based refill procurement from Dutch greenhouse cooperatives is compressing spot-market pellet premiums and forcing processors toward recurring revenue models with locked-in volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction flows. Premium tiers attach to OMRI-certified organic program compliance and full thermophilic documentation, while economy tiers serve conventional row-crop substitution without certification. Cost compression in standard-grade pellets is intensifying because Indian state depot procurement centralizes volume negotiations. Smallholder networks in Punjab and Haryana exhibit highest price sensitivity; German biodynamic operations show least.
Supply Chain Analysis
Refurbishment flows for used anaerobic digestion equipment from Netherlands-based vegetable cooperatives feed secondary processor expansion in Poland and Romania. Raw material sourcing draws from layer and broiler concentration zones in Iowa, Gujarat, and Murcia. Feedstock logistics hinge on transport radius constraints beyond three hundred kilometers. Single-source vulnerability clusters in EU F-Gas Regulation-compliant thermophilic processing capacity. Distribution runs through government-mandated depot networks in India and cooperative procurement hubs in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU Green Deal mandates on synthetic fertilizer reduction lock in structural demand substitution with regulatory enforcement.
For Market Incumbents: Acquire thermophilic processing documentation assets from distressed regional composting facilities to consolidate EU export eligibility. Backward integration into captive layer operation contracts in Iowa and Illinois secures feedstock against transport radius inflation. Invest in algae-bacteria biorefinery licensing to differentiate from commodity pellet competitors facing margin compression. For New Entrants and Emerging Players: India's PLI scheme for organic fertilizers opens a window for state depot network penetration without legacy distribution overhead. White-space targets concentrate in Gujarat cooperative federation technical service bundling and Spanish Almeria greenhouse liquid formulation integration. Go-to-market through agronomic advisory partnerships rather than product-only positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated biorefinery operators possessing proprietary microbial consortia and REACH-compliant documentation infrastructure. Long-term viability frames around carbon credit methodology qualification for soil sequestration claims. Monitor EU carbon credit verification protocol finalization as inflection signal for processor revenue model expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive layer operation contracts in Iowa and Gujarat eliminate transport radius cost volatility. |
| Thermophilic Processing Technology Licensing | REACH and FSSAI compliance acceleration unlocks EU and Indian depot network access. |
| Subscription-Based Refill System Deployment | Dutch greenhouse cooperative procurement shifts revenue toward recurring models with higher lifetime value. |
| Algae-Bacteria Biorefinery Capacity Buildout | Netherlands vegetable producer pilots demonstrate nitrogen mineralization rate premiums. |
| Carbon Credit Methodology Qualification | Soil sequestration verification protocols determine offset revenue eligibility for documented processors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant managers at thermophilic processing facilities, procurement leads at Indian state agricultural depots, distribution channel partners in German cooperative federations, and technical R&D directors at microbial inoculant laboratories. Secondary validation drew from EU F-Gas Regulation filings, BIS organic fertilizer standards documentation, USDA NRCS conservation program disbursement records, and customs trade data on processed manure amendments. Bottom-up facility capacity aggregation and top-down demand modeling from agricultural acreage statistics were cross-referenced for triangulation.
Segment-weighting across product type, application, and distribution channel dimensions anchored volume and value outputs. Pellet, liquid, granule, and powder formulations were modeled against crop, organic farming, horticulture, and turf management end-uses. CAGRs derived from historical procurement velocity in state depot networks and cooperative procurement consolidation trends. Industry-specific inputs incorporated PLI scheme subsidy disbursement trajectories and EU Green Deal enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon credit methodology delays or urea price collapse scenarios. Practitioners should monitor EU soil carbon sequestration verification finalization and Indian state depot procurement centralization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Artificial Insemination Market