
 Mycorrhiza-Based Biofertilizer Market | 2026-2036
Mycorrhiza-Based Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Mycorrhiza-Based Biofertilizer Market Foresight
A shift from single-source spore procurement to multi-strain consortium sourcing is repositioning supply chain resilience as a competitive priority for biofertilizer manufacturers. Novozymes A/S leverages its microbial fermentation infrastructure to sustain high-volume inoculant production across Scandinavian and North American facilities. Valent BioSciences Corporation anchors its market presence through specialized mycorrhizal formulations targeting high-value horticultural crops. Koppert competes by integrating biological control agents with mycorrhizal products, offering bundled crop protection solutions to distributors.
Mycorrhiza-based biofertilizer comprises formulations containing viable arbuscular or ectomycorrhizal fungal propagules, typically quantified at minimum 1,000 infective propagules per gram for commercial viability, designed to colonize plant root systems and enhance phosphorus and micronutrient uptake through extraradical hyphal networks. The liquid formulation segment dominates commercial volumes due to compatibility with existing irrigation and fertigation infrastructure, while granular products command margin premiums in orchard and plantation systems where soil incorporation precedes planting. Soil enhancement applications lead volume consumption across broadacre agriculture, whereas seed treatment represents the fastest-expanding application channel as coating technologies improve propagule adhesion and shelf stability.
The EU Fertilizing Products Regulation and REACH frameworks govern microbial strain safety and environmental release protocols across European markets, while the USDA National Organic Program and state-level fertilizer registration requirements shape product compliance pathways in the United States. India's FCO amendments under the Ministry of Agriculture now recognize mycorrhizal biofertilizers under scheduled fertilizer categories, streamlining interstate distribution for domestic manufacturers. Stakeholders must monitor evolving strain patent landscapes and regulatory divergence between organic certification bodies to anticipate which product formats will secure preferential market access.
Market Dynamics
Multi-strain consortium sourcing is electrifying supply chain resilience as a competitive priority, displacing single-source spore procurement across biofertilizer manufacturing. Manufacturers now prioritize strain diversity to mitigate propagation failure risks and secure consistent inoculant quality.
Growth Catalysts
- EU Fertilizing Products Regulation:Harmonization of biofertilizer standards across member states accelerates product registration timelines and reduces interstate compliance friction.
- Precision agriculture integration:Soybean and maize growers in the North American Corn Belt embed mycorrhizal applications into variable-rate input programs, normalizing biological soil amendments.
- Seed treatment technology:Advances in coating technologies improve propagule adhesion and shelf stability, expanding commercial viability beyond liquid formulations.
Market Restraints
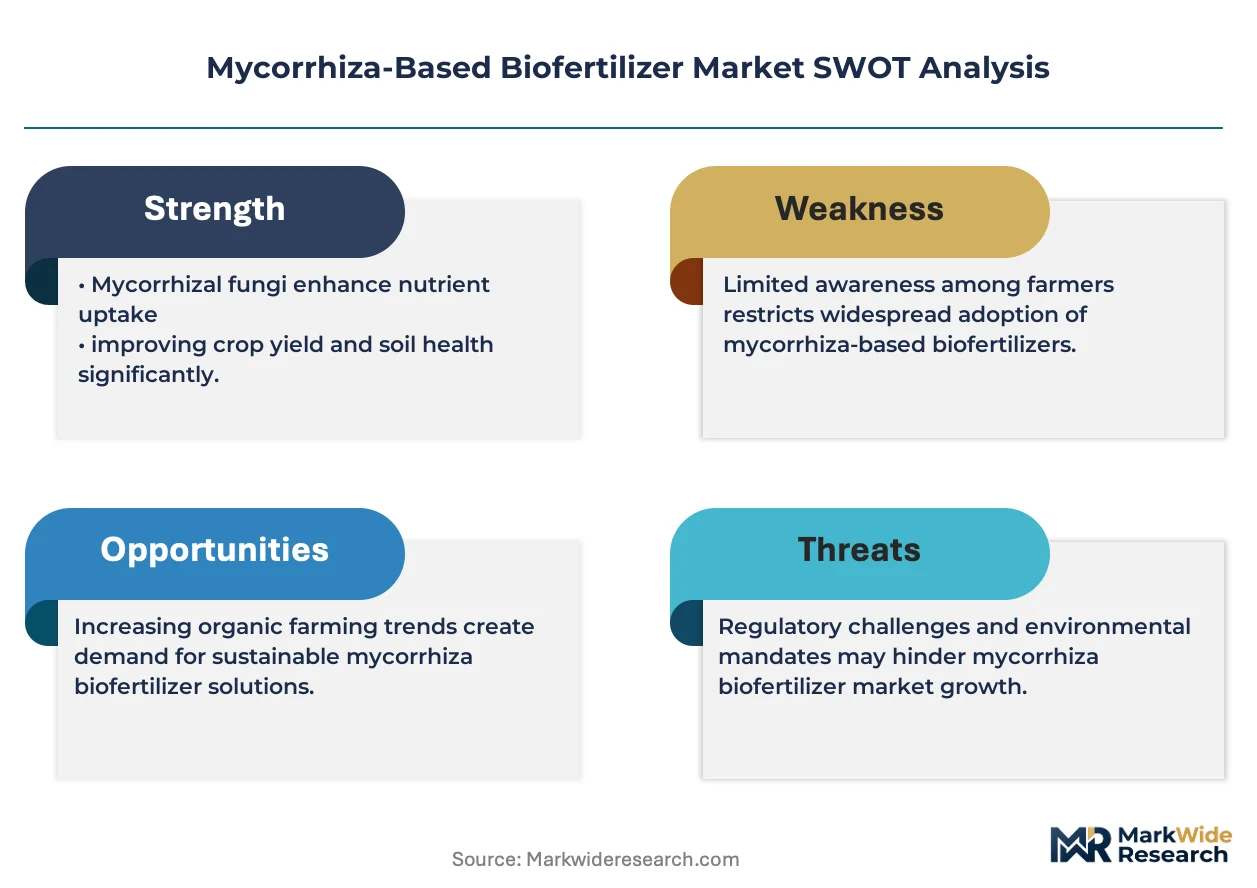
- Live culture volatility:Temperature sensitivity during transport and storage elevates spoilage rates for arbuscular mycorrhizal propagules, constraining distribution radius.
- Phosphorus fertilizer substitution economics:Synthetic phosphate remains price-competitive in commodity grain systems, limiting mycorrhizal penetration in cost-sensitive broadacre operations.
- REACH microbial safety protocols:Environmental release assessments for novel fungal strains extend development timelines and elevate regulatory compliance costs.
Strategic Opportunities
- India FCO scheduled recognition:Ministry of Agriculture amendments streamlining interstate distribution create pathway for domestic manufacturers to scale nationally.
- Horticultural bundled solutions:Integration of biological control agents with mycorrhizal products addresses distributor demand for simplified crop protection procurement.
- Orchard and plantation granular formats:Soil incorporation workflows in perennial systems support margin premiums unattainable in annual crop liquid applications.
Industry Challenges
- Strain patent landscape navigation:Evolving intellectual property claims around proprietary fungal isolates complicate licensing negotiations and product development freedom-to-operate assessments.
- Organic certification divergence:Inconsistent strain approval criteria between USDA National Organic Program and private organic bodies fragment product format standardization.
- Propagule quantification standardization:Variable laboratory methods for infective propagule counting create quality assurance disputes between manufacturers and agricultural extension services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycorrhiza-Based Biofertilizer Market |
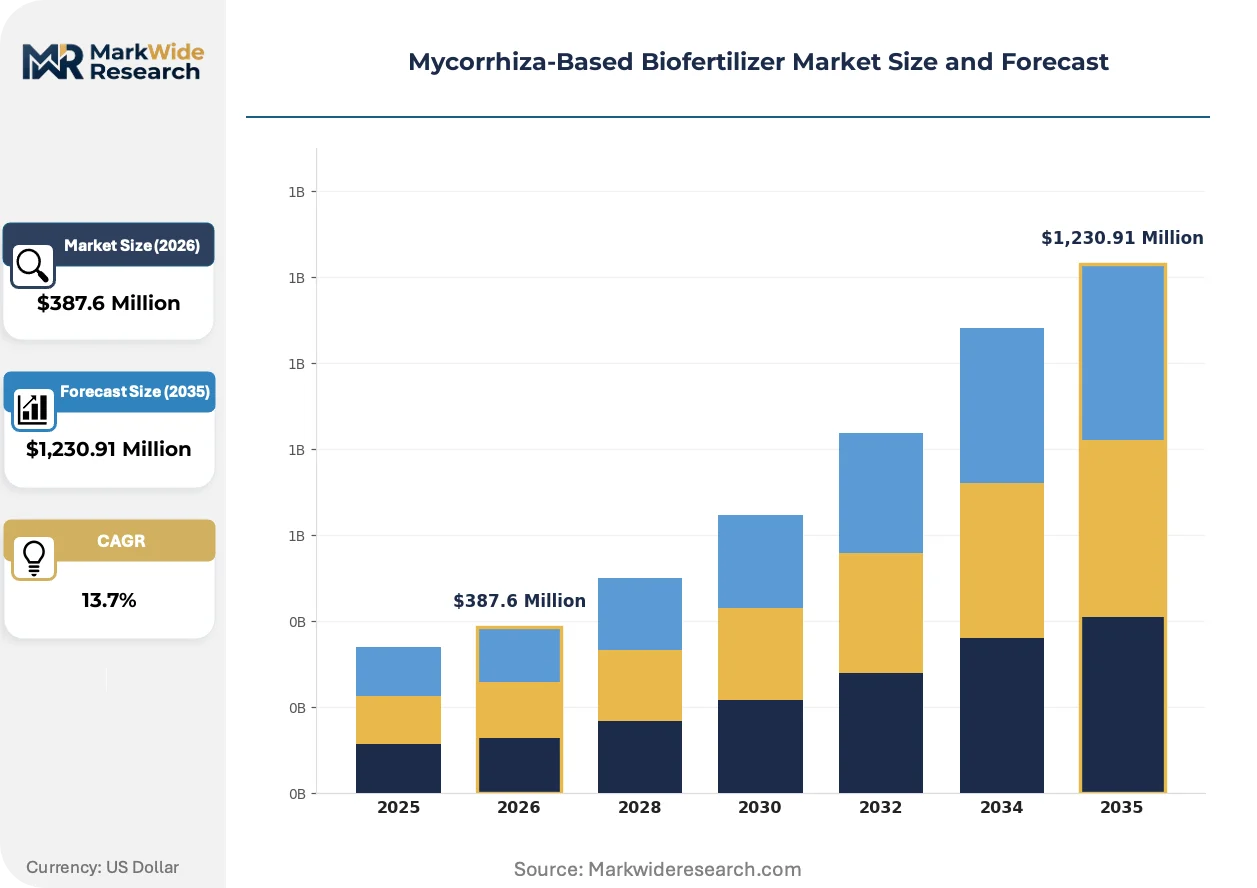
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,230.91 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powder, Tablet End Use Industry: Agriculture, Horticulture, Landscaping, Organic Farming Distribution Channel: Direct Sales, Online Retail, Supermarkets, Agricultural Stores Application: Soil Enhancement, Crop Protection, Nutrient Management, Seed Treatment |
| Companies Covered | AgriLife, Valent BioSciences Corporation, Novozymes A/S, Koppert, IPL Biologicals Limited, Lallemand Inc., Symborg, T. Stanes and Company Limited, UPL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycorrhiza-Based Biofertilizer Market Shifts & Advancements
Biological input integration is reshaping how growers manage soil fertility, with technology convergence between microbial science and precision application systems defining competitive differentiation. Three developments dominate current investment and product strategy.
Encapsulation technologies for arbuscular mycorrhizal propagules are electrifying shelf-life extension and field efficacy. Biopolymer matrices protect viable fungal structures from desiccation and temperature fluctuation. Large-scale vegetable producers in Spain and Italy adopt these formulations for transplant shock reduction. The technology is electrifying market expansion into regions previously excluded by logistics constraints.
India's FCO amendments under the Ministry of Agriculture now recognize mycorrhizal biofertilizers under scheduled fertilizer categories. This regulatory clarity streamlines interstate distribution permits and reduces compliance fragmentation for domestic manufacturers. Domestic producers respond by expanding fermentation capacity to capture preferential market access before multinational registration completion.
Buyer consolidation among agricultural cooperatives and integrated grain processors concentrates procurement authority. These entities negotiate volume-based biological input contracts that displace distributor-centric purchasing. France and Germany exhibit the most pronounced cooperative procurement concentration, with vineyard and vegetable production cooperatives standardizing on specified strain consortia.
Mycorrhiza-Based Biofertilizer Market Segmentation
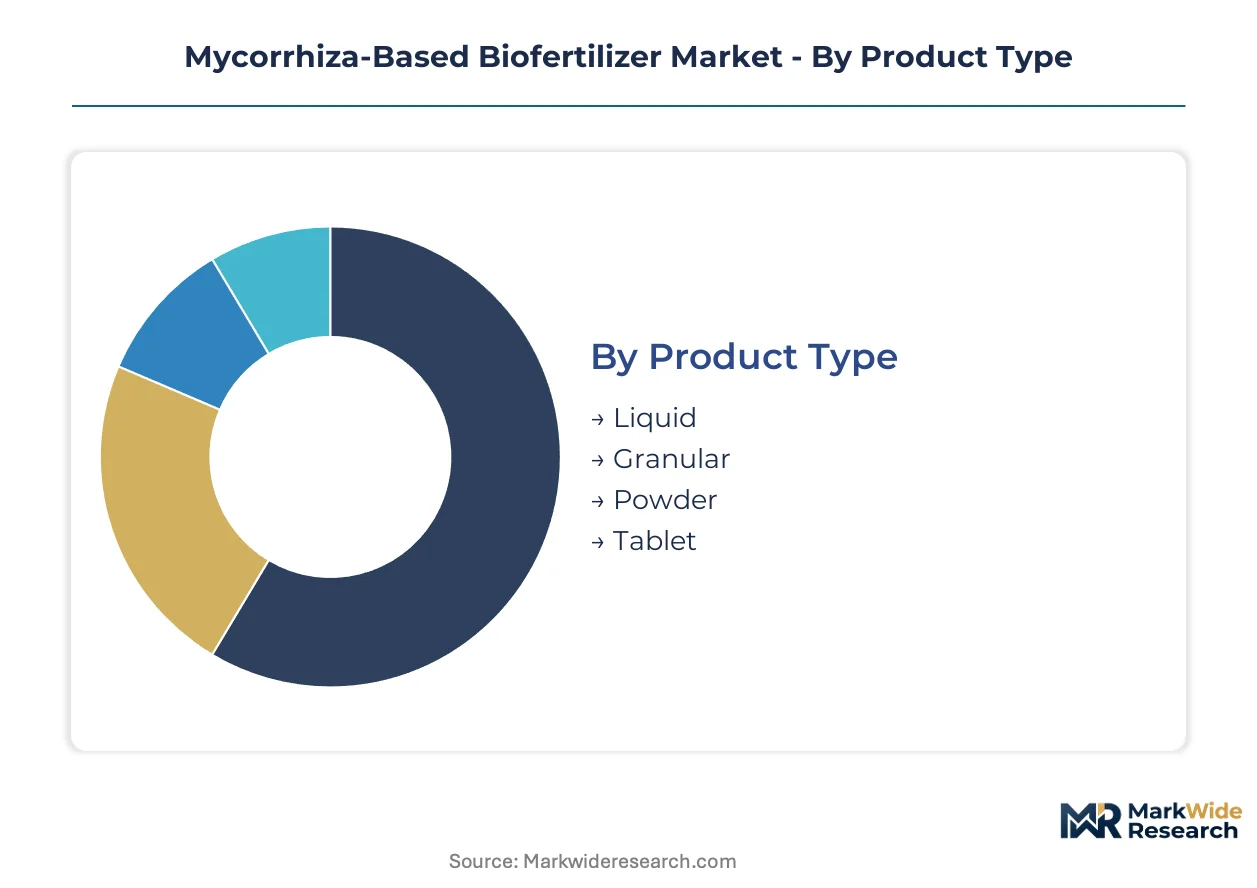
Mycorrhiza-based biofertilizer segmentation reflects divergent capital requirements across formulation technologies and application methods. Product type determines fermentation infrastructure investment, while application channel dictates field support and technical service intensity.
Product Type:
Liquid formulations demand the heaviest upfront capital for sterile fermentation tanks and aseptic filling lines. Granular and powder alternatives require lower bioreactor investment but carry higher downstream processing equipment costs.
- Liquid:Aqueous suspensions containing 1,000+ infective propagules per gram require continuous sterile production environments. North American Corn Belt soybean and maize growers embed these formulations into precision fertigation systems, normalizing biological soil amendments through variable-rate input programs.
- Granular:Clay or organic carrier matrices encapsulate fungal propagules for soil incorporation workflows. French and German vineyard operators procure these formulations for pre-planting root zone establishment, paying margin premiums unavailable in annual crop segments.
- Powder:Lyophilized or air-dried spore concentrates suit bulk blending with conventional fertilizers. The format appeals to agricultural cooperatives negotiating volume-based biological input contracts.
- Tablet:Compressed carrier systems enable precision placement at individual transplant sites. Spanish and Italian vegetable producers adopt these for transplant shock reduction in high-value greenhouse operations.
Most installed capacity flows through Liquid. Expansion is steepest in Granular.
End Use Industry:
Customer archetype determines technical service intensity and pricing power. Horticultural buyers demand strain-specific performance guarantees, while broadacre agriculture prioritizes cost-per-hectare efficiency.
- Agriculture:Broadacre grain and oilseed operations integrate mycorrhizal inoculants into conventional input programs. USDA National Organic Program certification requirements shape product selection for transitioning conventional acreage.
- Horticulture:Greenhouse and nursery producers specify multi-strain consortia for containerized production systems. Buyer consolidation among integrated processors concentrates procurement authority in France and Germany.
- Landscaping:Turf establishment and ornamental planting drive seasonal demand spikes. Municipal and commercial landscape contractors favor liquid formulations compatible with hydroseeding equipment.
- Organic Farming:Certified operations mandate third-party verified strain purity and exclusion of synthetic carriers. EU Fertilizing Products Regulation harmonization accelerates product registration timelines across member state markets.
Agriculture captures the largest volume share. Organic Farming is climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics. Direct sales require field technical staff investment, while retail channels demand trade promotion spending and inventory placement fees.
- Direct Sales:Manufacturer field representatives provide on-farm inoculation guidance and performance monitoring. Large-scale grain processors and cooperative buyers negotiate multi-year supply agreements through this channel.
- Online Retail:E-commerce platforms enable smallholder access to specialized formulations previously restricted to wholesale volumes. India's FCO scheduled recognition streamlines interstate distribution permit acquisition for domestic producers.
- Supermarkets:Mass-market garden centers stock consumer-packaged tablet and powder formats for home gardening segments. Shelf placement competes with synthetic fertilizer brands for seasonal merchandising space.
- Agricultural Stores:Independent farm supply dealers stock liquid and granular formulations alongside conventional crop inputs. Technical staff training on biological product handling remains inconsistent across independent retail networks.
Direct Sales handles the majority of commercial volume. Online Retail is gaining share fastest.
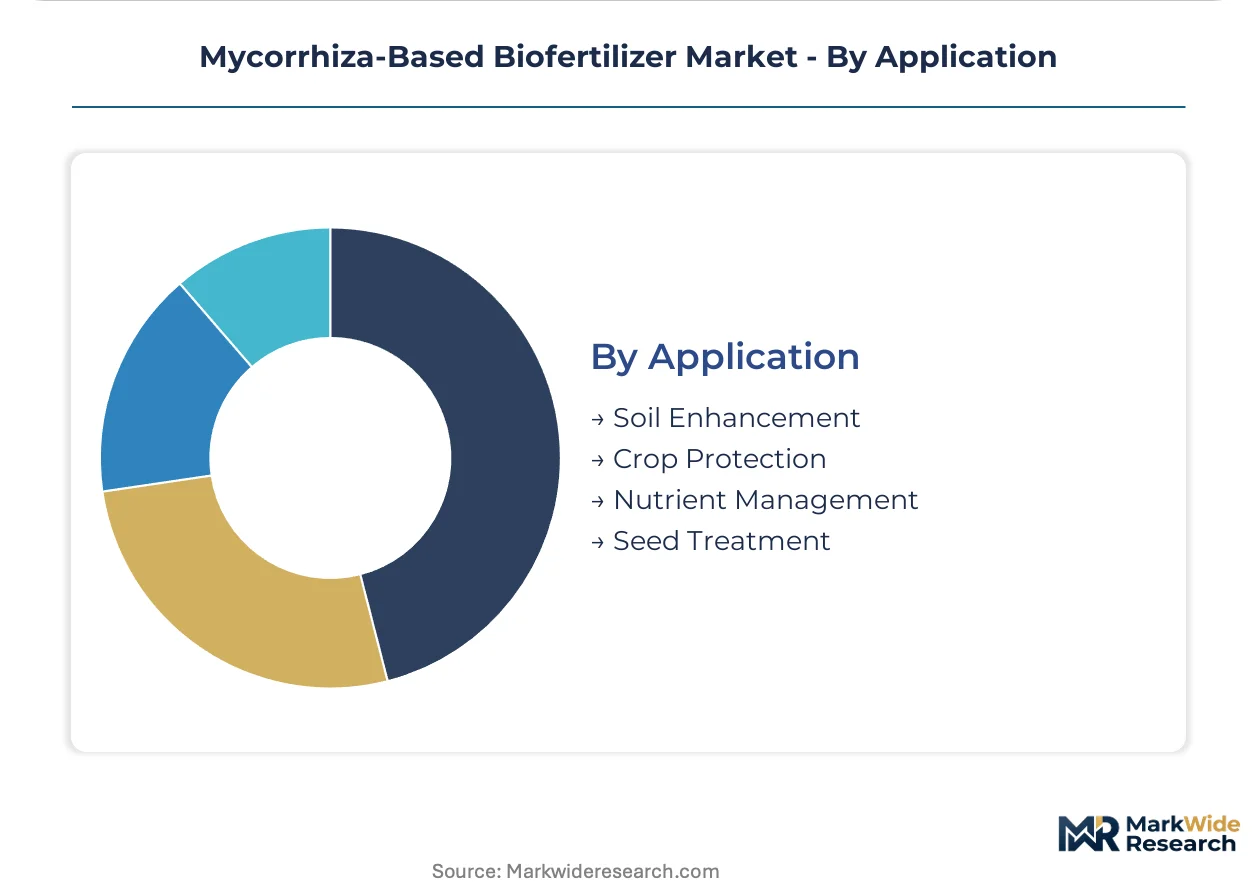
Application:
Application method determines propagule survival rates and colonization speed. Soil contact applications require higher dose rates but achieve more uniform root system establishment.
- Soil Enhancement:Broadcast or banded incorporation delivers propagules into the root zone of established crops. Broadacre agriculture in the North American Corn Belt dominates volume consumption through this channel.
- Seed Treatment:Coating technologies improve propagule adhesion and shelf stability, expanding commercial viability beyond liquid formulations. Advances in polymer binders and desiccation protectants accelerate adoption.
- Nutrient Management:Mycorrhizal inoculants integrate with precision agriculture platforms to optimize phosphorus uptake efficiency. Variable-rate application maps adjust inoculant density based on soil phosphorus tests.
- Crop Protection:Bundled biological control agent and mycorrhizal formulations address distributor demand for simplified procurement. Koppert and comparable suppliers compete through integrated crop protection solutions.
Soil Enhancement commands the dominant volume position. Seed Treatment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American Corn Belt anchors commercial volume deployment, where Iowa and Illinois soybean growers embed mycorrhizal inoculants into variable-rate precision agriculture programs. European organic farming cooperatives in France and Germany are scaling arbuscular mycorrhizal procurement for vineyard and vegetable production systems.
United States
Soybean and maize growers across Iowa, Illinois, and Indiana dominate commercial adoption through precision fertigation integration. The USDA National Organic Program and state-level fertilizer registration requirements shape compliance pathways for biological soil amendments. Chicago-area agricultural cooperatives negotiate multi-year volume contracts that displace traditional distributor-centric purchasing models.
Germany
Vineyard operators in Rhineland-Palatinate and Baden-Württemberg procure granular mycorrhizal formulations for pre-planting root zone establishment. The EU Fertilizing Products Regulation harmonizes biofertilizer standards across member states, accelerating product registration timelines. Bavarian vegetable production cooperatives standardize on specified multi-strain consortia for greenhouse operations.
France
Bordeaux and Burgundy wine regions drive premium-tier demand for specialized mycorrhizal inoculants targeting high-value perennial crops. ANSM and EFSA microbial safety protocols govern strain approval and environmental release assessments. Provence vegetable cooperatives concentrate procurement authority through buyer consolidation among integrated processors.
India
Maharashtra and Gujarat agricultural operations respond to FCO amendments recognizing mycorrhizal biofertilizers under scheduled fertilizer categories. The Ministry of Agriculture streamlines interstate distribution permits, reducing compliance fragmentation for domestic manufacturers. Domestic producers expand fermentation capacity in Pune and Ahmedabad industrial clusters to capture preferential market access.
Spain
Andalusian and Murcian greenhouse vegetable producers adopt encapsulated mycorrhizal formulations for transplant shock reduction. EU REACH frameworks govern novel fungal strain environmental release protocols, extending development timelines for imported products. Valencia-area agricultural technology clusters integrate biological input applications with precision irrigation infrastructure.
Mycorrhiza-Based Biofertilizer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized horticultural formulations and bundled crop protection solutions. The market structure reflects moderate consolidation around fermentation-capable multinationals and regional specialists with strain development expertise. Three archetypes dominate: microbial fermentation infrastructure holders, horticultural formulation specialists, and integrated biological control bundlers. Competitive moves center on multi-strain consortium sourcing partnerships and encapsulation technology licensing to extend distribution radius.
Among microbial fermentation infrastructure holders, Novozymes A/S represents the scale-driven archetype with Scandinavian and North American production assets. Valent BioSciences Corporation exemplifies the horticultural specialization tier, occupying a position targeting high-value crop segments. Koppert sits within the integrated solutions archetype, bundling biological control agents with mycorrhizal products to address distributor demand for simplified procurement. These three anchors demonstrate how competitive positioning stratifies across production scale, crop focus, and solution breadth.
| Leading Market Players |
|---|
| AgriLife |
| Valent BioSciences Corporation |
| Novozymes A/S |
| Koppert |
| IPL Biologicals Limited |
| Lallemand Inc. |
| Symborg |
| T. Stanes and Company Limited |
| UPL Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned fermentation specialists in Denmark and the Netherlands anchor upstream propagule production, translating captive strain libraries into pricing discipline that resists commodity erosion. Their ownership structure insulates long-term R&D cycles from quarterly margin pressure, reinforcing supply security premiums in contracted offtake agreements.
Pricing Analysis
Input-cost pass-through from sterile fermentation infrastructure and biopolymer encapsulation materials anchors pricing stratification across premium, standard, and economy tiers. Quality grade differentiation separates multi-strain consortia with verified infective propagule counts above 1,000 per gram from single-source alternatives, while USDA National Organic Program certification commands 15-25% premiums in transitioning acreage segments. Cost compression in liquid formulations is intensifying as Novozymes A/S and comparable fermentation-scale operators expand Scandinavian and North American capacity. Agricultural cooperatives in the North American Corn Belt exhibit highest price sensitivity through volume-based contract negotiations, whereas French vineyard operators in Bordeaux and Burgundy accept premium positioning for granular pre-planting formulations.
Supply Chain Analysis
Dual-sourcing requirements from agricultural cooperatives and integrated grain processors mandate multi-supplier qualification for arbuscular mycorrhizal propagules, fragmenting procurement across domestic and imported alternatives. Supply concentrates in Denmark, the Netherlands, and India, with Maharashtra and Gujarat fermentation clusters expanding under FCO scheduled recognition. Raw material dependencies center on sterile growth media, clay carrier matrices, and biopolymer encapsulation compounds. Single-source vulnerability in proprietary strain licensing elevates risk as patent landscapes evolve around fungal isolate intellectual property. Distribution runs through direct sales channels for commercial volume, with agricultural stores and online retail capturing residual smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation technology maturation and seed treatment coating advances compress per-hectare application costs while opening premium-tier pricing in high-value horticultural segments. Margin expansion rests on propagule survival rate improvements that reduce effective dose requirements.
For Market Incumbents: To counter live culture volatility during transport and storage, prioritize backward integration into biopolymer encapsulation technology licensing and expand sterile fermentation capacity in Pune and Ahmedabad industrial clusters. Secure multi-strain consortium patent positions before REACH environmental release assessments extend competitor development timelines. Channel control through direct sales field technical staff reinforces cooperative procurement relationships against distributor displacement. For New Entrants and Emerging Players: India's FCO amendments under the Ministry of Agriculture open a window for domestic manufacturers to capture interstate distribution permits before multinational registration completion. Target seed treatment application channels where polymer binder and desiccation protectant advances reduce technical barriers to propagule adhesion. Online retail platforms enable smallholder access with minimal trade promotion spending versus agricultural store inventory placement fees. For Investors and Strategic Acquirers: Agricultural biotechnology majors with existing microbial fermentation infrastructure are the most active acquirer in this space, seeking strain development expertise to complement capital-intensive production assets. Long-term viability centers on 5-10 year patent cliff navigation and regulatory harmonization tailwinds across EU member states. Encapsulation technology licensing deals signal inflection toward distribution radius extension and logistics-constrained market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Biopolymer matrices protect viable fungal structures from desiccation, extending shelf stability into temperature-variable regions. |
| Multi-Strain Consortium Patenting | Proprietary fungal isolate portfolios secure freedom-to-operate against evolving intellectual property claims in strain development. |
| Seed Treatment Coating Advancement | Polymer binder improvements enable propagule adhesion that rivals liquid formulation efficacy in precision agriculture programs. |
| Fermentation Capacity Expansion | Domestic producers in Pune and Ahmedabad industrial clusters capture preferential FCO-recognized market access. |
| Direct Sales Channel Investment | Field technical staff provision secures multi-year cooperative supply agreements displacing distributor-centric purchasing. |
Research Methodology
Bottom-up agriculture and horticulture end-use modeling reconciled against top-down fermentation capacity and propagule production tracking forms the analytical core. Primary interviews with biofertilizer manufacturing executives, agricultural cooperative procurement managers, vineyard operations directors, seed treatment technology specialists, and Ministry of Agriculture regulatory affairs officers combined with secondary validation from EU Fertilizing Products Regulation filings, USDA National Organic Program certification databases, India FCO amendment records, and customs trade data on microbial inoculant imports. Triangulation across these sources reconciles manufacturer shipment data with cooperative offtake reporting.
Historical trendline analysis of liquid formulation penetration in the North American Corn Belt and granular adoption in French and German vineyard systems establishes baseline growth trajectories. Segmentation modeling spans formulation type, application method, end-use industry, and distribution channel, with CAGRs derived from infective propagule demand curves and precision agriculture integration rates. Industry-specific forecast inputs include seed treatment coating technology adoption curves and encapsulation shelf-life extension coefficients.
Revisions become necessary when EU REACH microbial safety protocols extend novel strain approval timelines, India FCO enforcement fragmentation resurges, or synthetic phosphate fertilizer price volatility shifts substitution economics in commodity grain systems. Deviation in encapsulation technology cost curves or cooperative procurement consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Poultry Manure Biofertilizers Market