
 China Biopesticides Market | 2026-2036
China Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
China Biopesticides Market Outlook
China's zero-growth chemical pesticide action plan is pivoting the cost-of-entry calculus for domestic and foreign suppliers alike. Zhejiang Qianjiang Biochemical Co Ltd leverages its fermentation infrastructure to dominate microbial strain production at industrial scale. Koppert Biological Systems Inc navigates import registration pathways to sustain its position in high-value horticultural segments.
Biopesticides comprise living organisms, derived metabolites, and natural substance formulations that suppress agricultural pests through biological mechanisms rather than synthetic chemistry, typically requiring colony-forming unit counts above 10^8 per milliliter for bacterial products and specific spore concentrations for fungal agents. Their primary commercial purpose centers on crop protection with reduced pre-harvest intervals and lower non-target toxicity compared to conventional agrochemicals. Microbial formulations lead volume sales due to established Bacillus thuringiensis manufacturing bases, while botanical extracts command premium pricing in export-oriented vegetable production. The agricultural application segment anchors overall demand, though horticultural channels generate disproportionate margin pools through greenhouse and protected-cultivation contracts.
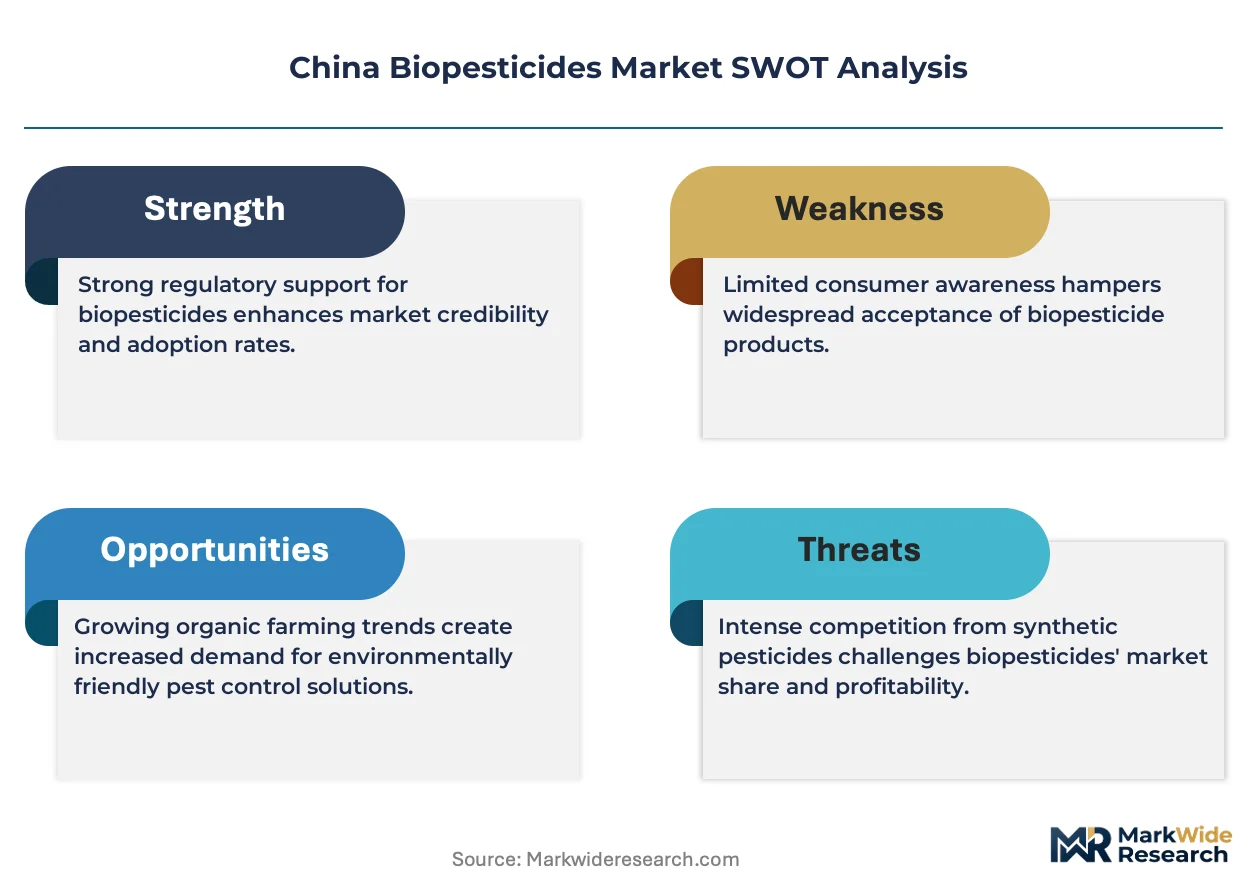
SAMR administers pesticide registration under China's revised Regulation on Pesticide Administration, while MEE enforces environmental compliance standards that favor biodegradable active ingredients over persistent synthetic alternatives. GB standards for microbial pesticide quality specifications and the national green food certification program collectively filter market access toward verified low-residue inputs. Stakeholders must monitor provincial subsidy allocation shifts and evolving organic certification criteria to anticipate procurement pattern changes.
Market Dynamics
China's zero-growth chemical pesticide mandate is compressing the window for biological alternatives to capture procurement budgets across provincial agricultural departments. Large-scale farming cooperatives in the Yangtze River Delta now face binding residue limits under GB 2763 standards, forcing rapid substitution of synthetic chemistries with microbial formulations.
Growth Catalysts
- Zero-growth chemical pesticide policy:The Ministry of Agriculture's action plan redirects provincial subsidy pools toward microbial formulations, creating immediate procurement pull-through in Shandong and Yunnan vegetable belts.
- GB 2763 residue standard tightening:Maximum allowable chemical residues on export vegetables are compressing pre-harvest intervals, making biopesticides the only viable compliance pathway for greenhouse operators.
- Fermentation infrastructure scaling:Industrial bioreactor capacity expansion in Zhejiang and Jiangsu provinces is collapsing unit production costs for Bacillus thuringiensis concentrates.
Market Restraints
- Livestock-derived substrate volatility:Microbial fermentation depends on soybean meal and molasses inputs, both subject to import price swings from Brazilian and Southeast Asian suppliers.
- Shelf-life technical ceiling:Fungal spore formulations degrade above 25°C, limiting distribution reach into southern provinces without cold-chain investment.
- SAMR registration timelines:Microbial strain approval under China's Regulation on Pesticide Administration requires multi-year field trials, freezing product pipelines for foreign entrants.
Strategic Opportunities
- Underpenetrated western corridors:Sichuan and Gansu high-altitude vegetable zones lack established biopesticide distribution, creating first-mover terrain for cooperative-direct sales models.
- Drone application convergence:Integration with agricultural UAV spraying systems is opening aerial delivery channels for liquid microbial formulations across flatland rice provinces.
- Green food certification premium:MEE-aligned organic certification programs are mandating biological inputs, locking in multi-year supply contracts from certified exporters.
Industry Challenges
- Field efficacy validation capacity:Provincial extension stations lack trained entomologists to demonstrate microbial performance against chemical benchmarks in grower trials.
- Strain IP enforcement gaps:Domestic competitors reverse-engineer imported Bacillus subtilis isolates, eroding exclusivity windows before patent litigation concludes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Biopesticides Market |
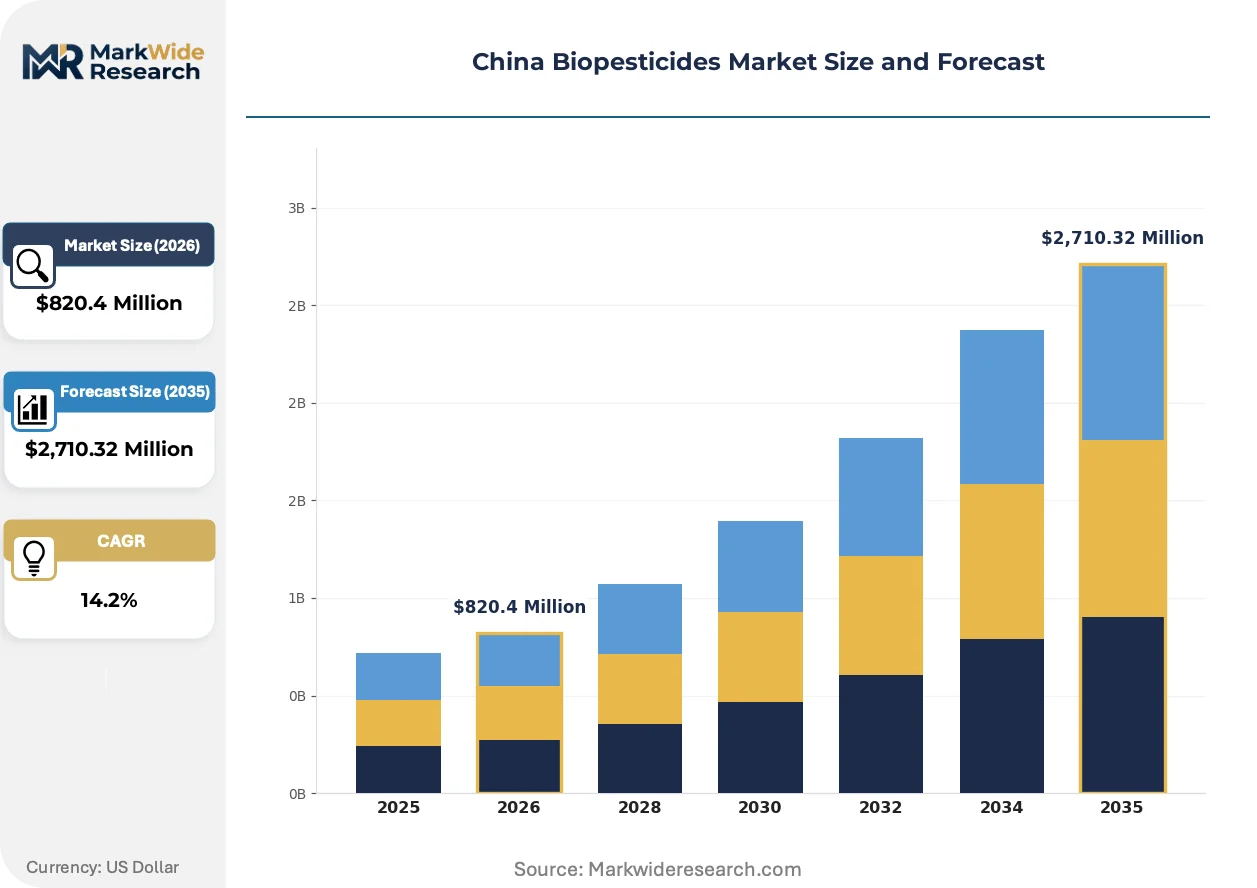
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $2,710.32 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Botanical, Bio-based, Natural Application: Agricultural, Horticultural, Turf, Ornamental Packaging Type: Bottles, Bags, Pouches, Drums End User: Farmers, Agri-businessman, Distributors, Researchers |
| Companies Covered | Dora Agri-Tech, Zhejiang Qianjiang Biochemical Co Ltd, Valent Biosciences LLC, Wuhan Taixin Biological Technology Co Ltd, Beijing Bioseen Crop Sciences Co Ltd, Koppert Biological Systems Inc, Biolchim SPA, Henan Jiyuan Baiyun Industry Co Ltd, Andermatt Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Biopesticides Market Strategic Shifts
Active fermentation process intensification and formulation chemistry advances are collapsing the performance gap between biological and synthetic crop protection. Three parallel developments are restructuring competitive positioning across microbial, biochemical, and semiochemical product classes.
Encapsulation technology is electrifying shelf-stability performance for thermolabile fungal agents. Jiangsu-based greenhouse operators are adopting spore-matrix microencapsulation at pilot scale this season. The technology is electrifying distribution economics by eliminating refrigerated transport requirements across the Yangtze corridor.
MEE enforcement of biodegradable active ingredient preferences is filtering procurement specifications at provincial tender levels. Industrial consequence includes mandatory biodegradability testing for all new pesticide registrations. Horticultural export zones in Shandong are responding fastest, rewriting cooperative supply contracts to exclude persistent synthetic chemistries.
Direct-to-cooperative technical service bundling is displacing traditional distributor-led sales in high-value vegetable segments. Agronomist-embedded supply contracts are replacing commission-based agent networks in Yunnan's protected cultivation belt. The shift is most visible among cherry tomato and cucumber exporters facing EU supermarket residue audits.
China Biopesticides Market Segmentation
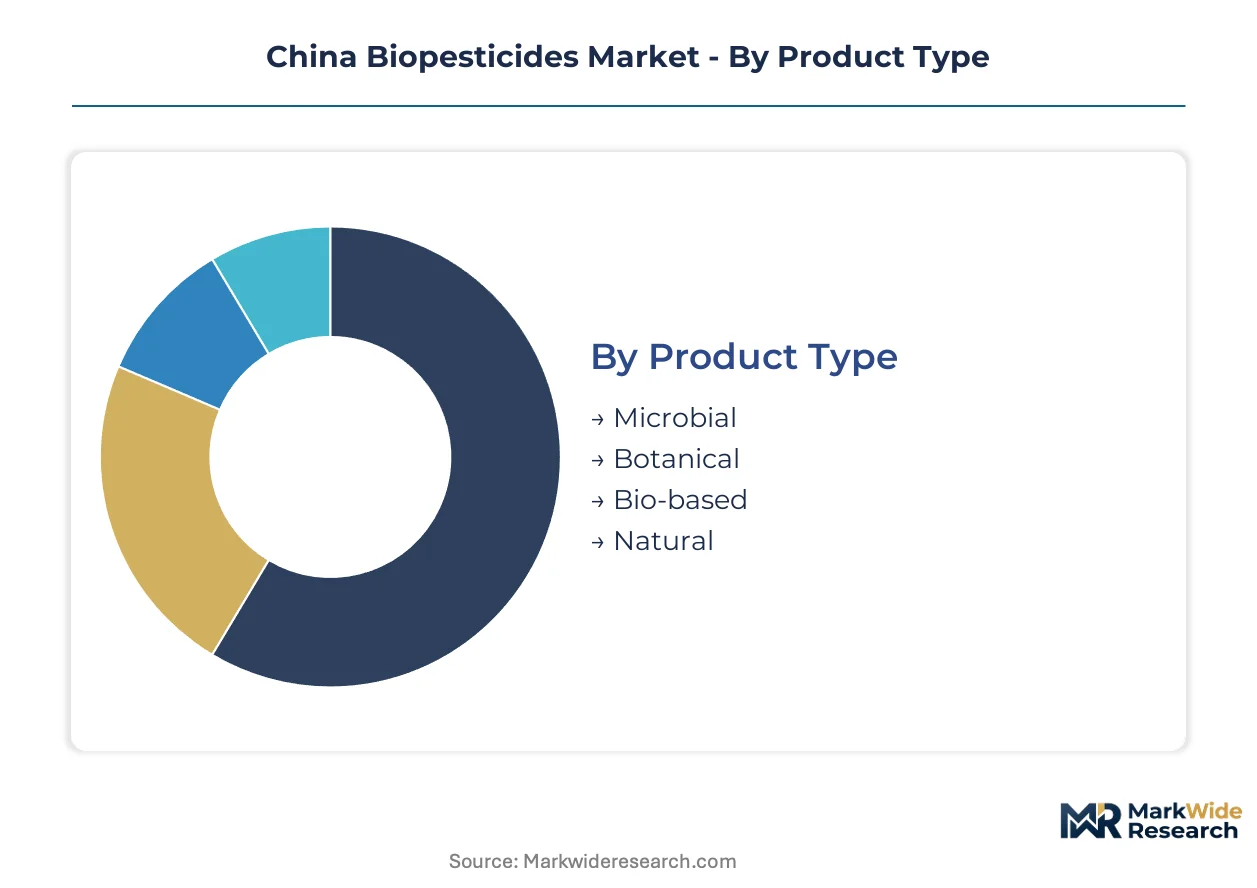
Segmentation in China's biopesticides market reveals how procurement authority, residue compliance pressure, and distribution infrastructure shape commercial outcomes. Understanding these divides exposes where subsidy flows concentrate and which customer types command pricing power.
Product Type:
Supply concentration tilts heavily toward fermentation-derived categories where domestic manufacturing scale exists.
- Microbial:Living bacterial and fungal formulations dominate commercial volumes, with Bacillus thuringiensis concentrates produced at industrial scale across Zhejiang and Jiangsu fermentation corridors. Yangtze River Delta vegetable cooperatives absorb the bulk of output as GB 2763 residue limits tighten.
- Botanical:Plant-derived extracts command premium positioning in export-oriented greenhouse operations, particularly among Shandong cherry tomato and cucumber producers facing EU supermarket audits. Higher input costs and extraction complexity limit penetration beyond high-margin horticultural channels.
- Bio-based:Synthetically modified natural compounds bridge performance gaps with conventional chemistry.
- Natural:Unprocessed botanical preparations serve niche organic certification requirements.
Today's leader: Microbial. Tomorrow's challenger: Botanical.
Application:
Cost tier differentiation separates mass-volume field crops from protected-cultivation premium segments.
- Agricultural:Broadacre field applications in rice and grain belts generate volume throughput but compress margins through provincial tender mechanisms. Drone-compatible liquid formulations are unlocking aerial delivery channels across flatland provinces.
- Horticultural:Greenhouse and protected-cultivation contracts in Yunnan and Shandong yield disproportionate margin pools. Direct-to-cooperative technical service bundling is displacing traditional distributor networks in this segment.
- Turf:Golf course and sports field maintenance drives concentrated demand in affluent coastal municipalities.
- Ornamental:Nursery and landscape applications remain fragmented across municipal procurement.
Agricultural commands current volume. Horticultural climbs the fastest on margin expansion.
Packaging Type:
Customer type dictates format selection, with scale farmers favoring bulk and smallholders requiring unitized distribution.
- Bottles:Standard liquid microbial formulations for cooperative-level procurement in the Yangtze corridor. Shelf-stability improvements through encapsulation technology are extending distribution reach without cold-chain dependency.
- Bags:Powder and granular formulations dominate western province penetration where Sichuan and Gansu high-altitude vegetable zones lack established cold-chain infrastructure.
- Pouches:Single-use sachets serve smallholder trial adoption and extension demonstration programs.
- Drums:Bulk concentrate delivery for large-scale farming cooperatives with on-site dilution capacity.
Bottles anchor current revenue. Bags represent the steepest expansion trajectory as western corridors develop.
End User:
Maturity gradients separate established procurement channels from emerging technical service relationships.
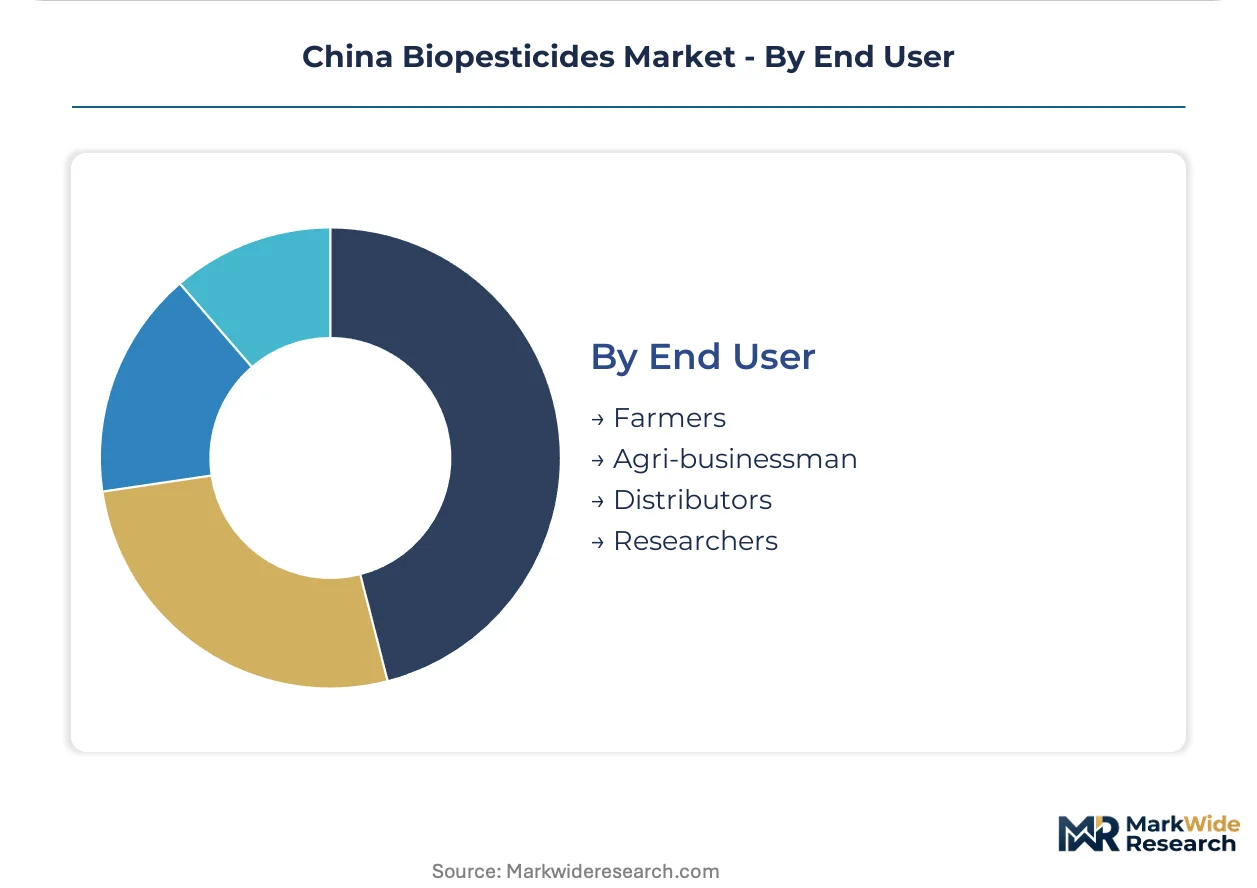
- Farmers:Individual smallholders in Shandong and Yunnan vegetable belts respond to provincial subsidy redirection under the zero-growth chemical pesticide mandate. Extension station validation capacity limits conversion speed.
- Agri-businessman:Large-scale cooperative managers command multi-year supply contracts tied to green food certification requirements. Agronomist-embedded service bundling is consolidating purchasing authority in this tier.
- Distributors:Traditional commission-based agent networks face displacement by direct cooperative sales models.
- Researchers:Strain development and field trial coordination supports SAMR registration pipelines.
Agri-businessman consolidates purchasing power. Farmers gain share fastest as subsidy pools deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopesticide manufacturing in China traces its industrial lineage to fermentation corridor development across Zhejiang and Jiangsu provinces during the early 2000s. These coastal clusters established the substrate supply chains and bioreactor infrastructure that now supply microbial formulations nationwide. Provincial subsidy redirection under the zero-growth chemical pesticide mandate is accelerating geographic expansion beyond traditional production centers.
Yangtze River Delta
Large-scale vegetable cooperatives in Jiangsu and Zhejiang dominate procurement volumes as GB 2763 residue limits tighten on export-bound produce. SAMR registration holders concentrate field trial coordination through Shanghai-based agricultural extension networks. Industrial fermentation capacity in Hangzhou and Ningbi anchors Bacillus thuringiensis concentrate supply for greenhouse operators across the corridor.
Shandong Peninsula
Protected cultivation zones around Weifang and Qingdao generate premium-tier demand for botanical extracts facing EU supermarket residue audits. Provincial agricultural departments redirect chemical pesticide procurement budgets toward microbial formulations under the Ministry of Agriculture action plan. Cold-chain infrastructure gaps in western Shandong counties limit fungal spore formulation penetration without encapsulation technology adoption.
Yunnan Plateau
High-altitude vegetable production around Kunming and Dali drives cooperative-direct technical service relationships displacing traditional distributor networks. MEE enforcement of biodegradable active ingredient preferences filters procurement specifications at municipal tender levels. Drone-compatible liquid microbial formulations are unlocking aerial delivery channels across flatland rice provinces adjacent to the plateau.
Sichuan Basin
Underpenetrated high-altitude vegetable zones in Chengdu's western corridor lack established biopesticide distribution, creating first-mover terrain for cooperative-direct sales models. Provincial extension stations struggle with trained entomologist capacity to demonstrate microbial performance against chemical benchmarks. Bag-packaged powder formulations dominate where cold-chain infrastructure remains undeveloped.
Beijing-Tianjin-Hebei
Research-intensive development of novel microbial strains concentrates around Chinese Academy of Agricultural Sciences facilities in Beijing. SAMR registration pipeline bottlenecks freeze product commercialization timelines despite strong laboratory output. Turf and ornamental applications in affluent Tianjin municipalities drive concentrated demand outside traditional agricultural channels.
China Biopesticides Market Competitive Environment
The competitive structure tilts toward fermentation-scale domestic incumbents with provincial subsidy capture capability. Market concentration remains moderate with clear tiering between industrial-scale microbial producers and import-dependent horticultural specialists. Two archetypes dominate: Zhejiang-based fermentation infrastructure owners leveraging unit cost collapse, and Dutch/Swiss entrants navigating SAMR registration pathways for high-value greenhouse segments. Dominant competitive moves include direct-to-cooperative technical service bundling and encapsulation technology licensing for shelf-stability extension.
Among domestic fermentation-scale players, Zhejiang Qianjiang Biochemical Co Ltd and Wuhan Taixin Biological Technology Co Ltd exemplify the infrastructure-heavy archetype controlling Bacillus thuringiensis concentrate supply. Koppert Biological Systems Inc occupies a position representing import-dependent horticultural specialists serving protected-cultivation premium segments. Beijing Bioseen Crop Sciences Co Ltd sits within the research-commercialization bridge tier, connecting strain development pipelines to provincial extension networks.
| Leading Market Players |
|---|
| Dora Agri-Tech |
| Zhejiang Qianjiang Biochemical Co Ltd |
| Valent Biosciences LLC |
| Wuhan Taixin Biological Technology Co Ltd |
| Beijing Bioseen Crop Sciences Co Ltd |
| Koppert Biological Systems Inc |
| Biolchim SPA |
| Henan Jiyuan Baiyun Industry Co Ltd |
| Andermatt Group AG |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between green food certified exports and domestic commodity vegetables splits pricing power and supply chain configurations across China's biopesticides sector. SAMR registration holders serving Yangtze River Delta cooperatives command bundled technical service premiums, while unregistered commodity suppliers compete on fermentation substrate costs alone.
Pricing Analysis
Bundled agronomist-embedded contracts versus unbundled commodity concentrate sales defines the pricing architecture across China's biopesticide market. Three-tier pricing structure across premium, standard, and economy levels reflects SAMR registration status, green food certification alignment, and cooperative scale. Pricing pressure stems from Zhejiang fermentation corridor capacity expansion collapsing unit production costs for Bacillus thuringiensis concentrates. Smallholder farmers in western provinces exhibit highest price sensitivity, while export-oriented greenhouse operators in Shandong absorb premium botanical extract pricing without volume elasticity.
Supply Chain Analysis
Regional distribution centers in Hangzhou and Ningbo anchor hub-and-spoke patterns radiating toward Yangtze River Delta vegetable belts. Manufacturing concentrates in Zhejiang and Jiangsu provinces, drawing from Brazilian soybean meal and Southeast Asian molasses substrate streams. Single-source vulnerability runs through imported fermentation feedstock exposure to Brazilian supply disruptions. Distribution runs through provincial agricultural extension networks with cooperative-direct technical service models displacing traditional commission-based agent tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's biopesticides market functions as a regulatory compounder where SAMR registration timelines and MEE biodegradability enforcement continuously steepen competitive barriers. The Ministry of Agriculture's zero-growth chemical pesticide mandate creates irreversible procurement budget redirection.
For Market Incumbents: Hedge fermentation infrastructure depreciation by securing multi-year substrate supply agreements with Brazilian and Southeast Asian suppliers before commodity volatility intensifies. Defend margin position through encapsulation technology licensing to eliminate cold-chain dependency for fungal spore distribution into southern provinces. Prioritize agronomist-embedded cooperative contracts over distributor networks to lock in green food certification-aligned procurement pools. For New Entrants and Emerging Players: Launch via drone-compatible liquid microbial formulation partnerships with agricultural UAV operators across flatland rice provinces. Target underpenetrated Sichuan and Gansu high-altitude vegetable zones where provincial extension stations lack trained entomologist capacity to validate incumbent performance claims. Prioritize cooperative-direct technical service bundling over traditional distributor channel buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-scale domestic players possessing SAMR registration pipelines and provincial subsidy capture relationships. Five-to-ten year viability hinges on green food certification program expansion locking biological input mandates into export supply contracts. Monitor encapsulation technology adoption rates as inflection indicator for shelf-stability competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Eliminates cold-chain dependency for fungal spore distribution across southern provinces. |
| Cooperative-Direct Technical Service Bundling | Displaces commission-based distributors with agronomist-embedded supply contracts in Yunnan. |
| Drone-Compatible Formulation Development | Unlocks aerial delivery channels across flatland rice provinces adjacent to plateau regions. |
| Substrate Supply Agreement Securement | Insulates fermentation operations from Brazilian soybean meal and molasses price volatility. |
| SAMR Registration Pipeline Investment | Accelerates microbial strain commercialization timelines for foreign and domestic entrants alike. |
Study Parameters
Multiple input streams — primary interviews with fermentation plant managers, provincial agricultural extension officers, and cooperative procurement directors, alongside secondary validation through SAMR registration databases, MEE enforcement bulletins, and customs trade records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured technical service bundling adoption patterns across Shandong and Yunnan vegetable belts. Secondary sources included GB standards documentation, green food certification program specifications, and provincial subsidy allocation disclosures.
Data-stream reconciliation anchored analytical framework development across the projection horizon. Segmentation dimensions modeled encompassed product type tier, application channel, packaging format, and end-user procurement authority. CAGRs were derived through fermentation capacity expansion trajectories, residue standard tightening velocity, and cooperative penetration rates. Industry-specific forecast inputs incorporated encapsulation technology adoption curves and drone spraying system deployment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR registration timeline delays or MEE enforcement intensity shifts. Forecasts reflect documented assumptions regarding subsidy pool redirection continuity and green food certification program expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market