
 Africa Biological Organic Fertilizers Market | 2026-2036
Africa Biological Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Biological Organic Fertilizers Market Outlook
Certified organic-grade formulation is redrawing competitive boundaries across the sector. Novozymes leverages its microbial strain library to dominate inoculant technology leadership. FOMI anchors North African production scale through its organo-mineral integration. Safi Organics Limited specializes in compact, decentralized composting systems for smallholder cooperatives.
Africa biological organic fertilizers comprise live microbial cultures, decomposed plant or animal matter, and natural mineral amendments processed through aerobic composting or anaerobic digestion to restore soil biology and nutrient cycling. These inputs typically carry specified colony-forming unit counts per gram and minimum organic carbon thresholds to ensure agronomic efficacy. Dry fertilizers occupy the largest volume share due to lower transport costs and extended shelf stability across fragmented rural distribution networks. Liquid fertilizers represent the fastest-expanding format, particularly in horticulture and precision drip-irrigation systems where root-zone application demands rapid microbial activation. Seaweed extract formulations command premium positioning in coastal markets with established harvesting infrastructure.
Kenya's Agriculture and Food Authority enforces compulsory organic input certification aligned with East African Community standards, filtering uncertified products from formal channels. Ethiopia's Environmental Protection Authority and South Africa's Department of Agriculture, Land Reform and Rural Development both mandate contaminant thresholds for heavy metals and pathogen loads in packaged organic amendments. Stakeholders must track evolving national organic certification reciprocity agreements and soil carbon measurement protocols that will determine which suppliers retain formal market access.
Market Dynamics
Certification mandates from Kenya's Agriculture and Food Authority and Ethiopia's Environmental Protection Authority are filtering uncertified biological inputs from formal distribution channels, forcing suppliers to rebuild compliance infrastructure or exit regulated markets entirely.
Growth Catalysts
- East African Community Standards:Kenya's compulsory organic input certification creates formal market access for compliant suppliers while squeezing informal competitors into gray channels.
- Soil Degradation in Nigeria's Northern Cereal Belt:Accelerated nutrient depletion across Kano, Kaduna, and Sokoto states drives farmer experimentation with compost-based alternatives to synthetic urea.
- Microbial Inoculant Technology:Advances in nitrogen-fixing and phosphate-solubilizing strain preservation enable longer shelf stability under tropical storage conditions.
Market Restraints
- Input Cost Volatility:Organic substrate prices fluctuate with livestock waste availability and seasonal crop residue collection patterns.
- Supply Concentration Risk:North African production scale concentrates in Morocco and Egypt, creating vulnerability to regional logistics disruptions.
- Technical Shelf-Life Limitation:Live microbial cultures degrade faster in ambient temperatures above 35°C, constraining rural distribution reach.
Strategic Opportunities
- Underpenetrated Smallholder Cooperatives:Decentralized composting systems in Tanzania and Uganda's lake basin regions remain below 15 percent adoption.
- Precision Drip-Irrigation Convergence:Liquid biological fertilizers paired with sensor-based fertigation enable root-zone microbial activation in horticulture.
- South Africa's Carbon Credit Framework:Emerging soil carbon measurement protocols create revenue stacking for verified organic amendment users.
Industry Challenges
- Microbiologist Talent Scarcity:Qualified strain isolation and quality control specialists command premium wages across Nairobi and Johannesburg.
- Certification Timeline Compression:Kenya's Agriculture and Food Authority processing delays extend product registration to 18-24 months.
- Legacy Synthetic Fertilizer Integration:Farmers struggle to calibrate reduced synthetic rates when transitioning to biological supplementation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Biological Organic Fertilizers Market |
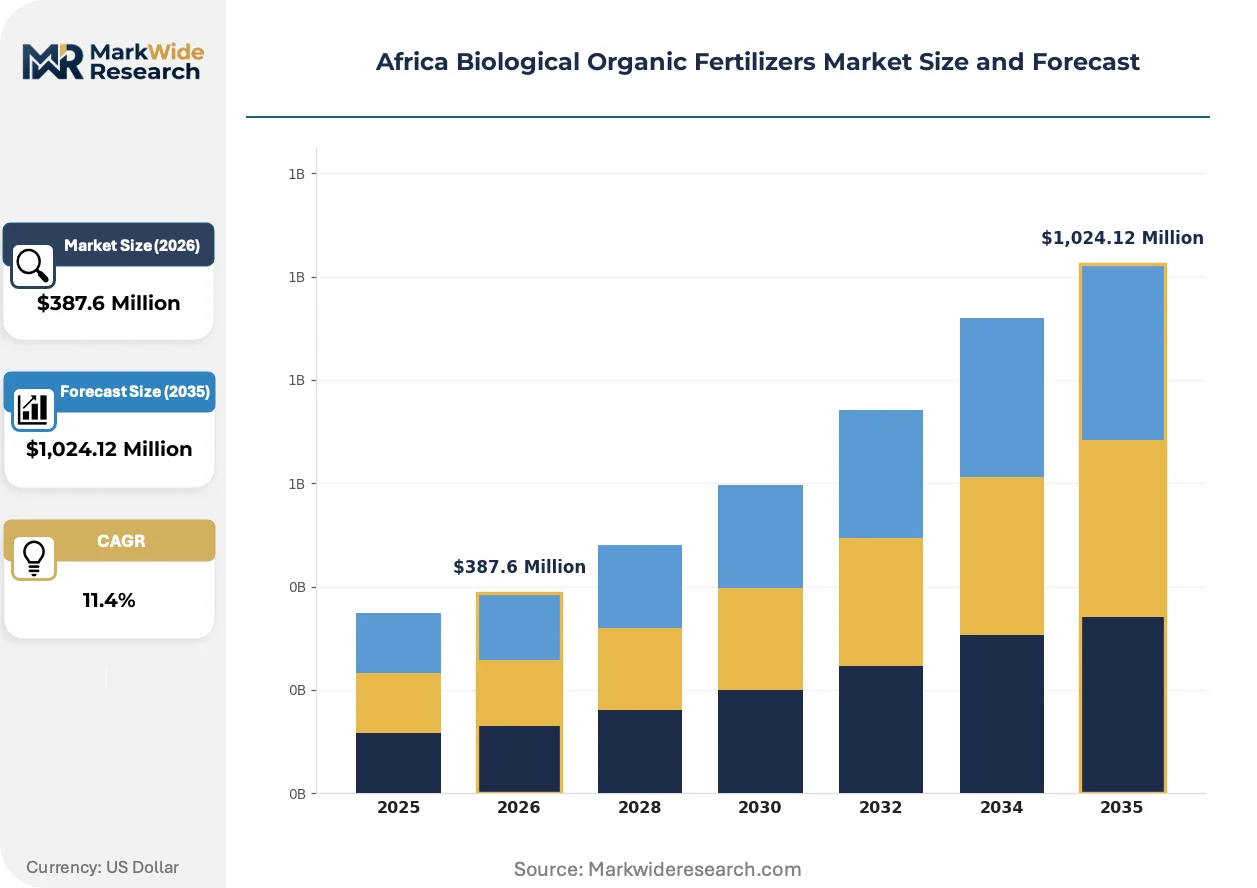
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Dry Fertilizers, Granular Fertilizers, Powder Fertilizers Application: Agricultural Fields, Horticulture, Organic Farming, Home Gardens Raw Material: Compost, Animal Manure, Green Manure, Seaweed Extract Distribution Channel: Direct Sales, Retail Stores, Online Marketplaces, Agricultural Cooperatives |
| Companies Covered | Bioceres Crop Solutions, Novozymes, FOMI (Organo-Mineral Fertilizers Industries), International Panaacea Limited, Rizobacter Argentina SA, Safi Organics Limited, T. Stanes and Company Limited, Symborg, Micro Biological Fertilizer International, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Biological Organic Fertilizers Market Strategic Shifts
Aerobic composting automation and microbial strain banking are compressing production cycles while regulatory reciprocity negotiations between Kenya, Ethiopia, and South Africa reshape formal market boundaries.
Advanced thermophilic composting with forced aeration and real-time temperature monitoring is decomposing organic substrates in 21-28 days versus traditional 90-day windrow cycles. Large-scale estates in Kenya's Rift Valley and Ethiopia's Awash Valley are adopting these systems to meet contract deadlines with export-oriented horticulture buyers. The technology is decomposing price premiums previously commanded by imported European organic fertilizers.
South Africa's Department of Agriculture, Land Reform and Rural Development has tightened heavy metal and pathogen load thresholds for packaged organic amendments. Domestic blenders must now submit third-party laboratory verification for every production batch. Small and mid-scale operators in KwaZulu-Natal and Western Cape are consolidating to share testing costs or exiting packaged goods for bulk commodity sales.
Cooperative procurement collectives in Nigeria's northern cereal belt now aggregate orders across 200-500 member farms to secure volume pricing and direct manufacturer relationships. Traditional agro-dealer networks lose margin as these groups negotiate ex-factory terms. This pattern is most visible in Kano State's groundnut and maize belts where farmer associations have formalized buying committees.
Africa Biological Organic Fertilizers Market Segmentation
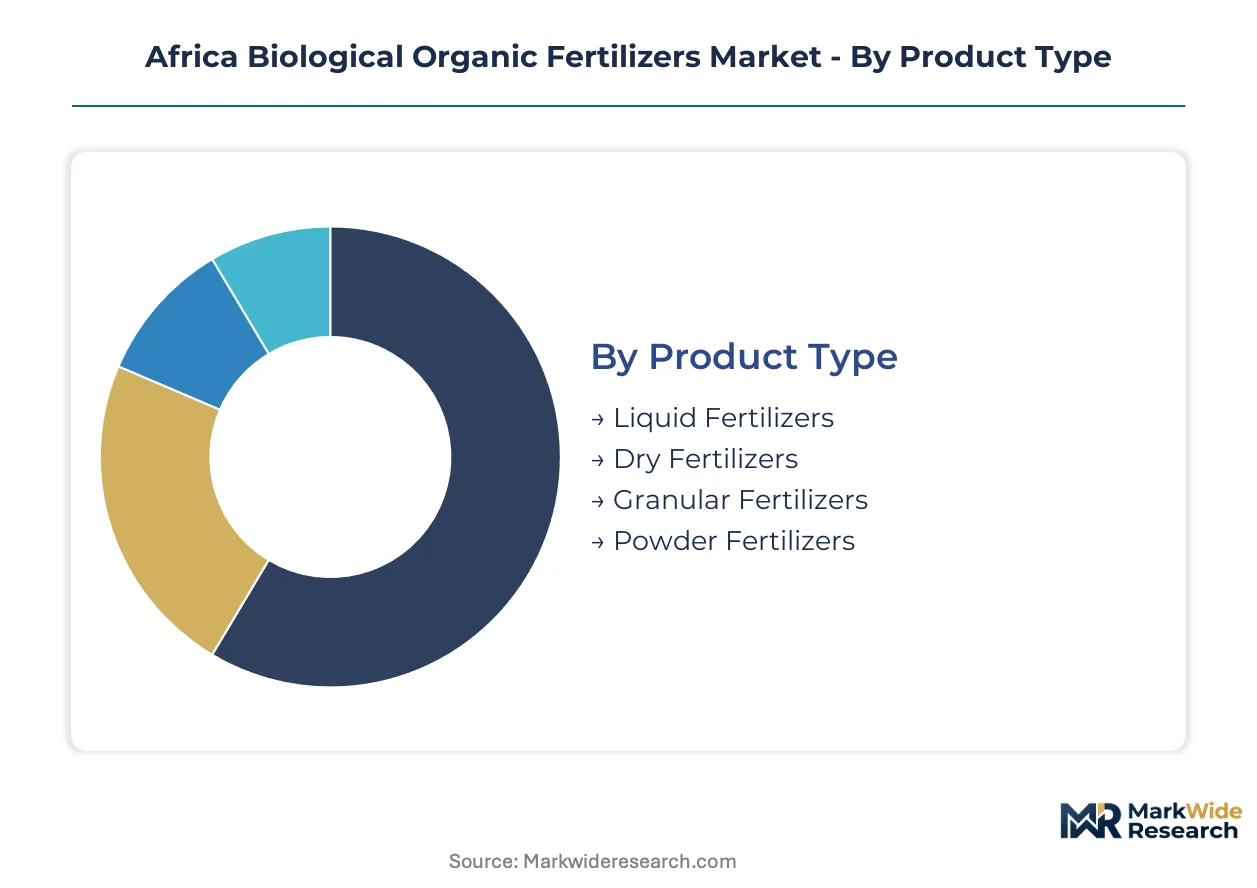
Biological organic fertilizers fragment across four structural dimensions that determine pricing power, shelf stability, and route-to-market economics. Product format dictates logistics costs across Africa's fragmented rural infrastructure. Raw material sourcing anchors regional competitive advantage.
Product Type:
Dry formats dominate domestic consumption across East and West African smallholder belts, while liquid concentrates serve export-oriented horticulture estates with precision irrigation infrastructure.
- Dry Fertilizers:These formulations combine composted organic matter with stabilized microbial inoculants at moisture levels below 15 percent. Demand concentrates in Nigeria's northern cereal belt and Ethiopia's highland maize zones where farmers prioritize transport economy over rapid nutrient release. Extended ambient shelf stability without cold chain dependency sustains penetration in remote distribution nodes.
- Liquid Fertilizers:Suspended microbial cultures and soluble organic extracts enable fertigation compatibility in drip-irrigation systems. Kenyan avocado and flower exporters in Naivasha and Thika drive uptake where root-zone precision application justifies per-liter premiums. Thermal degradation above 35°C constrains rural distribution reach beyond cold chain coverage.
- Granular Fertilizers:Pelletized compost blends with controlled-release coatings suit mechanized broadcasting equipment in South African commercial grain operations.
- Powder Fertilizers:Fine-ground organic amendments integrate into seed coating protocols and nursery substrate mixing in Tanzania's tobacco seedling operations.
Dry fertilizers hold the largest share; momentum sits with liquid concentrates.
Application:
Commercial agriculture absorbs volume at thin margins, while certified organic farming commands specification premiums that reward compliance investment.
- Agricultural Fields:Broadacre cereal and legume production across Nigeria's Kano-Kaduna-Sokoto corridor and Ethiopia's Awash Valley consumes compost-based bulk blends. Procurement runs through cooperative aggregators negotiating ex-factory terms that compress traditional agro-dealer margins.
- Horticulture:Precision-demanding fruit, vegetable, and flower operations in Kenya's Rift Valley and South Africa's Limpopo belt specify colony-forming unit counts and heavy metal thresholds. Kenya's Agriculture and Food Authority certification mandates filter uncertified suppliers from formal export supply chains.
- Organic Farming:Certified operations in Uganda's Lake Victoria basin and Tanzania's Arusha district require third-party verified input chains to maintain EU and US organic export eligibility.
- Home Gardens:Urban consumer segments in Lagos, Nairobi, and Johannesburg purchase packaged retail formats through garden centers and supermarket channels.
Agricultural fields absorb the greatest volume; horticulture climbs the fastest on export certification premiums.
Raw Material:
Feedstock geography determines production cost structure, with coastal access to seaweed and inland livestock density shaping regional specialization.
- Compost:Aerobically decomposed crop residues and municipal organic waste supply the substrate base for East African decentralized composting systems. Thermophilic processing with forced aeration compresses production cycles to 21-28 days versus traditional 90-day windrow methods.
- Animal Manure:Cattle, poultry, and pig waste from concentrated livestock operations in South Africa's Free State and Nigeria's Kaduna state anchor nitrogen-rich formulation. Seasonal availability fluctuations track calving cycles and feed price volatility.
- Green Manure:Leguminous cover crops incorporated prior to planting supply on-farm nitrogen fixation in Ethiopia's conservation agriculture programs.
- Seaweed Extract:Coastal harvesting infrastructure in Morocco and Tunisia enables premium phytohormone formulations for high-value horticulture.
Compost commands the greatest volume; seaweed extract gains fastest on coastal premium positioning.
Distribution Channel:
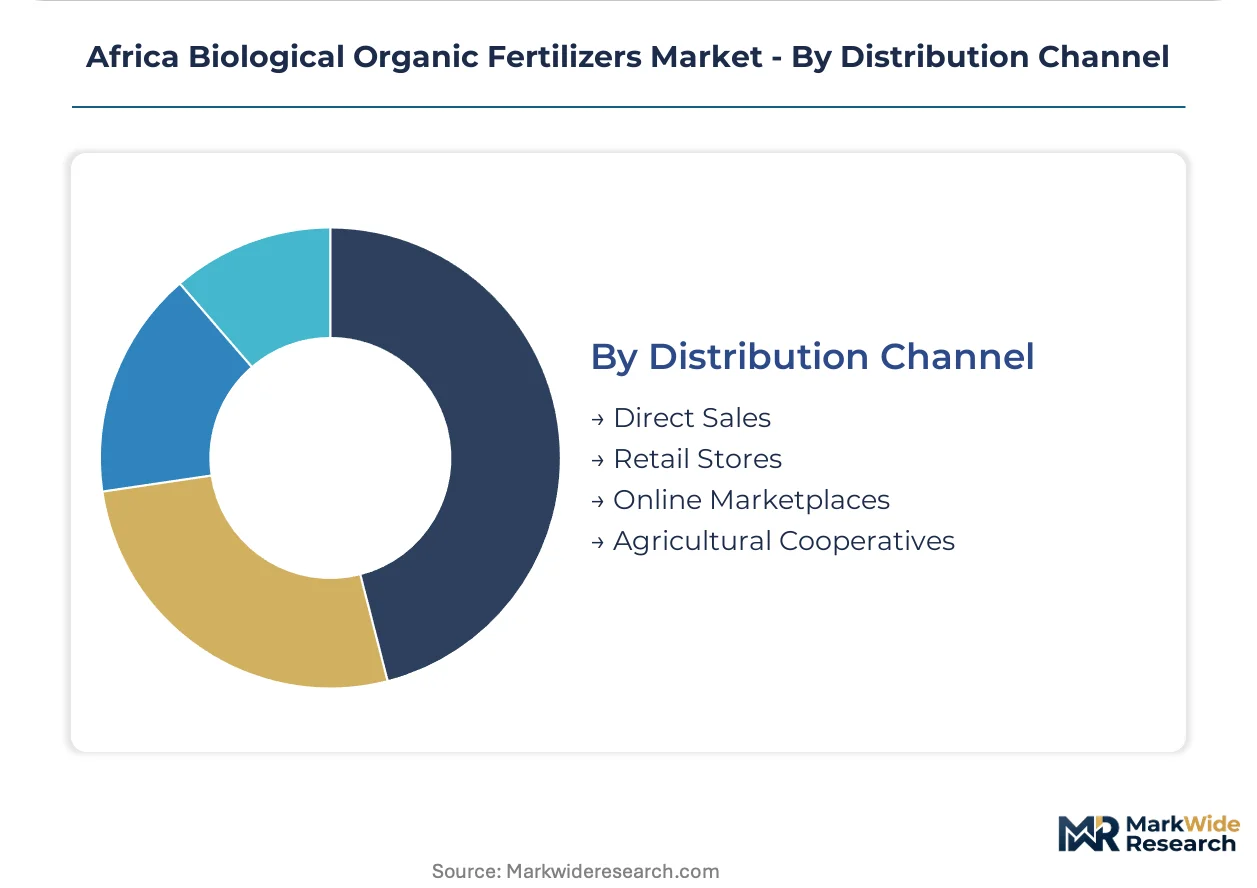
Channel structure determines working capital intensity and price realization, with cooperative aggregation disrupting legacy dealer networks.
- Agricultural Cooperatives:Member-based procurement collectives in Nigeria's groundnut belt aggregate 200-500 farm orders to secure manufacturer-direct pricing. Formal buying committees disintermediate traditional agro-dealer networks and capture margin previously lost to distribution tiers.
- Direct Sales:Large-scale estate operations in Kenya's flower sector and South Africa's commercial grain farms contract directly with blenders for customized formulation batches.
- Retail Stores:Agro-dealer networks remain relevant in fragmented smallholder markets where cooperative penetration lags, particularly in rural Tanzania and Malawi.
- Online Marketplaces:Urban gardening consumers in Johannesburg, Lagos, and Nairobi purchase packaged retail formats through e-commerce platforms with limited rural penetration.
Agricultural cooperatives capture the fastest volume shift; retail stores retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence on European organic fertilizers is narrowing as domestic production scales across East and West African manufacturing clusters. Export-oriented horticulture estates in Kenya and Ethiopia now source certified biological inputs from regional blenders, redirecting procurement spend previously captured by Dutch and Italian suppliers.
Kenya
Avocado and flower exporters in Naivasha and Thika drive specification-grade demand for liquid microbial concentrates compatible with drip-irrigation systems. Kenya's Agriculture and Food Authority enforces compulsory organic input certification aligned with East African Community standards, filtering uncertified products from formal channels. The Rift Valley hosts thermophilic composting operations with forced aeration systems that compress production cycles to 21-28 days.
Nigeria
Soil degradation across Kano, Kaduna, and Sokoto states accelerates farmer experimentation with compost-based alternatives to synthetic urea in the northern cereal belt. Cooperative procurement collectives aggregate orders across 200-500 member farms to secure volume pricing and direct manufacturer relationships. Kano State's groundnut and maize belts have formalized buying committees that disintermediate traditional agro-dealer networks.
Ethiopia
Highland maize zones and Awash Valley horticulture estates consume bulk compost blends and certified organic amendments for export-oriented production. Ethiopia's Environmental Protection Authority mandates contaminant thresholds for heavy metals and pathogen loads in packaged organic amendments. Addis Ababa and the Awash Valley anchor organo-mineral integration capacity serving domestic and regional markets.
South Africa
Commercial grain operations in the Free State and Limpopo belt specify granular and liquid biological fertilizers for mechanized broadcasting and precision application systems. The Department of Agriculture, Land Reform and Rural Development tightened heavy metal and pathogen load thresholds, requiring third-party laboratory verification for every production batch. KwaZulu-Natal and Western Cape blenders are consolidating to share testing costs or exiting packaged goods for bulk commodity sales.
Morocco
Coastal harvesting infrastructure enables premium seaweed extract formulations for high-value horticulture across North African and European export markets. Organo-mineral production scale concentrates in Morocco and Egypt, creating regional supply hubs for biological fertilizer substrates. Casablanca-Rabat corridor operations integrate phosphate rock processing with organic amendment blending for compound fertilizer output.
Africa Biological Organic Fertilizers Market Competitive Environment
Concentration sits with multinational microbial technology specialists and regional organo-mineral producers. The vendor base spans three functional tiers: global enzyme and strain-library developers, North African production-scale integrators, and East African decentralized composting specialists. Strategic moves center on certification infrastructure investment to retain formal market access under tightening national standards, and cooperative direct-procurement relationships that bypass legacy distribution tiers.
Among microbial technology developers, Novozymes anchors the strain-preservation and inoculant technology tier. FOMI occupies the North African organo-mineral integration position. Safi Organics Limited exemplifies the decentralized composting archetype serving smallholder cooperatives. These three represent the dominant competitive positioning vectors: proprietary microbial strain libraries, production scale through mineral-organic integration, and compact distributed systems for cooperative procurement channels.
| Leading Market Players |
|---|
| Bioceres Crop Solutions |
| Novozymes |
| FOMI (Organo-Mineral Fertilizers Industries) |
| International Panaacea Limited |
| Rizobacter Argentina SA |
| Safi Organics Limited |
| T. Stanes and Company Limited |
| Symborg |
| Micro Biological Fertilizer International |
| Others |
Value Chain & Pricing Dynamics
Kenya's Agriculture and Food Authority certification gates formal market access while simultaneously stratifying price tiers between compliant and uncertified suppliers, compressing margins for informal channel operators and rewarding investment in testing infrastructure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in Kenya's Rift Valley flower sector, where export certification requirements command premium-mid-economy pricing differentiation across colony-forming unit specifications and heavy metal thresholds. Price differentiation rests on certification grade alignment with East African Community standards and volume scale aggregation through cooperative procurement committees. Cost compression in economy-tier bulk compost intensifies as Nigerian cooperative buying committees disintermediate traditional agro-dealer networks. Smallholder cooperatives in Tanzania's lake basin regions exhibit highest price sensitivity, while South African commercial grain operations show lowest sensitivity due to mechanized application efficiency gains.
Supply Chain Analysis
Inventory cycles compress to 21-28 days for thermophilic composting operations with forced aeration, while liquid microbial concentrates face thermal degradation constraints above ambient temperatures. Production gravity centers on Morocco, Egypt, and Kenya, with substrate sourcing drawing from livestock waste streams in South Africa's Free State and crop residue collection networks in Ethiopia's highland zones. Single-source vulnerability concentrates in North African organo-mineral integration capacity, where Casablanca-Rabat corridor operations feed regional compound fertilizer demand. Distribution runs through cooperative procurement collectives in Nigeria's northern cereal belt and direct estate contracts in Kenya's export horticulture sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical advisory services and soil carbon verification protocols expand faster than base fertilizer volumes, creating recurring revenue attachment opportunities for compliance-capable suppliers.
For Market Incumbents: Consolidate testing infrastructure sharing arrangements among KwaZulu-Natal and Western Cape blenders to defray South Africa's batch verification requirements, while securing backward integration into livestock waste streams in Nigeria's Kaduna state to buffer seasonal substrate price volatility. Certification investment represents the critical defensive lever against Ethiopian Environmental Protection Authority threshold tightening. For New Entrants and Emerging Players: Lead with decentralized composting system deployment in Tanzania and Uganda's lake basin regions, where cooperative penetration sits below adoption thresholds and technical shelf-life limitations constrain incumbent liquid fertilizer reach. Direct manufacturer relationships with farmer association buying committees in Kano State's groundnut belt offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Reciprocal certification agreements between Kenya, Ethiopia, and South Africa reshape the acquisition landscape toward compliance-capable regional blenders with existing laboratory verification partnerships. Five-to-ten year viability favors organo-mineral integrators with coastal phosphate access and microbial strain banking capabilities. Watch for soil carbon measurement protocol finalization in South Africa as inflection signal for revenue-stacking model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | East African Community standards compliance secures formal channel access against informal competitors. |
| Backward Integration into Livestock Waste | Captive substrate supply in Nigeria's Kaduna state buffers seasonal availability fluctuations. |
| Cooperative Direct Procurement Partnerships | Kano State buying committees disintermediate agro-dealer networks and capture distribution margin. |
| Thermophilic Composting Automation | Forced aeration systems in Kenya's Rift Valley compress production cycles versus traditional windrow methods. |
| Soil Carbon Verification Service Layer | South Africa's emerging measurement protocols enable revenue stacking beyond base fertilizer sales. |
Study Parameters
A spread of perspectives from agronomists at export-oriented horticulture estates, procurement officers at farmer cooperative federations, quality control microbiologists in Nairobi and Johannesburg, and regulatory affairs specialists at national agricultural authorities converged on the working assumptions. Secondary validation drew from East African Community standards documentation, Kenya Agriculture and Food Authority certification registries, Ethiopia Environmental Protection Authority contaminant threshold guidelines, and South Africa Department of Agriculture batch verification records. Bottom-up demand modeling across smallholder cooperative segments triangulated against top-down supply capacity assessments at North African organo-mineral integration facilities.
Segmentation dimensions modeled span product format, application end-use, raw material feedstock, and distribution channel structure across the projection horizon. CAGRs derive from volume-weighted growth rate aggregation at segment level, calibrated against historical adoption curves in comparable agricultural input transitions. Forecast inputs incorporate microbial strain preservation technology advancement curves and cooperative procurement collective formation rates in Nigeria's northern cereal belt.
Forecasts assume regulatory continuity in Kenya's Agriculture and Food Authority enforcement posture, Ethiopia's Environmental Protection Authority threshold mandates, and South Africa's Department of Agriculture verification requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
German Biopesticides Market