
 Lignocellulosic Biomass Market | 2026-2036
Lignocellulosic Biomass Market Size, Share, and Industry Trends Forecast 2026-2036
Lignocellulosic Biomass Market Insights
The lignocellulosic biomass sector is restructuring around a sharp split between premium biochemical-grade feedstocks and commodity combustion fuels. UPM-Kymmene leverages its Nordic forestry assets to control high-purity cellulose streams for bioplastic precursors. WestRock anchors the North American pulp integration chain, converting residual fibers into packaging-grade materials. Novozymes differentiates through enzyme platform specialization, reducing hydrolysis costs for second-generation biofuel producers.
Lignocellulosic biomass consists of cellulose, hemicellulose, and lignin matrix structures derived from non-food plant matter, typically processed through acid pretreatment or enzymatic hydrolysis to release fermentable sugars for downstream conversion. Its primary commercial purpose centers on displacing fossil-derived intermediates in fuels, chemicals, and materials. Agricultural residue dominates feedstock volume due to seasonal abundance and low collection costs, while enzymatic conversion technology captures expanding margin pools as biocatalyst efficiency improves. Thermochemical pathways sustain cost leadership in power generation applications where product purity requirements remain minimal.
The EU Green Deal and REACH framework enforce sustainability certification for biomass sourcing, restricting market access for uncertified imports. The EPA's Renewable Fuel Standard and California's LCFS program shape North American demand by assigning credit value to cellulosic fuel pathways. Stakeholders must monitor evolving lifecycle assessment methodologies, as regulatory bodies on both continents tighten carbon intensity thresholds for feedstock eligibility.
Market Dynamics
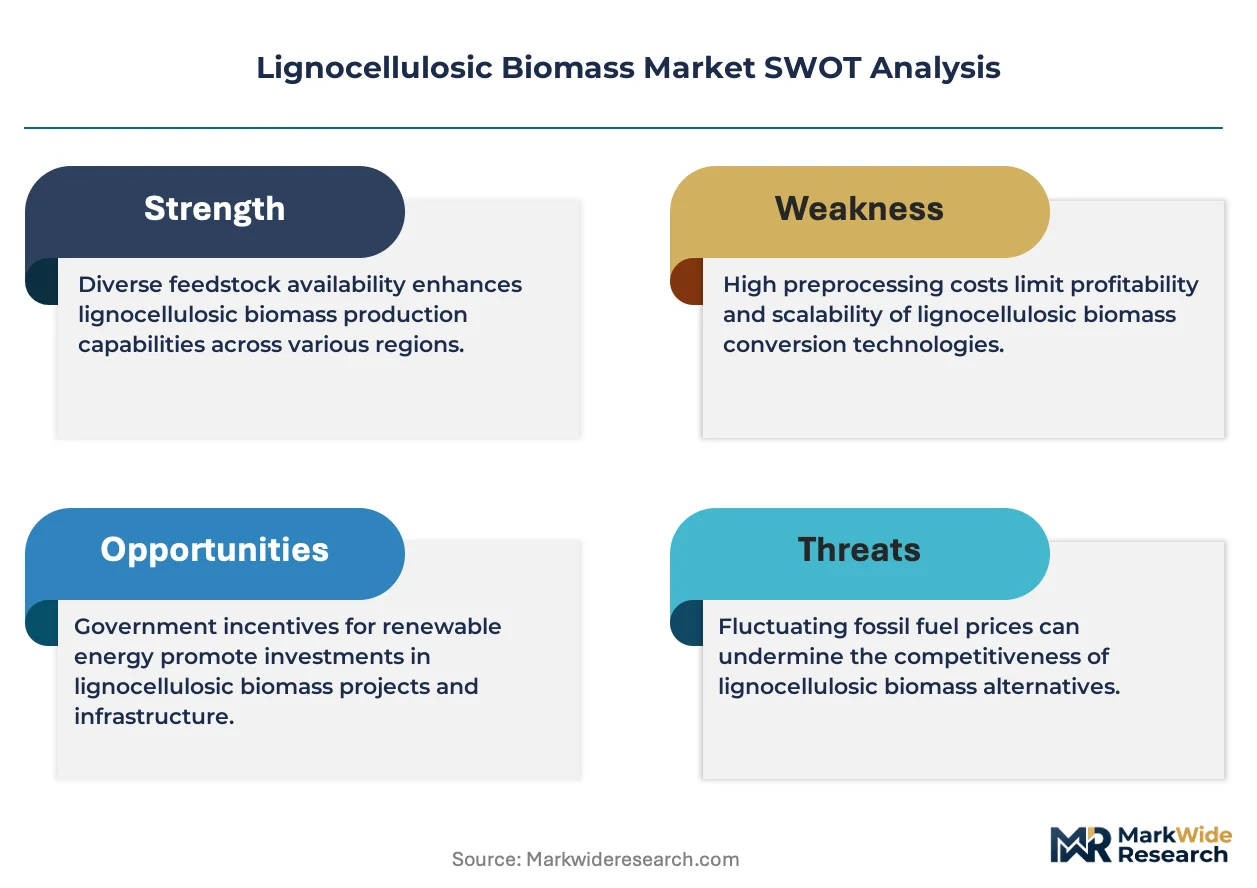
The lignocellulosic biomass sector is pivoting around enzyme cost compression, as Novozymes and DSM-Firmenich drive hydrolysis efficiency gains that determine whether second-generation biofuels achieve cost parity with fossil-derived gasoline.
Growth Catalysts
- EU Green Deal Renewable Fuel Mandates:The EU Green Deal and RED III directive tighten blending obligations for cellulosic ethanol, forcing fuel distributors to secure certified feedstock volumes from Nordic and Baltic forestry operations.
- Brazilian Integrated Biorefinery Clusters:Sugarcane bagasse and eucalyptus residue supply chains in São Paulo state anchor low-cost feedstock aggregation for biochemical conversion platforms.
- Enzymatic Hydrolysis Efficiency Gains:Consolidated enzyme cocktails now achieve 85% cellulose-to-glucose conversion rates, collapsing the historical cost barrier that stalled commercial-scale cellulosic ethanol deployment.
Market Restraints
- Feedstock Supply Concentration Risk:Agricultural residue collection depends on seasonal harvesting windows concentrated in the US Corn Belt and Brazilian Center-West, creating volume volatility during drought cycles.
- CAPEX Intensity of Pretreatment Infrastructure:Dilute acid and steam explosion facilities require $150-250 million per commercial-scale installation, freezing out mid-scale developers without utility-grade balance sheets.
- Lignin Valuation Ceiling:Low-grade lignin remains stranded in combustion applications due to limited purification infrastructure, compressing overall biorefinery economics despite high cellulose yields.
Strategic Opportunities
- Underpenetrated Southeast Asian Feedstock Base:Rice straw and palm empty fruit bunch collection networks in Indonesia and Thailand remain undeveloped, offering first-mover aggregation advantages for enzymatic conversion platforms.
- California LCFS Credit Arbitrage:The California Air Resources Board assigns carbon intensity scores to cellulosic pathways that trade at substantial premiums over conventional ethanol, rewarding low-carbon supply chain configurations.
- Bioplastic Precursor Convergence:Bio-based polyethylene furanoate and polylactic acid producers are sourcing high-purity cellulose streams, creating price premiums over fuel-grade fermentation sugars.
Industry Challenges
- Biochemical Process Engineering Talent Scarcity:Commercial-scale cellulosic ethanol facilities require specialized expertise in simultaneous saccharification and fermentation that remains concentrated among a narrow cohort of academic and industrial researchers.
- ISCC Certification Timeline Compression:Feedstock traceability requirements under the International Sustainability and Carbon Certification scheme demand 12-18 month audit cycles that delay offtake contract execution.
- Legacy Pulp Mill Retrofit Complexity:Kraft pulping infrastructure requires substantial reconfiguration to handle agricultural residues with high silica content, stranding existing capital in Nordic and North American locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignocellulosic Biomass Market |
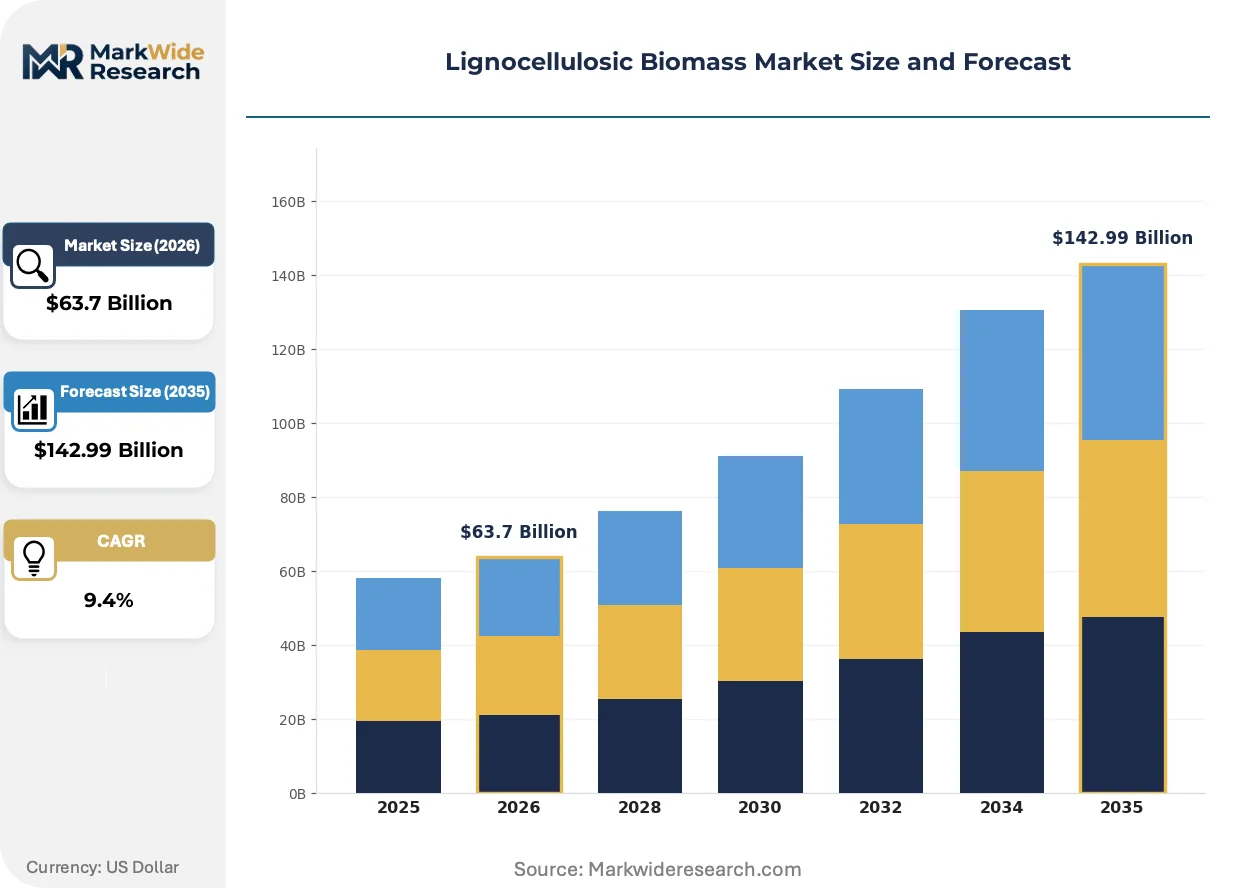
| Market Size in 2026 | $63.7 Billion |
| Market Size in 2035 | $142.99 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Agricultural Residue, Forestry Residue, Herbaceous Energy Crops, Wood Chips, Sawdust Conversion Technology: Thermochemical, Biochemical, Physicochemical, Mechanical, Enzymatic End Use Industry: Bioenergy, Bioplastics, Animal Feed, Pulp & Paper, Textile Manufacturing Product Form: Pellets, Powders, Briquettes, Liquids, Flakes |
| Companies Covered | UPM-Kymmene, WestRock, Nippon Paper Industries, Fortum, Versalis, The Dow Chemical Company, Novozymes, LyondellBasell, Neste, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignocellulosic Biomass Market Trends and Innovations
Consolidated biorefinery design is collapsing the traditional separation between power generation, fuel production, and materials extraction, forcing technology providers to engineer integrated process trains rather than standalone unit operations.
Consolidated bioprocessing platforms that combine enzyme production, cellulose hydrolysis, and fermentation in a single reactor vessel are electrifying project economics for cellulosic ethanol developers. Beta Renewables and Clariant have operationalized this architecture at commercial scale in Crescentino, Italy and Podari, Romania. The technology is electrifying investor appetite for greenfield biorefinery construction, compressing projected payback periods from eight years to under five.
REACH framework amendments under the EU Green Deal now mandate mass-balance accounting for bio-based content claims in packaging and automotive applications. Industrial users must document chain-of-custody from forest or field to finished product, disqualifying spot-market feedstock purchases. Automotive tier-one suppliers in Germany and Sweden are responding by executing ten-year offtake agreements directly with forestry cooperatives.
Long-term feedstock procurement contracts are displacing spot-market purchasing as the dominant sourcing mechanism for biochemical-grade cellulose. Bioplastic producers in the Netherlands and Belgium now require five-year minimum supply commitments with fixed escalators tied to agricultural commodity indices. This shift is most visible in the packaging value chain, where Nestlé and Unilever sustainability targets cascade backward to enforce supply security on their converter networks.
Lignocellulosic Biomass Market Segmentation
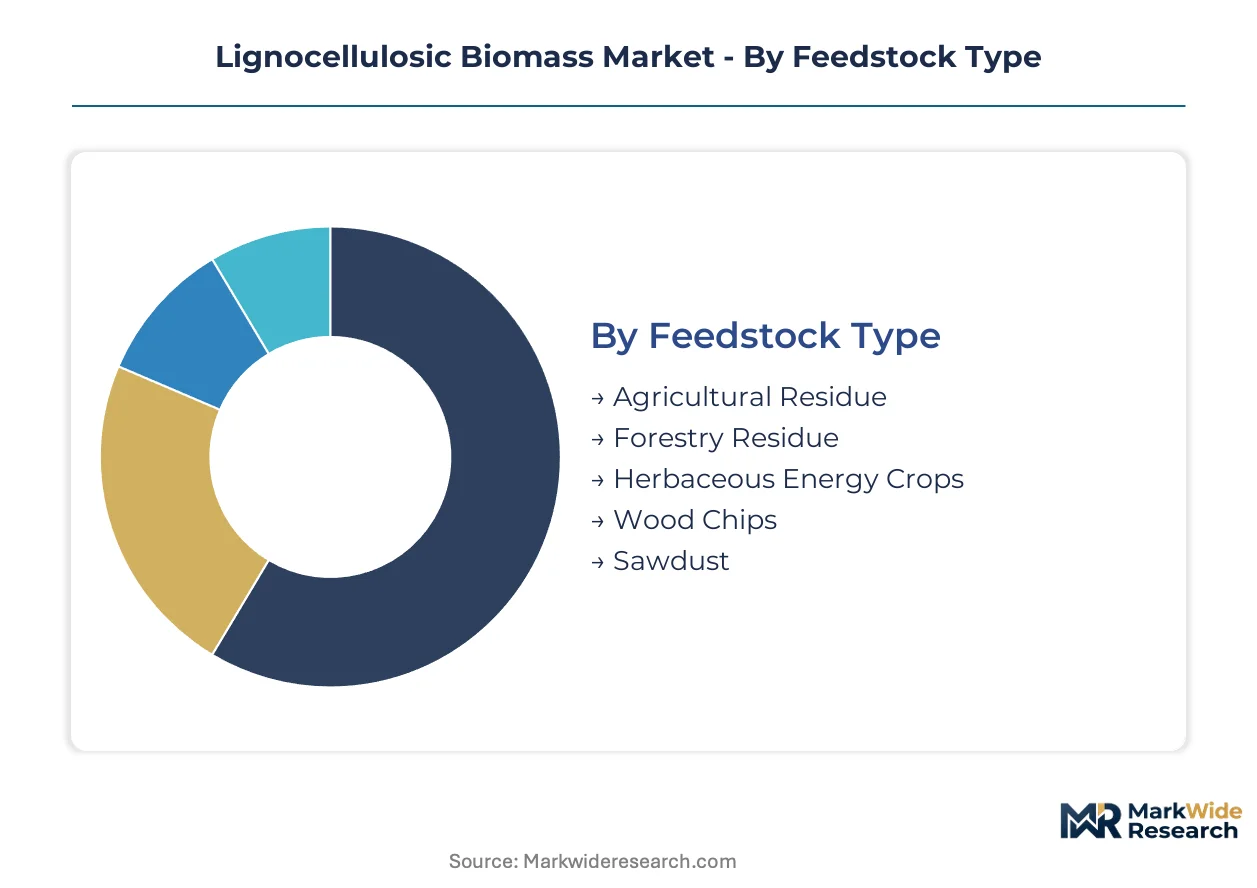
Lignocellulosic biomass markets fragment along conversion technology sophistication and feedstock purity gradients. Each segmentation axis determines capital intensity, regulatory eligibility, and offtake pricing power.
Feedstock Type:
Cellulose crystallinity and silica content define process economics across agricultural and woody matrices.
- Agricultural Residue:Corn stover, wheat straw, and rice husks deliver seasonal volume surges at collection costs below forestry alternatives. Demand concentrates in US Corn Belt biorefineries where EPA Renewable Fuel Standard credits reward cellulosic pathway certification.
- Forestry Residue:Bark, branches, and sawmill waste offer consistent lignin-to-cellulose ratios ideal for biochemical conversion. Nordic forestry cooperatives in Sweden and Finland control premium streams under EU Green Deal sustainability mandates.
- Herbaceous Energy Crops:Miscanthus and switchgrass provide dedicated cultivation with predictable supply schedules.
- Wood Chips:Standardized particle size supports efficient handling in thermochemical gasification systems.
- Sawdust:Fine particle distribution reduces pretreatment energy requirements for pelletization.
Mature deployment sits with Agricultural Residue. Newer deployment is concentrated in Forestry Residue for bioplastic precursor applications.
Conversion Technology:
Process selection locks in CAPEX requirements and product slate flexibility for decades.
- Enzymatic:Cellulase cocktails hydrolyze crystalline cellulose to fermentable glucose at temperatures below 50°C. Novozymes and DSM-Firmenich drive cost compression that enables Brazilian sugarcane bagasse refineries to achieve cellulosic ethanol parity.
- Thermochemical:Gasification and pyrolysis convert entire biomass matrices to syngas or bio-oil without fractionation. Projects in Crescentino, Italy and Podari, Romania deploy consolidated bioprocessing to collapse unit operation counts.
- Biochemical:Acid pretreatment combined with fermentation targets high-purity sugar streams.
- Physicochemical:Steam explosion and solvent extraction separate hemicellulose fractions for specialty chemical feedstocks.
- Mechanical:Size reduction and densification prepare raw biomass for combustion or gasification feed.
Enzymatic platforms are expanding most quickly. Thermochemical retains cost leadership in power generation where purity requirements remain minimal.
End Use Industry:
Application specifications range from bulk thermal value to pharmaceutical-grade polymer precursors.
- Bioenergy:Power and heat applications consume lowest-specification biomass at maximum volume scale. EU member states under RED III directive blend cellulosic ethanol to meet transport decarbonization targets.
- Bioplastics:Polyethylene furanoate and polylactic acid producers demand cellulose purity above 95% with controlled hemicellulose contamination. Netherlands and Belgium converters now require five-year supply commitments with fixed escalators.
- Animal Feed:Lignin-reduced fiber fractions substitute for cereal grains in ruminant nutrition.
- Pulp & Paper:Kraft pulping infrastructure in North America processes residual fibers into packaging-grade materials.
- Textile Manufacturing:Dissolving pulp streams regenerate into viscose and lyocell fibers.
Established offtake dominates Bioenergy. Steepest expansion trajectory belongs to Bioplastics as automotive tier-one suppliers execute direct forestry cooperative agreements.
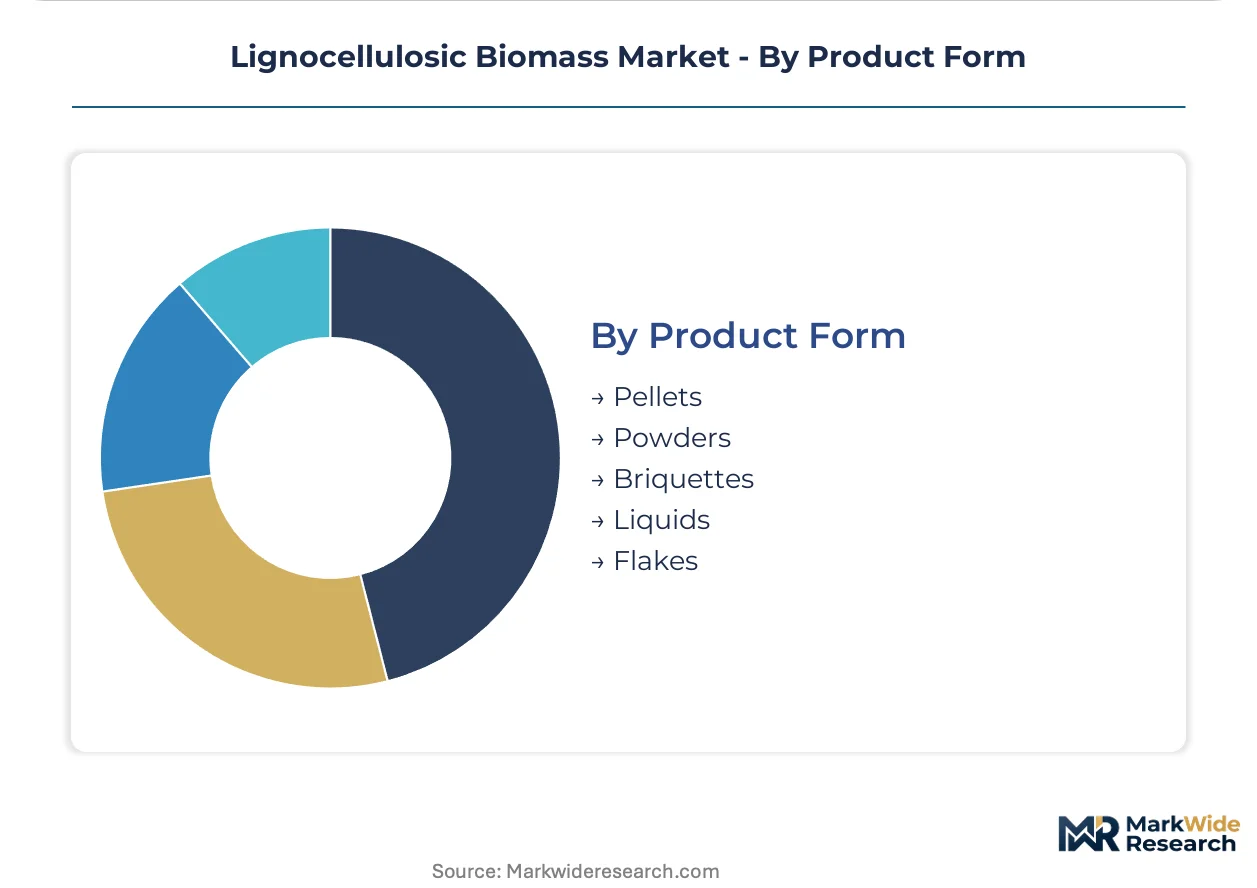
Product Form:
Densification and flow properties determine logistics economics and storage stability.
- Pellets:Standardized 6-8mm diameter enables automated handling in co-firing power plants. Industrial users in Germany and Sweden enforce ISCC certification with 12-18 month audit timelines.
- Liquids:Bio-oil and hydrothermal liquefaction products achieve maximum energy density for marine and aviation fuel precursors. California LCFS credit arbitrage rewards low-carbon intensity scores for cellulosic pathways.
- Powders:Fine grinding supports rapid enzymatic hydrolysis rates.
- Briquettes:Higher density than raw biomass reduces transport costs for distributed heating.
- Flakes:Intermediate sizing for pulping and textile dissolving applications.
Pellet infrastructure represents mature deployment. Liquid products are gaining share fastest as biorefinery clusters integrate hydrotreating for renewable diesel and sustainable aviation fuel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors the world's densest lignocellulosic biorefinery corridor, where sugarcane bagasse and eucalyptus residue aggregation networks supply integrated conversion platforms for cellulosic ethanol and biochemical production.
United States
EPA Renewable Fuel Standard credits reward cellulosic pathway certification, concentrating biorefinery construction in Iowa and Nebraska where corn stover collection costs undercut forestry alternatives. The Department of Energy funds pilot facilities testing consolidated bioprocessing architectures in the Corn Belt.
Brazil
Sugarcane bagasse supply chains in São Paulo state anchor low-cost feedstock aggregation for biochemical conversion platforms. ANVISA regulates bio-based chemical imports while the Renovabio program mandates carbon intensity reductions for fuel distributors sourcing from Center-West agricultural residues.
Germany
REACH framework amendments enforce mass-balance accounting for bio-based content claims in automotive applications, compelling tier-one suppliers in Baden-Württemberg to execute direct offtake agreements with forestry cooperatives. The KBA certifies renewable fuel pathways for transport decarbonization targets.
Sweden
Nordic forestry cooperatives control premium cellulose streams under EU Green Deal sustainability mandates, with biorefinery clusters concentrated in Västra Götaland processing bark and sawmill waste for bioplastic precursor applications. The Swedish Energy Agency subsidizes enzymatic conversion platform deployment.
China
Rice straw collection networks in Jiangsu and Zhejiang provinces remain underdeveloped, offering first-mover aggregation advantages for enzymatic conversion platforms. MIIT's dual carbon goals drive provincial subsidies for agricultural residue utilization in the Yangtze River Delta industrial corridor.
Lignocellulosic Biomass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across feedstock purity and certification tiers, with Nordic forestry cooperatives commanding price premiums for ISCC-certified cellulose streams while agricultural residue aggregators compete on volume scale. The vendor base splits between integrated forest products conglomerates, specialized enzyme technology providers, and regional feedstock aggregators. Three archetypes dominate: asset-heavy forestry owners controlling upstream supply security, technology licensors monetizing hydrolysis efficiency gains, and project developers arbitraging carbon credit premiums in regulated fuel markets. Competitive intensity centers on long-term offtake contract capture and pretreatment technology licensing.
Among Nordic-based forest products conglomerates, UPM-Kymmene and Fortum exemplify the asset-heavy archetype leveraging captive forestry assets for high-purity cellulose stream control. Novozymes occupies a position within the enzyme technology tier, representing specialists in hydrolysis cost compression that enables second-generation biofuel parity. These three companies anchor distinct competitive vectors: upstream resource control, biocatalyst efficiency, and integrated biorefinery operation.
| Leading Market Players |
|---|
| UPM-Kymmene |
| WestRock |
| Nippon Paper Industries |
| Fortum |
| Versalis |
| The Dow Chemical Company |
| Novozymes |
| LyondellBasell |
| Neste |
| Others |
Pricing and Supply Chain Analysis
Captive forestry integration anchors pricing power for Nordic cellulose streams, as UPM-Kymmene and Fortum leverage in-house timber assets to command premiums over spot-market agricultural residue aggregators competing on volume scale.
Pricing Analysis
Yield-based pricing anchors biochemical-grade cellulose contracts, with bioplastic producers paying premiums tied to fermentable sugar recovery rates above 85%. Price differentiation separates ISCC-certified forestry streams from uncertified agricultural residues, with EU Green Deal compliance requirements widening the gap. Cost compression in enzymatic conversion tiers is intensifying because Novozymes and DSM-Firmenich drive hydrolysis efficiency gains. Agricultural residue aggregators in the US Corn Belt exhibit highest price sensitivity, while automotive tier-one suppliers in Germany show lowest sensitivity due to long-term offtake commitments.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement contracts, as Nestlé and Unilever mandate qualified backup suppliers for high-purity cellulose streams to mitigate feedstock concentration risk. Geographic supply concentration centers on Brazil, Sweden, and the United States, where sugarcane bagasse, Nordic forestry residue, and corn stover aggregation networks feed integrated biorefinery clusters. Raw material dependencies rest on cellulase enzyme cocktails, dilute acid pretreatment chemicals, and lignin handling infrastructure. Single-source vulnerability runs through specialized enzyme technology providers. Distribution feeds from forestry cooperatives and agricultural collection networks through long-term contract structures rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock supply constraints prop pricing power, as seasonal harvesting windows and ISCC certification timelines compress available certified volumes below biorefinery demand growth.
For Market Incumbents: Deploy backward integration into captive forestry assets to secure high-purity cellulose streams against emerging agricultural residue aggregators. Fortify position by accelerating ISCC certification coverage across Nordic supply bases before EU Green Deal traceability mandates tighten. Channel control through direct offtake agreements with automotive tier-one suppliers locks out spot-market competitors. For New Entrants and Emerging Players: Begin with underdeveloped rice straw collection networks in Indonesia and Thailand, where first-mover aggregation advantages remain unclaimed. Target enzymatic conversion platforms serving California LCFS credit arbitrage as the most penetrable application. A go-to-market angle anchored to low-carbon intensity scoring commands premium pricing over conventional ethanol pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated biorefinery operators with proven consolidated bioprocessing deployment. Long-term viability favors asset-heavy forestry owners controlling upstream supply security over technology licensors exposed to enzyme cost compression cycles. Watch enzymatic hydrolysis efficiency gains as the inflection signal determining whether cellulosic ethanol achieves cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Captive timber supply secures ISCC-certified cellulose streams for bioplastic precursor contracts. |
| Long-term Supply Agreement | Five-year offtake commitments with fixed escalators satisfy Nestlé and Unilever sustainability targets. |
| Enzyme Platform Licensing | Novozymes technology transfer enables Brazilian sugarcane bagasse refineries to achieve cellulosic ethanol parity. |
| Consolidated Bioprocessing Deployment | Single-reactor architecture at Crescentino and Podari compresses biorefinery payback periods. |
| ISCC Certification Program | Twelve-month audit cycles qualify feedstock volumes for EU Green Deal renewable fuel mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biorefinery plant managers, forestry cooperative procurement leads, enzyme technology R&D directors, and automotive tier-one supplier sustainability officers. Bottom-up modeling triangulated against top-down sectoral aggregates from IEA bioenergy reports, EPA Renewable Fuel Standard credit databases, and EU ETS biomass registry disclosures.
Segment-level granularity modeled feedstock type, conversion technology sophistication, end-use industry specifications, and product form densification across the projection horizon. CAGRs derived from volume trajectory analysis incorporating enzyme cost compression curves, pretreatment CAPEX intensity, and regulatory credit value evolution. Industry-specific inputs included lignin valuation ceilings and consolidated bioprocessing adoption rates.
Underlying measurement precision varies by segment; enzymatic conversion platforms carry tighter precision than thermochemical pathways due to disclosed operational data availability. Forecasts reflect assumptions around EU Green Deal mandate enforcement, California LCFS credit stability, and Brazilian Renovabio program continuity. Deviation in enzyme efficiency gains or ISCC certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Brazil Biofertilizers Market