
 Rhizobium-Based Biofertilizer Market | 2026-2036
Rhizobium-Based Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Rhizobium-Based Biofertilizer Market Analytics
Microbiology talent is rotating toward agricultural biotech from pharmaceutical fermentation, expanding strain-development capacity for commercial inoculant producers. BASF leverages its microbial discovery pipeline to sustain leadership in multi-strain formulations. Rizobacter Argentina anchors South American supply through captive production of regionally adapted Bradyrhizobium and Rhizobium strains. Novozymes competes on enzyme-microbe synergy, extending its bioagriculture platform into nodulation enhancers.
Rhizobium-based biofertilizer denotes a live microbial inoculant containing nitrogen-fixing bacteria of the genus Rhizobium or related genera, typically formulated at colony-forming unit concentrations exceeding 10^9 CFU per gram and applied to legume seeds or soil to establish root-nodule symbiosis that converts atmospheric N2 into plant-available ammonia. Liquid formulations dominate high-volume commodity agriculture for ease of seed-coating integration, while granular and powder variants retain share in smallholder systems lacking precision application equipment. Legume applications, particularly soybean and pulse crops, command the largest revenue pool, though fruit and vegetable segments show faster expansion as protected horticulture adopts biological nutrient management.
The European Union's F-Gas Regulation and Farm to Fork Strategy under its Green Deal are restricting synthetic nitrogen access, while the US EPA and USDA jointly shape biopesticide and biofertilizer registration pathways that determine market entry timelines. India's FSSAI and BIS standards govern microbial load and contaminant thresholds for domestic manufacturers, with the PLI scheme incentivizing domestic strain-bank investment. Stakeholders must monitor how carbon-accounting methodologies treat biological nitrogen fixation, as this classification will determine whether rhizobium inoculants qualify for offset-linked procurement contracts.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing synthetic nitrogen allowances across European agriculture, redirecting procurement toward biological inputs and forcing rapid scaling of rhizobium strain development capacity.
Growth Catalysts
- EU F-Gas Regulation:Tightening synthetic fertilizer caps under the Green Deal are mandating biological nitrogen alternatives across member-state agricultural procurement.
- Brazil's Cerrado soybean belt:Legume cultivation at industrial scale creates concentrated offtake demand for Bradyrhizobium and Rhizobium formulations.
- Carbon-accounting methodologies:Emerging protocols for biological nitrogen fixation are positioning rhizobium inoculants for offset-linked procurement contracts.
Market Restraints
- Strain stability costs:Maintaining colony-forming unit viability above 10^9 CFU per gram through formulation and storage requires cold-chain infrastructure that elevates delivered cost.
- Registration friction:US EPA and USDA joint biofertilizer pathways create multi-year approval timelines that delay market entry for novel strain formulations.
- Synthetic nitrogen substitution threat:Urea and ammonium nitrate retain price competitiveness in markets lacking carbon pricing or regulatory nitrogen caps.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for domestic strain-bank investment are opening captive manufacturing opportunities for regionally adapted rhizobium collections.
- Protected horticulture:Fruit and vegetable segments in controlled-environment agriculture are adopting biological nutrient management faster than field crops.
- Enzyme-microbe convergence:Nodulation enhancers combining microbial inoculants with signaling compounds represent unclaimed white space in premium formulation tiers.
Industry Challenges
- Microbiology talent scarcity:Strain-development capacity constraints persist as agricultural biotech competes with pharmaceutical fermentation for skilled fermentation scientists.
- BIS compliance complexity:India's microbial load and contaminant thresholds require dedicated quality infrastructure that extends certification timelines for new manufacturing facilities.
Report Scope
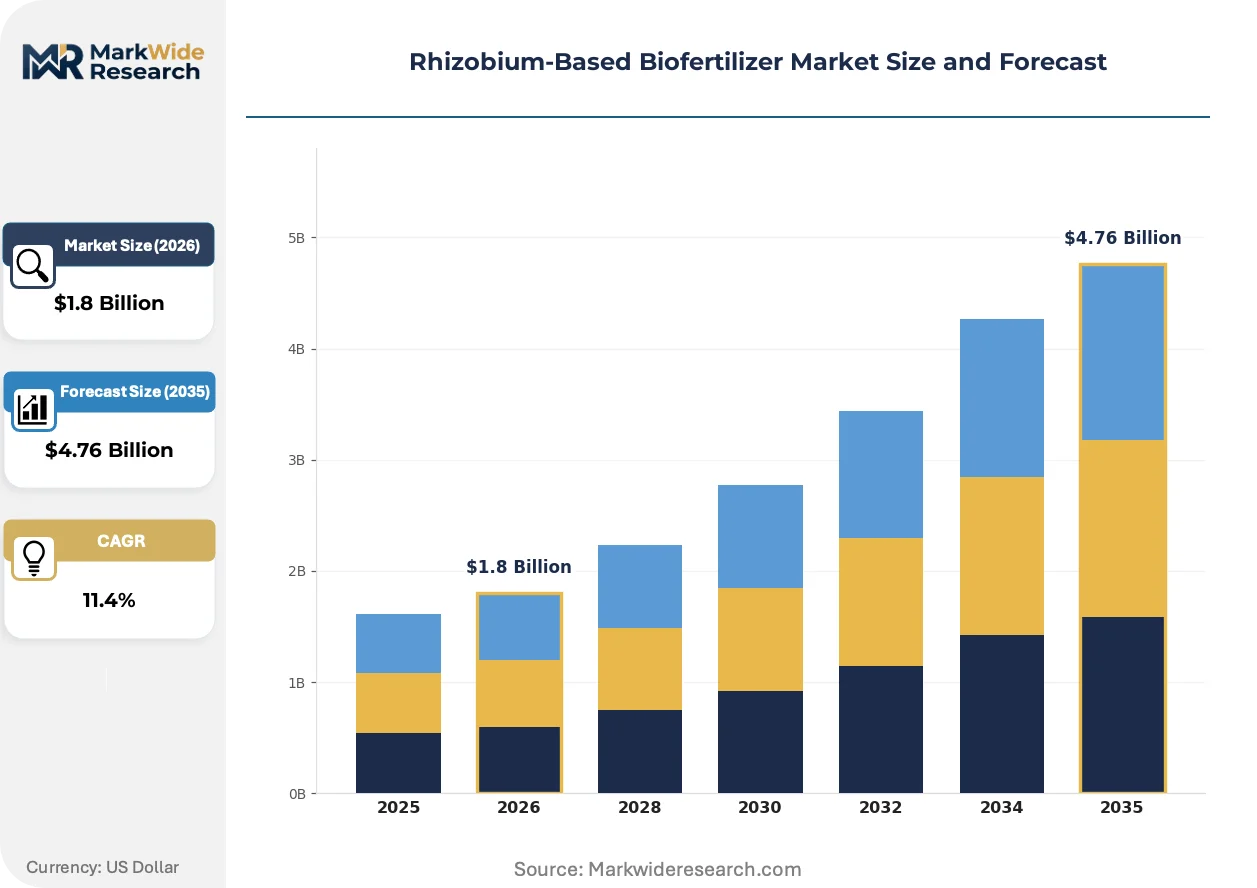
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhizobium-Based Biofertilizer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Capsules Application: Crops, Vegetables, Fruits, Legumes Distribution Channel: Direct Sales, Distributors, Online Retail, Agricultural Supply Stores Formulation: Single Strain, Multi-Strain, Blended, Customized |
| Companies Covered | Lallemand Inc., Rizobacter Argentina, Symborg, Madras Fertilizers Limited, National Fertilizers Limited, BASF, T. Stanes and Company Limited, AgriLife, Novozymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhizobium-Based Biofertilizer Market Evolving Landscape
Formulation science and regulatory chemistry are converging to reshape how rhizobium products reach farmers, with shelf-life extension and precision application commanding R&D priority.
Polymer-based seed-coating technologies are miniaturizing. These micro-encapsulation systems protect rhizobium cells from desiccation and chemical stress during planting. Large-scale commodity operations in Brazil and the US Midwest are adopting liquid formulations with integrated polymer carriers at accelerating rates. This miniaturization of protective matrices is compressing the viability gap between manufacturing and field application.
REACH and F-Gas Regulation compliance costs are restructuring European supplier economics. Synthetic nitrogen price volatility under carbon border adjustment mechanisms is amplifying biological input cost competitiveness. German and French distributors are consolidating procurement around multi-strain formulations that satisfy both agronomic and regulatory requirements in single applications.
Farmer buying patterns are fragmenting across channel types. Traditional agrochemical distributors face disintermediation from direct-to-farm digital platforms and cooperative bulk-purchasing networks. Brazil's Mato Grosso soybean producers are piloting subscription-based inoculant replenishment models that tie formulation delivery to planting schedules rather than annual purchase cycles.
Rhizobium-Based Biofertilizer Market Segmentation
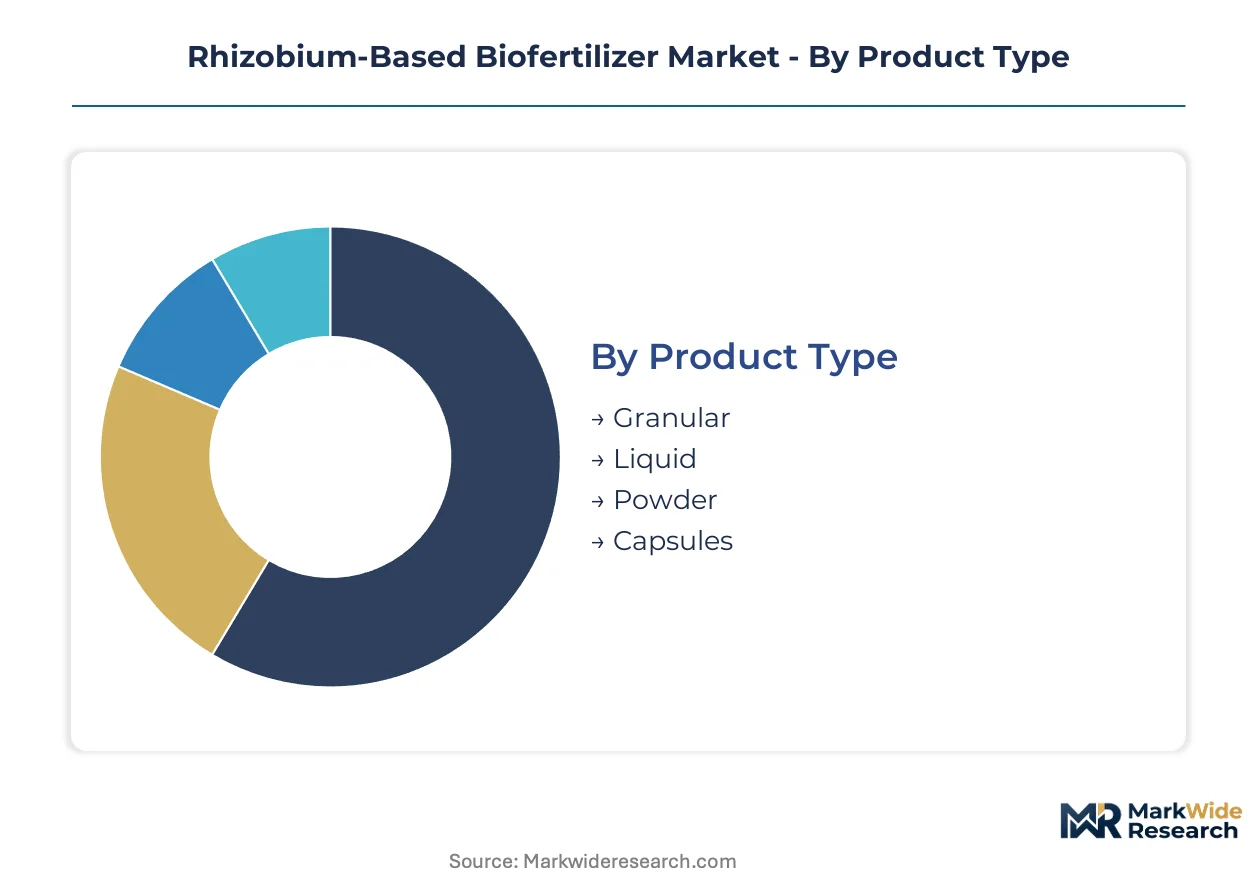
Rhizobium biofertilizer segmentation reflects divergent supply chain economics across formulation types and channel structures. Product characteristics determine cold-chain requirements, while application specificity dictates strain selection and pricing tiers.
Product Type:
Liquid formulations dominate export-oriented supply chains into Brazil and North America, while granular and powder variants serve domestic smallholder markets lacking precision application infrastructure.
- Liquid:Seed-coating integration at concentrations exceeding 10^9 CFU per gram enables seamless deployment in high-volume commodity agriculture across the US Midwest and Mato Grosso soybean belt. Polymer-based micro-encapsulation systems are compressing viability gaps between manufacturing and field application.
- Granular:Soil-direct application formats bypass seed-treatment equipment requirements, concentrating demand in Indian pulse cultivation and African smallholder systems where mechanization remains limited. Cold-chain constraints elevate delivered cost but extend market reach.
- Powder:Shelf-stable carriers suit cooperatives and bulk-purchasing networks in regions with intermittent refrigeration access.
- Capsules:Pre-measured single-plant dosing targets protected horticulture and high-value vegetable operations.
Liquid holds the largest share; momentum sits with granular as cold-chain infrastructure expands.
Application:
Cost tiers stratify sharply across crop categories, with legume cultivation commanding premium formulation pricing while fruit and vegetable segments absorb nodulation enhancers at steeper per-hectare rates.
- Legumes:Soybean, common bean, and pulse crops generate concentrated offtake for Bradyrhizobium and Rhizobium formulations at industrial scale. Brazil's Cerrado and the North American plains anchor volume demand.
- Crops:Cereal and oilseed rotations adopting rhizobium co-inoculation are expanding addressable market beyond traditional legume hosts.
- Vegetables:Protected horticulture in the Netherlands and Spain is absorbing biological nutrient management faster than field crops, with controlled-environment agriculture justifying premium enzyme-microbe synergies.
- Fruits:Perennial systems in Italy and Greece are piloting customized multi-strain formulations for tree-nut and citrus applications.
Legumes retain dominant volume; vegetables are climbing the fastest as greenhouse acreage expands.
Distribution Channel:
Customer-type fragmentation is accelerating, with digital platforms disintermediating traditional agrochemical distributors in concentrated farming regions while cooperative networks sustain smallholder access.
- Distributors:German and French distributors are consolidating procurement around multi-strain formulations that satisfy both agronomic and EU F-Gas regulatory requirements.
- Direct Sales:Subscription-based replenishment models in Brazil tie formulation delivery to planting schedules rather than annual purchase cycles.
- Agricultural Supply Stores:Traditional retail channels retain share in regions with established dealer relationships and credit financing.
- Online Retail:Digital platforms are capturing share among younger farmers and mid-scale operations seeking price transparency.
Distributors command current volume leadership; direct sales channels are gaining share fastest through subscription mechanics.
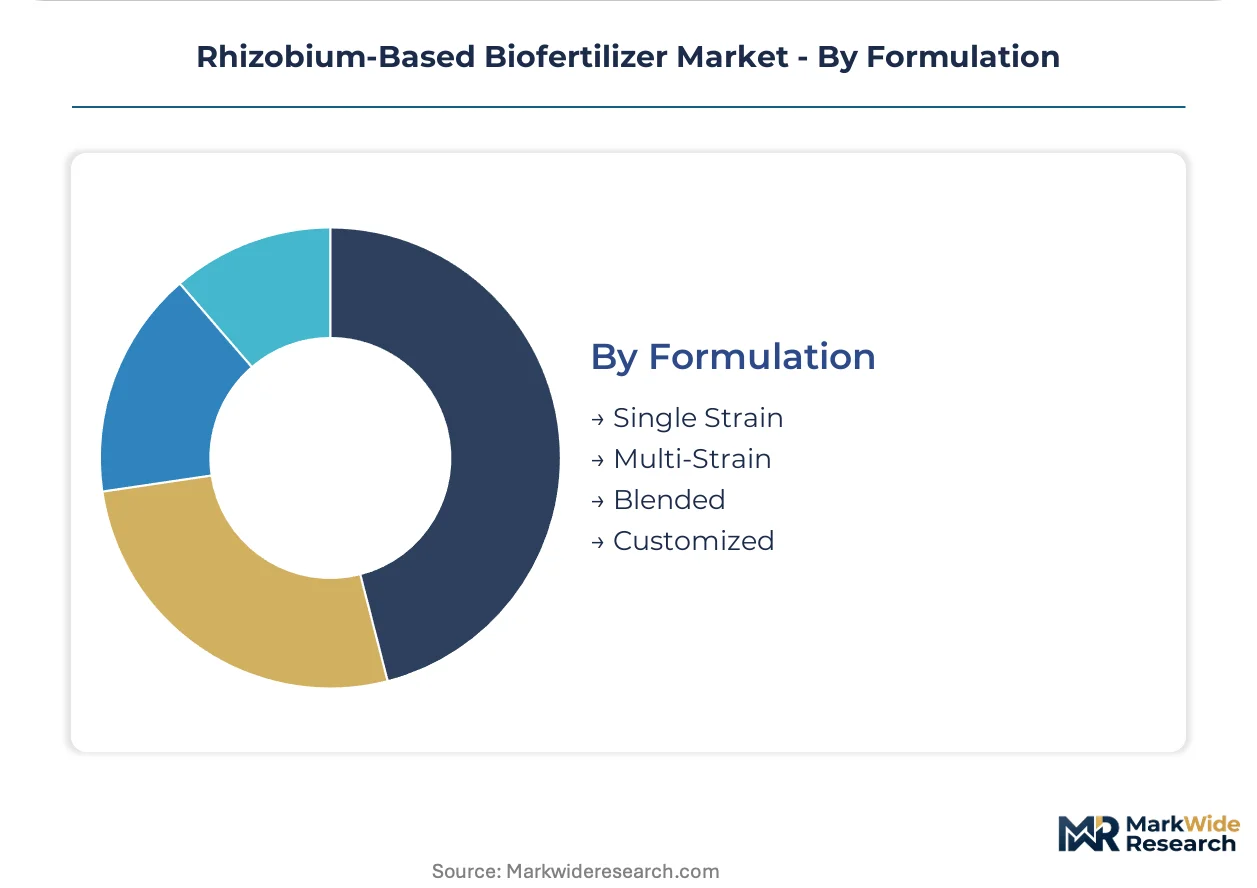
Formulation:
Margin structures diverge between standardized single-strain commodities and customized blends requiring captive strain-bank investment and regulatory navigation.
- Multi-Strain:Broad-host-range combinations reduce farmer decision complexity and align with EU procurement consolidation trends. BASF leverages microbial discovery pipelines to sustain leadership in this tier.
- Single Strain:Regionally adapted Bradyrhizobium japonicum and Rhizobium leguminosarum collections anchor South American supply through captive production.
- Blended:Co-formulation with phosphorus-solubilizing microbes extends functional claims beyond nitrogen fixation alone.
- Customized:Strain matching to local soil microbiomes and host genotypes commands premium pricing in high-value export crop systems.
Multi-strain formulations hold the largest share; customized blends show steepest expansion trajectory as precision agriculture advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA and Brazil's Ministry of Agriculture anchor the dominant geography for rhizobium biofertilizer demand, with the Cerrado soybean belt generating concentrated offtake that shapes global strain development priorities.
Brazil
The Cerrado region and Mato Grosso state drive industrial-scale Bradyrhizobium consumption for soybean cultivation. ANVISA registration pathways for biological inputs determine market entry timelines for imported formulations. Mato Grosso producers pilot subscription-based inoculant replenishment models tied to planting schedules.
United States
EPA and USDA joint biofertilizer registration pathways create multi-year approval timelines that filter novel strain entrants. The North American plains expand pulse crop inoculant use as nitrogen-fixation alternatives to synthetic inputs. Iowa and Illinois soybean operations integrate liquid seed-coating formulations at scale.
India
BIS microbial load standards and FSSAI contaminant thresholds govern domestic manufacturing quality infrastructure. The PLI scheme incentivizes captive strain-bank investment for regionally adapted rhizobium collections. Maharashtra and Gujarat pulse cultivation absorbs granular soil-direct application formats where mechanization remains limited.
Germany
REACH and EU F-Gas Regulation compliance costs restructure supplier economics toward multi-strain biological formulations. The Farm to Fork Strategy mandates procurement redirection from synthetic nitrogen toward certified biofertilizers. Bavarian distributors consolidate procurement around formulations satisfying both agronomic and regulatory requirements.
Argentina
The Pampas grain belt sustains demand for regionally adapted Rhizobium leguminosarum strains in common bean and soybean rotations. National agricultural biotechnology frameworks support captive production of Bradyrhizobium collections. Buenos Aires province anchors South American supply chain infrastructure for strain preservation and formulation.
Rhizobium-Based Biofertilizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated multi-strain formulation specialists competing against regional single-strain producers. The vendor base separates into three strategic tiers: global agrochemical conglomerates with microbial discovery pipelines, mid-cap regional specialists with captive strain banks, and domestic fertilizer incumbents leveraging distribution reach. Dominant competitive moves include backward integration into strain preservation infrastructure and geographic licensing partnerships to bypass registration friction.
Within the regional specialist tier, Rizobacter Argentina exemplifies captive production of locally adapted Bradyrhizobium and Rhizobium strains for South American supply security. BASF and Novozymes occupy positions on the technology-vector, with the former leveraging microbial discovery pipelines and the latter competing on enzyme-microbe synergy in nodulation enhancers. Lallemand Inc. represents the fermentation-science archetype, with capabilities rotating from pharmaceutical applications toward agricultural strain development.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Rizobacter Argentina |
| Symborg |
| Madras Fertilizers Limited |
| National Fertilizers Limited |
| BASF |
| T. Stanes and Company Limited |
| AgriLife |
| Novozymes |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Brazilian soybean cooperatives and Argentine strain banks lock in both supply access and price visibility across planting cycles, insulating buyers from spot-market volatility while committing producers to cold-chain infrastructure investment. These arrangements concentrate procurement power among Mato Grosso bulk purchasers and compress margins for formulation specialists lacking captive production.
Pricing Analysis
Brazil-Argentina price spreads exceed those between European and Indian markets due to freight differentials and ANVISA registration cost recovery. Three-tier pricing structure across premium multi-strain formulations, standard single-strain commodities, and economy bulk powders reflects certification grade and cold-chain reliability. Pricing pressure stems from urea price competitiveness in markets lacking carbon pricing. Smallholder systems in India and Africa show highest price sensitivity; protected horticulture operations in the Netherlands absorb premium enzyme-microbe synergies with least resistance.
Supply Chain Analysis
Cold-chain infrastructure gaps between Buenos Aires formulation plants and Mato Grosso application sites constitute the dominant chokepoint, with shelf-life degradation risk elevating insurance and expedited logistics costs. Supply concentrates in Argentina, Brazil, and India, with strain preservation capabilities drawing from specialized fermentation media and polymer carrier inputs. Single-source vulnerability runs through regionally adapted Bradyrhizobium collections held by captive producers. Distribution runs through agricultural cooperatives and direct-to-farm digital platforms, bypassing traditional distributor markups in concentrated farming regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: multi-year EPA-USDA and ANVISA approval timelines create switching costs that protect incumbent strain banks from rapid competitive displacement.
For Market Incumbents: Compound regulatory moats by accelerating novel strain submissions ahead of F-Gas Regulation enforcement deadlines in Europe. Prioritize backward integration into cryopreservation infrastructure to defend against emerging platform-based entrants offering subscription replenishment models. BASF and Novozymes should extend enzyme-microbe synergy patents before Indian PLI scheme recipients achieve comparable formulation science. For New Entrants and Emerging Players: Lead with protected horticulture vegetable applications in Spain and the Netherlands, where greenhouse biological nutrient management penetration lags technical feasibility and buyer education gaps create accessible white space. Target nodulation enhancer co-formulations as the most penetrable premium tier, leveraging direct-to-farm digital channels to bypass entrenched distributor relationships in commodity legume segments. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regional specialists with captive strain banks and established ANVISA or EPA registration pathways, as these assets compound in scarcity value across the analysis window. Watch for carbon-accounting methodology rulings on biological nitrogen fixation as the inflection signal determining offset-linked procurement contract eligibility and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Bank Acquisition | Captive preservation of regionally adapted Bradyrhizobium collections locks in ANVISA registration advantages for Brazilian supply. |
| Cold-Chain Partnership | Alliance with refrigerated logistics operators compresses viability gaps between Argentine production and Mato Grosso application. |
| Enzyme-Microbe R&D Expansion | Nodulation enhancer development extends functional claims beyond nitrogen fixation into premium horticulture tiers. |
| Direct-to-Farm Platform Launch | Subscription replenishment models disintermediate traditional distributors and capture planting-schedule data for demand forecasting. |
| Carbon Certification Investment | Third-party biological nitrogen fixation protocol alignment positions formulations for offset-linked procurement contracts under EU Green Deal. |
Research Methodology
A standing panel of fermentation science directors, agricultural cooperative procurement managers, regulatory affairs specialists at ANVISA and EPA, and strain-bank curators at Argentine and Indian research institutes provided ongoing calibration against field conditions. Primary interviews combined with secondary validation from FAO agricultural input databases, BIS microbial standard filings, EU F-Gas Regulation implementation reports, and customs trade data on biological inoculant flows. Bottom-up strain-production capacity estimates triangulated against top-down legume acreage projections and application-rate assumptions.
Consistency checks validated volume and value outputs against external benchmarks including FAO fertilizer consumption surveys and national agricultural biotechnology association production reports. The analytical framework modeled formulation type, crop application, distribution channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segmented growth rate blending weighted by addressable acreage expansion and substitution elasticity for synthetic nitrogen. Industry-specific inputs included cold-chain infrastructure buildout trajectories and carbon-accounting protocol adoption timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement, PLI scheme continuity in India, and stable ANVISA biological input pathways would require recalibration. Forecasts reflect assumptions on strain viability maintenance, farmer education progress, and synthetic nitrogen price volatility. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and biological nitrogen fixation certification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
United States Biocontrol Agents Market