
 Water Cooler Market | 2026-2036
Water Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Water Cooler Market Intelligence
A widening capital-intensity divergence between point-of-use system manufacturers and bottled cooler assemblers is unwinding legacy competitive positions across the industry. Primo Water Corporation leverages its direct-to-consumer refill network to sustain recurring revenue density in North American retail corridors. Waterlogic Holdings Ltd. anchors its European position through plumbed-in filtration specialization, while Midea Group dominates mass-market electric unit production through captive appliance manufacturing scale.
Water coolers are electromechanical dispensing appliances that condition potable water through thermoelectric or compressor-based cooling to temperatures between 4°C and 10°C, with heating variants maintaining 85°C to 95°C for commercial tea and instant-beverage preparation. Point-of-use systems connect directly to municipal plumbing, eliminating bottle logistics while requiring activated-carbon or reverse-osmosis filtration cartridges rated for specific contaminant reduction. Bottleless units command higher installed margins due to recurring filter replacement revenue, whereas bottled variants retain volume leadership in emerging retail channels where plumbing infrastructure remains underdeveloped. Energy-efficient compressor technology is displacing thermoelectric cooling in commercial specifications, driven by operating cost scrutiny in educational and industrial end-use contracts.
The United States EPA Energy Star program and NSF/ANSI 61 drinking water system standards shape product certification requirements and channel access for electric and point-of-use categories. China's SAMR enforces GB standards for electrical appliance safety and water-contact materials, while the EU Ecodesign Directive and REACH chemical restrictions govern material composition and efficiency labeling for units sold across member states. Stakeholders must monitor evolving refrigerant phase-down schedules under the Kigali Amendment, as hydrofluorocarbon transitions will force compressor redesigns and supplier qualification changes across all major manufacturing bases.
Market Dynamics
Compressor-based cooling technology is displacing thermoelectric systems across commercial water cooler specifications, driven by EPA Energy Star efficiency mandates and operating cost scrutiny from educational and industrial procurement teams.
Growth Catalysts
- EPA Energy Star tightening:Revised compressor efficiency thresholds force manufacturers toward variable-speed refrigeration systems, accelerating replacement cycles in US commercial installations.
- Corporate plastic-waste reduction:Campus sustainability mandates eliminate bottled delivery logistics, concentrating procurement toward plumbed-in filtration systems with activated-carbon cartridges.
- China eastern corridor development:Commercial real estate expansion in Shanghai, Suzhou, and Hangzhou drives bulk point-of-use procurement for manufacturing and logistics facilities.
Market Restraints
- Refrigerant transition costs:Kigali Amendment hydrofluorocarbon phase-down schedules force compressor redesigns and supplier requalification across all major manufacturing bases.
- Filter cartridge standardization gaps:Proprietary connection geometries lock buyers into single-source replacement schedules, limiting price competition in the aftermarket.
- Plumbing infrastructure dependency:Bottleless unit penetration stalls in emerging retail channels across Southeast Asia and sub-Saharan Africa where municipal water connections remain unreliable.
Strategic Opportunities
- India commercial real estate:Underpenetrated point-of-use installation in Bengaluru and Hyderabad tech campuses offers first-mover positioning before BIS electrical safety enforcement tightens.
- IoT-enabled predictive maintenance:Sensor-integrated filtration systems enable usage-based cartridge replacement billing, shifting revenue from hardware to recurring service contracts.
- EU Ecodesign Directive expansion:Efficiency labeling mandates create premium positioning for heat-pump-based hot water systems in German and French office markets.
Industry Challenges
- Refrigeration technician scarcity:Variable-speed compressor diagnostics require specialized training that vocational programs in Eastern Europe and Latin America have not scaled to match equipment complexity.
- NSF/ANSI 61 certification timelines:Drinking water system material safety testing creates 14-18 month product launch delays for new polymer formulations.
- Legacy thermoelectric inventory:Distributor channel stuffing of obsolete cooling technology blocks working capital and distorts price signaling in mid-market segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Cooler Market |
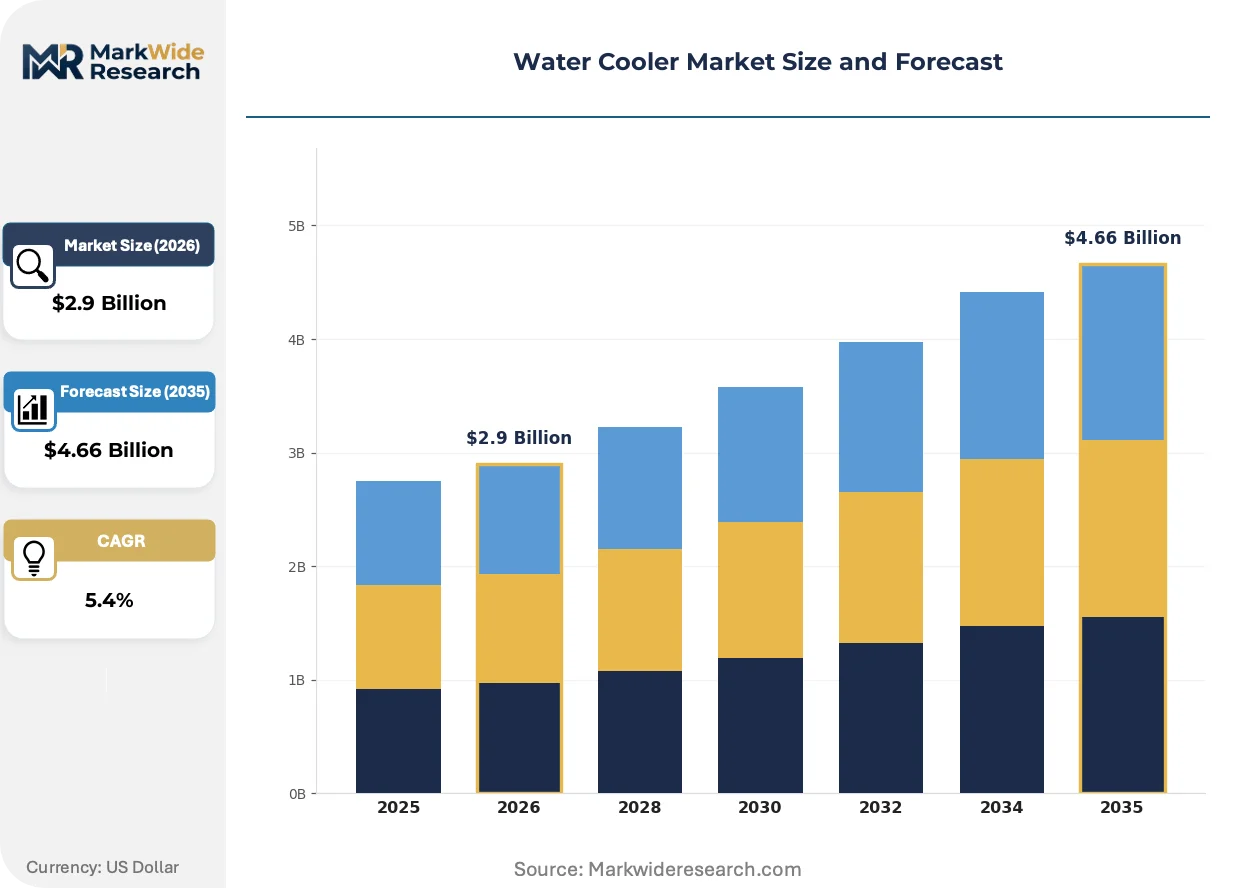
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Use, Bottled, Bottleless, Floor Standing Technology: Electric, Manual, Solar, Energy Efficient End User: Residential, Commercial, Industrial, Educational Distribution Channel: Retail, Online, Direct Sales, Wholesale |
| Companies Covered | Primo Water Corporation, Waterlogic Holdings Ltd., Clover Co. Ltd., Blue Star Limited, Voltas Ltd., Oasis International, Avalon Water Coolers, Culligan International Co., Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Cooler Market Strategic Shifts & Innovations
Water cooler technology is converging with building management systems and sustainability tracking platforms, transforming standalone appliances into networked infrastructure components.
Heat-pump-based hot water generation is fragmenting the traditional electric-resistance heating segment across European commercial specifications. German facility managers specify coefficient-of-performance ratings above 2.5 for tea-preparation units in corporate kitchens. This thermal efficiency hierarchy is compressing margins for conventional heating-element manufacturers while opening service-revenue streams for heat-pump maintenance specialists.
REACH chemical restrictions on water-contact materials are forcing polymer reformulation across EU-bound product lines. Manufacturers must eliminate bisphenol-A and specific phthalate plasticizers from reservoir and tubing assemblies. Italian and Spanish component suppliers are accelerating bio-based polymer qualification to maintain CE marking access ahead of 2025 enforcement deadlines.
Facility managers are consolidating vendor relationships through single-source water service contracts that bundle filtration, cooling, heating, and IoT monitoring. This procurement compression displaces fragmented equipment-only purchasing in US healthcare and educational sectors. The bundled model concentrates volume with full-service providers in Texas and California hospital systems where total-cost-of-ownership reporting dominates capital allocation.
Water Cooler Market Segmentation
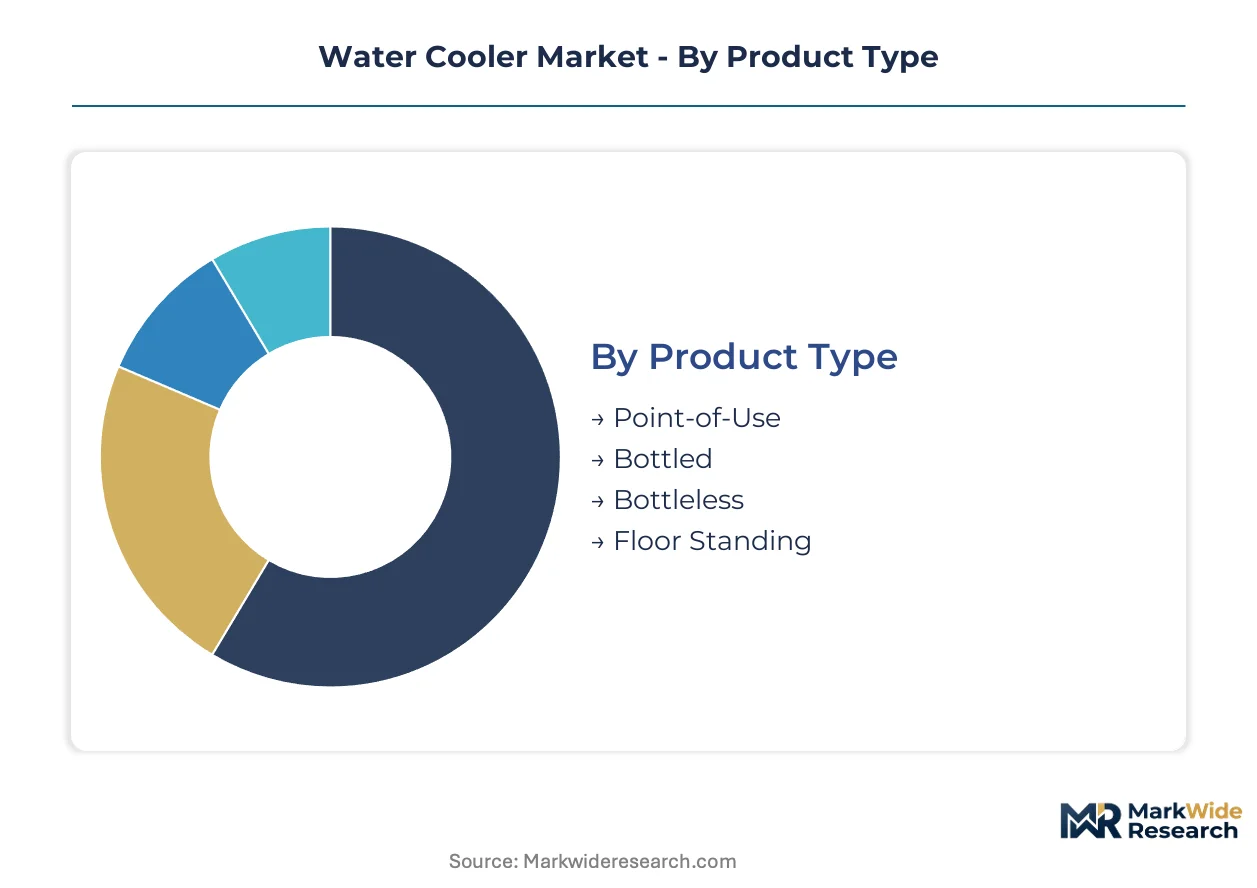
Water cooler procurement channels fragment sharply between plumbed-in commercial contracts and retail bottled-unit transactions. Channel mix determines margin structure, service revenue potential, and regulatory exposure across each segment category.
Product Type:
Point-of-use systems flow through direct-sales and wholesale channels to corporate buyers, while bottled units dominate retail and online paths to residential endpoints.
- Point-of-Use:Plumbed-in filtration systems connect directly to municipal water lines, eliminating bottle logistics. Corporate campuses in Shanghai and Suzhou drive bulk procurement through facilities management contracts with activated-carbon cartridge replacement schedules.
- Bottled:Removable bottle reservoirs accommodate locations lacking reliable plumbing infrastructure. Southeast Asian retail channels and sub-Saharan African commercial districts sustain volume leadership where municipal connections remain underdeveloped.
- Bottleless:Countertop plumbed units target small-office installations with space constraints. Direct-sales teams in Texas hospital systems bundle these with filtration service contracts.
- Floor Standing:Freestanding cabinet designs serve high-traffic industrial break rooms and educational cafeterias. German facility managers specify these for tea-preparation zones in corporate kitchens.
By volume, Bottled leads. By growth pace, Point-of-Use is expanding most quickly.
Technology:
Cost tier separates compressor-based electric systems from thermoelectric and manual alternatives, with efficiency mandates compressing mid-market positioning.
- Electric:Compressor-based cooling achieves temperatures between 4°C and 10°C through variable-speed refrigeration. EPA Energy Star tightening forces manufacturers toward these systems in US educational and industrial procurement.
- Manual:Non-electric gravity-fed dispensers serve off-grid locations and emergency backup scenarios. Sub-Saharan African rural distribution channels sustain niche demand where electrical infrastructure is unreliable.
- Solar:Photovoltaic-powered thermoelectric cooling targets remote industrial sites and agricultural operations. Indian commercial real estate in Bengaluru tech campuses experiments with solar-hybrid specifications ahead of BIS electrical safety enforcement.
- Energy Efficient:Heat-pump-based hot water generation achieves coefficient-of-performance ratings above 2.5. EU Ecodesign Directive labeling creates premium positioning in French and German office markets.
Electric systems dominate installed base. Energy Efficient variants are gaining share fastest.
End User:
Application intensity varies from low-usage residential kitchens to continuous-duty industrial floor operations with diverging durability specifications.
- Residential:countertop and floor-standing units serve household hydration and beverage preparation. Online channels in North American retail corridors concentrate volume through direct-to-consumer refill networks.
- Commercial:Corporate campuses and healthcare facilities drive point-of-use filtration adoption. California hospital systems consolidate vendor relationships through single-source water service contracts bundling cooling, heating, and IoT monitoring.
- Industrial:Heavy-duty specifications withstand continuous operation in manufacturing break rooms and logistics facilities. China's eastern manufacturing corridor in Hangzhou drives bulk procurement for worker hydration stations.
- Educational:K-12 and university procurement teams scrutinize operating costs and NSF/ANSI 61 certification. EPA Energy Star mandates accelerate replacement cycles in US school district installations.
Commercial segment leads by revenue concentration. Industrial is climbing the fastest on manufacturing facility expansion.
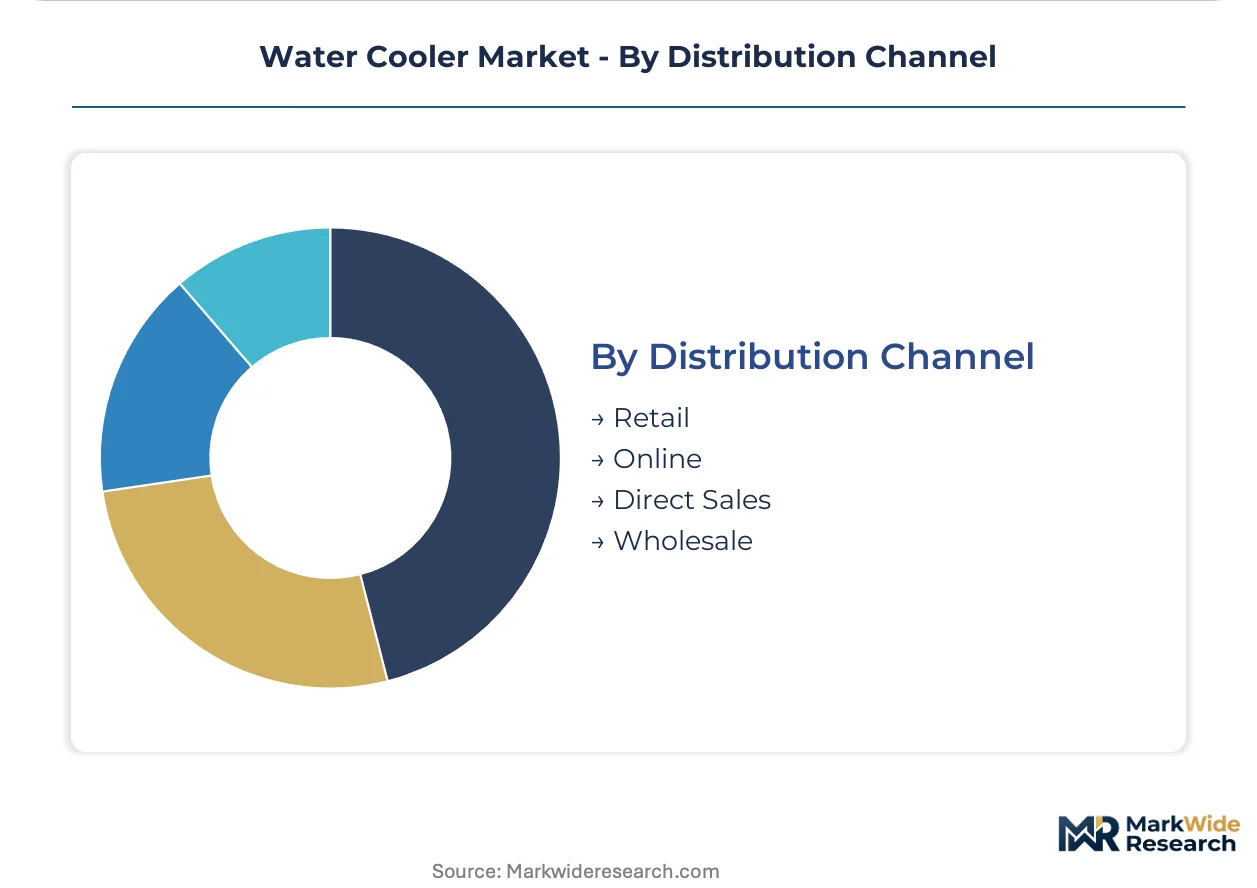
Distribution Channel:
Customer type dictates channel selection, with institutional buyers favoring direct relationships and residential purchasers fragmenting across retail touchpoints.
- Retail:Big-box and specialty stores move bottled units and countertop electrics to residential endpoints. North American retail corridors sustain volume leadership for Primo Water Corporation's refill network.
- Online:E-commerce platforms aggregate comparison shopping for replacement filters and compact residential units. Distributor channel stuffing of obsolete thermoelectric inventory distorts price signaling in mid-market segments.
- Direct Sales:Manufacturer field teams negotiate plumbed-in installations with facilities managers. Texas and California hospital systems favor this channel for total-cost-of-ownership reporting and bundled service contracts.
- Wholesale:Distributor networks supply contractor and reseller channels with floor-standing and industrial specifications. European markets concentrate through Waterlogic Holdings Ltd.'s plumbed-in filtration specialization.
Retail holds volume leadership. Direct Sales is expanding most quickly on corporate sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Corporate buyers in Germany absorb premium pricing for heat-pump efficiency, while Southeast Asian retail channels remain acutely price-sensitive on bottled units.
United States
Educational and healthcare procurement teams drive point-of-use filtration adoption. EPA Energy Star tightening forces manufacturers toward variable-speed compressor systems. California hospital systems consolidate vendor relationships through bundled water service contracts in Los Angeles and San Diego metro areas.
China
Commercial real estate expansion in Shanghai, Suzhou, and Hangzhou fuels bulk procurement for manufacturing facilities. SAMR enforces GB standards for electrical appliance safety and water-contact materials. The eastern manufacturing corridor dominates mass-market electric unit production through captive appliance manufacturing scale.
Germany
Facility managers specify coefficient-of-performance ratings above 2.5 for tea-preparation units in corporate kitchens. EU Ecodesign Directive efficiency labeling creates premium positioning for heat-pump-based systems. The Rhine-Ruhr industrial belt concentrates plumbed-in filtration specialization through direct-sales channels.
India
Bengaluru and Hyderabad tech campuses offer first-mover positioning for point-of-use installations. BIS electrical safety enforcement is tightening ahead of commercial real estate maturation. Solar-hybrid specifications experiment in tech corridor facilities before regulatory deadlines.
United Kingdom
Healthcare and educational sectors consolidate procurement around total-cost-of-ownership reporting. REACH chemical restrictions on water-contact materials force polymer reformulation for CE marking access. London and Southeast England concentrate facilities management contracts bundling filtration, cooling, and IoT monitoring.
Water Cooler Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around full-service providers with recurring revenue models while fragmenting among regional bottled-unit assemblers. Specialists in plumbed-in filtration systems occupy premium positions, whereas mass-market electric manufacturers compete on captive production scale. Dominant competitive moves include strategic partnerships for IoT-enabled service contracts and geographic expansion into underpenetrated commercial real estate corridors.
Within the full-service provider tier, Primo Water Corporation and Waterlogic Holdings Ltd. exemplify divergent regional strategies. Primo anchors North American retail corridors through direct-to-consumer refill network density. Waterlogic occupies European premium positioning through plumbed-in filtration specialization. Midea Group represents the scale-driven archetype, leveraging captive appliance manufacturing to dominate mass-market electric production.
| Leading Market Players |
|---|
| Primo Water Corporation |
| Waterlogic Holdings Ltd. |
| Clover Co. Ltd. |
| Blue Star Limited |
| Voltas Ltd. |
| Oasis International |
| Avalon Water Coolers |
| Culligan International Co. |
| Midea Group |
| Others |
Cost & Logistics Intelligence
Long-term service contracts with bundled filter replacement schedules lock in both supply access and price visibility for point-of-use system providers across US healthcare and educational procurement channels. These arrangements concentrate volume with full-service operators while compressing spot-market opportunities for equipment-only vendors in California and Texas hospital systems.
Pricing Analysis
After-sales filter cartridge revenue drives lifetime value across plumbed-in installations, with proprietary connection geometries enforcing single-source replacement schedules. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified commercial units from basic retail models. Cost compression in thermoelectric legacy inventory is intensifying because distributor channel stuffing distorts price signaling. Southeast Asian retail channels exhibit acute price sensitivity on bottled units, while German facility managers absorb premium positioning for heat-pump efficiency ratings above 2.5.
Supply Chain Analysis
Compressor manufacturing chokepoints in China and South Korea tether production schedules to variable-speed refrigeration component availability. Raw material dependencies span copper tubing assemblies, activated-carbon filtration media, and hydrofluorocarbon refrigerants subject to Kigali Amendment phase-downs. Single-source vulnerability concentrates in polymer formulation for NSF/ANSI 61-certified water-contact materials. Distribution runs through wholesale networks supplying contractor channels in Europe and direct-sales teams negotiating facilities management contracts in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring filter replacement revenue creates defensive moats through high switching costs that lock facilities managers into multi-year service agreements. Regulatory entrenchment deepens these positions as EPA Energy Star tightening and NSF/ANSI 61 certification timelines extend product launch barriers for challengers.
For Market Incumbents: Compound recurring revenue density by extending IoT-enabled predictive maintenance contracts that shift billing from hardware to usage-based cartridge replacement. Deepen vertical integration into activated-carbon filtration media production to defend margin position against commodity input volatility. Prioritize certification investment in heat-pump-based hot water systems ahead of EU Ecodesign Directive expansion deadlines. For New Entrants and Emerging Players: Anchor in Bengaluru and Hyderabad tech campuses where BIS electrical safety enforcement has not yet matured to full stringency. Target solar-hybrid specifications for remote industrial sites where grid reliability remains inconsistent. Pursue white-label manufacturing partnerships with Midea Group's captive appliance production scale to bypass capital-intensive facility buildouts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-service providers with bundled filtration-cooling-heating-IoT contracts in US healthcare and educational sectors. Five-to-ten-year viability favors acquisition targets possessing proprietary cartridge connection geometries that enforce aftermarket lock-in. Watch refrigerant transition cost absorption as the inflection indicator separating compressor redesign capability from stranded legacy inventory exposure.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Sensor-integrated filtration enables usage-based billing models in Texas hospital systems. |
| Heat-Pump Manufacturing Scale-Up | Coefficient-of-performance ratings above 2.5 unlock premium positioning in German office markets. |
| Backward Integration into Filtration Media | Activated-carbon cartridge production secures margin control against commodity input volatility. |
| Geographic Expansion into Indian Tech Corridors | Bengaluru and Hyderabad campuses offer first-mover positioning before BIS enforcement tightens. |
| Regulatory Certification Investment | NSF/ANSI 61 and EPA Energy Star compliance extends product launch barriers for competitors. |
Research Approach
Desk research of trade customs data, appliance manufacturing disclosures, and regulatory filing databases preceded structured interviews with facilities management directors, hospital procurement officers, and aftermarket service heads. Primary fieldwork with OEM procurement teams and distributor channel partners combined with secondary validation against SAMR GB standard enforcement records and EPA Energy Star certification timelines. Bottom-up unit shipment modeling triangulated against top-down revenue estimates from commercial real estate development pipelines.
Variance decomposition across product type, technology tier, end-use intensity, and distribution channel structure shaped analytical framework development over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including commercial construction spending and regulatory compliance cost absorption. Forecast inputs incorporated refrigerant phase-down schedules under Kigali Amendment timelines and IoT penetration curves in healthcare facilities.
Material uncertainties — refrigerant transition cost pass-through, filter cartridge standardization breakthroughs, municipal plumbing infrastructure development rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding BIS electrical safety enforcement pacing and EU REACH chemical restriction implementation. Revision becomes warranted when heat-pump coefficient-of-performance adoption thresholds cross 40% share in German and French office markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Bottle Dividers Market