
 Saudi Arabia Bariatric Surgery Market | 2026-2036
Saudi Arabia Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Bariatric Surgery Market Analytics
The gap between premium robotic-assisted procedures and conventional laparoscopic tiers is broadening in Saudi Arabia's bariatric surgery landscape. Medtronic PLC anchors its position through extensive distribution partnerships with Ministry of Health facilities across the Kingdom. Johnson and Johnson differentiates via its Ethicon suture and stapling portfolio tailored to metabolic surgery protocols. Stryker Saudi Arabia leverages its localized service infrastructure to sustain equipment uptime commitments in high-volume hospitals.
Bariatric surgery encompasses restrictive, malabsorptive, and combined procedures performed to induce sustained weight loss by reducing gastric capacity or altering intestinal nutrient absorption pathways, typically requiring staplers, trocars, energy devices, and implantable bands or balloons. Sleeve gastrectomy dominates procedure volumes due to its technical reproducibility and lower complication profile relative to gastric bypass, while adjustable gastric banding contracts as revision rates and patient dissatisfaction accumulate. Among end users, hospitals capture the deepest margin pools through bundled episode pricing for complex cases, whereas outpatient centers compete on throughput efficiency for lower-acuity interventions.
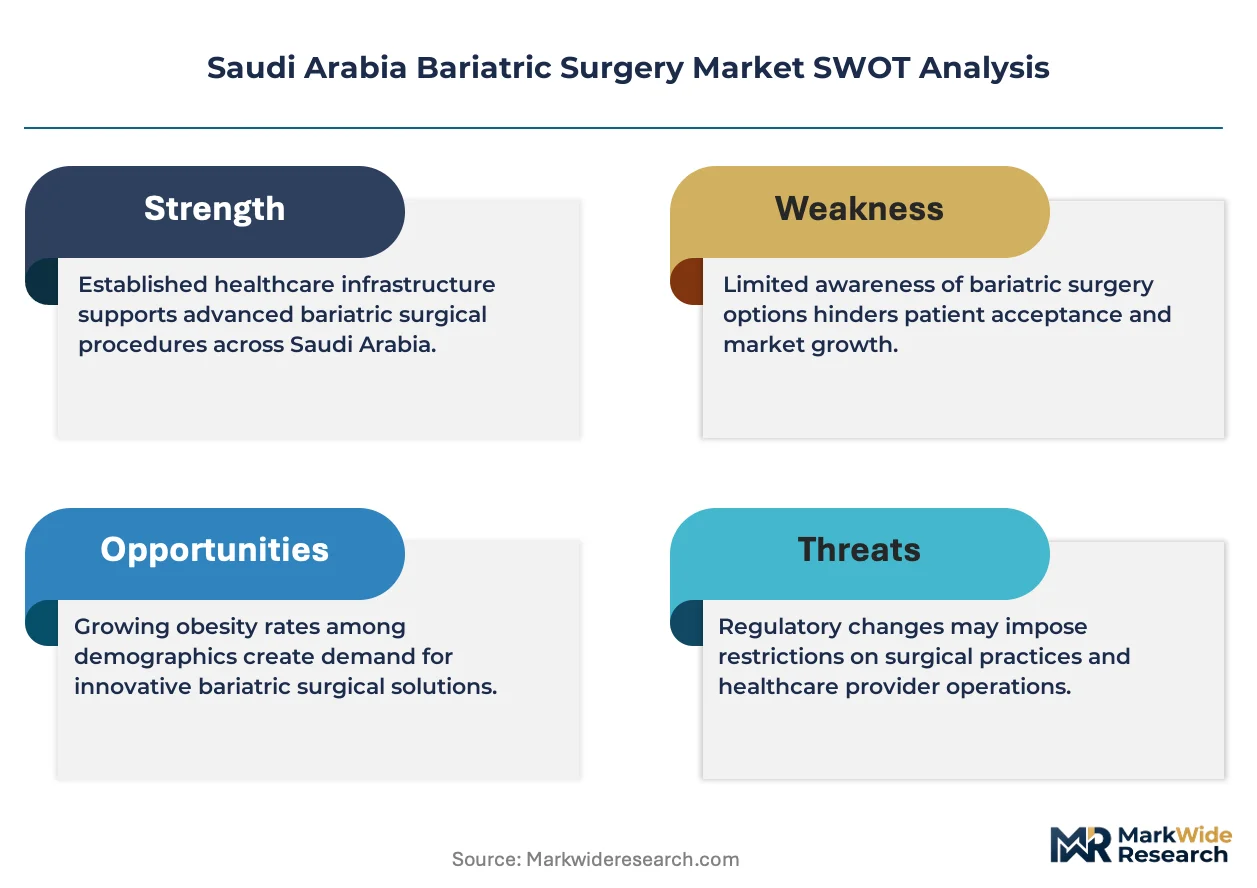
SFDA enforces medical device marketing authorization and post-market surveillance for all implantable bariatric products, while the Saudi Central Board for Accreditation of Healthcare Institutions mandates surgical volume thresholds and outcome reporting for metabolic surgery program certification. Compliance with these dual frameworks shapes vendor selection criteria and hospital procurement timelines. Stakeholders must monitor how SFDA's alignment with international harmonization initiatives affects registration pathways for novel endoluminal technologies.
Market Dynamics
SFDA's tightening marketing authorization pathways for implantable metabolic devices are compressing vendor qualification timelines and forcing hospital procurement departments to revalidate supplier portfolios ahead of Saudi Vision 2030 localization mandates.
Growth Catalysts
- Vision 2030 Health Sector Transformation:The national framework prioritizes localized obesity treatment capacity, directing capital expenditure toward metabolic surgery infrastructure expansion in tertiary centers across Riyadh and Jeddah.
- Sleeve Gastrectomy Protocol Standardization:Reproducible laparoscopic techniques reduce operative variability and training curves, enabling volume scaling at Ministry of Health referral hospitals managing BMI 40+ patient flows.
- Central Province Referral Network Density:Tertiary clustering in Riyadh concentrates complex cases into accredited high-volume centers, creating predictable demand baselines for device vendors.
Market Restraints
- SFDA Registration Timeline Friction:Post-market surveillance obligations and harmonization alignment with international standards extend marketing authorization cycles for novel endoluminal technologies.
- Adjustable Gastric Banding Contraction:Elevated revision rates and documented patient dissatisfaction are displacing this procedure category, stranding specialized instrumentation investments.
- Specialized Surgeon Supply Bottleneck:Metabolic surgery program certification thresholds set by the Saudi Central Board for Accreditation of Healthcare Institutions limit eligible operator pools.
Strategic Opportunities
- Western Province Outpatient Center Expansion:Jeddah's private hospital chains are developing ambulatory metabolic surgery capabilities for lower-acuity sleeve procedures outside traditional inpatient settings.
- Robotic-Assisted Procedure Tier Penetration:Da Vinci system deployment in premium private facilities is creating differentiated service lines for complex revisional bariatric cases.
- Endoluminal Balloon Regulatory Pathway:SFDA's evolving framework for non-implantable temporary devices presents first-mover positioning for intragastric balloon technologies.
Industry Challenges
- Bariatric Surgery Fellowship Pipeline Constraints:Accredited training program capacity limits annual qualified surgeon output relative to projected case volume growth.
- Implantable Device Traceability Infrastructure:SFDA's unique device identification requirements demand hospital IT system upgrades for lot-level tracking compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Bariatric Surgery Market |
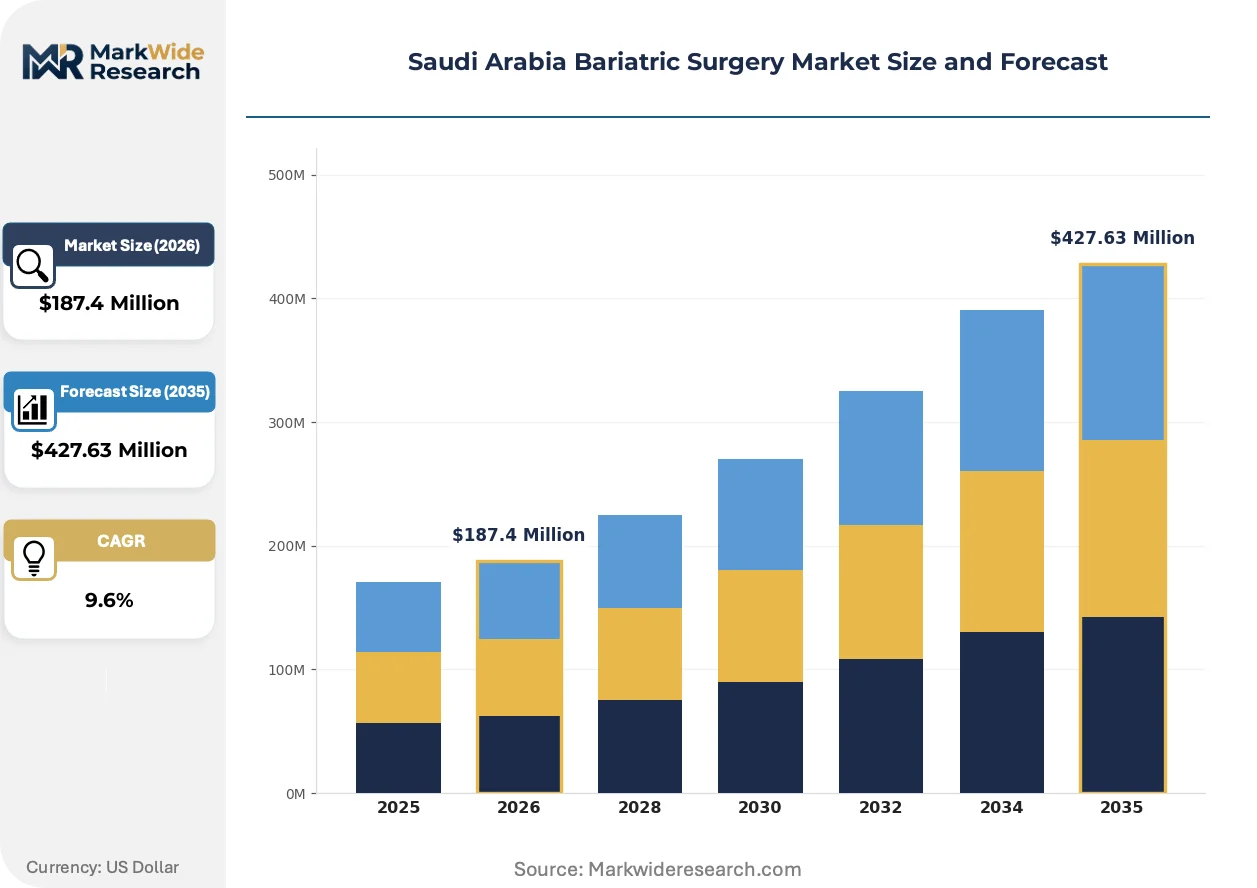
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion End User: Hospitals, Specialty Clinics, Outpatient Centers, Research Institutions Age Group: Children, Adolescents, Adults, Seniors Body Mass Index Range: 30-35, 35-40, 40-50, >50 |
| Companies Covered | Coopersurgical Inc, Conmed Corporation, Medtronic PLC, Olympus Corporation, B Braun SE, Johnson and Johnson, Intuitive Surgical Inc, Stryker Saudi Arabia, Apollo Endosurgery Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Bariatric Surgery Market Evolving Landscape
Digital surgical planning platforms and energy-based vessel sealing technologies are compressing operative time variability while SFDA's regulatory harmonization initiatives reshape device registration strategies for multinational suppliers.
Robotic surgical platforms equipped with haptic feedback and 3D visualization are automating suturing precision in gastric pouch formation during Roux-en-Y gastric bypass procedures. Private hospital chains in Riyadh are acquiring these systems to differentiate complex revisional surgery offerings. This automation is compressing the learning curve differential between high-volume academic centers and emerging metabolic surgery programs.
SFDA's alignment with International Medical Device Regulators Forum technical documentation standards is streamlining marketing authorization pathways for predicate devices while tightening novel technology review intensity. Manufacturers with existing CE-marked or FDA-cleared portfolios gain accelerated entry timelines. Implantable adjustable gastric bands and novel anastomotic devices face heightened clinical evidence requirements under this framework.
Episode-based bundled pricing is displacing fee-for-service reimbursement in Ministry of Health tertiary referral networks, compressing device procurement to total cost-of-care metrics rather than standalone product pricing. Hospital supply chain departments are consolidating vendor relationships to capture volume discounts across stapler, trocar, and energy device categories. This consolidation is most visible in Central Province academic medical centers managing complex metabolic surgery populations.
Saudi Arabia Bariatric Surgery Market Segmentation
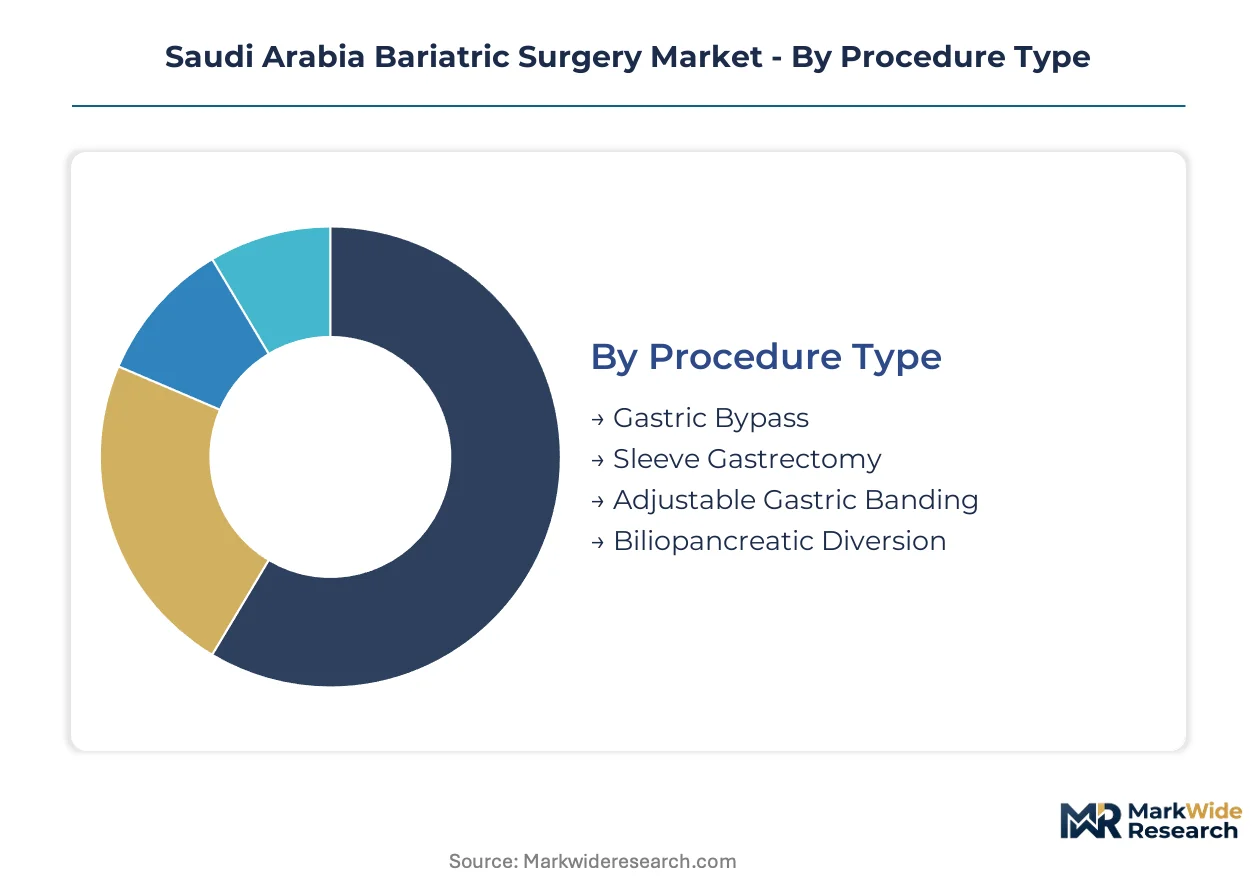
Procedure mix and patient acuity profiles in Saudi Arabia's bariatric surgery market diverge sharply across institutional settings and metabolic risk categories. SFDA device registration pathways and Saudi Vision 2030 infrastructure investments reshape how segments concentrate volume and margin.
Procedure Type:
Technical approach determines operative complexity, device utilization intensity, and reimbursement bundling structures across Saudi metabolic surgery programs.
- Sleeve Gastrectomy:Laparoscopic vertical gastrectomy resects the gastric fundus along the greater curvature, preserving pyloric integrity while reducing reservoir capacity. Central Province Ministry of Health hospitals in Riyadh channel BMI 40+ patients toward standardized sleeve protocols, compressing operative time variability through reproducible technique.
- Gastric Bypass:Roux-en-Y reconstruction creates a proximal gastric pouch with gastrojejunal anastomosis, combining restriction with malabsorption. Private hospital chains in Jeddah deploy Da Vinci robotic platforms for complex revisional bypass cases, differentiating premium service tiers through automated suturing precision.
- Adjustable Gastric Banding:Silicone band placement around the gastric cardia with subcutaneous port access for saline adjustment. Elevated revision rates and patient dissatisfaction are displacing this category, stranding specialized instrumentation investments.
- Biliopancreatic Diversion:Extended malabsorptive procedure with distal gastrectomy and ileal switch configuration. Reserved for super-obese populations at tertiary academic centers with specialized nutritional support infrastructure.
Mature deployment sits with Sleeve Gastrectomy. Newer deployment is concentrated in Gastric Bypass robotic-assisted tiers.
End User:
Institutional capabilities dictate case complexity thresholds, device procurement autonomy, and SFDA compliance infrastructure requirements.
- Hospitals:Tertiary academic medical centers and Ministry of Health referral facilities manage complex revisional cases and complication rescue. Bundled episode pricing concentrates device procurement to total cost-of-care metrics, consolidating vendor relationships across stapler and energy device categories.
- Outpatient Centers:Ambulatory surgical facilities in Jeddah's private hospital chains are developing same-day discharge capabilities for lower-acuity sleeve procedures. SFDA marketing authorization for non-implantable temporary devices enables intragastric balloon deployment outside traditional inpatient settings.
- Specialty Clinics:Focused metabolic surgery units with dedicated bariatric nursing and anesthesia protocols. Limited to uncomplicated primary procedures within defined BMI thresholds.
- Research Institutions:Academic centers with Saudi Central Board for Accreditation of Healthcare Institutions certification for fellowship training. Surgical volume mandates and outcome reporting requirements shape program eligibility.
Volume concentration sits with Hospitals. Margin expansion is accelerating in Outpatient Centers.
Age Group:
Metabolic surgery candidacy criteria and growth trajectory implications vary across developmental stages and physiological reserve.
- Adults:Dominant procedural volume among patients aged 18-64 with established comorbidity burdens. Central Province referral networks prioritize this segment for tertiary center channeling.
- Adolescents:Expanding most quickly as pediatric metabolic surgery programs gain accreditation under Saudi Vision 2030 capacity expansion. Strict endocrine and psychological evaluation protocols apply.
- Seniors:Careful selection criteria balance metabolic benefit against operative risk in patients over 65. Concentrated at high-volume academic centers with intensive care backup.
- Children:Rare intervention reserved for syndromic obesity with specialized multidisciplinary evaluation. Limited to national referral centers with pediatric anesthesia and critical care infrastructure.
Established volume sits with Adults. Steepest expansion trajectory is concentrated in Adolescents.
Body Mass Index Range:
Preoperative metabolic severity stratifies procedural selection, perioperative risk management, and long-term outcome monitoring intensity.
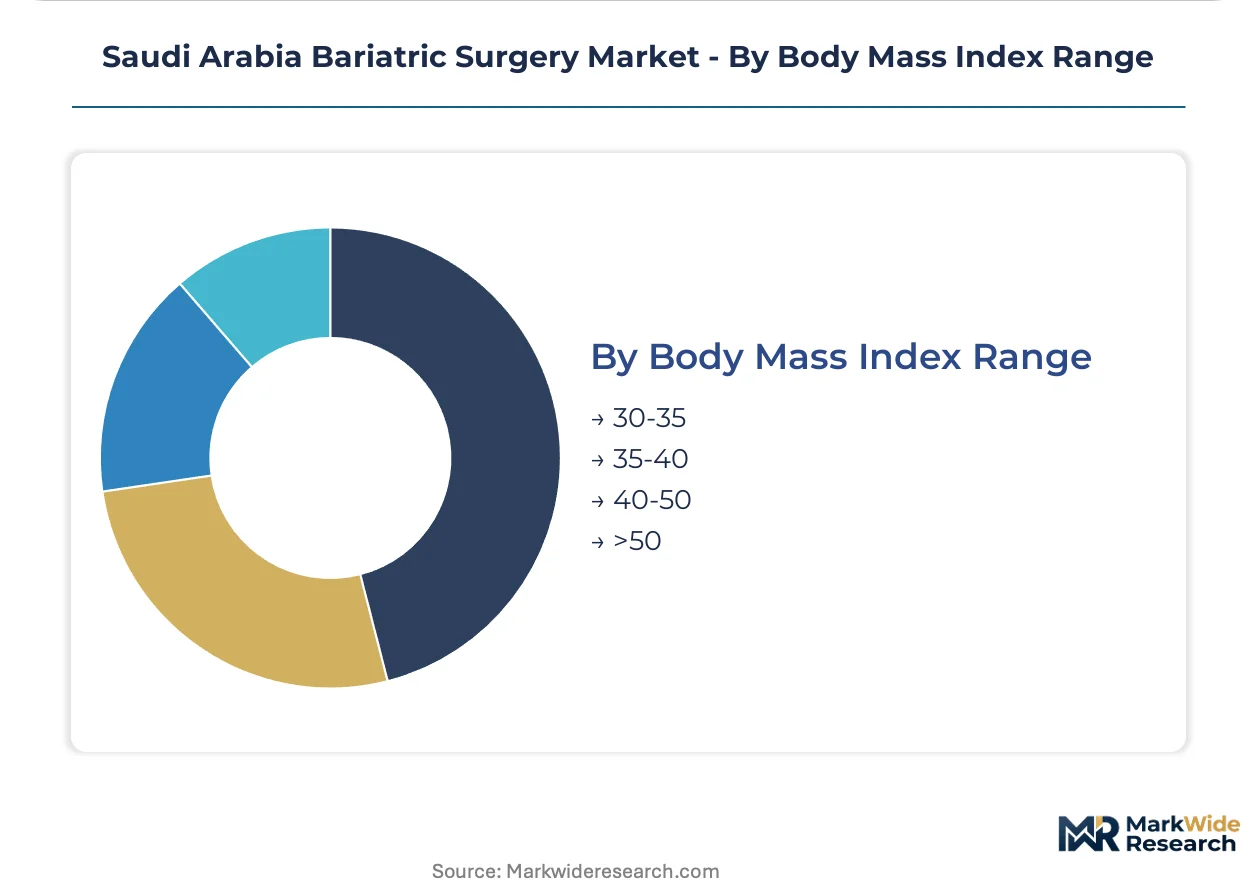
- 40-50:Core referral population for Ministry of Health tertiary networks. Sleeve gastrectomy standardization enables volume scaling with reproducible outcomes.
- >50:Super-obese category requiring specialized anesthesia, positioning, and postoperative monitoring infrastructure. Malabsorptive procedures gain relative preference for durable weight loss.
- 35-40:Intermediate range with comorbidity-driven surgical candidacy. Endoluminal balloon technologies target this segment under evolving SFDA temporary device frameworks.
- 30-35:Lower threshold with strict comorbidity requirements. Lifestyle intervention and pharmacotherapy precede surgical evaluation in most cases.
Clinical focus sits with 40-50. Emerging device opportunity is concentrated in 35-40.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors metabolic surgery capacity expansion as Saudi Vision 2030 channels tertiary infrastructure investment toward the Central Province's densest patient referral networks.
Central Province
Ministry of Health tertiary centers in Riyadh manage the deepest concentration of BMI 40+ surgical candidates through standardized sleeve gastrectomy protocols. SFDA's medical device registration requirements shape procurement timelines for implantable products across these high-volume facilities. King Faisal Specialist Hospital anchors the region's fellowship training pipeline under Saudi Central Board for Accreditation of Healthcare Institutions certification mandates.
Western Region
Jeddah's private hospital chains are developing ambulatory metabolic surgery capabilities for same-day discharge sleeve procedures outside traditional inpatient settings. SFDA marketing authorization pathways for non-implantable temporary devices enable intragastric balloon deployment in outpatient centers. King Abdulaziz University Hospital concentrates complex revisional cases requiring robotic-assisted intervention.
Eastern Province
Dammam's tertiary referral networks channel super-obese patients toward specialized malabsorptive procedure programs with dedicated nutritional support infrastructure. Saudi Vision 2030 health sector transformation directs capital expenditure toward metabolic surgery department expansion in Ministry of Health facilities. Johns Hopkins Aramco Healthcare anchors high-acuity case management for the region's industrial workforce populations.
NEOM Northwest
The giga-project zone is integrating metabolic surgery capacity into its preventive health infrastructure as part of comprehensive wellness ecosystem development. SFDA regulatory harmonization with international standards streamlines device procurement for greenfield healthcare facilities. NEOM's technology-forward hospital design incorporates digital surgical planning platforms from initial construction phases.
Saudi Arabia Bariatric Surgery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the robotic-assisted versus conventional laparoscopic procedure divide. The vendor structure concentrates around multinational medical device manufacturers with established SFDA registration portfolios and localized service infrastructure. Three archetypes dominate: integrated surgical platform suppliers, specialized metabolic surgery instrument manufacturers, and regional distribution partners with ministry contracting relationships. Consolidation pressure is intensifying through bundled episode pricing mandates and vendor relationship rationalization in high-volume hospital systems.
Among the integrated platform suppliers, Medtronic PLC and Johnson and Johnson exemplify the scale-driven archetype with extensive distribution networks across Ministry of Health facilities. Intuitive Surgical Inc occupies a differentiated position within the robotic-assisted tier, where automated suturing precision commands premium positioning for complex revisional cases. Stryker Saudi Arabia represents the localized service infrastructure model, sustaining equipment uptime commitments through dedicated technical support presence in Riyadh and Jeddah.
| Leading Market Players |
|---|
| Coopersurgical Inc |
| Conmed Corporation |
| Medtronic PLC |
| Olympus Corporation |
| B Braun SE |
| Johnson and Johnson |
| Intuitive Surgical Inc |
| Stryker Saudi Arabia |
| Apollo Endosurgery Inc |
| Others |
Value Network & Pricing Analysis
Ministry of Health tertiary referral networks concentrate procurement authority for implantable metabolic devices, anchoring episode-based bundled pricing that compresses standalone product margins into total cost-of-care metrics. SFDA registration compliance costs and localized service infrastructure requirements create pricing power asymmetries between established vendors with ministry contracts and emerging entrants facing qualification friction.
Pricing Analysis
Episode-based bundled pricing anchors Ministry of Health tertiary center contracts, tying device reimbursement to surgical outcome metrics and total care cycle costs rather than per-unit transactional rates. Price differentiation separates robotic-assisted premium tiers commanding automated suturing precision premiums from conventional laparoscopic standard tiers and economy consumables tiers. Pricing pressure stems from bundled episode mandates consolidating vendor relationships across stapler, trocar, and energy device categories. Private hospital chains in Jeddah exhibit least price sensitivity for Da Vinci system acquisitions, while outpatient centers competing on throughput efficiency for sleeve procedures demonstrate highest sensitivity to consumables unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Central Board for Accreditation of Healthcare Institutions mandate hospital procurement departments maintain qualified backup suppliers for critical implantable categories, extending vendor validation timelines. Geographic supply concentration draws from USA, Germany, and Ireland for predicate device portfolios with established CE marking or FDA clearance, while Japan and South Korea anchor energy device and advanced visualization component sourcing. Raw material dependencies rest on surgical-grade stainless steel, medical silicone for adjustable bands, and high-performance polymers for trocar housings. Single-source vulnerability concentrates in robotic platform technical service infrastructure, where Intuitive Surgical's localized Saudi Arabia presence creates asymmetric dependency. Distribution runs through ministry-approved medical device distributors with SFDA establishment licensing and hospital system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's tightening marketing authorization pathways and Saudi Vision 2030 localization mandates construct a cost-of-compliance moat that privileges incumbent vendors with established registration portfolios and ministry contracting relationships, while elevating barriers for unqualified entrants.
For Market Incumbents: Extend service infrastructure depth in Riyadh and Jeddah to defend equipment uptime commitments against emerging regional distribution partners. Consolidate stapler and energy device category relationships through volume discount structures that align with bundled episode pricing mandates. SFDA harmonization with International Medical Device Regulators Forum standards threatens accelerated entry for CE-marked competitors, demanding proactive predicate device portfolio expansion. For New Entrants and Emerging Players: The price-point gap between Da Vinci robotic premium tiers and conventional laparoscopic standard tiers creates white-space positioning for automated suturing alternatives and digital surgical planning platforms. Western Province outpatient center expansion in Jeddah offers the most penetrable geography, with ambulatory metabolic surgery capabilities developing outside traditional inpatient procurement hierarchies. A focused go-to-market angle targets intragastric balloon deployment under SFDA's evolving non-implantable temporary device framework, bypassing implantable product registration friction. For Investors and Strategic Acquirers: The window for entry favors regional distribution partners with ministry contracting relationships and established SFDA establishment licensing. Long-term viability across the analysis window depends on localization compliance infrastructure and service presence density rather than product innovation velocity. Acquisition targets should demonstrate surgical volume thresholds under Saudi Central Board for Accreditation of Healthcare Institutions certification. The signal to watch is SFDA alignment with international harmonization initiatives accelerating predicate device entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Marketing Authorization Pathway | Accelerated entry for predicate devices with CE marking or FDA clearance compresses novel technology review cycles. |
| Hospital System Partnership | Ministry of Health tertiary center contracts anchor predictable demand baselines for high-volume metabolic surgery programs. |
| Software Companion Development | Digital surgical planning platforms reduce operative time variability in standardized sleeve gastrectomy protocols. |
| Reimbursement Strategy | Episode-based bundled pricing alignment captures volume discounts across stapler and energy device categories. |
| CE Marking Pathway | International harmonization with IMDRF standards streamlines technical documentation for established portfolios. |
Research Methodology
Independent corroboration across hospital procurement committees, biomedical engineering leads, and metabolic surgery program directors underwrites the qualitative findings on vendor selection criteria and SFDA compliance infrastructure requirements. Secondary validation draws from SFDA medical device registration databases, Saudi Central Board for Accreditation of Healthcare Institutions certification records, and Ministry of Health capital expenditure disclosures. Bottom-up procedure volume modeling and top-down healthcare infrastructure investment tracking triangulate market size estimation.
Rate-of-change decomposition separates procedure volume growth drivers from pricing and mix shift contributions across the projection horizon. Segmentation dimensions modeled include procedure type, end user institution category, patient age group, and body mass index range. CAGRs derive from surgical volume scaling at accredited high-volume centers and robotic platform deployment trajectories in premium private facilities. Forecast inputs incorporate Saudi Vision 2030 health sector transformation capital allocation patterns and fellowship training pipeline capacity constraints.
Underlying measurement precision varies by segment; Ministry of Health tertiary center data carries tighter precision than private outpatient center volume estimates. Forecasts reflect assumptions on SFDA regulatory harmonization pace and localization mandate enforcement intensity. A model refresh is warranted upon material change in Saudi Vision 2030 health infrastructure investment allocation or SFDA marketing authorization timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Spain Bariatric Surgery Market