
 Global Bariatric Surgery Market | 2026-2036
Global Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bariatric Surgery Market Analysis
The capital-intensity gap between robotic platform providers and conventional laparoscopic instrument suppliers is collapsing. Intuitive Surgical leverages its installed da Vinci base to sustain recurring revenue from consumable instruments. Medtronic anchors its position through integrated energy and stapling portfolios that compete across open and minimally invasive bariatric workflows.
Bariatric surgery encompasses restrictive, malabsorptive, and combined metabolic procedures designed to reduce stomach volume or alter nutrient absorption pathways, typically requiring specialized stapling devices calibrated to tissue thickness and compression parameters. The primary commercial purpose centers on durable weight reduction and remission of obesity-related comorbidities including type 2 diabetes and hypertension. Sleeve gastrectomy dominates procedure volume among the four major intervention categories, while robotic-assisted minimally invasive techniques capture disproportionate growth in academic medical centers where capital budgets support platform acquisition. Gastric bands within the device taxonomy have matured into a declining margin pool as clinical preference shifts toward irreversible anatomical modifications.
FDA premarket notification and de novo pathways govern device commercialization in the United States, while EMA's Medical Device Regulation and CE marking requirements shape European market access and post-market surveillance obligations. The EU Green Deal's circular economy provisions are beginning to influence disposable instrument procurement specifications across member states. Stakeholders must monitor whether CMS and comparable national payers expand bundled reimbursement to cover preoperative optimization and long-term nutritional monitoring as standard care components.
Market Dynamics
Robotic-assisted surgical platforms are decomposing the capital barrier that historically separated academic medical centers from community hospital bariatric programs, redistributing procedure volume across facility tiers and compressing equipment amortization timelines.
Growth Catalysts
- CMS bundled reimbursement expansion:Medicare's coverage broadening for metabolic surgery preoperative optimization and long-term nutritional monitoring reduces patient out-of-pocket exposure and accelerates referral pipeline conversion in United States hospital systems.
- Single-anastomosis duodeno-ileal bypass with sleeve gastrectomy (SADI-S):This malabsorptive modification is capturing surgeon preference for its simplified intestinal reconstruction and reduced operative time compared to traditional Roux-en-Y gastric bypass.
- Type 2 diabetes remission protocols:Endocrinology societies in Germany, Japan, and Brazil are embedding surgical weight management into diabetes treatment algorithms, creating institutional demand for dedicated metabolic surgery units.
Market Restraints
- Staple line reinforcement material costs:Bioabsorbable polymer buttressing materials and fibrin sealants add per-procedure consumable expenses that compress margins in price-sensitive hospital purchasing environments.
- Da Vinci system supply concentration:Intuitive Surgical's installed base dominance in robotic platforms creates vendor lock-in effects that limit competitive pricing pressure on annual service contracts and instrument disposables.
- Long-term nutritional deficiency liability:Malabsorptive procedures generate lifetime monitoring obligations that expose healthcare systems to malpractice exposure and patient compliance enforcement costs.
Strategic Opportunities
- India's tier-2 city hospital networks:Underpenetrated metropolitan areas outside Mumbai, Delhi, and Bangalore present first-mover positioning for turnkey bariatric program establishment with localized surgeon training partnerships.
- Endoluminal revision technologies:Incisionless pouch reduction and stoma revision devices address weight regain in prior surgical patients, opening addressable population beyond naive bariatric candidates.
- EU Green Deal circular economy procurement:Member state hospital systems are rewriting disposable instrument specifications to favor reusable or recyclable stapling cartridge designs, rewarding suppliers with validated sustainability credentials.
Industry Challenges
- Robotic console operator certification bottlenecks:Proctoring requirements and case volume thresholds for independent da Vinci bariatric credentialing extend surgeon onboarding timelines and constrain program expansion velocity.
- Legacy electronic health record integration:Metabolic surgery registries require structured data capture for quality reporting that conflicts with existing EHR workflow architectures, forcing parallel documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bariatric Surgery Market |
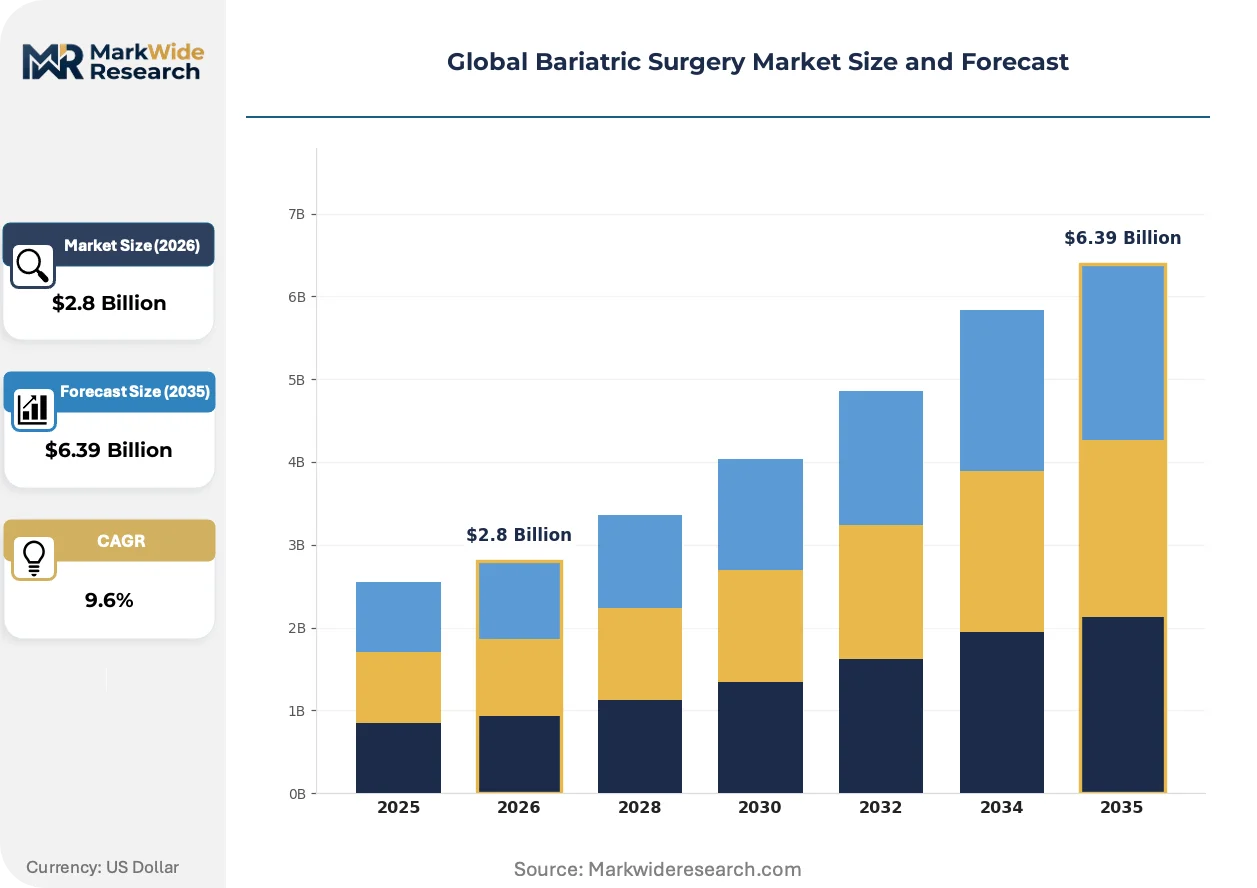
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Minimally Invasive Technique: Laparoscopic Surgery, Robotic Surgery, Endoscopic Approach, Transoral Approach End User: Hospitals, Outpatient Clinics, Surgical Centers, Academic Institutions Device Type: Gastric Bands, Sutures, Staplers, Trocar Systems |
| Companies Covered | Intuitive Surgical, Medtronic, Johnson & Johnson, Boston Scientific, Olympus Corporation, Apollo Endosurgery, Teleflex, Conmed, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bariatric Surgery Market Emerging Trajectories
Digital surgical planning and intraoperative navigation are compressing the learning curve for complex revisional procedures while real-world evidence generation is reshaping payer coverage determinations for device-based obesity interventions.
Articulating stapling devices with integrated tissue sensing are decomposing the historical trade-off between anastomotic security and perfusion preservation. Academic medical centers in the United States and South Korea are adopting these platforms for sleeve gastrectomy and gastric bypass applications. The technology is enabling more consistent staple line integrity across variable gastric wall thicknesses while compressing revision rates for leak and stricture complications.
EMA's Medical Device Regulation (MDR) recertification deadlines are forcing systematic clinical evidence regeneration for legacy bariatric staplers and energy devices already holding CE marks. Manufacturers must compile post-market surveillance data and updated biocompatibility documentation to maintain European market access. Class III implantable obesity devices face the most compressed timelines, with notified body capacity constraints extending review queues into late 2025.
Hospital supply chain committees are unbundling robotic service contracts from instrument purchasing agreements, separating platform maintenance from per-procedure disposable procurement. This disintermediation is most visible in German and Dutch hospital systems where procurement centralization has created leverage for multi-year total cost of ownership negotiations. The shift pressures device vendors to demonstrate standalone instrument value rather than relying on ecosystem lock-in effects.
Global Bariatric Surgery Market Segmentation
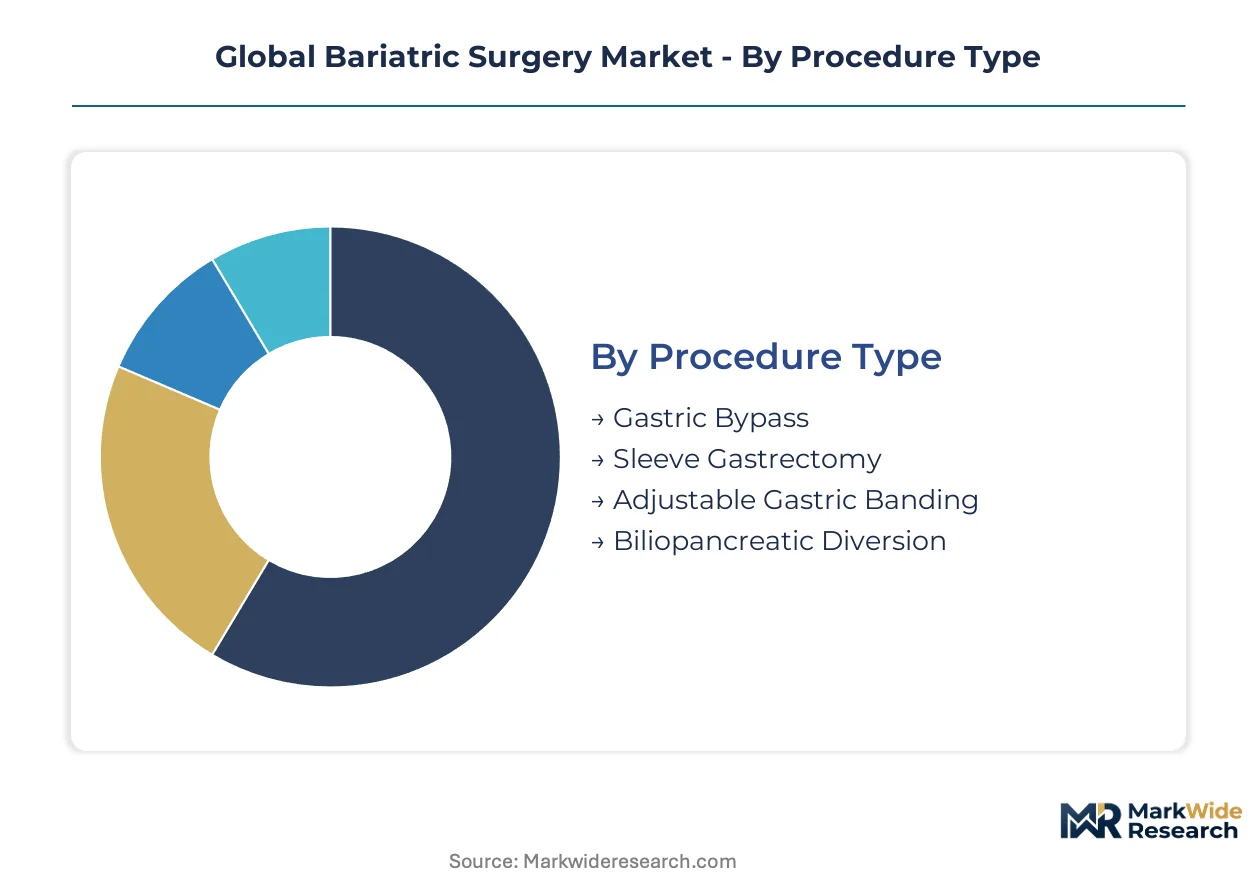
Segmentation in the Global Bariatric Surgery Market reveals how regulatory pathways, reimbursement structures, and clinical training requirements concentrate demand across distinct procedure categories and facility tiers. Understanding these divisions exposes where capital deployment, technology adoption, and pricing power actually reside.
Procedure Type:
FDA premarket notification requirements vary substantially across anatomical modification approaches, with combined malabsorptive-restrictive procedures facing more intensive clinical evidence thresholds than purely restrictive techniques.
- Sleeve Gastrectomy:This irreversible gastric volume reduction removes approximately 80% of stomach tissue along the greater curvature, leaving a tubular sleeve. Demand concentrates in United States community hospital systems where bundled CMS reimbursement favors shorter operative times and reduced perioperative resource utilization compared to intestinal bypass alternatives.
- Gastric Bypass:The Roux-en-Y configuration creates a small gastric pouch with gastrojejunal anastomosis and separate biliopancreatic limb. Academic medical centers in Germany and South Korea drive procedural volume for this technique given its superior diabetes remission rates and institutional capacity for managing long-term nutritional monitoring obligations.
- Adjustable Gastric Banding:Silicone band devices with subcutaneous port systems for saline adjustment dominate historical procedure registries but now face declining utilization as irreversible alternatives demonstrate superior sustained weight loss.
- Biliopancreatic Diversion:This malabsorptive technique with duodenal switch modification carries the most intensive nutritional supplementation requirements and concentrates in specialized metabolic surgery units with dedicated bariatric dietitian staffing.
Sleeve gastrectomy handles the majority of throughput; biliopancreatic diversion is the fastest mover on share among complex metabolic cases.
Minimally Invasive Technique:
Capital equipment amortization schedules and surgeon training pathway lengths create sharp cost tier differentiation across access modalities.
- Laparoscopic Surgery:Conventional multi-port abdominal access with 5-12mm trocar placement remains the volume foundation across all facility tiers, with reusable instrument options supporting cost containment in price-sensitive procurement environments.
- Robotic Surgery:Da Vinci platform utilization requires annual service contracts and per-procedure instrument disposables that elevate fixed cost structures, concentrating adoption in academic institutions and affluent metropolitan hospital systems with favorable payer mixes.
- Endoscopic Approach:Transoral sleeve gastroplasty and intragastric balloon placement avoid abdominal wall penetration entirely, expanding candidacy to patients with prohibitive surgical risk profiles.
- Transoral Approach:Incisionless magnetic anastomosis and endoluminal revision techniques address weight regain in prior surgical patients, opening addressable population beyond naive bariatric candidates.
Laparoscopic surgery anchors volume across all geographies; robotic platforms are climbing the fastest as console availability expands beyond flagship academic centers.
End User:
Facility accreditation requirements and case volume thresholds for quality certification reshape where procedures actually occur.
- Hospitals:Inpatient surgical suites with 24-hour critical care coverage manage complex revisional cases and complications requiring immediate intervention, capturing the highest-acuity portion of metabolic surgery volume.
- Outpatient Clinics:Standalone ambulatory facilities with limited overnight observation capacity concentrate on uncomplicated primary sleeve gastrectomy in selected low-BMI patients with minimal comorbidity burden.
- Surgical Centers:Multi-specialty facilities with dedicated bariatric nursing protocols achieve efficiency through standardized pathways but require transfer agreements with acute care hospitals for rare emergent complications.
- Academic Institutions:Teaching hospitals with fellowship programs generate procedural volume through resident and fellow participation, often subsidizing robotic platform acquisition through research grants and training revenue.
Hospitals retain the dominant share of complex metabolic procedures; outpatient clinics are expanding most quickly where state-level certificate-of-need regulations permit.
Device Type:
EMA MDR recertification timelines and biocompatibility documentation requirements are forcing portfolio rationalization among legacy suppliers.
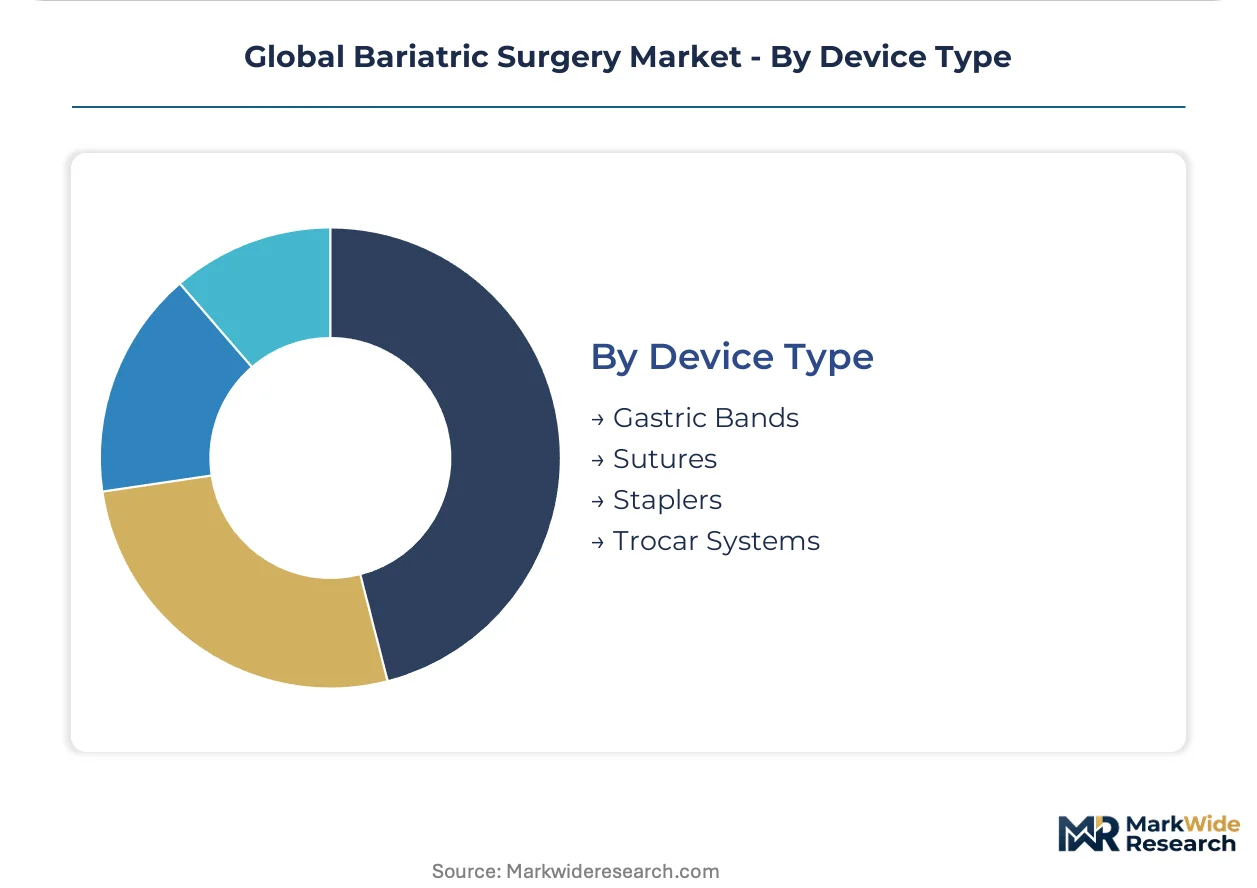
- Staplers:Articulating devices with integrated tissue sensing and variable height cartridges enable consistent staple line formation across variable gastric wall thicknesses, with articulating platforms gaining preference in sleeve gastrectomy applications.
- Trocar Systems:Bladeless optical entry devices and fixed-length versus adjustable cannula options compete on fascial defect size and port site hernia incidence, with disposable configurations dominating United States practice patterns.
- Sutures:Barbed and running closure techniques for mesenteric defects and enterotomy closure reduce operative time compared to interrupted hand-tied configurations in open conversion scenarios.
- Gastric Bands:Adjustable silicone devices with subcutaneous port systems face contracting demand as clinical societies revise guidelines to de-emphasize banding in favor of irreversible alternatives.
Staplers command the largest device expenditure share; trocar systems are gaining share fastest as single-use configurations displace reusable alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands stapler cartridge premiums that United States group purchasing organizations routinely suppress through volume-commitment contracts, creating a transatlantic margin asymmetry that shapes supplier resource allocation.
United States
CMS bundled reimbursement expansion and employer-sponsored wellness program incentives drive metabolic surgery volume in community hospital systems. FDA premarket notification pathways for obesity devices compress approval timelines for articulating staplers. The Cleveland Clinic and Mayo Clinic anchor robotic platform adoption in the Midwest, training surgical fellows who disperse credentialing capacity regionally.
Germany
Endocrinology society diabetes remission protocols and statutory health fund coverage for long-term nutritional monitoring institutionalize metabolic surgery demand. EMA MDR recertification deadlines force systematic clinical evidence regeneration for legacy staplers. The Rhine-Ruhr hospital network centralizes procurement leverage, extracting multi-year total cost of ownership concessions from device vendors.
India
Tier-2 city hospital networks outside Mumbai and Delhi present first-mover positioning for turnkey bariatric program establishment. CDSCO medical device registration requirements and PLI scheme domestic manufacturing incentives reshape supplier market entry economics. Apollo Hospitals and Max Healthcare in Bangalore deploy localized surgeon training partnerships to accelerate robotic credentialing beyond flagship metros.
Japan
PMDA consultation pathways for novel obesity devices and METI reimbursement pricing surveys for metabolic procedures concentrate demand in academic medical centers. JIS standards for surgical instrument materials influence procurement specifications in national university hospitals. The Keio University Hospital cluster in Tokyo generates real-world evidence for sleeve gastrectomy outcomes that shapes prefectural coverage determinations.
Brazil
ANVISA streamlined registration for Class II surgical instruments and SUS coverage expansion for diabetes remission surgery broaden patient access in southeastern state hospital systems. Unified Health System regional purchasing consortia in São Paulo and Minas Gerais aggregate volume for stapler cartridge negotiations. The Hospital das Clínicas network trains surgical residents who populate private practice capacity in Rio de Janeiro and Brasília.
Global Bariatric Surgery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with robotic platform vendors commanding premium pricing while conventional laparoscopic suppliers compete on per-procedure disposable economics. The market structure consolidates around three tiers: integrated surgical ecosystem providers, specialized stapling and energy device manufacturers, and emerging endoluminal technology developers. Dominant competitive moves include unbundling of service contracts from instrument procurement and geographic expansion through localized surgeon training partnerships.
Among integrated surgical ecosystem providers, Intuitive Surgical and Medtronic occupy positions that exemplify divergent strategic postures toward capital intensity. Intuitive Surgical leverages its installed da Vinci base to sustain recurring revenue streams, while Medtronic anchors market presence through integrated energy and stapling portfolios. Johnson & Johnson sits within the diversified medical technology tier, representing conventional laparoscopic instrument scale advantages.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Johnson & Johnson |
| Boston Scientific |
| Olympus Corporation |
| Apollo Endosurgery |
| Teleflex |
| Conmed |
| Karl Storz |
| Others |
Supply Flow & Price Mechanics
Multi-year service contracts bundled with instrument procurement lock in supply access for robotic platforms while anchoring price visibility across the analysis window. German hospital systems exploit this structure to extract total cost of ownership concessions from vendors, whereas United States group purchasing organizations suppress comparable premiums through volume-commitment leverage.
Pricing Analysis
The customization-premium spread separates standard laparoscopic instrument pricing from configured-to-order robotic console arrangements. Three-tier pricing structure across premium, standard, and economy levels dominates, with articulating staplers commanding premiums based on FDA clearance tier and integrated tissue sensing capability. Pricing pressure stems from hospital supply chain committees unbundling service contracts from disposable procurement in Dutch and German systems. Community hospital systems exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers absorb premium positioning for training and research access.
Supply Chain Analysis
United States and Germany anchor precision stapling device manufacturing, while Ireland and Puerto Rico concentrate final assembly for European and North American distribution. Supply draws from medical-grade stainless steel feedstock, bioabsorbable polymer resins, and specialized tungsten carbide cutting components. Single-source vulnerability concentrates in robotic console annual service contracts where vendor lock-in limits competitive substitution. Distribution runs through hospital supply chain committees and group purchasing organizations that aggregate procurement volume across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement centralization, with German Rhine-Ruhr networks and United States GPOs consolidating purchasing leverage across expanding facility footprints.
For Market Incumbents: Compound ecosystem stickiness through software companion development for metabolic surgery registries and EHR integration, while deepening backward integration into bioabsorbable polymer supply to offset raw material cost volatility. Da Vinci platform vendors face emerging threat from Medtronic's integrated energy-stapling bundles that compete across open and minimally invasive workflows. For New Entrants: Differentiate on sustainability credentials aligned with EU Green Deal circular economy procurement specifications, targeting India's tier-2 city hospital networks where turnkey program establishment remains underpenetrated. Endoluminal revision technologies present the most penetrable white-space segment, with incisionless pouch reduction addressing weight regain populations beyond naive surgical candidates. Go-to-market positioning should emphasize localized surgeon training partnerships rather than capital equipment sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated surgical ecosystem providers with installed platform bases and consumable instrument streams. Long-term viability over the five-to-ten year window favors suppliers with validated EMA MDR recertification pathways and CMS bundled reimbursement alignment. Acquisition target archetype: specialized endoluminal technology developers with CE marking progress and hospital system pilot data. Signal to watch: CMS coverage determinations for preoperative optimization and long-term nutritional monitoring as standard care components.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR recertification deadlines force systematic clinical evidence regeneration for legacy staplers holding existing marks. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic anchor robotic credentialing capacity that disperses regionally through fellowship training pipelines. |
| Reimbursement Strategy | CMS bundled reimbursement expansion for metabolic surgery preoperative optimization accelerates referral pipeline conversion. |
| Software Companion Development | Digital surgical planning and intraoperative navigation compress learning curves for complex revisional procedures. |
| FDA Submission | Premarket notification and de novo pathways for obesity devices reshape product approval timelines for articulating staplers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA premarket submissions, EMA MDR recertification databases, and hospital procurement contract disclosures. Primary interviews engaged metabolic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across United States, German, and Indian health systems. Secondary validation drew from CMS Medicare coverage determinations, CDSCO medical device registration filings, and SEC 10-K instrument revenue segment disclosures. Bottom-up procedure volume modeling triangulated against top-down device expenditure flows.
Segmentation dimensions modeled span procedure type, minimally invasive technique, end user facility tier, and device category across the projection horizon. CAGRs derive from logistic diffusion curves for robotic platform adoption, price elasticity estimates for stapler cartridge procurement, and procedure volume extrapolation from diabetes remission protocol embedding. Industry-specific forecast inputs include EMA MDR recertification timeline compression and PLI scheme domestic manufacturing incentive uptake in India.
Material uncertainties — regulatory pathway delays, payer coverage reversals, and supply chain disruption from circular economy specification changes — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained CMS reimbursement expansion and EMA notified body capacity constraints. Recalibration cycles align with material shifts in bundled reimbursement policy and MDR implementation progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Germany Bariatric Surgery Market