
 All Plastic Front End Module Market | 2026-2036
All Plastic Front End Module Market Size, Share, and Industry Trends Forecast 2026-2036
All Plastic Front End Module Market Analytics
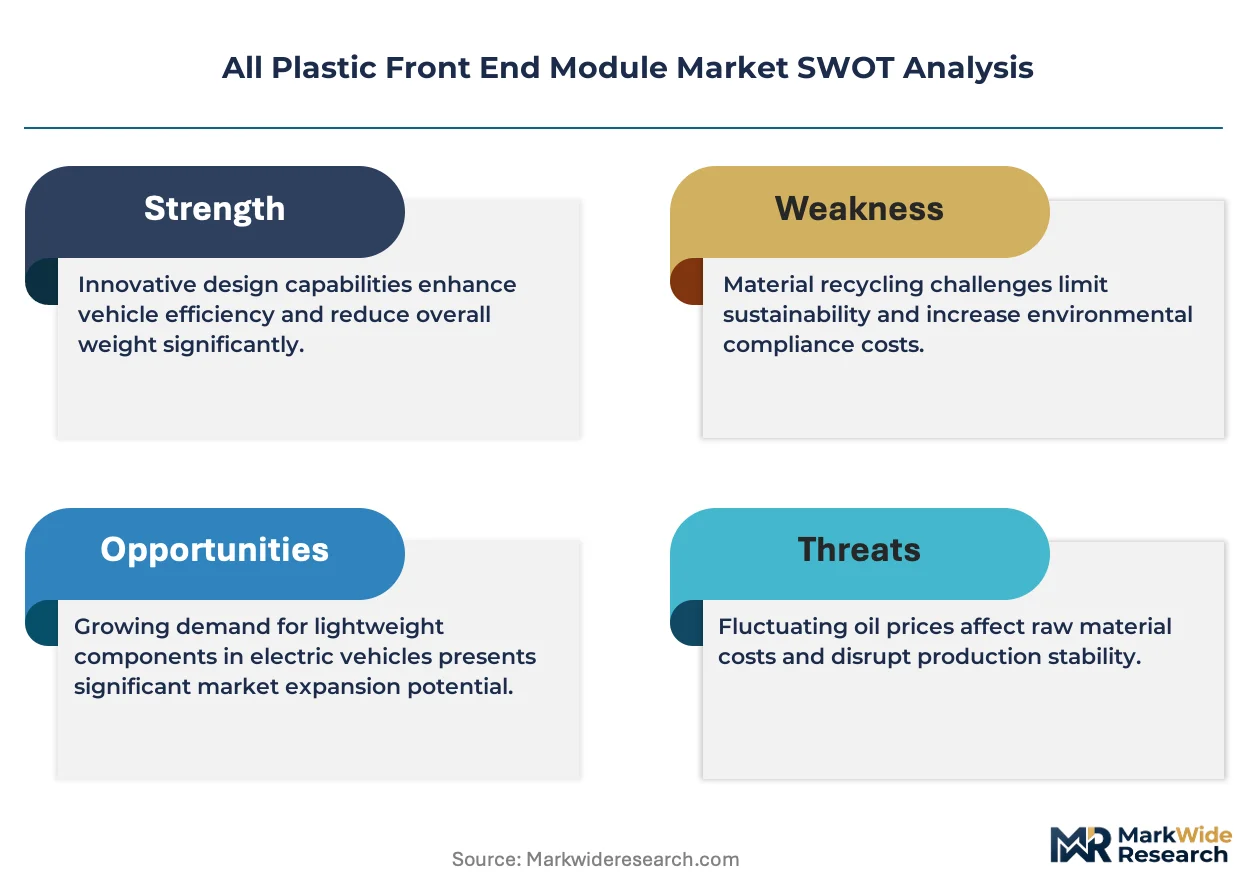
ISO 14001 environmental management certification is collapsing the supplier base for all plastic front end modules, eliminating uncertified molders from Tier-1 procurement lists. Plastic Omnium leverages its vertical integration from resin compounding to module assembly, sustaining cost advantages across European OEM programs. HBPO Group anchors its position through captive engineering partnerships with BMW and Mercedes-Benz, dominating specification-setting for integrated front end architectures. Magna International competes through multi-material expertise, extending beyond pure polymer solutions into hybrid steel-plastic designs.
An all plastic front end module is a structural carrier assembly manufactured from engineered polymers—typically long-glass-fiber-reinforced polypropylene with wall thicknesses of 2.5–4.0 mm—that integrates cooling components, headlights, and crash management systems into a single injection-molded unit, replacing stamped steel or aluminum stampings to reduce vehicle mass by 30–50 percent in the front overhang. Modular systems command the largest share of value given their integration complexity and OEM direct-supply relationships, while composite components represent the fastest-expanding category as Tier-1 suppliers seek to decompose monolithic designs for repairability and recycling compliance. Injection molding technology occupies the dominant process position due to cycle-time efficiency and surface-finish precision, though 3D printing is gaining traction for low-volume prototyping and aftermarket replacement tooling.
The US EPA corporate average fuel economy standards and NHTSA crashworthiness regulations jointly determine material thickness and reinforcement strategies, while Europe's REACH chemical restrictions and Ecodesign framework constrain halogenated flame retardants and certain plasticizers in automotive applications. China's GB standards and MIIT new-energy-vehicle mandates are accelerating localization of module production for domestic EV platforms. Stakeholders must monitor regulatory divergence between emissions-driven lightweighting mandates and end-of-life recycling requirements, as these forces create conflicting material specifications that will define competitive positioning in module design.
Market Dynamics
Electric vehicle platform architectures are compressing front end module development cycles, forcing suppliers to synchronize polymer formulations with battery thermal management requirements rather than traditional engine cooling layouts.
Growth Catalysts
- EU Ecodesign Framework:End-of-life vehicle directives mandate recyclable single-material assemblies, accelerating OEM specifications for pure polymer carriers over hybrid metal-plastic designs.
- Long-glass-fiber compounding:Advanced polypropylene formulations achieve structural parity with aluminum at 40% lower mass, penetrating premium EV architectures first.
- Stuttgart engineering cluster:German OEM technical centers are embedding front end module engineers into battery platform development teams, collapsing design iteration timelines.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs track naphtha and propylene monomer indices, compressing molders' margin buffers during upstream petrochemical disruptions.
- Tooling capex concentration:Large-tonnage injection presses exceeding 4,000 metric tons lock capital in Germany, China, and the US, constraining regional supply elasticity.
- REACH chemical restrictions:ECHA scrutiny of halogenated flame retardants limits formulation options for crash-rated modules, forcing reformulation investments.
Strategic Opportunities
- India PLI scheme:Domestic automotive component manufacturing incentives are attracting module assembly localization for Maruti Suzuki and Tata Motors EV platforms.
- 3D printed repair tooling:Additive manufacturing of replacement fixture components enables aftermarket service networks to bypass OEM captive parts distribution.
- Battery thermal integration:Front end carriers are absorbing coolant routing and charge port housing functions previously assigned to separate stampings.
Industry Challenges
- Simulation talent scarcity:Mold flow analysis for long-fiber orientation prediction requires specialized CAE engineers concentrated at German polytechnic institutes.
- ISO 14001 certification backlog:Environmental management system audits face 12-month scheduling delays at accredited bodies, freezing uncertified suppliers out of RFQ processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All Plastic Front End Module Market |
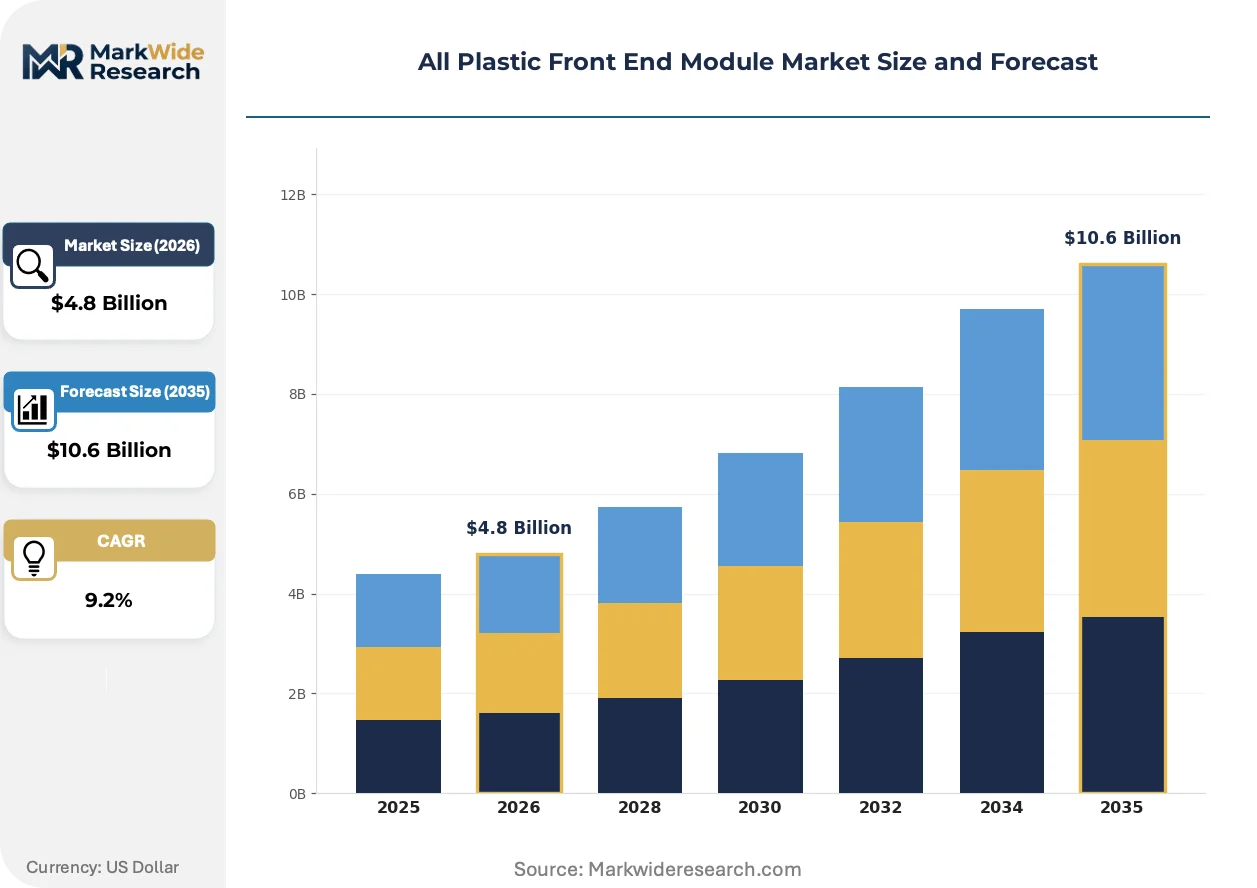
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Composite Components, Chassis Parts, Structural Assemblies End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Polypropylene, Polycarbonate, ABS, Nylon Technology: Injection Molding, Blow Molding, 3D Printing, Thermoforming |
| Companies Covered | Plastic Omnium, HBPO Group, Magna International, Hyundai Mobis, Denso Corporation, Faurecia, Valeo, Calsonic Kansei, Mahle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All Plastic Front End Module Market Evolving Landscape
Material science advances and regulatory chemistry constraints are rewriting specification standards for structural automotive polymers, collapsing the historical separation between crash performance and recyclability mandates.
Long-glass-fiber-reinforced thermoplastic composites are displacing short-fiber grades in load-bearing front end carrier applications. BMW and Mercedes-Benz EV architectures specify 50-60% glass loading for bumper beam integration. This material upgrade is displacing hybrid steel-plastic designs previously used to bridge stiffness requirements.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of flame-retardant polymer systems. Compounders are migrating to phosphorus-based and mineral filler alternatives for crash-rated modules. Tier-1 suppliers serving German OEMs face the most compressed compliance timelines given ECHA authorization sunset dates.
Direct OEM engineering engagement is replacing traditional Tier-1 specification control. Automakers are embedding polymer scientists into platform development teams, collapsing the historical boundary between resin supplier and module assembler. This pattern is most visible in Germany, where Stuttgart and Munich engineering clusters co-locate OEM, compounder, and molder technical staff.
All Plastic Front End Module Market Segmentation
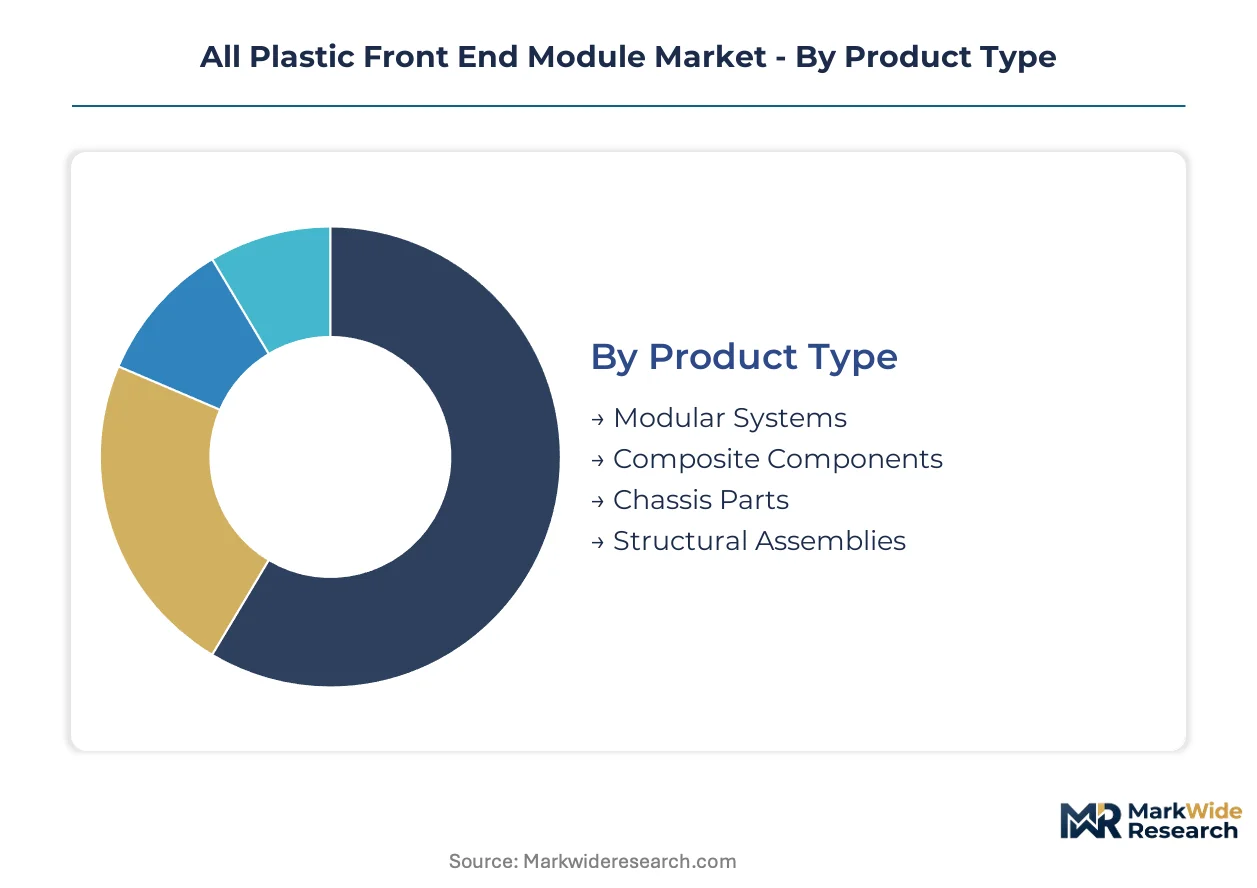
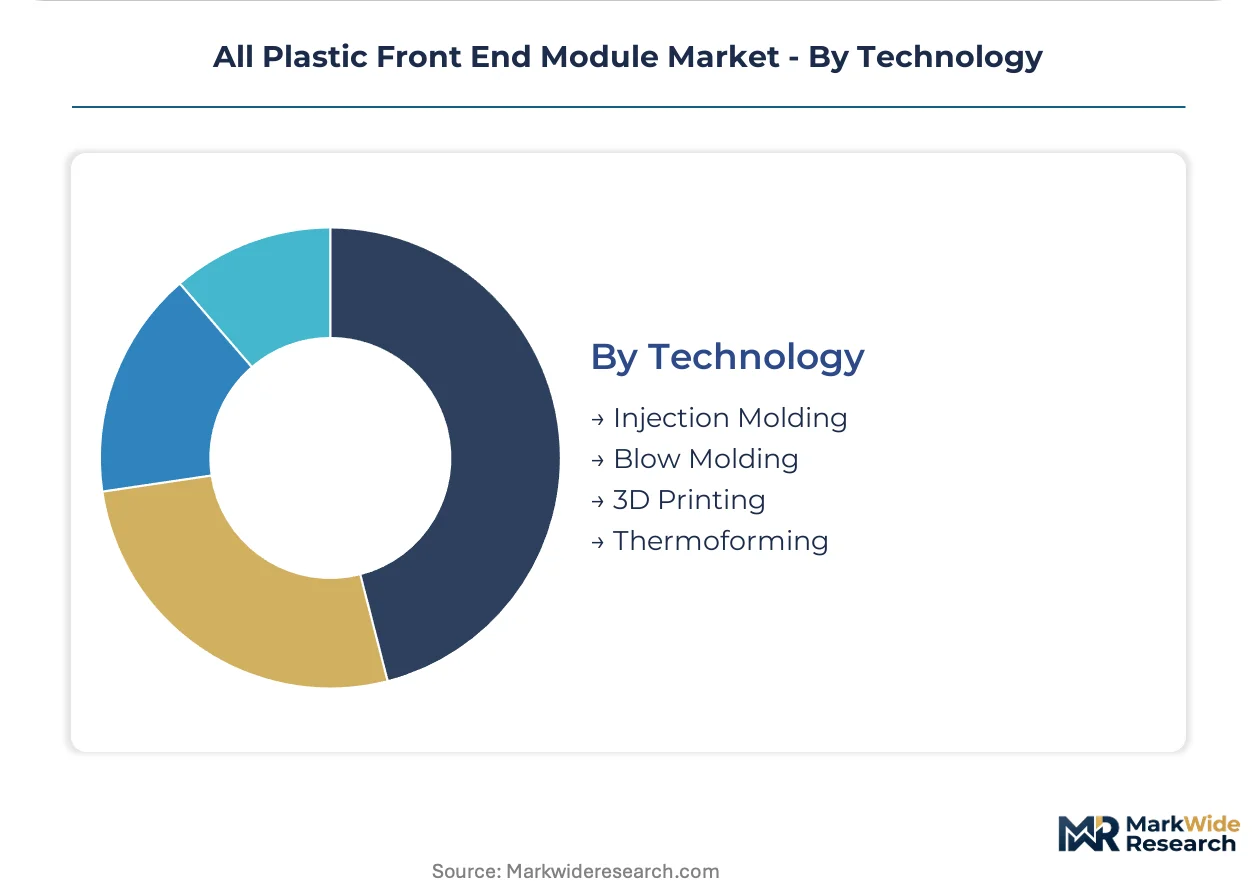
Segmentation in the all plastic front end module market reveals how engineering complexity, regulatory chemistry constraints, and supply chain positioning create distinct commercial pathways. Each dimension—product architecture, procurement channel, material specification, and manufacturing process—carries unique margin structures and certification requirements that determine supplier viability.
Product Type:
Channel distribution varies sharply by integration level, with fully assembled modular systems flowing direct to OEM engineering teams while discrete composite components move through Tier-1 distributors serving repair networks.
- Modular Systems:These integrated carrier assemblies combine cooling modules, headlight housings, and crash management into single injection-molded units. BMW and Mercedes-Benz EV platforms in Germany specify these for their Stuttgart and Munich assembly plants, driven by Ecodesign mandates for recyclable single-material construction.
- Composite Components:Decomposed sub-assemblies designed for repairability and end-of-life disassembly. These are gaining specification share fastest among European OEMs confronting REACH recycling compliance deadlines, particularly for bumper beam and grille surround applications.
- Chassis Parts:Lower-integration structural elements including radiator supports and fender liners. These flow primarily through Tier-1 supplier catalogs for legacy internal combustion platforms.
- Structural Assemblies:Load-bearing carriers for hood latches and hinge mountings. Demand concentrates in US pickup and SUV segments where NHTSA pedestrian protection standards dictate reinforcement strategies.
By volume, modular systems lead given their dominance in premium EV architectures. By growth pace, composite components are climbing the fastest as repairability regulations tighten across European markets.
End User:
Procurement authority is fragmenting as automakers embed polymer scientists into platform teams, collapsing traditional Tier-1 specification control and creating direct resin supplier relationships.
- OEMs:Direct engineering engagement now dominates specification-setting for new EV platforms. German automakers maintain captive polymer laboratories in Stuttgart and Munich that validate long-glass-fiber formulations before production authorization.
- Tier-1 Suppliers:Module assemblers serving multiple OEM programs face compressed margins from resin price volatility. These suppliers concentrate in Germany, China, and the US where large-tonnage injection press capacity locks capital.
- Aftermarket Providers:Service networks sourcing replacement modules and repair tooling. India's PLI scheme is attracting assembly localization for Maruti Suzuki and Tata Motors EV platforms.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities. These operations typically procure through approved Tier-1 vendor lists with ISO 14001 certification requirements.
OEMs command specification authority for new platforms. Tier-1 suppliers retain volume leadership in legacy program fulfillment.
Material:
Cost tiers separate by performance grade, with long-glass-fiber-reinforced grades commanding premium positioning over commodity formulations.
- Polypropylene:Long-glass-fiber-reinforced grades achieve structural parity with aluminum at reduced mass. These formulations dominate German premium EV specifications where Ecodesign recyclability mandates favor single-material solutions.
- Polycarbonate:Optical-grade specifications for headlight lenses and transparent grille elements. Demand concentrates in styling-driven premium segments where surface finish precision justifies material cost premiums.
- ABS:Lower-cost option for non-structural cosmetic components. These formulations face REACH scrutiny on plasticizer content, forcing compound reformulation investments.
- Nylon:High-heat applications including engine bay proximity components. Niche positioning as EV thermal architectures shift cooling loads to front end carriers.
Polypropylene holds volume dominance across all major production regions. Nylon is expanding most quickly from a small base as battery thermal integration creates new application spaces.
Technology:
Maturity gradients separate established high-volume processes from emerging capabilities, with capital intensity and cycle time determining regional supply concentration.
- Injection Molding:Large-tonnage presses exceeding 4,000 metric tons dominate structural carrier production. Cycle-time efficiency and surface-finish precision sustain this technology's grip on OEM direct-supply contracts in Germany and China.
- Blow Molding:Hollow-section components including coolant reservoirs and ducting. Lower capital requirements attract regional suppliers serving secondary assembly operations.
- 3D Printing:Additive manufacturing for prototyping and aftermarket repair tooling. This technology is gaining fastest among service networks seeking to bypass OEM captive parts distribution.
- Thermoforming:Limited to large-format non-structural panels where wall thickness tolerance is less critical. Marginal positioning in front end module applications.
Injection molding anchors production volume globally. 3D printing is advancing most rapidly from minimal base as digital tooling disrupts traditional aftermarket supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's polymer import infrastructure for automotive molding operations. This maritime gateway sustains feedstock flows to Stuttgart and Munich engineering clusters where specification standards crystallize.
Germany
Long-glass-fiber formulation demand concentrates around BMW and Mercedes-Benz EV platform teams in Stuttgart. REACH Annex XVII restrictions on halogenated flame retardants compress compliance timelines for compounders serving these OEMs. Munich's technical centers now embed polymer scientists directly into battery thermal management development cycles.
China
MIIT new-energy-vehicle mandates accelerate localization of module production for domestic EV platforms. GB standards for automotive plastics constrain formulation choices differently than European regulations. Yangtze River Delta molding operations around Shanghai lock large-tonnage injection press capacity for structural carrier production.
United States
NHTSA crashworthiness regulations and EPA corporate average fuel economy standards jointly determine material thickness strategies for pickup and SUV segments. The Detroit Three maintain polymer laboratories that validate formulations before production authorization. Midwest tooling corridors concentrate capital in presses exceeding 4,000 metric tons.
India
PLI scheme incentives attract module assembly localization for Maruti Suzuki and Tata Motors EV platforms. BIS automotive component standards create certification requirements distinct from European or North American regimes. Tamil Nadu and Gujarat manufacturing corridors concentrate Tier-1 supplier investments.
Japan
METI carbon neutrality roadmaps reshape material selection criteria for domestic automaker platforms. JIS standards for automotive plastics maintain specification independence from European REACH frameworks. Nagoya engineering clusters coordinate resin supplier and OEM technical staff for platform development cycles.
All Plastic Front End Module Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and specification-setting authority. The supplier base consolidates around molders with ISO 14001 certification and large-tonnage press capacity, eliminating uncertified competitors from Tier-1 procurement lists. Three archetypes dominate: vertically integrated resin-to-module operators, captive engineering partners for premium OEMs, and multi-material specialists extending beyond pure polymer solutions. Competitive moves concentrate on backward integration into resin compounding and geographic expansion to follow EV platform localization.
Among European-based fabricators, Plastic Omnium SE and HBPO Group exemplify contrasting scale and specialization strategies. Magna International Inc. represents North American multi-material capability. These three anchors illustrate how certification, capital, and customer proximity stratify competitive positioning across premium EV platform supply.
| Leading Market Players |
|---|
| Plastic Omnium |
| HBPO Group |
| Magna International |
| Hyundai Mobis |
| Denso Corporation |
| Faurecia |
| Valeo |
| Calsonic Kansei |
| Mahle GmbH |
| Others |
Value Network & Pricing Analysis
ISO 14001 certification gates both supplier qualification and price differentiation in the all plastic front end module market, eliminating uncertified molders from Tier-1 procurement lists while commanding premium positioning for certified operators serving German OEM programs. This environmental management standard collapses the supplier base into two tiers: certified molders with pricing power and excluded competitors forced into aftermarket or non-automotive channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates long-glass-fiber-reinforced polypropylene formulations from commodity short-fiber grades and uncertified imports. Price differentiation hinges on ISO 14001 certification status and glass loading percentage, with 50-60% reinforced grades commanding structural premiums for BMW and Mercedes-Benz EV platforms. Cost compression in standard-tier modules is intensifying because resin price volatility tracks naphtha and propylene monomer indices. Aftermarket providers exhibit highest price sensitivity, while OEM direct-supply contracts prioritize performance specifications over unit economics.
Supply Chain Analysis
The Port of Hamburg's container throughput underwrites polymer feedstock flows to Stuttgart and Munich engineering clusters, creating a logistics chokepoint for European automotive molding operations. Supply concentrates in Germany, China, and the United States where large-tonnage injection presses exceeding 4,000 metric tons lock capital. Raw material dependencies draw from propylene monomer, glass fiber roving, and phosphorus-based flame retardant formulations. Single-source vulnerability concentrates in German compounders serving REACH-compliant formulations for premium OEM specifications. Distribution runs through Tier-1 supplier networks for legacy programs and direct OEM engineering channels for new EV platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German OEM platform teams embedding polymer scientists into battery thermal development cycles, fragmenting traditional Tier-1 specification control and collapsing procurement authority into direct resin supplier relationships.
For Market Incumbents: Fortify backward integration into long-glass-fiber compounding to defend margin buffers against resin price volatility tracking naphtha indices. Prioritize ISO 14001 certification maintenance to preserve Tier-1 procurement list eligibility as ECHA scrutiny tightens on halogenated flame retardants. Capacity addition in China's Yangtze River Delta secures proximity to MIIT-mandated EV platform localization.
For New Entrants and Emerging Players: Lead with 3D printed repair tooling for aftermarket service networks seeking to bypass OEM captive parts distribution. India's PLI scheme offers the most penetrable geography for module assembly localization serving Maruti Suzuki and Tata Motors EV platforms. Target battery thermal integration applications where front end carriers absorb coolant routing functions previously assigned to separate stampings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed molders lacking ISO 14001 certification and facing exclusion from RFQ processes. Long-term viability over a 5-10 year window favors compounders with captive resin formulation capabilities and direct OEM engineering partnerships. Monitor ECHA authorization sunset dates for halogenated flame retardants as an inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive control over long-glass-fiber formulations insulates Plastic Omnium from propylene monomer price swings. |
| Battery Thermal Integration Partnership | Coolant routing absorption into front end carriers deepens HBPO Group's embedded role in BMW platform teams. |
| ISO 14001 Certification Acceleration | Environmental management system completion unlocks Tier-1 supplier status before audit backlog extends beyond 12 months. |
| India PLI Scheme Localization | Tamil Nadu manufacturing corridor positioning captures Maruti Suzuki and Tata Motors EV module assembly mandates. |
| Phosphorus-Based Flame Retardant Migration | REACH Annex XVII compliance reformulation preserves German OEM supply relationships through ECHA sunset deadlines. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, resin compounder technical directors, and aftermarket distributor operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and REACH Annex XVII regulatory filings. Bottom-up triangulation against top-down market sizing ensured consistency across module volume estimates and material consumption forecasts.
Outputs were validated against external benchmarks including production capacity disclosures from large-tonnage injection press manufacturers and resin consumption trends reported by European compounder associations. Segmentation dimensions modeled encompass product architecture, procurement channel, material specification, manufacturing process, and regional production cluster. CAGRs were derived from slope analysis of year-over-year growth patterns adjusted for platform transition timelines. Industry-specific forecast inputs incorporated EV platform launch schedules and Ecodesign recycling compliance deadlines.
Underlying assumptions cover sustained EV platform rollout momentum, REACH chemical restriction enforcement timelines, and resin feedstock price stability, with deviation risk concentrated in petrochemical supply disruptions and regulatory divergence between lightweighting mandates and end-of-life recycling requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Global Car Air Purifier Market