
 North America Automotive Market | 2026-2036
North America Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Market Outlook
Detroit's legacy automakers is rebalancing production capacity toward electrification after decades of SUV and truck dominance. General Motors sustains vertical integration through its Ultium battery platform and dedicated EV assembly plants in Michigan and Tennessee. Ford Motor Company anchors its position with the F-150 Lightning and commercial fleet electrification programs targeting utility and logistics buyers. Tesla dominates battery cost curves and software-defined vehicle architecture, forcing incumbent redesign cycles.
The North America Automotive sector encompasses the design, engineering, and assembly of passenger and commercial vehicles powered by internal combustion, hybrid, or fully electric drivetrains, with unibody or body-on-frame construction, crash safety ratings per FMVSS protocols, and connected-vehicle communication stacks. Its primary purpose is to provide mobility for individual consumers, commercial fleets, and public agencies across varied terrain, climate, and duty cycles. The fuel type dimension shows electric and hybrid architectures capturing incremental share as battery energy density improves and charging infrastructure densifies, while pickup trucks and SUVs within vehicle type generate outsized margin pools due to higher average transaction prices and accessory content. Autonomous driving technology remains concentrated in premium trims and commercial pilot programs, with safety features now standard across mass-market segments.
The US EPA, NHTSA, and California Air Resources Board collectively shape vehicle design through Corporate Average Fuel Economy mandates, greenhouse gas emission limits, and zero-emission vehicle sales requirements that manufacturers must satisfy for market access. Canada's Environment and Climate Change Canada aligns with US federal standards under the integrated auto sector framework, while Mexico's environmental regulator implements parallel tailpipe rules affecting cross-border supply chains. Stakeholders must monitor how battery mineral sourcing rules under the US Inflation Reduction Act alter eligible vehicle tax credits and reshape supplier geography across the continent.
Market Dynamics
The US EPA tailpipe emission standards and California's Advanced Clean Cars II program are compressing the compliance window for internal combustion engines, forcing capital reallocation toward electrified drivetrains and battery supply chain localization.
Growth Catalysts
- Zero-emission vehicle mandates:California Air Resources Board's ACC II program requires escalating ZEV sales percentages, pulling battery electric vehicle demand forward across the US Southeast manufacturing corridor.
- Fleet electrification:Utility and logistics operators are consolidating procurement around electric drivetrains for total cost of ownership advantages in last-mile and regional haul duty cycles.
- Battery energy density gains:Solid-state and high-nickel cathode chemistries are extending range capabilities, reducing range anxiety barriers in cold-climate states.
Market Restraints
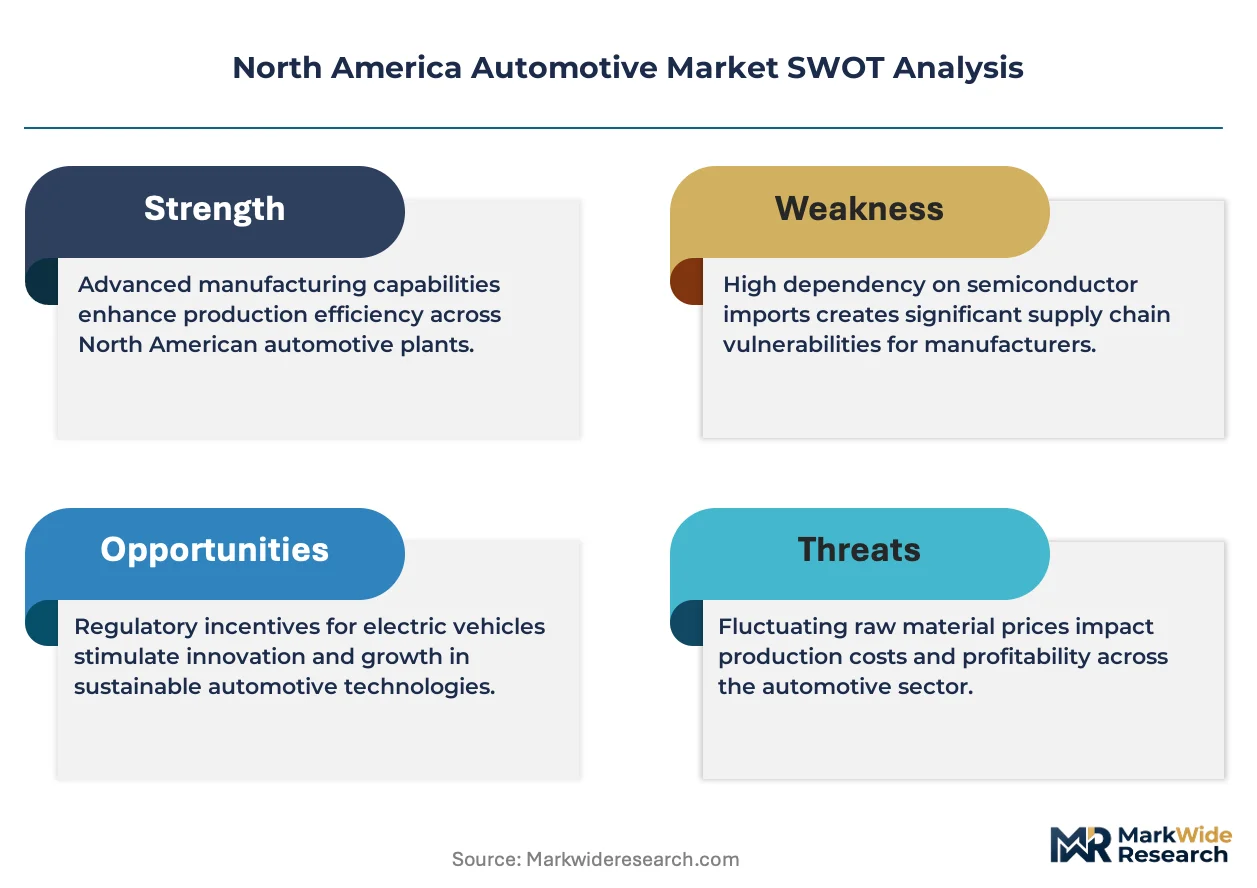
- Lithium and cobalt concentration:Cathode active material supply chains remain concentrated with Chinese chemical processors, creating geopolitical exposure for North American cell manufacturers.
- Charging infrastructure gaps:Rural interstate corridors and multi-unit residential buildings lack sufficient DC fast charging density to support mass-market adoption outside urban cores.
- Grid interconnection delays:Utility-scale charging depot upgrades face 18-36 month transmission queue timelines, throttling commercial fleet electrification rollouts.
Strategic Opportunities
- US Inflation Reduction Act battery sourcing:Critical mineral and component assembly requirements for consumer tax credits are incentivizing North American mining and cell manufacturing investments.
- Vehicle-to-grid integration:Bidirectional charging capabilities in electric pickups and commercial vans create distributed energy resource revenue streams for fleet operators.
- Mexico nearshoring:Cross-border supplier parks in Nuevo León and Coahuila offer tariff-advantaged component sourcing for US assembly plants.
Industry Challenges
- Electrical engineering talent scarcity:Power electronics and battery management system expertise shortages are extending product development cycles and inflating compensation costs.
- Legacy powertrain retooling:Internal combustion engine manufacturing facilities require $500M-$2B conversion investments for electric vehicle assembly, straining balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Market |
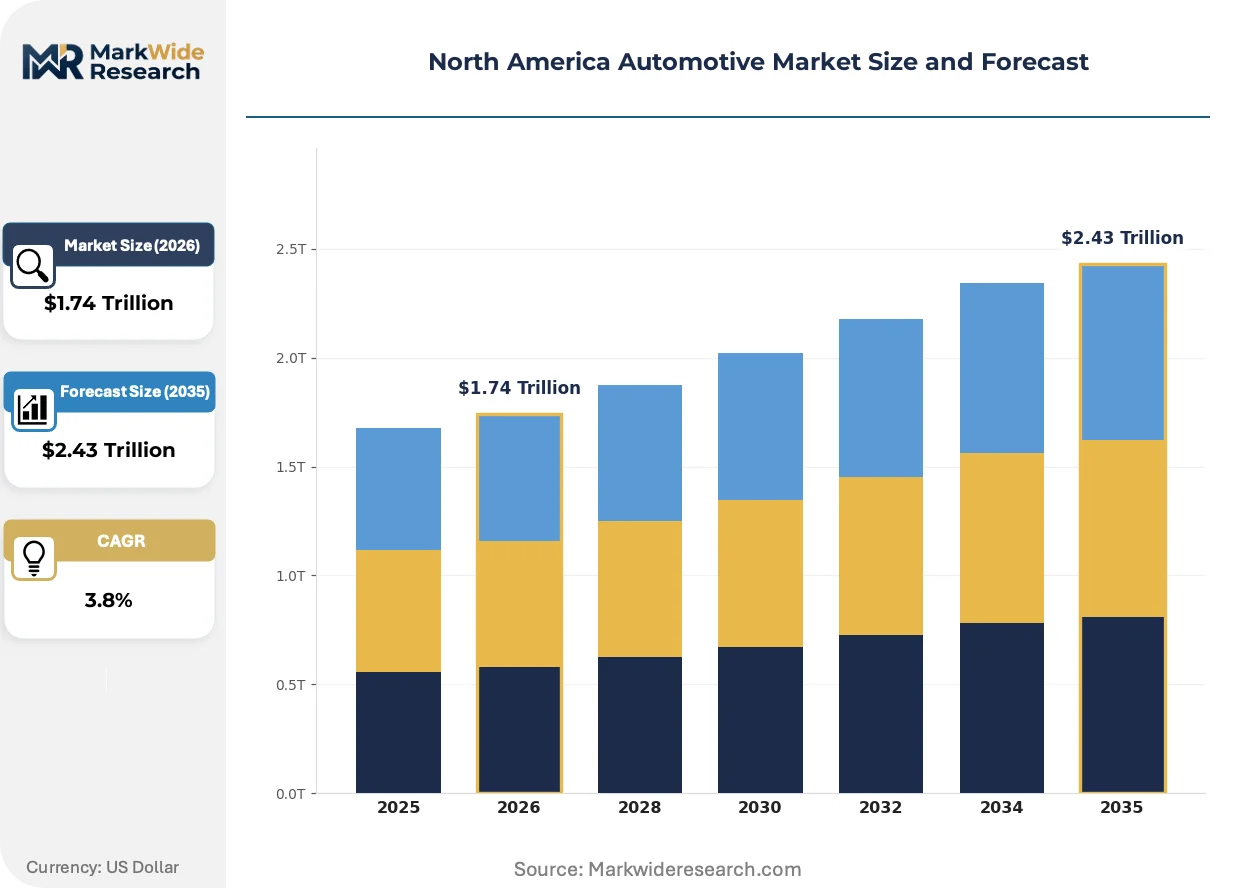
| Market Size in 2026 | $1.74 Trillion |
| Market Size in 2035 | $2.43 Trillion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Pickup Truck, Hatchback Fuel Type: Petrol, Diesel, Electric, Hybrid End User: Individual Consumers, Fleet Operators, Dealerships, Government Agencies Technology: Autonomous Driving, Infotainment Systems, Telematics, Safety Features |
| Companies Covered | General Motors, Toyota Motor Company, Ford Motor Company, Stellantis, Honda, Hyundai-Kia, Tesla, Nissan, BMW, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Market Strategic Shifts
Software-defined vehicle architectures are decoupling hardware from feature delivery, enabling over-the-air updates that extend revenue capture beyond the initial transaction.
800-volt electrical architectures are rewriting thermal management and charging speed expectations in the premium segment. Porsche, Hyundai, and General Motors have deployed these platforms, cutting DC fast charging times from 10-80% state of charge to under 20 minutes. This voltage transition is compressing the competitive window for 400-volt platforms in the mass market.
The US Inflation Reduction Act's domestic content requirements are reshaping supplier geography across the continent. Battery cell and pack assembly must originate in North America to preserve consumer tax credits, accelerating greenfield investments in Michigan, Tennessee, and Kentucky. Mexico's integrated auto sector framework allows component qualification under USMCA rules of origin, creating cross-border supply chain reconfigurations.
Fleet procurement departments are consolidating vehicle sourcing around total cost of ownership metrics rather than upfront capital expenditure. Rental car, delivery, and utility fleet managers are negotiating direct battery service agreements and residual value guarantees with manufacturers. This shift is most pronounced in California and the US Northeast, where state-level ZEV mandates intersect with high electricity cost differentials versus gasoline.
North America Automotive Market Segmentation
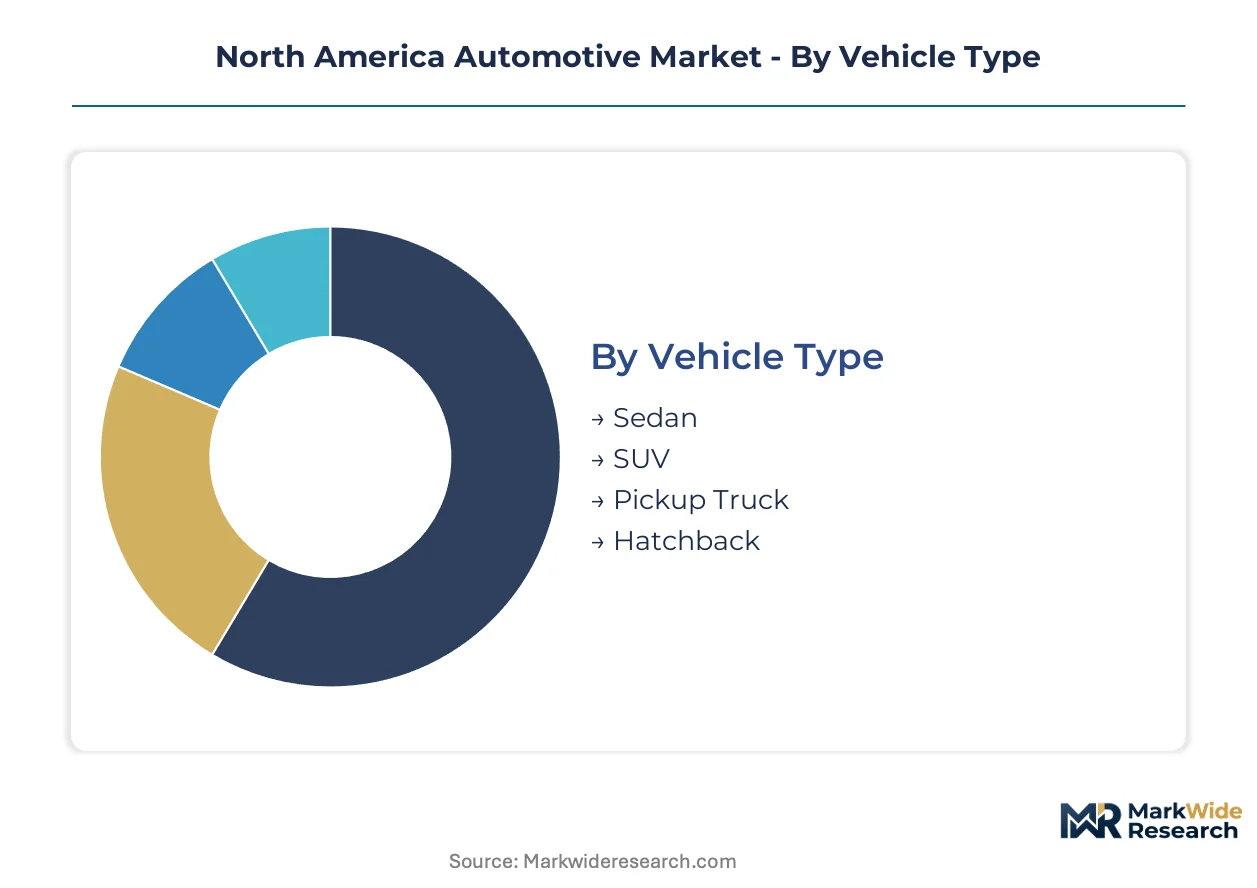
Segmentation in the North America Automotive Market reveals how regulatory pressure and infrastructure readiness distribute unevenly across vehicle configurations. Manufacturers must align production with distinct certification pathways, buyer economics, and technology maturity curves to optimize capital deployment.
Vehicle Type:
FMVSS crash testing protocols apply uniformly, but EPA greenhouse gas compliance burdens vary sharply by segment mass and aerodynamic profile.
- SUV:Unibody and body-on-frame architectures dominate family transportation and fleet crossover applications. Demand concentrates in the US Southeast manufacturing corridor where Tennessee and Georgia assembly plants supply dealers across Sun Belt states with lower electricity cost differentials favoring larger battery packs.
- Pickup Truck:Body-on-frame construction with high towing capacity anchors commercial fleet procurement and personal utility buyers. Ford, General Motors, and Ram capture outsized margins through tiered trim structures, with electrified variants targeting utility and logistics operators in Texas and California markets.
- Sedan:Three-box passenger car designs with lower center of gravity remain significant in rental fleet and urban commuter segments.
- Hatchback:Compact two-box configurations with flexible cargo capacity serve price-sensitive urban buyers and European-influenced coastal markets.
Leading the category by volume: SUV. Growing fastest: Pickup Truck.
Fuel Type:
EPA tailpipe standards and California's ACC II program create divergent compliance economics across propulsion architectures.
- Electric:Battery electric drivetrains with zero direct emissions require US Inflation Reduction Act mineral sourcing compliance for consumer tax credit eligibility. Demand concentrates in California and the US Northeast where state ZEV mandates intersect with high gasoline-electricity cost spreads, though charging infrastructure gaps persist in rural interstate corridors.
- Hybrid:Parallel and series-parallel architectures combining internal combustion with electric assist deliver immediate fuel economy gains without charging dependency. Toyota, Honda, and Ford hybrid systems capture fleet buyers seeking total cost of ownership reduction in last-mile delivery and regional haul duty cycles.
- Petrol:Spark-ignition internal combustion engines with port and direct injection remain prevalent in price-sensitive segments and cold-climate states.
- Diesel:Compression-ignition engines with high torque output serve heavy-duty pickup and commercial van applications requiring towing capacity.
Hybrid architectures command the largest transaction volume. Electric drivetrains show the steepest expansion trajectory as battery energy density improves.
End User:
Procurement patterns split between retail transaction economics and fleet total cost of ownership optimization.
- Fleet Operators:Utility, logistics, and rental companies negotiate direct manufacturer relationships with battery service agreements and residual value guarantees. Electrification concentrates in California and the US Northeast where state mandates and electricity cost differentials align, though grid interconnection delays throttle depot charging rollouts.
- Individual Consumers:Retail buyers prioritize monthly payment affordability, brand loyalty, and feature content over lifecycle cost analysis. Southeast and Southwest states show highest pickup and SUV preference due to terrain, climate, and fuel price sensitivity.
- Government Agencies:Municipal, state, and federal procurement follows Federal Acquisition Regulation guidelines with increasing ZEV procurement mandates.
- Dealerships:Franchise and independent dealer networks manage inventory risk, floorplan financing, and manufacturer incentive programs.
Fleet operators are expanding procurement fastest. Individual consumers retain dominant volume share.
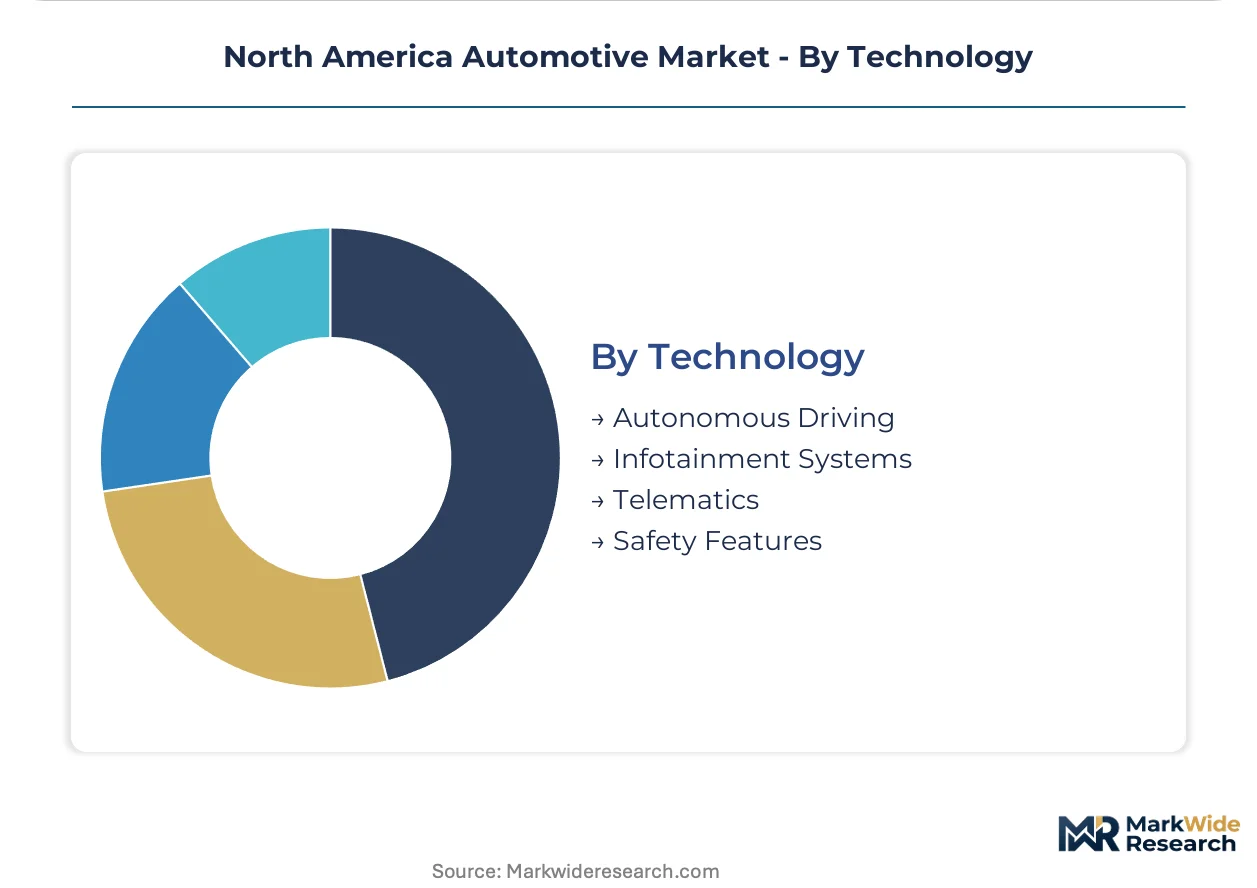
Technology:
NHTSA and insurance industry crash testing protocols drive standardization of active safety systems while autonomous features remain premium-tier options.
- Safety Features:Automatic emergency braking, lane departure warning, and blind spot monitoring achieve mass-market standardization through IIHS Top Safety Pick requirements and NHTSA NCAP ratings. These systems now penetrate entry trim levels as manufacturers defend liability exposure and brand positioning.
- Infotainment Systems:Touchscreen-centered human-machine interfaces with smartphone integration and subscription revenue potential define cabin experience differentiation. General Motors, Ford, and Stellantis deploy proprietary software stacks to capture recurring revenue beyond initial transaction.
- Telematics:Cellular-connected vehicle data transmission enables remote diagnostics, stolen vehicle recovery, and usage-based insurance.
- Autonomous Driving:SAE Level 2 and 3 conditional automation remains concentrated in premium trims and commercial pilot programs due to regulatory uncertainty and liability frameworks.
Safety features lead technology deployment by unit volume. Autonomous driving systems are gaining share fastest in premium segments and commercial logistics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Nevada's Clayton Valley and cobalt refining capacity in Ontario anchor North American battery supply chain investments. These raw material localities are pulling cell manufacturing and vehicle assembly into regional proximity.
United States
Fleet electrification programs and consumer tax credit eligibility under the Inflation Reduction Act drive procurement shifts. The EPA tailpipe emission standards and California's ACC II program compress ICE compliance windows. Michigan and Tennessee assembly plants concentrate Ultium battery platform production for Southeast distribution.
Canada
Critical mineral processing investments and integrated auto sector alignment with US federal standards attract supply chain capital. Environment and Climate Change Canada maintains harmonized greenhouse gas rules affecting cross-border component flows. Ontario's Windsor-Oshawa corridor hosts Stellantis and Ford battery plant investments serving Great Lakes assembly.
Mexico
Nearshoring advantages under USMCA rules of origin and labor cost differentials pull component manufacturing south. The environmental regulator implements parallel tailpipe standards affecting supplier park configurations. Nuevo León and Coahuila border states concentrate EV component fabrication for Tennessee and Texas assembly plants.
California
Zero-emission vehicle mandates and high gasoline-electricity cost spreads accelerate fleet and retail electrification. The Air Resources Board's ACC II program requires escalating ZEV sales percentages through 2035. Fremont and Los Angeles Basin manufacturing clusters anchor Tesla and legacy automaker EV output for Western states.
Texas
Utility fleet procurement and commercial logistics electrification target total cost of ownership advantages in regional haul duty cycles. State-level electricity market deregulation supports depot charging infrastructure buildout. The Austin-San Antonio corridor hosts Tesla's assembly expansion and supplier logistics hubs serving Sun Belt demand.
North America Automotive Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined vehicle architectures and direct-to-consumer distribution. The market structures around three legacy Detroit manufacturers, a dominant California-based EV pure-play, and Asian transplants with hybrid technology depth. Strategic archetypes include vertically integrated battery platforms, fleet-focused commercial electrification programs, and premium software-centric positioning. Competitive moves concentrate on cell manufacturing joint ventures and over-the-air capability deployment.
Among Detroit-based legacy manufacturers, General Motors and Ford Motor Company exemplify platform-centric electrification strategies, while Tesla occupies the pure-play EV archetype with cost curve advantages in battery pack integration. These three entities represent contrasting approaches to capital allocation: captive cell manufacturing partnerships, commercial fleet verticals, and software-first architecture development.
| Leading Market Players |
|---|
| General Motors |
| Toyota Motor Company |
| Ford Motor Company |
| Stellantis |
| Honda |
| Hyundai-Kia |
| Tesla |
| Nissan |
| BMW |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement consolidation around total cost of ownership metrics is forcing manufacturers to unbundle battery service agreements from vehicle transactions, compressing upfront sticker prices while shifting revenue capture toward recurring service streams.
Pricing Analysis
Warranty and service bundling separates premium electric pickup configurations from mass-market economy tiers, with Ford and General Motors offering extended battery coverage as a price differentiator against Tesla's software-centric model. Price differentiation rests on charging speed tiering and cold-climate range certification, with 800-volt platforms commanding premiums over 400-volt architectures. Cost compression in the standard tier is intensifying because IRA mineral sourcing compliance adds qualification overhead. Fleet operators show lowest price sensitivity due to depreciation and fuel cost modeling, while individual retail buyers in the Southeast remain most responsive to monthly payment thresholds.
Supply Chain Analysis
Qualification gating under USMCA rules of origin and IRA domestic content requirements is reshaping supplier geography across Mexico, Canada, and the United States. Cathode active material supply draws from Chinese chemical processors, Canadian cobalt refining, and Nevada lithium extraction, creating single-source vulnerability in precursor chemicals. Distribution runs through cross-border supplier parks in Nuevo León and Coahuila feeding Tennessee and Michigan assembly plants, with tariff exposure concentrated in battery component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Automotive Market sits in a technology-transition phase where battery electric drivetrains are displacing internal combustion architectures under regulatory compression.
For Market Incumbents: Hedge against power electronics talent scarcity by acquiring captive cell manufacturing capacity in Kentucky or Tennessee, and defend margin position through Ultium-style platform standardization that spreads R&D across multiple vehicle programs. The threat from Tesla's software-defined vehicle architecture demands accelerated over-the-air capability deployment to preserve aftermarket revenue streams. For New Entrants and Emerging Players: California's ACC II program in the United States opens a window for fleet-focused electric van and last-mile delivery vehicle specialization, targeting utility and logistics operators in the Northeast corridor where state ZEV mandates intersect with high electricity cost differentials. White-space targets include bidirectional charging integration for vehicle-to-grid revenue and commercial depot charging software. A direct battery service agreement go-to-market model bypasses dealership channel friction. For Investors and Strategic Acquirers: The window for entry favors Tier 1 power electronics and battery management system specialists with automotive qualification pedigree and scarce electrical engineering talent pools. Long-term viability hinges on IRA tax credit eligibility through North American mineral and component assembly compliance. The signal to watch is grid interconnection queue clearance rates for commercial fleet depot upgrades, indicating throttle release on electrification rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in cathode material flows from Canadian and Nevada sources for IRA credit eligibility. |
| Software-Defined Vehicle Investment | Enables General Motors and Ford to capture subscription revenue beyond initial transaction. |
| Geographic Manufacturing Footprint | Positions assembly plants in Tennessee and Georgia for Southeast Sun Belt demand concentration. |
| Charging Infrastructure Partnership | Resolves rural interstate DC fast charging gaps throttling mass-market adoption. |
| Platform Standardization | Spreads Ultium and F-150 Lightning development costs across multiple vehicle programs. |
Study Parameters
Document review covered EPA regulatory filings, NHTSA safety databases, California Air Resources Board rulemakings, and USMCA origin documentation, complemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, dealership operations directors, and aftermarket distributors. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC automotive segment disclosures, and utility interconnection queue reports. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Unit shipment and revenue estimates across the projection horizon reflect segment-level modeling of vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical powertrain mix shifts and regulatory mandate trajectories, with battery energy density improvement curves and charging infrastructure buildout schedules as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about IRA credit continuity and EPA tailpipe standard enforcement. A model refresh is warranted upon material change in California ACC II program implementation timelines or USMCA rules of origin interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Large Suvs Market