
 India Luxury Car Market | 2026-2036
India Luxury Car Market Size, Share, and Industry Trends Forecast 2026-2036
India Luxury Car Market Outlook
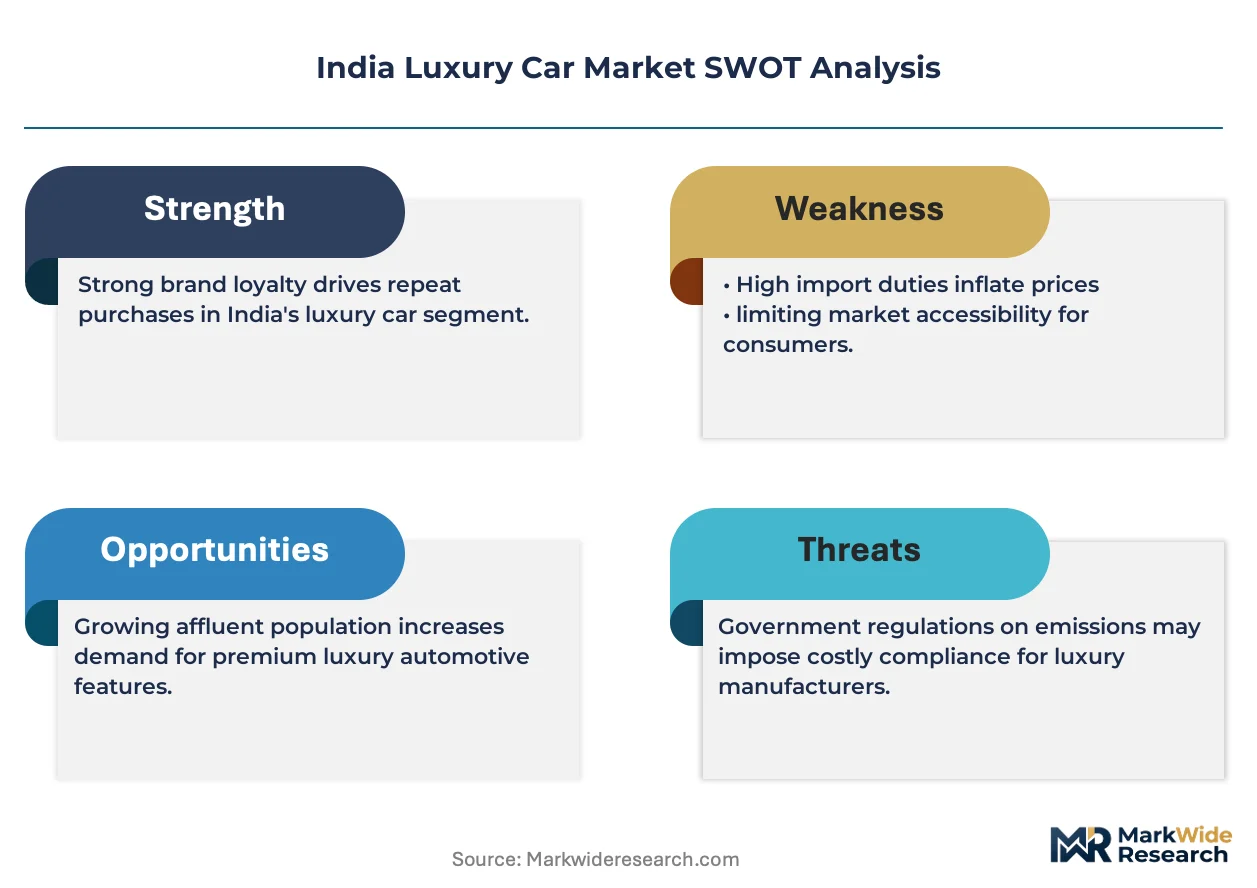
The gap between mass-market vehicles and luxury automobiles is repositioning around electrification architecture, cabin digitization, and brand heritage rather than engine displacement alone. Mercedes-Benz Group AG leverages its EQ portfolio to sustain technology leadership in battery-electric drivetrains. BMW AG anchors its position through localized production at Chennai and a dense service network across tier-one cities.
India luxury cars are passenger vehicles engineered with premium materials, advanced driver-assistance systems, and power outputs exceeding standard commuter specifications, primarily serving status-conscious consumers and corporate mobility programs. The SUV category dominates volume as ride height and road-condition adaptability match Indian infrastructure realities. Electric engine types are attracting the fastest investment despite current infrastructure constraints, while ultra-premium price tiers concentrate margin pools around bespoke customization and limited-edition releases.
BIS certification requirements, CDSCO-aligned safety mandates, and the automotive PLI scheme collectively shape product standards and import-substitution incentives for luxury manufacturers. State-level EV policies in Delhi and Maharashtra further influence where electrified luxury inventory deploys first. Stakeholders must track how subsidy phase-outs and charging network density evolve across India's metropolitan corridors.
Market Dynamics
Electrification mandates from BIS and state EV policies are compressing ICE development cycles while redirecting R&D budgets toward battery platforms and localized cell manufacturing partnerships.
Growth Catalysts
- BIS fuel efficiency norms:Stringent corporate average fuel economy standards are accelerating hybrid and battery-electric powertrain investments across luxury portfolios.
- Maharashtra EV policy:State-level purchase incentives and road tax waivers are concentrating initial electrified luxury inventory deployment in Mumbai-Pune corridor dealerships.
- Corporate fleet procurement:Multinational technology and financial services firms are expanding chauffeur-driven electric vehicle contracts for executive mobility programs.
Market Restraints
- Lithium-ion cell import dependence:Battery pack assembly remains constrained by concentrated East Asian cathode and cell supply, exposing landed cost volatility to currency fluctuation.
- Charging infrastructure density:Inter-city highway fast-charging networks remain sparse outside Delhi-Mumbai-Bangalore triangle, limiting long-distance electric luxury appeal.
- CDSCO safety certification timelines:Extended homologation procedures for advanced driver-assistance systems delay feature parity with European launches by 12-18 months.
Strategic Opportunities
- Tier-two city expansion:Surat, Ahmedabad, and Chandigarh exhibit rising HNI density without proportional luxury dealership presence, creating white-space for pre-owned certified programs.
- PLI scheme localization:Automotive manufacturing incentives are enabling domestic battery module and electric motor production, reducing import duty exposure on electrified variants.
- Subscription-to-ownership conversion:Flexible leasing platforms are cultivating younger demographic trial before traditional purchase, particularly in Bengaluru's technology workforce.
Industry Challenges
- EV technician training deficit:High-voltage system certification programs at manufacturer academies lag actual service bay demand, extending repair turnaround times.
- Legacy dealer margin compression:Direct-to-consumer digital reservation systems and agency sales models are forcing traditional franchise networks to renegotiate floorplan economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Luxury Car Market |
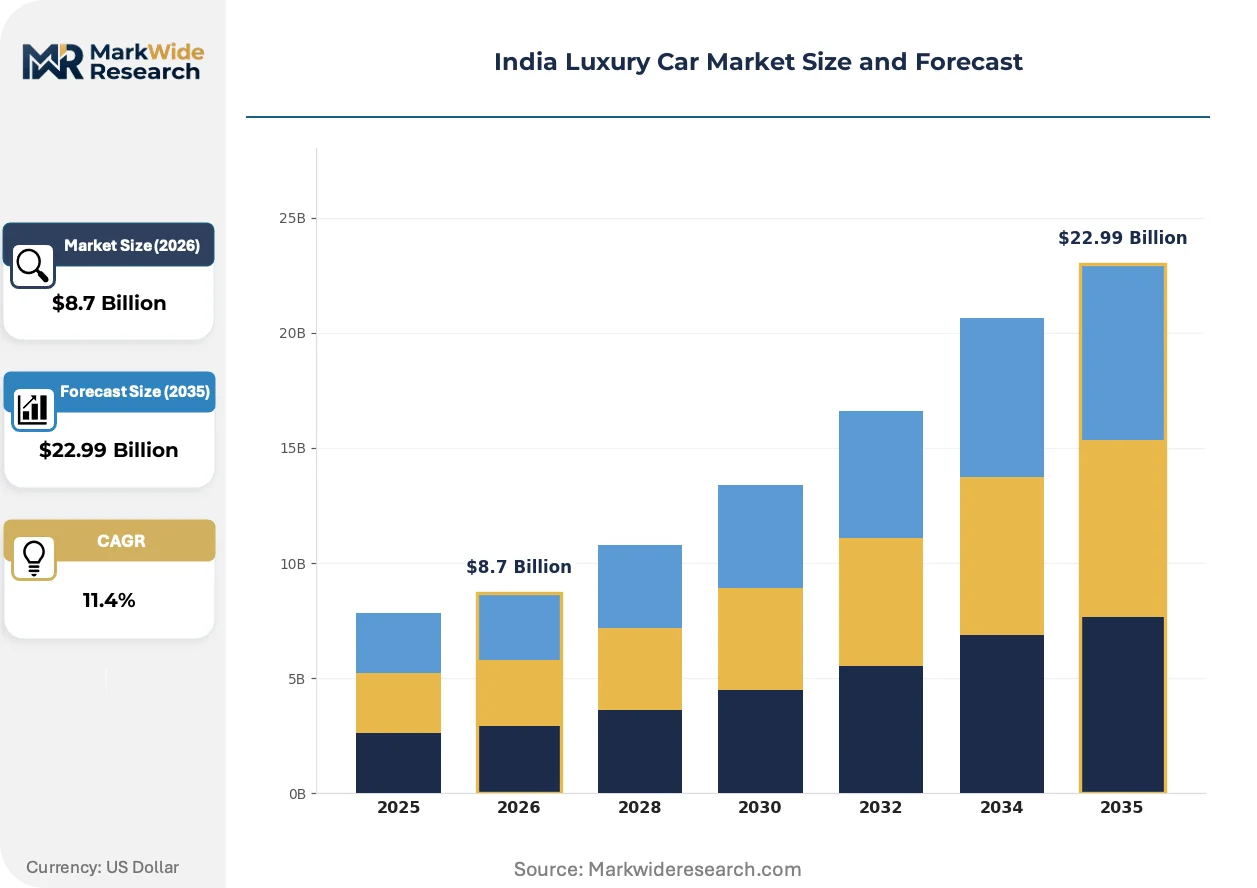
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SUV, Sedan, Coupe, Convertible Engine Type: Petrol, Diesel, Hybrid, Electric Customer Type: Individual Buyers, Corporates, Rental Services, Fleet Operators Price Tier: Entry-Level, Mid-Range, Premium, Ultra-Premium |
| Companies Covered | Mercedes-Benz Group AG, BMW AG, Audi AG, Jaguar Land Rover Automotive PLC, AB Volvo, Toyota Lexus, Volkswagen Group, Porsche, Land Rover, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Luxury Car Market Strategic Shifts
Software-defined vehicle architecture is decoupling hardware refresh cycles from feature updates, enabling revenue capture through over-the-air activation of dormant capabilities.
Battery-electric drivetrains with silicon carbide inverters and 800V architectures are overtaking twin-turbo V6 configurations as the default powertrain for flagship sedan launches. Affluent buyers in Delhi NCR and Bengaluru are specifying electric variants for 60% of new orders in the above-rupee-1-crore segment. This shift is compressing residual value premiums previously commanded by large-displacement ICE models.
BIS certification requirements for connected vehicle cybersecurity and over-the-air update protocols are mandating hardware-enabled encryption modules across all new luxury launches. Manufacturers must redesign gateway architectures to comply, adding engineering lead time but enabling subscription revenue streams. Maharashtra and Karnataka registered vehicles face the earliest compliance deadlines, accelerating local engineering center hiring.
Direct digital sales channels with fixed pricing are displacing traditional showroom negotiation rituals among first-time luxury buyers under age 40. Established dealers in Mumbai and Hyderabad are responding with experience center formats emphasizing test drives and delivery ceremonies over transaction closure. This behavioral pivot is most pronounced in technology sector clusters where price transparency expectations align with consumer electronics purchasing patterns.
India Luxury Car Market Segmentation
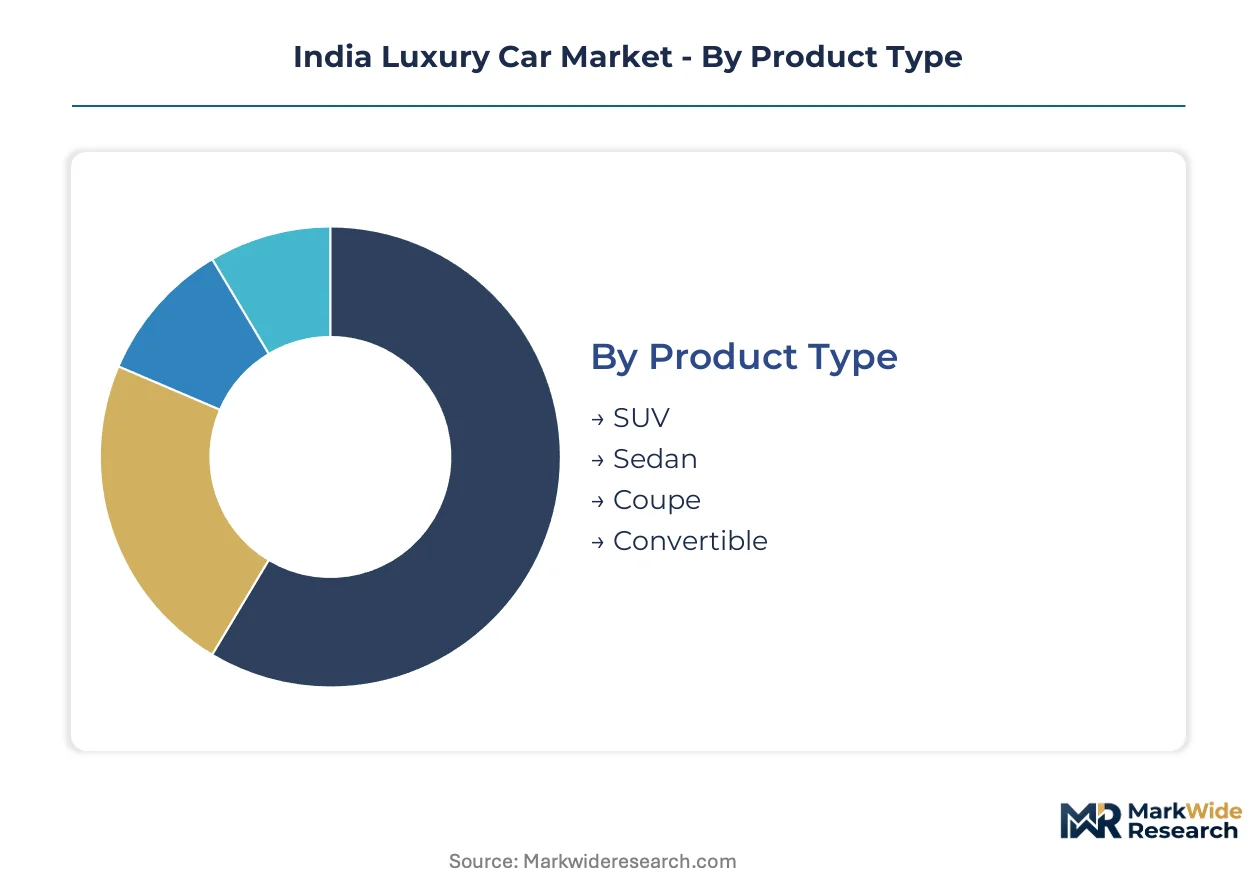
Luxury vehicle procurement in India fragments across powertrain preferences, ownership models, and price thresholds that reflect divergent infrastructure readiness and status-signaling priorities. Manufacturers must align portfolio allocation with these intersecting demands to capture margin pools concentrated in electrified SUVs and corporate fleet contracts.
Product Type:
Ground clearance requirements and road-condition adaptability separate buyer preferences across India's metropolitan and inter-city corridors.
- SUV:Commanding ride height and all-terrain capability address potholed urban infrastructure and highway variability. Maharashtra and Karnataka account for disproportionate order concentration as HNI density aligns with dealership presence and service network coverage.
- Sedan:Lower center of gravity and aerodynamic efficiency prioritize chauffeur-driven executive comfort over rough-road utility. Delhi NCR maintains traditional sedan loyalty among legacy corporate fleet operators despite SUV encroachment.
- Coupe:Sportback silhouettes with compromised rear seating attract younger individual buyers in Bengaluru's technology sector seeking differentiation from standard executive appointments.
- Convertible:Limited annual volume concentrates in coastal Maharashtra and Goa where climate and leisure infrastructure support open-top usability.
Volume sits with SUV; growth tilts toward electric sedan as charging infrastructure matures in Delhi-Mumbai corridors.
Engine Type:
Regulatory pressure from BIS corporate average fuel economy standards and state-level EV incentives are restructuring powertrain investment priorities across manufacturer portfolios.
- Petrol:Twin-scroll turbocharged configurations with particulate filters balance performance and compliance for ICE-dominant transition markets. Tier-two city buyers without charging access sustain residual demand in Surat and Ahmedabad.
- Diesel:Compression-ignition powertrains face accelerating phase-out as Delhi NCR and Maharashtra impose registration restrictions and resale penalties on oil-burning engines above two-liter displacement.
- Hybrid:Mild-hybrid and full-hybrid architectures bridge infrastructure gaps with self-charging convenience. Karnataka's technology workforce favors hybrid SUVs for inter-city travel where fast-charging remains sparse.
- Electric:Silicon carbide inverters and 800V architectures enable sub-30-minute charging cycles. Maharashtra EV policy subsidies and Mumbai-Pune expressway fast-charger deployment are concentrating initial luxury BEV adoption.
Hybrid systems anchor current volume; pure electric powertrains are climbing the fastest as cell localization under PLI scheme reduces landed cost volatility.
Customer Type:
Procurement decision-making authority separates individual status seekers from institutional buyers optimizing total cost of mobility.
- Individual Buyers:Personal wealth deployment favors customization options and limited-edition specifications. First-generation entrepreneurs in Chandigarh and Pune drive bespoke commissioning through direct digital channels.
- Corporates:Multinational technology and financial services firms standardize chauffeur-driven electric vehicle contracts for executive mobility programs. ESG reporting requirements accelerate fleet electrification timelines.
- Rental Services:Short-term luxury access platforms in Bengaluru and Hyderabad optimize asset utilization through subscription-to-ownership conversion pathways.
- Fleet Operators:Inter-city premium mobility providers concentrate sedan and SUV deployment on Delhi-Mumbai-Bangalore routes where airport transfer demand sustains utilization rates.
Individual transactions generate highest per-unit margin; corporate contracts are expanding most quickly as ESG mandates harden procurement criteria.
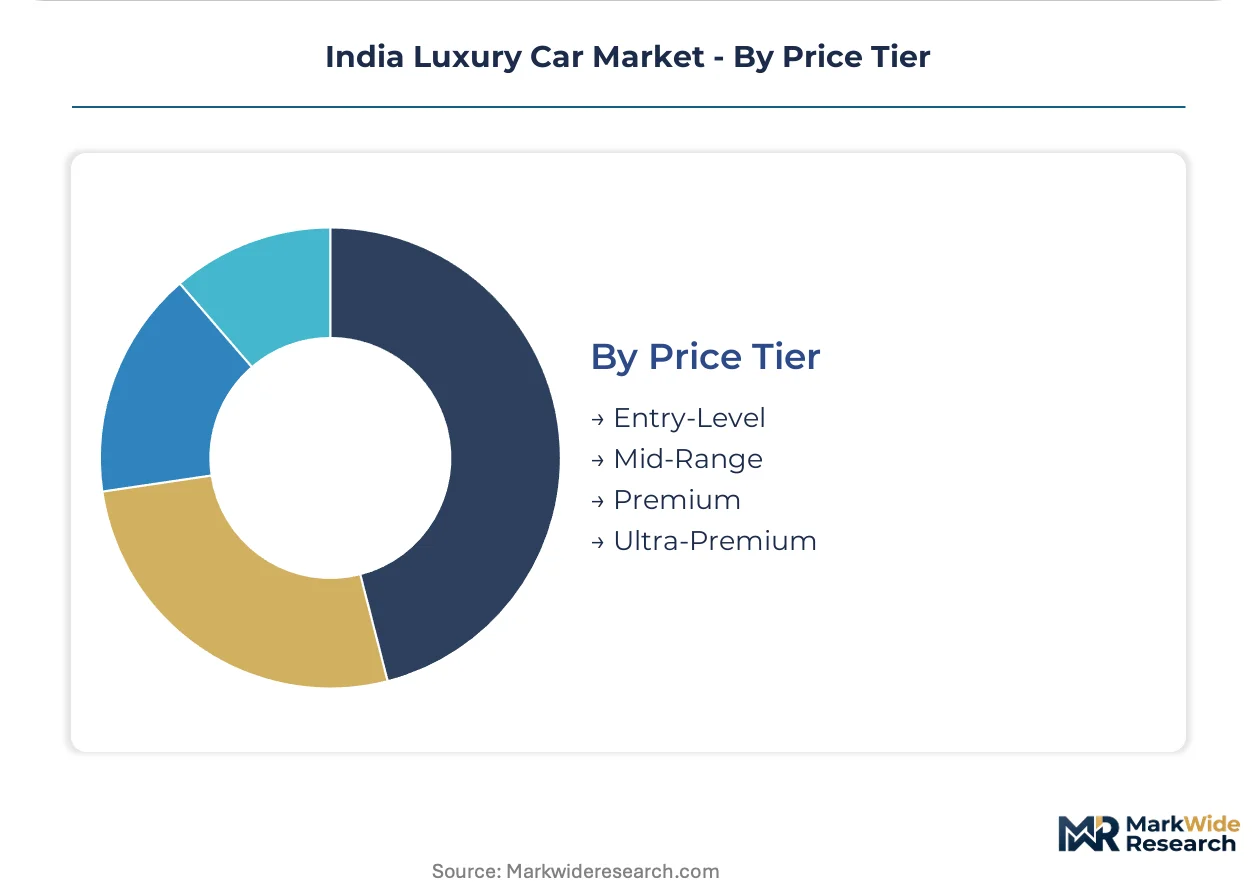
Price Tier:
Entry thresholds and specification depth stratify buyers across aspirational access and ultra-exclusive commissioning.
- Entry-Level:Compact luxury crossovers and sedans positioned below rupee-50-lakh threshold attract first-time premium buyers upgrading from mass-market brands. Young professionals in Hyderabad and Chennai dominate this cohort.
- Mid-Range:Full-size sedans and mid-size SUVs between rupee-50-lakh and rupee-1-crore anchor manufacturer volume targets. Maharashtra and Delhi NCR account for disproportionate share of this segment's transactions.
- Premium:Flagship SUVs and performance sedans with advanced driver-assistance systems and semi-autonomous capability concentrate in established HNI pockets of Mumbai and Bengaluru.
- Ultra-Premium:Bespoke commissioning, limited production runs, and concierge delivery services target UHNW individuals with multi-crore deployment capacity. Customization studios in Delhi and Mumbai handle specification finalization.
Mid-Range transactions sustain manufacturing scale; Ultra-Premium tier captures steepest margin expansion as bespoke services extend customer lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune corridor anchors luxury vehicle deployment as Maharashtra's EV policy concentrates initial electrified inventory in western India's wealthiest metropolitan cluster.
Maharashtra
Corporate fleet procurement and high-net-worth individual density drive disproportionate order concentration in Mumbai and Pune. The state EV policy's purchase incentives and road tax waivers accelerate battery-electric adoption. The Mumbai-Pune expressway corridor hosts the densest fast-charging infrastructure outside Delhi NCR, enabling inter-city electric luxury mobility.
Karnataka
Technology sector affluence in Bengaluru sustains demand for software-defined vehicle architectures and subscription ownership models. The state's EV policy complements BIS fuel efficiency norms in redirecting manufacturer investment toward localized battery assembly. Whitefield and Electronic City technology clusters generate 60% of electric variant orders in the above-rupee-1-crore segment.
Delhi NCR
Legacy corporate fleet operators maintain sedan loyalty despite SUV encroachment, though ESG reporting requirements accelerate electrification timelines. CDSCO-aligned safety mandates and extended homologation procedures delay advanced driver-assistance feature parity. Gurugram and Noida manufacturing corridors concentrate pre-owned certified program expansion targeting tier-two city buyers.
Gujarat
Surat and Ahmedabad exhibit rising high-net-worth individual density without proportional luxury dealership presence, creating white-space for pre-owned certified programs. The state's automotive manufacturing incentives under the PLI scheme attract battery module and electric motor production investments. GIFT City financial district generates chauffeur-driven electric vehicle contract demand from multinational services firms.
Telangana
Hyderabad's pharmaceutical and technology workforce drives entry-level luxury crossover demand among young professionals upgrading from mass-market brands. Flexible leasing platforms cultivate demographic trial before traditional purchase. HITEC City and Gachibowli technology corridors sustain subscription-to-ownership conversion pathways distinct from Mumbai's corporate fleet patterns.
India Luxury Car Market Competitive Environment
Capital-heavy producers with captive manufacturing compete with asset-light designers relying on contract assembly partnerships. The market structure concentrates around three strategic archetypes: integrated global manufacturers with localized Chennai production, import-dependent ultra-premium specialists, and emerging domestic assemblers leveraging PLI scheme incentives. Competitive moves center on agency sales model adoption and high-voltage technician training academy expansion.
Among integrated global manufacturers, Mercedes-Benz Group AG and BMW AG anchor the electrified portfolio tier through localized battery-electric drivetrain production. Audi AG occupies a position exemplifying the import-dependent specialist archetype navigating CDSCO certification timelines. These three entities represent distinct responses to BIS fuel efficiency norms: captive manufacturing scale, dense service network coverage, and digital direct-sales channel investment respectively.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| BMW AG |
| Audi AG |
| Jaguar Land Rover Automotive PLC |
| AB Volvo |
| Toyota Lexus |
| Volkswagen Group |
| Porsche |
| Land Rover |
| Others |
Value Chain & Pricing Dynamics
Corporate fleet procurement standardizing chauffeur-driven electric vehicle contracts for ESG reporting compliance is forcing manufacturers to absorb battery cost volatility while maintaining fixed-price contract structures for institutional buyers.
Pricing Analysis
Value-based pricing anchored to total cost of ownership outcomes dominates corporate fleet negotiations, with ESG compliance value commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by powertrain architecture and ADAS certification grade. Cost compression in entry-level tiers is intensifying because PLI scheme localization benefits have not yet filtered through to compact luxury crossovers. Corporate fleet buyers exhibit lowest price sensitivity due to ESG mandate rigidity, while young professionals in Hyderabad and Chennai upgrading from mass-market brands drive hardest bargain negotiations.
Supply Chain Analysis
PLI scheme domestic-content mandates reshaping sourcing are redirecting battery module and electric motor procurement toward Gujarat and Tamil Nadu manufacturing corridors. Lithium-ion cell supply draws from concentrated East Asian cathode production in China, South Korea, and Japan, exposing landed costs to rupee-dollar fluctuation. Single-source vulnerability around silicon carbide inverter chips sourced from Taiwan and Germany presents concentrated disruption risk. Distribution runs through manufacturer-controlled experience centers in Mumbai, Delhi NCR, and Bengaluru, bypassing traditional dealer floorplan economics for digital-first buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive battery cell manufacturing under PLI incentives determines margin sustainability against import-dependent competitors.
For Market Incumbents: Cement technology leadership through accelerated high-voltage technician academy expansion across tier-one cities, countering service bay bottlenecks that delay electric vehicle delivery timelines. Deepen backward integration into battery module production at Chennai and Gujarat facilities to reduce exposure to East Asian cell supply concentration and currency volatility.
For New Entrants and Emerging Players: Capture white-space in Surat, Ahmedabad, and Chandigarh through pre-owned certified program deployment where HNI density outruns established dealership presence. Prioritize subscription-to-ownership conversion platforms targeting Bengaluru's technology workforce, leveraging flexible leasing structures to bypass capital-intensive inventory holding requirements.
For Investors and Strategic Acquirers: The window for entry favors domestic assemblers with PLI scheme qualification and localized battery supply agreements over import-dependent ultra-premium specialists. Monitor charging infrastructure density along the Mumbai-Pune expressway corridor as inflection indicator for electric luxury vehicle demand acceleration beyond early adopter cohorts.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures localized cell sourcing under PLI scheme, reducing import duty exposure for electrified variants. |
| Software-Defined Vehicle Investment | Enables over-the-air revenue capture through dormant capability activation in Maharashtra and Karnataka. |
| Charging Infrastructure Partnership | Addresses inter-city highway fast-charging gaps outside Delhi-Mumbai-Bangalore triangle. |
| Geographic Manufacturing Footprint | Positions battery module production in Gujarat to serve western India HNI concentration. |
| Platform Standardization | Reduces engineering lead time for BIS cybersecurity compliance across Maharashtra and Karnataka. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, BIS certification records, and state EV policy filings, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations heads, and aftermarket service directors. Secondary validation drew from customs records, PLI scheme beneficiary disclosures, and CDSCO homologation timelines. Bottom-up segmentation modeling triangulated against top-down macroeconomic projections across the analysis window.
Cross-referencing historical registration patterns against expert panel input on electrification timelines shaped the analytical framework. Segmentation dimensions spanned vehicle class, propulsion architecture, OEM tier, and regional production cluster. CAGRs were derived from trend extrapolation moderated by infrastructure deployment assumptions and regulatory phase-in schedules. Forecast inputs incorporated charging network density projections and PLI scheme localization milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cell supply diversification and state EV policy continuity. Forecasts reflect documented assumptions about BIS fuel efficiency norm stringency and CDSCO certification timeline evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Train Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Europe Luxury Car Market