
 Sports Utility Vehicles (Suvs) Market | 2026-2036
Sports Utility Vehicles (Suvs) Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Utility Vehicles (Suvs) Market Outlook
The EU Green Deal is expanding compliance requirements for automotive CO2 reductions, pushing manufacturers to restructure SUV portfolios toward electrified architectures. Toyota Motor Corporation leverages its hybrid technology leadership to sustain competitive positioning in midsize and full-size segments. Ford Motor Company anchors North American production through integrated battery supply partnerships and dedicated EV platforms. BYD Company Ltd. dominates China's electrified SUV segment with in-house cell production and vertically integrated powertrain manufacturing.
Sports utility vehicles are passenger automobiles built on light-truck chassis or unibody platforms with elevated ground clearance, commanding seating position, and configurable cargo capacity typically exceeding 1,500 liters. These vehicles serve dual commercial and consumer purposes, combining family transportation utility with towing capability and all-weather traction for fleet, recreational, and suburban applications. Compact SUVs and electric fuel-type variants represent the fastest-expanding structural segments, driven by urban parking constraints and total cost of ownership advantages in regulated markets. Luxury SUVs command concentrated margin pools as BMW AG and Mercedes-Benz Group AG compete through advanced driver assistance systems and premium interior configurations.
The EPA enforces Corporate Average Fuel Economy standards that shape SUV powertrain mix and vehicle footprint calculations for US market access. EMA's evolving Euro 7 emission protocols will force European manufacturers to deploy hybrid or battery-electric architectures across compact and midsize SUV lineups. China's MIIT administers new energy vehicle credit mandates that direct domestic and joint-venture production quotas toward electrified SUVs. Stakeholders must monitor regulatory divergence between US, European, and Chinese compliance frameworks when allocating platform development resources and supplier contracts.
Market Dynamics
The Sports Utility Vehicles (Suvs) Market is being fundamentally restructured by regulatory mandates forcing powertrain electrification across major automotive markets, compelling manufacturers to reconfigure platform architectures and supplier relationships simultaneously.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These US regulations are tightening vehicle footprint calculations and pushing manufacturers toward hybrid and battery-electric SUV architectures to avoid penalties.
- Fleet electrification mandates:Corporate sustainability targets are accelerating procurement of electrified SUVs by logistics and rental operators seeking scope 3 emission reductions.
- China's MIIT new energy vehicle credit system:This production quota mechanism directs domestic and joint-venture manufacturing capacity toward plug-in hybrid and pure-electric SUV models.
Market Restraints
- Battery cell supply concentration:Cathode and cell production capacity clusters in China and South Korea create geographic vulnerability for Western SUV manufacturers.
- Raw material cost volatility:Lithium, nickel, and cobalt price swings directly compress margins on electrified SUV variants versus conventional powertrains.
- Euro 7 emission protocol complexity:EMA's evolving testing requirements for cold-start emissions and real-driving conditions extend development timelines and certification costs.
Strategic Opportunities
- Suburban charging infrastructure gaps:Second-tier Chinese cities and Indian metropolitan areas present white space for affordable compact electric SUVs with moderate range specifications.
- Vehicle-to-grid integration:Bidirectional charging capability in electric SUVs creates new revenue streams for owners and utility partnerships.
- US Inflation Reduction Act domestic content credits:Battery assembly and critical mineral sourcing incentives are reshaping North American supplier geography.
Industry Challenges
- Power electronics engineering scarcity:Shortages of inverter and motor control specialists delay electrified SUV program launches.
- Software-hardware integration complexity:Over-the-air update architectures and advanced driver assistance systems require new supplier coordination models.
- Homologation timeline compression:Parallel certification requirements across US EPA, EMA, and China MIIT protocols strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Utility Vehicles (Suvs) Market |
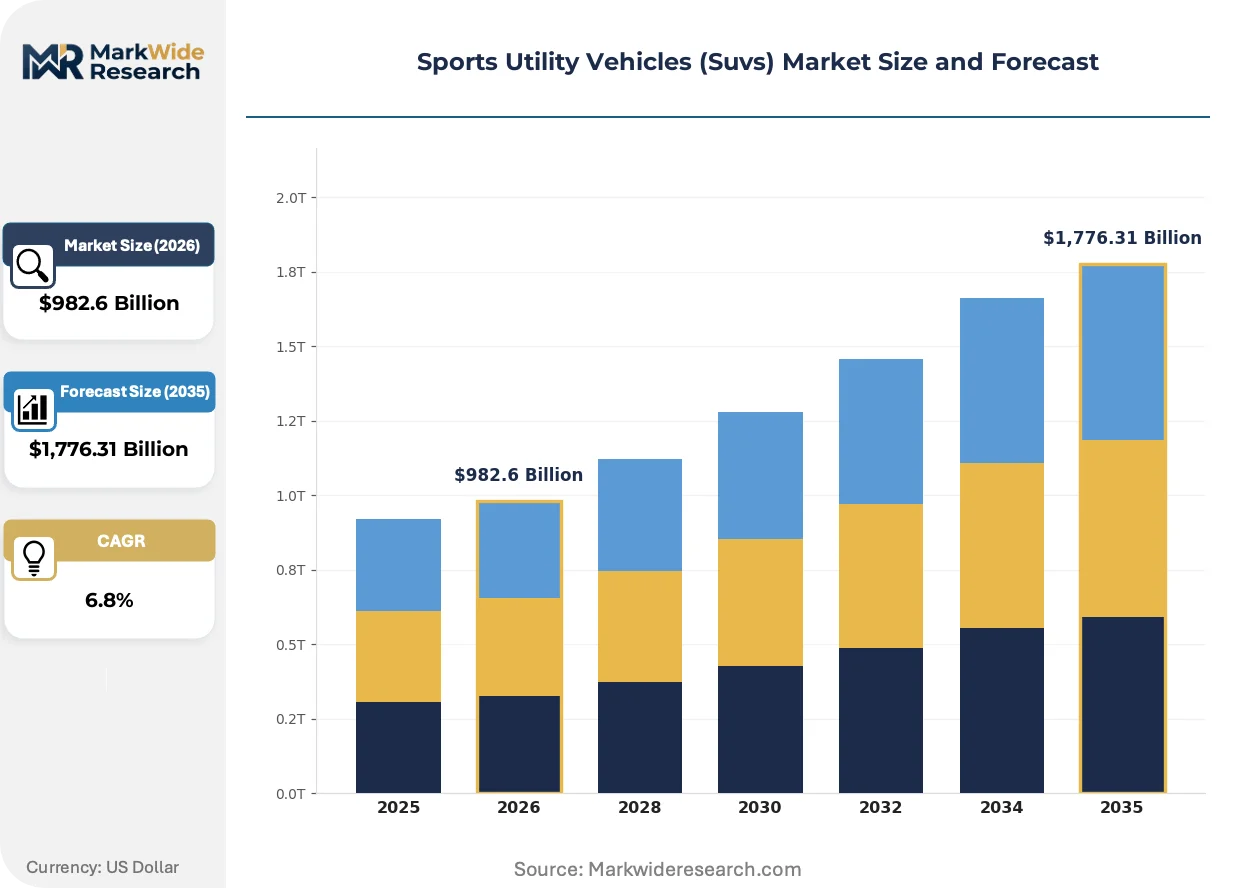
| Market Size in 2026 | $982.6 Billion |
| Market Size in 2035 | $1,776.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact SUVs, Midsize SUVs, Full-Size SUVs, Luxury SUVs Fuel Type: Gasoline, Diesel, Hybrid, Electric End User: Individual Consumers, Fleet Operators, Rental Agencies, Government Entities Feature: All-Wheel Drive, Towing Capacity, Infotainment System, Safety Features |
| Companies Covered | General Motors, Ford Motor Company, Toyota Motor Corporation, Volkswagen Group, BMW AG, Mercedes-Benz Group AG, Hyundai Motor Company, Honda Motor Co., Ltd., BYD Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Utility Vehicles (Suvs) Market Strategic Shifts
Electrification is collapsing the traditional powertrain hierarchy in SUVs, replacing engine displacement as the primary segmentation variable with battery capacity, charging speed, and software-defined feature sets.
800-volt electrical architectures are consolidating as the premium segment standard for electric SUVs, enabling 350kW fast-charging that reduces highway stop times to under twenty minutes. European and Chinese manufacturers are adopting these platforms fastest, with North American brands following to match competitive parity. This voltage transition is consolidating supplier tiers around specialized semiconductor and cable manufacturers capable of meeting thermal and insulation specifications.
The EU Green Deal's 2035 internal combustion engine phase-out is forcing European manufacturers to eliminate mild-hybrid bridging strategies and commit fully to battery-electric platforms. This regulatory deadline is compressing SUV development cycles and accelerating factory retooling investments. Midsize family SUVs face the steepest compliance cost escalation, driving consolidation toward scalable dedicated electric architectures.
Direct-to-consumer sales models are disrupting traditional dealer-dependent distribution for electric SUVs, with manufacturers establishing experience centers and online configuration tools. This channel shift is most advanced in China and select US states with franchise law exemptions. Urban buyers in these markets increasingly complete transactions without physical test drives, relying on subscription and return policies to reduce purchase risk.
Sports Utility Vehicles (Suvs) Market Segmentation
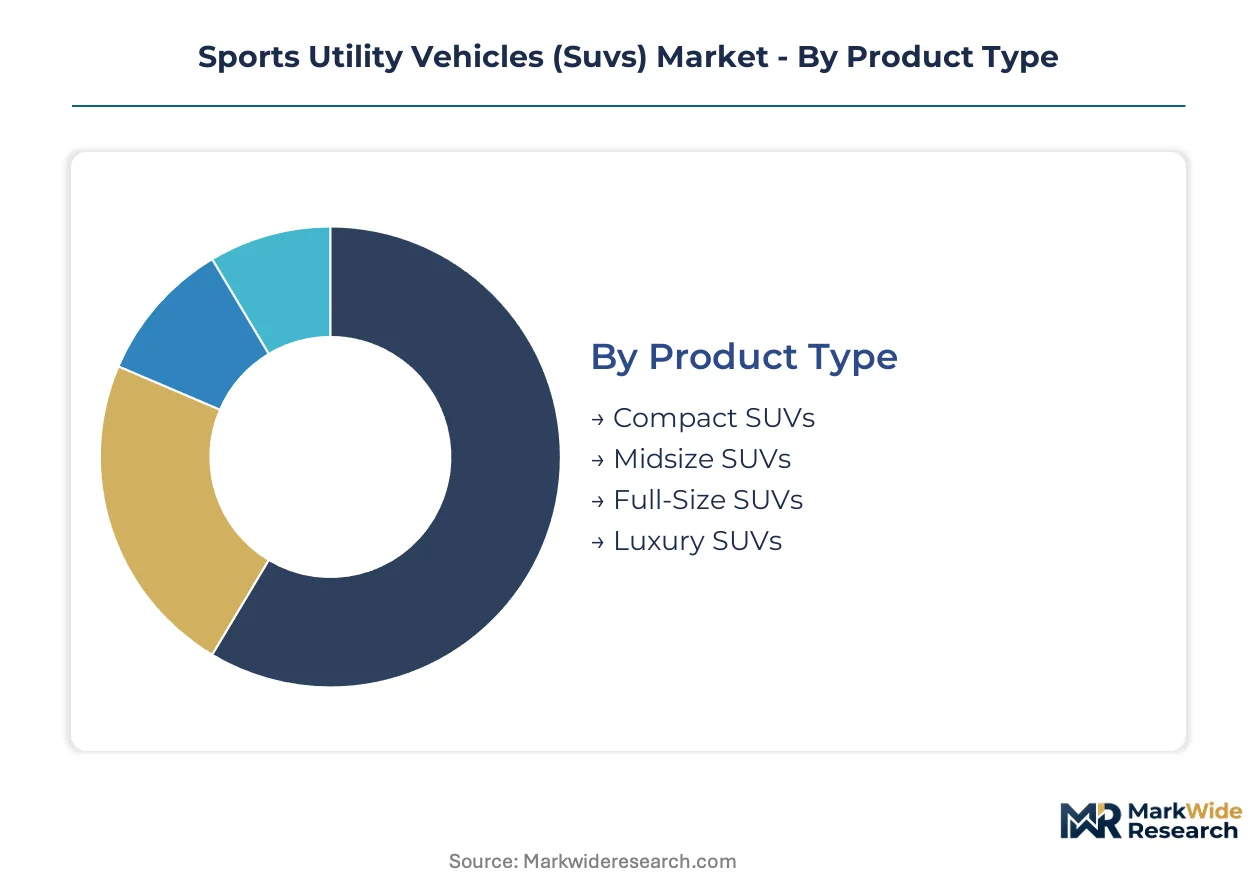
SUV segmentation reveals how manufacturers balance platform standardization against powertrain and feature customization to capture distinct buyer economics. Structural categories determine supplier contracts, factory allocation, and margin profiles across electrification transitions.
Product Type:
Customization intensity spans from mass-market unibody platforms to body-on-frame architectures serving divergent duty cycles and price elasticities.
- Compact SUVs:Built on shared passenger car platforms with 4.0-4.6 meter lengths and 1,500+ liter cargo volumes. Demand clusters in Chinese tier-2 cities and Indian metropolitan areas where parking constraints and congestion pricing favor smaller footprints.
- Midsize SUVs:Unibody construction dominates this volume anchor, offering three-row seating and 2,000 kg towing capacity. Fleet procurement from North American rental agencies and European corporate pools sustains production scale as consumer preference shifts toward electrified variants.
- Full-Size SUVs:Body-on-frame platforms with 3.5+ ton towing ratings serve commercial operators and recreational buyers in the US, Middle East, and Australia.
- Luxury SUVs:Premium materials, adaptive air suspension, and advanced driver assistance systems command price premiums through BMW, Mercedes-Benz, and Tesla configurations.
Leading the category by volume: Midsize SUVs. Expanding most quickly: Compact SUVs.
Fuel Type:
Cost tier stratification separates legacy internal combustion from electrified architectures requiring fundamentally different supply chains and manufacturing footprints.
- Gasoline:Port-injection and direct-injection engines remain dominant in price-sensitive markets and developing economies lacking charging infrastructure. EPA Corporate Average Fuel Economy standards and Euro 7 protocols are compressing gasoline SUV development budgets toward compliance rather than performance.
- Electric:Battery-electric architectures with 400-800V systems and 300-600 km ranges are capturing regulatory preference in China, Europe, and select US states. MIIT credit mandates and EU Green Deal deadlines are accelerating factory conversions to dedicated EV platforms.
- Diesel:Compression-ignition engines persist in European fleet applications and towing-intensive markets despite urban access restrictions.
- Hybrid:Toyota's power-split and European P2 architectures bridge emission compliance and range anxiety in markets with uneven charging coverage.
Highest volume concentration: Gasoline. Steepest expansion trajectory: Electric.
End User:
Customer type determines fleet sizing, financing structures, and feature prioritization across private ownership versus commercial utilization models.
- Individual Consumers:Private buyers prioritize seating configuration, infotainment integration, and total cost of ownership calculations including fuel and maintenance. Chinese and US suburban households drive demand for three-row and electrified variants with home charging compatibility.
- Fleet Operators:Logistics and delivery companies specify durability ratings, telematics integration, and service interval optimization. Scope 3 emission reduction targets are redirecting procurement toward hybrid and electric SUVs with predictable total cost of ownership.
- Rental Agencies:Turn frequency and residual value sensitivity shape acquisition toward mainstream segments with broad appeal and standardized maintenance.
- Government Entities:Public procurement mandates for domestic content and alternative fuel compatibility influence fleet composition in China, the US, and EU member states.
Dominant volume share: Individual Consumers. Gaining share fastest: Fleet Operators.
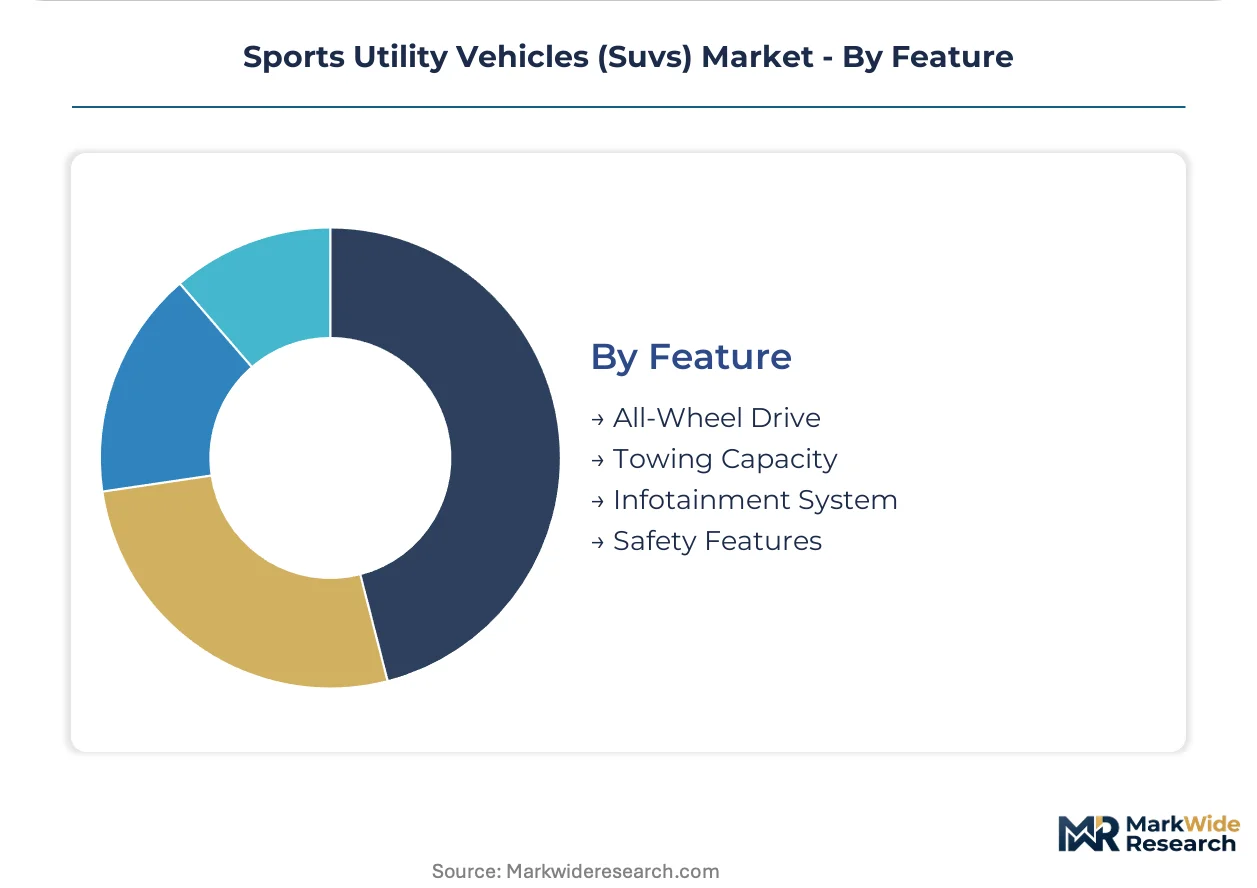
Feature:
Margin concentration tracks capability differentiation versus commodity availability across drivetrain, utility, and digital experience dimensions.
- All-Wheel Drive:Multi-plate clutch and torque-vectoring systems command premiums in snow-belt US states, Nordic countries, and mountainous terrain. Electrified AWD using dual-motor layouts is displacing mechanical differentials in premium electric SUVs.
- Safety Features:Automatic emergency braking, lane-keeping assistance, and adaptive cruise control are becoming regulatory baseline requirements rather than differentiators. Euro NCAP and IIHS testing protocols are accelerating sensor and software integration across price tiers.
- Towing Capacity:Hitch integration and cooling package specifications segment buyers by recreational and commercial utility requirements.
- Infotainment System:Large-format touchscreens, over-the-air update capability, and smartphone integration are standardizing rapidly as competitive parity points.
Widest penetration: Safety Features. Climbing the fastest: All-Wheel Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors electrified SUV manufacturing through Tesla's Gigafactory and SAIC-GM-Wuling joint ventures, while Detroit sustains full-size body-on-frame production for North American commercial and recreational buyers.
United States
Fleet operators in Texas and Florida are electrifying suburban delivery routes through bulk procurement of compact electric SUVs. The EPA's Corporate Average Fuel Economy standards tighten footprint-based calculations, pressuring manufacturers toward hybrid architectures. Michigan's Detroit-Hamtramck corridor hosts retooling investments for dedicated EV platforms serving North American markets.
China
Urban households in Chengdu and Hangzhou favor compact electric SUVs with 400-kilometer ranges for intercity commuting. MIIT's new energy vehicle credit mandates direct joint-venture production quotas toward plug-in hybrid and battery-electric models. BYD anchors production in Shenzhen with vertically integrated cell manufacturing and dedicated EV platforms for domestic and export markets.
Germany
Corporate fleet pools in Bavaria and Baden-Württemberg specify plug-in hybrid SUVs to meet scope 3 emission reduction targets. The EU Green Deal's 2035 internal combustion phase-out accelerates factory conversions in Stuttgart and Munich toward dedicated battery-electric architectures. KBA certification timelines compress as Euro 7 protocols extend testing requirements for cold-start emissions.
Japan
Suburban families in Osaka and Nagoya prioritize hybrid SUVs for uneven charging infrastructure coverage. METI's green growth strategy channels investment toward solid-state battery development for next-generation electric platforms. Toyota anchors production in Toyota City with power-split hybrid systems serving domestic and export demand.
South Korea
Technology-focused buyers in Seoul and Busan demand 800-volt architectures with sub-20-minute fast charging. MFDS automotive safety standards accelerate advanced driver assistance system integration across domestic lineups. Hyundai Motor Group's Ulsan complex hosts dedicated EV platform production for global export markets.
Sports Utility Vehicles (Suvs) Market Competitive Environment
The competitive structure tilts toward diversified automotive conglomerates with multi-brand portfolios spanning mass-market and premium segments. Scale advantages concentrate with manufacturers controlling battery supply partnerships and dedicated EV platform architectures. Two strategic archetypes dominate: legacy automakers retooling combustion-era factories, and battery-native entrants with vertically integrated cell production. Competitive moves center on strategic partnerships for cathode supply security and geographic expansion through joint-venture manufacturing in regulated markets.
Among diversified automotive conglomerates, Toyota Motor Corporation, Ford Motor Company, and BYD Company Ltd. occupy distinct competitive positions. Toyota exemplifies hybrid technology leadership through power-split architectures bridging emission compliance and range anxiety. Ford anchors North American production through integrated battery supply partnerships and dedicated EV platforms for fleet and consumer segments. BYD represents battery-native vertical integration with in-house cell production and captive powertrain manufacturing serving domestic and export electrified SUV demand.
| Leading Market Players |
|---|
| General Motors |
| Ford Motor Company |
| Toyota Motor Corporation |
| Volkswagen Group |
| BMW AG |
| Mercedes-Benz Group AG |
| Hyundai Motor Company |
| Honda Motor Co., Ltd. |
| BYD Company Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate and nickel sulfate contract volatility cascades through battery pack costs into three-tier pricing structure across premium, standard, and economy levels for electrified SUVs. Manufacturers with in-house cathode production in China and South Korea buffer margin compression better than Western brands dependent on spot market sourcing.
Pricing Analysis
Range-per-dollar serves as the dominant value-based pricing anchor for electric SUV buyers comparing total cost of ownership against gasoline alternatives. Pricing stratifies across premium, standard, and economy tiers based on battery capacity certification and charging speed specifications. Cost compression in the standard tier is intensifying because BYD and SAIC-GM-Wuling are scaling 400-kilometer compact electric SUVs below legacy OEM cost structures. Fleet operators exhibit the highest price sensitivity due to residual value risk and charging infrastructure capital requirements, while luxury individual buyers show the least sensitivity to upfront premiums for 800-volt architectures and sub-20-minute fast charging.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode precursor and separator membrane suppliers that feed cell manufacturing in South Korea and Japan. Battery cell production draws from lithium brine extraction in Chile and Argentina, nickel laterite in Indonesia, and cobalt hydroxide in the Democratic Republic of Congo. Tariff exposure on Chinese battery components entering the US and EU strains Western manufacturers pursuing IRA and Green Deal compliance. Distribution runs through OEM captive assembly plants and joint-venture manufacturing clusters rather than independent tiered supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sports Utility Vehicles (Suvs) Market is a vertical-integration race where battery cell manufacturing and cathode precursor refining determine cost parity and regulatory credit generation. Players securing upstream mineral offtake and midstream cell capacity gain pricing power against assembly-only competitors.
For Market Incumbents: To counter BYD's vertically integrated cost advantage in compact electric SUVs, legacy OEMs must secure long-term cathode supply agreements with Indonesian nickel and Chilean lithium producers while retooling European and North American plants for dedicated EV platforms. Platform standardization across midsize and compact segments reduces engineering overhead and supplier qualification costs. For New Entrants and Emerging Players: Enter via second-tier Chinese cities and Indian metropolitan areas where charging infrastructure gaps favor affordable compact electric SUVs with 300-400 kilometer ranges and moderate fast-charging specifications. Partner with local fleet operators for telematics-integrated procurement contracts that guarantee production volume and service network density. For Investors and Strategic Acquirers: MIIT credit mandate enforcement tightening is the leading indicator that domestic Chinese brands will consolidate joint-venture market share faster than projected. Target acquisition candidates with solid-state battery development pipelines and existing OEM supply relationships rather than pure assembly operations. Watch for cathode precursor plant commissioning announcements in non-Chinese geographies as the signal for supply chain diversification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in cathode and cell capacity from Chinese or South Korean producers for EPA compliance. |
| Platform Standardization | Reduces engineering costs across compact and midsize SUVs for MIIT credit optimization. |
| Charging Infrastructure Partnership | Secures 800-volt fast-charging network access for premium electric SUV buyers in urban clusters. |
| Geographic Manufacturing Footprint | Positions IRA-compliant assembly in Michigan or Tennessee for domestic content tax credits. |
| Software-Defined Vehicle Investment | Enables over-the-air feature monetization and subscription revenue beyond hardware margins. |
Study Parameters
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, battery cell manufacturing executives, and fleet operator sustainability officers underwrites the qualitative findings. Secondary validation draws from EPA certification filings, MIIT new energy vehicle production databases, EU Green Deal implementation trackers, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulates against top-down macroeconomic demand modeling for the automotive sector.
Comparable historical production and registration patterns anchor the projection framework across the analysis window. The forecast models vehicle class, propulsion architecture, and regional production cluster dimensions with OEM tier stratification. CAGRs derive from segment-level demand elasticity and regulatory compliance cost trajectories. Battery cost curve assumptions and charging infrastructure deployment schedules feed directly into electrified SUV adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Euro 7 protocol acceleration or Chinese export restriction scenarios. Forecasts reflect documented assumptions about mineral supply expansion and cathode chemistry transitions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
North American Lightweight Car Market