
 Stolen Vehicle Recovery Market | 2026-2036
Stolen Vehicle Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Stolen Vehicle Recovery Market Analysis
The gap between premium integrated platforms and standalone recovery hardware is hardening in the stolen vehicle recovery landscape. CalAmp leverages its telematics heritage to anchor cloud-native recovery architectures for commercial fleets. Ituran Global sustains dominant channel control through direct insurance partnerships in Latin America and Southern Europe. Robert Bosch competes on manufacturing scale, embedding forensic-grade tracking modules into OEM production lines across multiple vehicle classes.
Stolen vehicle recovery encompasses technologies and services designed to locate, immobilize, and return stolen automobiles to rightful owners, typically employing GPS satellite triangulation, cellular data transmission, and RF beaconing with location accuracy thresholds under ten meters. GPS Tracking leads the technology dimension by revenue scale, while Mobile Apps represent the fastest-expanding interface layer as smartphone-native recovery workflows displace dedicated hardware consoles. Fleet Operators anchor the end-user segment by contract value, yet Government Agencies command disproportionate margin pools through mandated public-safety procurement frameworks.
The United States NHTSA and the European Union's Vehicle Security Regulation shape product standards by mandating factory-fitted tracking capability in new passenger vehicles, while ISO 9001 and IEC 60730 certifications govern supplier qualification for OEM integration. The EU AI Act introduces emerging compliance burdens for automated recovery decision systems that initiate immobilization without human intervention. Stakeholders must monitor regulatory divergence between privacy-protective jurisdictions and security-first regimes to anticipate which recovery architectures will retain market access.
Market Dynamics
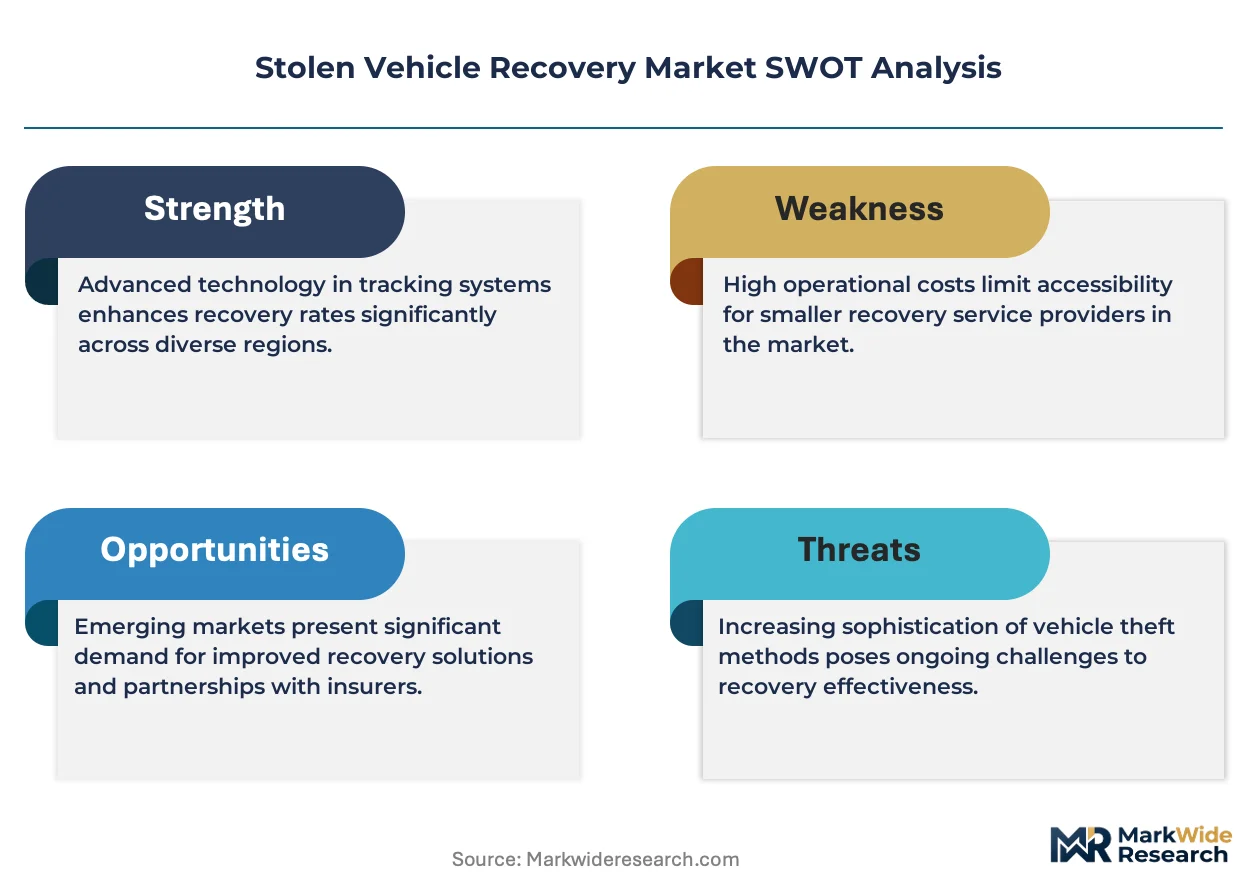
Factory-installed tracking mandates from the United States NHTSA and the European Union's Vehicle Security Regulation are compressing the aftermarket installation window, forcing recovery providers to embed deeper into OEM supply chains or pivot toward fleet retrofit services.
Growth Catalysts
- EU Vehicle Security Regulation:Mandates factory-fitted tracking capability in new passenger vehicles, eliminating dealer-installed aftermarket competition and locking in multi-year service contracts.
- Telematics platform consolidation:Fleet operators demand unified recovery, routing, and driver behavior analytics, expanding contract values for integrated platform providers.
- Insurance-linked recovery services:Premium discounts tied to active tracking in Germany, the United Kingdom, and the United States accelerate consumer adoption at point of vehicle financing.
Market Restraints
- Semiconductor supply concentration:GPS and cellular module production clusters in East Asian foundries expose recovery hardware manufacturers to input volatility and allocation rationing.
- RF spectrum licensing friction:Dedicated short-range communications bands for immobilization signals face contested allocation in multiple jurisdictions, delaying product certification.
- Privacy-protective jurisdictions:GDPR-derived location data restrictions in Germany and France limit automated recovery decision systems and require human-in-the-loop protocols that slow response times.
Strategic Opportunities
- Electric vehicle native architecture:Battery management system integration enables power-cut immobilization without standalone hardware, opening design-win positions for recovery technology suppliers.
- Latin America insurance channel:Underpenetrated markets in Brazil and Mexico present first-mover advantage for direct carrier partnership models proven in Southern Europe.
- EU AI Act automated response frameworks:Compliance-grade decision systems for immobilization without human intervention will command premium positioning as regulatory clarity emerges.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 and ISO/SAE 21434 compliance for connected recovery systems extends product development cycles by 12-18 months.
- Legacy fleet integration complexity:Retrofit installations in vehicles predating CAN bus standardization require custom wiring harnesses that erode technician productivity and margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stolen Vehicle Recovery Market |
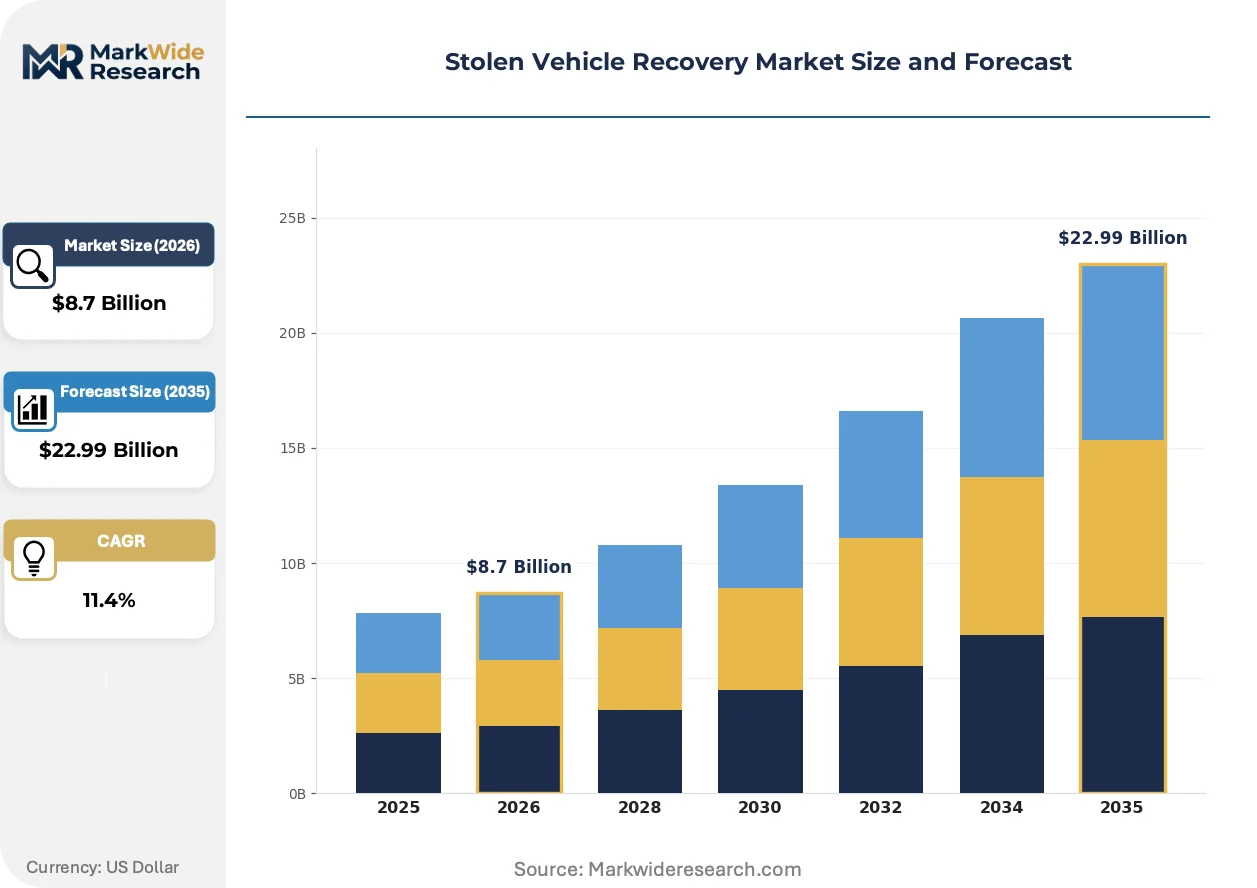
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, RFID Systems, Mobile Apps, Forensic Recovery End User: Insurance Companies, Fleet Operators, Government Agencies, Individual Vehicle Owners Service Type: Recovery Services, Monitoring Services, Consulting Services, Incident Reporting Integration Level: Standalone Solutions, Integrated Platforms, Cloud-Based Systems, Mobile Integrations |
| Companies Covered | CalAmp, Ituran Global, Verizon Connect, Geotab, Teletrac Navman, Spireon, Netstar, Vodafone Automotive, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stolen Vehicle Recovery Market Emerging Trajectories
Recovery workflows are migrating from dedicated hardware consoles toward smartphone-native interfaces, compressing equipment costs while expanding real-time owner engagement during theft events.
RF beaconing is converging with GPS cellular triangulation in hybrid tracking architectures that maintain location capability in underground parking structures and dense urban canyons where satellite signals degrade. Tier-1 automotive suppliers are adopting these dual-mode modules for factory installation across mid-range and premium vehicle lines. The convergence is compressing standalone GPS hardware margins while elevating firmware and cloud-platform differentiation.
The EU AI Act introduces emerging compliance burdens for automated recovery decision systems that initiate immobilization without human intervention. Suppliers must demonstrate algorithmic transparency and bias mitigation to retain market access in privacy-protective jurisdictions. Germany and France are responding with national implementation guidelines that exceed baseline EU requirements, fragmenting product certification pathways.
Fleet procurement teams are unbundling recovery services from bundled telematics contracts, negotiating direct relationships with specialized recovery platform providers. This disintermediation of fleet management company intermediaries is visible most acutely in North American commercial vehicle operations where contract values exceed consumer thresholds. Specialized recovery providers are capturing margin previously allocated to generalist telematics vendors.
Stolen Vehicle Recovery Market Segmentation
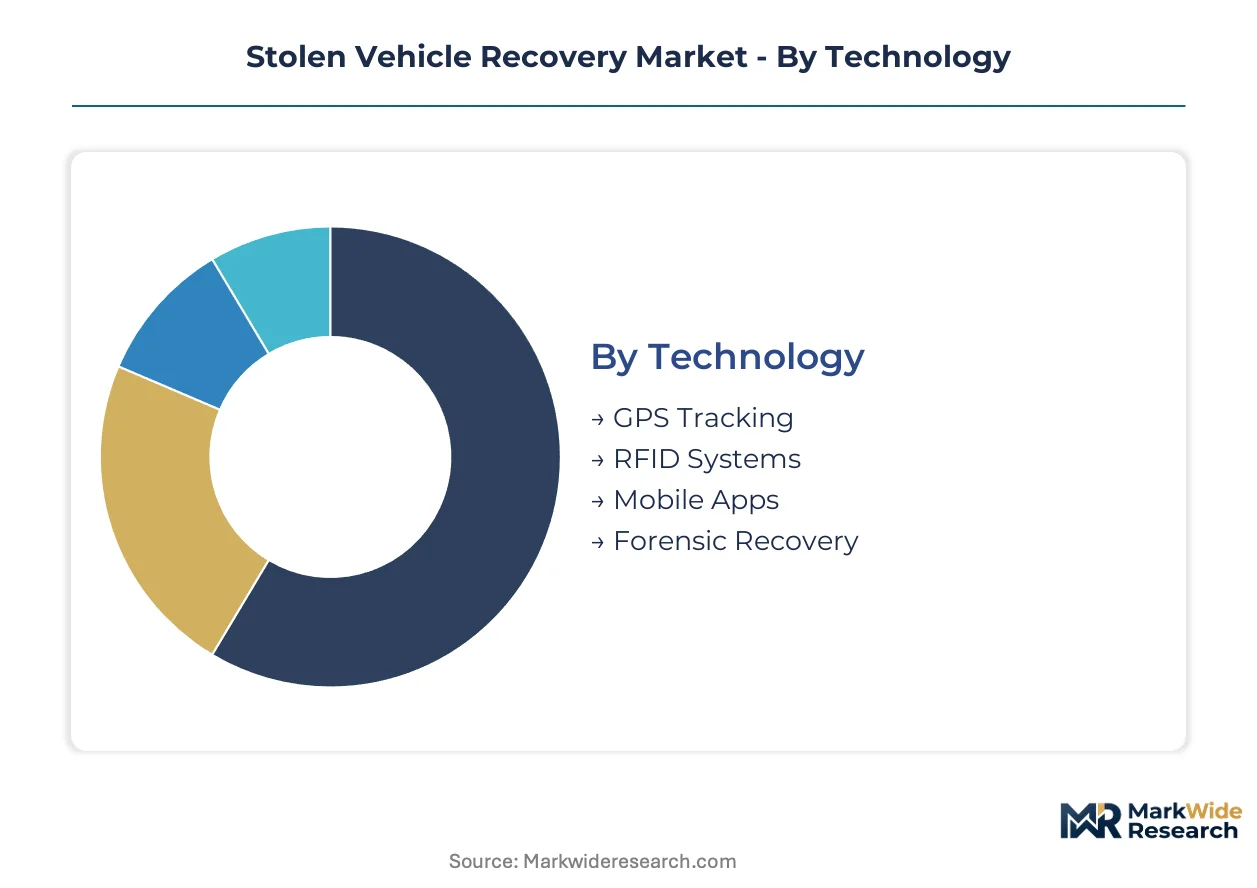
Segmentation in the stolen vehicle recovery market reveals divergent value capture between standardized hardware components and customized service architectures. Fleet procurement teams and insurance underwriters prioritize different performance attributes, fragmenting vendor go-to-market strategies across technology, service, and integration dimensions.
Technology:
Customization intensity varies sharply across this category, with forensic-grade modules demanding bespoke calibration while consumer-facing interfaces standardize rapidly.
- GPS Tracking:Satellite triangulation systems achieve location accuracy thresholds under ten meters through multi-constellation reception. Demand concentrates among fleet operators in the United States and Germany where insurance-linked recovery services mandate continuous position reporting.
- Mobile Apps:Smartphone-native recovery workflows displace dedicated hardware consoles through real-time owner engagement during theft events. Individual vehicle owners in the United Kingdom and United States drive adoption fastest as premium discounts tie directly to active smartphone verification.
- RFID Systems:Short-range radio frequency tags enable rapid vehicle identification in controlled environments like port facilities and impound lots.
- Forensic Recovery:Law enforcement-grade tracking modules embed covert installation protocols and tamper-evident sealing for evidence chain integrity.
Leading the category by volume: GPS Tracking. Growing fastest: Mobile Apps.
End User:
Contract value scales inversely with decision velocity across this category, with government procurement cycles extending 18-24 months while individual purchases complete in days.
- Fleet Operators:Commercial vehicle operators anchor segment revenue through multi-year service contracts spanning recovery, routing, and driver behavior analytics. United States-based logistics companies and German freight carriers dominate contract values as unified telematics platforms consolidate vendor relationships.
- Government Agencies:Public-safety procurement frameworks command disproportionate margin pools through mandated specifications and sole-source justifications. Police departments and transportation authorities in the United States and United Kingdom drive specialized requirements for covert installation and chain-of-custody documentation.
- Insurance Companies:Direct carrier partnerships in Brazil and Mexico present first-mover expansion opportunities following proven Southern Europe models.
- Individual Vehicle Owners:Retail demand concentrates in premium vehicle segments where factory-installed tracking satisfies financing institution requirements.
Highest contract values: Fleet Operators. Steepest expansion trajectory: Government Agencies.
Service Type:
Margin architecture separates real-time response capabilities from retrospective documentation functions across this category.
- Recovery Services:Physical vehicle retrieval operations coordinate law enforcement liaison, secure transport, and owner handoff protocols. Demand clusters in urban corridors with established theft-to-export pipelines, particularly container ports in California and Florida.
- Monitoring Services:Continuous surveillance subscriptions generate recurring revenue through geofence alerts and unauthorized movement detection. Fleet operators in Texas and Illinois prioritize these services for high-value cargo protection.
- Consulting Services:Risk assessment and security architecture advisory supports enterprise fleet security program design.
- Incident Reporting:Automated documentation workflows streamline insurance claim filing and law enforcement notification.
Dominant revenue source: Recovery Services. Climbing the fastest: Monitoring Services.
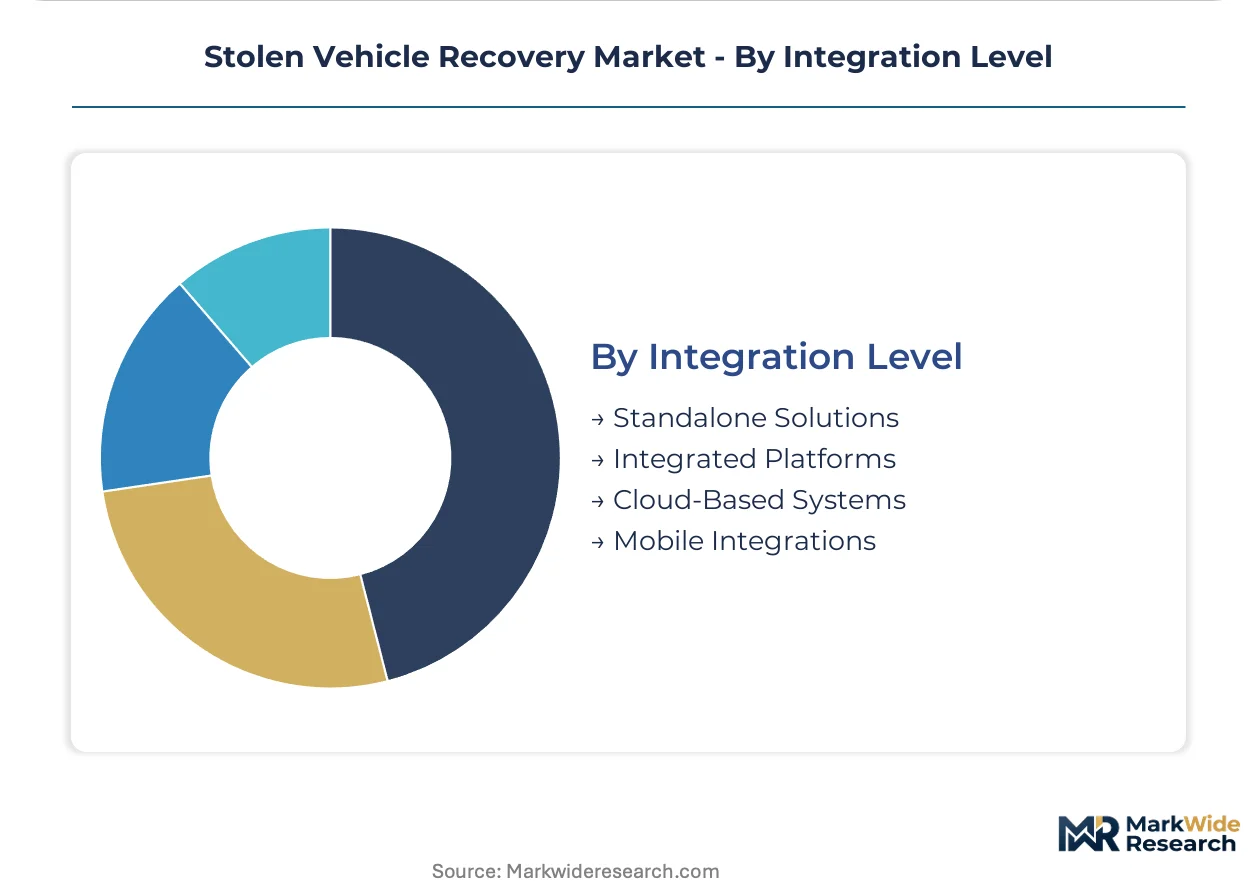
Integration Level:
Supply chain positioning determines whether vendors capture value at the module, platform, or ecosystem layer across this category.
- Integrated Platforms:Unified recovery, routing, and analytics architectures command premium positioning through single-vendor accountability. OEM production lines across Germany and the United States embed these systems during vehicle assembly under NHTSA and EU Vehicle Security Regulation mandates.
- Cloud-Based Systems:Remote software update capability and elastic compute scaling reduce hardware refresh cycles. Fleet management companies in the United Kingdom and Netherlands migrate fastest to eliminate on-premise infrastructure maintenance.
- Standalone Solutions:Aftermarket hardware installations face compressing demand windows as factory-fit mandates expand.
- Mobile Integrations:Smartphone-tethered recovery workflows leverage existing device penetration without dedicated console investment.
Widest deployment: Integrated Platforms. Gaining share fastest: Cloud-Based Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors North American stolen vehicle recovery deployment, with factory-installed tracking mandates from the United States NHTSA compressing aftermarket windows across major production hubs worldwide.
United States
Insurance-linked recovery services in Texas and California drive consumer adoption through premium discounts tied to active tracking verification. The United States NHTSA mandates factory-fitted capability in new passenger vehicles, eliminating dealer-installed competition. Fleet operators in the Chicago-Detroit corridor negotiate direct contracts with specialized recovery platform providers, disintermediating legacy telematics vendors.
Germany
German freight carriers and logistics companies anchor European contract values through unified telematics platforms consolidating recovery, routing, and driver analytics. GDPR-derived location data restrictions from the KBA and CNIL-derived implementations limit automated immobilization systems. Stuttgart and Munich host OEM production lines embedding forensic-grade tracking modules under EU Vehicle Security Regulation mandates.
United Kingdom
Individual vehicle owners in Greater London and the Southeast drive fastest adoption of smartphone-native recovery workflows as premium discounts tie to active mobile verification. The UK Driver and Vehicle Licensing Agency coordinates with insurance underwriters on tracking compliance frameworks. Container ports in Felixstowe and Southampton cluster demand for physical recovery operations targeting theft-to-export pipelines.
Brazil
Direct carrier partnerships in São Paulo and Rio de Janeiro present first-mover expansion opportunities following proven Southern European insurance channel models. ANVISA oversight intersects with automotive security regulations as factory-fit mandates expand. Underpenetrated markets in Minas Gerais and Paraná attract specialized recovery providers seeking margin outside saturated North American and European corridors.
Japan
Tokyo-based fleet operators demand integrated recovery architectures with battery management system compatibility for electric vehicle native immobilization. METI guidelines shape domestic certification requirements for connected recovery systems. Automotive suppliers in the Nagoya corridor embed cloud-native tracking modules into OEM production lines for export markets.
Stolen Vehicle Recovery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the stolen vehicle recovery landscape, with module manufacturers facing margin compression as firmware and cloud-platform differentiation escalates. The vendor base stratifies between OEM-integrated Tier-1 suppliers, insurance-channel specialists, and fleet-focused platform consolidators. Two strategic archetypes dominate: telematics heritage players leveraging cloud-native architectures, and manufacturing-scale specialists embedding forensic-grade modules into production lines. Competitive moves concentrate on strategic partnerships with automotive OEMs and geographic expansion through direct insurance carrier relationships.
Within the telematics-platform tier, CalAmp and Geotab occupy positions representing cloud-native recovery architecture specialization for commercial fleet operators. Robert Bosch exemplifies the manufacturing-scale archetype through OEM production line integration across multiple vehicle classes. Ituran Global anchors the insurance-channel specialist position, with its corporate structure reflecting direct carrier partnership models proven in underpenetrated markets.
| Leading Market Players |
|---|
| CalAmp |
| Ituran Global |
| Verizon Connect |
| Geotab |
| Teletrac Navman |
| Spireon |
| Netstar |
| Vodafone Automotive |
| Robert Bosch |
| Others |
Supply Flow & Price Mechanics
Factory-embedded versus aftermarket installation bifurcation creates divergent margin architectures across the stolen vehicle recovery landscape. OEM-integrated modules command premium positioning through multi-year service lock-ins mandated by NHTSA and EU Vehicle Security Regulation, while standalone hardware faces compressing demand windows and price erosion in dealer channels.
Pricing Analysis
Outcome-based pricing tied to successful vehicle recovery anchors premium tiers in insurance-linked contracts, particularly in Germany and the United Kingdom where premium discounts validate tracking investment. Three-tier pricing structure across forensic-grade, fleet-integrated, and consumer-retail levels separates certification-intensive OEM modules from commodity aftermarket hardware. Cost compression in standalone GPS hardware intensifies as dual-mode RF-GPS convergence elevates firmware differentiation over component value. Fleet operators exhibit lowest price sensitivity given cargo value exposure, while individual vehicle owners in Brazil and Mexico remain most responsive to financing-bundled subscription models.
Supply Chain Analysis
Reverse-logistics flows for warranty replacement modules and end-of-life recovery hardware concentrate refurbishment activity in Taiwan and South Korea, where GPS and cellular module foundries cluster. Semiconductor inputs draw from East Asian fabrication networks, with RF beacon components and battery management system interfaces resting on Japanese and German automotive supplier relationships. Single-source vulnerability in advanced node GPS chipsets exposes hardware manufacturers to allocation rationing during demand spikes. Distribution runs through Tier-1 automotive supplier networks for factory-fit mandates, while aftermarket channels rely on regional telematics integrators and insurance carrier direct procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native recovery workflows are displacing dedicated hardware consoles, compressing equipment economics while expanding platform subscription value. This technology transition rewards vendors with cloud-native architectures and penalizes hardware-dependent incumbents.
For Market Incumbents: Cement OEM production line positions through IEC 62443 cybersecurity certification investment ahead of regulatory enforcement waves. Deepen backward integration into cellular module sourcing to defend margin against East Asian foundry allocation volatility. Channel control through direct insurance carrier partnerships in underpenetrated Latin American markets provides defensive moat against cloud-native entrants.
For New Entrants and Emerging Players: Battery management system integration expertise offers entry wedge into electric vehicle native immobilization architectures where incumbent hardware players lack embedded systems competency. Target Brazilian and Mexican insurance channels with proven Southern European partnership models. Lead with compliance-grade automated response frameworks addressing EU AI Act algorithmic transparency requirements as regulatory clarity emerges.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized recovery platform providers given fleet procurement disintermediation trends and cloud-native margin expansion. Long-term viability favors vendors with dual-mode RF-GPS firmware differentiation and OEM integration certification depth. Monitor NHTSA mandate expansion timelines and EU AI Act national implementation divergence as inflection signals for architecture winners.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Integration Partnership | Locks in multi-year service contracts under NHTSA and EU Vehicle Security Regulation factory-fit mandates. |
| Insurance Channel Expansion | Captures premium discount validation in Germany, United Kingdom, and underpenetrated Brazilian markets. |
| Cybersecurity Certification Investment | Accelerates IEC 62443 and ISO/SAE 21434 compliance ahead of connected recovery system enforcement. |
| Cloud-Native Platform Migration | Enables smartphone-native workflows and elastic compute scaling for fleet operator disintermediation capture. |
| Latin America Geographic Entry | Replicates proven Southern European direct carrier models in São Paulo and Rio de Janeiro corridors. |
Methodological Framework
SEC filings, automotive production databases, and insurance regulatory filings formed the secondary backbone, cross-referenced with primary interviews across fleet procurement directors, Tier-1 supplier platform engineers, insurance underwriter technology leads, and law enforcement vehicle recovery coordinators. Bottom-up and top-down triangulation validated unit economics and service contract values. Primary fieldwork concentrated in the United States, Germany, United Kingdom, and Brazil to capture mandate implementation variance and channel structure divergence.
Bottom-up modeling segmented volume and value across technology, end user, service type, and integration level dimensions, with additional granularity for electric vehicle native versus retrofit installation pathways. CAGRs were derived from installed base projections and service contract renewal patterns throughout the forecast period. Key inputs included NHTSA mandate compliance timelines, EU AI Act implementation guidance from KBA and CNIL, and fleet telematics platform consolidation rates in North American logistics corridors.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian semiconductor supply, unanticipated RF spectrum allocation reversals, and accelerated privacy regulation restricting automated immobilization. Forecasts reflect assumptions around regulatory enforcement consistency and OEM integration pace. Practitioners should monitor EU AI Act national implementation divergence and NHTSA mandate expansion signals for early revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Global Road Maintenance Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market