
 Electric Vehicle Speed Reducer Market | 2026-2036
Electric Vehicle Speed Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Speed Reducer Market Foresight
Software-defined predictive maintenance contracts for reducer systems is consolidating supplier revenue models away from pure hardware sales. Schaeffler leverages its bearing-reducer integration expertise to capture long-term service agreements. ZF Friedrichshafen anchors European OEM relationships through modular e-axle platforms that bundle speed reducers with in-house motors.
An electric vehicle speed reducer is a precision gear transmission that steps down motor rotational speed to wheel-applicable torque, typically achieving ratios between 8:1 and 12:1 through planetary or helical gear architectures for single-speed and multi-speed drivetrains. Planetary gear configurations dominate passenger vehicle powertrains due to compact axial packaging and torque density advantages, while helical gear variants occupy heavy-duty truck applications where noise reduction and load capacity command premium positioning. Electromechanical technology leads the technology split as integrated motor-reducer units displace discrete mechanical assemblies, yet hydraulics retains niche traction in commercial vehicle brake system actuation where fail-safe redundancy governs specification.
China's MIIT enforces GB standards for NEV drivetrain efficiency that directly shape reducer design targets, while EPA tailpipe rules in the United States and EU Green Deal automotive CO2 thresholds in Europe create parallel compliance pressure across export-bound production. India's BIS and PLI scheme for advanced automotive components are accelerating local reducer qualification requirements for domestic EV programs. Stakeholders must monitor how divergent efficiency certification timelines across these three regulatory zones reshape supplier qualification costs and platform standardization strategies.
Market Dynamics
Integrated e-axle architectures are collapsing the traditional supplier tier structure by bundling speed reducers with motors and inverters into single procurement units, forcing standalone reducer manufacturers to defend their position through bearing integration or software-enabled service contracts.
Growth Catalysts
- China's NEV mandate architecture:MIIT efficiency benchmarks for drivetrain components are tightening annually, compelling automakers to source higher-precision reducer modules that minimize energy loss during torque conversion.
- Planetary gear torque density:Advances in compact axial packaging enable single-speed reducers to handle rising motor outputs without dimensional penalties, supporting platform standardization across battery-electric passenger vehicle lineups.
- Yangtze River Delta manufacturing corridor:Concentrated supplier ecosystems around BYD, NIO, and Tesla Shanghai generate procurement scale effects that drive down unit costs for integrated reducer-axle modules.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet motor-reducer integration expose suppliers to margin compression when raw material markets spike.
- Single-source precision gear grinding capacity:European and Japanese machine tool builders control the capital equipment base for sub-5-micron tolerance manufacturing, creating supply bottlenecks during demand surges.
- Helical gear noise floor limitations:Tooth contact pattern geometry constraints prevent helical architectures from matching planetary configurations in passenger vehicle packaging efficiency, relegating them to heavy-duty niches.
Strategic Opportunities
- India's PLI scheme for advanced automotive components:Domestic qualification requirements for EV programs are accelerating local reducer manufacturing investments, opening qualification pathways for suppliers meeting BIS certification timelines.
- Software-defined predictive maintenance:Long-term service agreements for reducer health monitoring are displacing pure hardware transactions, enabling recurring revenue streams tied to fleet uptime guarantees.
- Multi-speed drivetrain convergence:Two-speed reducer architectures paired with high-RPM motors are penetrating premium electric truck platforms where towing capacity and highway efficiency must coexist.
Industry Challenges
- GB standard compliance timeline compression:China's MIIT revises drivetrain efficiency certification benchmarks faster than typical 18-month product development cycles, forcing parallel engineering tracks to avoid disqualification.
- Electromechanical-hydraulic system integration:Commercial vehicle brake actuation redundancy requirements demand hybrid architectures that complicate supplier qualification and warranty liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Speed Reducer Market |
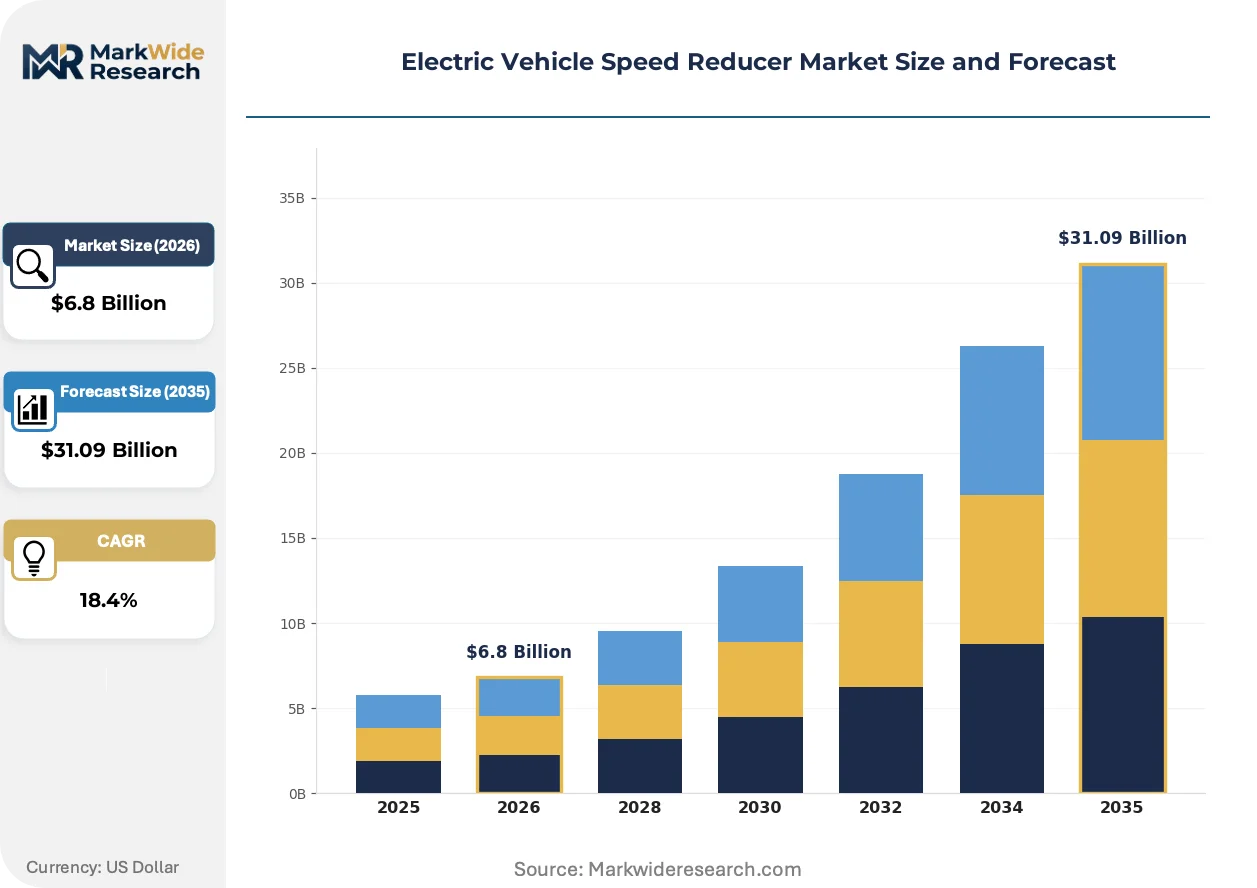
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planetary Gear, Worm Gear, Bevel Gear, Helical Gear End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Technology: Electromechanical, Hydraulics, Pneumatics, Mechanical Application: Powertrain, Traction Systems, Brake Systems, Steering Systems |
| Companies Covered | Schaeffler, Magna International, ZF Friedrichshafen, Hyundai Transys, Nidec Corporation, BorgWarner, GKN Automotive, Aisin Corporation, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Speed Reducer Market Shifts & Advancements
Distributed manufacturing footprints and modular platform architectures are reconfiguring how speed reducer suppliers engage with OEM assembly networks, compressing traditional tier boundaries while elevating software competency requirements.
Integrated motor-reducer units with shared thermal management circuits are decentralizing the historical separation between power electronics and mechanical transmission engineering teams. Tier 1 suppliers are consolidating these competencies in-house to capture e-axle platform awards. This convergence is compressing the addressable market for standalone reducer specialists unable to extend into motor control firmware development.
EPA tailpipe rules in the United States are tightening CO2 thresholds for light-duty vehicle fleets, indirectly pressuring drivetrain efficiency across export-bound production. OEMs are specifying reducer modules with sub-97% efficiency floors to preserve range ratings under combined cycle testing. Heavy-duty electric truck programs are responding with dedicated thermal management investments to maintain reducer performance under sustained load conditions.
After-sales service unbundling is fragmenting traditional supplier-OEM warranty relationships in European commercial vehicle markets. Fleet operators are negotiating direct predictive maintenance contracts with reducer manufacturers, bypassing dealer service networks. Germany's KBA type-approval framework has yet to adapt to this disintermediation, creating regulatory ambiguity around liability for safety-critical drivetrain components.
Electric Vehicle Speed Reducer Market Segmentation
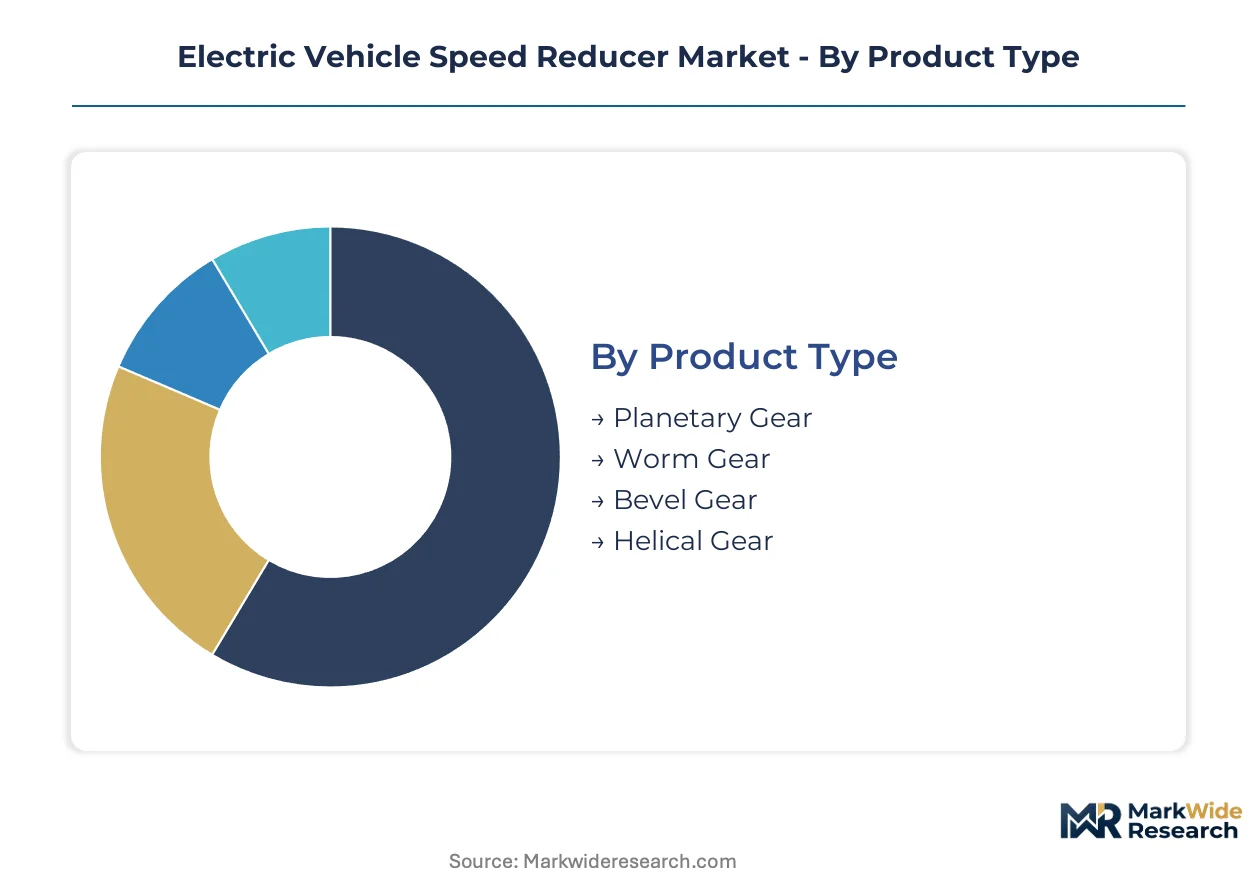
Speed reducer segmentation reveals how packaging constraints, duty cycles, and integration depth fragment procurement specifications across passenger, commercial, and industrial mobility platforms. Component selection hinges on torque density requirements, thermal management needs, and OEM platform standardization strategies.
Product Type:
Standardization pressure from integrated e-axle platforms is compressing the customization spectrum, yet gear architecture selection still varies sharply by load rating and acoustic targets.
- Planetary Gear:Concentric sun-planet-ring configurations deliver the highest torque density per unit volume, enabling single-speed designs that dominate battery-electric passenger vehicle procurement from the Yangtze River Delta manufacturing corridor. BYD and Tesla Shanghai specify planetary modules for their platform scalability across multiple vehicle classes.
- Helical Gear:Angled tooth engagement distributes load across broader contact surfaces, supporting sustained torque transmission in heavy-duty truck applications where noise reduction and bearing longevity command specification priority. European OEMs specify helical variants for electric long-haul platforms where thermal fatigue governs warranty exposure.
- Worm Gear:Screw-wheel meshing provides irreversible torque transmission for steering column and limited-slip differential applications requiring self-locking characteristics.
- Bevel Gear:Right-angle power transfer enables driveline packaging in axle-mounted configurations where motor-reducer alignment constraints demand orthogonal shaft arrangements.
Planetary Gear leads on scale; Helical Gear leads on momentum in commercial vehicle electrification.
End User:
Vehicle class determines thermal duty cycles, with passenger platforms prioritizing packaging efficiency and heavy-duty segments demanding sustained load capacity.
- Passenger Vehicles:Battery-electric platforms drive procurement volumes for integrated reducer-axle modules, with China's MIIT efficiency benchmarks compelling automakers to source sub-2% energy loss transmissions. NIO and Tesla Shanghai anchor supplier ecosystems with annual procurement scale that compresses unit costs.
- Heavy-Duty Trucks:Towing capacity and gradeability requirements are penetrating two-speed reducer architectures where high-RPM motors must coexist with low-speed torque multiplication. Thermal management investments dominate specification discussions for sustained highway load conditions.
- Commercial Vehicles:Delivery van and bus platforms balance payload capacity with urban packaging constraints, driving demand for compact coaxial reducer designs.
- Two-Wheelers:Cost-sensitive scooter and motorcycle applications specify stamped housing reducers with minimal gear count, prioritizing manufacturing simplicity over efficiency optimization.
Passenger Vehicles dominate volume capture; Heavy-Duty Trucks exhibit the steepest expansion trajectory as freight electrification accelerates.
Technology:
Integration depth separates electromechanical convergence from legacy mechanical preservation, with hydraulics retaining niche fail-safe applications.
- Electromechanical:Integrated motor-reducer units with shared thermal management circuits are displacing discrete mechanical assemblies, consolidating Tier 1 supplier competencies in firmware and power electronics. Schaeffler and ZF Friedrichshafen anchor European OEM relationships through modular e-axle platforms bundling speed reducers with in-house motors.
- Hydraulics:Commercial vehicle brake system actuation retains hydraulic redundancy where fail-safe requirements govern specification, complicating supplier qualification through hybrid architecture warranty liability allocation.
- Pneumatics:Compressed air systems occupy limited auxiliary applications where weight minimization outweighs energy efficiency in specialty vehicle segments.
- Mechanical:Discrete gearboxes persist in aftermarket replacement and cost-optimized two-wheeler platforms where integration investment cannot be recovered.
Electromechanical commands revenue concentration; Hydraulics defends niche positioning through safety-critical specification lock-in.
Application:
Functional location within the vehicle determines load profile severity and thermal management investment, with powertrain integration commanding the deepest supplier-OEM collaboration.
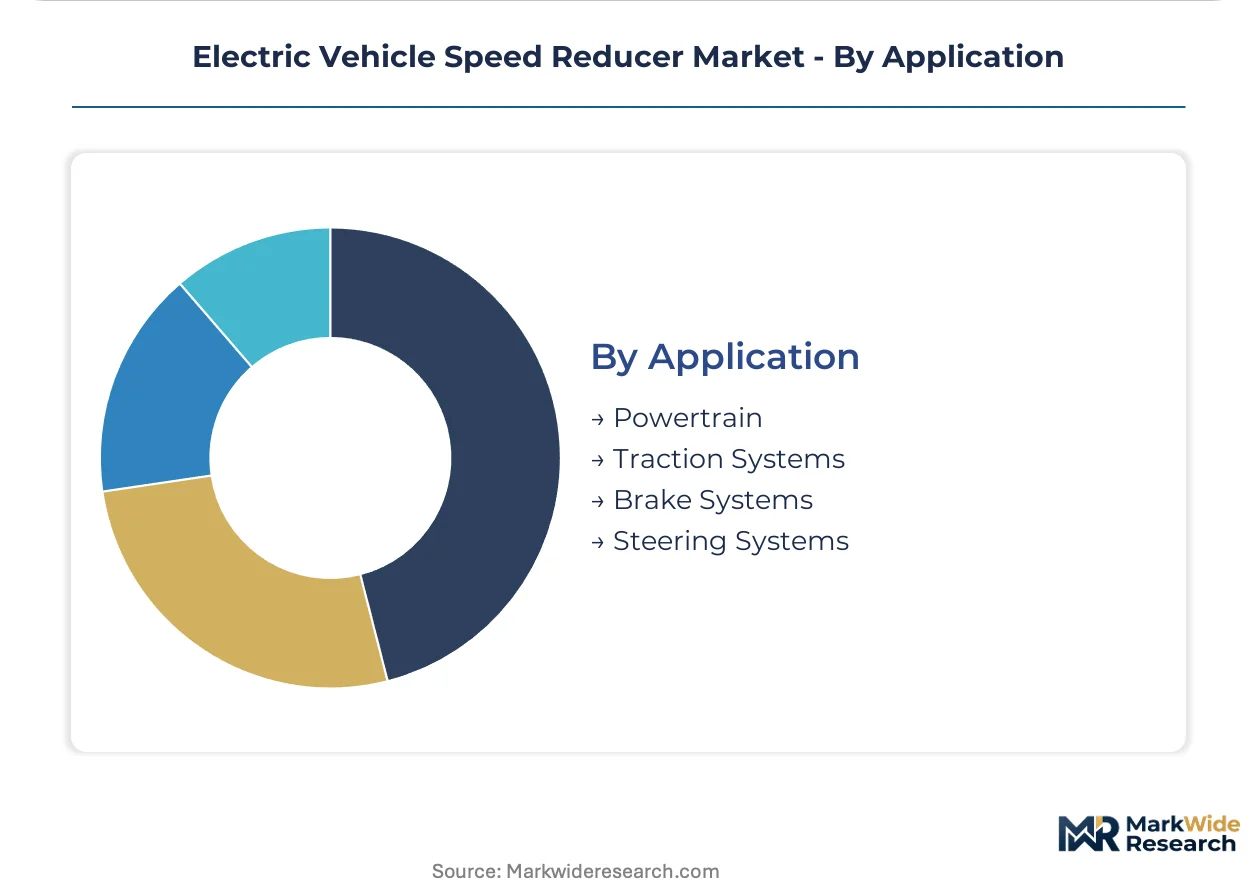
- Powertrain:Motor-to-wheel torque conversion represents the primary reducer application, with efficiency floors above 97% specified to preserve range ratings under EPA combined cycle testing. Integrated e-axle architectures are collapsing traditional supplier tier structures by bundling reducers with motors and inverters.
- Brake Systems:Electromechanical-hydraulic hybrid architectures in commercial vehicles demand redundancy that complicates supplier qualification, with Germany's KBA type-approval framework creating regulatory ambiguity around liability allocation.
- Traction Systems:All-wheel-drive and torque-vectoring applications specify multi-reducer configurations with electronic differential control.
- Steering Systems:Electric power steering columns utilize compact worm or planetary reducers to amplify motor torque for rack actuation.
Powertrain absorbs the dominant share of engineering resources; Brake Systems generate the most complex certification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting reducer production toward jurisdictions with faster certification timelines and concentrated supplier ecosystems, as automakers seek to minimize qualification costs while securing proximity to high-volume EV assembly.
China
MIIT's GB standards for drivetrain efficiency are tightening annually, compelling suppliers to engineer higher-precision planetary gear modules that minimize energy loss. The Yangtze River Delta manufacturing corridor concentrates procurement scale effects around BYD, NIO, and Tesla Shanghai, driving down unit costs for integrated reducer-axle modules through localized supplier ecosystems.
Germany
KBA type-approval frameworks create regulatory ambiguity around liability for safety-critical drivetrain components as fleet operators negotiate direct predictive maintenance contracts. ZF Friedrichshafen anchors European OEM relationships through modular e-axle platforms, while Schaeffler leverages bearing-reducer integration expertise to capture long-term service agreements.
United States
EPA tailpipe rules are tightening CO2 thresholds for light-duty vehicle fleets, indirectly pressuring drivetrain efficiency across export-bound production. OEMs specify reducer modules with sub-97% efficiency floors to preserve range ratings under combined cycle testing, with thermal management investments dominating specification discussions.
India
BIS certification timelines and the PLI scheme for advanced automotive components are accelerating local reducer qualification requirements for domestic EV programs. Suppliers meeting compressed domestic qualification pathways are opening manufacturing investments to serve accelerating fleet electrification in commercial vehicle segments.
Japan
METI efficiency benchmarks and JIS standards govern precision gear manufacturing requirements for export-bound production. Nidec Corporation and Aisin Corporation anchor supplier ecosystems serving both domestic OEMs and technology licensing arrangements across Southeast Asian assembly networks.
Electric Vehicle Speed Reducer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated e-axle platforms collapsing traditional tier boundaries while standalone reducer specialists defend position through bearing integration or software-enabled service contracts. The market structure concentrates around Tier 1 suppliers with in-house motor control firmware development capabilities, while discrete mechanical assembly specialists face compressing addressable markets. Three archetypes dominate: integrated e-axle platform providers, bearing-reducer integration specialists, and software-defined predictive maintenance contractors. Competitive moves center on strategic partnerships for thermal management circuit integration and geographic expansion into India's PLI-qualified manufacturing zones.
Among European-anchored platform providers, ZF Friedrichshafen and Schaeffler exemplify the integrated e-axle archetype, with the former occupying a position in modular platform bundling and the latter representing bearing-reducer convergence. Hyundai Transys sits within the Asia-Pacific supplier tier, reflecting Korean industrial group structuring around captive automotive supply relationships.
| Leading Market Players |
|---|
| Schaeffler |
| Magna International |
| ZF Friedrichshafen |
| Hyundai Transys |
| Nidec Corporation |
| BorgWarner |
| GKN Automotive |
| Aisin Corporation |
| Robert Bosch |
| Others |
Supply & Pricing Matrix
Neodymium and dysprosium price swings embedded in permanent magnet motor-reducer integration cascade through three pricing tiers: premium planetary gear modules for Yangtze River Delta OEMs, mid-range helical variants for European long-haul trucks, and economy stamped-housing units for Indian two-wheeler platforms.
Pricing Analysis
Distributor margins compress as integrated e-axle platforms consolidate procurement into direct OEM relationships. Pricing stratifies across premium, standard, and economy tiers based on gear precision grade and MIIT efficiency certification level. Cost compression in the mid-tier intensifies because rare earth magnet volatility erodes supplier margins. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while two-wheeler manufacturers resist any premium above commodity mechanical alternatives.
Supply Chain Analysis
Freight costs from Japanese and German precision grinding machine builders inflate landed equipment costs for sub-5-micron tolerance manufacturing capacity. Supply concentrates in China, Germany, and Japan for finished reducer modules, with raw material dependencies spanning neodymium from Myanmar, steel alloys from South Korea, and specialized cutting tools from Switzerland. Single-source vulnerability in European machine tool capacity creates chokepoints during demand surges. Distribution runs through Tier 1 e-axle integrators who bundle reducers with motors and inverters for OEM platform awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bearing-reducer integration expertise and software-enabled predictive maintenance contracts that displace pure hardware transactions.
For Market Incumbents: Lock in long-term service agreements with fleet operators bypassing dealer networks, as Germany's KBA type-approval ambiguity around liability allocation threatens traditional warranty structures. Deepen backward integration into precision gear grinding capacity to escape single-source machine tool dependency. Prioritize thermal management circuit R&D to defend against integrated e-axle platform consolidation. For New Entrants and Emerging Players: Begin with India's PLI-qualified manufacturing zones where BIS certification timelines create qualification windows for domestic EV commercial vehicle programs. Target heavy-duty truck two-speed reducer architectures where European OEMs seek alternatives to incumbent helical gear suppliers. Pursue direct fleet operator relationships for predictive maintenance software rather than competing on hardware cost. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone reducer specialists lack motor control firmware capabilities and face collapsing addressable markets. Five-to-ten year viability favors bearing-reducer integration specialists with software service revenue streams over discrete mechanical assemblers. Monitor MIIT GB standard revision frequency as inflection indicator for supplier qualification cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Bearing-Reducer Integration Investment | Schaeffler's expertise captures long-term service agreements displacing hardware-only transactions. |
| Software-Defined Predictive Maintenance Platform | Recurring revenue models tied to fleet uptime guarantees reshape supplier-OEM relationships. |
| India PLI Manufacturing Footprint | BIS certification timelines open qualification pathways for domestic EV commercial vehicle supply. |
| Two-Speed Reducer Architecture Development | Premium electric truck platforms demand towing capacity and highway efficiency coexistence. |
| Thermal Management Circuit Integration | Shared cooling systems with motors and inverters consolidate Tier 1 e-axle platform awards. |
Research Methodology
Multiple input streams — OEM platform engineering directors, Tier 1 supplier procurement leads, precision gear machine tool operators, and aftermarket fleet maintenance managers — were reconciled against MIIT regulatory filings, EPA tailpipe rule dockets, vehicle production databases, and customs trade records. Bottom-up unit shipment estimates across planetary, helical, worm, and bevel gear architectures were cross-validated with top-down value aggregation from integrated e-axle platform awards.
Historical production trajectories were cross-referenced against expert panel assessments of MIIT efficiency benchmark tightening and rare earth magnet cost volatility. Segmentation dimensions modeled span gear architecture type, vehicle class, integration depth, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and procurement scale effects in the Yangtze River Delta manufacturing corridor.
Several conditions sit outside the modeled scope, including potential rare earth export restrictions, abrupt KBA liability framework revisions, and breakthrough solid-state motor technologies eliminating mechanical reduction. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market