
 Middle-East and Africa Electric Vehicle (EV) Fluids Market | 2026-2036
Middle-East and Africa Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Electric Vehicle (EV) Fluids Market Outlook
Fleet procurement among commercial vehicle operators is consolidating into fewer, larger tenders with multi-year supply agreements. Exxon Mobil Corporation leverages its integrated base oil and additive supply chain to compete for these centralized contracts. Shell plc anchors its position through direct partnerships with OEM service networks across the Gulf. TotalEnergies differentiates via specialized coolants formulated for high-ambient-temperature climates prevalent across the region.
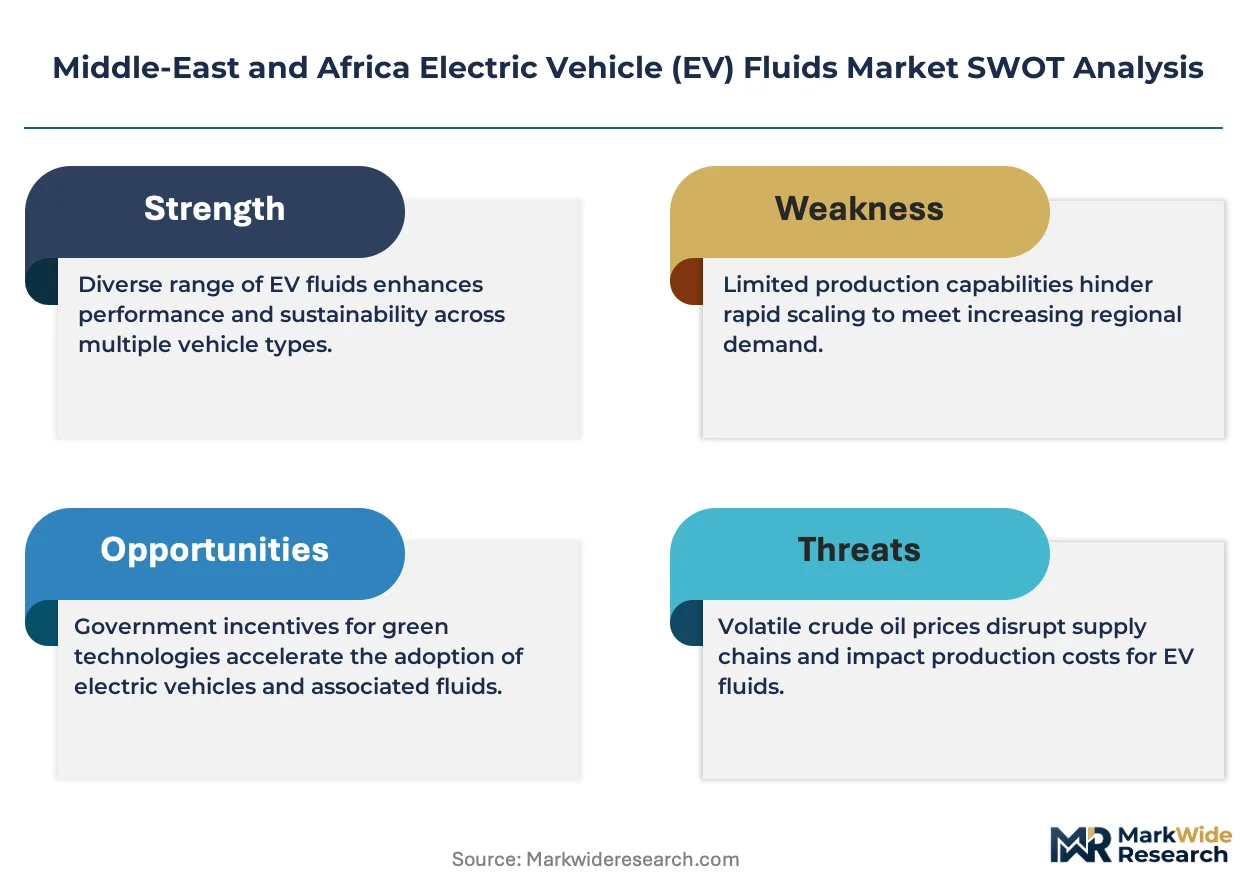
Middle-East and Africa Electric Vehicle (EV) Fluids encompass dielectric coolants, thermally conductive lubricants, and low-conductivity brake fluids engineered with specific viscosity grades and additive packages to manage battery thermal runaway risks and electric motor efficiency losses. These fluids serve the critical function of heat extraction and friction reduction in electrified powertrains operating under extreme desert thermal loads. Coolants and lubricants together represent the dominant product categories, with coolants capturing the largest margin pools due to formulation complexity and replacement frequency requirements. The passenger vehicle application leads current volumes, though commercial vehicles and buses are expanding fastest as municipal transit electrification accelerates in Dubai, Riyadh, and Cape Town.
Saudi Arabia's national regulator SAMR enforces product labeling and quality certification for automotive fluids, while the UAE's Emirates Authority for Standardization and Metrology (ESMA) mandates thermal performance testing for EV-specific formulations. South Africa's National Regulator for Compulsory Specifications (NRCS) governs brake fluid safety standards that extend to electrified commercial fleets. Stakeholders must monitor how Gulf Cooperation Council harmonization of EV technical regulations reshapes formulation requirements and import compliance pathways.
Market Dynamics
Fleet electrification mandates across municipal transit systems are compressing fluid replacement cycles and forcing reformulation of thermal management chemistries for desert operating conditions.
Growth Catalysts
- UAE Corporate Average Fuel Economy Standards:Updated efficiency benchmarks accelerate commercial fleet electrification, expanding addressable fluid volumes for dielectric coolants in heavy-duty applications.
- High-ambient-temperature formulations:Specialized additive packages engineered for Gulf thermal loads open premium positioning opportunities distinct from temperate-climate products.
- Gauteng province fleet density:South Africa's concentrated logistics corridors enable efficient service network deployment and bulk supply consolidation for electrified commercial vehicles.
Market Restraints
- Base oil supply concentration:Regional dependence on imported Group III and synthetic base stocks exposes formulators to freight cost volatility and currency fluctuation risks.
- SAMR certification timelines:Saudi Arabia's extended product registration procedures for EV-specific fluids delay market entry and compress effective patent windows.
- Legacy internal combustion service infrastructure:Existing lube bay equipment and technician training curricula require capital-intensive retooling for dielectric fluid handling protocols.
Strategic Opportunities
- Saudi Vision 2030 dual carbon targets:National decarbonization commitments create mandated demand pull for electrified bus fleets and associated thermal management fluids.
- Direct OEM service network partnerships:Bypassing traditional aftermarket distributors captures higher margins through captive supply agreements with manufacturer-authorized facilities.
- Cape Town municipal transit electrification:South Africa's leading metro presents a testbed for high-temperature coolant formulations before broader African rollout.
Industry Challenges
- Dielectric fluid safety certification:NRCS compliance testing for electrified commercial vehicle brake fluids requires specialized laboratory capacity currently limited in the region.
- Thermal management technician training:Gulf service networks face acute shortages of personnel qualified to handle high-voltage cooling system maintenance without OEM direct supervision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Electric Vehicle (EV) Fluids Market |
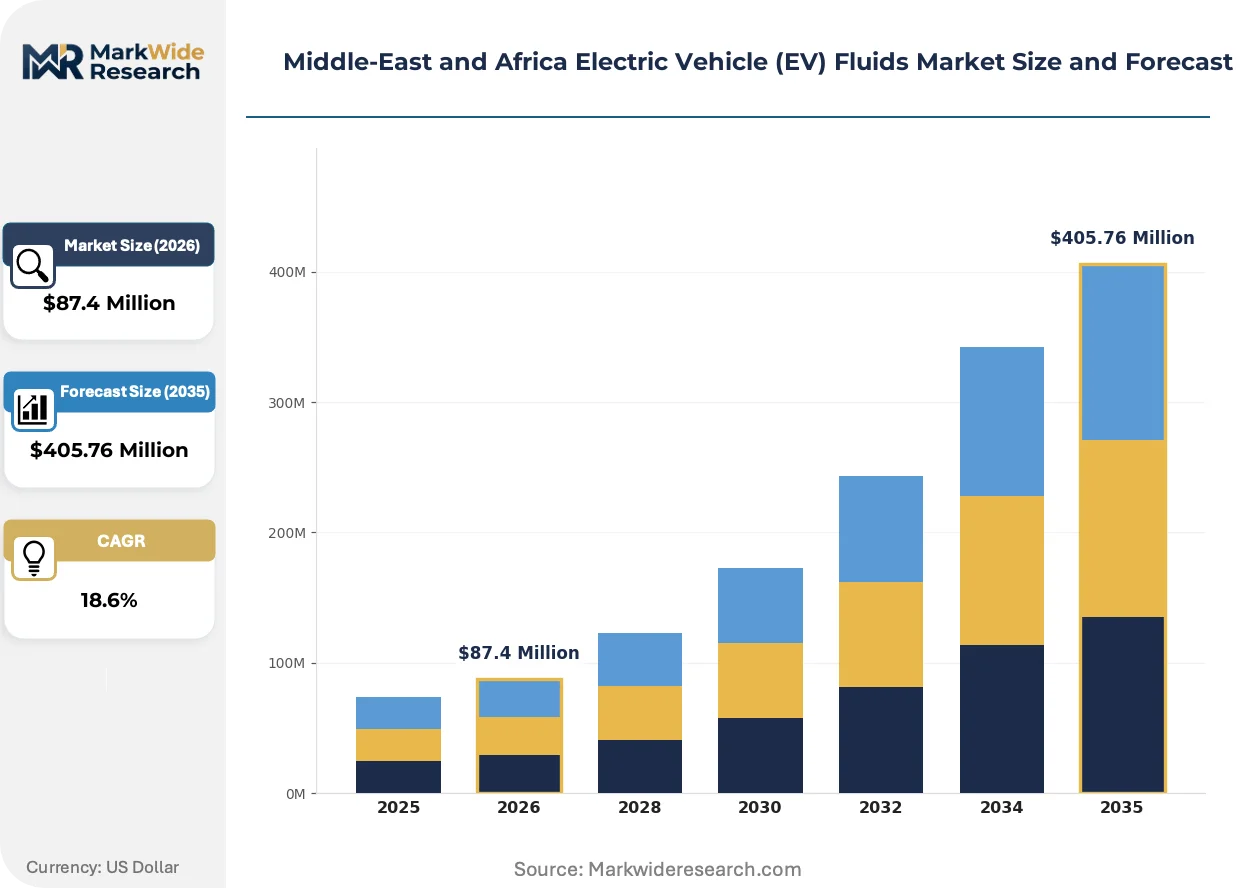
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolants, Lubricants, Brake Fluids, Transmission Fluids Application: Passenger Vehicles, Commercial Vehicles, Buses, Motorbikes Distribution Channel: Online, Retail, Direct Sales, Service Stations End User: OEMs, Aftermarket, Fleet Operators, Repair Shops |
| Companies Covered | Exxon Mobil Corporation, Shell plc, TotalEnergies, FUCHS, Saudi Arabian Oil Co, Gulf Oil International Ltd, ENEOS Corporation, Repsol, Petroliam Nasional Berhad (PETRONAS), Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Electric Vehicle (EV) Fluids Market Strategic Shifts
Formulation science is pivoting toward single-fluid architectures that combine thermal management with electrical insulation, collapsing the traditional separation between coolants and lubricants in electrified powertrains.
Advanced silicone-based dielectric fluids are integrating graphene nanoplatelet additives to enhance thermal conductivity without compromising electrical resistivity. Dubai-based fleet operators are piloting these formulations in air-conditioned depot environments where thermal cycling stress is most severe. The technology is integrating previously separate cooling loops for batteries and power electronics into unified architectures, reducing part count and service complexity.
ESMA thermal performance testing mandates are forcing disclosure of fluid degradation curves under sustained high-temperature operation. Gulf Cooperation Council harmonization discussions are extending these requirements across member states, creating a unified compliance pathway for suppliers. Formulators serving the UAE-Dubai-Abu Dhabi corridor are responding by accelerating validation protocols to capture first-mover certification status.
Centralized procurement through municipal tender boards is displacing fragmented distributor purchasing across Middle-East transit authorities. Multi-year supply agreements with performance guarantees are replacing spot-market transactions in Riyadh and Jeddah bus electrification programs. This consolidation is most visible in Saudi Arabia where SAMR quality certification serves as a pre-qualification barrier for contract participation.
Middle-East and Africa Electric Vehicle (EV) Fluids Market Segmentation
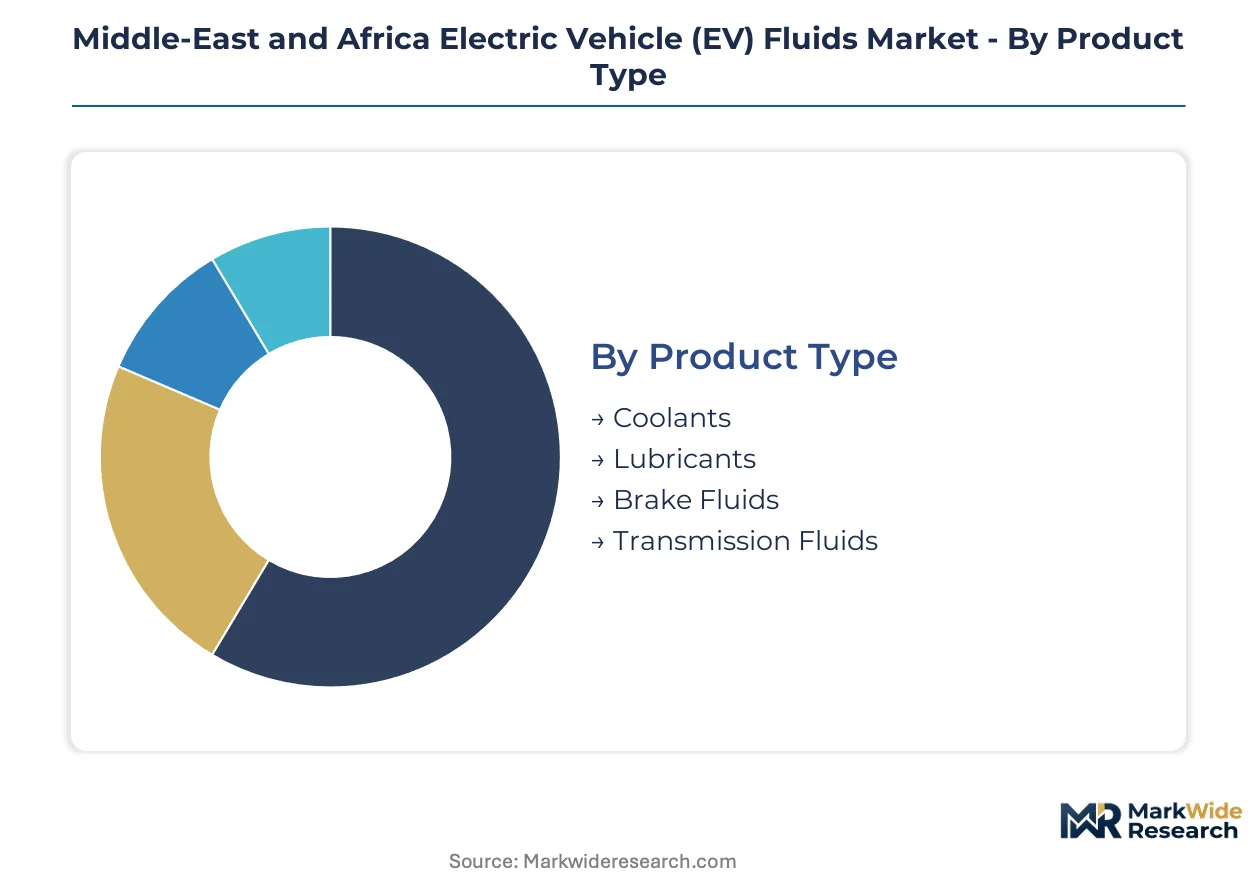
Segmentation in the Middle-East and Africa Electric Vehicle (EV) Fluids Market reveals how formulation complexity, thermal performance requirements, and procurement concentration vary across product categories and customer types. Distinct certification burdens from SAMR, ESMA, and NRCS apply unevenly across segments, creating tiered barriers to entry that reshape competitive positioning.
Product Type:
Coolants and lubricants carry the heaviest certification loads under ESMA thermal performance testing and SAMR quality registration, while brake fluids face NRCS safety compliance for electrified commercial fleets.
- Coolants:Dielectric formulations with specialized additive packages manage battery thermal runaway risks under extreme desert thermal loads. Demand concentrates in Dubai-Abu Dhabi corridor fleet depots where air-conditioned environments create severe thermal cycling stress on unified battery-power electronics cooling architectures.
- Lubricants:Thermally conductive grades reduce electric motor efficiency losses in electrified powertrains. Saudi Arabia's dual carbon targets are pulling reformulated chemistries into Riyadh and Jeddah bus electrification programs with multi-year supply guarantees.
- Brake Fluids:Low-conductivity specifications serve electrified commercial vehicle braking systems under NRCS safety standards. South Africa's Gauteng province logistics corridors drive bulk supply consolidation for compliant formulations.
- Transmission Fluids:Specialized viscosity grades for single-speed and multi-speed e-axle configurations. Cape Town municipal transit electrification pilots are validating high-temperature performance before broader African rollout.
Coolants sit at the top of the volume ranking, with lubricants climbing the fastest as commercial fleet electrification accelerates.
Application:
Cost tier differentiation separates premium thermal management formulations for heavy-duty commercial duty cycles from standard-grade products serving temperate-climate passenger applications.
- Passenger Vehicles:Current volume leader with established dielectric coolant replacement cycles. UAE corporate average fuel economy standards are compressing service intervals and expanding addressable fluid volumes across Dubai-Abu Dhabi private fleets.
- Commercial Vehicles:Fastest-expanding segment as municipal transit electrification mandates tighten across the region. Fleet procurement consolidation into centralized tenders with performance guarantees is displacing fragmented distributor purchasing.
- Buses:High-ambient-temperature formulations dominate Riyadh, Jeddah, and Cape Town electrification programs. SAMR certification serves as pre-qualification barrier for contract participation in Saudi Vision 2030 transit initiatives.
- Motorbikes:Emerging application with limited dedicated formulation development. Regional dependence on imported base stocks constrains localized product development for this lower-volume segment.
Passenger vehicles capture the largest revenue base today, with commercial vehicles gaining share fastest through fleet tender consolidation.
Distribution Channel:
Customer type determines channel preference, with fleet operators bypassing traditional retail for direct supply agreements while independent repair shops remain tethered to service station networks.
- Online:Limited penetration due to dielectric fluid handling safety protocols and technician qualification requirements. Direct OEM service network partnerships are capturing higher margins through captive supply agreements.
- Retail:Fragmented aftermarket purchasing persists for independent passenger vehicle owners. Legacy internal combustion service infrastructure requires capital-intensive retooling for proper dielectric fluid handling.
- Direct Sales:Dominant channel for fleet operators and municipal tender boards. Multi-year supply agreements with thermal performance guarantees are replacing spot-market transactions across Saudi Arabia and UAE.
- Service Stations:Traditional lube bay networks face acute shortages of personnel qualified for high-voltage cooling system maintenance. Gulf Cooperation Council harmonization of EV technical regulations is reshaping service equipment standards.
Direct sales command the premium tier by volume, with online channels expanding most quickly as safety training protocols standardize.
End User:
Supply concentration favors OEMs and fleet operators with centralized procurement power, while aftermarket and repair shops face margin compression from certification complexity and equipment retooling costs.
- OEMs:Manufacturer-authorized facilities anchor Shell plc's partnership strategy across Gulf service networks. First-mover certification status under ESMA and SAMR protocols creates captive supply lock-in.
- Aftermarket:Independent distributors face displacement as municipal tender boards consolidate procurement. Extended SAMR registration timelines compress effective market windows for new entrants.
- Fleet Operators:Fastest-growing buyer segment with multi-year supply agreements demanding performance guarantees. Exxon Mobil Corporation competes for these centralized contracts through integrated base oil and additive supply chain control.
- Repair Shops:Limited laboratory capacity for NRCS compliance testing constrains service expansion for electrified commercial fleets. Technician training curricula lag behind dielectric fluid handling protocol requirements.
Fleet operators are climbing the fastest by volume, with OEMs retaining the top revenue position through captive service network agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's dual carbon targets and the UAE's corporate fuel economy standards are compressing fluid replacement cycles faster than South Africa's concentrated logistics corridors can match, creating a three-speed electrification landscape across the region.
United Arab Emirates
Dubai-Abu Dhabi fleet depots drive concentrated demand for dielectric coolants in air-conditioned environments with severe thermal cycling stress. ESMA thermal performance testing mandates force disclosure of fluid degradation curves under sustained high-temperature operation. The Dubai-Abu Dhabi corridor anchors Shell plc's direct OEM service network partnerships across Gulf manufacturer-authorized facilities.
Saudi Arabia
Riyadh and Jeddah bus electrification programs pull reformulated lubricant chemistries through multi-year supply agreements with performance guarantees. SAMR quality certification serves as pre-qualification barrier for municipal tender board contract participation under Vision 2030 transit initiatives. The Eastern Province's industrial base supports localized blending capacity for high-ambient-temperature formulations.
South Africa
Gauteng province logistics corridors enable efficient bulk supply consolidation for electrified commercial vehicle fleets. NRCS safety standards govern brake fluid compliance for electrified commercial fleets with limited regional laboratory capacity. Cape Town municipal transit electrification pilots validate high-temperature coolant formulations before broader African rollout.
Qatar
Doha's municipal fleet electrification creates demand pull for specialized additive packages engineered for Gulf thermal loads. The country's national standardization body aligns product registration requirements with Gulf Cooperation Council harmonization discussions. Lusail's smart city infrastructure integrates unified battery-power electronics cooling architectures in electrified transit depots.
Middle-East and Africa Electric Vehicle (EV) Fluids Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around integrated base oil and additive supply chains. The vendor base separates into three archetypes: global majors with captive raw material positions, regional oil companies leveraging downstream integration, and specialized formulators targeting high-ambient-temperature niches. Dominant competitive moves include direct OEM service network partnerships bypassing traditional aftermarket distributors and accelerated ESMA/SAMR certification protocols capturing first-mover regulatory lock-in.
Within the integrated supply chain tier, Exxon Mobil Corporation and Shell plc exemplify archetypes competing for centralized fleet procurement contracts. TotalEnergies occupies a position representing specialized climate-specific formulation focus. Among regional oil companies, Saudi Arabian Oil Co and Gulf Oil International Ltd anchor positions leveraging geographic proximity to Gulf demand centers. FUCHS exemplifies the specialized formulator archetype targeting thermal management complexity premiums.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| TotalEnergies |
| FUCHS |
| Saudi Arabian Oil Co |
| Gulf Oil International Ltd |
| ENEOS Corporation |
| Repsol |
| Petroliam Nasional Berhad (PETRONAS) |
| Others |
Value Chain & Pricing Dynamics
Municipal tender boards across Saudi Arabia and the UAE anchor pricing power through multi-year supply agreements with performance guarantees, compressing spot-market premiums and forcing formulators toward contract-based long-term offtake structures. This procurement concentration rewards suppliers with first-mover ESMA and SAMR certification status, locking in margin pools that fragmented aftermarket channels cannot match.
Pricing Analysis
Capacity additions in the UAE's Eastern Province are reshaping price floors for high-ambient-temperature formulations. Three-tier pricing structure across premium, standard, and economy levels separates ESMA-certified dielectric coolants from generic imports and commodity base stocks. Price differentiation hinges on thermal performance disclosure requirements and Gulf Cooperation Council harmonization timelines. Cost compression in standard-grade lubricants is intensifying because Group III base oil freight volatility feeds directly into landed costs. Fleet operators show lowest price sensitivity due to captive service network lock-in, while independent repair shops face acute margin pressure from equipment retooling requirements.
Supply Chain Analysis
Single-source vulnerability sits with imported Group III and synthetic base stocks from South Korea, Japan, and Singapore. Regional formulators draw from concentrated additive packages, specialized dielectric chemistries, and graphene nanoplatelet feedstocks anchored in East Asian manufacturing hubs. Tariff exposure runs through Gulf Cooperation Council customs union alignment gaps with major supplier jurisdictions. Distribution runs through direct OEM service network partnerships bypassing traditional aftermarket distributors, with Shell plc and Exxon Mobil Corporation capturing captive supply channels across manufacturer-authorized facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SAMR quality certification and ESMA thermal performance testing create escalating barriers that concentrate margin pools among first-movers. Saudi Vision 2030 transit electrification mandates represent the pivotal demand milestone compressing fluid replacement cycles and expanding addressable volumes.
For Market Incumbents: Hedge against emerging pure-play thermal management specialists by deepening backward integration into base oil blending capacity and accelerating validation protocols for unified battery-power electronics cooling architectures. Defensive consolidation through direct OEM service network partnerships locks out distributor-dependent challengers. Priority investment in Cape Town municipal transit pilot programs secures African rollout precedence before NRCS laboratory capacity constraints ease. For New Entrants and Emerging Players: Launch via specialized high-ambient-temperature formulations targeting Qatar's Lusail smart city infrastructure and Doha's municipal fleet electrification, where Gulf Cooperation Council harmonization discussions have not yet closed certification windows. The most penetrable white space sits with transmission fluids for single-speed e-axle configurations in South Africa's Gauteng logistics corridors, where bulk supply consolidation favors agile formulators. Go-to-market angle: performance-guaranteed pilot programs with thermal cycling stress validation in air-conditioned depot environments. For Investors and Strategic Acquirers: Integrated base oil and additive conglomerates represent the most active acquirer category in this space, seeking captive supply chain control for centralized fleet procurement contracts. Long-term viability over a five-to-ten year horizon rests on regulatory harmonization completion across Gulf Cooperation Council member states. Acquisition target archetype: specialized formulators with ESMA first-mover certification and validated graphene nanoplatelet additive integration. Signal to watch: NRCS laboratory capacity expansion announcements indicating South African market entry barriers easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Blending | Captive supply of Group III stocks insulates Exxon Mobil Corporation from freight cost volatility. |
| ESMA First-Mover Certification Acceleration | Early thermal performance disclosure creates regulatory lock-in across Dubai-Abu Dhabi corridor fleet depots. |
| Direct OEM Service Network Partnerships | Shell plc bypasses fragmented distributors through manufacturer-authorized facility captive supply agreements. |
| Graphene Nanoplatelet Additive Integration | Advanced silicone-based dielectric formulations unify battery-power electronics cooling architectures in Gulf thermal loads. |
| Cape Town Municipal Transit Pilot Programs | High-temperature coolant validation before broader African rollout tests TotalEnergies climate-specific positioning. |
Study Parameters
Direct dialogue with thermal management R&D directors, fleet procurement managers at municipal transit authorities, ESMA certification specialists, and aftermarket service network operators grounded qualitative findings in operational reality. Secondary validation drew from SAMR product registration databases, ESMA thermal performance testing protocols, NRCS safety standard filings, and Gulf Cooperation Council harmonization discussion records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Bottom-up modeling anchored volume projections in vehicle electrification penetration curves by propulsion architecture and regional production cluster, while top-down approaches tested aggregate fluid demand against OEM service network expansion plans. Segmentation dimensions spanned product type, application, distribution channel, and end user, with additional granularity around thermal performance tier and certification status. CAGRs emerged from fitted growth curves incorporating fleet electrification mandate timelines and base oil supply elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Gulf Cooperation Council regulatory harmonization delays or NRCS laboratory capacity expansion failures. Forecasts reflect assumptions around SAMR registration timeline compression and ESMA disclosure requirement adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
North America Electric Vehicle Market