
 Electric Car Rental Market | 2026-2036
Electric Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Car Rental Market Analysis
Certified EV fleet technician availability is collapsing across major rental hubs, forcing operators to restructure maintenance partnerships or build in-house training academies. The Hertz Corporation leverages its direct OEM relationships to secure priority vehicle allocations during supply constraints. Avis Budget Group Inc. sustains competitive density through airport concession dominance in North American gateways. Europcar Mobility Group anchors its European position with city-center micromobility integration alongside full-size electric offerings.
Electric car rental denotes the short-to-medium-term commercial provision of battery-electric passenger vehicles to end-users through structured fee-based agreements, with fleet composition governed by range certification, charging interface standards, and residual value forecasting algorithms. The service exists to decarbonize temporary mobility without imposing ownership capital burdens or battery degradation risk on individual users. Compact and sedan categories currently dominate fleet procurement due to lower per-unit acquisition costs and superior energy efficiency metrics in urban duty cycles. The subscription service model exhibits the fastest structural ascent as it captures consumers seeking fixed-cost electric access without long-term commitment. Corporate customer segments concentrate margin pools through negotiated volume contracts and centralized billing structures.
The EPA tailpipe standards and NHTSA fuel economy frameworks in the United States compel rental fleets to electrify to avoid penalty exposure and maintain airport operating licenses. The EU Green Deal and F-Gas Regulation in Europe mandate progressive CO2 reduction across commercial vehicle pools, directly accelerating replacement timelines for combustion rental units. China's MIIT new energy vehicle mandates and GB charging standards create compliance-driven procurement floors for operators seeking license renewals. Stakeholders must monitor charging infrastructure buildout velocity against fleet expansion rates to avoid utilization collapse from range anxiety or dwell-time bottlenecks.
Market Dynamics
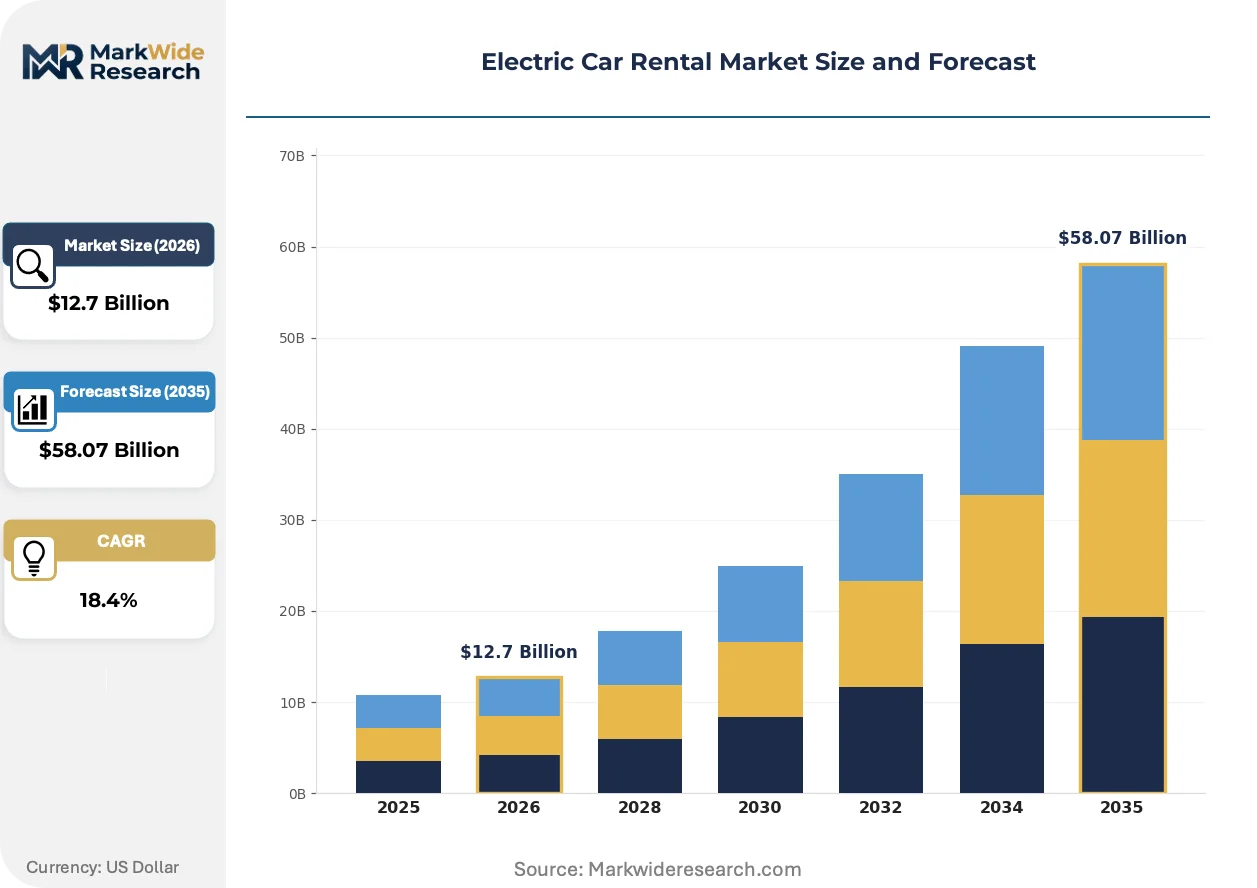
Fleet electrification timelines now hinge on charging infrastructure buildout velocity outpacing vehicle procurement rates, with battery swapping protocols emerging as the decisive operational variable for rental density economics.
Growth Catalysts
- EPA Tailpipe Standards:United States rental operators face penalty exposure and airport license revocation risks without zero-emission fleet transitions, accelerating procurement commitments.
- Corporate Mobility Programs:Enterprise travel managers negotiate volume contracts for employee electric vehicle access, consolidating margin pools through centralized billing structures.
- Fast-Charging Corridors:Dense highway networks in Germany, China, and the United States eliminate range anxiety barriers for intercity rental utilization.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Cathode active material processing clusters in China create procurement vulnerability for fleet operators without long-term offtake agreements.
- Residual Value Forecasting Uncertainty:Battery degradation algorithms lack standardization, compressing lender confidence and raising lease rate floors.
- Grid Interconnection Queues:Utility upgrade timelines for depot fast-charging installations extend 18-36 months in major metropolitan markets.
Strategic Opportunities
- Micromobility Integration:City-center electric scooter and bike pooling converges with full-size vehicle subscriptions, capturing last-mile corporate travel spend.
- MIIT New Energy Mandates:China's license renewal requirements for commercial operators create compliance-driven procurement floors with predictable replacement cycles.
- Battery-as-a-Service Models:Decoupling vehicle chassis from energy storage transfers degradation risk to third-party asset owners, improving rental unit turnover economics.
Industry Challenges
- Certified EV Technician Scarcity:High-voltage systems repair capability concentrates at OEM-authorized service centers, forcing rental operators into costly maintenance partnerships or captive training academy investments.
- Charging Protocol Fragmentation:CCS, NACS, and GB/T interface incompatibility forces multi-cable inventory and dwell-time inefficiencies at mixed-use charging depots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Car Rental Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact, SUV, Sedan, Luxury Rental Duration: Daily, Weekly, Monthly, Long-term Customer Type: Leisure, Corporate, Tourists, Locals Service Model: Traditional, Peer-to-Peer, Subscription, Corporate Fleets |
| Companies Covered | The Hertz Corporation, Avis Budget Group Inc., Enterprise Holdings Inc., Europcar Mobility Group, Sixt SE, Zoomcar Inc., Green Motion International, Zipcar, UFODrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Car Rental Market Emerging Trajectories
Operational models are splitting between asset-heavy fleet ownership and asset-light platform intermediation, with technology deployment racing ahead of standardization consensus across charging hardware and software stacks.
Battery chemistry is bifurcating between lithium-iron-phosphate cells for urban duty cycles and nickel-rich formulations for highway-range applications. Airport-based rental fleets prioritize the former for superior cycle life and thermal stability under high-frequency turnover. This chemistry split is compressing procurement standardization and forcing operators to segment maintenance protocols by vehicle deployment pattern.
The EU Green Deal's F-Gas Regulation mandates progressive CO2 reduction across commercial vehicle pools, directly accelerating combustion unit replacement timelines for European rental operators. Fleet managers must now synchronize procurement waves with regulatory phase-out schedules or face operating license restrictions. Germany's KBA enforces type-approval documentation that rental aggregators struggle to aggregate across multi-OEM portfolios.
Subscription service contracts displace traditional daily-rate structures as consumers seek fixed-cost electric access without ownership capital burdens. Corporate procurement teams consolidate vendor relationships through multi-year mobility-as-a-service agreements, displacing transactional rental counter economics. This contract compression is most visible in United States technology sector travel programs, where sustainability reporting requirements mandate emissions visibility per trip.
Electric Car Rental Market Segmentation
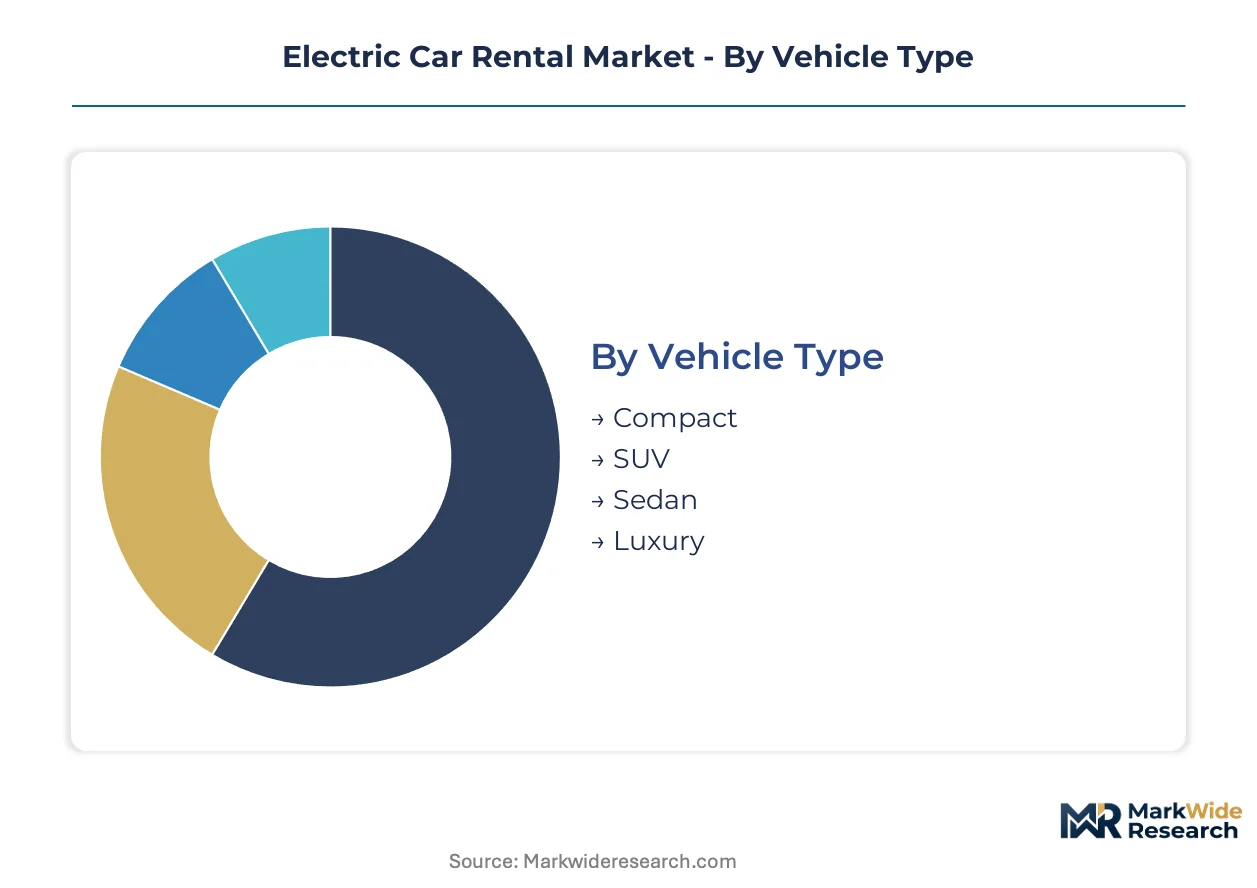
Segmentation in electric car rental determines fleet procurement priorities, pricing architecture, and depot placement strategy. Each dimension channels capital deployment toward distinct utilization patterns and margin structures.
Vehicle Type:
Airport counters and city-center hubs route different vehicle classes through divergent customer acquisition channels, with fleet mix directly constraining per-unit revenue realization.
- Compact:Lithium-iron-phosphate battery packs dominate this segment for superior thermal stability under high-frequency turnover. Demand concentrates in German urban hubs where EU Green Deal emission mandates accelerate municipal fleet replacement. This chemistry choice compresses maintenance protocol standardization across multi-OEM portfolios.
- Sedan:Mid-size four-door configurations balance range certification with trunk capacity for corporate airport transfers. Procurement volumes cluster in China under MIIT new energy vehicle mandates that establish compliance floors for commercial license renewals. Battery degradation algorithms here lack standardization, raising residual value uncertainty.
- SUV:Nickel-rich cathode formulations serve highway-range duty cycles with expanded cabin space.
- Luxury:Premium appointments and extended range specifications target corporate executive mobility programs.
By volume, Compact leads. By growth pace, Sedan is expanding most quickly.
Rental Duration:
Duration tiers segment working capital intensity, with longer commitments shifting depreciation risk profiles and lender collateral valuations.
- Monthly:Thirty-day structures capture remote workers and extended-stay corporate assignments seeking fixed-cost electric access without ownership burdens. Procurement concentrates in United States technology sector travel programs where EPA tailpipe standards and sustainability reporting requirements mandate emissions visibility per trip.
- Long-term:Multi-quarter agreements transfer battery degradation risk to rental operators while locking utilization rates. Demand clusters among European corporate fleet managers synchronizing procurement waves with F-Gas Regulation phase-out schedules to avoid operating license restrictions.
- Daily:Transactional counter economics serve sporadic leisure demand with highest per-mile rates.
- Weekly:Seven-day blocks target vacation travelers and project-based corporate travel.
Monthly contracts dominate revenue contribution. Long-term agreements are climbing the fastest as mobility-as-a-service procurement consolidates vendor relationships.
Customer Type:
Customer taxonomy determines channel economics, with corporate segments consolidating margin pools through centralized billing against fragmented leisure acquisition costs.
- Corporate:Enterprise travel managers negotiate volume contracts for employee electric vehicle access, consolidating margin pools through centralized billing structures. Procurement concentrates in Germany, China, and the United States where dense fast-charging corridors eliminate range anxiety barriers for intercity utilization.
- Leisure:Sporadic demand patterns require dynamic pricing algorithms to maintain utilization against seasonal fluctuation. This segment channels through airport concession dominance in North American gateways and city-center micromobility integration in European urban cores.
- Tourists:International visitors drive seasonal demand spikes at gateway airports.
- Locals:Resident users seek alternatives to ownership in congestion-charged metropolitan zones.
Corporate segments command premium rate floors. Leisure volume is gaining share fastest as post-ownership mobility preferences shift.
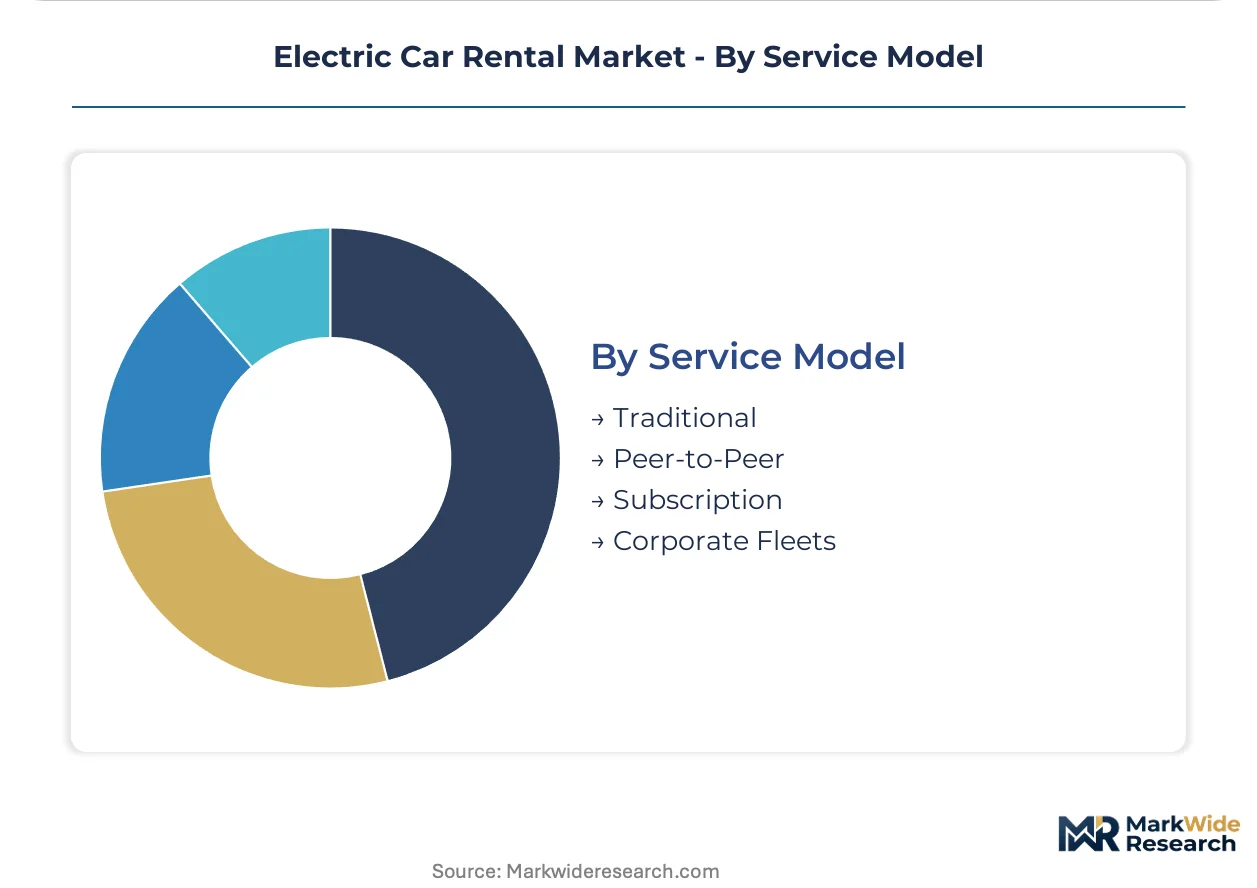
Service Model:
Model architecture splits between asset-heavy fleet ownership and asset-light platform intermediation, with technology deployment racing ahead of charging protocol standardization.
- Subscription:Fixed-cost electric access without long-term commitment captures consumers seeking predictable mobility budgeting. Demand concentrates in United States metropolitan markets where grid interconnection queues for depot fast-charging extend eighteen to thirty-six months, forcing operators toward battery-as-a-service models that transfer degradation risk to third-party asset owners.
- Corporate Fleets:Multi-year mobility-as-a-service agreements displace transactional rental counter economics through consolidated vendor relationships. Procurement clusters in European Union markets where EU Green Deal mandates progressive CO2 reduction across commercial vehicle pools, directly accelerating combustion unit replacement timelines.
- Traditional:Counter-based daily rental maintains airport concession economics with high customer acquisition costs.
- Peer-to-Peer:Platform intermediation matches private EV owners with short-term renters, reducing fleet capital intensity.
Corporate Fleets anchor revenue stability. Subscription models are on the steepest expansion trajectory as fixed-cost mobility preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe standards and NHTSA fuel economy frameworks in the United States compel rental fleets to electrify to avoid penalty exposure and maintain airport operating licenses. The EU Green Deal and F-Gas Regulation in Europe mandate progressive CO2 reduction across commercial vehicle pools. China's MIIT new energy vehicle mandates and GB charging standards create compliance-driven procurement floors for operators.
United States
Corporate travel managers in the United States technology sector negotiate volume contracts for employee electric vehicle access under sustainability reporting requirements. EPA tailpipe standards and NHTSA frameworks accelerate zero-emission fleet transitions to avoid penalty exposure. Dense fast-charging corridors along interstate highways in California, Texas, and the Northeast Corridor eliminate range anxiety barriers for intercity rental utilization.
Germany
German urban hubs concentrate demand for compact electric rentals where EU Green Deal emission mandates accelerate municipal fleet replacement. The KBA enforces type-approval documentation that rental aggregators struggle to aggregate across multi-OEM portfolios. Battery swapping infrastructure pilots in Berlin and Munich are unlocking operational viability for high-frequency urban rental turnover.
China
MIIT new energy vehicle mandates establish compliance floors for commercial license renewals, driving procurement volumes for mid-size sedan configurations. GB charging standards create technical uniformity that supports battery-as-a-service model adoption. Shenzhen and Shanghai lead fleet electrification with integrated swapping stations and municipal procurement preferences for rental operators.
France
Corporate mobility programs in Paris and Lyon consolidate vendor relationships through multi-year mobility-as-a-service agreements. The EU Green Deal's F-Gas Regulation mandates progressive CO2 reduction across commercial vehicle pools, accelerating combustion unit replacement timelines. Île-de-France regional authorities coordinate charging depot placement with rental operator expansion plans to avoid grid interconnection bottlenecks.
United Kingdom
London congestion charging and ultra-low emission zone enforcement drive resident demand for electric alternatives to private ownership. Corporate fleet managers synchronize procurement waves with regulatory phase-out schedules to avoid operating license restrictions. The Southeast corridor anchors intercity rental utilization with dense rapid-charging networks along major motorway routes.
Electric Car Rental Market Vendor Landscape
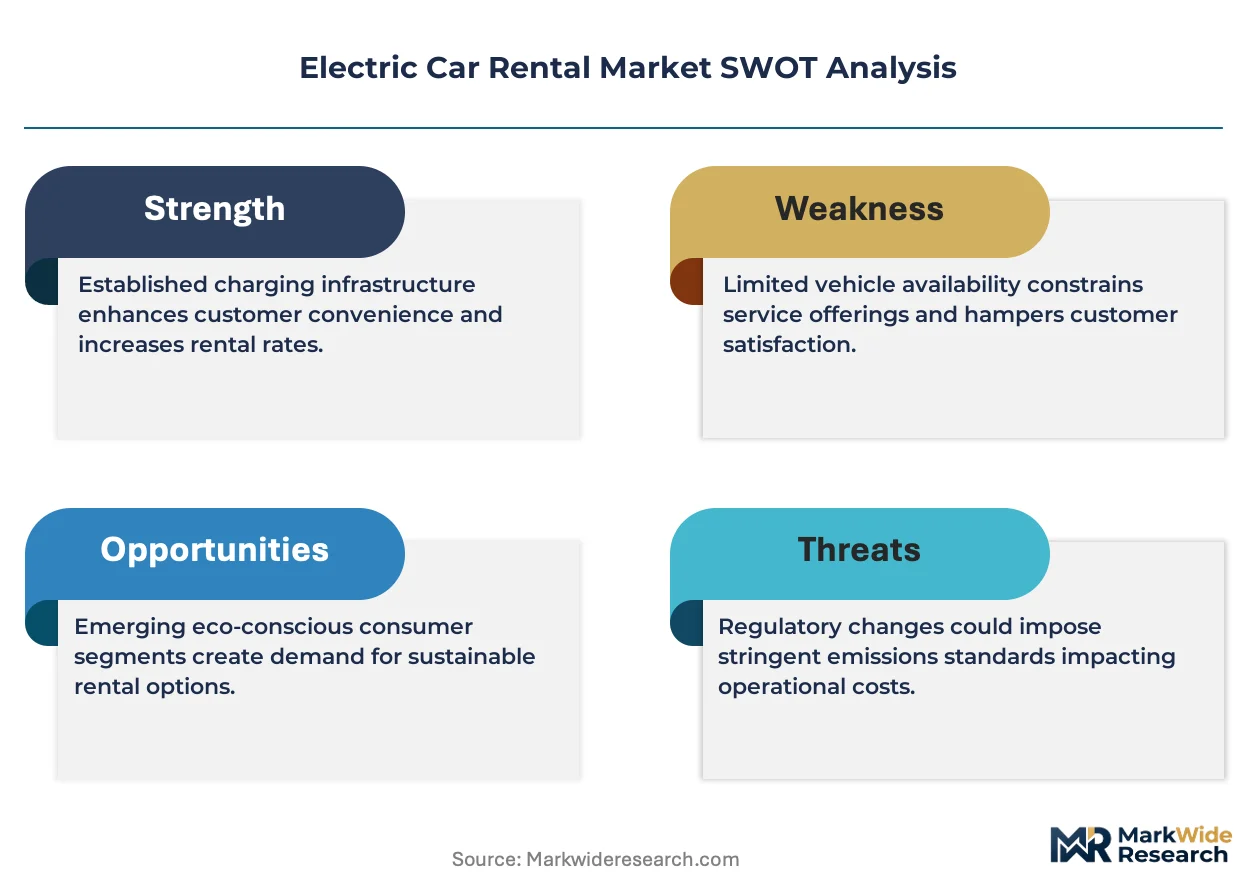
A small set of integrated leaders sits above a broader specialist tier in the electric car rental market. Fleet-scale operators with direct OEM relationships secure priority vehicle allocations during supply constraints, while platform intermediaries reduce capital intensity through peer-to-peer matching. Strategic archetypes include asset-heavy airport concession holders, asset-light subscription platforms, and integrated mobility-as-a-service providers. Competitive moves concentrate on securing charging infrastructure partnerships and building captive technician training capabilities.
Within the integrated fleet tier, The Hertz Corporation and Avis Budget Group Inc. represent asset-heavy operators with established airport concession dominance, while Europcar Mobility Group exemplifies the European mobility integrator combining full-size electric offerings with city-center micromobility services. These entities occupy positions shaped by their geographic footprints and service model architectures rather than differentiated technology ownership.
| Leading Market Players |
|---|
| The Hertz Corporation |
| Avis Budget Group Inc. |
| Enterprise Holdings Inc. |
| Europcar Mobility Group |
| Sixt SE |
| Zoomcar Inc. |
| Green Motion International |
| Zipcar |
| UFODrive |
| Others |
Supply Flow & Price Mechanics
Lithium-iron-phosphate chemistry substitution for nickel-rich formulations simultaneously shifts procurement geography toward Chinese cathode processing clusters and compresses per-kilowatt-hour pricing floors for compact fleet segments. This substitution dynamic redirects supplier relationships from South Korean and Japanese battery makers toward domestic Chinese cell manufacturers, altering maintenance protocol standardization and residual value forecasting methodologies across rental operator portfolios.
Pricing Analysis
Geographic price spreads between German urban hubs and North American airport gateways exceed thirty percent for equivalent compact vehicle classes, driven by divergent EU Green Deal compliance cost allocations and EPA penalty exposure structures. Three-tier pricing structure across premium, standard, and economy levels dominates subscription service contracts, with differentiation anchored in range certification tiers and bundled charging access rather than vehicle appointments alone. Cost compression in economy-tier daily rentals is intensifying because fleet operators absorb residual value uncertainty from non-standardized battery degradation algorithms. Corporate mobility programs demonstrate lowest price sensitivity due to sustainability reporting mandates, while leisure tourists at gateway airports exhibit highest elasticity to per-mile rate fluctuations.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and trans-Pacific container availability constraints inflate landed battery pack costs for European and North American rental operators by fifteen to twenty percent during peak procurement windows. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material processing drawing from Indonesian nickel and Chilean lithium concentrate feedstocks. Supply chain risk centers on single-source vulnerability for high-voltage power electronics and thermal management components sourced from Tier 1 automotive suppliers in Germany and Japan. Distribution runs through OEM-direct fleet allocation agreements for integrated operators, while asset-light platforms rely on peer-to-peer owner matching that bypasses traditional wholesale vehicle procurement channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric car rental market fragmentation creates multiple viable positioning niches as corporate procurement teams disaggregate mobility-as-a-service contracts from traditional fleet ownership structures. Subscription service demand and micromobility integration generate specialized entry points beyond incumbent airport concession dominance.
For Market Incumbents: Compound fleet density advantages through captive technician training academies that reduce dependency on OEM-authorized service center partnerships and accelerate vehicle turnaround times. Secure long-term offtake agreements with Chinese cell manufacturers to mitigate lithium-ion supply concentration risk during procurement crunches. Vertical integration into battery-as-a-service models transfers degradation risk exposure while locking recurring revenue streams from corporate accounts. For New Entrants and Emerging Players: CE marking fast-track for vehicle type-approval documentation enables rapid European market entry before KBA enforcement complexity blocks aggregator business models. Target United States technology sector travel programs where sustainability reporting requirements mandate emissions visibility per trip and incumbent relationships remain unconsolidated. Deploy peer-to-peer platform architecture to minimize fleet capital intensity while capturing leisure demand at city-center locations outside airport concession zones. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light platform intermediaries with proven charging infrastructure partnerships over capital-intensive fleet ownership models. Long-term viability across the analysis window rests on battery swapping protocol adoption velocity and standardized residual value algorithm development. Acquisition target archetype: regional specialists with integrated micromobility offerings and established municipal procurement relationships. Signal to watch: MIIT mandate enforcement intensity in China as proxy for global compliance-driven procurement floor expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Partnership | Transfers degradation risk to third-party asset owners while improving rental unit turnover economics for operators. |
| Certified Technician Academy Buildout | Addresses EV technician scarcity that concentrates repair capability at OEM-authorized service centers. |
| Micromobility Integration Launch | Captures last-mile corporate travel spend through city-center scooter and bike pooling convergence. |
| Fast-Charging Depot Expansion | Eliminates range anxiety barriers for intercity utilization along dense highway corridors in Germany and the United States. |
| Corporate Mobility-as-a-Service Contract | Consolidates vendor relationships through multi-year agreements displacing transactional rental counter economics. |
Methodological Framework
The analysis maps subscription service providers, airport concession operators, peer-to-peer platforms, and integrated mobility-as-a-service vendors, each validated through fleet procurement directors, charging infrastructure developers, corporate travel managers, and regulatory compliance officers. Primary interviews with OEM fleet sales executives, rental operator maintenance heads, and municipal transportation planners combined with secondary validation from EPA regulatory filings, EU Green Deal implementation documents, MIIT new energy vehicle mandate disclosures, and IHS Markit vehicle registration databases. Bottom-up fleet size estimates and top-down market size triangulation cross-check volume assumptions against charging infrastructure deployment rates and corporate contract disclosure patterns.
Consistency checks against external benchmarks validated volume and value outputs against disclosed fleet procurement commitments, charging station utilization data, and regulatory compliance timeline announcements. Segmentation modeling incorporated vehicle class, rental duration tier, customer type taxonomy, and service model architecture dimensions throughout the projection horizon. CAGRs derived from fleet expansion rates synchronized with infrastructure buildout velocity, battery cost curve trajectories, and regulatory phase-out schedule enforcement intensity. Industry-specific forecast inputs included residual value algorithm standardization progress and certified technician training pipeline expansion rates.
Decision-makers should treat outputs as directional under assumptions of sustained EPA tailpipe standard enforcement, EU Green Deal F-Gas Regulation adherence, and MIIT mandate compliance floor maintenance; material deviation in regulatory intensity or charging infrastructure deployment velocity would warrant model refresh. Forecasts reflect base-case assumptions regarding lithium-ion cell supply availability and grid interconnection queue resolution timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market