
 EV Condenser Market | 2026-2036
EV Condenser Market Size, Share, and Industry Trends Forecast 2026-2036
EV Condenser Market Insights
A shift from single-source to multi-source procurement is recalibrating supplier relationships across the EV condenser value chain. Denso Corporation leverages its captive semiconductor and thermal component ecosystem to maintain design-to-delivery continuity. Hanon Systems anchors its position through dedicated EV-focused manufacturing footprints in multiple geographies. Valeo SA differentiates via integrated heat pump and condenser module architectures that reduce assembly complexity for OEM customers.
An EV condenser is a heat exchanger component that liquefies high-pressure refrigerant vapor discharged from the compressor, typically constructed from aluminum microchannel tubes with fin-and-tube or parallel-flow configurations and operating at pressures up to 45 bar in R-134a or R-1234yf systems. Its primary function is to reject thermal energy from the passenger cabin and, in integrated designs, from the battery pack and power electronics to maintain optimal operating temperatures. Scroll compressors paired with water-cooled condensers are capturing the fastest growth trajectory as 800V architectures demand higher heat rejection density per unit volume. The OEM end-user channel dominates absolute volume while aftermarket providers are building specialized inventory positions for the emerging electric bus and commercial vehicle installed base.
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing reformulation of working fluids and compatible condenser materials in the United States. EMA's MDR framework and REACH substance restrictions in Europe are elevating documentation and material traceability requirements for thermal system suppliers. China's GB standards and MIIT new energy vehicle certification protocols mandate thermal runaway propagation resistance, which integrates condenser performance into battery safety validation. Stakeholders must monitor refrigerant transition timelines and voltage platform migrations to align capacity investments with the next generation of thermal architecture specifications.
Market Dynamics
800V electrical architectures are compressing thermal management design cycles and forcing condenser suppliers to requalify materials for higher pressure operation and dielectric compatibility with next-generation refrigerants.
Growth Catalysts
- China's dual carbon goals:NEV mandates and MIIT certification protocols are accelerating domestic production capacity expansion and creating captive demand for localized thermal component supply.
- R-1234yf refrigerant transition:The EPA's phasedown of hydrofluorocarbons under the AIM Act is retrofitting vehicle platforms and opening replacement cycles for compatible condenser designs.
- Integrated heat pump architectures:Battery thermal management convergence with cabin conditioning is expanding condenser duty cycles and functional specifications across passenger EV segments.
Market Restraints
- Aluminum alloy supply concentration:Microchannel tube fabrication depends on specialized extrusion capacity concentrated in East Asian manufacturing clusters, exposing procurement to logistics volatility.
- REACH substance documentation:ECHA's expanded traceability requirements for thermal system materials are extending qualification timelines and elevating compliance overhead for European-bound production.
- Scroll compressor cost structure:Water-cooled condenser pairing with high-efficiency compressors carries 15-25% premium over traditional air-cooled configurations, constraining adoption in cost-sensitive vehicle classes.
Strategic Opportunities
- Electric bus aftermarket:Municipal fleet operators in Germany and the United States are building dedicated service networks for thermal system maintenance, creating inventory positions for high-duty condenser replacements.
- Battery safety integration:China's GB standards mandating thermal runaway propagation resistance are embedding condenser performance into OEM platform validation, deepening supplier-OEM co-development relationships.
- Multi-source procurement models:Tier-1 thermal module suppliers are diversifying condenser sourcing across three-plus qualified vendors, opening volume allocation for secondary manufacturers with proven 800V qualification.
Industry Challenges
- High-voltage qualification talent scarcity:Electrification of thermal systems requires engineers conversant in both refrigerant thermodynamics and electrical isolation protocols, a skill intersection currently underrepresented in automotive hiring pools.
- Refrigerant-material compatibility validation:Each new working fluid chemistry demands exhaustive corrosion and permeation testing against aluminum microchannel alloys, compressing development calendars without parallel test infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Condenser Market |
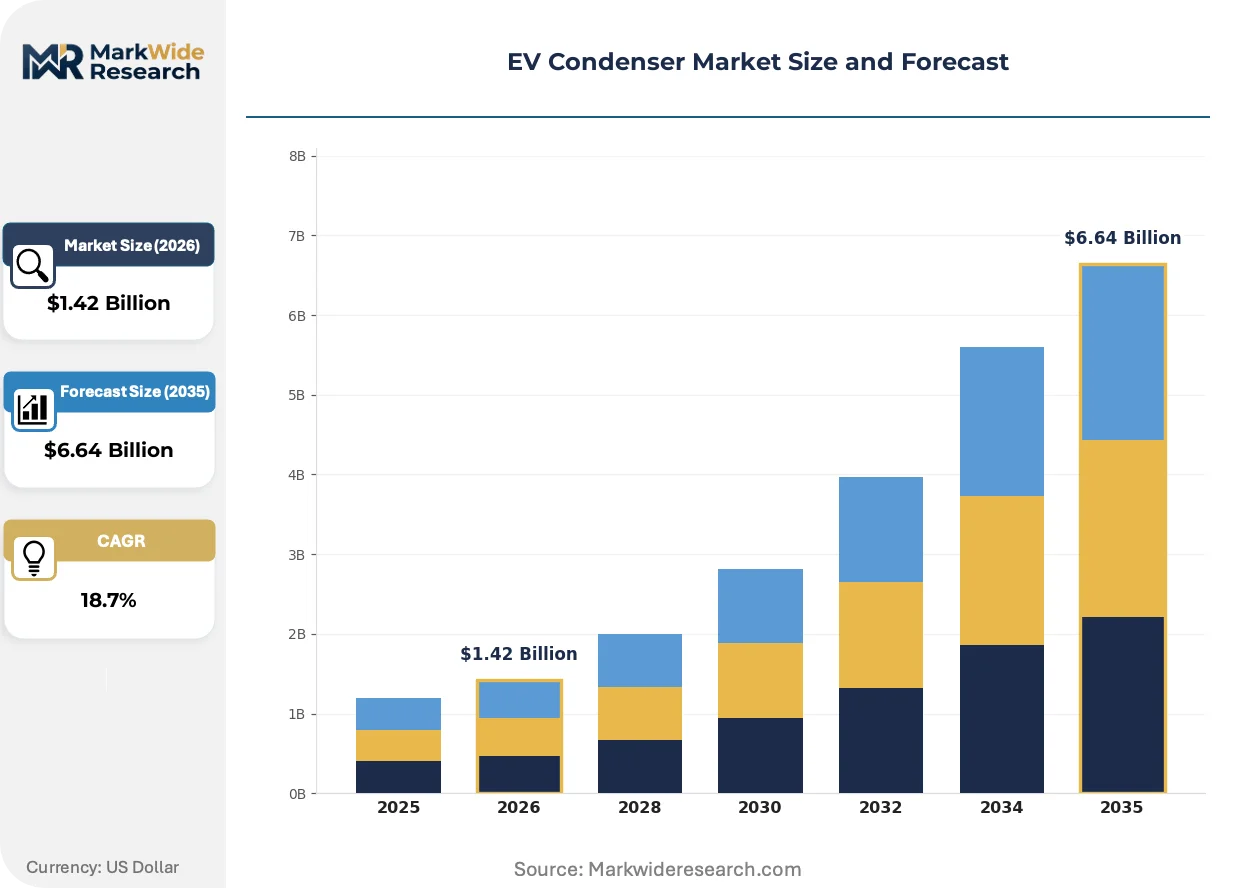
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston, Scroll, Rotary, Cryogenic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: Air-Cooled, Water-Cooled, Hybrid, Active End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops |
| Companies Covered | Denso Corporation, Hanon Systems, Valeo SA, MAHLE GmbH, Sanden Holdings Corporation, Modine Manufacturing Company, Keihin Corporation, Calsonic Kansei Corporation, Subros Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Condenser Market Trends and Innovations
Refrigerant chemistry transitions and voltage platform migrations are forcing simultaneous material and architectural reinvention across the condenser value chain, collapsing traditional sequential development timelines into parallel qualification sprints.
Parallel-flow aluminum microchannel condensers are absorbing the thermal load from combined cabin and battery cooling circuits in 800V architectures. Premium passenger EV platforms are specifying these designs as standard equipment. The technology is absorbing engineering resources previously allocated to discrete component optimization, consolidating supplier value capture at the module level.
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compelling working fluid reformulation across United States-bound vehicle programs. Condenser suppliers must revalidate aluminum alloy compatibility with lower-GWP alternatives and pressure-test revised sealing geometries. Light-duty truck and SUV segments face the steepest retooling burden given their higher refrigerant charge volumes and extended model cycles.
Fleet procurement departments are consolidating thermal system purchasing under platform-level contracts rather than component-level agreements. Tier-1 module suppliers capture condenser volume through integrated heat pump offerings, squeezing standalone component vendors into secondary sourcing roles. This concentration is most pronounced in China's NEV manufacturing clusters, where domestic OEMs favor single-source thermal module responsibility.
EV Condenser Market Segmentation
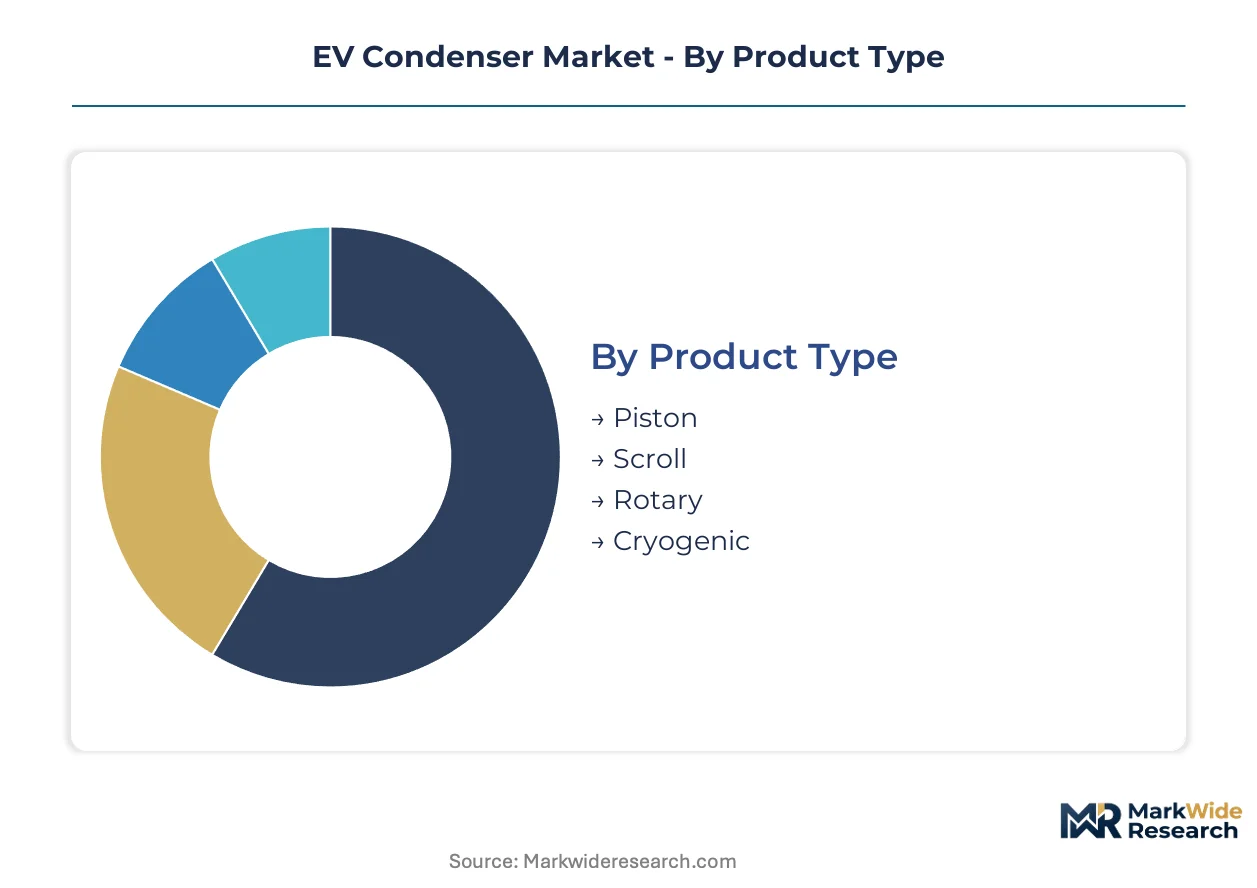
Segmentation in the EV condenser market reflects divergent thermal load requirements across voltage platforms and vehicle duty cycles. Compressor technology and cooling architecture choices directly determine condenser pressure ratings, material specifications, and supplier qualification pathways.
Product Type:
Volume production concentrates on established compressor architectures, while premium positioning attaches to systems qualified for 800V operation and integrated heat pump duty.
- Piston:Reciprocating compression technology dominates legacy 400V platforms and entry-level passenger EV segments. Cost-sensitive OEMs in China specify piston compressors for compact battery electric vehicles where thermal loads remain moderate and refrigerant charge volumes are constrained.
- Scroll:Orbiting scroll mechanisms deliver higher isentropic efficiency and quieter operation, making them the specification of choice for premium passenger EVs and 800V architectures. Water-cooled condenser pairing with scroll compressors commands procurement priority from German and US-based OEMs building extended-range electric platforms.
- Rotary:Vane-based compression suits small-displacement systems in two-wheeler and compact urban vehicle applications. Japanese OEMs favor rotary configurations for kei-car derivatives and ASEAN-market electric micro-vehicles.
- Cryogenic:Ultra-low temperature refrigeration cycles serve specialized battery thermal management in extreme climate operating envelopes. Arctic-region commercial fleet trials and aerospace-adjacent prototyping programs in Canada represent the current addressable base.
Mature deployment sits with Piston compressors across mass-market 400V platforms. Newer deployment is concentrated in Scroll configurations as 800V architectures expand the addressable premium segment.
Application:
Passenger vehicle electrification is absorbing the majority of condenser engineering resources, while commercial and municipal fleet segments present aftermarket and retrofit opportunities with distinct qualification timelines.
- Passenger Vehicles:Battery electric sedans, crossovers, and SUVs generate the absolute volume demand for aluminum microchannel condensers. China's NEV mandate compliance and MIIT certification protocols are compressing development cycles for domestic OEMs building annual production runs exceeding six-figure volumes.
- Commercial Vehicles:Light-duty electric vans and medium-duty delivery trucks require condensers rated for extended duty cycles and higher refrigerant charge volumes. German last-mile logistics operators and US regional freight carriers are specifying thermal systems with predictive maintenance telemetry integration.
- Two-Wheelers:Electric scooters and motorcycles deploy compact condenser assemblies with minimal refrigerant inventory. Indian and Southeast Asian markets drive volume, though thermal management sophistication lags four-wheeled applications by a full platform generation.
- Buses:Electric transit and coach applications impose the highest thermal loads per vehicle, with condensers sized for simultaneous cabin cooling and battery conditioning across stop-start duty profiles. Municipal procurement in Germany and fleet electrification mandates in California are building dedicated aftermarket service networks for high-duty replacements.
Engineering investment clusters on Passenger Vehicles where platform consolidation permits module-level supplier integration. Margin expansion is concentrated in Buses where thermal system lifecycle contracts extend beyond initial vehicle procurement.
Technology:
Cooling medium selection determines condenser packaging density, refrigerant compatibility requirements, and the degree of integration with battery thermal management circuits.
- Air-Cooled:Fin-and-tube aluminum constructions reject heat directly to ambient air, remaining the default for compact vehicles with limited front-end packaging space. Cost-sensitive Chinese OEMs specify air-cooled condensers for urban runabout segments where thermal loads are predictable and auxiliary cooling demand is minimal.
- Water-Cooled:Refrigerant-to-coolant heat exchangers enable higher heat rejection density per unit volume and seamless integration with battery cooling loops. Premium European and North American OEMs are standardizing water-cooled condensers across 800V platforms where combined cabin and battery thermal management is mandatory.
- Hybrid:Dual-mode systems switch between air and water cooling based on thermal load and ambient conditions. Transitional architectures in mid-market EV platforms bridge 400V legacy and 800V target specifications without full platform redesign.
- Active:Electronically controlled variable-flow condensers with embedded sensors and predictive thermal algorithms. Early deployment in luxury EV flagships and commercial fleet pilots where energy efficiency certification drives procurement scoring.
Production scale favors Air-Cooled configurations where tooling amortization is complete across multiple vehicle generations. Technology migration is accelerating toward Water-Cooled systems as 800V platform share expands.
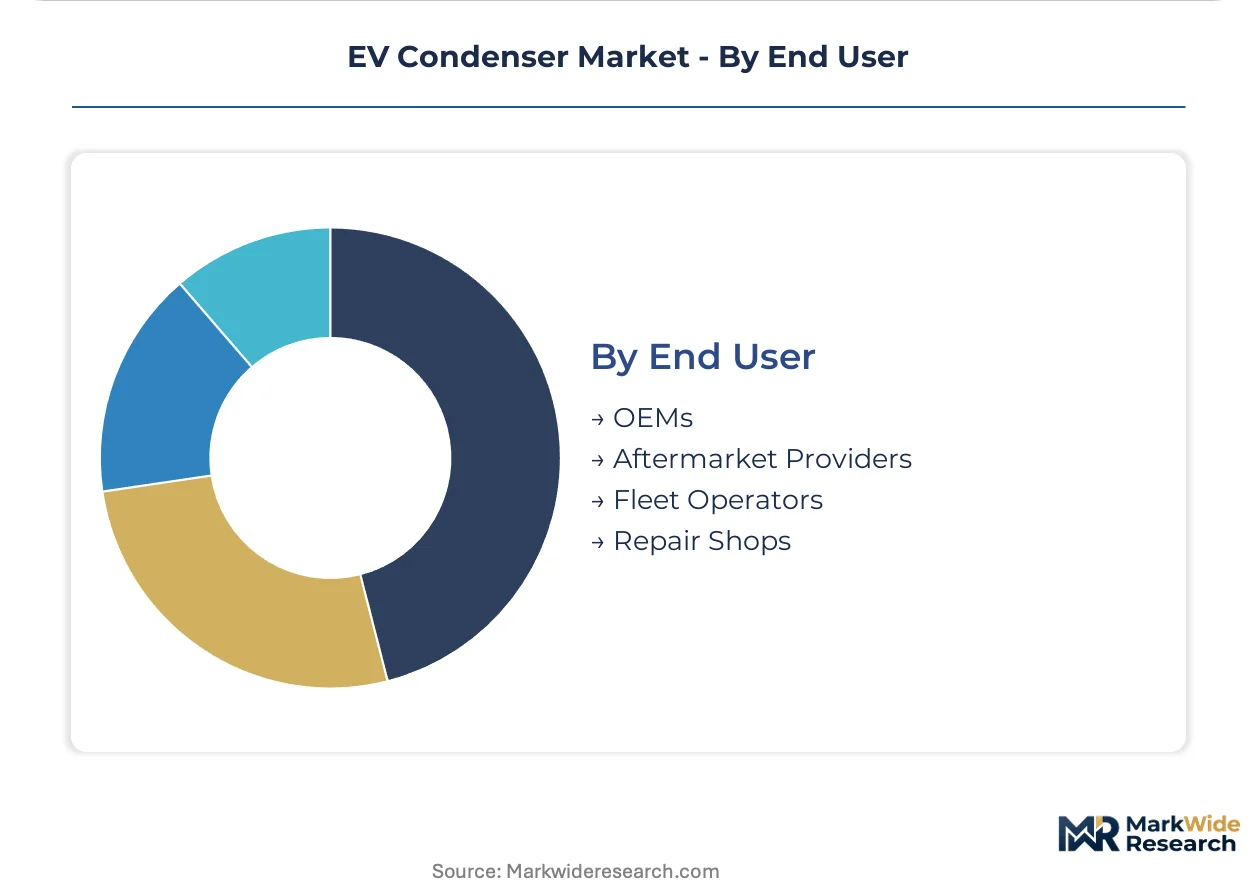
End User:
Procurement authority is consolidating at the module level, compressing standalone component vendors into secondary sourcing roles while elevating integrated thermal system suppliers.
- OEMs:Vehicle manufacturers specify condensers through platform-level thermal module contracts rather than discrete component procurement. China's NEV manufacturing clusters favor single-source thermal module responsibility, with domestic OEMs awarding consolidated heat pump and condenser programs to qualified Tier-1 suppliers.
- Aftermarket Providers:Independent distributors and service chains are building inventory positions for the emerging electric bus and commercial vehicle installed base. German municipal fleet operators and US school bus electrification programs are creating dedicated procurement channels for high-duty condenser replacements.
- Fleet Operators:Large-scale commercial and transit fleet owners are negotiating lifecycle thermal system contracts spanning initial specification through mid-life refurbishment. Total cost of ownership modeling is elevating condenser durability and serviceability in procurement scoring.
- Repair Shops:Independent service facilities require access to qualified replacement condensers with refrigerant compatibility documentation for EPA AIM Act compliance. US-based repair networks face the steepest retraining burden as R-1234yf transition accelerates retrofit demand.
Contract value concentrates with OEMs where platform-scale procurement drives supplier qualification investment. Channel development priority is shifting toward Fleet Operators as electrified commercial vehicle populations reach service-intensive maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum microchannel tube extrusion capacity clusters in East Asian manufacturing hubs, concentrating procurement leverage for condenser fabricators. This feedstock geography shapes regional competitive positioning across the EV thermal management value chain.
China
Domestic NEV production exceeding six-figure annual volumes for multiple OEMs compresses thermal component development cycles. MIIT certification protocols mandate thermal runaway propagation resistance, embedding condenser performance into battery safety validation. Yangtze River Delta manufacturing clusters host captive supply relationships between Tier-1 thermal module suppliers and condenser specialists.
Germany
Premium passenger EV platforms from Stuttgart and Munich OEMs specify scroll compressors paired with water-cooled condensers as standard equipment. ECHA's expanded REACH substance documentation requirements extend qualification timelines for European-bound production. Bavarian and Baden-Württemberg automotive clusters concentrate engineering talent for 800V thermal architecture development.
United States
Light-duty truck and SUV electrification programs face steep retooling burdens under EPA's AIM Act hydrofluorocarbon phasedown. Michigan and Ohio manufacturing corridors anchor domestic EV assembly capacity, pulling thermal system procurement decisions toward localized supply. Fleet electrification mandates in California are building dedicated aftermarket service networks for high-duty condenser replacements.
Japan
Kei-car derivatives and ASEAN-market electric micro-vehicles sustain demand for compact rotary compressor configurations. METI industrial policy supports thermal management component exports to Southeast Asian EV assembly operations. Kanto and Kansai industrial zones retain specialized aluminum alloy processing capabilities for microchannel tube fabrication.
South Korea
Battery electric platform consolidation among Seoul-based OEMs drives module-level thermal system procurement contracts. MFDS chemical substance regulations and KSA safety standards shape export-oriented production specifications. Busan-Ulsan manufacturing corridors concentrate condenser assembly capacity serving both domestic and export vehicle programs.
EV Condenser Market Competitive Landscape
Global majors compete with regional champions across qualification timelines and voltage platform coverage, producing a tiered supplier structure. The vendor base organizes around three strategic archetypes: integrated thermal module suppliers capturing OEM platform contracts, standalone condenser specialists serving aftermarket channels, and captive automotive component divisions leveraging parent-company vehicle programs. Dominant competitive moves include geographic manufacturing footprint expansion to satisfy local content requirements and multi-source procurement qualification to secure volume allocation from consolidating Tier-1 thermal system suppliers.
Within the integrated module supplier tier, Denso Corporation and Hanon Systems exemplify archetypes combining captive component ecosystems with dedicated EV-focused manufacturing footprints across multiple geographies. Valeo SA occupies a position representing European-headquartered suppliers differentiating through integrated heat pump and condenser module architectures. These three anchors demonstrate how supplier-OEM co-development relationships deepen as 800V platform specifications embed condenser performance into battery safety validation protocols.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| Valeo SA |
| MAHLE GmbH |
| Sanden Holdings Corporation |
| Modine Manufacturing Company |
| Keihin Corporation |
| Calsonic Kansei Corporation |
| Subros Limited |
| Others |
Pricing and Supply Chain Analysis
Platform-scale OEM procurement from China's NEV manufacturing clusters anchors pricing power at the module level, compressing standalone condenser margins while elevating integrated heat pump suppliers. This buyer concentration forces secondary vendors to absorb qualification costs for 800V architectures without guaranteed volume allocation.
Pricing Analysis
Warranty and service-bundling separates premium thermal module contracts from unbundled component transactions. Three-tier pricing structure across premium, standard, and economy levels reflects 800V qualification status, refrigerant compatibility certification, and geographic service coverage. Pricing pressure stems from multi-source procurement models as Tier-1 suppliers qualify three-plus vendors per platform. Cost-sensitive Chinese OEMs exhibit highest price sensitivity, while German premium manufacturers prioritize performance specifications over unit economics.
Supply Chain Analysis
China's MIIT local-content requirements and domestic NEV mandates are reshaping sourcing patterns toward Yangtze River Delta manufacturing clusters. Aluminum microchannel tube extrusion concentrates in China, Japan, and South Korea, drawing from specialized alloy feedstock and precision extrusion die capabilities. Single-source vulnerability pervades high-pressure rating tube supply for 800V architectures. Distribution runs through captive Tier-1 thermal module supplier networks serving OEM platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aluminum microchannel extrusion capacity for 800V pressure ratings operates at binding constraints, propping pricing for qualified suppliers while extending lead times for secondary market entrants.
For Market Incumbents: Deepen co-development relationships with OEMs embedding condenser performance into battery safety validation under China's GB standards. Expand dedicated EV-focused manufacturing footprints in Germany and the United States to satisfy local-content requirements. Lock in multi-year alloy supply agreements before commodity volatility transmits through microchannel tube pricing. For New Entrants and Emerging Players: EPA's AIM Act hydrofluorocarbon phasedown in the United States opens a window for R-1234yf-compatible condenser designs in light-duty truck and SUV retrofit cycles. Target aftermarket channels for electric bus thermal system replacements in California and German municipal fleets. Pursue qualification as third-source vendor for Tier-1 thermal module suppliers diversifying beyond captive component divisions. For Investors and Strategic Acquirers: Distressed-cycle entries favor standalone condenser specialists with proven 800V qualification and established OEM relationships in South Korea or Japan. Long-term viability hinges on module-level integration capability rather than discrete component manufacturing. Watch for Tier-1 thermal supplier consolidation signals as platform-scale procurement concentrates contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Architecture Qualification | Denso and Hanon Systems capture premium platform contracts through early voltage platform certification. |
| Integrated Heat Pump Module Development | Valeo SA reduces OEM assembly complexity by consolidating condenser and heat pump architectures. |
| Multi-Source Procurement Qualification | Secondary manufacturers secure volume allocation from Tier-1 suppliers diversifying vendor bases. |
| Aftermarket Service Network Buildout | Independent distributors capture electric bus replacement demand in California fleet electrification programs. |
| Alloy Supply Agreement Structuring | Long-term aluminum microchannel tube contracts hedge against East Asian manufacturing cluster logistics volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier-1 thermal module procurement leads, aftermarket distributor operations heads, and aluminum alloy processing specialists validated demand assumptions. EPA AIM Act implementation timelines, MIIT certification protocols, and ECHA REACH documentation requirements supplied regulatory boundary conditions. Bottom-up vehicle production forecasts triangulated against top-down thermal system content-per-vehicle estimates.
Granularity-level modeling addressed compressor technology, cooling architecture, vehicle application, and voltage platform specifications across the projection horizon. Passenger EV, commercial vehicle, bus, and two-wheeler segments were modeled separately with distinct thermal load profiles and duty cycle assumptions. CAGRs derived from production volume trajectories and content-per-vehicle scaling for 400V-to-800V platform transitions. Refrigerant chemistry transition timelines and regional regulatory compliance costs informed price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for water-cooled condenser integration would alter the outlook if air-cooled designs retain share in cost-sensitive vehicle classes. Forecasts incorporate assumptions regarding alloy supply continuity, logistics cost normalization, and OEM platform consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market