
 United Arab Emirates Smart Grid Market | 2026-2036
United Arab Emirates Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Smart Grid Market Analytics
Multi-source procurement is repositioning how UAE utilities acquire smart grid infrastructure. Siemens AG leverages its automation portfolio to anchor large-scale substation modernization contracts across the northern emirates. ABB Ltd. competes through integrated SCADA and digital substation offerings tailored to desert climate conditions. Dubai Electricity and Water Authority sustains in-house engineering capabilities while selectively outsourcing communication layer deployment to specialized vendors.
A smart grid integrates digital communication, sensing, and control technologies into electrical power networks to enable bidirectional energy flow, real-time demand management, and automated fault detection with sub-second response thresholds. Its primary purpose centers on improving reliability, integrating renewable generation, and reducing operational losses across transmission and distribution systems. Smart meters within the product type segment dominate current deployment volumes as utilities prioritize consumption visibility and automated billing. Advanced Metering Infrastructure from the technology dimension attracts the fastest capital allocation due to its role as the foundational data layer for downstream analytics. Cloud-based deployment models are gaining share among commercial and industrial end users seeking scalable energy management without heavy on-premise infrastructure.
MOHAP oversees federal building energy codes that mandate smart monitoring systems in new commercial developments, directly expanding addressable demand for grid-connected building automation. DEWA's regulatory standards for distributed generation interconnection establish technical compliance thresholds that equipment vendors must satisfy for market access. The Emirates Authority for Standardization and Metrology enforces product certification requirements for electrical equipment deployed in outdoor environments. Stakeholders must track evolving interconnection rules for rooftop solar and battery storage as these distributed assets fundamentally alter load profiles and grid stability requirements.
Market Dynamics
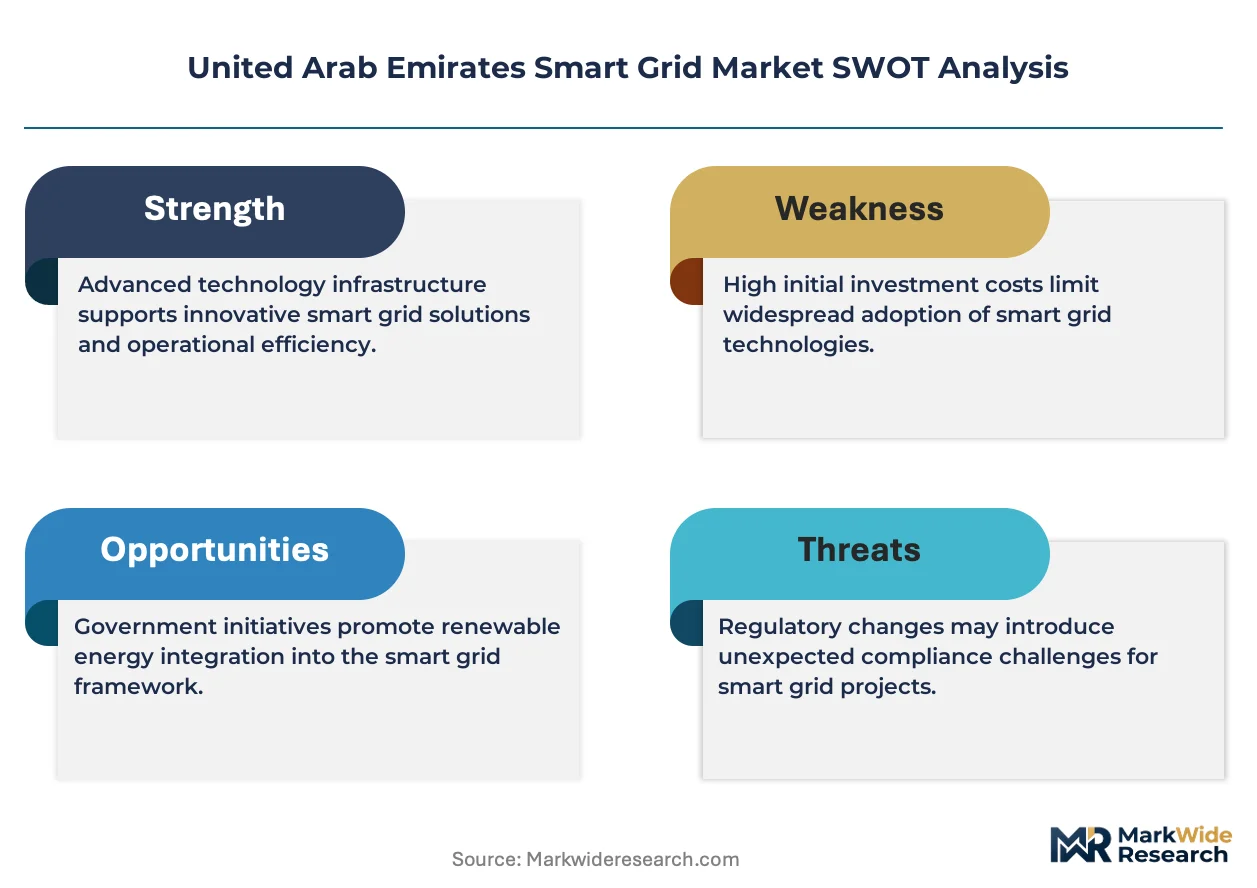
Federal mandates under the UAE Net Zero by 2050 strategy are compressing procurement cycles for grid infrastructure, forcing utilities to accelerate deployment timelines while maintaining interoperability with legacy SCADA systems.
Growth Catalysts
- UAE Net Zero by 2050 Strategy:Federal carbon neutrality targets mandate smart metering deployment across commercial buildings, creating guaranteed procurement pipelines for infrastructure vendors.
- Distributed Solar Interconnection:DEWA's technical standards for rooftop PV integration require bidirectional grid communication protocols, expanding demand for advanced inverter and energy storage interface technologies.
- Desert Climate Hardening:Extreme temperature operating requirements specified by ESMA certification rules favor specialized equipment designs, creating technical differentiation opportunities for compliant suppliers.
Market Restraints
- Copper and Rare Earth Input Volatility:Transformer core materials and power electronics components face price instability, compressing margins on fixed-price utility contracts.
- Vendor Concentration in Communication Modules:Narrow supplier bases for cellular LPWAN chipsets create single-source dependencies for AMI rollout schedules.
- Cybersecurity Compliance Burden:Federal Critical Infrastructure Protection standards impose certification delays and recurring audit costs on equipment procurement.
Strategic Opportunities
- Northern Emirates Grid Extension:Ras Al Khaimah and Fujairah distribution networks remain underpenetrated relative to Dubai and Abu Dhabi, offering first-mover positioning for integrated automation contracts.
- Building-to-Grid Integration:MOHAP energy code mandates for smart building systems create convergence demand between HVAC automation and grid-responsive load management.
- Cloud-Based Energy Management:Commercial and industrial users are bypassing traditional on-premise SCADA deployments in favor of subscription-based analytics platforms.
Industry Challenges
- SCADA-AMI Integration Complexity:Utilities struggle to synchronize legacy supervisory control architectures with new metering data streams without operational disruption.
- Specialized Field Technician Scarcity:Shortages of certified protection engineers and substation automation specialists delay commissioning schedules across emirate-level utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Smart Grid Market |
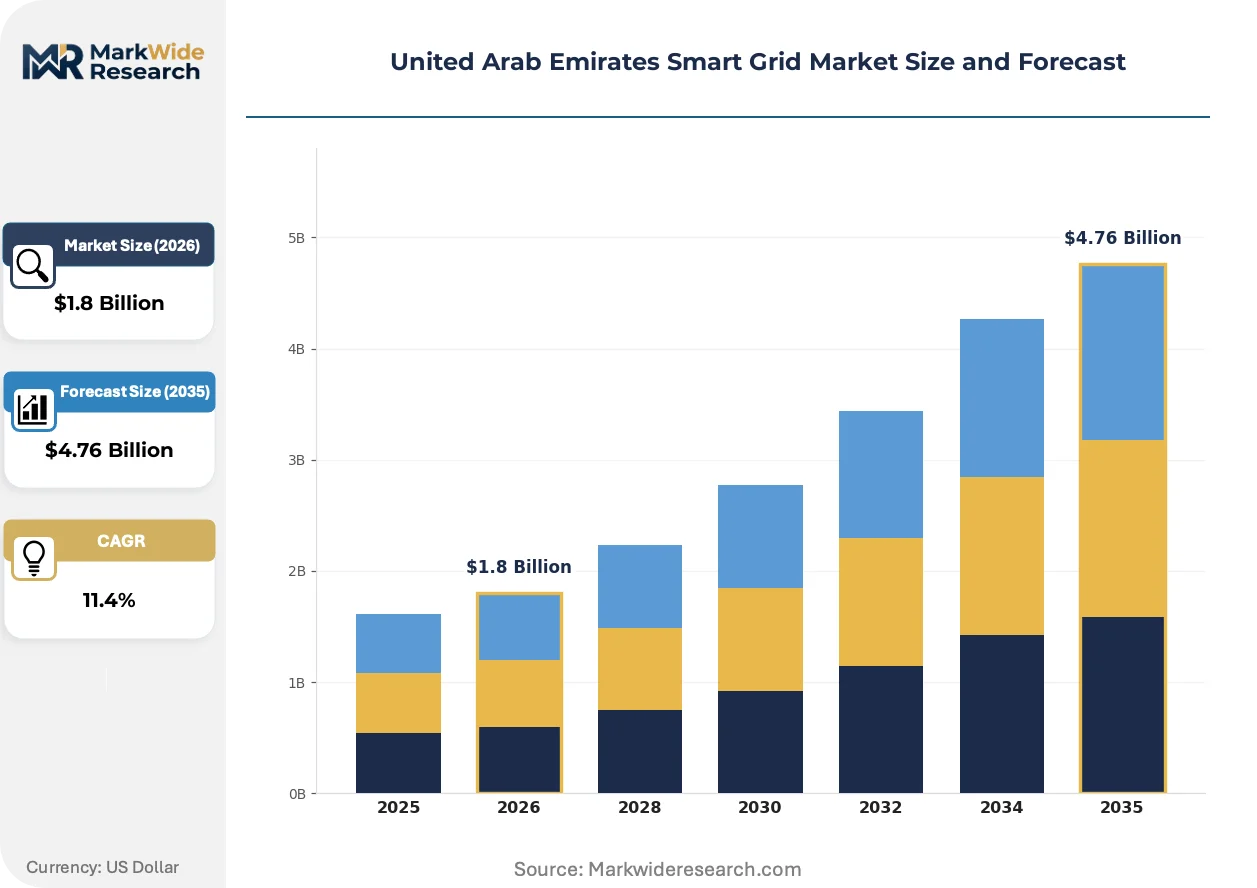
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Grid Automation, Communication Networks, Energy Management Systems Technology: Advanced Metering Infrastructure, Demand Response, Distributed Generation, SCADA Systems End User: Utilities, Commercial, Residential, Industrial Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | General Electric Company, ABB Ltd., Abu Dhabi Distribution Company, Siemens AG, Honeywell International Inc., Dubai Electricity and Water Authority, Schneider Electric SE, Korea Electric Power Corporation, Sharjah Electricity and Water Authority, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Smart Grid Market Evolving Landscape
Digital substation architectures are displacing conventional copper-wired protection systems, compressing equipment footprints while enabling remote diagnostics. Three developments are restructuring competitive positioning.
Digital substation platforms incorporating process bus communication and non-conventional instrument transformers are modularizing protection and control functions into software-defined modules. DEWA and ADNOC Distribution are piloting these architectures in greenfield substations, enabling faster upgrades without hardware replacement cycles. This modularity is compressing capital deployment timelines and reducing spare parts inventory burdens.
MOHAP building energy codes now mandate real-time monitoring interfaces for new commercial developments above specified floor areas. These regulations are forcing MEP contractors to specify grid-communicating building management systems as standard, expanding the addressable market for interoperable automation protocols. Dubai's construction pipeline is the primary demand concentration responding to this compliance pressure.
Performance-based service agreements are displacing traditional equipment procurement with capital expenditure commitments. Industrial offtakers in Jebel Ali and Khalifa Industrial Zone are contracting energy savings guarantees rather than purchasing hardware directly. Abu Dhabi's manufacturing sector shows the fastest uptake of this risk-transfer model.
United Arab Emirates Smart Grid Market Segmentation
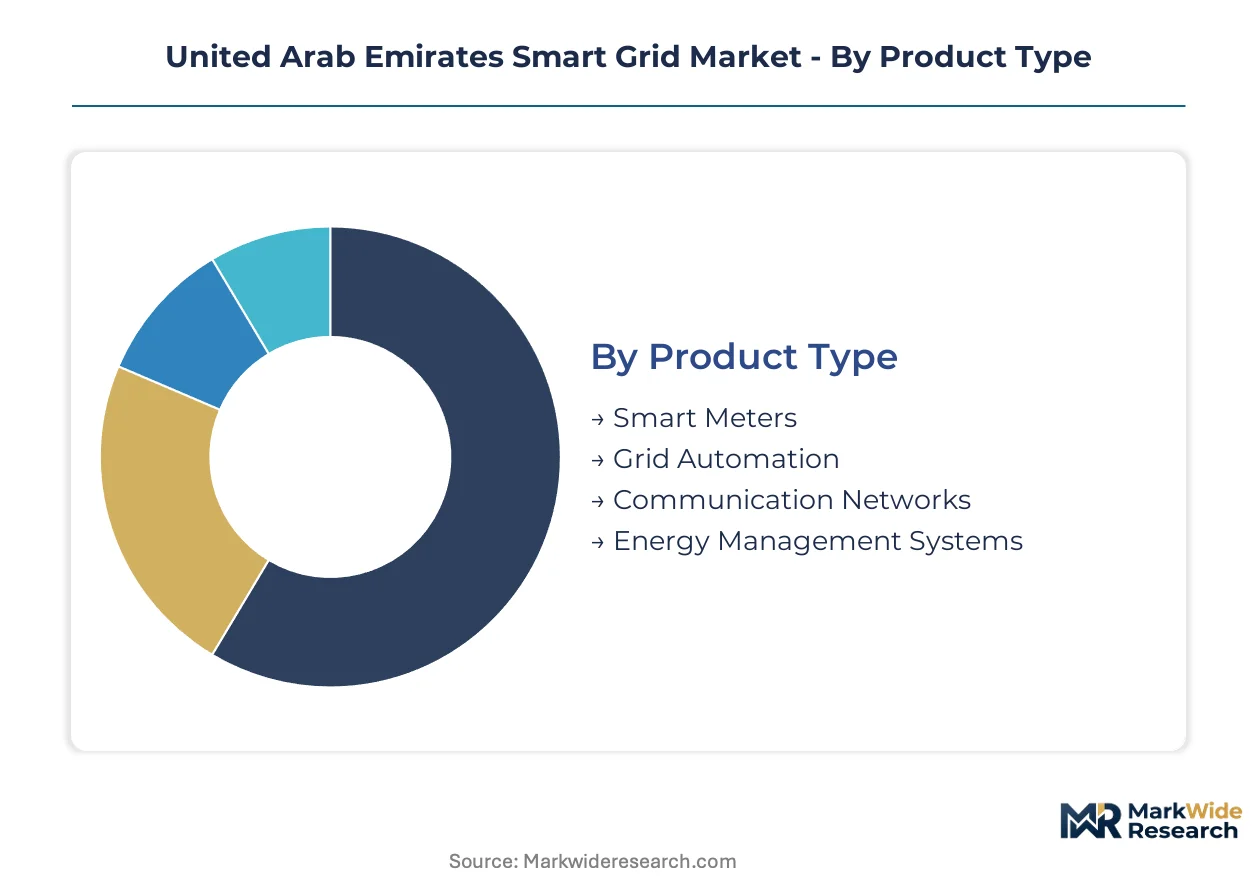
Segmentation reveals how procurement priorities diverge across the UAE's emirate-level utilities and federal efficiency mandates. Each axis exposes distinct technical requirements, from desert-hardened hardware specifications to cloud-native software architectures demanded by commercial offtakers.
Product Type:
Technical specifications vary sharply between outdoor substation equipment and indoor building automation systems, with ESMA certification requirements filtering supplier eligibility.
- Smart Meters:Bidirectional communication endpoints with cellular or RF mesh connectivity form the data foundation for consumption visibility and automated billing reconciliation. DEWA's mass deployment across Dubai's residential and commercial premises anchors regional demand, with federal Net Zero mandates compressing procurement timelines for remaining emirates.
- Grid Automation:Digital substation platforms integrating non-conventional instrument transformers and process bus communication enable remote protection management and predictive maintenance workflows. ADNOC Distribution and northern emirate utilities are accelerating adoption as they modernize aging distribution infrastructure.
- Communication Networks:Field area networks and backhaul infrastructure bridge substation edge devices to central control centers.
- Energy Management Systems:Software platforms for demand optimization and distributed resource coordination serve commercial and industrial sites.
Mature deployment sits with Smart Meters. Newer deployment is concentrated in Grid Automation.
Technology:
Capital allocation patterns reflect foundational infrastructure buildout versus advanced application layers, with interoperability requirements constraining vendor selection.
- Advanced Metering Infrastructure:The integrated system of smart meters, communication networks, and meter data management platforms establishes the measurement layer for downstream analytics. Dubai and Abu Dhabi utilities have completed foundational AMI deployment, while Ras Al Khaimah and Fujairah distribution companies are tendering remaining coverage.
- SCADA Systems:Supervisory control platforms with real-time data acquisition and automated control logic remain the operational backbone for transmission and primary distribution networks. Legacy system replacement cycles and cybersecurity hardening requirements are driving upgrade demand across federal and emirate-level utilities.
- Demand Response:Load curtailment and price-responsive control systems for peak demand management.
- Distributed Generation:Interconnection and control technologies for rooftop solar and battery storage integration.
SCADA Systems retain the largest installed base. Advanced Metering Infrastructure is gaining share fastest in current procurement cycles.
End User:
Procurement authority and technical sophistication create four distinct customer segments with diverging contract structures and performance requirements.
- Utilities:Emirates-level transmission and distribution companies with centralized procurement authority and standardized technical specifications. DEWA and Abu Dhabi Distribution Company dominate capital deployment volumes, with federal efficiency mandates reshaping their technology roadmaps toward bidirectional grid operation.
- Commercial:Office, retail, and hospitality developments subject to MOHAP building energy codes mandating smart monitoring interfaces. Dubai's construction pipeline concentrates near-term demand as developers comply with real-time energy visibility requirements for new buildings above specified floor areas.
- Residential:Individual household consumers receiving smart meter deployment through utility programs.
- Industrial:Manufacturing and processing facilities in Jebel Ali and Khalifa Industrial Zone contracting energy performance guarantees.
Utilities command the largest contract values. Commercial is expanding most quickly on regulatory compliance pressure.
Deployment:
Infrastructure location and data sovereignty requirements shape procurement preferences across customer types, with hybrid architectures emerging as a compromise position.
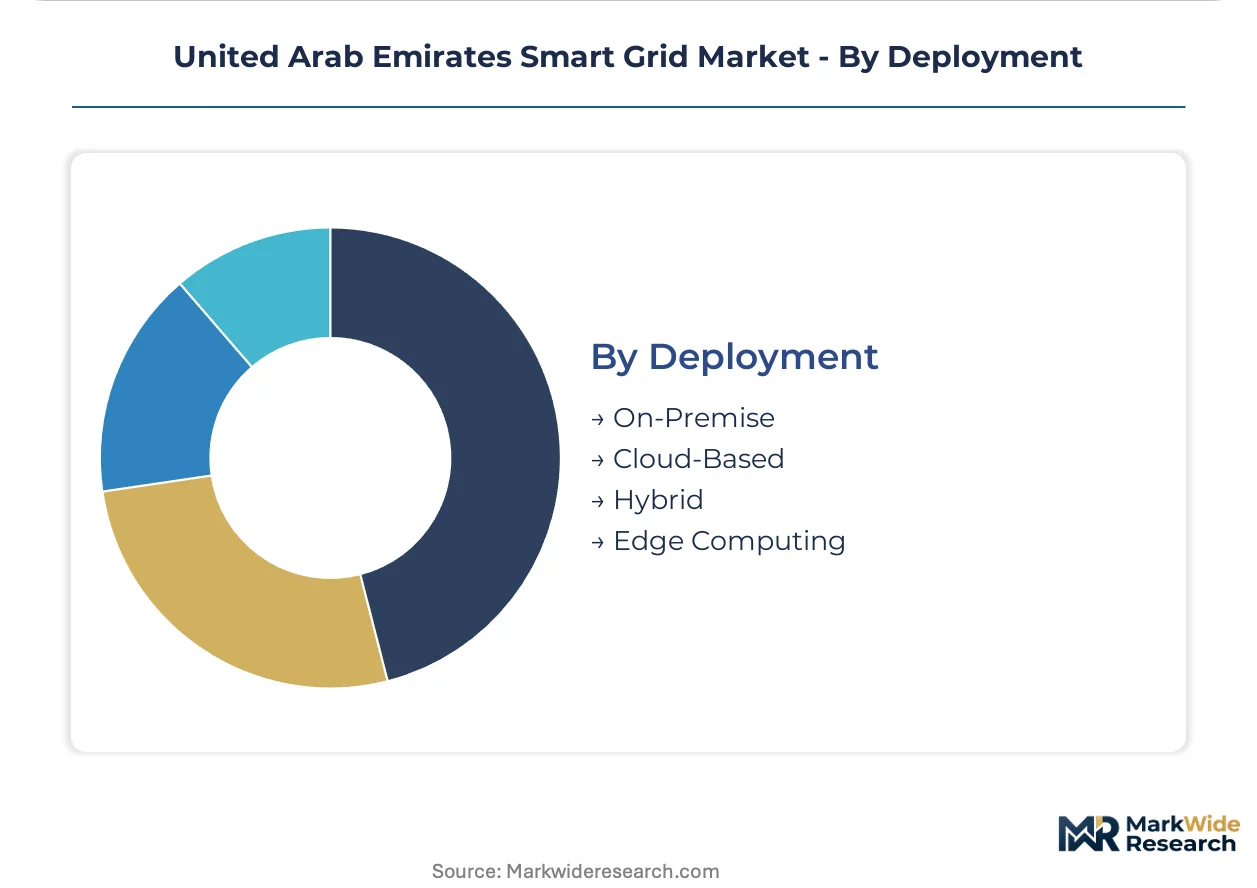
- Cloud-Based:Subscription-hosted analytics platforms delivering scalable energy management without capital-intensive on-premise infrastructure. Commercial and industrial users in Dubai's free zones are bypassing traditional SCADA deployments in favor of software-as-a-service models with faster implementation timelines.
- On-Premise:Dedicated hardware installations within utility control centers or facility server rooms meeting cybersecurity air-gap requirements. Critical infrastructure protection standards and operational technology isolation needs preserve demand among transmission operators and large industrial offtakers.
- Hybrid:Split architectures with sensitive control functions on-premise and analytics workloads in cloud environments.
- Edge Computing:Localized processing at substation or building level for sub-second response requirements.
On-Premise retains dominance in utility applications. Cloud-Based is climbing the fastest among commercial end users seeking operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and rare earth processing facilities in Abu Dhabi's Khalifa Industrial Zone anchor the UAE's smart grid component supply chain, with desert-hardened equipment specifications driving localized manufacturing requirements across all seven emirates.
Dubai
DEWA's Al Shera'a headquarters and Mohammed bin Rashid Al Maktoum Solar Park drive concentrated demand for bidirectional grid infrastructure. MOHAP building energy codes mandate smart monitoring interfaces for commercial developments exceeding specified floor areas. Jebel Ali Industrial Zone hosts manufacturing facilities contracting performance-based energy management guarantees rather than traditional equipment procurement.
Abu Dhabi
ADNOC Distribution's retail network and Emirates Water and Electricity Company anchor utility-scale modernization spending. Federal Net Zero by 2050 targets compress procurement timelines for grid automation across transmission corridors. Masdar City and Khalifa Industrial Zone Abu Dhabi pilot digital substation architectures with process bus communication and non-conventional instrument transformers.
Sharjah
Sharjah Electricity and Water Authority manages distribution network upgrades serving the emirate's manufacturing and logistics clusters. ESMA certification requirements for outdoor electrical equipment filter supplier eligibility for desert climate deployments. Hamriyah Free Zone and Sharjah Research Technology and Innovation Park concentrate commercial and industrial demand for cloud-based energy management platforms.
Northern Emirates
Ras Al Khaimah and Fujairah distribution companies tender remaining Advanced Metering Infrastructure coverage as Dubai and Abu Dhabi complete foundational deployment. Federal energy efficiency mandates extend smart metering requirements to commercial buildings in these underpenetrated markets. Al Hamra Industrial Zone and Fujairah Free Zone offer first-mover positioning for integrated automation contracts as grid extension accelerates.
United Arab Emirates Smart Grid Market Competitive Landscape
Strategic partnerships dominate the current landscape as foreign technology providers align with local utilities to satisfy domestic content requirements and navigate federal procurement regulations. The vendor base clusters around three archetypes: European industrial conglomerates with automation portfolios, Korean and Japanese power equipment specialists, and Gulf-based utilities with in-house engineering capabilities. Portfolio diversification and technology licensing represent the primary competitive moves, with vendors expanding from hardware supply into software-defined service agreements.
Within the European industrial tier, Siemens AG and ABB Ltd. occupy positions exemplifying automation-to-grid integration strategies. Dubai Electricity and Water Authority and Abu Dhabi Distribution Company anchor the utility-operator segment, representing the concentrated procurement authority that shapes vendor selection criteria. General Electric Company sits within the power equipment specialist archetype, with Schneider Electric SE and Honeywell International Inc. rounding out the diversified technology provider grouping that competes across metering, automation, and building management system interfaces.
| Leading Market Players |
|---|
| General Electric Company |
| ABB Ltd. |
| Abu Dhabi Distribution Company |
| Siemens AG |
| Honeywell International Inc. |
| Dubai Electricity and Water Authority |
| Schneider Electric SE |
| Korea Electric Power Corporation |
| Sharjah Electricity and Water Authority |
| Others |
Value Network & Pricing Analysis
Copper and rare earth oxide prices transmit directly through transformer core manufacturing into equipment procurement tiers, with ESMA-certified desert-hardened hardware commanding distinct premiums over standard industrial grades. Procurement officers at DEWA and northern emirate utilities negotiate long-term offtake agreements that buffer spot volatility while embedding service and commissioning bundles into capital contracts.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier digital substation contracts from economy AMI meter procurements. Three-tier pricing structure across premium, standard, and economy levels reflects ESMA certification grade and after-sales service depth. Pricing pressure stems from fixed-price utility tenders compressing margins on transformer and power electronics components. Commercial building developers show highest price sensitivity due to MOHAP code compliance deadlines, while transmission operators prioritize reliability over cost.
Supply Chain Analysis
Domestic content requirements under UAE federal procurement rules are redirecting component sourcing toward Khalifa Industrial Zone assembly facilities and Saudi downstream partners. Manufacturing concentrates in China, South Korea, and Germany for power electronics and non-conventional instrument transformers. Supply chains draw from Chilean copper concentrate, Chinese rare earth processing, and German precision manufacturing. Single-source vulnerability sits with cellular LPWAN chipset suppliers. Distribution runs through emirate-level utility procurement authorities with centralized tendering authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE smart grid market sits in a technology-transition phase as digital substation architectures displace copper-wired protection systems. Process bus communication and software-defined protection modules are replacing legacy hardware-centric substation designs.
For Market Incumbents: Anticipate margin compression from Korean power equipment specialists entering AMI tenders by deepening backward integration into transformer core manufacturing within Khalifa Industrial Zone. Lock in multi-year service agreements with DEWA and ADNOC Distribution before procurement cycles accelerate under Net Zero mandates. Certification investment in ESMA desert-hardening standards remains the critical lever for maintaining technical differentiation.
For New Entrants and Emerging Players: The premium-to-economy price gap in grid automation hardware offers entry positioning through specialized communication module supply to northern emirate utilities. Ras Al Khaimah and Fujairah distribution networks represent the most penetrable geography with remaining AMI coverage gaps. Cloud-native energy management platforms for Jebel Ali and Khalifa Industrial Zone commercial offtakers provide a software-first go-to-market angle bypassing capital-intensive hardware competition.
For Investors and Strategic Acquirers: Accelerated tender releases from SEWA and northern emirate utilities are the leading indicator that procurement velocity is shifting from pilot to scale deployment. Long-term viability centers on vendors with demonstrated interoperability between legacy SCADA and next-generation AMI data streams. Acquisition targets should show proven ESMA certification pathways and established utility reference contracts. Watch for federal cybersecurity compliance deadlines as the inflection signal for vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Substation Platform Deployment | DEWA and ADNOC Distribution pilots validate process bus architectures for Gulf climate conditions. |
| AMI Communication Network Expansion | Ras Al Khaimah and Fujairah tenders create first-mover positioning for field area network specialists. |
| Cloud-Based Energy Management Licensing | Commercial offtakers in Dubai free zones bypass traditional SCADA for subscription analytics platforms. |
| ESMA Certification Investment | Desert-hardening compliance requirements filter supplier eligibility for outdoor electrical equipment. |
| Building-to-Grid Integration Partnership | MOHAP energy code mandates force convergence between HVAC automation and grid-responsive load management. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, and grid automation specialists underwrites the qualitative findings in this analysis. Primary interviews with substation protection engineers, AMI program managers at emirate-level utilities, and procurement leads at DEWA and ADNOC Distribution were cross-referenced against secondary validation from FERC-style regulatory filings, IEA grid modernization reports, and ESMA certification databases. Bottom-up equipment deployment tallies and top-down utility capital expenditure disclosures were reconciled to establish market sizing boundaries.
Comparable historical deployment windows anchored the projection framework to observed AMI rollout velocities and digital substation commissioning timelines across the analysis window. Segmentation modeling incorporated product type, technology layer, end-user procurement authority, and deployment architecture dimensions. CAGRs were derived from utility-published capital plans and federal mandate compliance schedules. Forecast inputs included rooftop solar interconnection trajectories under DEWA technical standards and commercial building completion pipelines subject to MOHAP energy codes.
Underlying measurement precision varies by segment; utility-scale procurement data carries tighter precision than commercial building automation estimates. Forecasts reflect assumptions around federal Net Zero timeline adherence and rare earth supply continuity. Cybersecurity certification delays or copper price spikes could revise deployment trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Demand Response Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Smart Water Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Demand Response Market