
 Demand Response Management System Market | 2026-2036
Demand Response Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Demand Response Management System Market Intelligence
Modular bundling of hardware, software, and ancillary services is hardening as the dominant procurement pattern for grid operators. Siemens AG leverages its digital grid portfolio to anchor European utility contracts. Honeywell International Inc. competes through deep building-automation integration that extends into demand response orchestration.
A Demand Response Management System is an integrated software and control platform that dispatches load curtailment signals to distributed energy resources, typically operating with sub-minute response latencies and bidirectional telemetry protocols. Its primary commercial purpose is to monetize electricity consumption flexibility as a grid-balancing asset. Automated Demand Response now leads solution deployments because algorithmic dispatch outperforms manual protocols during price volatility events. Cloud-Based deployment models capture the fastest expansion as hyperscale infrastructure reduces capital barriers for mid-sized utilities.
The US Federal Energy Regulatory Commission, the EU Agency for the Cooperation of Energy Regulators, and California's Public Utilities Commission each mandate interoperability standards that shape vendor certification requirements and market access conditions. FERC Order 2222 explicitly compels regional transmission organizations to integrate distributed energy resource aggregations, forcing platform upgrades across incumbent suppliers. Stakeholders must monitor how jurisdiction-specific telemetry standards fragment procurement specifications and determine whether to pursue multi-certification strategies or geographic specialization.
Market Dynamics
Automated algorithmic dispatch is compressing response latencies below sixty seconds, forcing utilities to retire manual demand response protocols and restructure procurement around sub-minute telemetry certification.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2222 compels regional transmission organizations to integrate distributed energy resource aggregations, expanding addressable market for aggregation platforms.
- California:The state's Public Utilities Commission enforces emergency load reduction programs that require automated demand response participation from large commercial and industrial facilities.
- Inflation Reduction Act Tax Credits:Investment tax credits for grid flexibility infrastructure reduce payback periods for utility-scale demand response deployments.
Market Restraints
- Interoperability Fragmentation:Jurisdiction-specific telemetry standards from FERC, EU Agency for the Cooperation of Energy Regulators, and state-level public utility commissions force multi-certification costs on vendors.
- Cloud Infrastructure Concentration:Hyperscale provider lock-in creates operational risk for mid-sized utilities migrating demand response platforms to cloud-based deployment models.
- Cybersecurity Compliance Burden:North American Electric Reliability Corporation critical infrastructure protection standards impose recurring audit costs on demand response management system operators.
Strategic Opportunities
- Behind-the-Meter Storage Convergence:Battery energy storage systems paired with demand response algorithms unlock frequency regulation revenue streams for commercial building operators.
- Texas ERCOT Market:Volatile wholesale electricity pricing creates arbitrage opportunities for automated load curtailment services in the state's deregulated grid.
- Virtual Power Plant Aggregation:Residential thermostat and water heater fleets aggregated through software platforms qualify for capacity market payments previously reserved for centralized generation.
Industry Challenges
- SCADA Integration Complexity:Legacy supervisory control and data acquisition systems at municipal utilities require costly middleware development to achieve bidirectional telemetry with modern demand response platforms.
- Data Science Talent Scarcity:Shortage of engineers skilled in both power systems operations and machine learning model deployment constrains algorithmic dispatch optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand Response Management System Market |
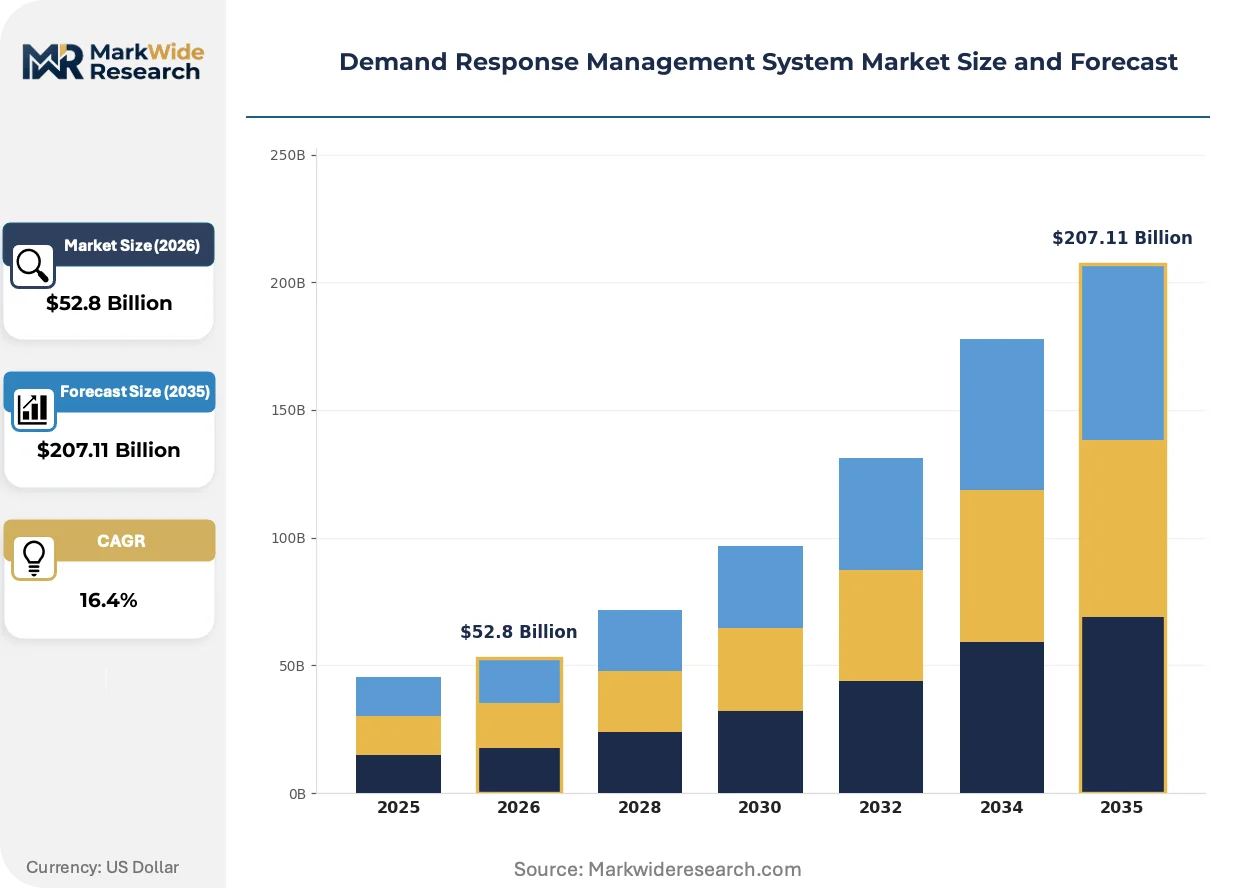
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $207.11 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Automated Demand Response, Manual Demand Response, Price-Based Demand Response, Incentive-Based Demand Response, Real-Time Demand Response Application: Load Management, Peak Shaving, Emergency Demand Reduction, Demand Forecasting, Grid Stability, Ancillary Services Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Complexes, Government Institutions |
| Companies Covered | Honeywell International Inc., Johnson Controls International PLC, Siemens AG, Enel SpA, Eaton Corporation PLC, ABB Ltd, General Electric Company, Itron Inc., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand Response Management System Market Strategic Shifts & Innovations
Artificial intelligence and edge computing architectures are rewriting the technical specifications that define competitive viability in demand response platform procurement.
Machine learning-based load forecasting is integrating historical consumption patterns, weather data, and real-time price signals to predict curtailment potential at individual facility level. Large industrial energy managers in Texas and California are deploying these predictive models to pre-position load flexibility before price spike events. The technology is integrating formerly siloed building management systems with wholesale market interfaces, collapsing the latency between price signal and physical response.
EU Agency for the Cooperation of Energy Regulators recently finalized interoperability frameworks for cross-border demand response aggregation. The regulation enables utilities in Germany, France, and the Netherlands to pool distributed flexibility resources across transmission system operator boundaries. Nordic grid operators are responding fastest, restructuring procurement contracts to reward sub-second frequency response from aggregated residential loads.
Building automation vendors are unbundling hardware sales from software subscriptions, converting capital expenditure procurement into operational expenditure models. Facility managers at Class A commercial real estate portfolios now license demand response capability as a metered service rather than owning control infrastructure. This shift is most pronounced in California, where property owners face mandated emissions disclosure requirements that favor outsourced energy management over in-house capability development.
Demand Response Management System Market Segmentation
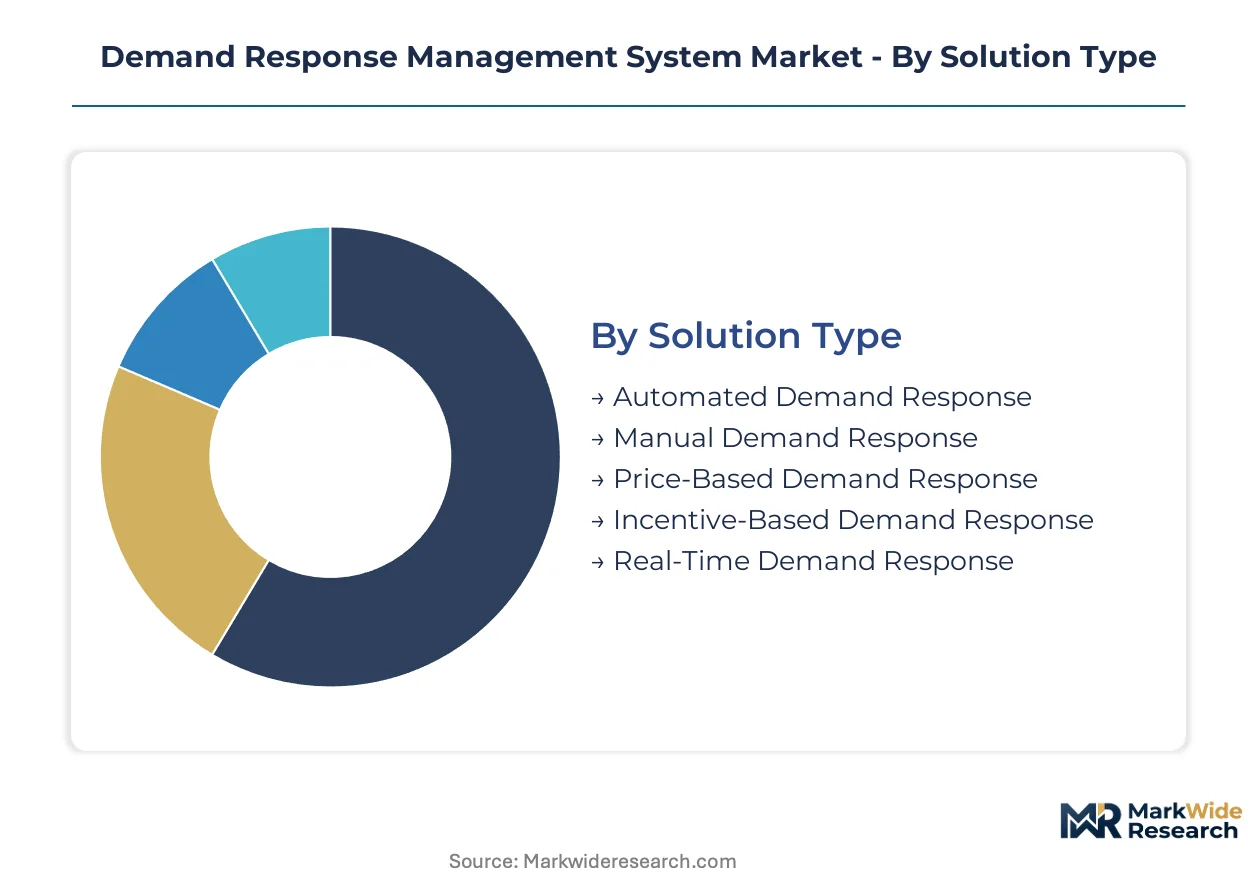
Segmentation in the Demand Response Management System market determines procurement pathways, certification requirements, and integration complexity for grid operators. Vendors structure their platform architectures around specific solution types and deployment models that align with regulatory mandates and operational risk profiles.
Solution Type:
FERC Order 2222 certification applies differentially across solution types, with automated protocols requiring sub-minute telemetry validation while manual systems face grandfathering deadlines.
- Automated Demand Response:Algorithmic dispatch platforms execute load curtailment through machine learning models with sub-sixty-second response latencies. Industrial facilities in Texas ERCOT territory concentrate procurement here, driven by volatile wholesale price arbitrage opportunities that reward speed over manual intervention.
- Manual Demand Response:Human-operator protocols rely on phone or email dispatch for load reduction events, typically achieving five- to fifteen-minute response times. Municipal utilities with legacy SCADA infrastructure in California maintain these systems as transitional deployments while pursuing automated upgrades mandated by the state's Public Utilities Commission emergency load reduction programs.
- Price-Based Demand Response:Direct consumer response to dynamic electricity pricing signals without centralized dispatch control.
- Incentive-Based Demand Response:Capacity market payments or bill credits trigger participation through pre-committed curtailment obligations.
- Real-Time Demand Response:Continuous telemetry streams enable instantaneous load modulation for frequency regulation services.
Leading the category by volume: Automated Demand Response. Growing fastest: Real-Time Demand Response.
Application:
Cost tiering separates applications by integration depth, with grid stability commanding premium platform licensing versus standalone load management modules.
- Load Management:Baseline demand shaping through scheduled curtailment of non-critical equipment.
- Peak Shaving:Commercial building operators in California deploy these applications to avoid demand charges during summer afternoon peaks, with software subscriptions replacing capital-intensive battery installations under new operational expenditure procurement models.
- Emergency Demand Reduction:Last-resort curtailment protocols activated during grid emergency declarations.
- Demand Forecasting:Predictive analytics platforms aggregate historical consumption, weather data, and price signals to pre-position flexibility assets before market events.
- Grid Stability:Frequency and voltage regulation services require sub-second telemetry and bidirectional control architectures certified to North American Electric Reliability Corporation standards.
- Ancillary Services:Spinning reserves and non-spinning reserves monetized through regional transmission organization markets.
Dominant by revenue: Grid Stability. Expanding most quickly: Demand Forecasting.
Deployment Model:
Customer type determines deployment architecture, with hyperscale utilities favoring cloud elasticity while security-sensitive government operators mandate on-premise air-gapped systems.
- Cloud-Based:Hyperscale infrastructure eliminates capital expenditure barriers for mid-sized utilities migrating from legacy platforms. The model concentrates fastest in Texas, where deregulated market structures and independent system operator governance reduce procurement friction for software-as-a-service contracts.
- On-Premise:Dedicated hardware installations within utility data centers satisfy North American Electric Reliability Corporation critical infrastructure protection standards without third-party provider dependencies.
- Hybrid:Split architectures process sensitive operational data locally while leveraging cloud analytics for non-critical forecasting workloads.
- Edge Computing:Distributed processing nodes at substation or facility level reduce telemetry latency for time-critical frequency response applications.
Highest volume segment: Cloud-Based. Steepest expansion trajectory: Edge Computing.
End User:
Supply concentration in platform development favors utility-scale deployments, though margin structures attract vendor investment toward commercial building automation integration.
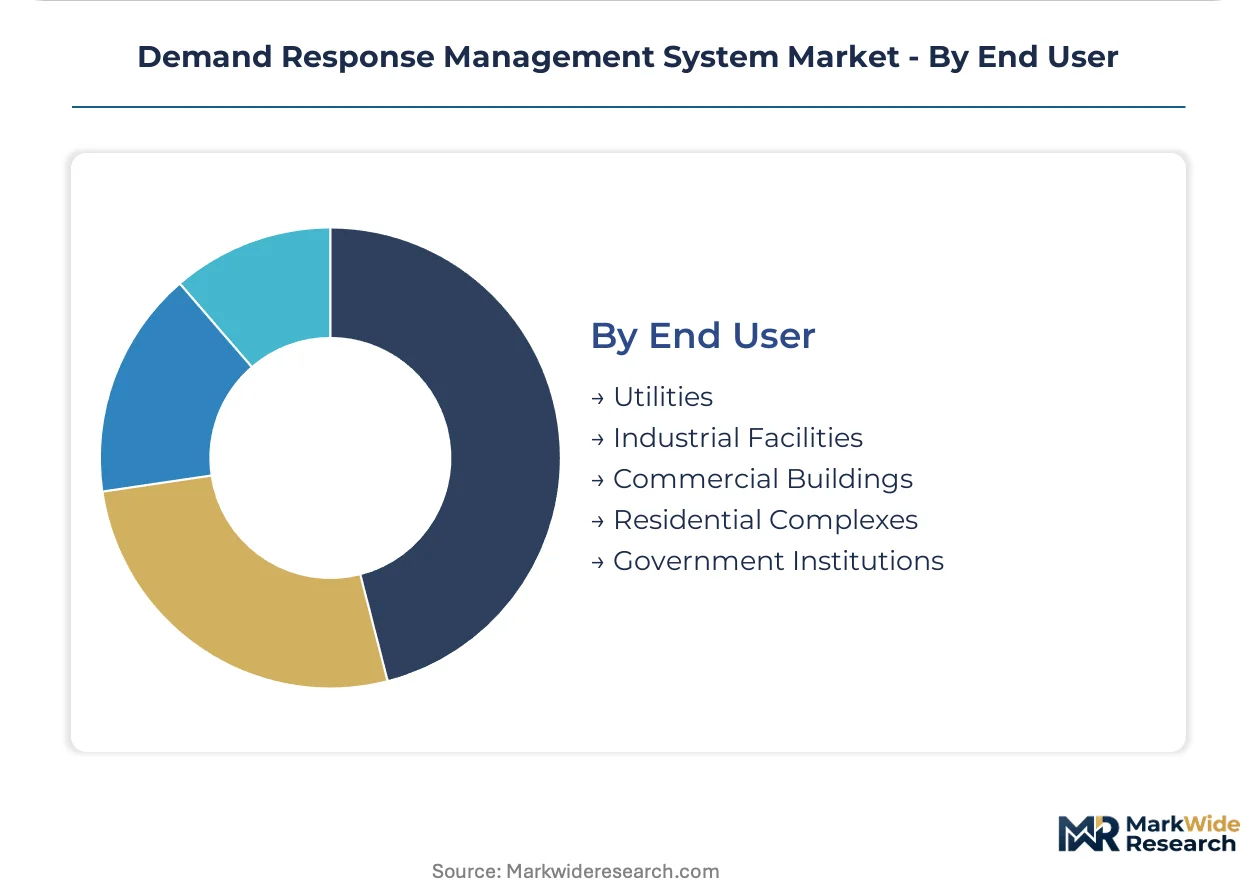
- Utilities:Transmission and distribution operators procure enterprise-grade platforms for aggregated demand response program administration.
- Industrial Facilities:Large manufacturing campuses in Texas and California deploy behind-the-meter control systems to capture wholesale market arbitrage while maintaining production process continuity through predictive curtailment algorithms.
- Commercial Buildings:Class A real estate portfolios license demand response capability as metered services, outsourcing energy management to building automation vendors unbundling hardware from software subscriptions.
- Residential Complexes:Virtual power plant aggregation of thermostat and water heater fleets qualifies for capacity payments through software platforms.
- Government Institutions:Municipal and federal facilities face procurement rules prioritizing cybersecurity compliance over cost optimization.
Leading by deployment count: Utilities. Gaining share fastest: Commercial Buildings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment tax credits under the US Inflation Reduction Act have concentrated demand response platform deployment in states with deregulated wholesale markets and aggressive decarbonization mandates. California and Texas together absorb the majority of North American procurement volume.
United States
FERC Order 2222 compels regional transmission organizations to integrate distributed energy resource aggregations, expanding addressable markets for automation vendors. The Inflation Reduction Act extends investment tax credits for grid flexibility infrastructure through 2032. Texas ERCOT territory leads automated deployment, with industrial facilities in Houston and Dallas-Fort Worth metroplexes capturing wholesale price arbitrage through sub-minute response systems.
Germany
The EU Agency for the Cooperation of Energy Regulators finalized cross-border interoperability frameworks enabling German utilities to pool flexibility with French and Dutch grid operators. Bundesnetzagentur implements telemetry certification aligned with EU network codes. Industrial load aggregators in the Ruhr region and Bavarian manufacturing corridors are restructuring procurement contracts to reward frequency response from commercial building fleets.
China
Provincial grid operators in Jiangsu and Guangdong provinces pilot demand response markets to absorb renewable curtailment from utility-scale solar and wind installations. The National Development and Reform Commission mandates peak-shaving participation from large industrial consumers in select pilot zones. Yangtze River Delta manufacturing clusters deploy automated load control to avoid capacity charges during summer demand peaks.
United Kingdom
Ofgem's Targeted Charging Review reshapes network cost recovery, indirectly incentivizing peak demand reduction through demand response participation. The Capacity Market auction mechanism procures demand-side response alongside generation assets. London and Southeast commercial property portfolios license building automation integration to satisfy tightening emissions disclosure requirements under Streamlined Energy and Carbon Reporting rules.
Japan
METI's Electricity System Reform established a balancing market open to demand-side resources, with Tokyo Electric Power and Kansai Electric piloting aggregator registration. The Feed-in Tariff transition to Feed-in Premium creates price exposure that industrial consumers hedge through automated curtailment. Osaka-Kobe industrial corridor facilities represent the densest concentration of behind-the-meter control system deployment.
Demand Response Management System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with market structure tilting toward integrated building automation vendors. Tiering separates enterprise-grade platform providers serving transmission operators from modular software vendors targeting commercial building portfolios. Two archetypes dominate: industrial conglomerates leveraging cross-divisional grid portfolios, and building automation specialists extending control systems into demand response orchestration. Consolidation pressure drives incumbent suppliers toward middleware partnerships with municipal utilities, while geographic specialization strategies multiply to manage multi-certification burdens.
Within the diversified industrial tier, Honeywell International Inc. and Johnson Controls International PLC exemplify building automation incumbents extending control infrastructure into demand response capability. Siemens AG anchors European utility contracting through digital grid portfolio breadth. These three occupy positions where hardware-software bundling hardens as the dominant procurement pattern, converting capital expenditure deployments into operational expenditure service models.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International PLC |
| Siemens AG |
| Enel SpA |
| Eaton Corporation PLC |
| ABB Ltd |
| General Electric Company |
| Itron Inc. |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Edge computing architectures for sub-second telemetry are compressing hardware costs while concentrating procurement power among vendors certified to North American Electric Reliability Corporation standards. This dual shift simultaneously lowers capital barriers for mid-sized utilities and tightens margin capture for incumbent platform providers holding interoperability certifications.
Pricing Analysis
Short lead-time premiums for certified hardware-software bundles command substantial markups over standard procurement cycles, while spot inventory of legacy manual systems trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because municipal utilities delay automated upgrades amid budget constraints. Commercial building operators in California exhibit highest price sensitivity due to operational expenditure procurement models, while transmission operators show lowest sensitivity given grid stability mandates.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act are reshaping sourcing patterns for grid flexibility hardware, favoring North American assembly of telemetry devices and control modules. Manufacturing concentrates in the United States, Germany, and China for specialized industrial controllers, with semiconductor inputs drawing from Taiwan and South Korea. Lithium-ion battery cells for behind-the-meter storage integration rest on South Korean and Chinese supply. Single-source vulnerability in advanced metering infrastructure chipsets creates exposure to export control restrictions. Distribution runs through utility procurement consortia and building automation vendor direct sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
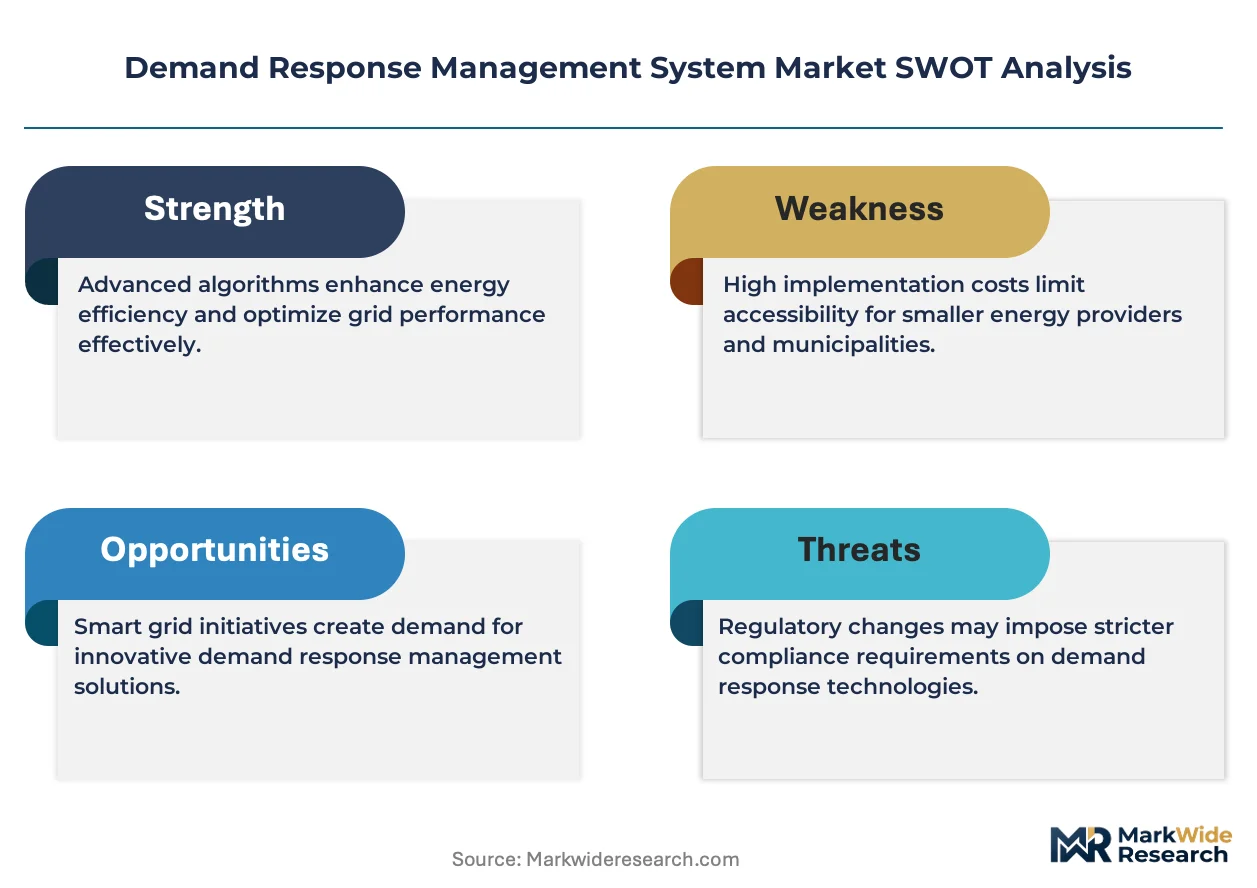
FERC Order 2222 compliance costs erect a formidable barrier-to-entry moat, privileging incumbent vendors with existing regional transmission organization certifications and locking out undercapitalized challengers unable to sustain multi-jurisdiction audit burdens.
For Market Incumbents: Anchor market position through middleware partnerships with municipal utilities struggling with SCADA integration complexity, while accelerating certification investment for EU Agency for the Cooperation of Energy Regulators interoperability frameworks. Threat of pure-play software entrants with cloud-native architectures demands defensive consolidation of channel relationships with building automation vendors. Vertical integration into edge computing hardware secures supply continuity for time-critical frequency response deployments. For New Entrants and Emerging Players: Capture white-space in Texas ERCOT territory where deregulated market structures reduce procurement friction for software-as-a-service contracts, and target mid-sized commercial building portfolios in California facing mandated emissions disclosure requirements. The most penetrable segment lies in virtual power plant aggregation for residential thermostat fleets. Go-to-market leverage rests on outcome-based pricing tied to verified load curtailment performance. For Investors and Strategic Acquirers: Re-rating potential sits with building automation specialists holding deep integration relationships with Class A real estate portfolios given the operational expenditure procurement shift. Long-term viability favors vendors with multi-certification capabilities spanning FERC, EU Agency for the Cooperation of Energy Regulators, and state-level mandates. Acquisition target archetype: edge computing platform developers with sub-second telemetry validation. Signal to watch is frequency regulation market rule changes that expand addressable revenue per aggregated kilowatt.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Partnership Development | Unlocks municipal utility segment by bridging legacy SCADA with modern telemetry protocols. |
| Multi-Jurisdiction Certification Investment | Secures market access across FERC Order 2222, EU network codes, and state emergency load reduction programs. |
| Edge Computing Hardware Integration | Reduces response latency for frequency regulation services in Nordic and Texas markets. |
| Software-as-a-Service Model Conversion | Aligns with California commercial building procurement shifts toward operational expenditure structures. |
| Virtual Power Plant Platform Launch | Captures capacity market payments from residential thermostat and water heater aggregation. |
Research Approach
Independent corroboration across utility planning officers, building automation vendor executives, grid operator engineers, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FERC filings, EIA demand response program databases, EU Agency for the Cooperation of Energy Regulators interoperability frameworks, and regional transmission organization market rule dockets. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators for the energy infrastructure investment cycle.
Comparable historical reference periods anchor the forecast window to pre-pandemic utility capital expenditure baselines and post-Inflation Reduction Act incentive acceleration phases. The analytical framework models deployment model, solution type, end-user scale tier, and regional regulatory cluster dimensions across the projection horizon. CAGRs derive from segment-level adoption curves weighted by jurisdiction-specific mandate enforcement timelines. Forecast inputs include utility-scale battery storage co-deployment rates and wholesale market price volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal incentive extension decisions and cybersecurity standard evolution. The analysis reflects assumptions regarding regional transmission organization rule implementation pace and state-level renewable portfolio standard stringency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Energy Security Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Industrial Energy Management System Market
Energy Management
Power SCADA Market
Energy Management
Smart Energy Solutions Market
Energy Management
Brazil Energy Sector Market
Energy Management
Microgrid Control System Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Thermostat Market
Energy Management
Heat Meter Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Global Utility Asset Management Market
Energy Management
Electric Sub-Meter Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Germany Demand Response Management Systems Market