
 Tilapia Market | 2026-2036
Tilapia Market Size, Share, and Industry Trends Forecast 2026-2036
Tilapia Market Intelligence
Foodservice procurement consolidation among North American restaurant chains is recalibrating tilapia sourcing toward vertically integrated suppliers. Regal Springs leverages its Central American lake-farming operations to sustain year-round fillet supply commitments to major quick-service buyers. Baiyang Investment Group anchors Chinese domestic distribution through integrated hatchery-to-retail networks. Charoen Pokphand Foods competes across Southeast Asian markets with controlled-environment aquaculture systems that reduce seasonal yield variance.
Tilapia denotes freshwater finfish within the Cichlidae family, typically harvested at 450–900 grams live weight for fillet processing or sold whole at 200–400 grams for ethnic retail channels. The species tolerates brackish conditions and achieves market size in six to ten months under intensive feeding regimes, making it a cost-efficient protein source for price-sensitive protein markets. Frozen fillets dominate export trade flows due to extended shelf stability and containerized shipping economics, while fresh whole fish commands premium positioning in domestic Chinese and Southeast Asian wet markets. Processed products including breaded portions and marinated ready-to-cook items capture margin pools in European and North American retail, though nuggets remain a nascent category with limited brand development.
FDA seafood HACCP requirements govern United States import safety protocols, while EFSA residue monitoring shapes European Union maximum residue limits for aquaculture therapeutics. China's Ministry of Agriculture and Rural Affairs encloses freshwater aquaculture within environmental compliance zones that restrict pond expansion in watershed-sensitive provinces. Stakeholders must monitor evolving antibiotic-use restrictions across Brazil's Ministério da Agricultura and emerging carbon-footprint disclosure obligations under the EU Green Deal before committing to multi-year supply contracts or processing capacity additions.
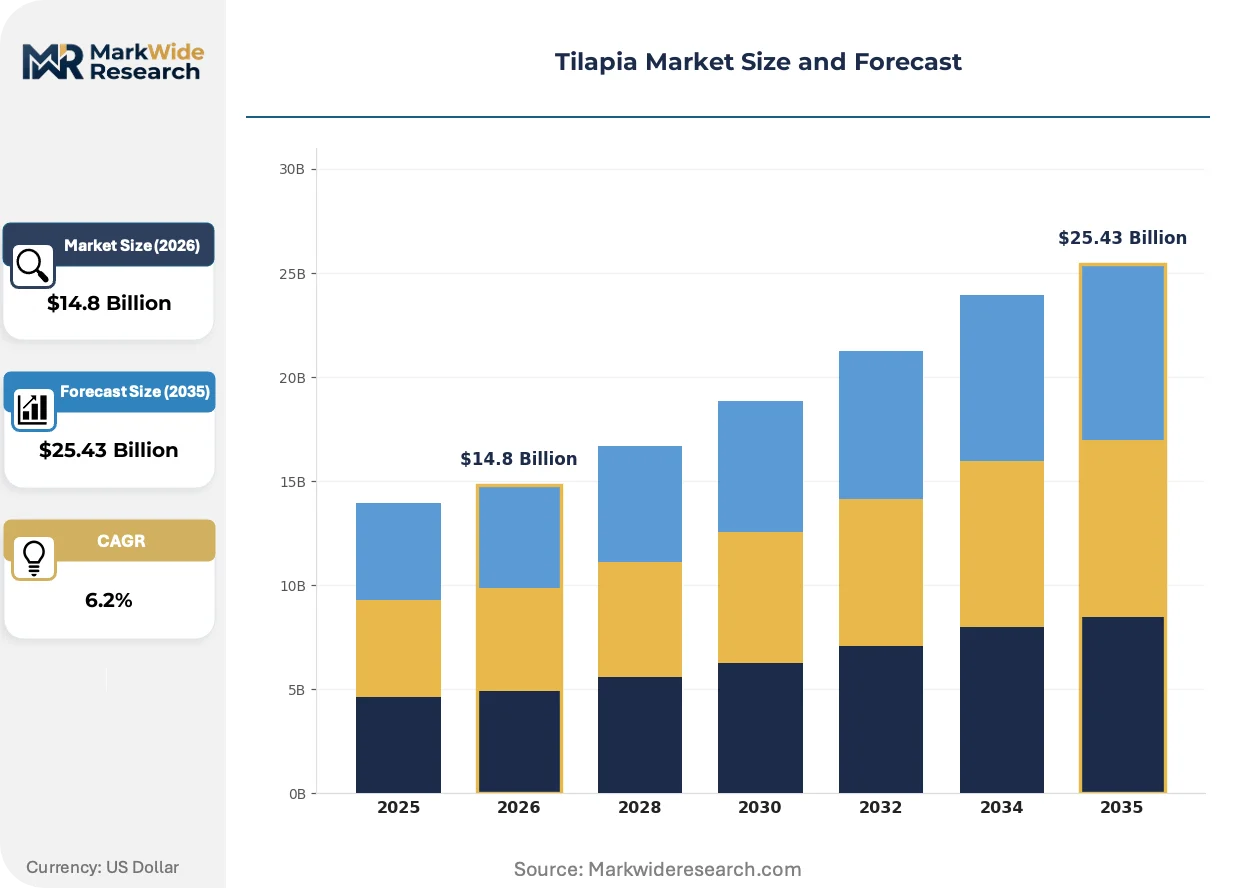
Market Dynamics
Feed conversion ratio improvements and recirculating aquaculture system adoption are compressing production cycles while China's environmental compliance zones restrict pond expansion in watershed-sensitive provinces, creating a supply squeeze that favors intensive operators.
Growth Catalysts
- EU Green Deal carbon-footprint disclosure:Early compliance positions suppliers for preferential procurement from European retail chains prioritizing scope 3 emissions transparency.
- Quick-service restaurant chains:North American foodservice operators are expanding tilapia menu placements as a lower-cost whitefish alternative to cod and pollock.
- Brazilian domestic production:Farmed tilapia output in São Paulo and Paraná states is displacing imports across retail and foodservice channels.
Market Restraints
- Soymeal and fishmeal price volatility:Feed input costs represent the largest variable in intensive pond operations, squeezing margins when commodity markets spike.
- China supply concentration:Environmental compliance zones in Guangdong and Hubei provinces restrict expansion, capping output from the world's largest producer.
- Antibiotic residue monitoring:EFSA maximum residue limits and Brazil's Ministério da Agricultura restrictions create compliance friction for therapeutic use.
Strategic Opportunities
- Processed value-added segments:Breaded portions and marinated ready-to-cook items capture margin pools in European and North American retail where brand development remains nascent.
- Indonesian archipelago expansion:Underpenetrated domestic markets across Java and Sumatra offer white space for vertically integrated hatchery-to-retail networks.
- Recirculating aquaculture system convergence with solar:Renewable-powered closed-loop systems reduce energy opex while satisfying EU Green Deal disclosure requirements.
Industry Challenges
- Genetic broodstock management expertise:Qualified hatchery technicians capable of strain selection and disease resistance breeding remain scarce outside established production clusters.
- FDA seafood HACCP certification timelines:United States import safety protocols require documented hazard analysis plans that delay new supplier market entry by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tilapia Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Fish, Fillets, Nuggets, Processed Products Distribution Channel: Supermarkets, Online Retail, Fishmonger, Foodservice End User: Households, Restaurants, Hotels, Caterers Form: Fresh, Frozen, Dried, Canned |
| Companies Covered | Hainan Xiangtai Fishery, Mazzetta Company LLC, Regal Springs, Charoen Pokphand Foods, Thai Union Group, Baiyang Investment Group, Netuno Internacional, Aquabest, Blue Ridge Aquaculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tilapia Market Strategic Shifts & Innovations
Automation and data-driven feeding systems are reshaping how producers optimize biomass throughput, while regulatory pressure on therapeutics and carbon accounting is forcing capital reallocation toward traceable supply chains.
Recirculating aquaculture systems with integrated biofiltration and oxygen injection are absorbing capital from traditional pond operators seeking to bypass watershed restrictions. Chinese producers in Jiangsu and Shandong provinces are retrofitting facilities at accelerated pace. The technology is absorbing regulatory pressure that would otherwise cap output, enabling year-round production with predictable harvest schedules.
EFSA residue monitoring protocols are tightening maximum allowable limits for aquaculture therapeutics across European Union member states. Exporters to Germany and France must now maintain batch-level documentation of antibiotic-free certification. Vietnamese and Indonesian suppliers are responding by investing in vaccine programs and probiotics to replace chemotherapeutic interventions.
Ethnic retail channels in North American metropolitan areas are consolidating purchasing through specialized seafood distributors rather than traditional broadline foodservice purveyors. Whole fish buyers in Los Angeles, Houston, and Toronto now demand live-tank holding capability and same-day delivery windows. This channel rotation is most visible in Chinese and Southeast Asian demographic corridors where wet-market authenticity commands premium positioning.
Tilapia Market Segmentation
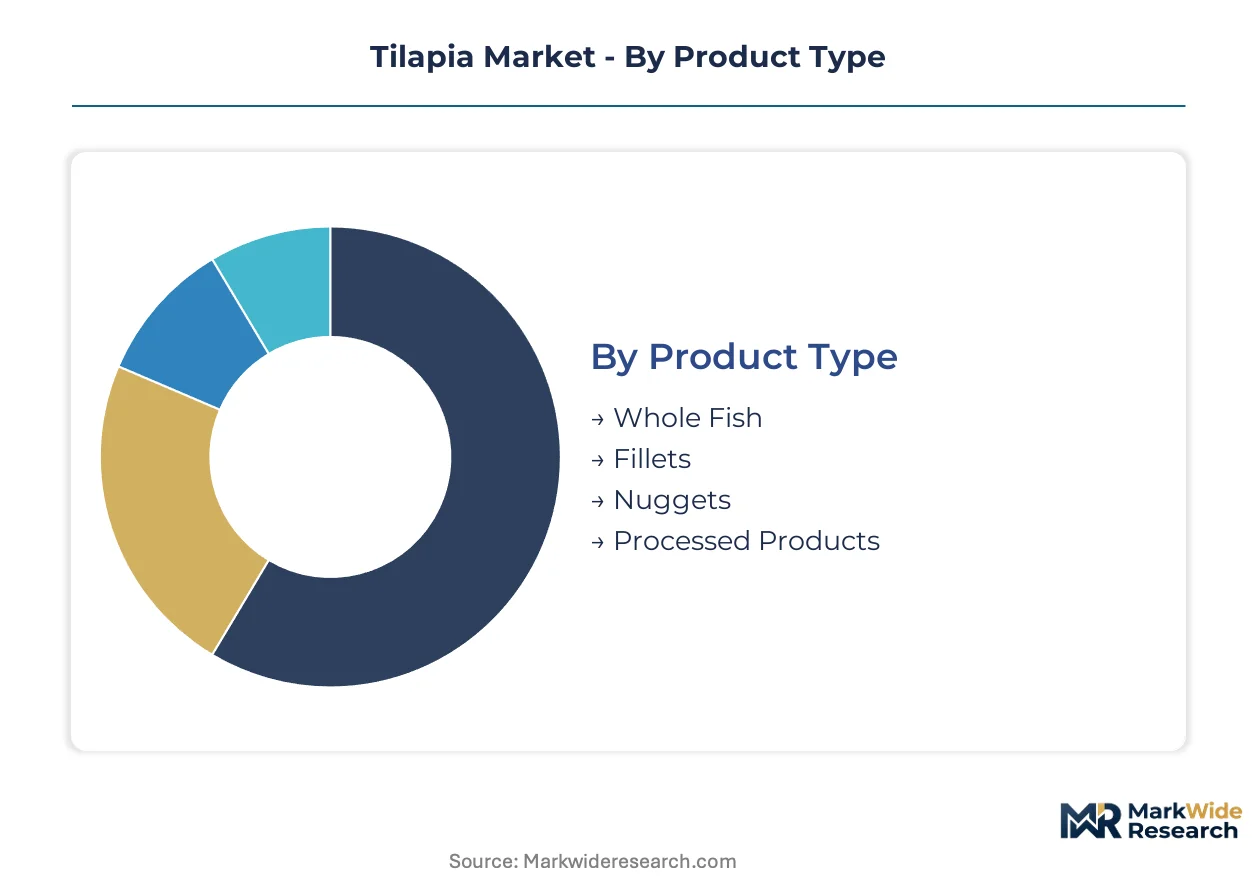
Tilapia market segmentation reveals how processing intensity, channel access, and consumption context reshape procurement economics across the value chain. Distinct margin pools attach to each slice, from commodity whole fish through value-added processed lines.
Product Type:
Upgrade cycles in tilapia consumption track protein format sophistication, with buyers trading up from whole fish to convenience-oriented cuts as cold chain infrastructure matures.
- Fillets:Boneless, skin-on or skinless cuts dominate North American and European retail and foodservice procurement. Quick-service chains specify individually quick-frozen portions for portion-cost control. Demand concentrates in US coastal metropolitan markets where whitefish substitution from cod and pollock accelerates.
- Processed Products:Breaded portions, marinated steaks, and ready-to-cook items command 40-60% gross margins above commodity fillets. European retail chains source these for private-label seafood lines where brand development remains nascent.
- Whole Fish:Live or gutted fish serves ethnic retail channels and wet markets across China, Southeast Asia, and North American demographic corridors. Scale and gill-color freshness standards determine pricing tiers.
- Nuggets:Minced and formed products occupy limited shelf space in North American retail, primarily targeting child-oriented meal solutions with minimal brand differentiation.
Volume placements concentrate in Fillets; the faster expansion belongs to Processed Products.
Distribution Channel:
Channel selection dictates working capital requirements and traceability obligations, with direct foodservice contracts demanding longer payment terms but securing volume commitments.
- Foodservice:Broadline distributors and specialized seafood purveyors supply restaurant chains, institutional cafeterias, and catering operations. North American procurement consolidation favors suppliers with year-round fillet availability and HACCP documentation.
- Supermarkets:Hypermarket and grocery chains across Brazil and China drive domestic offtake, with fresh counter displays competing against pre-packed frozen alternatives. Private-label programs absorb increasing volume from branded suppliers.
- Fishmonger:Independent seafood retailers and wet market stallholders dominate whole fish distribution in China, Indonesia, and ethnic corridors of Toronto and Los Angeles. Live-tank holding capability differentiates suppliers.
- Online Retail:E-commerce platforms capture emerging demand for home-delivered frozen portions in Chinese tier-one cities and Brazilian metropolitan areas, though cold chain reliability constrains geographic reach.
Revenue concentration sits with Foodservice; the channel climbing fastest is Online Retail.
End User:
End-user segmentation separates price-sensitive volume buyers from premium-positioned hospitality operators willing to pay for provenance documentation and consistent sizing.
- Restaurants:Quick-service chains and casual dining operators specify frozen fillets for menu items where tilapia substitutes higher-cost whitefish. Procurement teams prioritize suppliers with vertical integration into processing.
- Households:Retail purchasers across Brazil and China drive whole fish and fresh fillet demand, with purchasing decisions shaped by per-kilogram pricing and visual freshness cues.
- Hotels:International hospitality chains in Southeast Asian tourist corridors source standardized fillet portions for buffet and à la carte applications, requiring consistent portion weights.
- Caterers:Event and institutional food providers purchase frozen bulk packs for high-volume preparation, prioritizing cost stability over origin traceability.
Procurement scale peaks with Restaurants; the user category expanding most quickly is Households in underpenetrated provincial markets.
Form:
Form selection reflects cold chain maturity and consumption occasion, with frozen formats enabling intercontinental trade flows that fresh products cannot support.
- Frozen:Individually quick-frozen fillets and bulk-packed whole fish dominate export trade, with containerized shipping economics favoring -18°C supply chains from China and Southeast Asia to North America and Europe.
- Fresh:Whole fish and chilled fillets command premium positioning in domestic Chinese wet markets and Brazilian retail, requiring rapid harvest-to-sale logistics that limit geographic radius.
- Dried:Salt-cured and sun-dried products serve traditional consumption patterns across West African and Southeast Asian markets where refrigeration penetration remains limited.
- Canned:Retort-pouched and tin-packed tilapia occupies niche positioning in emergency food reserves and military procurement, with minimal retail presence outside specific demographic segments.
Trade volume aggregates in Frozen; the steepest expansion trajectory belongs to Fresh in domestic Brazilian and Chinese channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of tilapia consumption through domestic wet markets and processing export channels. Brazil and the United States follow as high-growth demand centers where local production is displacing import dependency.
China
Jiangsu and Shandong provinces drive recirculating aquaculture system retrofitting as producers bypass watershed expansion limits. The Ministry of Agriculture and Rural Affairs enforces environmental compliance zones that cap pond development in Guangdong and Hubei. Qingdao processing clusters now supply year-round frozen fillet commitments to European retail chains.
Brazil
São Paulo and Paraná state farms displace imports across retail and foodservice channels with domestically harvested whole fish. ANVISA antibiotic residue monitoring tightens therapeutic use protocols for export-bound production. Maringá industrial parks concentrate fillet processing capacity serving São Paulo metropolitan supermarket buyers.
United States
Quick-service restaurant chains specify individually quick-frozen portions for whitefish substitution menus. FDA seafood HACCP requirements extend supplier onboarding timelines to 12-18 months for documented hazard analysis. Los Angeles ethnic retail corridors demand live-tank holding capability from whole fish distributors.
Indonesia
Java and Sumatra underpenetrated domestic markets offer expansion space for hatchery-to-retail network development. The national fisheries ministry channels subsidy programs toward intensive pond modernization in East Java. Surabaya processing zones capture emerging demand from Jakarta metropolitan e-commerce platforms.
Mexico
Chiapas and Veracruz aquaculture zones supply fresh whole fish to Mexico City metropolitan wet markets. Federal environmental regulations restrict pond expansion in watershed-sensitive southern provinces. Tapachula cluster operators now direct surplus output toward Guatemalan cross-border retail channels.
Tilapia Market Key Industry Players
Chinese producers anchor the volume tier; Central American lake-farming specialists hold premium positioning through year-round supply reliability. The vendor base separates into three strategic archetypes: vertically integrated hatchery-to-retail networks, recirculating aquaculture system technology adopters, and regional whole fish distributors serving ethnic retail corridors. Competitive moves concentrate on backward integration into captive broodstock programs and renewable-powered facility retrofits that satisfy EU Green Deal disclosure requirements.
Within the integrated network tier, Baiyang Investment Group and Charoen Pokphand Foods exemplify geographic diversification strategies across domestic and export channels. Regal Springs occupies a position among Central American lake-farming operators with sustained supply commitments to North American foodservice buyers. These three entities represent contrasting approaches to regulatory navigation: Chinese state-coordinated distribution networks, Southeast Asian controlled-environment systems, and Central American natural lake exploitation with processing integration.
| Leading Market Players |
|---|
| Hainan Xiangtai Fishery |
| Mazzetta Company LLC |
| Regal Springs |
| Charoen Pokphand Foods |
| Thai Union Group |
| Baiyang Investment Group |
| Netuno Internacional |
| Aquabest |
| Blue Ridge Aquaculture |
| Others |
Cost & Logistics Intelligence
Sovereign-backed Chinese producers and Central American lake-farming operators anchor supply concentration, translating watershed access rights and year-round harvest capability into pricing discipline across frozen fillet contracts. This ownership pattern compresses spot-price volatility for integrated suppliers while squeezing margin pools for non-vertically aligned distributors dependent on spot-market procurement.
Pricing Analysis
Volume placements concentrate in commodity frozen fillets; margin expansion belongs to processed value-added lines. Three-tier pricing structure across premium lake-farmed, standard intensive-pond, and economy mixed-source tiers separates suppliers by HACCP certification status and origin traceability. Pricing pressure stems from soymeal and fishmeal input cost spikes that squeeze intensive pond operators. Quick-service restaurant chains exhibit highest price sensitivity; European retail private-label buyers accept modest premiums for antibiotic-free batch documentation.
Supply Chain Analysis
Feed input supply rests on Brazilian and Argentine soymeal exporters, Peruvian and Chilean fishmeal processors, and Chinese domestic amino acid compounders. Raw material dependencies span soy protein concentrate, marine-derived fishmeal, and vitamin premix formulations. Single-source vulnerability concentrates in Peruvian anchovy harvest fluctuations that trigger global fishmeal price spikes. Distribution runs through vertically integrated hatchery-to-retail networks in China, broadline foodservice purveyors in North America, and specialized seafood distributors serving ethnic retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tilapia sector is consolidating into a vertical-integration race where captive broodstock programs and controlled-environment aquaculture systems determine cost structure and supply reliability. Players are pursuing downstream processing capacity and direct retail channel access as the decisive competitive lever.
For Market Incumbents: Anticipate regulatory tightening on antibiotic residue limits by accelerating vaccine and probiotic replacement programs. Lock in multi-year frozen fillet supply commitments with North American quick-service chains before new RAS operators achieve scale. Defensive moves center on backward integration into proprietary broodstock genetics and renewable-powered facility retrofits that satisfy EU Green Deal disclosure requirements.
For New Entrants and Emerging Players: Begin with underpenetrated domestic markets across Indonesian Java and Sumatra where hatchery-to-retail networks remain sparse. Target Brazilian state-level supermarket chains seeking to displace import dependency with local whole fish supply. A direct e-commerce go-to-market angle captures emerging home-delivery demand in Chinese tier-one cities and Brazilian metropolitan areas.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale RAS technology adopters in Jiangsu and Shandong provinces facing capital constraints from environmental compliance retrofit costs. Long-term viability over a multi-year horizon hinges on securing watershed-access rights or closed-loop system permits before regulatory caps harden. Watch Chinese Ministry of Agriculture enforcement patterns in Guangdong and Hubei provinces as the inflection signal for supply-constraint timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Recirculating Aquaculture System Retrofit | Enables year-round production bypassing watershed expansion limits in Jiangsu and Shandong provinces. |
| Captive Broodstock Program Development | Secures genetic supply chain control reducing dependency on external hatchery inputs. |
| Renewable-Powered Facility Conversion | Satisfies EU Green Deal carbon-footprint disclosure requirements for European retail procurement. |
| Direct E-Commerce Channel Launch | Captures emerging home-delivery demand in Chinese tier-one cities and Brazilian metropolitan markets. |
| Antibiotic-Free Certification Investment | Meets tightening EFSA residue monitoring protocols for German and French retail access. |
Research Approach
Multi-period observation of feed conversion ratios, RAS adoption rates, and import displacement patterns anchored the trend analysis, supplemented by interviews with hatchery operations managers, foodservice procurement directors at North American quick-service chains, seafood category buyers at Brazilian supermarket chains, and regulatory affairs specialists at export-oriented processing facilities. Secondary validation drew from Chinese Ministry of Agriculture aquaculture output statistics, FDA seafood import refusal data, EFSA residue monitoring reports, and Brazilian ANVISA therapeutic use disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and regional demand clusters.
Input-output matrix framing connected feed cost variables, production cycle timelines, and cold chain logistics to volume and value projections across the analysis window. Segmentation dimensions spanned product format sophistication, channel working capital requirements, end-user procurement scale, and form-specific cold chain maturity. CAGRs derived from regression analysis of historical output trends against regulatory constraint scenarios and technology adoption curves. Industry-specific forecast inputs incorporated soymeal price volatility indices and RAS capital expenditure cycles.
Underlying measurement precision varies by segment; processed value-added and online retail channels carry tighter precision than fragmented fishmonger and dried product segments. Forecasts reflect assumptions around environmental compliance enforcement intensity and feed input cost trajectories. A small set of triggers warrants ongoing watch: Chinese watershed zoning enforcement actions, Brazilian ANVISA antibiotic protocol revisions, and EU Green Deal scope 3 disclosure implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Hatchery Product Market